
 Automotive Aftermarket Market | 2026-2036
Automotive Aftermarket Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Aftermarket Market Intelligence
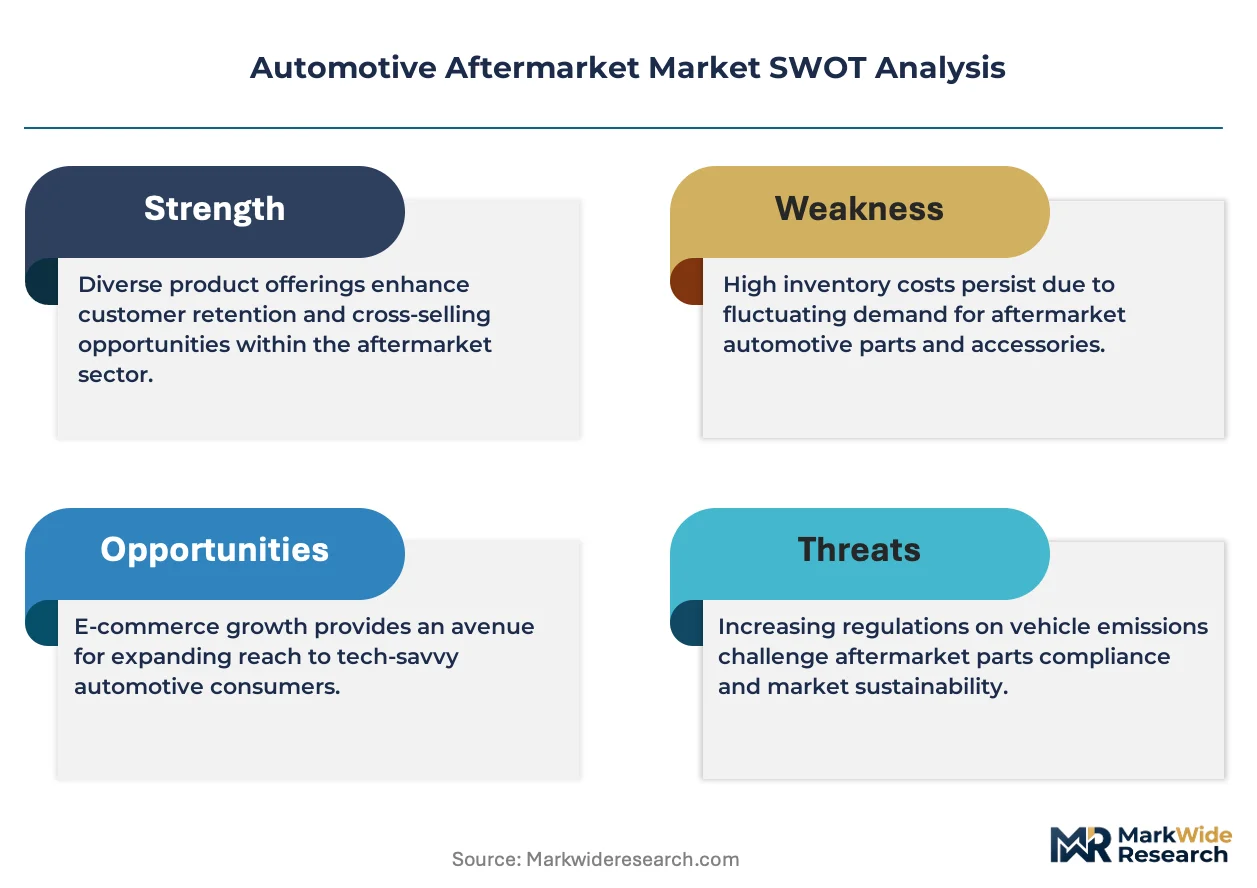
Asset-light leasing models for diagnostic equipment and inventory financing are reshaping how independent repair shops enter the Automotive Aftermarket. Robert Bosch GmbH leverages its manufacturing scale to supply OEM-grade components across multiple product lines. AutoZone, Inc. anchors its position through dense retail coverage and proprietary private-label parts. Denso Corporation specializes in thermal and powertrain components for hybrid vehicle servicing.
The Automotive Aftermarket encompasses all parts, accessories, and services sold after the original sale of a vehicle, including brake pads engineered to SAE J661 friction coefficients, catalytic converters meeting EPA Tier 3 emissions standards, and lubricants formulated to API SP and ILSAC GF-6 specifications. Its primary purpose is to maintain vehicle safety, performance, and regulatory compliance throughout the operating life of passenger and commercial vehicles. Replacement Parts and Tires represent the largest value pools due to predictable wear cycles and mandated safety inspections across major markets. E-commerce channels within the Distribution Channel segment are capturing disproportionate growth as digital fitment tools reduce return rates and expand addressable geographic reach.
FCC oversight of connected-car diagnostics, EPA enforcement of emissions-compliant replacement components, and state-level right-to-repair statutes shape product certification requirements and channel access rules in the United States. The EU Green Deal and REACH chemical restrictions impose parallel compliance burdens on suppliers serving European professional repair networks. Stakeholders must monitor how software-locked components and over-the-air updates alter the definitional boundary between hardware replacement and proprietary service access.
Market Dynamics
Software-defined vehicle architectures are fragmenting the traditional boundary between hardware replacement and proprietary service access, forcing aftermarket suppliers to recalibrate certification strategies around encrypted diagnostics and over-the-air update protocols.
Growth Catalysts
- Right-to-repair statutes:State-level legislation in the United States mandates diagnostic tool access for independent repair shops, expanding addressable service volumes beyond dealer networks.
- Hybrid powertrain proliferation:Thermal management and battery servicing requirements create specialized component demand from professional repair networks.
- Vehicle longevity extension:Fleet operators in Germany and China are stretching replacement cycles, generating sustained demand for preventive maintenance components.
Market Restraints
- Rare earth supply concentration:Catalytic converter substrates depend on palladium and rhodium sourcing concentrated in South African and Russian mining operations.
- EPA Tier 3 friction:Emissions-compliant replacement part certification timelines extend inventory holding periods for distributors serving California and Northeast corridor markets.
- Software lock-in:OEM-controlled telematics platforms restrict independent access to fault codes and calibration parameters.
Strategic Opportunities
- India aftermarket penetration:Organized service networks remain underdeveloped relative to installed vehicle base, creating whitespace for branded parts distribution.
- EV battery remanufacturing:Second-life cell grading and module replacement protocols are converging with thermal management expertise from hybrid servicing.
- EU Green Deal compliance services:REACH chemical restrictions and circular economy mandates generate demand for certified recycling and refurbishment programs.
Industry Challenges
- Diagnostic technician scarcity:High-voltage system certification requirements outpace vocational training program output in major markets.
- Multi-standard compliance:SAE J2534 pass-through device compatibility must align with manufacturer-specific reprogramming protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Aftermarket Market |
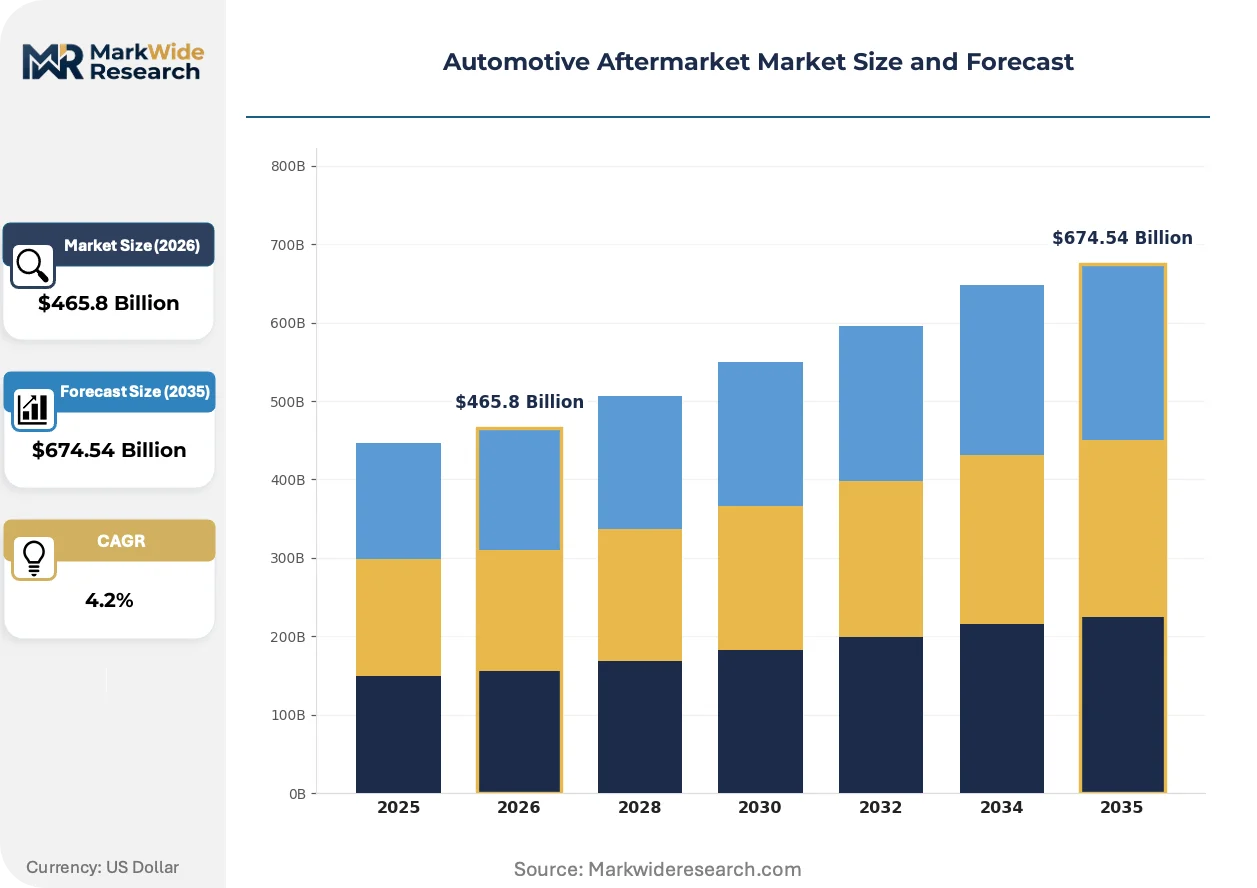
| Market Size in 2026 | $465.8 Billion |
| Market Size in 2035 | $674.54 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Replacement Parts, Accessories, Lubricants, Tires, Batteries, Electronics Distribution Channel: Specialty Stores, E-commerce, Wholesalers, Authorized Dealers, Independent Retailers Customer Type: Professional Repair Shops, Car Dealerships, Fleet Operators, Individual Car Owners Service Type: Maintenance, Repair, Customization, Installation, Diagnostics |
| Companies Covered | Robert Bosch GmbH, AutoZone, Inc., Advance Auto Parts, O’Reilly Auto Parts, Continental AG, ZF Friedrichshafen AG, Denso Corporation, LKQ Corporation, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Aftermarket Market Strategic Shifts & Innovations
Connected vehicle data streams and predictive maintenance algorithms are compressing traditional failure-mode-based replacement cycles, while regulatory pressure on emissions traceability intensifies documentation requirements across supply chains.
Telematics-integrated prognostic systems are hybridizing conventional scheduled maintenance with condition-based intervention protocols. Commercial fleet managers are adopting these platforms fastest, particularly in long-haul trucking segments. The technology is hybridizing parts procurement patterns by triggering just-in-time inventory pulls rather than bulk preventive stocking.
REACH chemical restrictions under the EU Green Deal are mandating substance-of-concern disclosure across coating and friction material supply chains. Component suppliers must now maintain material passports from raw input through end-of-life processing. Professional repair networks in Germany and France face the steepest compliance documentation burdens.
Digital fitment tools and VIN-specific cataloging are compressing return rates for e-commerce channels serving DIY installers. Independent online retailers are capturing share from traditional jobber networks by integrating augmented reality guidance for component identification. This shift concentrates in the United States and United Kingdom where consumer comfort with self-service diagnostics runs highest.
Automotive Aftermarket Market Segmentation
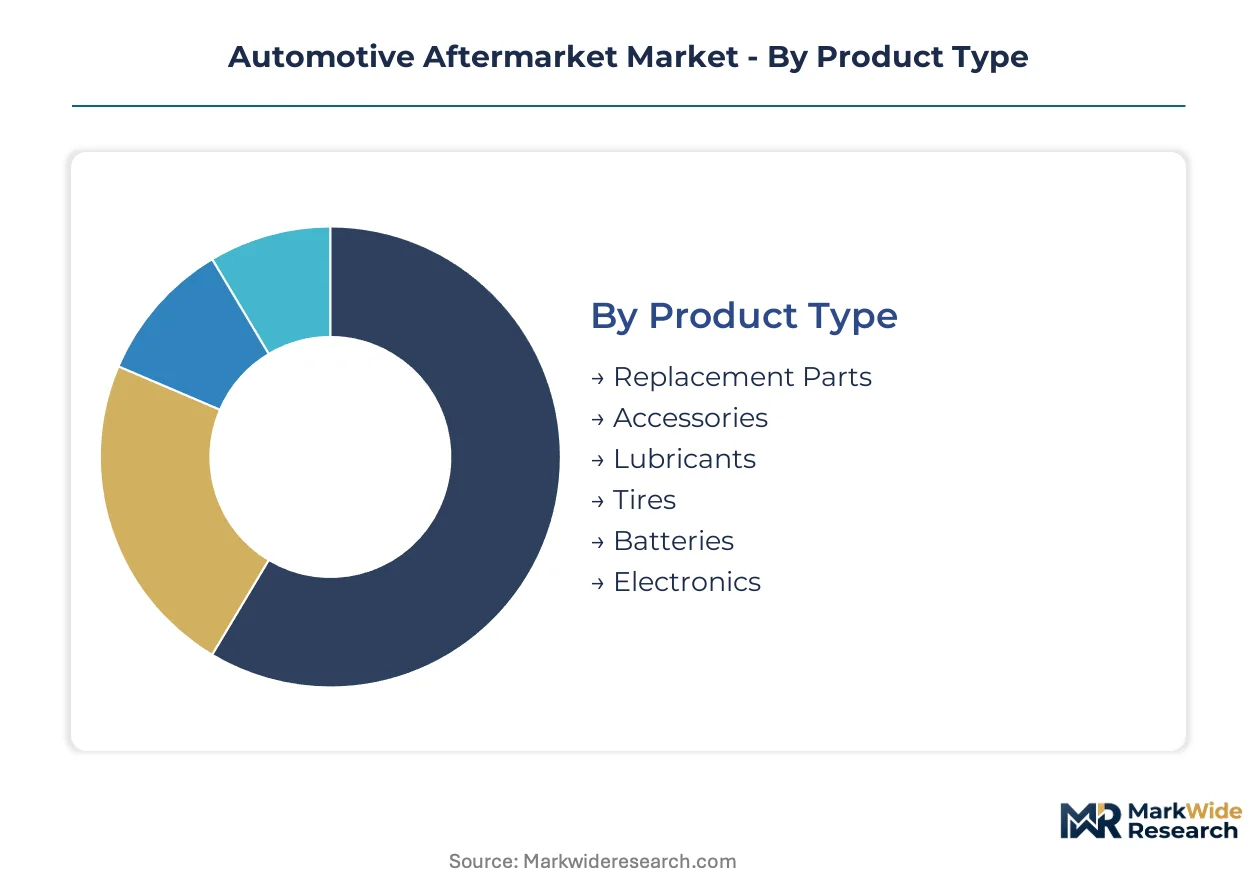
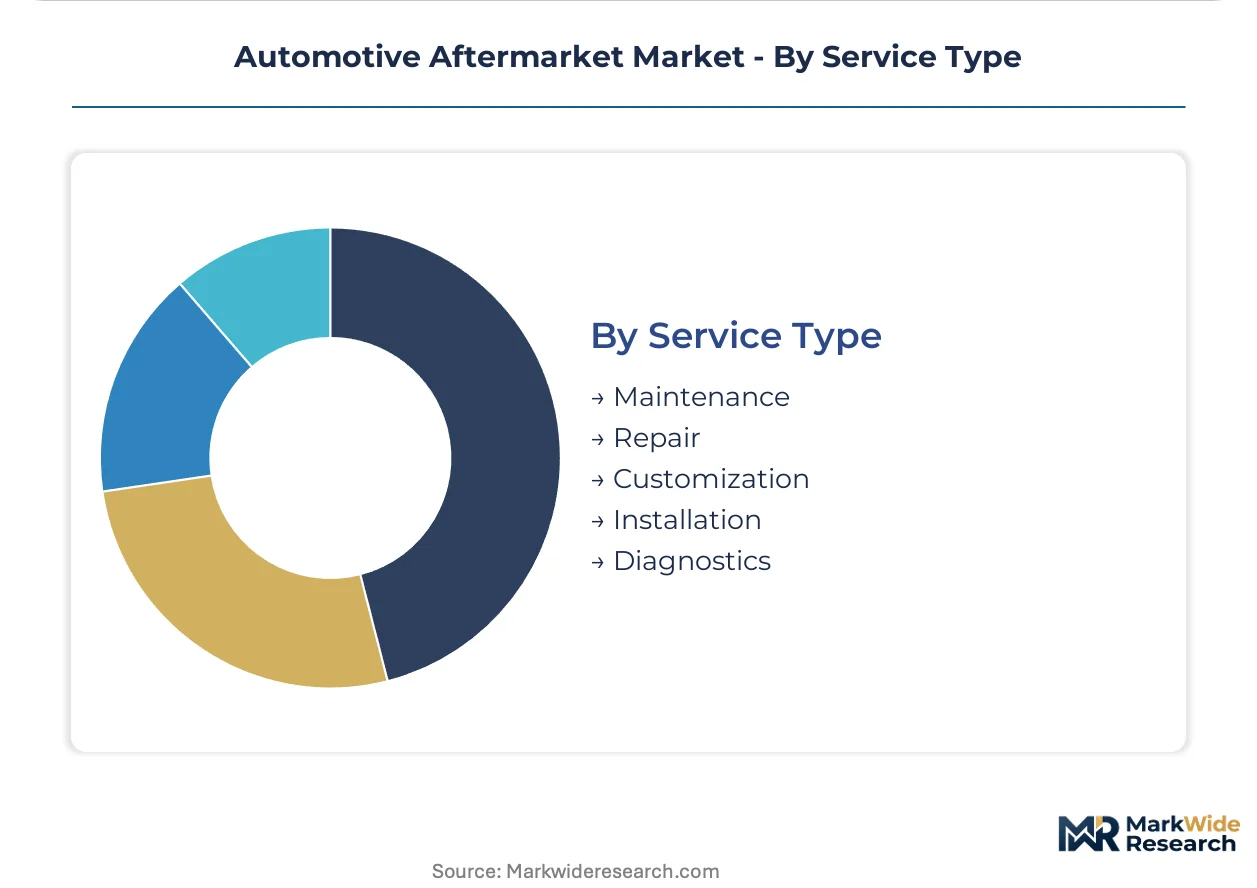
Segmentation in the Automotive Aftermarket reveals how service intensity, procurement authority, and technical complexity fragment demand across distinct value pools. Each dimension exposes different margin structures, certification requirements, and channel control points that suppliers must navigate.
Product Type:
After-sales-service intensity varies dramatically across product categories, with wear-cycle predictability and regulatory compliance burden determining professional versus DIY purchase patterns.
- Replacement Parts:Brake pads engineered to SAE J661 friction coefficients, catalytic converters meeting EPA Tier 3 standards, and filtration components dominate procurement volumes for professional repair networks. Fleet operators in Germany and China generate sustained demand as vehicle longevity stretches replacement cycles beyond historical norms.
- Tires:Mandated safety inspections across the United States, Germany, and China create predictable replacement demand tied to tread-wear indicators and seasonal changeover patterns. Commercial fleet managers prioritize total-cost-of-ownership procurement over upfront unit economics.
- Lubricants:Formulations meeting API SP and ILSAC GF-6 specifications serve hybrid powertrain thermal management requirements alongside conventional internal combustion engines.
- Batteries:Start-stop systems and mild-hybrid architectures are expanding absorbed glass mat and lithium-ion starter battery demand beyond traditional lead-acid replacement cycles.
- Electronics:Sensors, control modules, and telematics hardware face software-lock-in constraints from OEM-controlled diagnostic access protocols.
- Accessories:Aesthetic and functional add-ons concentrate in consumer-direct channels with minimal regulatory compliance overhead.
Replacement Parts holds the largest share; momentum sits with Electronics as software-defined architectures expand addressable component value.
Distribution Channel:
Channel economics reflect inventory velocity, technical support requirements, and geographic coverage density rather than simple markup layering.
- E-commerce:Digital fitment tools using VIN-specific cataloging compress return rates below traditional jobber benchmarks. Independent online retailers capture share fastest in the United States and United Kingdom where DIY diagnostic comfort runs highest.
- Specialty Stores:Dense retail coverage and proprietary private-label parts anchor competitive positioning through immediate availability and counter-level technical guidance.
- Wholesalers:Jobber networks serving independent repair shops face margin compression from direct-to-installer digital platforms.
- Authorized Dealers:OEM-controlled channels maintain exclusive access to software-locked components and warranty-compliant service records.
- Independent Retailers:Regional chains and single-location operators compete on localized inventory depth and relationship-based credit terms.
E-commerce climbs the fastest; Specialty Stores retain the deepest penetration in professional repair procurement.
Customer Type:
Procurement authority and technical sophistication determine whether demand flows through consolidated fleet contracts or fragmented consumer transactions.
- Professional Repair Shops:State-level right-to-repair statutes in the United States mandate diagnostic tool access, expanding service volumes beyond dealer networks for emissions-compliant component installation.
- Fleet Operators:Preventive maintenance programs and predictive analytics adoption concentrate demand for high-volume, scheduled replacement cycles in long-haul trucking segments.
- Car Dealerships:Warranty service and software-update bundling protect proprietary access to encrypted calibration parameters.
- Individual Car Owners:Price-sensitive DIY installers drive e-commerce growth for accessories and consumables with low technical barrier to installation.
Professional Repair Shops command the highest product mix complexity; Fleet Operators show the steepest expansion trajectory in telematics-integrated procurement platforms.
Service Type:
Service segmentation tracks the progression from predictable maintenance schedules through unplanned failure interventions to discretionary customization.
- Maintenance:Oil changes, filter replacements, and inspection services follow manufacturer-prescribed intervals with high volume and compressed margins.
- Repair:Component failure interventions require diagnostic certainty and parts availability coordination, favoring suppliers with technical documentation depth.
- Diagnostics:Connected-vehicle data streams and prognostic algorithms are hybridizing scheduled maintenance with condition-based intervention protocols.
- Installation:Accessory and electronics fitting demands specialized tooling and calibration expertise increasingly restricted by OEM software controls.
- Customization:Aesthetic and performance modifications operate outside regulatory compliance frameworks with highest margin but most volatile demand.
Maintenance holds the largest share; Diagnostics gains share fastest as predictive platforms compress traditional failure-mode replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in automotive aftermarket components tilt toward import-dependent markets with aging vehicle fleets, while manufacturing exporters capture premium segments through certified component exports. Currency volatility and emissions compliance divergence are fragmenting procurement patterns across major economies.
United States
Right-to-repair statutes in Massachusetts and California mandate diagnostic tool access for independent repair shops, expanding service volumes beyond dealer networks. EPA Tier 3 enforcement extends certification timelines for emissions-compliant replacement parts. Detroit anchors thermal management component production for hybrid powertrain servicing.
Germany
Fleet operators stretch replacement cycles beyond historical norms, generating sustained preventive maintenance demand. EU Green Deal REACH chemical restrictions impose substance-of-concern documentation across coating supply chains. Stuttgart industrial cluster concentrates OEM-grade brake pad and filtration component manufacturing.
China
Vehicle longevity extension and rising installed base density concentrate aftermarket demand in tier-one cities. MIIT enforces GB standards for replacement part quality certification. Yangtze River Delta hosts organized service network expansion targeting underpenetrated provincial markets.
India
Organized service networks remain underdeveloped relative to installed vehicle base, creating whitespace for branded parts distribution. BIS certification requirements for automotive components tighten import quality gates. Maharashtra industrial corridor attracts distribution hub investment for pan-Indian aftermarket coverage.
Japan
Hybrid powertrain proliferation sustains specialized thermal and battery servicing component demand. METI promotes circular economy mandates for remanufactured parts procurement. Nagoya manufacturing belt supplies precision-engineered replacement modules for professional repair networks.
Automotive Aftermarket Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper technical documentation. Market structure tilts toward consolidated manufacturing scale at the top and fragmented regional distribution below. Three archetypes dominate: diversified industrial conglomerates with captive aftermarket divisions, pure-play parts retailers with dense geographic coverage, and specialized component engineers serving hybrid-EV thermal systems. Competitive moves concentrate on strategic partnerships for diagnostic tool access and portfolio diversification into remanufactured product lines.
Within the diversified industrial tier, Robert Bosch GmbH and Denso Corporation exemplify manufacturing-scale suppliers spanning multiple product categories. AutoZone, Inc. anchors the retail-centric archetype through proprietary private-label parts and counter-level technical guidance. These three occupy positions that reflect divergent strategic bets on channel control versus component engineering depth.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| AutoZone, Inc. |
| Advance Auto Parts |
| O'Reilly Auto Parts |
| Continental AG |
| ZF Friedrichshafen AG |
| Denso Corporation |
| LKQ Corporation |
| 3M |
| Others |
Cost & Logistics Intelligence
Palladium and rhodium mining concentration in South African and Russian operations anchors catalytic converter substrate costs, concentrating margin pools with distributors serving California and Northeast corridor markets under EPA Tier 3 enforcement timelines.
Pricing Analysis
Fleet operators and professional repair shops anchor a contract-based long-term offtake structure for high-volume replacement parts, with price differentiation driven by EPA Tier 3 certification grade and volume scale. Cost compression in emissions-compliant inventory runs through extended certification timelines. DIY installers show highest price sensitivity, while OEM-authorized dealers absorb premium positioning through warranty bundling.
Supply Chain Analysis
Extended payment terms from Tier 1 suppliers to independent distributors feed working capital constraints across the channel. Manufacturing concentrates in Germany, China, and Japan for precision-engineered brake and thermal components. Rare earth dependencies for catalytic converters rest on South African and Russian sourcing. Single-source vulnerability in palladium supply chains threatens price stability. Distribution runs through dense jobber networks competing with direct-to-installer digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation across long-haul trucking segments is shifting procurement power toward volume-contract buyers, fragmenting margin capture across smaller independent repair networks.
For Market Incumbents: Entrench diagnostic tool access partnerships before right-to-repair statutes fully mature. Deepen backward integration into remanufactured component lines to offset margin pressure from software-locked OEM calibrations. Certification investment in EPA Tier 3 and EU REACH compliance protects channel access against regulatory exclusion. For New Entrants and Emerging Players: India's underdeveloped organized service networks relative to its installed vehicle base represent the most penetrable entry point for branded parts distribution. EV battery remanufacturing protocols in Japan and Germany offer specialized white-space demand from hybrid powertrain proliferation. A digital-first go-to-market angle using VIN-specific fitment tools bypasses incumbent jobber relationships. For Investors and Strategic Acquirers: Capital is best deployed toward thermal management specialists with hybrid-EV servicing expertise and established OEM technical documentation libraries. Long-term viability over the next decade hinges on software-defined vehicle adaptation capability. Watch for inflection signals in telematics-integrated procurement platform adoption rates among commercial fleet managers.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic Tool Access Partnership | Right-to-repair statutes in Massachusetts and California mandate independent shop access, expanding serviceable market volume. |
| Remanufactured Component Line Expansion | EU Green Deal circular economy mandates and REACH compliance create certified refurbishment demand in Germany and France. |
| Digital Fitment Platform Investment | VIN-specific cataloging compresses e-commerce return rates below traditional jobber benchmarks in United States and United Kingdom. |
| Hybrid Thermal System Specialization | Proliferation of hybrid powertrains sustains specialized battery and thermal servicing component demand from professional networks. |
| India Distribution Hub Buildout | Maharashtra industrial corridor investment captures whitespace in underpenetrated provincial markets beyond tier-one cities. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with aftermarket distributors, OEM platform engineers, fleet procurement managers, and independent repair shop owners. Secondary validation drew from EPA enforcement records, state-level right-to-repair statute filings, vehicle registration databases, and customs trade data for catalytic converter substrate materials. Bottom-up segment sizing and top-down macroeconomic calibration were triangulated to ensure consistency.
Calibration against historical replacement part demand patterns and fleet operator procurement surveys anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, customer archetype, and propulsion architecture. CAGRs were derived from trend extrapolation adjusted for regulatory enforcement intensity and technology substitution effects. Forecast inputs incorporated EPA Tier 3 certification timeline extensions and MIIT GB standards enforcement in China.
Practitioners should monitor right-to-repair statute expansion, rare earth supply disruption events, and OEM telematics platform lock-in escalation for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Car Recycling Market
Vehicle Maintenance & Aftermarket
Global Integrated Vehicle Health Management Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Glass Market
Vehicle Maintenance & Aftermarket
Non OEM EV MRO Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Wash Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Mobile Car Wash and Detailing Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Cleaning Products Market
Vehicle Maintenance & Aftermarket
Car Care Products Market
Vehicle Maintenance & Aftermarket
Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Stolen Vehicle Recovery Market
Vehicle Maintenance & Aftermarket
Antimicrobial Car Care Products Market
Vehicle Maintenance & Aftermarket
Highway Maintenance Market
Vehicle Maintenance & Aftermarket
APEJ Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Car Cleaning Products Market
Vehicle Maintenance & Aftermarket
Body Repair Tools Market