
 China DC Motor Market | 2026-2036
China DC Motor Market Size, Share, and Industry Trends Forecast 2026-2036
China DC Motor Market Insights
Equipment leasing and project finance for automated production lines is fragmenting competitive access across China's DC motor sector. Inovance Technology leverages its servo system integration to dominate high-precision robotics applications. Wolong Electric Group sustains manufacturing scale advantages through captive winding and magnet processing operations. Broad-Ocean Motor anchors coastal supply chains with dedicated low-voltage motor capacity serving appliance OEMs in Zhejiang and Jiangsu.
A DC motor converts direct current electrical energy into mechanical rotation through electromagnetic torque generation between stator windings and a commutated rotor assembly, with brushed types using carbon brush contact and brushless variants employing electronic commutation via Hall-effect sensors for superior efficiency above 85% in continuous-duty cycles. Brushed motors retain cost-sensitive positions in automotive auxiliary and home appliance applications where price tolerance limits electronic complexity. Brushless architectures lead growth trajectories across industrial equipment and robotics segments where positioning accuracy and thermal stability command premium procurement. Servo motor configurations concentrate margin pools in semiconductor manufacturing and CNC machine tool installations requiring closed-loop feedback control.
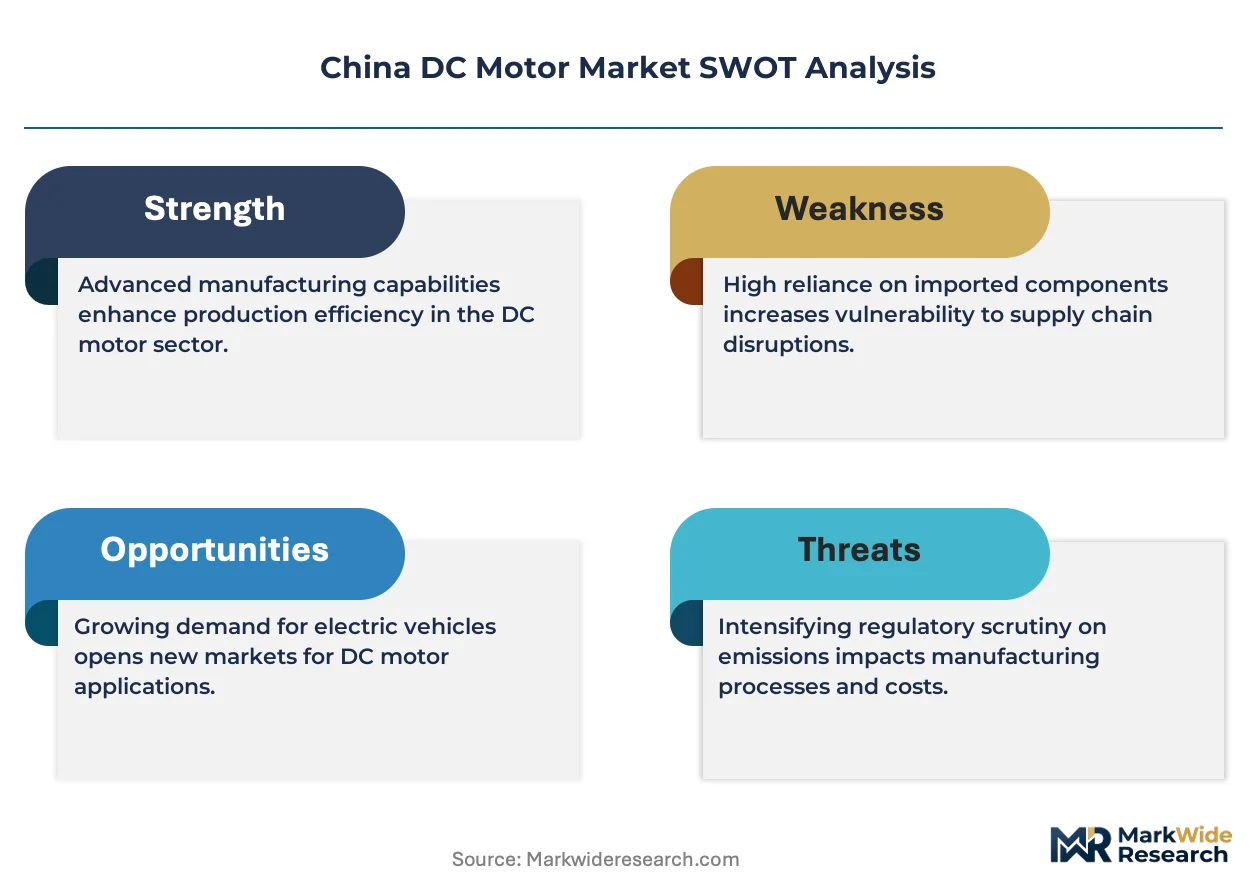
MIIT enforces GB energy-efficiency standards that phase out Class IE1 induction equivalents and redirect procurement toward premium-efficiency DC alternatives in state-backed industrial upgrades. NMPA medical device regulations and SAMR product safety certifications impose electromagnetic compatibility testing that extends development timelines for brushless motor suppliers targeting diagnostic equipment and surgical robot platforms. Stakeholders must monitor how China's dual carbon goals reshape magnet material sourcing constraints and rare-earth processing quotas before committing to capacity expansion schedules.
Market Dynamics
Brushless motor architectures are compressing brushed motor margins across China's industrial automation sector as MIIT efficiency mandates accelerate procurement upgrades in state-backed manufacturing clusters.
Growth Catalysts
- Electric vehicle powertrain integration:Domestic OEM supply chains are expanding brushless motor procurement volumes for traction and auxiliary systems. Tier-one automotive suppliers in Guangdong Province are scaling dedicated production lines.
- GB energy-efficiency standards:MIIT regulations phase out Class IE1 induction equivalents and redirect procurement toward premium-efficiency DC alternatives. State-backed industrial upgrade programs mandate compliance timelines.
- Robotics precision requirements:Semiconductor manufacturing and CNC machine tool installations demand closed-loop servo configurations. Positioning accuracy specifications command premium motor procurement in the Pearl River Delta.
Market Restraints
- Rare-earth magnet cost volatility:Neodymium and dysprosium price swings compress margin stability for permanent magnet motor producers. Sourcing constraints intensify under China's dual carbon processing quotas.
- NMPA certification friction:Medical device electromagnetic compatibility testing extends development timelines for brushless suppliers targeting diagnostic equipment. Surgical robot platforms face prolonged approval cycles.
- Brushed motor substitution ceiling:Cost-sensitive automotive auxiliary and home appliance applications resist electronic commutation complexity. Price tolerance limits brushless penetration in high-volume, low-margin segments.
Strategic Opportunities
- Zhejiang-Jiangsu appliance corridor:Dedicated low-voltage motor capacity serving coastal OEMs remains underpenetrated by premium-efficiency suppliers. Appliance export manufacturers seek compliant alternatives for EU-bound shipments.
- SAMR product safety alignment:Convergence with international electromagnetic compatibility standards creates regulatory tailwinds for certified suppliers. Export-oriented producers gain competitive positioning in cross-border medical device supply chains.
- Servo-drive convergence:Integration of brushless motors with variable frequency drives and motion controllers enables system-level value capture. Industrial automation integrators bundle hardware with predictive maintenance software.
Industry Challenges
- Magnet material sourcing reconfiguration:Dual carbon goals reshape rare-earth processing quotas and require supply chain recalibration before capacity expansion commitments.
- NMPA-SAMR compliance synchronization:Overlapping medical device and product safety certification timelines create documentation bottlenecks. Diagnostic equipment manufacturers demand synchronized approval pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China DC Motor Market |
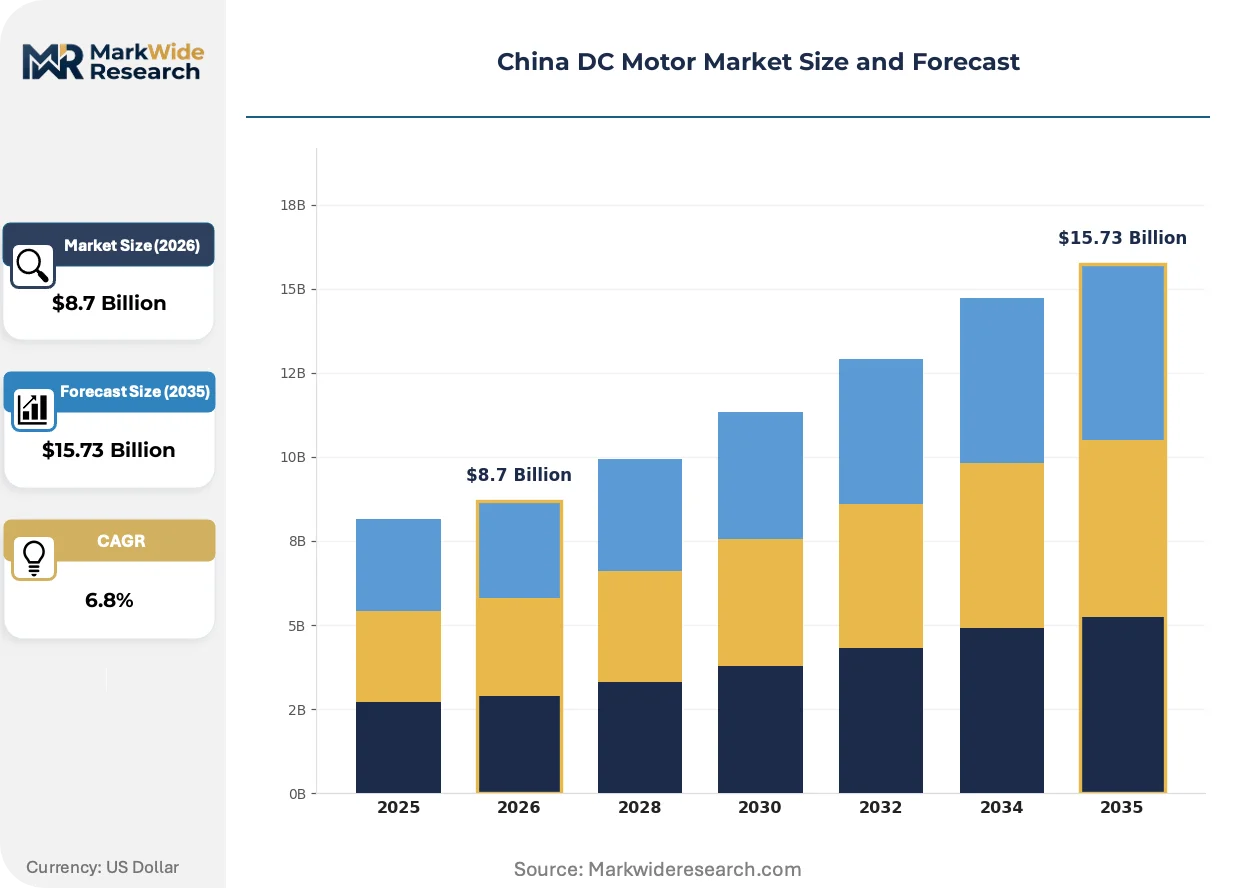
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Automobiles, Robotics, Industrial Equipment, Consumer Electronics Type: Brushed, Brushless, Stepper, Servo End User: Manufacturing, Automotive, Aerospace, Home Appliances Voltage Rating: Low Voltage, Medium Voltage, High Voltage, Others |
| Companies Covered | Inovance Technology, Sunrise Electric Motor, Power Motor, DynaMotion Drive Systems, Sinotech Motors, Wolong Electric Group, Broad-Ocean Motor, Johnson Electric, Leili Motor, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China DC Motor Market Trends and Innovations
Electronic commutation architectures are displacing mechanical brush systems across precision manufacturing segments, while regulatory pressure on energy intensity accelerates technology refresh cycles in state-backed industrial zones.
Permanent magnet synchronous motor technology is migrating from standard industrial pumps and fans toward high-precision robotics and semiconductor manufacturing equipment. Automotive tier-one suppliers in Guangdong are adopting these configurations for electric power steering and thermal management systems at accelerated procurement volumes. The shift is compressing brushed motor market share in continuous-duty applications above 85% efficiency thresholds.
MIIT's GB energy-efficiency standards are tightening compliance thresholds for industrial motor procurement in state-backed upgrade programs. The regulations phase out Class IE1 induction equivalents and redirect public procurement toward premium-efficiency DC alternatives. Manufacturers in the Pearl River Delta are retooling winding operations to meet revised testing protocols before mandatory enforcement windows.
Buyer concentration among robotics OEMs and automotive tier-one suppliers is consolidating procurement authority around integrated servo system vendors. Discrete motor suppliers face margin compression as customers demand bundled drive electronics and motion control software. This pattern concentrates in Guangdong Province's precision manufacturing cluster, where foundries compete on system integration capability rather than component specifications alone.
China DC Motor Market Segmentation
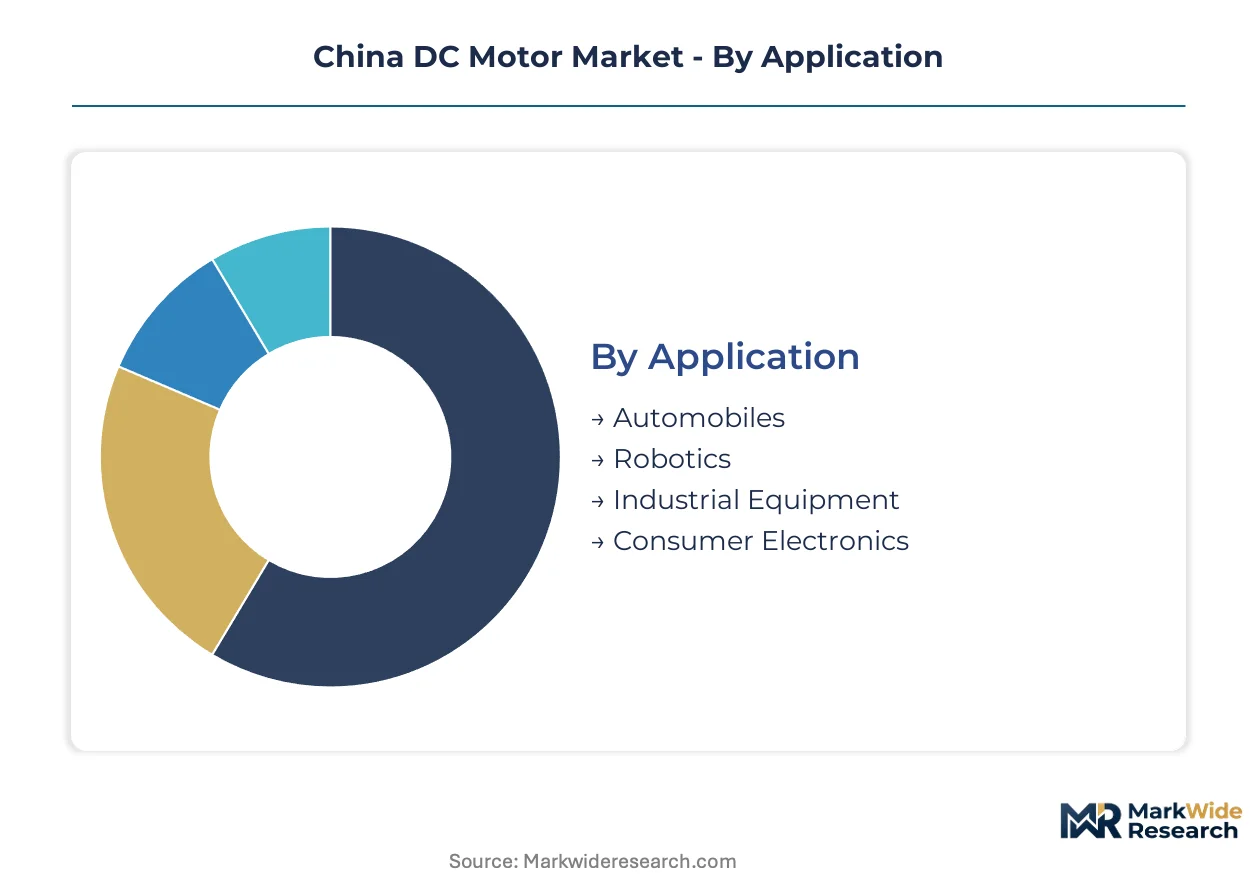
Segmentation in China's DC motor market reveals how technology choices, voltage requirements, and end-use specifications create distinct procurement ecosystems. Manufacturers compete across fundamentally different performance and cost parameters depending on which segment combination they target.
Application:
Use-case spectrum spans precision motion control in semiconductor fabs to cost-optimized auxiliary drives in mass-market vehicles.
- Automobiles:Traction motors and thermal management systems demand continuous-duty cycles above 85% efficiency. Guangdong Province's tier-one automotive suppliers are scaling dedicated brushless production lines for domestic OEM powertrain integration.
- Robotics:Closed-loop servo configurations with Hall-effect sensor feedback enable positioning accuracy for CNC machine tools. Pearl River Delta foundries command premium procurement from semiconductor manufacturing equipment buyers.
- Industrial Equipment:Pumps, fans, and conveyor systems under MIIT GB standards phase out Class IE1 induction equivalents.
- Consumer Electronics:Miniature brushed motors retain cost-sensitive positions in personal devices where electronic commutation complexity exceeds price tolerance.
Established volume favors Automobiles; emerging adoption favors Robotics.
Type:
Cost tier separation runs from commodity brushed architectures to integrated servo systems with bundled drive electronics.
- Brushless:Electronic commutation via Hall-effect sensors eliminates carbon brush wear and enables efficiency thresholds above 85%. NMPA electromagnetic compatibility testing extends development timelines for medical device and surgical robot applications.
- Servo:Integrated motor-drive configurations with predictive maintenance software capture system-level value. Buyer concentration among automation integrators concentrates procurement authority around bundled motion control solutions.
- Brushed:Carbon brush contact systems dominate automotive auxiliary and home appliance applications where procurement prioritizes unit cost over lifecycle efficiency.
- Stepper:Open-loop positioning suits low-cost automation in packaging and textile machinery without feedback sensor overhead.
Technology refresh under MIIT mandates favors Brushless; margin concentration favors Servo.
End User:
Customer type determines certification burden and procurement scale, from state-backed industrial upgrades to export-oriented appliance manufacturing.
- Manufacturing:State-backed upgrade programs mandate premium-efficiency DC alternatives in accordance with MIIT GB standards. Public procurement timelines accelerate compliance transitions.
- Automotive:Domestic OEM supply chains expand brushless motor procurement for electric power steering and battery thermal management. Dual carbon goals reshape magnet material sourcing constraints for permanent magnet synchronous configurations.
- Aerospace:Precision positioning requirements and weight constraints drive specialized high-reliability specifications.
- Home Appliances:Zhejiang and Jiangsu coastal OEMs seek compliant alternatives for EU-bound shipments under SAMR product safety alignment.
Policy tailwinds favor Manufacturing; export compliance pressure favors Home Appliances.
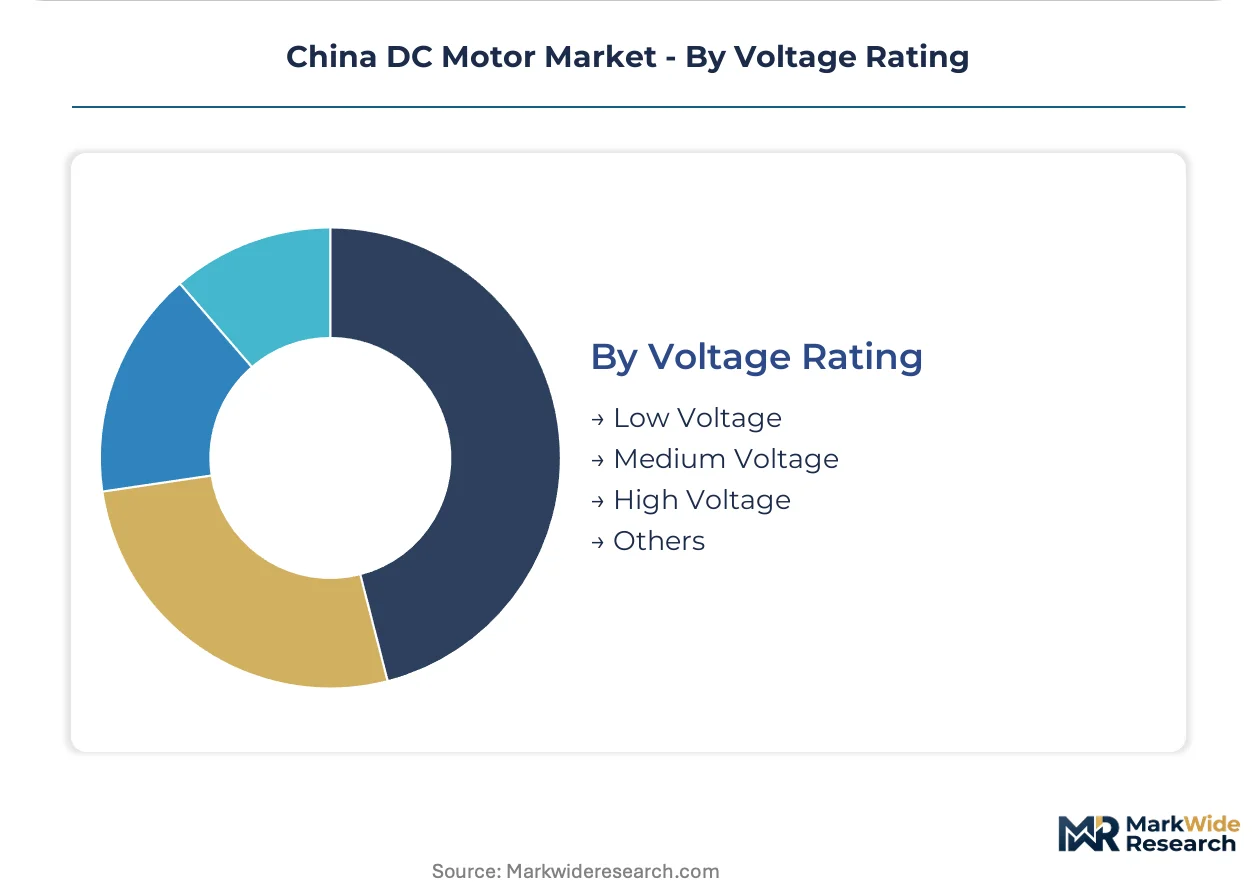
Voltage Rating:
Power band segmentation aligns with safety certification tiers and insulation material specifications.
- Low Voltage:Dedicated capacity serving appliance OEMs in Zhejiang and Jiangsu remains underpenetrated by premium-efficiency suppliers. Broad-Ocean Motor anchors this coastal corridor with standardized production.
- Medium Voltage:Industrial automation integrators specify these ratings for continuous-duty pumps and fans in Pearl River Delta manufacturing clusters.
- High Voltage:Traction applications in electric vehicle powertrains require specialized winding insulation and thermal management.
- Others:Custom voltage specifications serve specialized medical diagnostic and laboratory equipment with non-standard power requirements.
Volume concentration favors Low Voltage; technology differentiation favors High Voltage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's DC motor sector maintains a substantial export surplus in low-voltage units while importing high-precision servo configurations from Japan and Germany. Trade flows concentrate through Guangdong and Zhejiang ports serving appliance OEMs and automotive tier-one suppliers.
Guangdong Province
Pearl River Delta foundries supply brushless traction motors to domestic electric vehicle OEMs at expanding procurement volumes. MIIT energy-efficiency mandates accelerate compliance transitions among Shenzhen and Dongguan manufacturers. Tier-one automotive suppliers in Foshan are scaling dedicated production lines for powertrain integration.
Jiangsu Province
Yangtze River Delta industrial zones concentrate medium-voltage motor capacity for pumps and conveyor systems. GB standards phase-out timelines redirect state-backed procurement toward premium-efficiency alternatives. Suzhou and Wuxi manufacturing clusters retool winding operations to meet revised testing protocols.
Zhejiang Province
Ningbo and Wenzhou appliance corridors drive demand for dedicated low-voltage motor capacity serving coastal OEMs. SAMR product safety alignment creates regulatory tailwinds for export-bound manufacturers. Premium-efficiency suppliers remain underpenetrated in this cost-sensitive segment.
Shandong Province
Jinan and Qingdao industrial bases serve northern China's manufacturing equipment upgrade programs. Dual carbon processing quotas reshape magnet material sourcing constraints for permanent magnet synchronous configurations. Local foundries face supply chain recalibration pressures before capacity expansion commitments.
Sichuan-Chongqing Region
Western China manufacturing relocation policies concentrate automotive auxiliary motor production in Chengdu and Chongqing. Cost-sensitive brushed architectures dominate this inland corridor where electronic commutation complexity exceeds price tolerance. NMPA certification friction limits medical device motor penetration.
China DC Motor Market Competitive Landscape
On the supply side, the industry is consolidating around integrated servo system vendors while fragmenting across discrete motor fabricators. Three strategic archetypes dominate: captive magnet processors controlling upstream rare-earth supply, precision foundries bundling drive electronics with motion control software, and scale-oriented manufacturers serving standardized appliance specifications. Competitive moves center on backward integration into winding operations and strategic partnerships with automotive tier-one suppliers.
Among China-based industrial automation specialists, Inovance Technology and Wolong Electric Group exemplify the integrated systems archetype, while Broad-Ocean Motor anchors the coastal low-voltage segment. These three occupy positions across fundamentally different margin pools—servo-drive convergence in Guangdong, captive magnet processing in the Yangtze Delta, and dedicated appliance capacity in Zhejiang.
| Leading Market Players |
|---|
| Inovance Technology |
| Sunrise Electric Motor |
| Power Motor |
| DynaMotion Drive Systems |
| Sinotech Motors |
| Wolong Electric Group |
| Broad-Ocean Motor |
| Johnson Electric |
| Leili Motor |
| Others |
Pricing and Supply Chain Analysis
Rare-earth magnet processing concentration in Inner Mongolia and Jiangxi Province directly determines where margin pools accumulate downstream, with permanent magnet synchronous motor producers capturing value while brushed motor fabricators face cost compression.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates NMPA-certified brushless configurations for medical devices from commodity brushed units for home appliances, with certification grade and volume scale as primary drivers. Cost compression in the brushed motor tier is intensifying because electronic commutation complexity remains above price tolerance for automotive auxiliary applications. Appliance OEMs in Zhejiang and Jiangsu exhibit highest price sensitivity, while robotics integrators in Guangdong demonstrate lowest sensitivity due to positioning accuracy requirements.
Supply Chain Analysis
Neodymium and dysprosium feedstock draws from China, Myanmar, and Australia, with magnet alloy processing concentrated in Baotou and Ganzhou. Raw material dependencies include rare-earth oxides, silicon steel laminations, and copper winding wire. Single-source vulnerability in heavy rare-earth sourcing creates structural risk under dual carbon processing quotas. Distribution runs through Guangdong and Zhejiang port clusters serving coastal OEMs and export manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brushless motor architectures are displacing brushed systems across China's industrial base, with MIIT efficiency mandates accelerating technology refresh cycles in state-backed manufacturing zones.
For Market Incumbents: Pre-empt margin erosion in the brushed motor segment by accelerating backward integration into captive magnet processing operations in Inner Mongolia. Defend servo system market share by bundling predictive maintenance software with motion control hardware, countering discrete motor suppliers attempting to unbundle procurement. Certification investment in NMPA electromagnetic compatibility testing creates switching costs against emerging brushless entrants targeting surgical robot platforms.
For New Entrants and Emerging Players: Mid-market industrial equipment in Shandong and Sichuan-Chongqing represents the most penetrable entry point, where GB standards phase-out timelines create compliance-driven replacement demand. Zhejiang-Jiangsu appliance corridors offer second-mover advantage as coastal OEMs seek EU-compliant alternatives for export-bound shipments. Go-to-market positioning should emphasize SAMR product safety alignment as a regulatory tailwind for cross-border medical device supply chains.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision foundries in the Pearl River Delta lacking integrated drive electronics capability. Long-term viability favors targets with servo-drive convergence technology and established automotive tier-one supplier relationships. Monitor NMPA-SAMR compliance synchronization timelines as an inflection indicator for diagnostic equipment motor demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Processing | Captive rare-earth supply insulates margin stability against dual carbon quota volatility. |
| Servo-Drive System Integration | Bundled motion control software captures system-level value from robotics OEMs in Guangdong. |
| NMPA Certification Investment | Electromagnetic compatibility approval creates barriers for surgical robot motor competitors. |
| Coastal Low-Voltage Capacity Expansion | Dedicated appliance motor production serves Zhejiang-Jiangsu export corridors under SAMR alignment. |
| Automotive Tier-One Partnership | Powertrain integration agreements with Guangdong OEMs secure volume commitments for brushless traction motors. |
Research Methodology
Initial hypotheses were tested against primary input from motor procurement managers at automotive tier-one suppliers, robotics OEM technical directors, appliance manufacturing engineers, and rare-earth processing operators, then refined against MIIT regulatory filings, SAMR certification databases, customs trade statistics, and SEC filings from listed motor manufacturers. Bottom-up production capacity estimates from Pearl River Delta and Yangtze River Delta foundries were triangulated against top-down demand projections from industrial automation and electric vehicle powertrain forecasts.
Demand-supply balance modeling across the analysis window incorporated voltage rating segmentation, application-specific duty cycles, and end-user certification requirements. CAGRs were derived from installed base replacement rates under GB energy-efficiency mandates and electric vehicle production ramp schedules. Industry-specific inputs included neodymium price elasticity coefficients and NMPA approval timeline distributions for medical device motors.
Practitioners should monitor rare-earth processing quota adjustments and NMPA-SAMR regulatory convergence for early signals of forecast revision. Cross-checking against MIIT industrial motor procurement statistics and automotive OEM powertrain sourcing disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Middle East and Africa Electric Drives Market
Electrical Equipment
Passover Humidifiers Market
Electrical Equipment
Motor Control Centers (MMC) Market
Electrical Equipment
Earth Leakage Circuit Breakers Market
Electrical Equipment
Current Clamps Market
Electrical Equipment
Pad-Mounted Transformer Market
Electrical Equipment
High Voltage Electric Insulators Market
Electrical Equipment
Cable Distribution Cabinets Market
Electrical Equipment
North America Circuit Breakers Market
Electrical Equipment
Saudi Arabia Electric Motor Market
Electrical Equipment
Asia-Pacific Electrical Bushing Market
Electrical Equipment
HID Ballast Market
Electrical Equipment
High Voltage Electric Capacitor Market
Electrical Equipment
Portable Misting Fans Market
Electrical Equipment
Fiberglass Electrical Enclosure Market
Electrical Equipment
DC Contactor Market