
 South America Feed Palatability Enhancers Market | 2026-2036
South America Feed Palatability Enhancers Market Size, Share, and Industry Trends Forecast 2026-2036
South America Feed Palatability Enhancers Market Analytics
Market Context
The South America feed palatability enhancers market is rebalancing between premium natural-extract formulations and commodity-grade synthetic flavoring tiers, with ingredient costs and export compliance requirements splitting buyer budgets along quality lines. Kemin Industries Inc leverages its vertically integrated botanical supply chain to anchor premium positioning across Brazilian poultry integrators. DuPont competes through microbial fermentation expertise that sustains consistent sweetener output for large-scale swine operations. Adisseo differentiates via methionine-adjacent palatability systems that dominate ruminant feed channels in Argentina and Uruguay.
Technical Definition and Segment Structure
Feed palatability enhancers comprise sensory-active additives—flavoring agents, sweeteners, amino acid profiles, and natural extracts—formulated at inclusion rates between 0.01% and 0.5% to stimulate voluntary feed intake, mask bitter pharmacological residues, and stabilize consumption patterns across species. Powder and liquid forms lead volume throughput due to blending compatibility with standard feed mill equipment, while granular and pellet forms capture premium margins in aquaculture and specialty diet applications where leaching resistance determines efficacy. Poultry and swine end-user segments absorb the majority of flavoring agent and sweetener volumes, whereas aquaculture demand tilts toward natural extract formulations as export-oriented Chilean salmon producers face escalating EU residue scrutiny.
Regulatory Framework and Outlook
ANVISA coordinates with Brazil's Ministry of Agriculture to enforce maximum residue limits and Good Manufacturing Practice standards for feed additives, directly shaping product registration timelines and import substitution patterns across the Mercosur trade zone. Argentina's National Service for Agri-Food Health and Quality and Chile's Agricultural and Livestock Service impose parallel certification requirements that fragment compliance costs for multinational suppliers. Stakeholders must monitor the divergence between Mercosur harmonization talks and individual country residue protocols when allocating R&D spending across natural versus synthetic formulation platforms.
Market Dynamics
ANVISA's tightening residue protocols are compressing synthetic flavoring margins while redirecting R&D budgets toward botanical extraction capabilities across Brazilian feed manufacturing corridors.
Growth Catalysts
- ANVISA Residue Protocols:Brazil's pharmaceutical regulator mandates stricter maximum residue limits, accelerating formulator migration toward natural extract alternatives that command premium positioning.
- Poultry Integration Density:High-density operations across São Paulo and Minas Gerais states drive systematic adoption of sweetener-enhanced rations to stabilize feed conversion ratios under heat stress conditions.
- Mercosur Export Alignment:Harmonized veterinary drug standards across Argentina, Brazil, and Uruguay create cross-border demand for palatability systems that mask pharmacological bitterness without triggering EU border rejections.
Market Restraints
- Botanical Input Volatility:Stevia and monk fruit extract prices fluctuate with harvest cycles in Paraguay and southern Brazil, compressing gross margins for natural-formulation specialists.
- Import Dependency Concentration:Synthetic flavoring precursors concentrate through Argentine petrochemical corridors, exposing Brazilian formulators to peso-dollar volatility and cross-border logistics friction.
- Extraction Yield Ceiling:Cold-press and CO2 supercritical extraction methods for citrus and herbaceous derivatives face inherent throughput limits that constrain scale economies below synthetic alternatives.
Strategic Opportunities
- Uruguayan Ruminant Channel:Underpenetrated beef feedlot operations present white space for methionine-adjacent palatability systems that improve roughage acceptance in backgrounding diets.
- EU Green Deal Alignment:Export-oriented Chilean salmon producers face escalating residue scrutiny, creating demand for natural extract formulations that satisfy Brussels certification requirements.
- Direct Mill Integration:Bypassing traditional distributor networks through embedded technical service teams at major Brazilian integrators captures margin and locks in formulation specifications.
Industry Challenges
- Phytochemistry Talent Scarcity:Formulation teams lack sufficient expertise in botanical standardization and terpene stability, slowing natural product development cycles.
- Dual Registration Burden:Separate ANVISA and Ministry of Agriculture approval pathways extend product commercialization timelines and multiply compliance documentation costs.
- Legacy Equipment Incompatibility:Older feed mills in Argentina's interior lack precision liquid application systems, limiting adoption of advanced emulsion-based flavoring technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Feed Palatability Enhancers Market |
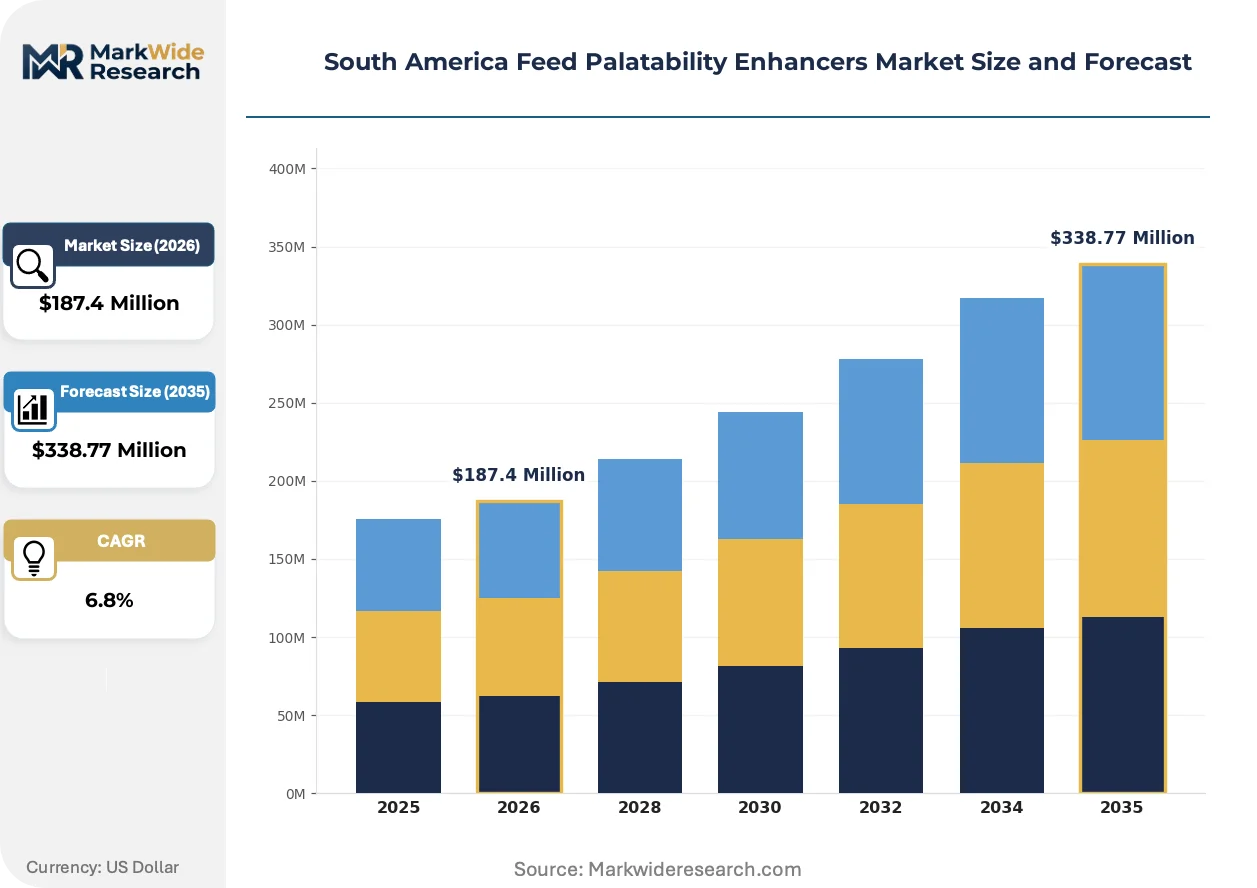
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amino Acids, Flavoring Agents, Sweeteners, Natural Extracts End User: Poultry, Swine, Ruminants, Aquaculture Application: Livestock Feed, Aquatic Feed, Pet Feed, Specialty Diets Form: Liquid, Powder, Granular, Pellet |
| Companies Covered | Kemin Industries Inc, DuPont, Adisseo, Diana Group, Kerry Group plc, Pancosma, Kent Nutrition Group, Symrise AG, Associated British Foods plc, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Feed Palatability Enhancers Market Evolving Landscape
Formulation science is pivoting from synthetic masking agents toward bioactive botanical matrices that deliver palatability alongside functional gut health benefits.
Encapsulated terpene complexes derived from Brazilian citrus and Amazonian botanicals are expanding into poultry and swine premix applications. Major integrators in São Paulo state trial these systems at inclusion rates below 0.1% to achieve heat-stable flavor release. This technology is expanding into aquaculture feed channels where leaching resistance determines pond-side efficacy.
ANVISA's coordination with MAPA on Good Manufacturing Practice enforcement creates compliance differentiation between registered and gray-market additives. Facilities lacking certified quality systems face registration suspension, channeling procurement toward established suppliers with documented traceability. Argentine and Uruguayan regulators are adopting parallel certification frameworks, fragmenting multinational compliance architectures.
Buyer concentration among Brazil's top ten poultry integrators compresses supplier negotiation cycles and unbundles technical service from product pricing. Procurement teams now separate flavoring compound costs from on-farm application support, pressuring mid-tier formulators to demonstrate measurable feed intake improvements or face volume displacement. This pattern concentrates most visibly in Minas Gerais state where three processors account for regional sweetener demand.
South America Feed Palatability Enhancers Market Segmentation
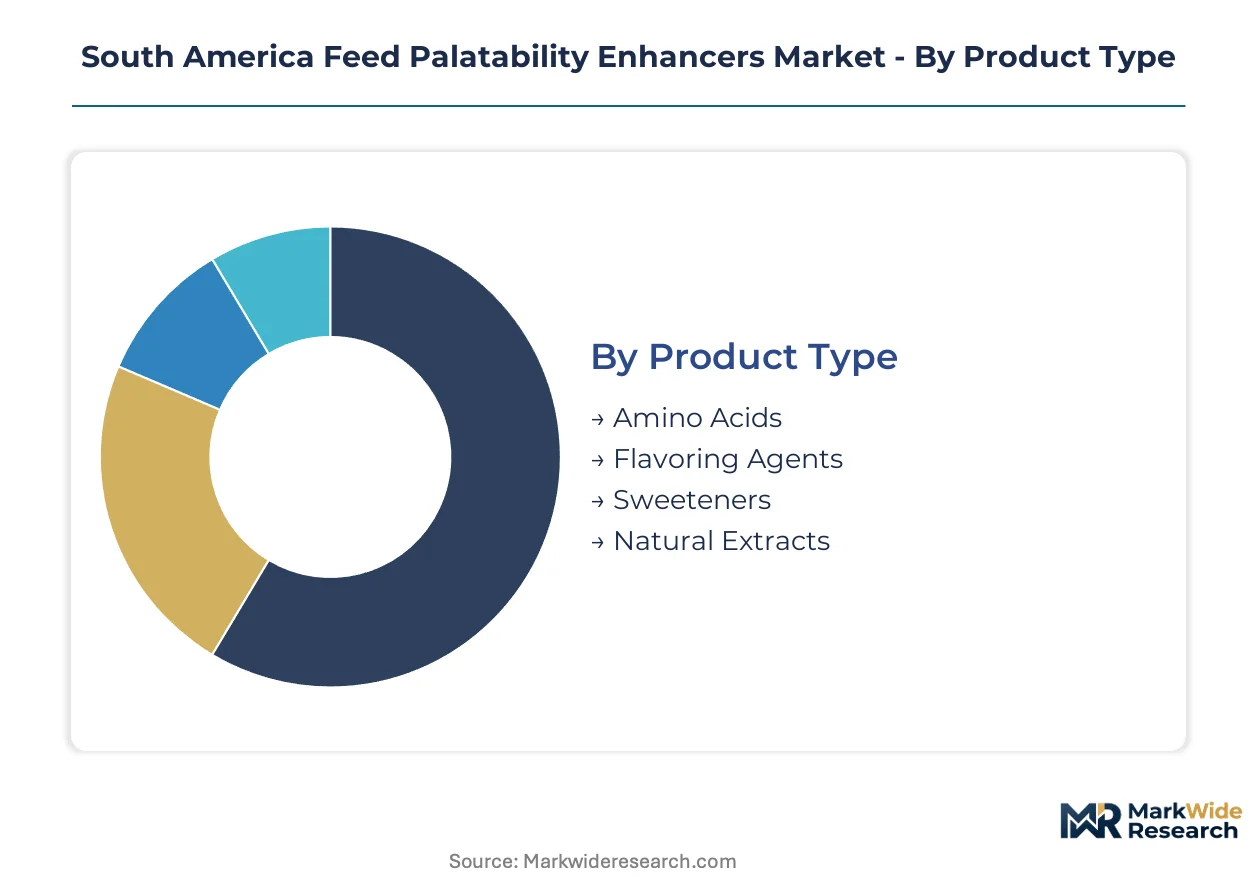
Feed palatability enhancers in South America fragment across four critical dimensions that determine formulation economics and procurement patterns. Product chemistry dictates regulatory pathway and margin structure, while end-user species concentration shapes volume contracts with Brazilian integrators. Application context and physical form further stratify pricing tiers based on mill equipment compatibility and export compliance requirements.
Product Type:
Buyer procurement teams split budgets between synthetic commodity tiers and premium natural-extract positions based on ANVISA residue scrutiny and export destination requirements.
- Flavoring Agents:Synthetic and natural aromatic compounds formulated at 0.01-0.1% inclusion to mask pharmacological bitterness and standardize intake across batches. Demand concentrates in São Paulo poultry corridors where heat-stressed birds reject unpalatable rations. ANVISA's tightening maximum residue limits are compressing synthetic margins while redirecting volumes toward botanical alternatives.
- Sweeteners:High-intensity compounds including saccharin, neohesperidin dihydrochalcone, and stevia derivatives that trigger cephalic phase digestive responses. Swine operations across Minas Gerais and Paraná states absorb the majority of volumes as integrators optimize feed conversion ratios in high-density finishing barns. Stevia harvest volatility in Paraguay creates periodic supply squeezes.
- Amino Acids:Methionine-adjacent palatability systems that improve roughage acceptance in ruminant backgrounding diets. Argentine and Uruguayan beef feedlots represent the primary demand channel.
- Natural Extracts:Cold-pressed citrus terpenes and Amazonian botanical matrices delivering dual-function palatability and gut health benefits. Chilean salmon producers facing EU residue scrutiny drive premium positioning.
Flavoring agents lead on scale; natural extracts lead on momentum.
End User:
Species-specific digestive physiology and production intensity determine inclusion rate economics and formulation complexity.
- Poultry:Broiler and layer operations across Brazil's southeastern feed manufacturing corridor absorb the majority of flavoring agent and sweetener volumes. Heat stress conditions in São Paulo state drive systematic adoption of palatability-enhanced rations to stabilize voluntary intake.
- Swine:Finishing operations in Minas Gerais and Santa Catarina states prioritize sweetener systems that accelerate weight gain through improved feed conversion ratios. Large-scale integrators unbundle technical service from product pricing.
- Ruminants:Argentine and Uruguayan beef feedlots present underpenetrated white space for methionine-adjacent systems that improve roughage acceptance during backgrounding phases.
- Aquaculture:Chilean salmon producers facing escalating EU Green Deal residue scrutiny demand natural extract formulations with documented traceability and leaching resistance in pond-side applications.
Poultry dominates current procurement volumes; aquaculture offers the steepest expansion trajectory.
Application:
Regulatory jurisdiction and export compliance tier split the market between commodity livestock channels and certified specialty positions.
- Livestock Feed:Standard rations for poultry, swine, and cattle operations across Mercosur trade zone. ANVISA and MAPA dual registration requirements extend commercialization timelines.
- Aquatic Feed:Salmon and shrimp diets where EU border rejection risk concentrates demand on natural-extract formulations with certified residue profiles.
- Pet Feed:Premium companion animal nutrition representing niche volume but highest margin per kilogram inclusion.
- Specialty Diets:Medicated feeds and organic-certified rations requiring masking systems that satisfy multiple regulatory frameworks simultaneously.
Livestock feed anchors volume scale; specialty diets capture premium pricing expansion.
Form:
Mill equipment vintage and blending precision requirements determine physical specification adoption across Brazilian manufacturing corridors.
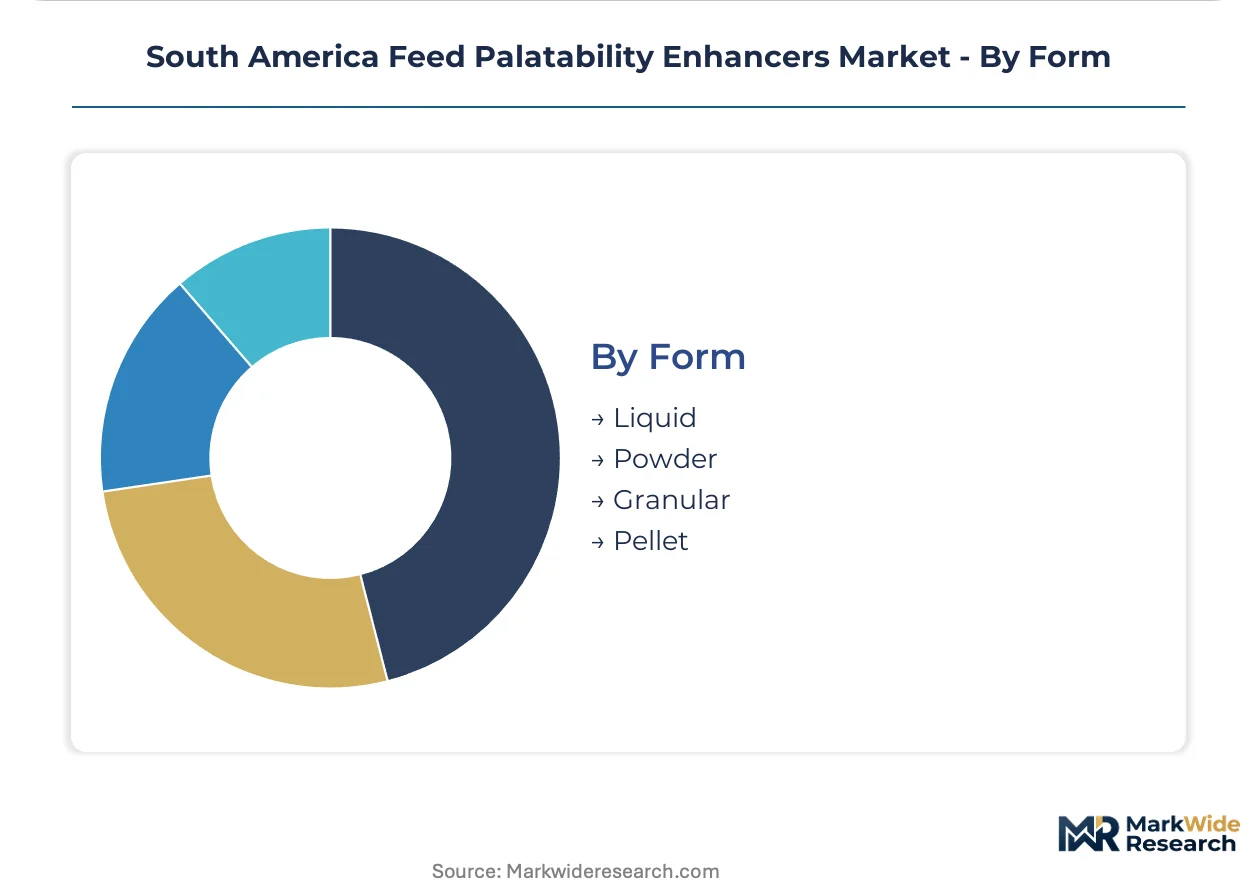
- Powder:Fine-ground formulations compatible with standard feed mill mixing equipment. Dominates volume throughput in legacy facilities across Argentina's interior.
- Liquid:Emulsion-based systems requiring precision application equipment. São Paulo integrators with modern mills adopt these for uniform distribution and heat-stable release profiles.
- Granular:Coated particles with leaching resistance for aquaculture and specialty diet applications where pond-side efficacy determines value capture.
- Pellet:Compressed forms for premium aquaculture and export-oriented channels demanding extended stability in storage and transport.
Powder leads on installed base compatibility; liquid forms gain share fastest among capital-upgrading integrators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists and feed mill engineers concentrate across Brazil's southeastern manufacturing corridor, anchoring regional technical capacity and shaping procurement patterns throughout the continent.
Brazil
Poultry integrators in São Paulo and Minas Gerais states drive systematic sweetener adoption to stabilize feed conversion ratios under heat stress conditions. ANVISA coordinates with MAPA to enforce Good Manufacturing Practice standards that channel procurement toward certified suppliers. The feed manufacturing corridor spanning Campinas to Uberlândia absorbs the majority of flavoring agent volumes as three processors consolidate regional demand.
Argentina
Beef feedlot operations in Buenos Aires and Córdoba provinces present underpenetrated demand for methionine-adjacent palatability systems that improve roughage acceptance. The National Service for Agri-Food Health and Quality imposes residue certification requirements that fragment compliance costs for imported formulations. Petrochemical corridors around Bahía Blanca concentrate synthetic flavoring precursor production, exposing formulators to peso-dollar volatility.
Chile
Salmon producers in Los Lagos and Aysén regions face escalating EU Green Deal residue scrutiny, redirecting volumes toward natural extract formulations with documented traceability. The Agricultural and Livestock Service enforces parallel certification frameworks that extend product registration timelines. Puerto Montt anchors aquaculture feed manufacturing, where leaching-resistant granular forms capture premium positioning.
Uruguay
Backgrounding operations in Paysandú and Florida departments represent white space for palatability-enhanced beef diets that improve weight gain consistency. Mercosur harmonization talks with Brazil and Argentina create cross-border regulatory alignment opportunities. The country's smaller feed mill base limits adoption of precision liquid application systems found in Brazilian facilities.
Paraguay
Stevia cultivation in Caazapá and Itapúa departments supplies raw material for natural sweetener formulations across the southern cone. Harvest volatility creates periodic supply squeezes that compress margins for extraction specialists. Asunción-based traders coordinate botanical shipments to Brazilian formulators, though infrastructure constraints limit scale economies.
South America Feed Palatability Enhancers Market Competitive Landscape
Capital-heavy producers with captive botanical supply chains compete with asset-light formulators that source extracts through third-party agreements. The market structures around three tiers: multinational ingredient suppliers with Mercosur-wide registration portfolios, regional specialists focused on single-country compliance, and commodity traders supplying synthetic precursors through Argentine petrochemical channels. Consolidation pressures intensify as Brazilian poultry integrators unbundle technical service from product pricing, forcing mid-tier players toward specialty aquaculture or ruminant niches. Dominant competitive moves include backward integration into stevia and citrus cultivation, plus embedded technical service teams at major integrator mills.
Among multinational suppliers, Kemin Industries Inc exemplifies the vertically integrated archetype through its botanical supply chain control, while DuPont occupies a position emphasizing microbial fermentation consistency for large-scale swine operations. Adisseo represents the methionine-adjacent specialization vector that dominates Argentine and Uruguayan ruminant channels.
| Leading Market Players |
|---|
| Kemin Industries Inc |
| DuPont |
| Adisseo |
| Diana Group |
| Kerry Group plc |
| Pancosma |
| Kent Nutrition Group |
| Symrise AG |
| Associated British Foods plc |
| Others |
Value Network & Pricing Analysis
Encapsulated terpene extraction technology is compressing synthetic flavoring margins while concentrating procurement leverage among Brazilian poultry integrators with capital-upgrading feed mills. This production-method transition simultaneously elevates natural-extract price premiums and fragments supply chains between certified botanical suppliers and gray-market synthetic traders.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive positioning across São Paulo and Minas Gerais feed manufacturing corridors. Three-tier pricing structure across premium, standard, and economy levels separates ANVISA-certified natural extracts from commodity synthetic flavorings and unregistered gray-market alternatives. Price differentiation hinges on certification grade and volume scale, with large integrators extracting technical service unbundling to drive cost compression in standard tiers. Pricing pressure stems from stevia harvest volatility in Paraguay, compressing margins for natural-formulation specialists. Small-scale Argentine feedlots exhibit highest price sensitivity; Chilean salmon exporters facing EU residue scrutiny show least.
Supply Chain Analysis
Workforce availability constraints in Campinas-Uberlândia manufacturing clusters and Puerto Montt aquaculture corridors are elevating automation premiums and channeling investment toward precision liquid application systems. Supply concentrates in Brazil, Argentina, and Paraguay, with raw material dependencies spanning stevia leaf, citrus terpenes, and synthetic petrochemical precursors from Bahía Blanca corridors. Single-source vulnerability runs through Paraguayan stevia harvest cycles, exposing formulators to periodic supply squeezes. Distribution runs through embedded technical service teams at major Brazilian integrators, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Brazil's tightening ANVISA residue protocols and Argentina's lagging enforcement timelines, creating cost and compliance differentials for cross-border formulation strategies.
For Market Incumbents: Hedge synthetic flavoring margin erosion by accelerating backward integration into stevia cultivation in Caazapá and citrus terpene extraction in São Paulo state. Prioritize ANVISA-MAPA dual registration completion before Argentine regulators adopt parallel certification frameworks, locking in channel access before compliance costs fragment.
For New Entrants and Emerging Players: The premium-economy price-point gap in ruminant feed channels creates entry space for methionine-adjacent palatability systems targeting Uruguayan and Argentine beef feedlots. Target underpenetrated backgrounding operations in Paysandú and Florida departments with direct mill integration models that bypass established distributor relationships.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier formulators lacking captive botanical supply chains but holding Mercosur-wide registration portfolios. Long-term viability over the coming decade hinges on natural-extraction capability buildout. Monitor ANVISA-MAPA harmonization velocity as the critical inflection signal for consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stevia Cultivation | Captures margin from Paraguayan harvest volatility while securing ANVISA-compliant natural extract supply. |
| Embedded Technical Service Teams | Locks formulation specifications at São Paulo poultry integrators by bypassing traditional distributor networks. |
| Dual ANVISA-MAPA Registration Completion | Preempts compliance fragmentation as Argentine and Uruguayan regulators adopt parallel certification frameworks. |
| Precision Liquid Application System Deployment | Enables heat-stable emulsion-based flavoring adoption at capital-upgrading Brazilian feed mills. |
| Leaching-Resistant Granular Form Development | Captures premium positioning in Chilean salmon channels facing escalating EU Green Deal residue scrutiny. |
Research Methodology
Coverage spans Brazil, Argentina, Chile, Uruguay, and Paraguay, with primary inputs from each market gathered through structured interviews with feed mill operations directors, poultry integrator procurement heads, botanical extraction specialists, ANVISA regulatory affairs consultants, and Argentine petrochemical procurement managers. Secondary validation drew from ANVISA registration databases, MAPA Good Manufacturing Practice enforcement records, Mercosur trade flow statistics, and EU border rejection incident reports. Bottom-up volume modeling triangulated against top-down value estimates across natural extract and synthetic formulation tiers.
Granularity-level modeling deployed product chemistry, end-user species, application context, and physical form as core segmentation dimensions, with additional cross-cutting analysis of ANVISA certification status and export destination compliance tiers. CAGRs across the analysis window derived from weighted average of historical trajectory momentum and policy-driven inflection assumptions. Forecast inputs incorporated stevia harvest cycle patterns, heat stress frequency projections for southeastern Brazil poultry corridors, and EU Green Deal implementation velocity for Chilean salmon channels.
Caveats apply where ANVISA-MAPA regulatory divergence, Paraguayan stevia crop failure, or EU residue limit tightening could materially shift the outlook. Forecasts embed assumptions about Mercosur harmonization progress and extraction yield improvements that may not materialize. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Crumb Softener Market
Food Enhancers and Additives
Asia-Pacific Flavor Enhancer Market
Food Enhancers and Additives
Spain Food Flavor and Enhancer Market
Food Enhancers and Additives
Trans-Resveratrol Market
Food Enhancers and Additives
Emulsion Stabilizer for Beverages Market
Food Enhancers and Additives
Kaempferol Market
Food Enhancers and Additives
Flavonoid Phytogenic Feed Additive Market
Food Enhancers and Additives
Raising Agents Market
Food Enhancers and Additives
Food Thickening Agents Market
Food Enhancers and Additives
Australia Food Flavor and Enhancer Market
Food Enhancers and Additives
Africa Water Enhancer Market
Food Enhancers and Additives
Mexico Water Enhancer Market
Food Enhancers and Additives
Cake Softener Market
Food Enhancers and Additives
Thaumatin Market
Food Enhancers and Additives
Isomalt Market
Food Enhancers and Additives
North America Food Thickeners Market