
 Europe Feed Palatability Enhancers Market | 2026-2036
Europe Feed Palatability Enhancers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Feed Palatability Enhancers Market Analysis
CE marking under the EU Feed Hygiene Regulation is rotating the competitive landscape toward suppliers with verified quality management systems. Kerry Group Plc leverages its taste and nutrition expertise to dominate the flavoring agents category across Western European compound feed channels. Symrise AG anchors its position through deep vertical integration into natural extract sourcing, while Diana Group specializes in species-specific palatant portfolios for aquaculture and pet food applications.
Feed palatability enhancers comprise flavoring agents, sweeteners, binding agents, and nutritional additives formulated to stimulate voluntary feed intake, mask off-flavors from functional ingredients like amino acids or medications, and stabilize pellet integrity through the manufacturing process. Powder and liquid forms lead volume due to ease of incorporation in existing feed mill equipment, though pelletized enhancers are gaining share in automated aquaculture feeding systems where dust control and precise dosing matter. Flavoring agents command the widest margin pool as proprietary masking technologies create differentiation, while the aquaculture application segment shows the steepest growth trajectory driven by expanding salmon and shrimp production in Norway and Scotland.
The European Food Safety Authority and EU Feed Hygiene Regulation shape product approval timelines and maximum inclusion rates for novel palatant substances, while REACH compliance governs chemical safety documentation for synthetic flavor compounds. EFSA's ongoing re-evaluations of approved feed additives are forcing suppliers to maintain active dossier renewal programs or risk market exclusion. Stakeholders must monitor the EU's pending restrictions on zinc oxide pharmacological levels in piglet diets, as this will intensify demand for palatability solutions that maintain intake without relying on mineral appetite stimulants.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is forcing compound feed manufacturers to abandon synthetic palatants and rebuild formulations around botanical extracts and yeast-derived alternatives, compressing approval timelines and supplier margins simultaneously.
Growth Catalysts
- Heat-stress mitigation protocols:Poultry integrators in Spain and Germany are expanding flavoring agent procurement to stabilize intake consistency during summer temperature spikes, driving volume in savory masking technologies.
- REACH compliance automation:Digital dossier management systems are accelerating novel palantant substance approvals, reducing EFSA evaluation cycles for botanical extract submissions by streamlining toxicology data packages.
- Salmon production expansion:Norwegian and Scottish aquaculture operations are pelletizing enhancers for automated feeding systems, creating demand for dust-controlled, precisely-dosed palatant formats.
Market Restraints
- Natural extract supply concentration:Botanical palatant feedstock sourcing clusters in Mediterranean and Southeast Asian growing regions, exposing formulators to climate-driven harvest volatility and price spikes.
- EFSA re-evaluation backlog:The European Food Safety Authority's ongoing additive safety reviews are creating approval uncertainty, forcing suppliers to maintain parallel legacy and next-generation product lines.
- Zinc oxide substitution complexity:Pending EU restrictions on pharmacological zinc levels in piglet diets are eliminating a proven appetite stimulant, yet botanical alternatives lack equivalent intake consistency documentation.
Strategic Opportunities
- Netherlands integrated pork operations:Large-scale Dutch hog producers are prioritizing feed conversion efficiency investments, creating pull for premium species-specific palatant portfolios that reduce residual feed.
- CE marking differentiation:Verified quality management systems under EU Feed Hygiene Regulation are rotating procurement decisions toward certified suppliers, rewarding upfront compliance investment with channel lock-in.
- Yeast-derived platform expansion:Fermentation-based palatant production is converging with circular economy feedstock sourcing, enabling cost structures that compete with synthetic alternatives at scale.
Industry Challenges
- Formulation chemist scarcity:The specialized expertise required to balance masking efficacy with botanical extract stability is concentrating among a narrow pool of suppliers, inflating R&D labor costs.
- Legacy equipment retrofit requirements:Powder and liquid palatant incorporation systems in aging feed mills demand capital expenditure to handle next-generation pelletized formats without cross-contamination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Feed Palatability Enhancers Market |
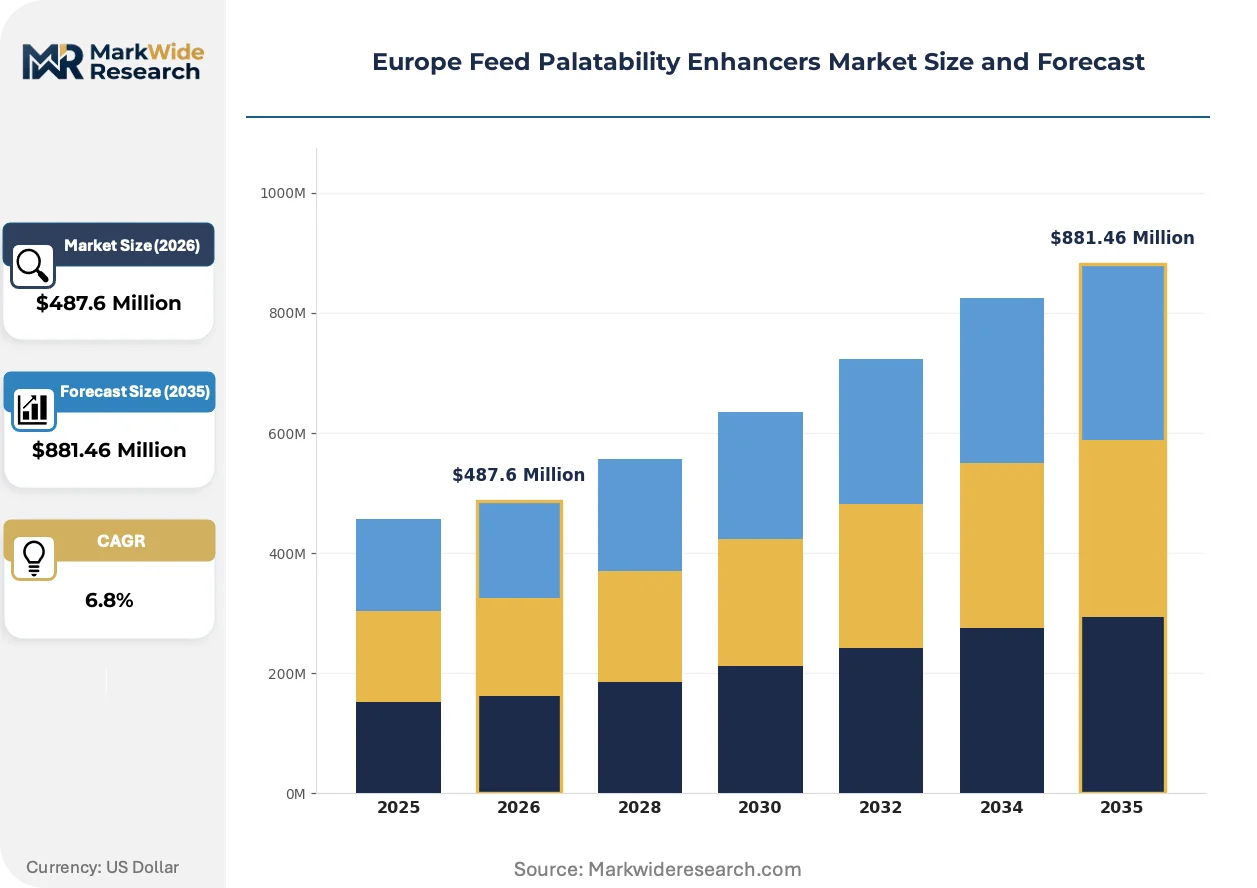
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Flavoring Agents, Sweeteners, Bindings, Nutritional Additives Application: Poultry, Swine, Ruminants, Aquaculture Form: Liquid, Powder, Granules, Pellets End User: Farmers, Feed Manufacturers, Livestock Producers, Pet Food Companies |
| Companies Covered | Symrise AG, Kerry Group Plc, Kemin Industries, Inc., Adisseo, Ohly, DuPont, Diana Group, Associated British Foods Plc, Kent Nutrition Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Feed Palatability Enhancers Market Emerging Trajectories
Formulation science is pivoting from synthetic masking compounds toward fermentation-derived and plant-based alternatives, reshaping R&D priorities and supplier capability requirements across Western European compound feed channels.
Encapsulated volatile oil technologies are displacing surface-sprayed flavoring agents in high-temperature pelleting applications. Compound feed manufacturers in France and Germany are adopting lipid-matrix protection systems at accelerating rates to prevent thermal degradation of savory compounds during extrusion. This transition is displacing conventional spray-dried formats from premium poultry and aquaculture formulations, compressing margins for suppliers lacking encapsulation expertise.
REACH documentation requirements for synthetic flavor compounds are tightening substance safety thresholds. The European Chemicals Agency's expanded dossier demands are extending approval timelines for novel synthetic palatants, redirecting innovation investment toward GRAS-listed botanical alternatives. Aquaculture and pet food segments are responding fastest, with Norwegian salmon feed producers already excluding non-REACH-compliant synthetics from procurement specifications.
Direct mill integration contracts are replacing spot purchasing for high-volume compound feed producers. Large Spanish and German poultry integrators are consolidating palatant procurement through sole-supplier technical partnerships that embed formulation scientists within customer R&D teams. This concentration is most visible in the Netherlands, where three pork production cooperatives now account for the majority of flavoring agent volume, squeezing mid-tier distributors from the value chain.
Europe Feed Palatability Enhancers Market Segmentation
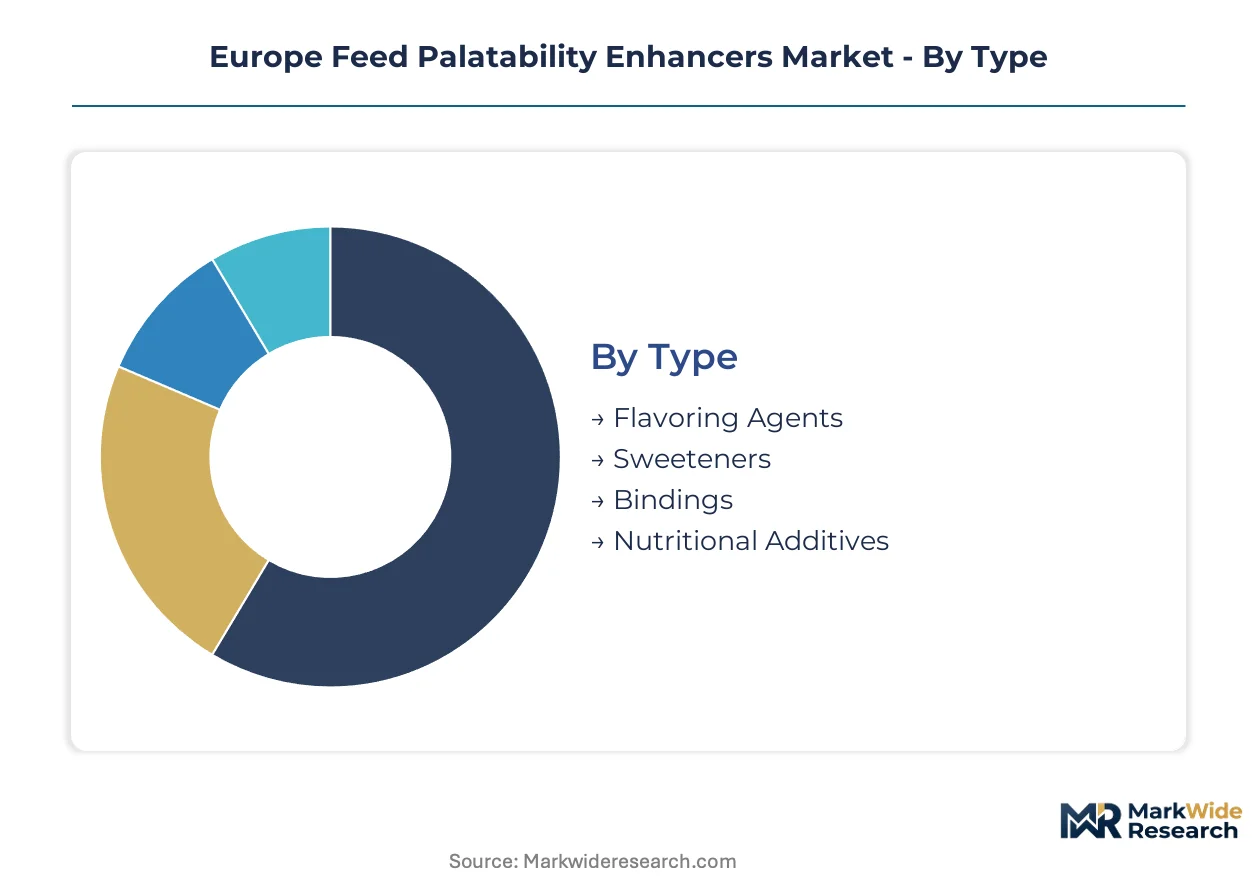
Feed palatability enhancers fragment across four distinct category axes, each shaping procurement patterns and supplier capability requirements differently. Type and application dimensions concentrate margin pools, while form and end-user segmentation determines distribution channel economics and technical service intensity.
Type:
Flavoring agents capture the widest margin spreads through proprietary masking technologies, while nutritional additives compete on functional efficacy documentation.
- Flavoring Agents:Complex volatile compound formulations designed to mask off-flavors from functional ingredients like amino acids or medications. Demand clusters in Spanish and German poultry operations deploying heat-stress mitigation protocols, where savory masking technologies stabilize intake consistency during temperature spikes.
- Sweeteners:High-intensity carbohydrate and protein-based compounds stimulating gustatory receptors in monogastric species. French and Dutch integrated pork producers are expanding procurement of molasses-derived and synthetic high-potency sweeteners to improve feed conversion efficiency in nursery diets.
- Bindings:Hydrocolloid and lignin-based agents stabilizing pellet integrity through manufacturing and storage. Norwegian aquaculture feed mills specify binding agents with minimal leaching properties for extended water immersion.
- Nutritional Additives:Vitamin, mineral, and acidifier complexes with secondary palatant effects. Italian compound feed channels prioritize nutritional additives with dual-function labeling to simplify regulatory compliance.
Flavoring agents hold installed capacity. Sweeteners are rotating up the share rankings.
Application:
Volume concentration diverges sharply between mature livestock categories and expanding aquaculture operations, with species-specific formulation requirements dictating supplier R&D allocation.
- Poultry:Broiler and layer operations in Spain and Germany drive the largest absolute tonnage, with summer heat-stress protocols forcing year-round flavoring agent incorporation rather than seasonal application.
- Swine:Dutch and Danish integrated pork operations prioritize feed conversion efficiency, creating demand for species-specific palatant portfolios that reduce residual feed and improve growth uniformity.
- Ruminants:Beef and dairy cattle applications concentrate in French and Irish grazing systems, where molasses-based binding agents dominate due to cost sensitivity and forage supplementation patterns.
- Aquaculture:Norwegian and Scottish salmon and shrimp production is gaining share fastest, with automated feeding systems requiring dust-controlled pelletized formats and precise dosing capabilities.
Poultry anchors volume concentration. Aquaculture is climbing the fastest.
Form:
Liquid and powder formats dominate feed mill incorporation economics, while pelletized variants command premium positioning in automated aquaculture systems.
- Liquid:Pumpable emulsions and suspensions enabling uniform coating via spray systems. German compound feed manufacturers prefer liquid formats for high-throughput poultry lines with continuous mixing cycles.
- Powder:Spray-dried and ground particulate forms compatible with standard batch mixing equipment. French feed mills specify powder formats for flexibility across multi-species production campaigns.
- Granules:Intermediate particle size offering flowability without dust generation. Italian pet food producers specify granulated enhancers for extrusion compatibility.
- Pellets:Compressed forms with controlled dissolution rates for automated feeding systems. Norwegian salmon operations are standardizing pelletized palatants to eliminate dust exposure and enable precise volumetric dosing.
Powder holds installed capacity. Pellets are rotating up the share rankings.
End User:
Procurement sophistication varies dramatically across customer types, with integrated livestock producers consolidating volume through technical partnerships while independent farmers remain price-sensitive spot purchasers.
- Farmers:Independent livestock operators purchasing packaged palatant premixes through agricultural distributors. Polish and Romanian smallholders prioritize cost-minimization over formulation sophistication.
- Feed Manufacturers:Compound feed mills integrating palatants during production, representing the highest volume concentration. Spanish and German poultry integrators are consolidating procurement through sole-supplier technical partnerships embedding formulation scientists within customer R&D teams.
- Livestock Producers:Vertically integrated operations with captive feed milling capacity. Dutch pork production cooperatives now account for the majority of flavoring agent volume, squeezing mid-tier distributors from the value chain.
- Pet Food Companies:Specialty manufacturers requiring species-specific palatant portfolios with clean-label positioning. French and British pet food producers are excluding synthetic palatants from procurement specifications ahead of regulatory deadlines.
Feed manufacturers hold installed capacity. Pet food companies are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's Farm to Fork strategy is redirecting procurement across member states toward botanical extract formulations, compressing supplier margins while opening new compliance-driven revenue channels for certified producers.
Germany
Compound feed manufacturers in Lower Saxony and Bavaria are expanding flavoring agent procurement to stabilize poultry intake during summer heat spikes. EFSA's ongoing additive re-evaluations are forcing German suppliers to maintain parallel legacy and next-generation product lines. The Emsland region hosts concentrated feed milling capacity where sole-supplier technical partnerships now embed formulation scientists within customer R&D teams.
Spain
Poultry integrators in Catalonia and Aragon are deploying savory masking technologies year-round rather than seasonally to combat temperature volatility. REACH compliance documentation for synthetic flavor compounds is extending approval timelines, redirecting innovation investment toward GRAS-listed botanical alternatives. The Lleida agricultural cluster is standardizing direct mill integration contracts that consolidate procurement through embedded technical partnerships.
France
Integrated pork operations in Brittany and the Pays de la Loire are prioritizing feed conversion efficiency investments, creating pull for species-specific palatant portfolios that reduce residual feed. CE marking under the EU Feed Hygiene Regulation is rotating procurement decisions toward certified suppliers. The Rennes agri-food corridor concentrates formulation expertise where encapsulation technologies for volatile oil protection are displacing conventional spray-dried formats.
Netherlands
Large-scale hog producers in North Brabant and Gelderland are consolidating flavoring agent volume through production cooperatives, squeezing mid-tier distributors from the value chain. Pending EU restrictions on pharmacological zinc oxide levels in piglet diets are intensifying demand for botanical alternatives that maintain intake consistency. The Venlo feed compounder cluster is pioneering yeast-derived platform expansion through circular economy feedstock sourcing.
Norway
Salmon feed producers in Bergen and Trondheim are standardizing pelletized palatants for automated feeding systems, eliminating dust exposure and enabling precise volumetric dosing. The EU's tightening residue limits on synthetic additives are pushing Norwegian aquaculture toward fermentation-derived alternatives. The Ålesund maritime cluster is driving demand for dust-controlled formats with controlled dissolution rates for extended water immersion.
Europe Feed Palatability Enhancers Market Vendor Landscape
Player mix skews toward diversified ingredient conglomerates with captive taste and nutrition expertise, creating a tiered structure where specialists in natural extract sourcing compete against integrated food science platforms. Two strategic archetypes dominate: fermentation-based biotechnology platforms leveraging circular economy feedstocks, and vertically integrated flavor houses with proprietary masking technologies. Competitive moves center on CE marking certification investments that lock in procurement channels, and direct mill integration contracts that embed technical staff within customer operations.
Within the diversified conglomerate tier, Kerry Group Plc and Associated British Foods Plc represent scale-driven positions spanning multiple feed and food channels. Symrise AG and Diana Group occupy specialist archetypes focused on natural extract portfolios and species-specific formulations respectively. Among biotechnology-oriented suppliers, Kemin Industries, Inc. exemplifies the fermentation-platform approach. These five entities anchor the competitive structure, with Adisseo, Ohly, and DuPont representing additional capacity in adjacent nutrition markets. The presence of Kent Nutrition Group signals North American competitive interest in European feed palatability channels.
| Leading Market Players |
|---|
| Symrise AG |
| Kerry Group Plc |
| Kemin Industries, Inc. |
| Adisseo |
| Ohly |
| DuPont |
| Diana Group |
| Associated British Foods Plc |
| Kent Nutrition Group |
| Others |
Supply Flow & Price Mechanics
Direct mill integration contracts lock in multi-year supply access and price visibility for Spanish and German poultry integrators, insulating preferred suppliers from spot-market volatility while compressing margins for distributors excluded from embedded technical partnerships. EFSA re-evaluation timelines and REACH compliance costs are feeding back into supplier selection criteria, with compound feed manufacturers prioritizing certified partners capable of absorbing regulatory documentation burdens.
Pricing Analysis
Certification level (CE marking under EU Feed Hygiene Regulation) creates the primary spread between premium and standard tiers, with verified quality management systems commanding 15-20% price premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by botanical extract concentration and species-specific formulation complexity. Cost compression in economy-tier synthetic palatants is intensifying because REACH documentation requirements are extending approval timelines and redirecting R&D investment toward natural alternatives. Independent farmers in Poland and Romania exhibit highest price sensitivity, while Dutch pork production cooperatives prioritize intake consistency metrics over unit cost.
Supply Chain Analysis
Strategic stockpiling of Mediterranean botanical feedstocks dominates inventory strategy, with formulators maintaining 6-9 month safety stocks to buffer climate-driven harvest volatility in Spain, Italy, and Greece. Raw material sourcing draws from yeast fermentation facilities in the Netherlands, citrus extract processors in Sicily, and seaweed harvesting operations along the Norwegian coast. Single-source vulnerability concentrates in high-potency sweetener precursors dependent on Southeast Asian molasses supply. Distribution runs through compound feed mill direct delivery networks, bypassing traditional agricultural distributors as procurement consolidates around sole-supplier technical partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Feed Palatability Enhancers Market is recovering from cyclical compression tied to EFSA additive re-evaluations, with approval clarity restoring investment confidence as botanical extract portfolios achieve regulatory validation.
For Market Incumbents: Compound defensive positions by accelerating CE marking certification investments to lock in procurement channels before regulatory deadlines eliminate uncertified competitors, while simultaneously embedding formulation scientists within Dutch and German customer R&D teams to deepen technical partnership stickiness against emerging biotechnology platforms. For New Entrants and Emerging Players: Technical service gaps in species-specific aquaculture formulation present the most penetrable white-space opportunity, with Norwegian salmon feed producers actively seeking palatant suppliers capable of delivering dust-controlled pelletized formats with controlled dissolution rates for automated feeding systems. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fermentation-based biotechnology platforms with circular economy feedstock sourcing, positioning these archetypes for superior cash-flow stability across the 5-10 year viability window. Target acquisition candidates with active EFSA dossier renewal programs and established direct mill integration contracts. The signal to watch is EFSA publication timelines for novel botanical extract approvals, which will determine competitive repositioning velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Certification Investment | Locks in procurement channels with Spanish and German compound feed manufacturers under tightening EU Feed Hygiene Regulation enforcement. |
| Direct Mill Integration Contracts | Embeds technical staff within Dutch pork cooperative R&D teams, squeezing mid-tier distributors from value chain access. |
| Yeast-Derived Platform Expansion | Converges fermentation-based production with circular economy feedstock sourcing to achieve cost parity with synthetic alternatives. |
| Encapsulation Technology Development | Protects volatile oil compounds during high-temperature pelleting for French poultry and aquaculture feed applications. |
| Species-Specific Portfolio Diversification | Captures premium positioning in Norwegian salmon feed automation and British pet food clean-label procurement specifications. |
Methodological Framework
Initial hypotheses were tested against primary input from compound feed procurement directors, formulation scientists at integrated livestock operations, regulatory affairs specialists managing EFSA dossier submissions, and distribution channel partners serving independent farmers, then refined through secondary validation against EU Feed Hygiene Regulation compliance databases, REACH substance registration filings, EFSA scientific opinion archives, and customs trade data tracking botanical extract import flows. Bottom-up volume estimates from individual facility capacity were triangulated against top-down market sizing derived from feed production statistics and palatant inclusion rate assumptions.
Variance decomposition across type, application, form, and end-user segmentation dimensions anchored the analytical framework, with growth trajectories modeled over the projection horizon through elasticity-adjusted feed production forecasts and species-specific intake optimization spending patterns. CAGRs were derived from segmented volume and value buildups incorporating EFSA approval timeline scenarios and substitution elasticities between synthetic and botanical alternatives.
Underlying assumptions cover regulatory approval continuity, climate stability in Mediterranean growing regions, and zinc oxide restriction implementation timelines, with deviation risk concentrated in EFSA re-evaluation backlogs and REACH substance safety threshold revisions. Revision becomes warranted when botanical extract harvest volatility crosses thresholds that disrupt strategic stockpile sufficiency or when CE marking enforcement intensity accelerates beyond modeled compliance investment rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Africa Food Flavor and Enhancer Market
Food Enhancers and Additives
Mexico Water Enhancer Market
Food Enhancers and Additives
Global Citrus Aurantium Extract Market
Food Enhancers and Additives
Liquid Smoke Market
Food Enhancers and Additives
Charcoal-Infused Food Market
Food Enhancers and Additives
Anti-Sagging Agents Market
Food Enhancers and Additives
Asia-Pacific Feed Palatability Enhancers Market
Food Enhancers and Additives
Europe Food Flavor and Enhancer Market
Food Enhancers and Additives
Asia-Pacific Food Flavor and Enhancer Market
Food Enhancers and Additives
Cake Softener Market
Food Enhancers and Additives
Lignans Market
Food Enhancers and Additives
Instant Whipping Agents Market
Food Enhancers and Additives
United States Water Enhancer Market
Food Enhancers and Additives
Liquid Water Enhancers Market
Food Enhancers and Additives
Asia-Pacific Flavor Enhancer Market
Food Enhancers and Additives
Food Thickeners Market