
 Trimethylcyclohexanone Market | 2026-2036
Trimethylcyclohexanone Market Size, Share, and Industry Trends Forecast 2026-2036
Trimethylcyclohexanone Market Analytics
REACH chemical registration is realigning the cost-of-entry calculus for European trimethylcyclohexanone suppliers, forcing reformulation investments ahead of 2025 renewal deadlines. BASF SE leverages its Ludwigshafen integrated aromatics complex to sustain captive feedstock advantages across ketone derivative chains. Asahi Kasei Corporation anchors its position through membrane-based purification technology that competes on pharmaceutical-grade specifications. Domo Chemicals specializes in nylon intermediate applications, occupying a narrow but defensible niche in polyamide 6,6 precursor supply.
Trimethylcyclohexanone is a cyclic ketone with three methyl substituents on a six-membered ring, typically existing as a colorless to pale yellow liquid with characteristic camphor-like odor and boiling points ranging from 198°C to 205°C depending on isomeric distribution; manufacturers produce it via catalytic hydrogenation of trimethylphenol or oxidation of trimethylcyclohexanol for use as a specialty solvent, chemical intermediate in vitamin E synthesis, and coalescing agent in high-solids coatings. Solvent-grade material leads volume consumption across the product-type spectrum, though pharmaceutical-intermediate specifications command premium pricing due to residual impurity limits below 50 ppm. Paints and coatings end-use demand concentrates in automotive refinish and industrial maintenance segments, while plastics applications in polycarbonate processing additives represent the fastest-expanding consumption pool.
The European Chemicals Agency enforces REACH registration and SVHC candidate-list screening that shapes import compliance costs for Asian producers serving EU coating-formulator customers. China's Ministry of Ecology and Environment implements GB standard revisions for volatile organic compound content in industrial solvents, directly affecting formulation thresholds for domestic adhesive and coating applications. India's Central Pollution Control Board mandates solvent-recovery obligations under revised hazardous-waste rules that alter operating economics for small-batch chemical processors. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation tailoring or unified product-platform strategies offer superior returns.
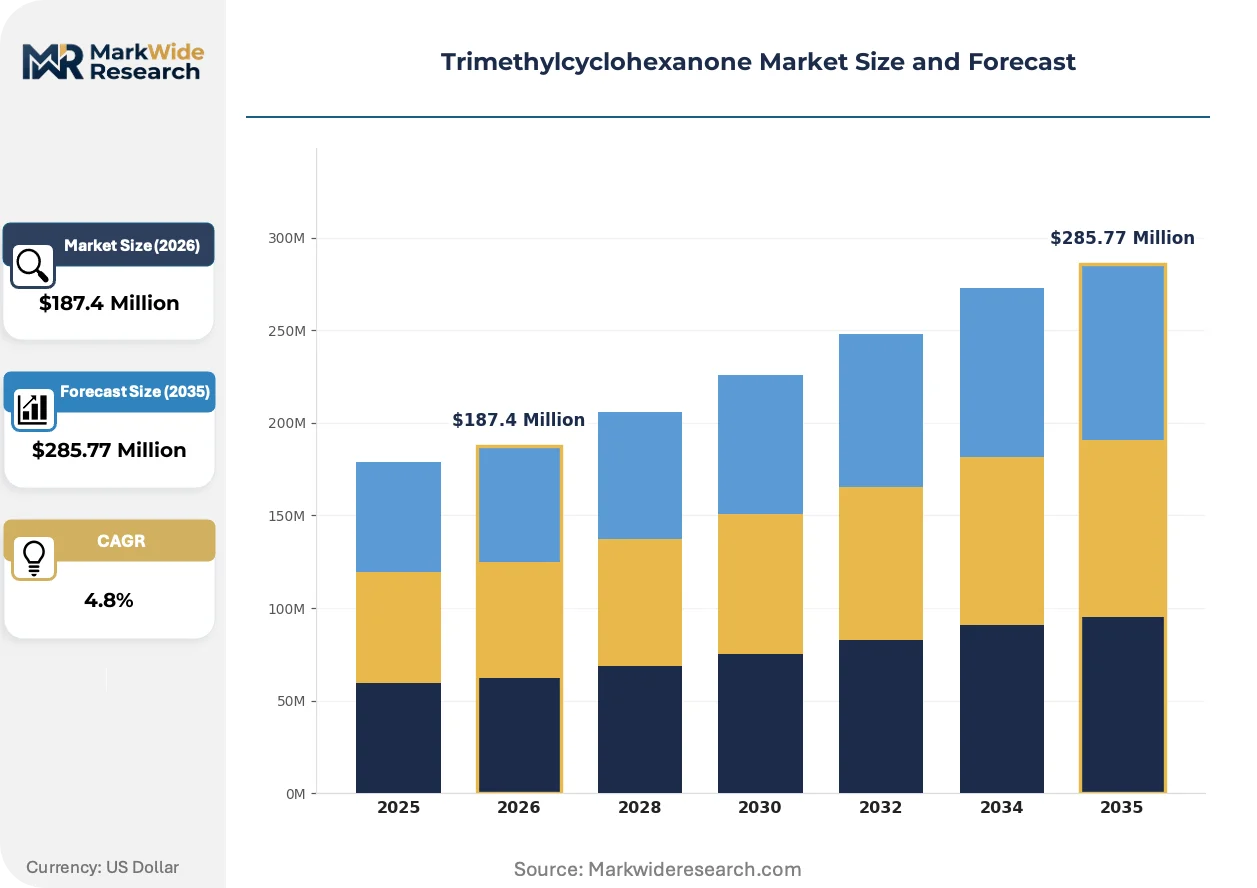
Market Dynamics
REACH registration deadlines are forcing European trimethylcyclohexanone suppliers to reconfigure purification trains ahead of 2025 renewal cycles, while coating formulators simultaneously demand lower-VOC solvent systems. This dual pressure is compressing margins for non-integrated producers and rewarding those with captive hydrogenation capacity.
Growth Catalysts
- Automotive refinish coatings:OEM solvent reformulation programs are absorbing higher volumes of trimethylcyclohexanone as a coalescing agent in high-solids systems. Collision repair networks in Germany and the United States are specifying this ketone for improved flow characteristics.
- GB standard revisions:China's Ministry of Ecology and Environment tightened VOC thresholds for industrial solvents, accelerating domestic substitution toward compliant ketone intermediates. Local adhesive manufacturers are retooling formulation lines.
- Membrane purification:Pharmaceutical-grade specifications below 50 ppm residual impurities are creating demand pull for advanced separation technology. Vitamin E synthesis circuits require this purity tier.
Market Restraints
- Feedstock volatility:Trimethylphenol hydrogenation feedstock tracks aromatics complex pricing, exposing non-integrated producers to naphtha-derived cost swings. Ludwigshafen and Rotterdam pricing benchmarks transmit directly to ketone margins.
- Asian supply concentration:Solvent-grade material production clusters in Shandong and Jiangsu provinces, creating single-geography risk for European coating formulators dependent on import flows.
- Cyclohexanone substitution:General-purpose solvent applications face displacement from methyl isobutyl ketone in cost-sensitive industrial maintenance coatings.
Strategic Opportunities
- India solvent recovery:Central Pollution Control Board mandates under revised hazardous-waste rules are creating aftermarket service demand. Equipment providers can attach recovery-unit contracts to ketone supply agreements.
- Polycarbonate processing additives:Plastics applications represent underdeveloped consumption relative to coatings. Polymerization circuit integration offers specification premium capture.
- EU Green Deal chemistry:Renewable feedstock certification pathways for bio-based trimethylcyclohexanone are opening preferential procurement channels. Mass-balance accounting methods enable premium positioning.
Industry Challenges
- Catalytic hydrogenation expertise:Selective hydrogenation of trimethylphenol isomers requires specialized reactor engineering. Talent scarcity in continuous-flow catalysis limits capacity expansion timelines.
- REACH dossier maintenance:Substance data gap closure for toxicological endpoints demands sustained toxicology investment. Small-batch processors face disproportionate compliance cost burdens.
- Isomer separation complexity:Mixed isomer feeds require fractional distillation trains with tight temperature control. Capital intensity for pharmaceutical-grade specification lines exceeds solvent-grade economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trimethylcyclohexanone Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent Grade, Chemical Intermediate, Coating Agent, Adhesive End Use Industry: Automotive, Paints & Coatings, Pharmaceuticals, Plastics Form: Liquid, Powder, Crystalline, Emulsion Packaging Type: Drum, Tanker, Bottle, Bulk |
| Companies Covered | BASF SE, Asahi Kasei Corporation, Domo Chemicals, UBE INDUSTRIES, LTD., TPCC, Fibrant, Qingdao Hisea Chem Co., Ltd, Shreeji Chemical, Shandong Haili Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trimethylcyclohexanone Market Evolving Landscape
Membrane-based purification systems are displacing conventional distillation in high-specification segments, while regulatory chemistry is tightening across major manufacturing jurisdictions. Formulation science is simultaneously pulling toward lower-VOC and higher-performance solvent systems.
Membrane separation technology is converging with continuous-flow reactor design to enable pharmaceutical-grade trimethylcyclohexanone production at scale. Asahi Kasei and specialized engineering firms are deploying ceramic membrane modules that cut energy intensity versus thermal separation. This convergence is compressing the cost gap between solvent-grade and high-purity specifications, enabling broader access to vitamin E synthesis and fragrance intermediate markets.
REACH SVHC candidate-list screening is expanding compliance documentation burdens for ketone derivatives entering European coating supply chains. The European Chemicals Agency's 2024-2025 substance evaluation wave targets residual phenolic impurities in hydrogenation feeds. Importers from China and India are responding by investing in third-party analytical certification and pre-shipment testing protocols to avoid customs detention.
Automotive OEM procurement teams are consolidating approved solvent lists and demanding lifecycle VOC documentation from coating suppliers. Tier-1 refinish material providers are shifting from spot purchasing toward annual framework contracts with certified ketone producers. This concentration is most visible in Germany, where KBA type-approval requirements for refinish systems create specification lock-in effects.
Trimethylcyclohexanone Market Segmentation
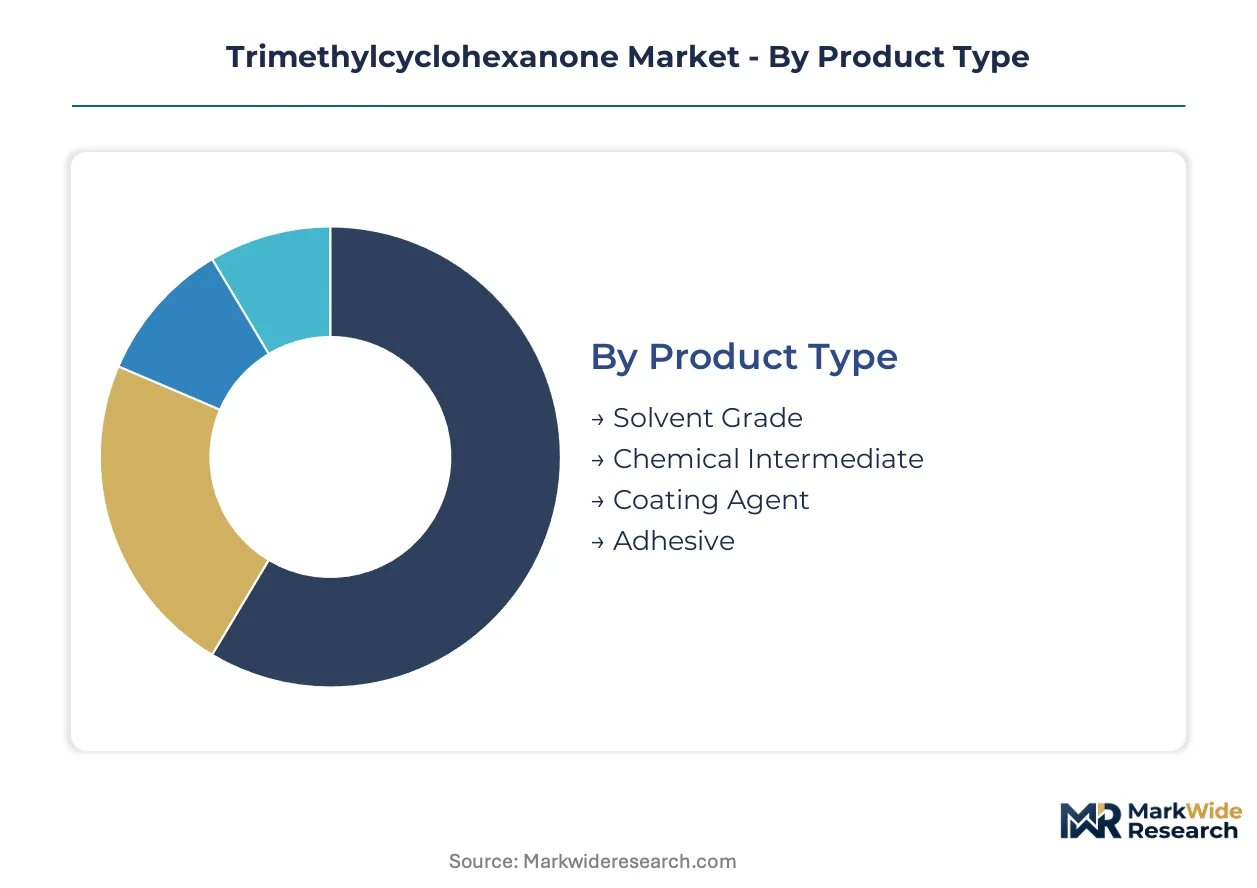
Trimethylcyclohexanone demand fragments across specification tiers that command radically different margin profiles. Buyers sort primarily by purity thresholds and regulatory certification requirements rather than commodity pricing.
Product Type:
Purchasing decisions pivot on whether the application tolerates residual aromatic impurities or demands sub-50 ppm specifications.
- Solvent Grade:Contains mixed isomer distributions with residual phenolic content up to 500 ppm. Automotive refinish coating formulators in Germany and the United States absorb the largest volumes for high-solids system coalescence.
- Chemical Intermediate:Purified to 99.5% minimum assay for vitamin E synthesis and fragrance precursor circuits. Pharmaceutical manufacturers in Switzerland and Japan specify this tier for synthetic tocopherol production.
- Coating Agent:Modified with flow-control additives for direct incorporation into industrial maintenance formulations. Demand concentrates among marine and protective coating specialists requiring improved substrate wetting.
- Adhesive:Lower-purity material serving hot-melt and pressure-sensitive tape manufacturers. China's domestic adhesive sector retooling under GB standard revisions is pulling incremental volumes.
Solvent Grade leads on scale; Chemical Intermediate leads on momentum.
End Use Industry:
Application selection determines whether suppliers compete on throughput economics or technical service intensity.
- Automotive:OEM refinish programs specify certified ketone lots with full REACH documentation. KBA type-approval requirements in Germany create specification lock-in for approved suppliers.
- Paints & Coatings:Industrial maintenance and marine protective segments dominate consumption. Formulators prioritize low-VOC compliance over unit cost in European and North American procurement.
- Pharmaceuticals:Vitamin E synthesis and synthetic fragrance intermediates require membrane-purified material. Residual impurity limits below 50 ppm command 40-60% price premiums over solvent-grade benchmarks.
- Plastics:Polycarbonate processing additives represent the most steeply expanding consumption pool. Polymerization circuit integration offers specification premium capture for integrated producers.
Paints & Coatings leads on scale; Plastics leads on momentum.
Form:
Physical state selection constrains logistics infrastructure and handling equipment requirements.
- Liquid:Standard delivery form for solvent-grade and coating-agent specifications. Tanker and drum distribution networks favor liquid material for coating formulator just-in-time delivery.
- Powder:Spray-dried crystalline material for adhesive hot-melt compounding. Reduced shipping costs versus liquid offset higher production energy intensity for long-haul supply.
- Crystalline:High-purity solid for pharmaceutical intermediate applications. Swiss and Japanese synthetic vitamin E producers specify crystalline feedstock for reactor charging precision.
- Emulsion:Water-dispersed form for low-VOC coating formulations. Waterborne adhesive manufacturers in China's Jiangsu province are testing emulsion compatibility.
Liquid leads on scale; Emulsion leads on momentum.
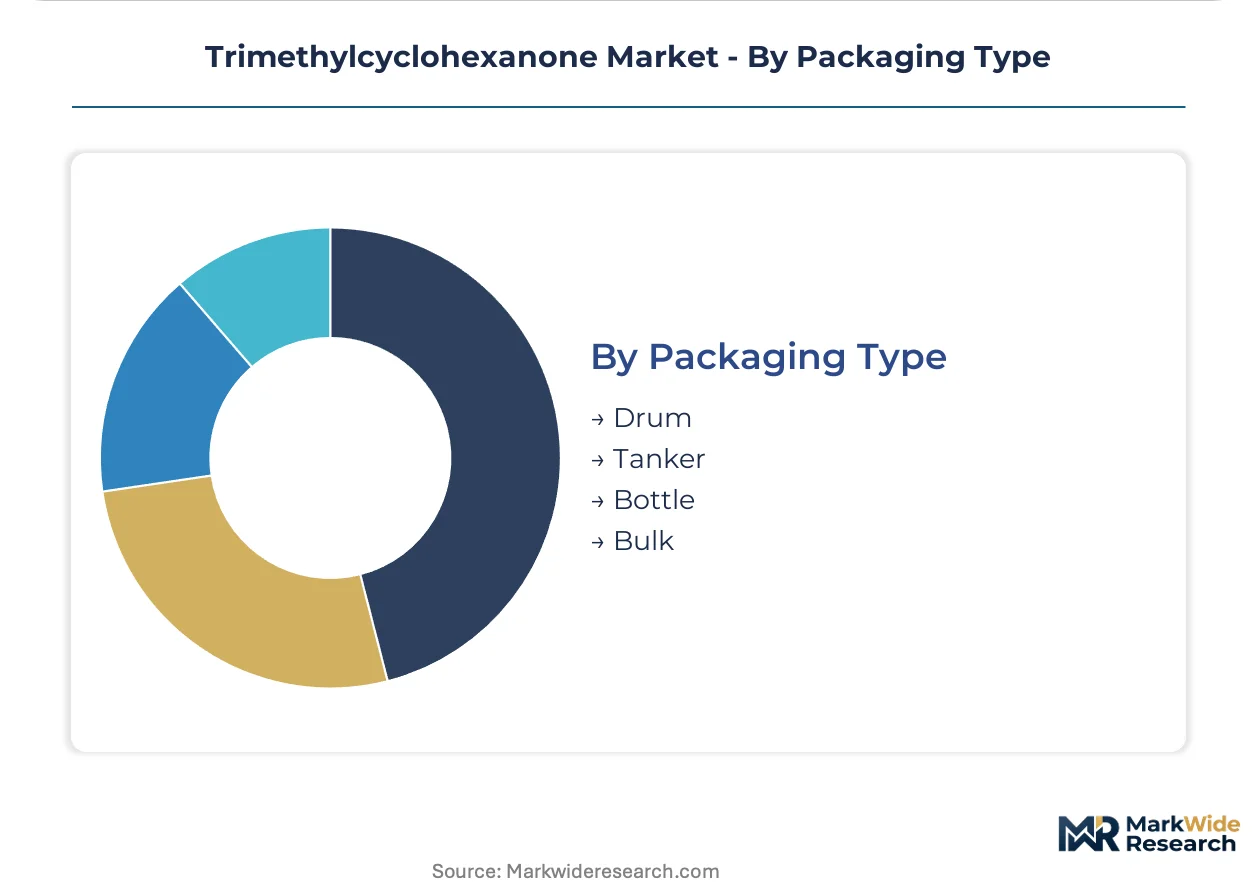
Packaging Type:
Container selection reflects order scale, inventory turnover, and hazardous material handling capabilities.
- Drum:200-liter steel drums dominate mid-volume coating formulator procurement. German and US collision repair networks specify drum quantities for regional distribution depot stocking.
- Tanker:Bulk liquid delivery for integrated automotive OEM coating operations. Ludwigshafen and Rotterdam aromatics complex proximity enables tanker economics for large European consumers.
- Bottle:Laboratory and pilot-scale quantities for pharmaceutical process development. Swiss fragrance houses and Japanese vitamin researchers specify amber glass for light-sensitive material.
- Bulk:Railcar and iso-tank shipments for solvent-grade material to adhesive compounders. Shandong and Jiangsu province producers favor bulk export to minimize per-unit logistics burden.
Drum leads on scale; Bulk leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Catalytic hydrogenation specialists cluster near Ludwigshafen, Shandong, and Gujarat, anchoring regional production networks. Regulatory divergence between ECHA, MEE, and CPCB compliance frameworks fragments formulation strategies across manufacturing jurisdictions.
Germany
Automotive refinish coating formulators in Stuttgart and Munich absorb solvent-grade volumes for high-solids OEM programs. ECHA REACH renewal deadlines force purification train investments ahead of 2025 substance evaluation cycles. BASF's Ludwigshafen aromatics complex sustains captive feedstock integration across ketone derivative chains.
China
Domestic adhesive manufacturers in Jiangsu province retool formulation lines under tightened GB standard VOC thresholds. MEE enforcement of volatile organic compound limits accelerates substitution toward compliant ketone intermediates. Shandong province production clusters supply solvent-grade material for polymerization circuits across the Yangtze River Delta.
United States
Collision repair networks specify trimethylcyclohexanone for improved flow characteristics in industrial maintenance coatings. EPA oversight of hazardous air pollutant emissions shapes solvent system reformulation timelines. Gulf Coast petrochemical corridors provide naphtha-derived feedstock access for non-integrated hydrogenation operators.
India
Small-batch chemical processors in Gujarat face altered operating economics under CPCB solvent-recovery mandates. Central Pollution Control Board hazardous-waste rules create aftermarket equipment demand attached to ketone supply contracts. Maharashtra-based pharmaceutical intermediate users specify membrane-purified material for vitamin E synthesis circuits.
Switzerland
Synthetic tocopherol producers require crystalline feedstock with residual impurity limits below 50 ppm. Swissmedic oversight of pharmaceutical-grade chemical intermediates mandates third-party analytical certification protocols. Basel-area fragrance houses anchor demand for high-purity ketone derivatives in specialty chemical applications.
Trimethylcyclohexanone Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across specification tiers. Market structure tilts toward consolidated capacity at the solvent-grade volume end and fragmented specialty production at pharmaceutical-grade purity thresholds. Three archetypes dominate: integrated aromatics complexes with captive hydrogenation, membrane-technology purifiers serving life-science specifications, and regional solvent distributors with formulation-tailoring capabilities. Capacity expansion and strategic partnerships represent the dominant competitive moves, with backward integration into trimethylphenol feedstock gaining traction among margin-pressured operators.
Among European integrated chemical producers, BASF SE exemplifies the diversified conglomerate archetype with Ludwigshafen-based captive supply chains. Asahi Kasei Corporation represents the technology-specialist tier, occupying a position defined by membrane-based purification capabilities. Domo Chemicals sits within the focused intermediate supplier category, exemplifying narrow-but-defensible niche positioning in polyamide precursor markets. These three anchors illustrate how competitive advantage fragments across feedstock integration, separation technology, and application-specific formulation expertise.
| Leading Market Players |
|---|
| BASF SE |
| Asahi Kasei Corporation |
| Domo Chemicals |
| UBE INDUSTRIES, LTD. |
| TPCC |
| Fibrant |
| Qingdao Hisea Chem Co., Ltd |
| Shreeji Chemical |
| Shandong Haili Chemical Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Captive hydrogenation capacity at Ludwigshafen and Shandong province anchors supply positions and pricing power for integrated aromatics producers serving European coating formulators. Non-integrated operators face margin compression from feedstock volatility and REACH compliance investments, forcing tiered service bundling to retain solvent-grade accounts.
Pricing Analysis
Bundled certification-and-delivery contracts dominate pharmaceutical-grade transactions, while unbundled spot pricing persists for solvent-grade volumes to adhesive compounders. Three-tier pricing structure across pharmaceutical-intermediate, chemical-intermediate, and solvent-grade levels reflects membrane purification investment recovery and REACH dossier maintenance costs. Pricing pressure stems from methyl isobutyl ketone substitution in industrial maintenance coatings. Small-batch coating formulators in India exhibit highest price sensitivity; Swiss vitamin E producers accept premium positioning for sub-50 ppm specifications.
Supply Chain Analysis
Single-source vulnerability sits with Shandong and Jiangsu province production clusters for solvent-grade material serving European import demand. Trimethylphenol hydrogenation feedstock draws from naphtha-derived aromatics complexes in Rotterdam and Gulf Coast corridors. Tariff exposure on Chinese ketone intermediates entering EU coating supply chains threatens cost structures. Distribution runs through drum-and-tanker networks for German automotive refinish depots and bulk iso-tank shipments to Indian adhesive processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA REACH renewal deadlines and China's GB standard revisions simultaneously tighten compliance thresholds and accelerate formulation substitution cycles.
For Market Incumbents: Lock in KBA type-approval specifications for German automotive refinish networks before competitor certification investments mature. Secure backward integration into trimethylphenol feedstock to defend margins against naphtha price volatility at Rotterdam and Ludwigshafen benchmarks. Membrane purification capacity expansion in Basel-region proximity captures pharmaceutical-grade premium retention.
For New Entrants and Emerging Players: Enter via polycarbonate processing additive specifications where polymerization circuit integration remains underdeveloped relative to coatings saturation. India's Gujarat solvent-recovery equipment attachment contracts offer service-anchored market entry under CPCB hazardous-waste mandates. Emulsion-form compatibility testing with Jiangsu waterborne adhesive manufacturers provides formulation partnership pathway.
For Investors and Strategic Acquirers: Consolidation pressure builds where REACH dossier maintenance costs disproportionately burden small-batch European processors without captive hydrogenation. Five-to-ten year viability favors membrane-technology purifiers with pharmaceutical-grade certification depth over commodity solvent distributors. Watch for EU Green Deal bio-based feedstock certification adoption as margin structure inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Trimethylphenol Feedstock | Ludwigshafen aromatics complex operators secure captive supply chains against Rotterdam price volatility. |
| Membrane Purification Capacity Expansion | Asahi Kasei ceramic module deployment cuts energy intensity for pharmaceutical-grade specification capture. |
| REACH Dossier Pre-Registration Investment | Third-party toxicological endpoint closure enables continued EU coating formulator supply access. |
| Solvent Recovery Equipment Bundling | Gujarat aftermarket service contracts attach to ketone supply agreements under CPCB mandates. |
| Bio-Based Feedstock Certification Pathway | Mass-balance accounting methods open EU Green Deal preferential procurement channels for renewable ketone derivatives. |
Research Methodology
Direct dialogue with plant managers at hydrogenation facilities, procurement leads at German automotive OEM coating operations, distribution channel partners in Shandong province, and technical R&D directors at Swiss pharmaceutical intermediate users grounded qualitative assessment. Secondary validation drew from ECHA substance evaluation databases, China customs trade statistics, Cefic solvent market reports, and SEC 10-K filings of diversified chemical producers. Bottom-up capacity modeling and top-down consumption triangulation cross-verified volume estimates.
Bottom-up segment modeling across solvent-grade, chemical-intermediate, and pharmaceutical-intermediate purity tiers combined with end-use industry splits in coatings, plastics, and pharmaceutical synthesis. Regional production hub clustering around Ludwigshafen, Shandong, and Gujarat informed geographic allocation. CAGRs were derived from trend extrapolation of OEM reformulation program adoption rates and GB standard enforcement timelines. Price elasticity assumptions incorporated methyl isobutyl ketone substitution threat and REACH compliance cost pass-through.
Inputs from ECHA pre-registration filings and China MEE enforcement bulletins were available through the study window; gaps in small-batch processor operating cost disclosure introduce uncertainty bands around margin compression estimates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Chloroacetyl Chloride Market
Organic Chemicals
Oryzenin Market
Organic Chemicals
Gamma-Butyrolactone (GBL) Market
Organic Chemicals
North America Biphenyl Market
Organic Chemicals
Anthracene Market
Organic Chemicals
Ethylamine Market
Organic Chemicals
Behenyl Alcohol Market
Organic Chemicals
N-Pentane Market
Organic Chemicals
Acetic Acid Market
Organic Chemicals
Aliphatic Amines Market
Organic Chemicals
N-Hexanol Market
Organic Chemicals
Organic Hydrosols Market
Organic Chemicals
Benzyl Cyanide Market
Organic Chemicals
Isophthalic Acid Market
Organic Chemicals
2-Fluorobenzotrifluoride Market
Organic Chemicals
Global Benzoic Acid Market