
 Cyclohexanone Market | 2026-2036
Cyclohexanone Market Size, Share, and Industry Trends Forecast 2026-2036
Cyclohexanone Market Analysis
Long-term supply contracts with embedded maintenance and technical service packages is restructuring how cyclohexanone moves from producers to nylon and coating resin buyers. BASF leverages its integrated caprolactam-cyclohexanone chain across Ludwigshafen and Antwerp to sustain feedstock security for European nylon fiber customers. Sinopec dominates merchant cyclohexanone supply in East Asia through refinery-adjacent phenol and cyclohexane oxidation units.
Cyclohexanone is a six-membered cyclic ketone with a carbonyl group at the 1-position, typically produced via liquid-phase oxidation of cyclohexane or dehydrogenation of cyclohexanol, yielding a water-white to pale yellow liquid with a distinctive peppermint-like odor and a boiling point near 155 degrees Celsius. The compound serves primarily as a chemical intermediate for caprolactam and adipic acid manufacture, which together account for the vast majority of industrial consumption. Precursors for nylon production anchors volume demand, while solvent-grade material for paints and coatings competes on specification purity and volatile organic compound profiles. Intermediates for synthetic resins differentiate on peroxide specifications and color stability thresholds demanded by automotive coating formulators.
EPA oversight of hazardous air pollutant emissions from cyclohexane oxidation units shapes US plant investment decisions, while REACH registration and downstream authorization requirements in Europe filter market access for non-integrated importers. China's MEE enforces stricter volatile organic compound emission standards around petrochemical clusters, pressuring smaller oxidation units toward technology upgrades or closure. Stakeholders must weigh feedstock flexibility against regulatory compliance costs when evaluating capacity additions or retrofit commitments.
Market Dynamics
Caprolactam demand from nylon-6 fiber and resin producers is compressing cyclohexanone supply chains into refinery-adjacent oxidation clusters, privileging integrated phenol-to-ketone producers over standalone merchant suppliers.
Growth Catalysts
- Nylon-6 resin expansion in automotive:Lightweighting mandates from NHTSA are pulling caprolactam consumption upward, tightening ketone demand through the derivative chain.
- REACH authorization pathways:ECHA's streamlined intermediate registration for captive cyclohexanone users is reducing regulatory friction for integrated European producers.
- Phenol-based oxidation economics:Refinery-chemical complex integration in East Asia is lowering feedstock cost volatility for ketone output.
Market Restraints
- Cyclohexane price volatility:Crude-linked naphtha costs transmit directly to oxidation unit margins, squeezing standalone producers without phenol flexibility.
- Merchant supply concentration:Three refinery-adjacent complexes control the majority of non-captive ketone volume, creating sourcing risk for coating resin formulators.
- Adipic acid substitution pressure:Bio-based diacid development for nylon-6,6 is threatening the ketone-adipic pathway in long-cycle automotive contracts.
Strategic Opportunities
- India specialty solvent penetration:BIS certification alignment for electronics-grade ketone is opening specification-driven niches in PCB cleaning applications.
- EU Green Deal hydrogen integration:Green hydrogen retrofits for cyclohexanol dehydrogenation units are attracting transition financing for carbon-intensive ketone assets.
- Direct-to-formulator digital channels:Specialty chemical platforms are disintermediating traditional distributor networks for solvent-grade volumes below tank-car scale.
Industry Challenges
- Process control engineering scarcity:Liquid-phase oxidation expertise is concentrating among retiring specialists at legacy cyclohexane units.
- EPA NESHAP compliance timelines:Hazardous air pollutant monitoring upgrades for existing oxidation stacks require extended turnaround windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyclohexanone Market |
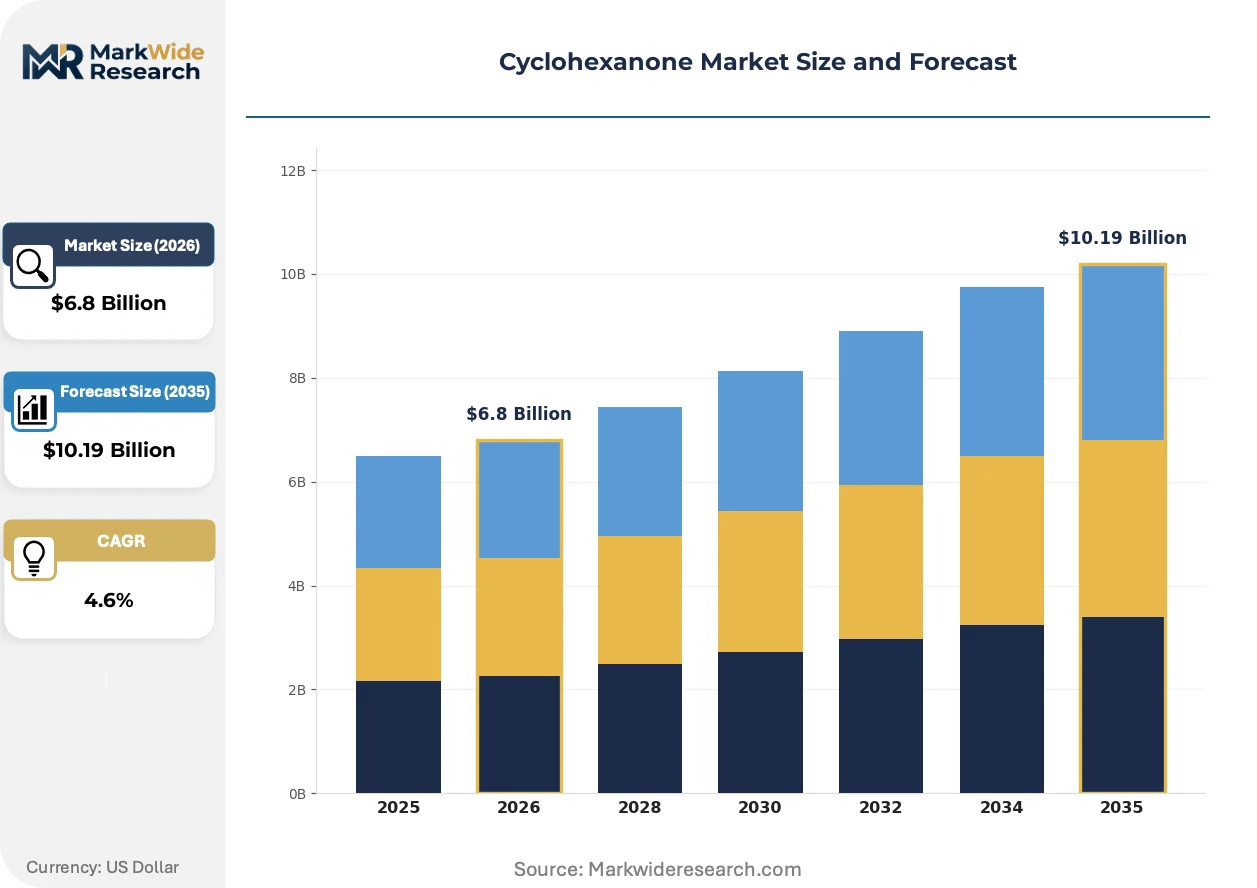
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvents, Precursors, Intermediates, Cleaning Agents End User: Chemical Manufacturing, Paints & Coatings, Adhesives, Pharmaceuticals Application: Synthetic Resins, Nylon Production, Coatings, Fuel Additives Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | BASF, Asahi Kasei Corporation, Gujarat State Fertilizers & Chemicals Limited (GSFC), Dow Chemical Company, Domo Chemicals, Sinopec Limited, Fibrant, Ostchem, Koninklijke DSM N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyclohexanone Market Emerging Trajectories
Process intensification and emissions abatement are restructuring how cyclohexanone is manufactured, distributed, and specified across end-use verticals.
Membrane-based cyclohexane oxidation is unifying reaction and separation stages into single-unit operations. Adipic acid producers in the US Gulf Coast are piloting these systems to reduce peroxide handling volumes. The technology is compressing capital intensity for mid-scale ketone-adipic integrated plants.
REACH authorization requirements for downstream users are tightening substance volume tracking across the caprolactam chain. ECHA's updated intermediate definition is forcing merchant ketone importers to register full dossiers rather than relying on upstream exemptions. Coating resin formulators in Germany and Benelux are consolidating supplier lists to reduce compliance fragmentation.
Specification-driven spot purchasing is displacing annual solvent contracts in automotive coating supply chains. Tier-1 paint suppliers are unbundling ketone volumes from broad hydrocarbon supply agreements to capture purity-grade arbitrage. This pattern is most visible in Michigan and Ohio manufacturing corridors serving Detroit-area assembly plants.
Cyclohexanone Market Segmentation
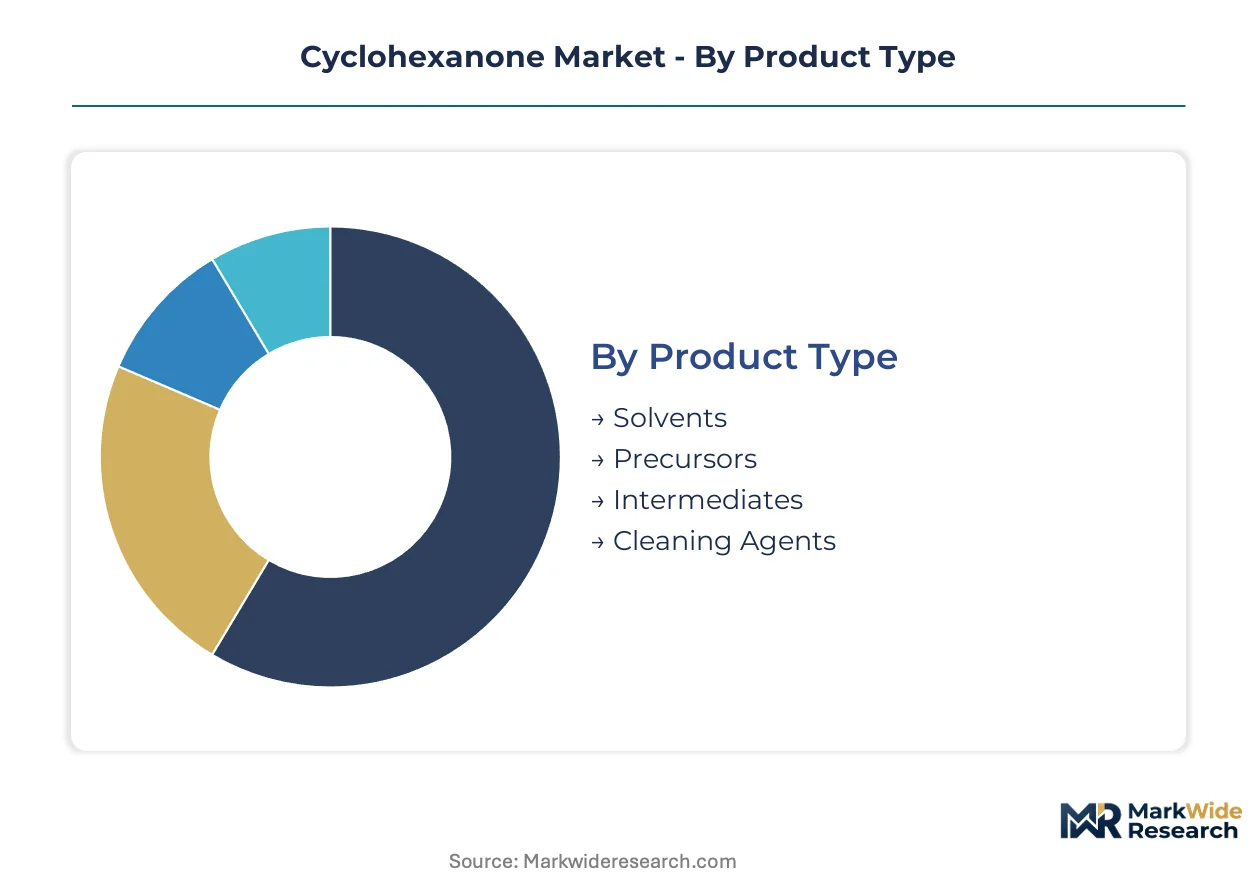
Cyclohexanone segmentation reflects divergent purity specifications between captive chemical intermediates and merchant solvent grades. Specification tiers determine pricing architecture, with automotive coating solvents commanding premium certification against standard industrial ketone.
Product Type:
Standardization dominates solvent grades while precursors and intermediates demand customer-specific peroxide and color-stability thresholds.
- Solvents:Water-white to pale yellow liquid meeting VOC emission standards for coating formulations. Demand concentrates in automotive paint supply chains across Michigan and Ohio manufacturing corridors, where EPA NESHAP compliance drives specification upgrades.
- Precursors:High-purity ketone feedstock for caprolactam and adipic acid synthesis with stringent peroxide specifications. German and Benelux coating resin formulators consolidate supplier lists to reduce REACH compliance fragmentation.
- Intermediates:Captive-grade material for nylon-6 polymerization with embedded technical service packages.
- Cleaning Agents:Electronics-grade specifications for PCB cleaning applications requiring BIS certification alignment in India.
Leading the category by volume: Precursors. Growing fastest: Cleaning Agents.
End User:
Volume concentration in chemical manufacturing contrasts with margin capture in pharmaceutical applications.
- Chemical Manufacturing:Integrated caprolactam-adipic acid producers consuming ketone through captive oxidation chains. Sinopec scales refinery-adjacent phenol and cyclohexane oxidation capacity to serve nylon-6 expansion.
- Paints & Coatings:Tier-1 automotive suppliers unbundling ketone volumes from broad hydrocarbon agreements to capture purity-grade arbitrage. Specification-driven spot purchasing displaces annual contracts in Detroit-area supply chains.
- Adhesives:Solvent-grade material competing on specification purity and volatile organic compound profiles.
- Pharmaceuticals:High-purity ketone for active pharmaceutical ingredient synthesis with documented volume tracking under REACH authorization.
Chemical Manufacturing anchors volume demand. Pharmaceuticals posts the steepest expansion trajectory.
Application:
Application segmentation tracks the nylon-6 derivative chain against dispersed solvent demand.
- Synthetic Resins:Ketone feedstock for coating resin production with color stability thresholds demanded by automotive formulators. Membrane-based oxidation pilots on the US Gulf Coast target peroxide reduction for this segment.
- Nylon Production:Caprolactam demand from fiber and resin producers compressing supply chains into refinery-adjacent oxidation clusters. NHTSA lightweighting mandates pull consumption upward through the derivative chain.
- Coatings:Solvent-grade volumes below tank-car scale moving through specialty chemical platforms disintermediating traditional distributors.
- Fuel Additives:Niche ketone derivatives for combustion performance enhancement.
Nylon Production leads by volume. Synthetic Resins gains share fastest.
Distribution Channel:
Channel structure bifurcates between integrated direct supply and fragmented spot purchasing.
- Direct Sales:Long-term contracts with embedded maintenance and technical service packages restructuring producer-to-buyer relationships. BASF leverages integrated caprolactam-cyclohexanone chains across Ludwigshafen and Antwerp for European nylon fiber customers.
- Online Retail:Digital platforms penetrating solvent-grade volumes below tank-car scale, disintermediating traditional distributor networks.
- Wholesalers:Bulk ketone aggregation for coating resin formulators without integrated supply.
- Distributors:Traditional hydrocarbon supply agreements being unbundled as tier-1 paint suppliers capture purity-grade arbitrage.
Direct Sales commands volume leadership. Online Retail climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ludwigshafen anchors European cyclohexanone production through BASF's integrated caprolactam corridor. Sinopec's refinery-adjacent complexes in Ningbo and Shanghai dominate East Asian merchant supply. The US Gulf Coast concentrates phenol-based oxidation capacity serving adipic acid producers.
United States
EPA NESHAP compliance timelines drive hazardous air pollutant monitoring upgrades at legacy cyclohexane oxidation stacks. Michigan and Ohio automotive coating corridors pull specification-grade solvent demand from Texas and Louisiana production clusters. Houston-area membrane-based oxidation pilots target peroxide reduction for mid-scale ketone-adipic integration.
Germany
ECHA's streamlined intermediate registration reduces regulatory friction for captive cyclohexanone users across the caprolactam chain. REACH authorization requirements tighten substance volume tracking for coating resin formulators in Benelux supply chains. Ludwigshafen and Antwerp host Europe's most concentrated integrated phenol-to-ketone production.
China
MEE volatile organic compound emission standards pressure smaller oxidation units toward technology upgrades or closure in petrochemical clusters. Sinopec scales refinery-adjacent phenol and cyclohexane oxidation capacity to serve nylon-6 expansion. Ningbo and Shanghai complexes control the majority of non-captive merchant ketone volume.
India
BIS certification alignment for electronics-grade ketone opens specification-driven niches in PCB cleaning applications. Domestic caprolactam producers scale cyclohexanone oxidation capacity to reduce import dependence for nylon fiber manufacturing. Gujarat and Maharashtra chemical corridors concentrate merchant solvent distribution for coating formulators.
Japan
METI industrial standards govern solvent-grade purity specifications for automotive coating supply chains serving domestic OEMs. Asahi Kasei maintains integrated caprolactam-ketone production for nylon-6 fiber and resin customers. Chubu and Kansai industrial belts concentrate dehydrogenation-based ketone output for captive chemical manufacturing.
Cyclohexanone Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent integration models. The market structures around three tiers: refinery-adjacent phenol oxidizers with feedstock flexibility, standalone cyclohexane units exposed to naphtha volatility, and merchant distributors serving specification-driven solvent niches. Strategic differentiation concentrates on backward integration depth and REACH compliance infrastructure. Dominant competitive moves include capacity consolidation near chemical clusters and technology licensing for membrane-based oxidation retrofits.
Among European integrated chemical producers, BASF and Domo Chemicals exemplify the captive-use archetype through Ludwigshafen and Antwerp corridor control. Sinopec occupies a position as the scale-driven merchant supplier across East Asian refinery complexes. Gujarat State Fertilizers & Chemicals Limited represents the emerging domestic specialist archetype in Indian caprolactam feedstock security.
| Leading Market Players |
|---|
| BASF |
| Asahi Kasei Corporation |
| Gujarat State Fertilizers & Chemicals Limited (GSFC) |
| Dow Chemical Company |
| Domo Chemicals |
| Sinopec Limited |
| Fibrant |
| Ostchem |
| Koninklijke DSM N.V. |
| Others |
Supply Flow & Price Mechanics
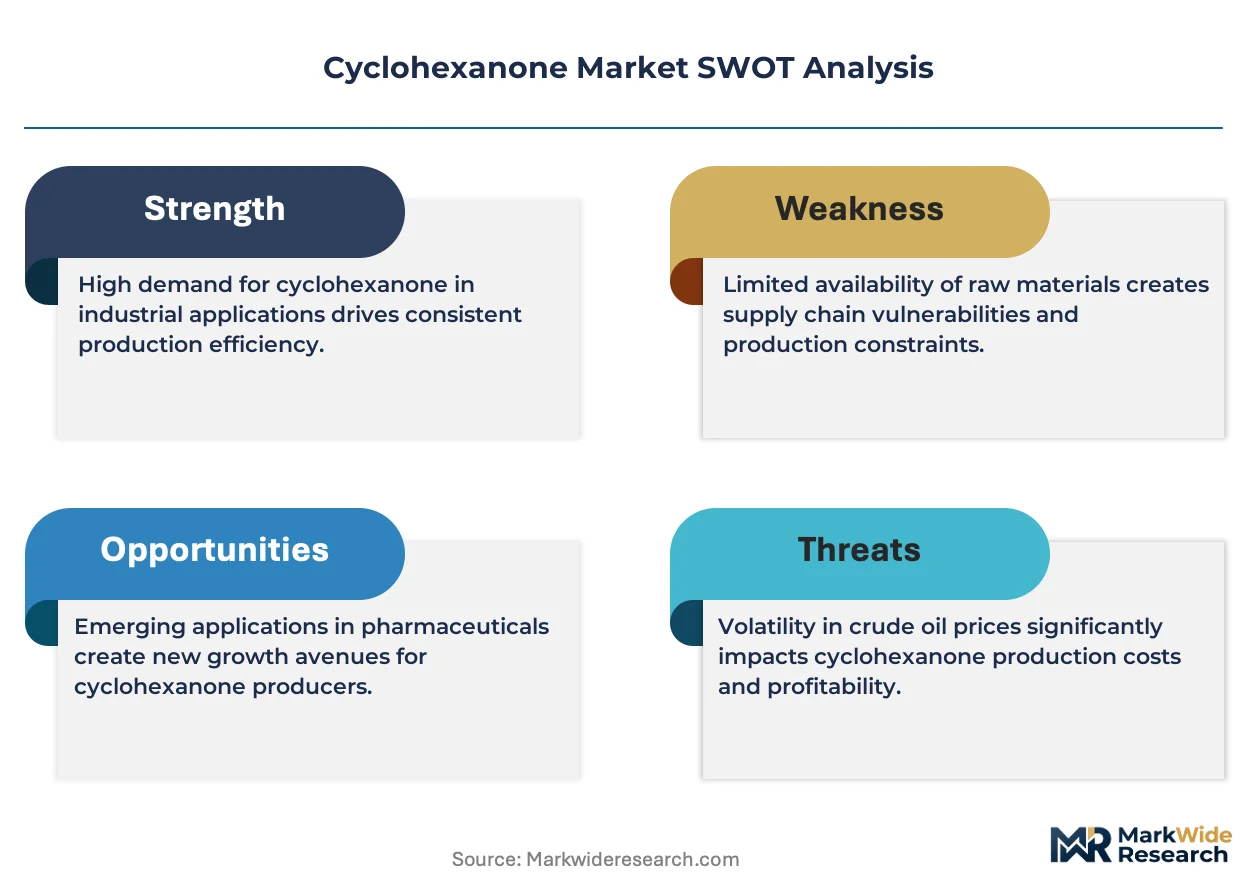
Naphtha-linked feedstock indices cascade through cyclohexanone supply chains into three distinct pricing tiers, with refinery-adjacent phenol oxidizers capturing margin advantages over standalone cyclohexane units exposed to crude volatility.
Pricing Analysis
Cost-down pressure on merchant solvent grades accelerates because coating formulators unbundle ketone volumes from broad hydrocarbon agreements to capture purity-grade arbitrage. Three-tier pricing structure across electronics-grade, automotive-coating, and standard industrial levels separates specification thresholds. Price differentiation traces to REACH compliance infrastructure and peroxide specification stringency. Tier-1 automotive suppliers in Michigan and Ohio manufacturing corridors show least price sensitivity; smaller coating resin formulators without integrated supply face highest cost pressure.
Supply Chain Analysis
Regional distribution centers near Ningbo, Shanghai, and Antwerp handle bulk ketone aggregation for coating formulators without captive oxidation capacity. Supply concentrates in China, Germany, and the United States, with Sinopec's refinery-adjacent complexes controlling East Asian merchant volume. Raw material flows draw from cyclohexane, phenol, and hydrogen feedstocks. Single-source vulnerability concentrates in three refinery-adjacent complexes supplying non-captive ketone volume. Distribution runs through long-term direct contracts with embedded technical service packages for nylon-6 producers, alongside spot purchasing for solvent-grade volumes below tank-car scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cyclohexanone manufacturing sits at a technology-transition inflection as membrane-based oxidation unifies reaction and separation stages, displacing legacy liquid-phase systems that depend on retiring specialist expertise.
For Market Incumbents: Lock in feedstock security through phenol-to-ketone integration at Ludwigshafen or Antwerp scale to defend against naphtha volatility squeezing standalone cyclohexane margins. Deepen REACH compliance infrastructure to filter market access for non-integrated merchant importers facing ECHA's tightened intermediate definitions. Prioritize membrane-based oxidation retrofits for peroxide reduction in adipic acid supply chains. For New Entrants and Emerging Players: Electronics-grade solvent buyers in India's Gujarat and Maharashtra chemical corridors offer specification-driven entry points with BIS certification alignment requirements. Specialty chemical platforms disintermediating traditional distributor networks for sub-tank-car volumes present channel-control opportunities. Target direct-to-formulator digital channels with documented purity certification and rapid lot-tracking capabilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale ketone-adipic integrated plants in the US Gulf Coast with EPA NESHAP compliance upgrade timelines forcing extended turnaround windows. Long-term viability hinges on hydrogen integration feasibility for cyclohexanol dehydrogenation retrofits under EU Green Deal financing. Watch membrane-based oxidation pilot outcomes as inflection signal for capital intensity compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Phenol-to-ketone integration at BASF's Ludwigshafen complex secures feedstock security for European nylon fiber customers. |
| Green Manufacturing Transition | Green hydrogen retrofits for cyclohexanol dehydrogenation attract EU transition financing for carbon-intensive ketone assets. |
| Long-term Supply Agreement | Embedded maintenance and technical service packages restructure producer-to-buyer relationships in nylon-6 supply chains. |
| Joint Venture | Refinery-chemical complex partnerships in East Asia lower feedstock cost volatility through shared phenol oxidation infrastructure. |
| Technology Licensing | Membrane-based oxidation licensing compresses capital intensity for mid-scale ketone-adipic integrated plants on the US Gulf Coast. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving plant managers at oxidation units, procurement leads at caprolactam producers, distribution channel partners in coating supply chains, and technical R&D directors overseeing process intensification. Bottom-up capacity modeling and top-down demand triangulation validated volume estimates across the analysis window.
Segment-level granularity applied grade tier, end-use industry, and regional production hub dimensions throughout the projection horizon. CAGRs derived from trend extrapolation of nylon-6 fiber and resin consumption patterns, EPA NESHAP compliance cost assumptions, and REACH authorization pathway friction coefficients for merchant versus captive supply chains.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to bio-based diacid substitution timelines for nylon-6,6 and hydrogen cost trajectories for dehydrogenation retrofits. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Cyclopentanone Market
Organic Chemicals
Global Biphenyl Market
Organic Chemicals
Anisole Derivatives Market
Organic Chemicals
N-Hexanol Market
Organic Chemicals
Chlorocyclopentane Market
Organic Chemicals
Ethylamine Market
Organic Chemicals
Chloroacetyl Chloride Market
Organic Chemicals
1,3-Dioxolane Market
Organic Chemicals
North America Cycloalkanes Market
Organic Chemicals
Organic Acids Market
Organic Chemicals
North America Biphenyl Market
Organic Chemicals
Global Ketones Market
Organic Chemicals
Aliphatic Amines Market
Organic Chemicals
Chlorinated Methane Market
Organic Chemicals
Synthetic Camphor Market
Organic Chemicals
Acetaldehyde Market