
 Global Dye Sublimation Inks Market | 2026-2036
Global Dye Sublimation Inks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dye Sublimation Inks Market Foresight
Aftermarket service revenue for printhead maintenance and color profiling is fragmenting across regional service networks and OEM-certified technicians. Sawgrass Technologies dominates the desktop and small-format segment through its closed ink-system architecture and proprietary color-management software. Mimaki Engineering Co., Ltd. leverages its integrated printer-and-ink portfolio to control workflow bundling in wide-format commercial installations. Seiko Epson Corporation anchors high-volume industrial textile printing through its PrecisionCore printhead ecosystem and bulk-ink supply agreements with mills.
Dye sublimation inks are formulated disperse dyes suspended in aqueous or solvent carriers, designed to transition from solid to gas without liquid phase under heat and pressure, typically at 350-400°F, bonding permanently with polyester fibers and polymer-coated substrates. Water-based formulations lead volume in textile printing due to lower volatile organic compound emissions and compatibility with high-speed piezoelectric printheads. Disperse dye concentrates represent the fastest-growing ink type as garment manufacturers demand deeper blacks and wider color gamuts for athleisure and teamwear applications. Solvent-based variants occupy a narrowing niche in outdoor signage where substrate compatibility requirements override environmental compliance pressures.
EPA regulations on hazardous air pollutants from coating operations constrain solvent-based ink formulations in US manufacturing facilities, while REACH registration requirements in Europe mandate full chemical disclosure across dye sublimation supply chains. China's MEE enforces wastewater discharge standards that push domestic ink producers toward closed-loop water-based production systems. Stakeholders must monitor how divergent chemical compliance regimes between North America, Europe, and Asia reshape formulation R&D priorities and regional sourcing strategies.
Market Dynamics
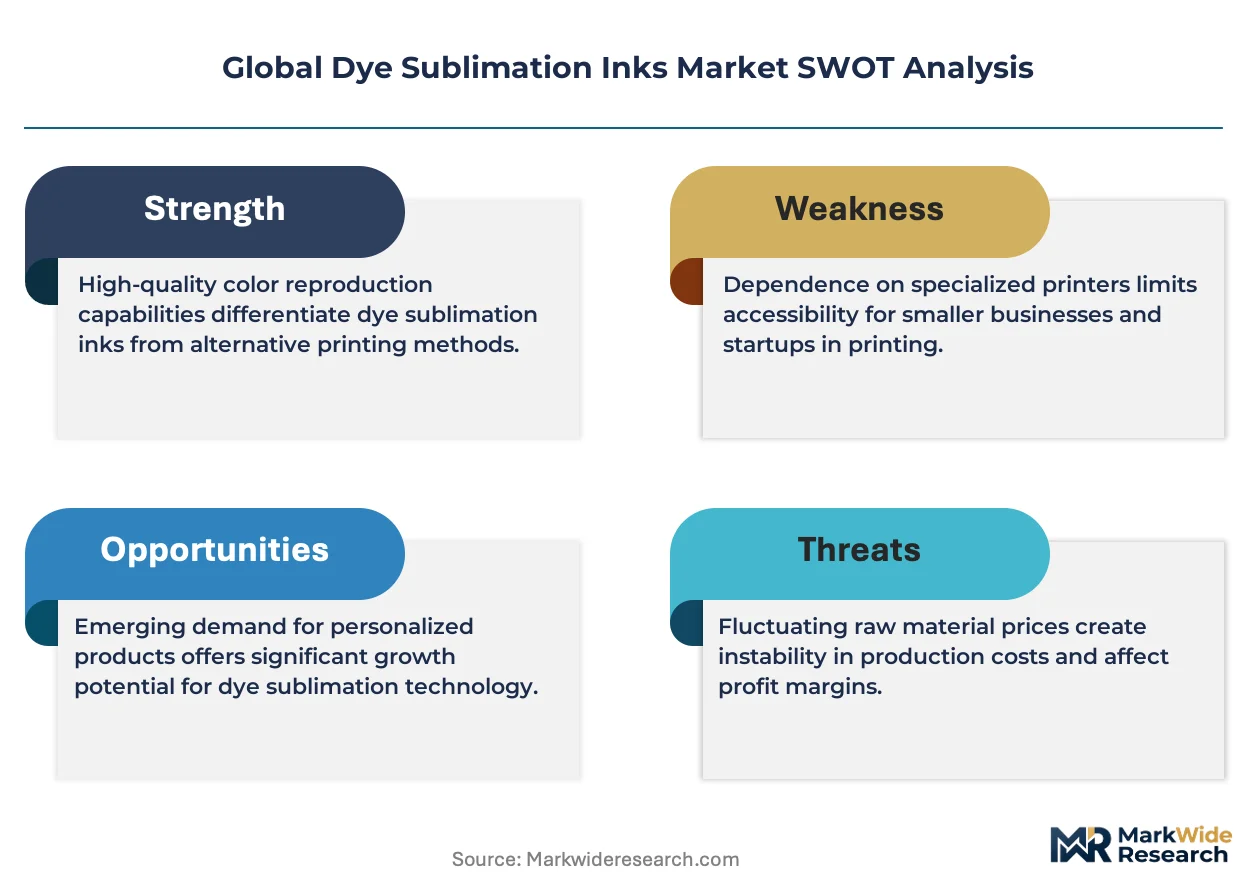
Polyester fabric customization demand from sportswear producers is compressing print-run lengths while expanding color complexity requirements, forcing ink suppliers to reformulate for shorter batch cycles without sacrificing gamut depth.
Growth Catalysts
- REACH chemical disclosure mandates:European RoHS compliance requirements are accelerating substitution of legacy solvent carriers with water-based disperse dye systems among imported ink portfolios.
- Polyester sportswear customization:Teamwear and athleisure manufacturers are expanding adoption of dye sublimation for all-over-print applications on recycled polyester feedstocks.
- China textile printing scale-up:Domestic mills in Zhejiang and Guangdong provinces are building backward integration into dye intermediates, reducing import dependency for ink manufacturers.
Market Restraints
- Disperse dye concentrate volatility:Crude oil derivatives and petrochemical feedstocks expose aqueous ink formulations to input cost swings that squeeze blender margins.
- Solvent-based niche contraction:EPA hazardous air pollutant constraints on coating operations are eliminating outdoor signage applications as a volume buffer for legacy solvent ink producers.
- Polymer substrate limitation:Dye sublimation chemistry bonds exclusively with polyester and coated hard substrates, excluding cotton, wool, and uncoated natural fiber markets from addressable demand.
Strategic Opportunities
- India textile cluster expansion:Surat and Tiruppur garment hubs remain underpenetrated by precision digital textile printing, creating first-mover positioning for bulk-ink supply agreements.
- Dual carbon policy alignment:China's MEE wastewater discharge standards and carbon neutrality targets are subsidizing closed-loop water-based production systems that exceed legacy environmental footprints.
- Printhead-ink bundling convergence:Piezoelectric PrecisionCore architecture integration with bulk delivery systems is collapsing workflow friction for high-volume mill installations.
Industry Challenges
- Color profiling expertise scarcity:Regional service networks lack sufficient OEM-certified technicians to support aftermarket printhead maintenance and ICC profile calibration at mill scale.
- REACH registration timelines:Full chemical disclosure requirements across European dye sublimation supply chains extend formulation approval cycles by 18-24 months for new disperse dye chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dye Sublimation Inks Market |
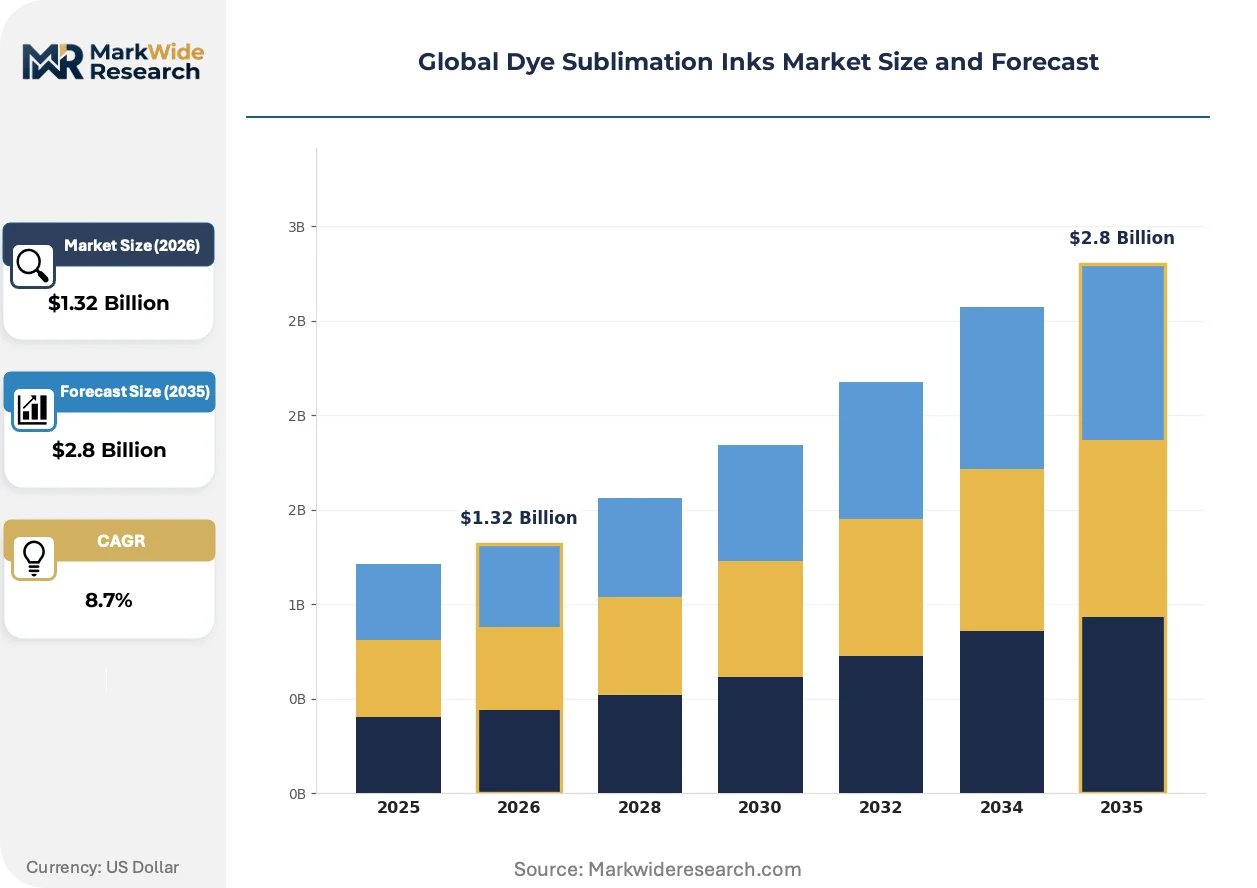
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.8 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ink Type: Water-Based, Solvent-Based, UV Reactive, Acid, Disperse, Others Application: Textile Printing, Signage, Ceramic Decoration, Polyester Fabrics, Hard Substrates End User Industry: Advertising Agencies, Garment Manufacturers, Interior Decorators, Sportswear Producers, Promotional Product Makers Packaging Type: Cartridges, Bottles, Bulk Containers, Pouches, Refillable Containers |
| Companies Covered | DuPont, Sawgrass Technologies, Mimaki Engineering Co., Ltd., Seiko Epson Corporation, STS Inks, Splashjet Print Technologies, InkTec Co., Ltd., Sensient Technologies Corporation, Nazdar Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dye Sublimation Inks Market Shifts & Advancements
Formulation science and hardware integration are converging to compress the trade-off between environmental compliance and color performance that has historically segmented the installed base.
Nano-particle disperse dye concentrates are collapsing the performance gap between water-based and solvent ink systems in deep-black and extended-gamut applications. Garment manufacturers in Italy and Portugal are adopting these concentrates for premium athleisure lines previously reserved for solvent-based output. The technology is collapsing premium-mid-economy pricing stratification by enabling single-formulation flexibility across quality tiers.
EPA enforcement of hazardous air pollutant standards from coating operations is eliminating grandfathered solvent ink production in US manufacturing facilities. Ink blenders are reallocating R&D spend toward aqueous carrier optimization and volatile organic compound recovery systems. Wide-format commercial installations in North Carolina and California are retrofitting ventilation infrastructure to maintain production permits.
Mill procurement departments are consolidating vendor relationships around integrated printer-and-ink workflow bundles rather than discrete component sourcing. Regional distributors in Germany and Japan are losing share to direct OEM mill contracts that bundle color management software with bulk-ink supply agreements. This consolidation is most visible in high-volume textile printing clusters where downtime costs exceed hardware premium spreads.
Global Dye Sublimation Inks Market Segmentation
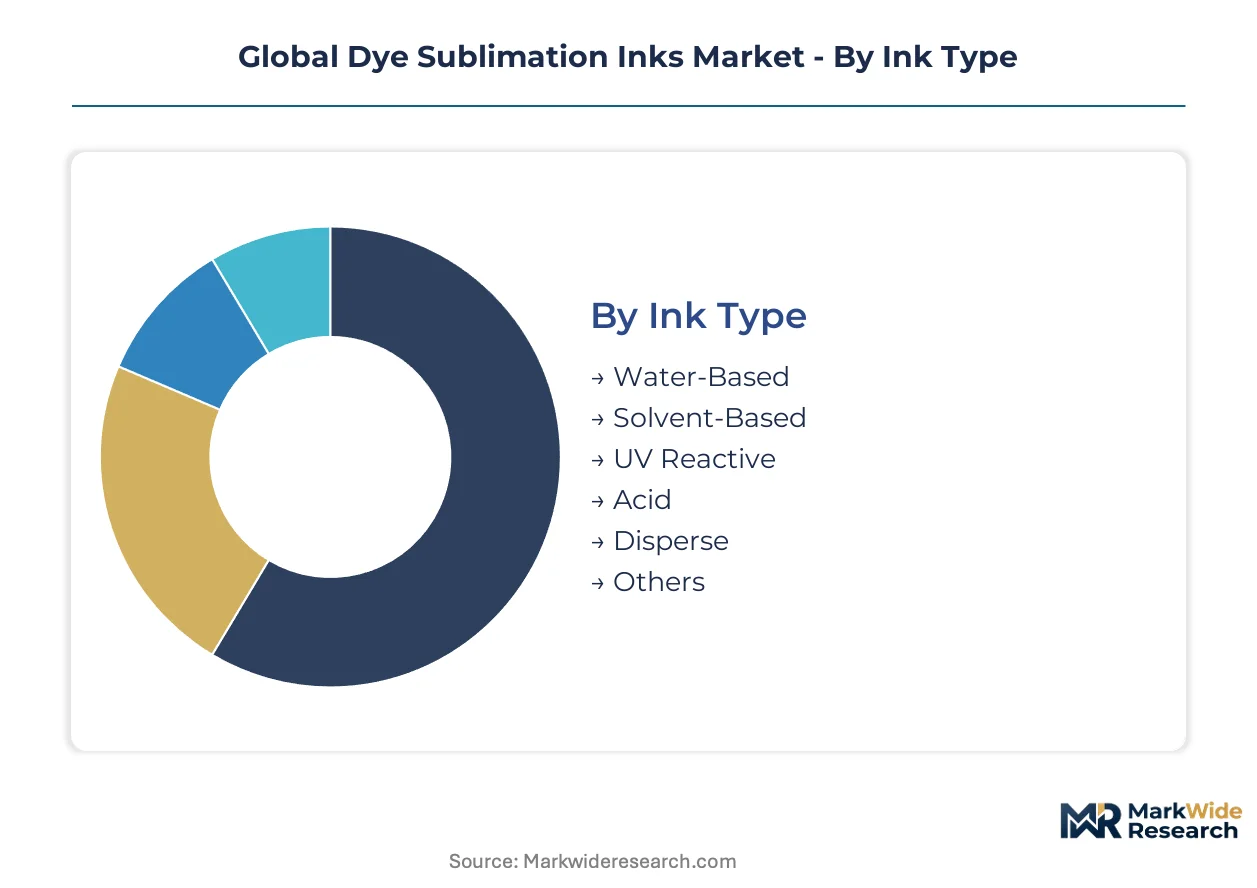
Dye sublimation ink suppliers configure product portfolios around four critical dimensions: chemical formulation determines environmental compliance and substrate compatibility; application use case dictates color gamut requirements; end-user operational scale shapes packaging and service needs; and delivery format influences total cost of ownership for high-volume mills versus desktop installations.
Ink Type:
Cost tier stratification across formulation chemistry separates premium performance from regulatory compliance-driven alternatives.
- Water-Based:Aqueous carriers suspend disperse dyes for compatibility with piezoelectric printheads in high-speed textile production. Demand concentrates in Zhejiang province mills where China's MEE wastewater standards mandate closed-loop aqueous systems.
- Disperse:Concentrated dye formulations deliver deep blacks and extended gamuts for athleisure and teamwear applications. Italian and Portuguese garment manufacturers are adopting these for premium polyester lines previously reserved for solvent output.
- Solvent-Based:Hydrocarbon carriers persist in narrow outdoor signage niches where substrate compatibility overrides EPA hazardous air pollutant constraints.
- UV Reactive:Photoinitiator-integrated formulations cure instantly under UV exposure for rigid substrate applications.
- Acid:Protein-fiber-compatible chemistry serves wool and silk markets excluded from standard disperse dye bonding.
- Others:Emerging hybrid carriers and specialty formulations address niche industrial applications.
Water-based formulations hold installed capacity across textile printing clusters. Disperse concentrates are rotating up the share rankings in premium garment segments.
Application:
Application segmentation tracks how substrate chemistry and thermal transfer requirements fragment addressable demand across soft goods and rigid surfaces.
- Textile Printing:Roll-to-roll polyester fabric decoration dominates volume, with mills in Surat and Tiruppur expanding digital capacity for shorter print runs.
- Signage:Outdoor display graphics drive solvent-based residual demand despite regulatory compression in US and European manufacturing facilities.
- Polyester Fabrics:Recycled PET feedstocks for sportswear and athleisure require reformulated disperse dyes optimized for lower-temperature transfer.
- Ceramic Decoration:Heat-activated dye transfer onto glazed surfaces serves custom tile and promotional merchandise producers.
- Hard Substrates:Polymer-coated metals, plastics, and composites extend sublimation chemistry beyond fiber applications.
Textile printing anchors volume commitments from integrated printer-ink bundles. Polyester fabrics are climbing fastest as recycled feedstock adoption accelerates.
End User Industry:
Customer type segmentation reveals how operational scale and color complexity requirements differentiate procurement behavior across creative services and manufacturing.
- Garment Manufacturers:High-volume mills in Bangladesh and Vietnam negotiate bulk-ink supply agreements with OEMs to secure color consistency across multi-shift production.
- Sportswear Producers:Teamwear and athleisure brands demand all-over-print capability on recycled polyester, compressing batch sizes while expanding color complexity.
- Advertising Agencies:Creative services firms prioritize ICC profile accuracy and rapid turnaround over unit ink costs.
- Interior Decorators:Custom soft furnishings and wall coverings require smaller lot sizes with premium color matching.
- Promotional Product Makers:Hard substrate customization for corporate merchandise operates at lower volumes with higher SKU fragmentation.
Garment manufacturers command the largest bulk-ink procurement volumes. Sportswear producers are expanding most quickly as athleisure customization penetrates mid-market tiers.
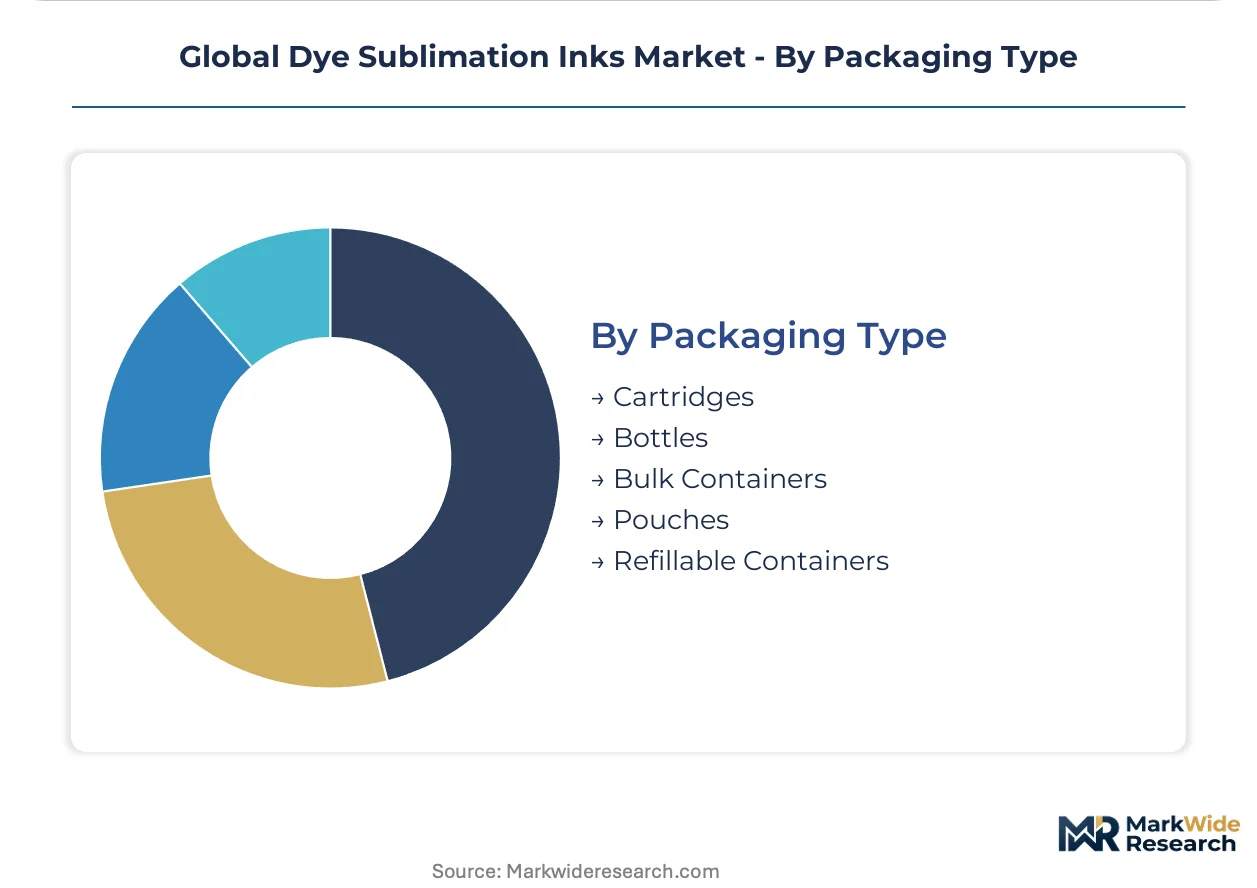
Packaging Type:
Delivery format segmentation aligns with operational scale, from desktop cartridge systems to tanker-truck bulk supply for continuous-feed industrial installations.
- Bulk Containers:Tote and drum deliveries serve high-volume textile mills with automated ink delivery systems integrated into PrecisionCore printhead workflows.
- Cartridges:Sealed single-use systems dominate desktop and small-format installations where closed-system architecture prevents contamination.
- Bottles:Hand-fill containers address mid-volume commercial shops with mixed equipment fleets.
- Refillable Containers:Returnable bulk systems reduce packaging waste for mills under carbon accounting pressure.
- Pouches:Flexible film packaging offers shipping efficiency for regional distributor networks serving fragmented customer bases.
Bulk containers dominate mill-direct procurement. Refillable systems are gaining share fastest as environmental accounting penetrates procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: European mills prioritize REACH-compliant aqueous formulations, Chinese manufacturers scale bulk-ink integration with domestic dye intermediates, and US facilities retrofit solvent-based capacity under EPA enforcement pressure.
China
Zhejiang and Guangdong province mills consume the largest aqueous ink volumes globally as domestic textile printing capacity scales. China's MEE enforces wastewater discharge standards that push producers toward closed-loop water-based production systems. Local ink manufacturers in Shaoxing are building backward integration into disperse dye intermediates, reducing import dependency.
United States
North Carolina and California wide-format commercial installations drive demand for aqueous carrier optimization. EPA enforcement of hazardous air pollutant standards from coating operations is eliminating grandfathered solvent ink production. Facilities in Charlotte and Los Angeles retrofit ventilation infrastructure to maintain production permits under tightening environmental compliance.
Germany
Industrial textile printing clusters in North Rhine-Westphalia anchor European demand for REACH-compliant formulations. ECHA registration requirements mandate full chemical disclosure across dye sublimation supply chains, extending formulation approval cycles. Regional distributors in the Ruhr region are losing share to direct OEM mill contracts bundling color management with bulk-ink supply.
India
Surat and Tiruppur garment hubs remain underpenetrated by precision digital textile printing, creating expansion opportunity for bulk-ink supply agreements. BIS standards for textile chemicals are tightening quality requirements for imported ink formulations. Domestic mills in Tamil Nadu are negotiating multi-shift production contracts with integrated printer-ink vendors to secure color consistency.
Italy
Premium athleisure manufacturers in Lombardy and Veneto adopt nano-particle disperse dye concentrates for deep-black applications previously reserved for solvent output. REACH RoHS compliance requirements accelerate substitution of legacy solvent carriers with water-based systems among imported ink portfolios. Como silk district printers are expanding polyester fabric customization capabilities for teamwear export contracts.
Global Dye Sublimation Inks Market Competitive Landscape
Capability concentration sits with integrated printer-ink bundlers; scale advantage sits with bulk-ink suppliers serving high-volume textile mills. The vendor base organizes around three archetypes: closed-system desktop specialists, wide-format workflow bundlers, and industrial PrecisionCore ecosystem anchors. Competitive moves center on mill-direct contract consolidation and regional service network certification.
Within the integrated workflow tier, Mimaki Engineering Co., Ltd. and Seiko Epson Corporation exemplify printer-ink bundling strategies that collapse procurement friction for high-volume installations. Sawgrass Technologies anchors the closed-system desktop segment through proprietary architecture. DuPont and Sensient Technologies Corporation occupy positions in chemical formulation supply, while InkTec Co., Ltd. represents Korean-based bulk-ink positioning. Nazdar Company and STS Inks sit within the North American regional distribution tier serving fragmented commercial shops.
| Leading Market Players |
|---|
| DuPont |
| Sawgrass Technologies |
| Mimaki Engineering Co., Ltd. |
| Seiko Epson Corporation |
| STS Inks |
| Splashjet Print Technologies |
| InkTec Co., Ltd. |
| Sensient Technologies Corporation |
| Nazdar Company |
| Others |
Supply & Pricing Matrix
Commodity volatility in petrochemical feedstocks compresses blender margins while simultaneously widening spreads between water-based economy formulations and disperse concentrate premium tiers. This input cost instability forces procurement departments to alternate between long-term offtake contracts for volume certainty and spot purchases for formulation flexibility, reshaping supplier-buyer power dynamics across the value chain.
Pricing Analysis
Long-term offtake agreements dominate mill-direct procurement for high-volume textile installations, while spot purchasing persists among fragmented commercial shops with mixed equipment fleets. Three-tier pricing structure across premium, standard, and economy levels separates nano-particle disperse concentrates from conventional aqueous carriers and basic solvent formulations. Cost compression in mid-tier water-based segments is intensifying because China's domestic dye intermediate production reduces import dependency for regional blenders. Garment manufacturers in Bangladesh and Vietnam exhibit highest price sensitivity due to thin conversion margins, whereas premium athleisure brands in Italy prioritize color gamut depth over unit cost.
Supply Chain Analysis
Export-control scrutiny on advanced piezoelectric printhead technology limits PrecisionCore component flows to certain jurisdictions, constraining integrated workflow bundling in targeted markets. Manufacturing concentration centers on China for aqueous ink production, Germany for REACH-compliant formulation R&D, and South Korea for bulk chemical intermediates. Disperse dye concentrates draw from crude oil derivatives and petrochemical feedstocks, while closed-loop water-based systems rest on specialized filtration equipment and wastewater recovery infrastructure. Single-source vulnerability sits with precision printhead supply from Japanese manufacturers. Distribution runs through direct OEM mill contracts in high-volume clusters and regional distributor networks serving fragmented commercial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dye sublimation inks market functions as a service-attach opportunity where aftermarket printhead maintenance and ICC profile calibration generate recurring revenue expanding faster than hardware sales. Color management expertise scarcity creates premium positioning for certified technician networks.
For Market Incumbents: Build switching-cost moats through proprietary color-management software integration with bulk-ink supply agreements. Secure backward integration into disperse dye intermediates in Zhejiang province to defend against emerging Chinese domestic competitors. Invest in REACH registration capabilities to extend formulation approval timelines as a barrier against new chemistry entrants. Channel control through direct mill contracts in Surat and Tiruppur limits distributor margin capture. For New Entrants and Emerging Players: Build out regional service certification programs to address the technician scarcity constraining mill-scale adoption. Target underpenetrated precision digital textile printing capacity in India's Tamil Nadu garment hubs where multi-shift production contracts remain available. Pursue white-space positioning in closed-loop water-based production systems aligned with China's MEE wastewater standards. Go-to-market leverage rests on carbon-accounting-compliant refillable container programs for mills under environmental procurement pressure. For Investors and Strategic Acquirers: REACH registration timelines reshapes the acquisition landscape by extending payback periods for novel disperse dye chemistry platforms. Long-term viability favors integrated printer-ink bundlers with captive printhead ecosystems over standalone formulation suppliers. Acquisition target archetype: regional distributors with certified technician networks in underpenetrated textile clusters. Monitor EPA enforcement intensity on hazardous air pollutant standards as inflection signal for solvent-based capacity strandedness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dye Intermediates | Shaoxing-based production reduces import dependency for Chinese aqueous ink manufacturers. |
| Closed-Loop Water-Based Production Systems | China's MEE wastewater standards subsidize environmental footprint advantages over legacy solvent operations. |
| PrecisionCore Printhead Ecosystem Expansion | Seiko Epson's bulk-ink supply agreements anchor high-volume mill installations with workflow bundling. |
| REACH-Compliant Formulation Registration | ECHA chemical disclosure mandates extend approval cycles, creating regulatory moats for established European suppliers. |
| Regional Service Network Certification | OEM-certified technician programs address color profiling expertise scarcity constraining aftermarket revenue capture. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with textile mill procurement directors, ink formulation R&D leads, piezoelectric printhead engineers, and regional distribution channel managers. Secondary validation drew from customs trade data on disperse dye intermediate flows, EPA enforcement records on hazardous air pollutant standards, ECHA REACH registration databases, and SEC filings from publicly traded chemical suppliers. Bottom-up capacity estimates from Zhejiang and Guangdong province installations were triangulated against top-down consumption models for polyester fabric decoration demand.
Calibration against historical capacity expansion patterns and regulatory implementation timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include ink formulation chemistry, application use case, end-user operational scale, and delivery format packaging type. CAGRs were derived from installed base growth rates and replacement cycle analysis. Industry-specific forecast inputs incorporated China's dual carbon policy trajectory and the diffusion rate of nano-particle disperse dye concentrate adoption in premium garment segments.
Practitioners should monitor REACH registration timeline extensions and EPA enforcement intensity shifts for early signals of competitive repositioning. Forecasts reflect assumptions on petrochemical feedstock cost stability and printhead technology transfer restrictions. Material shifts in China's MEE wastewater discharge standards or export-control tightening on precision printing components would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Offset Ink Market
Printing Inks
Rotogravure Printing Inks Market
Printing Inks
Global Conductive Inks Market
Printing Inks
Global Gravure Printing Inks Market
Printing Inks
Thermal Inkjet Inks Market
Printing Inks
Ink-Cartridge Market
Printing Inks
Global Light Changing Packaging Inks Market
Printing Inks
Packaging Inks and Coatings Market
Printing Inks
Solvent-Based Inks Market
Printing Inks
Global Chemical Indicator Inks Market
Printing Inks
Specialty Printing Consumables Market
Printing Inks
Flexible Letterpress Printing Ink Market
Printing Inks
Anti-Counterfeit Printing Ink Market
Printing Inks
Plant Oil Based Printing Inks Market
Printing Inks
Radiation Curable Inks Market
Printing Inks
Ink Resins Market