
 Global Carboxylic Acid Market | 2026-2036
Global Carboxylic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Carboxylic Acid Market Foresight
Multi-sourced feedstock procurement is realigning competitive dynamics across the Global Carboxylic Acid Market. BASF SE anchors European supply through integrated acetic acid complexes in Ludwigshafen. OQ Chemicals GmbH leverages Oxo synthesis expertise to dominate C4-C10 specialty acid niches. Celanese Corporation controls methanol carbonylation capacity across US Gulf Coast and Singapore manufacturing nodes.
Carboxylic acids constitute a class of organic compounds characterized by a carboxyl functional group (COOH), typically produced via oxidation of primary alcohols, aldehydes, or hydrocarbons with carbon chain lengths ranging from C1 to C18 depending on target application. These compounds serve as fundamental intermediates for esterification, polymerization, and neutralization reactions across industrial chemistry. Acetic acid leads product type volume as mature vinyl acetate monomer and purified terephthalic acid demand sustains baseline offtake, while propionic acid registers fastest application growth driven by grain preservative regulations in livestock feed. Plasticizers application segment captures concentrated margin pools as phthalate replacement chemistry elevates demand for adipate and benzoate ester precursors.
EPA industrial chemical reporting requirements and REACH substance authorization protocols shape purity thresholds and documentation burdens for US and European market access respectively. China's MEE environmental compliance inspections enforce wastewater discharge limits on fermentation-based acid producers, redirecting capacity toward cleaner carbonylation routes. ISO 9001 and FSSC 22000 certifications govern food-grade acid qualification protocols for Pharmaceutical Manufacturing and Food Additives end users. Stakeholders must monitor carbon intensity disclosure mandates as Scope 3 reporting obligations extend downstream to chemical intermediate procurement decisions.
Market Dynamics
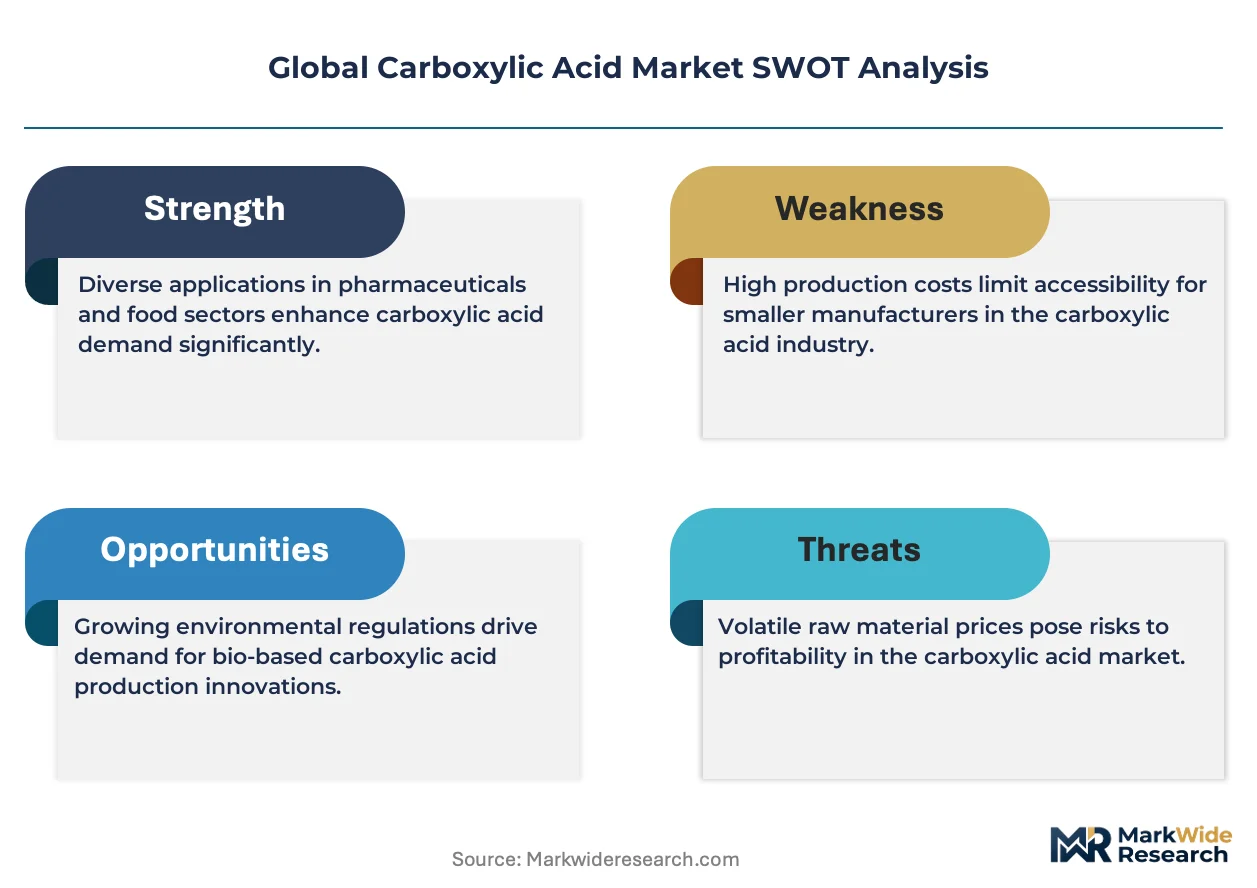
Feedstock volatility and carbon intensity disclosure mandates are compressing margins for fermentation-based producers while carbonylation operators capture preferential offtake from pharmaceutical formulators seeking documented Scope 3 reductions.
Growth Catalysts
- REACH substance authorization:The EU's tightening purity benchmarks for active ingredient synthesis are disqualifying uncertified acid grades and consolidating procurement toward REACH-registered suppliers with full documentation trails.
- Grain preservative regulations:Livestock feed safety mandates across major agricultural economies are elevating propionic acid demand as mold inhibitors replace legacy fumigants in stored grain protection.
- Vinyl acetate monomer demand:Acetic acid offtake from mature VAM and purified terephthalic acid production sustains baseline volume even as specialty acids capture faster application growth.
Market Restraints
- Methanol feedstock volatility:Carbonylation route economics remain exposed to natural gas and coal-to-methanol price swings, particularly affecting US Gulf Coast and Singapore manufacturing nodes.
- China MEE wastewater enforcement:Environmental compliance inspections on fermentation-based producers are forcing capacity idling or costly effluent treatment retrofits without guaranteed restart permits.
- Ester plasticizer substitution:Non-phthalate alternatives including bio-based plasticizers are displacing adipate and benzoate ester precursors in flexible PVC applications.
Strategic Opportunities
- India PLI scheme alignment:Specialty acid producers qualifying under production-linked incentive frameworks for active pharmaceutical ingredients can access subsidized capital for carbonylation capacity expansion.
- FSSC 22000 certification gap:Food-grade acid qualification protocols remain underpenetrated among mid-tier fermentation operators, creating acquisition targets for integrated players seeking backward control.
- Biogenic carbon accounting:Fermentation-based acids with verified biomass feedstock documentation command premium positioning as EU CSRD disclosure obligations extend to chemical intermediate procurement.
Industry Challenges
- ISO 9001 documentation burden:Pharmaceutical Manufacturing customers now require batch-level purity certificates with full analytical methodology disclosure, extending sales cycle timelines.
- Scope 3 data infrastructure:Downstream chemical intermediate buyers lack standardized carbon intensity measurement tools, forcing acid producers to build proprietary lifecycle assessment capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Carboxylic Acid Market |
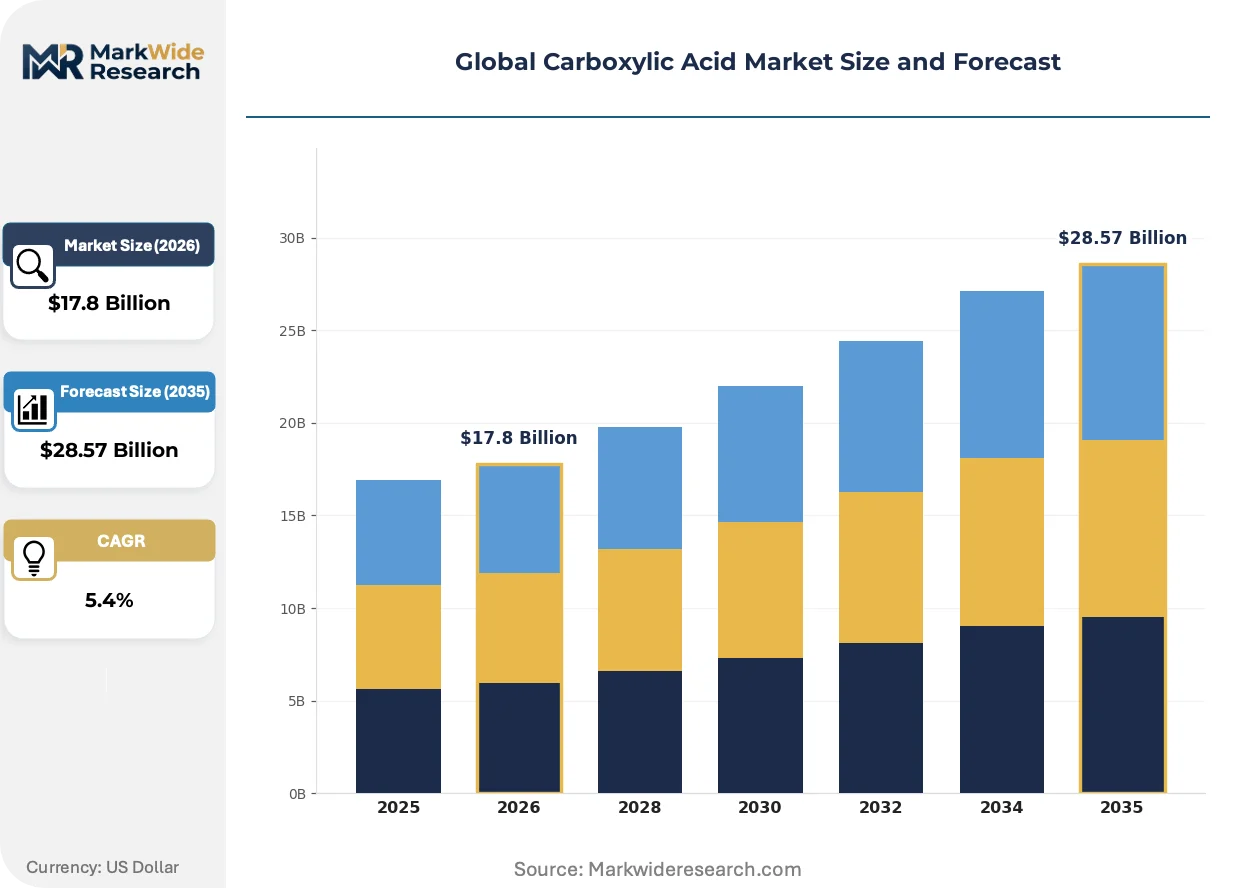
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $28.57 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetic Acid, Formic Acid, Propionic Acid, Oxalic Acid, Butyric Acid Application: Food Additives, Textile Processing, Plasticizers, Pesticides, Coatings End User Industry: Pharmaceutical Manufacturing, Agriculture, Paper Production, Personal Care, Chemicals Processing Packaging Type: Drums, Bulk Containers, Carboys, Flexible Bags, Intermediate Bulk Containers |
| Companies Covered | Celanese Corporation, OQ Chemicals GmbH, BASF SE, Merck KGaA, Mitsui Chemicals, Inc., Eastman Chemical Company, LyondellBasell Industries N.V., Perstorp, The Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Carboxylic Acid Market Shifts & Advancements
Process intensification and regulatory disclosure automation are compressing the gap between commodity and specialty acid production economics, while digital traceability tools reshape customer qualification protocols.
Continuous flow carbonylation reactor design is modularizing acetic acid production scale, allowing mid-cap operators to deploy standardized 50-100 kiloton units with 40% lower capital intensity than legacy batch systems. Pharmaceutical formulators in Germany and Switzerland are qualifying these units for high-purity acid supply faster than traditional plant approvals. The technology is modularizing regional supply patterns by enabling distributed production closer to European chemical processing clusters.
REACH substance authorization protocols now require full exposure scenario documentation for C4-C10 specialty acids used in polymer additives, extending registration timelines and compliance costs for non-integrated producers. The industrial consequence is a bifurcation between authorized suppliers with complete dossiers and traders facing customer disqualification. Specialty acid niches in coatings and plasticizers are responding by consolidating procurement toward Oxo synthesis specialists with in-house regulatory affairs capabilities.
Certificate-of-analysis verification is migrating to blockchain-anchored documentation systems as pharmaceutical and food additive buyers demand immutable batch records for FDA and EFSA inspections. Distributors serving mid-size compounders are being disintermediated by direct supplier portals offering real-time analytical data access. This behavioral shift is most visible in US and EU markets where large formulators have deployed vendor-managed inventory systems with automated purity threshold alerts.
Global Carboxylic Acid Market Segmentation
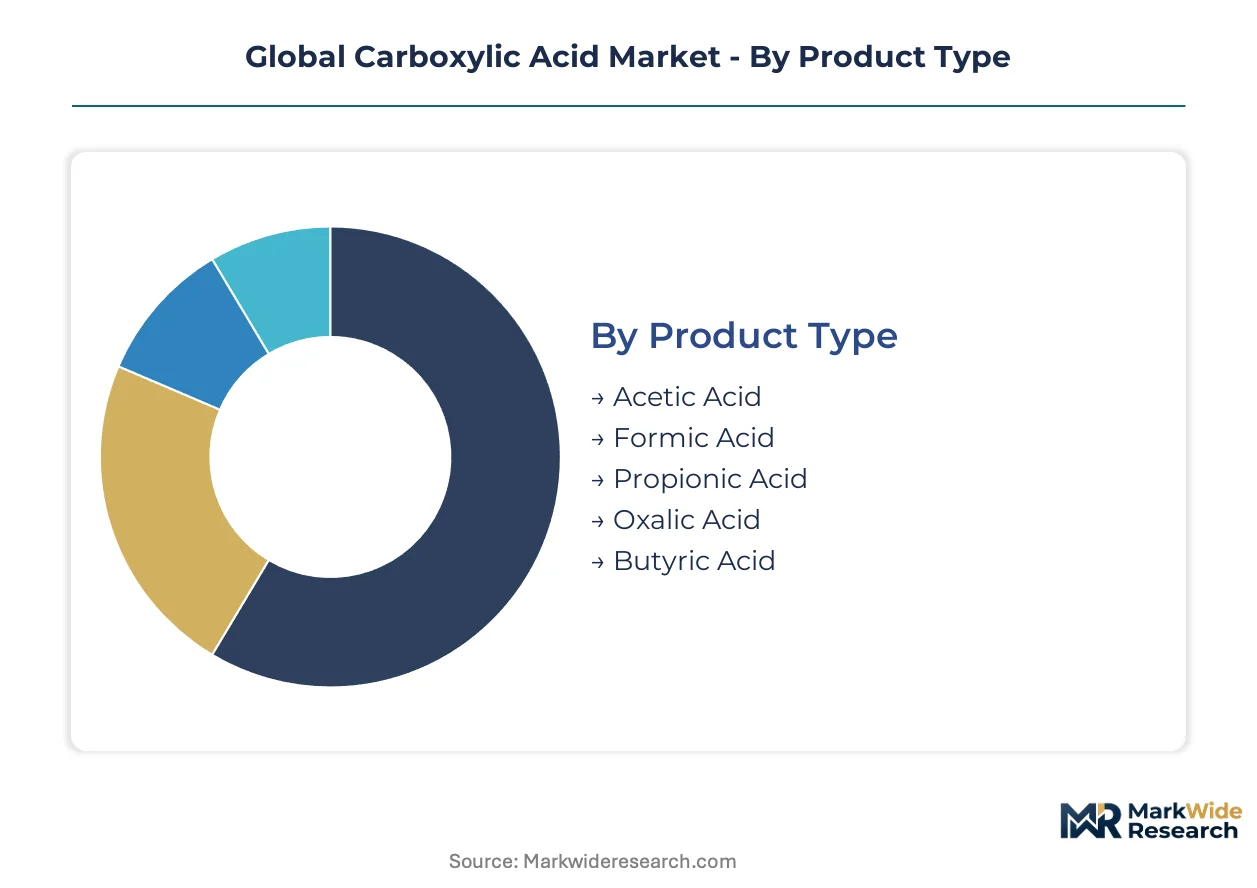
Carboxylic acid procurement patterns diverge sharply across product chemistry, application purity requirements, and end-user regulatory exposure. Understanding these fault lines reveals where margin pools concentrate and which qualification barriers protect incumbent positions.
Product Type:
Buyers in this category separate by carbonylation versus fermentation process economics and the downstream purity thresholds their customers enforce.
- Acetic Acid:The C2 workhorse produced via methanol carbonylation dominates industrial offtake for vinyl acetate monomer and purified terephthalic acid synthesis. Volume concentrates in China and US Gulf Coast manufacturing clusters where integrated petrochemical complexes secure feedstock cost advantages.
- Propionic Acid:C3 preservative-grade acid registers the steepest expansion trajectory as grain storage regulations across Brazil, India, and the European Union displace legacy fumigants with mold inhibitors. REACH-registered supply is consolidating toward Oxo synthesis specialists with documented exposure scenarios.
- Formic Acid:C1 acid serves leather tanning and silage preservation applications with moderate purity requirements.
- Oxalic Acid:C2 dicarboxylic acid finds niche demand in rare earth extraction and metal cleaning formulations.
- Butyric Acid:C4 fermentation-derived acid supplies animal feed palatability enhancers and pharmaceutical intermediates with odor-control specifications.
Acetic acid leads volumes today; propionic acid is climbing the fastest.
Application:
Margin capture in this category depends on whether the application faces direct food contact, environmental release, or industrial processing exposure.
- Plasticizers:Adipate and benzoate ester precursors command premium positioning as phthalate replacement chemistry accelerates in flexible PVC compounding. EU REACH authorization protocols and US EPA reporting requirements are disqualifying uncertified acid grades from pharmaceutical and food packaging supply chains.
- Food Additives:FSSC 22000-certified acids for preservative and acidulant functions face concentrated demand from multinational formulators in Germany, Switzerland, and the Netherlands with immutable batch documentation requirements.
- Textile Processing:Formic and acetic acids serve fiber dyeing and finishing operations with moderate purity thresholds.
- Pesticides:Herbicide and fungicide intermediates require REACH-registered supply with full analytical methodology disclosure.
- Coatings:Solvent and resin applications tolerate broader specification ranges than food or pharmaceutical segments.
Plasticizers generate the highest margin concentration; food additives face the steepest qualification barriers.
End User Industry:
Procurement sophistication in this category scales with regulatory inspection frequency and liability exposure from finished product contamination.
- Pharmaceutical Manufacturing:Active ingredient synthesis demands batch-level purity certificates with full analytical methodology disclosure per FDA and EMA guidelines. ISO 9001 documentation burdens extend sales cycles but protect incumbent suppliers from trader competition.
- Agriculture:Livestock feed safety mandates across major producing regions are elevating propionic acid demand for grain preservation. Brazil's ANVISA and India's FSSAI are tightening residue limits that favor certified-grade suppliers.
- Chemicals Processing:Intermediate buyers lack standardized carbon intensity measurement tools, forcing acid producers to build proprietary lifecycle assessment capabilities for Scope 3 reporting.
- Paper Production:Pulping and bleaching applications consume lower-purity acid grades with price-sensitive procurement.
- Personal Care:Cosmetic-grade acids require compliance with EU Cosmetics Regulation and US FDA cosmetic ingredient safety standards.
Pharmaceutical Manufacturing commands premium pricing; Agriculture is expanding most quickly.
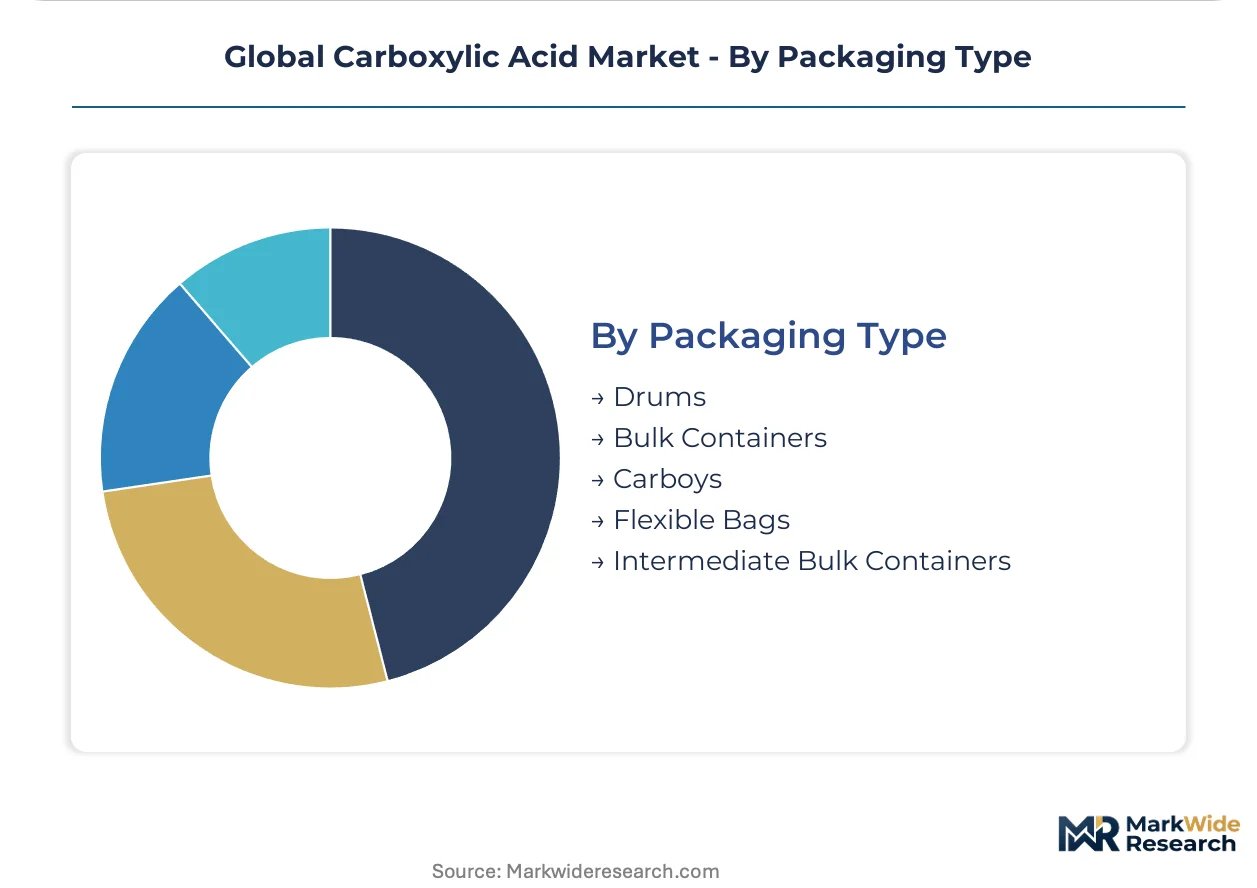
Packaging Type:
Logistics economics in this category hinge on shipment volume, hazard classification, and customer inventory management sophistication.
- Bulk Containers:Rail and tanker shipments serve integrated chemical processors with dedicated unloading infrastructure at Ludwigshafen, Singapore Jurong Island, and Houston Ship Channel. Unit cost advantages are substantial for acetic acid offtake above 5,000 metric tons annually.
- Intermediate Bulk Containers:1,000-liter totes capture mid-size compounder demand with forklift handling compatibility and reduced drum disposal costs. Pharmaceutical formulators in Basel and Mumbai are qualifying IBC supply for high-purity acids with tamper-evident sealing.
- Drums:200-liter steel and polyethylene containers serve smaller batch chemical processors with limited storage capacity.
- Carboys:Glass and fluoropolymer vessels protect ultra-high-purity acids for analytical and electronic applications.
- Flexible Bags:Powder and flake acid derivatives ship in bulk bags for food additive and agricultural compounders.
Bulk containers dominate tonnage; IBC formats are gaining share fastest among mid-size buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ludwigshafen's integrated petrochemical complexes anchor European carboxylic acid supply chains. China dominates carbonylation capacity expansion. India and Brazil register fastest demand acceleration from feed preservative mandates.
United States
Gulf Coast methanol carbonylation clusters supply vinyl acetate monomer producers with cost-advantaged acetic acid offtake. EPA industrial chemical reporting requirements enforce batch-level documentation burdens that favor integrated operators over merchant traders. Houston Ship Channel bulk terminals handle concentrated acetic acid volumes for domestic PTA and VAM synthesis.
China
Yangtze River Delta chemical processing parks scale specialty C4-C10 acid output for export markets. MEE environmental compliance inspections enforce wastewater discharge limits that redirect fermentation capacity toward cleaner carbonylation routes. Ningbo and Shanghai manufacturing nodes concentrate high-purity acid production for pharmaceutical intermediate export.
Germany
Rhineland-Palatinate's Ludwigshafen complex anchors European acetic acid supply through backward-integrated feedstock control. REACH substance authorization protocols disqualify uncertified acid grades from pharmaceutical formulator procurement. BASF SE's manufacturing infrastructure exemplifies the regulatory compliance capabilities that protect incumbent positions.
India
Maharashtra and Gujarat pharmaceutical clusters drive specialty acid demand for active ingredient synthesis. PLI scheme incentives for API production subsidize carbonylation capacity expansion among qualified producers. CDSCO and FSSAI tightening of residue limits favors certified-grade suppliers in grain preservative applications.
Brazil
São Paulo state agribusiness operations elevate propionic acid consumption for stored grain mold inhibition. ANVISA livestock feed safety mandates displace legacy fumigants with preservative-grade acids. Santos port logistics infrastructure supports import dependence for high-purity grades until domestic carbonylation capacity scales.
Global Carboxylic Acid Market Competitive Landscape
Global majors compete with regional champions across certification depth and feedstock integration. The vendor base separates into three tiers: integrated petrochemical operators with captive methanol supply, Oxo synthesis specialists dominating C4-C10 specialty niches, and fermentation-based merchants facing margin compression from environmental compliance costs. Consolidation pressures concentrate in pharmaceutical-grade segments where REACH registration and ISO 9001 documentation create qualification barriers. Strategic moves center on M&A targeting FSSC 22000-certified fermentation assets and partnerships for biogenic carbon accounting verification.
Within the integrated petrochemical tier, Celanese Corporation and BASF SE exemplify operators with methanol carbonylation scale across multiple manufacturing nodes. OQ Chemicals GmbH occupies a distinct position as an Oxo synthesis specialist with concentrated expertise in C4-C10 specialty acid production.
| Leading Market Players |
|---|
| Celanese Corporation |
| OQ Chemicals GmbH |
| BASF SE |
| Merck KGaA |
| Mitsui Chemicals, Inc. |
| Eastman Chemical Company |
| LyondellBasell Industries N.V. |
| Perstorp |
| The Dow Chemical Company |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between REACH-registered pharmaceutical acids and commodity industrial grades manifests in both pricing power concentration and supply chain configuration. Premium tier producers capture 40-60% margin spreads over standard grades through integrated carbonylation assets, while fermentation-based merchants face downstream price compression from wastewater compliance costs.
Pricing Analysis
Methanol feedstock pass-through dominates contract structures for US Gulf Coast and Singapore carbonylation operators, with natural gas price volatility transmitting directly to acetic acid quotations within 30-60 day lags. Pricing stratifies across pharmaceutical-grade, food-grade, and industrial-grade tiers, with ISO 9001 documentation burdens extending sales cycles and protecting incumbent premiums. Cost compression in fermentation-based supply is intensifying because China's MEE enforcement has idled uncertified capacity without restart guarantees. Chemical processing intermediates exhibit highest price sensitivity, while pharmaceutical formulators absorb premium positioning for documented Scope 3 reductions.
Supply Chain Analysis
Regional distribution centers in Ludwigshafen, Ningbo, and Houston anchor hub-and-spoke patterns for bulk acid movements, with intermediate bulk containers gaining share among mid-size European and Indian pharmaceutical compounders. Manufacturing concentrates in China, the United States, and Germany, with feedstock supply drawing from coal-to-methanol complexes, natural gas steam crackers, and bio-based fermentation feedstocks respectively. Single-source vulnerability runs through Yangtze River Delta environmental permitting, where MEE inspections have forced unplanned capacity idling. Distribution runs through integrated petrochemical complexes for large-volume offtake, while specialty acids deploy direct supplier portals with blockchain-anchored documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Carboxylic Acid Market functions as a stable compounder anchored by irreversible regulatory upgrades in pharmaceutical and food safety standards that perpetually refresh certification demand.
For Market Incumbents: Anchor defensive positioning through backward integration into captive methanol supply and accelerated FSSC 22000 certification of fermentation assets before mid-tier competitors achieve compliance. The threat of blockchain-anchored documentation disintermediating distributors demands direct portal investment, while REACH registration depth protects against trader competition in C4-C10 specialty niches. For New Entrants and Emerging Players: The price-point gap between premium REACH-registered supply and economy-grade industrial acids creates entry space for modular continuous-flow carbonylation units serving mid-size European pharmaceutical clusters. India's PLI-subsidized API capacity expansion offers the most penetrable geography, with grain preservative regulation in Brazil and India providing fastest application growth. A go-to-market angle anchored in biogenic carbon accounting documentation captures EU CSRD-driven procurement shifts. For Investors and Strategic Acquirers: Consolidation pressure builds where FSSC 22000 certification gaps strand mid-tier fermentation assets at distressed valuations. Long-term viability favors integrated operators with multi-node carbonylation scale and in-house regulatory affairs capabilities over pure-play fermentation merchants facing structural margin compression. The signal to watch is EU CSRD disclosure mandate expansion to Scope 3 chemical intermediate procurement, which would accelerate premium positioning for verified biomass feedstock documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methanol Supply | Captive feedstock control insulates Celanese and BASF from natural gas price volatility at US Gulf Coast and Ludwigshafen nodes. |
| Modular Continuous-Flow Reactor Deployment | Standardized 50-100 kiloton units enable distributed European production with 40% lower capital intensity than batch systems. |
| FSSC 22000 Certification Acquisition | Food-grade qualification protocols create acquisition targets among stranded mid-tier fermentation operators facing MEE compliance costs. |
| Blockchain-Anchored Documentation Systems | Immutable batch records satisfy FDA and EFSA inspection demands while disintermediating distributor layers. |
| Biogenic Carbon Accounting Verification | Fermentation-based acids with verified biomass documentation command premium positioning under EU CSRD disclosure obligations. |
Research Methodology
Direct dialogue with plant managers at carbonylation complexes, procurement leads at downstream pharmaceutical formulators, distribution channel partners serving chemical processing clusters, and technical R&D directors at Oxo synthesis specialists grounded qualitative assessment. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and REACH registration databases. Bottom-up capacity modeling and top-down demand segmentation were triangulated against disclosed production figures and import-export flows.
Bottom-up volume builds aggregated individual asset capacities across methanol carbonylation, Oxo synthesis, and fermentation routes, while top-down demand models traced consumption through vinyl acetate monomer, purified terephthalic acid, grain preservative, and pharmaceutical intermediate channels. Segmentation dimensions included product chemistry chain length, application purity tier, end-use regulatory exposure, and regional production hub classification. CAGRs were derived from regression analysis of historical capacity additions correlated with downstream demand elasticities, with forecast inputs incorporating REACH authorization timeline probabilities and MEE enforcement intensity scenarios.
The model assumes a particular technology adoption path favoring carbonylation route expansion; alternative pathways for electrochemical CO2 reduction to C2-C4 acids would alter the outlook for fermentation-based competitive positioning. Forecasts reflect documented assumptions around regulatory enforcement continuity, feedstock price correlation structures, and certification penetration rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
1,3-Dichloroacetone Market
Organic Chemicals
Bromobenzene Market
Organic Chemicals
Organic Rheological Modifiers Market
Organic Chemicals
Benzyl Cyanide Market
Organic Chemicals
North America Phenol Market
Organic Chemicals
Organocatalyst Market
Organic Chemicals
Acrylonitrile Market
Organic Chemicals
Cycloalkanes Market
Organic Chemicals
2-Iodophenol Market
Organic Chemicals
High Purity Metal Organics Market
Organic Chemicals
Benzethonium Chloride Market
Organic Chemicals
Global Biphenyl Market
Organic Chemicals
Alanine Market
Organic Chemicals
Dimethyl Carbonate Market
Organic Chemicals
Methacrylic Acid Market
Organic Chemicals
Global Metal-Organic Framework Market