
 2-Iodophenol Market | 2026-2036
2-Iodophenol Market Size, Share, and Industry Trends Forecast 2026-2036
2-Iodophenol Market Outlook
Buyer concentration across pharmaceutical contract manufacturers is rebalancing as large API producers consolidate iodophenol procurement while mid-size research labs fragment demand into smaller batch orders. Sancai Industry leverages its Jiangsu manufacturing base to anchor domestic supply for Chinese pharmaceutical intermediates. Xiamen Equation Chemical Co Ltd competes through specialized crystal-grade output for high-purity dye applications. Skyrun Industrial Co Ltd sustains export channels into European agrochemical formulators.
2-Iodophenol is an ortho-substituted halogenated phenol with molecular formula C6H5IO, typically synthesized via diazotization of 2-aminophenol followed by Sandmeyer iodination, and serves primarily as a building block for iodinated pharmaceuticals and azo dye precursors. Crystal and powder product types dominate volume given their stability in long-haul shipment and precise dosing for batch synthesis, while liquid formulations capture margin in just-in-time pharmaceutical workflows. The intermediates application leads absolute consumption as downstream API makers stockpile halogenated precursors, whereas agrochemical demand differentiates through seasonal procurement spikes tied to pre-planting formulation cycles.
REACH registration requirements in Europe and EPA toxic substance controls in the United States shape purity thresholds and documentation burdens for cross-border shipments. China's MEE enforces wastewater discharge limits on iodination facilities, pushing producers toward closed-loop recovery systems. Stakeholders must monitor how dual carbon mandates in China and evolving EU F-Gas analog rules for halogenated organics redirect capital toward cleaner iodination chemistries.
Market Dynamics
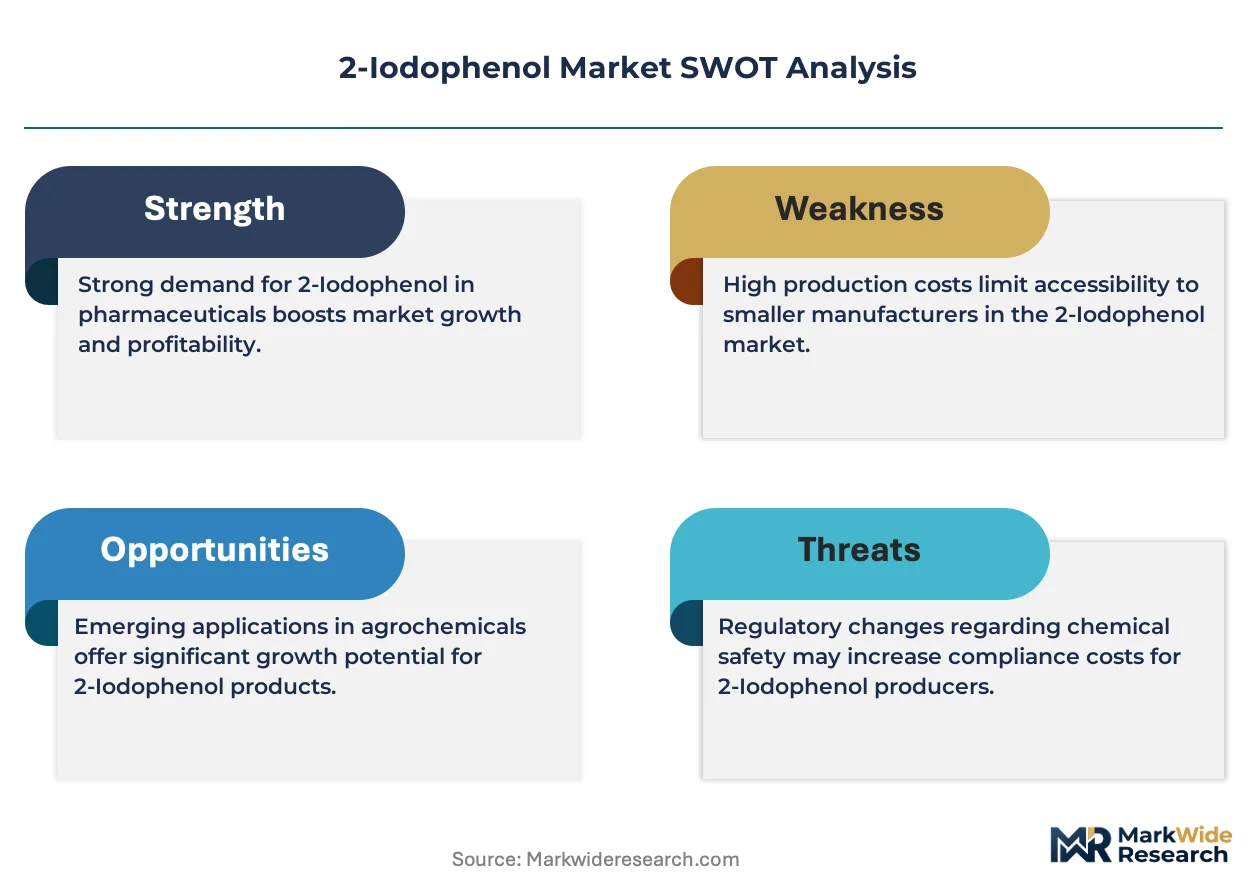
Contract manufacturers of iodinated APIs are consolidating procurement power while REACH and EU Green Deal mandates force purification capex, squeezing mid-tier producers without closed-loop recovery systems.
Growth Catalysts
- Pharmaceutical intermediates demand:API stockpiling by contract manufacturers in Jiangsu and Gujarat is pulling volume through the channel. Stockpile cycles now run 18-24 months versus historical 12-month patterns.
- REACH registration thresholds:ECHA documentation requirements for halogenated organics are filtering out non-compliant suppliers, concentrating volume among registered producers with dedicated regulatory affairs teams.
- Closed-loop iodine recovery:MEE wastewater discharge limits are accelerating adoption of solvent-recovery systems that cut raw material costs by capturing spent iodine for re-sublimation.
Market Restraints
- Iodine price volatility:Chilean caliche ore supply disruptions transmit directly to 2-iodophenol input costs, compressing margin for non-integrated formulators without long-term offtake agreements.
- Jiangsu production concentration:Over 60% of Chinese output sits within a single province, creating single-point-of-failure exposure to regional environmental enforcement actions or power rationing.
- Fluorinated phenol substitution:Agrochemical formulators in select applications are trialing trifluoromethyl-phenol alternatives that bypass iodine supply chains entirely.
Strategic Opportunities
- Indian agrochemical export channel:Gujarat-based formulators serving Latin American soybean belt demand represent underpenetrated volume for crystal-grade suppliers with DGFT-compliant documentation.
- Dual carbon policy tailwinds:China's carbon intensity targets are subsidizing electrified iodination reactor upgrades, creating first-mover advantage for producers with MEE-certified green process credentials.
- Continuous-flow microreactor convergence:Sandmeyer chemistry paired with flow technology is enabling just-in-time liquid formulation output for pharmaceutical CMOs with compressed campaign timelines.
Industry Challenges
- Halogenation chemist scarcity:Sandmeyer reaction expertise is retiring faster than universities replenish trained synthetic organic chemists with diazotization safety certification.
- REACH dossier maintenance burden:ECHA substance evaluation updates require ongoing toxicology study commissioning, diverting technical resources from process development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2-Iodophenol Market |
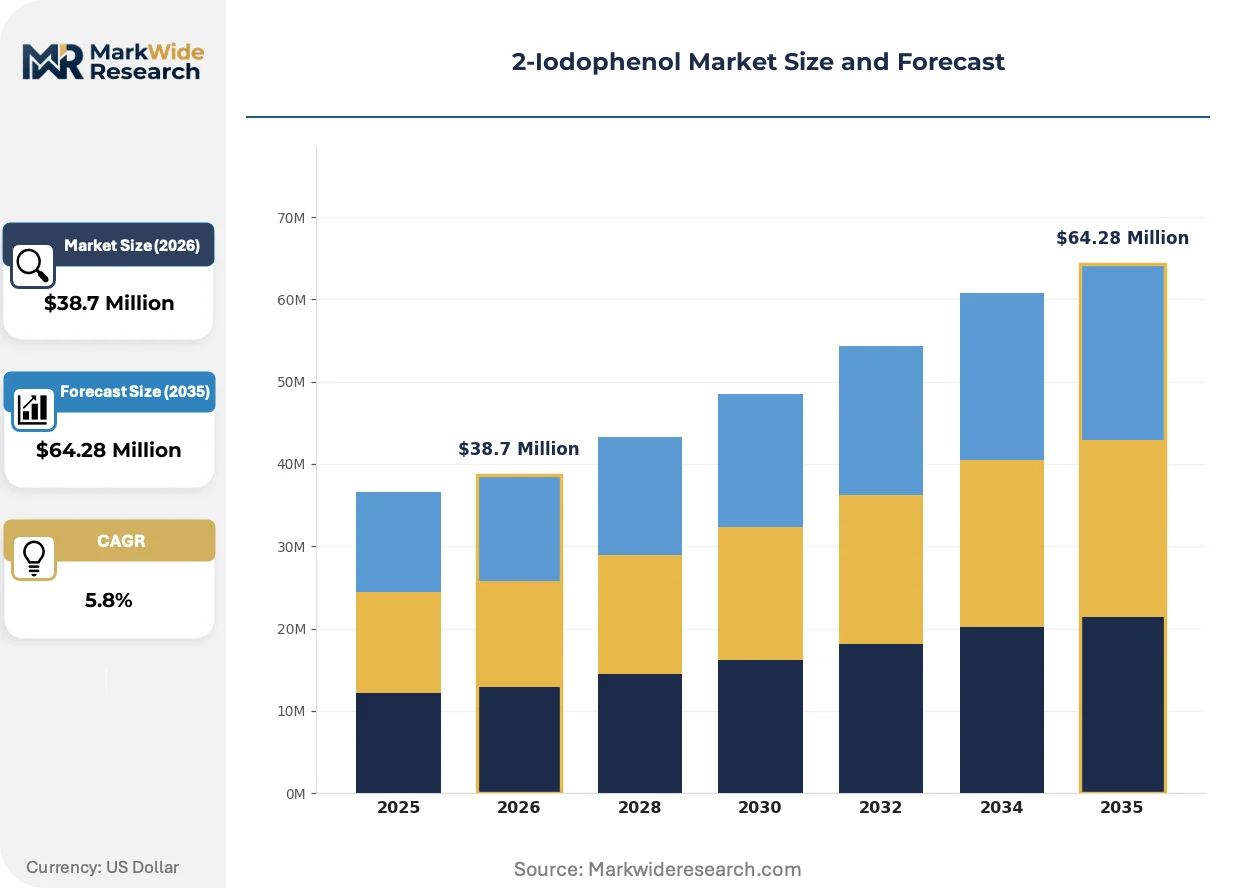
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $64.28 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystals, Granules, Powder, Liquid Application: Pharmaceuticals, Dyes, Agrochemicals, Intermediates End User: Chemical Manufacturers, Research Labs, Formulators, Universities Packaging Type: Drums, Bags, Bottles, Totes |
| Companies Covered | Sancai Industry, Xiamen Equation Chemical Co Ltd, Sarex Overseas, Fintech Industry Ltd, Autech Industry Co Ltd, Spec-Chem products Inc, Daming Changda Co Ltd, Skyrun Industrial Co Ltd, Kingreat company Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2-Iodophenol Market Strategic Shifts
Process intensification and regulatory disclosure requirements are simultaneously compressing batch sizes and expanding documentation overhead, favoring producers with modular manufacturing footprints and dedicated compliance infrastructure.
Continuous-flow microreactor systems for diazotization-Sandmeyer sequences are modularizing production economics by shrinking campaign changeover downtime from days to hours. Pharmaceutical CMOs with high-mix, low-volume portfolios are piloting these units for 50-200 kg iodophenol batches. The technology is modularizing asset utilization rates and enabling toll-manufacturing models that were previously uneconomical at sub-tonne scale.
EU F-Gas Regulation analog proposals for halogenated organics are tightening containment and leak-detection mandates for iodinated phenol storage and transfer operations. ECHA guidance documents now classify certain iodophenol concentrations as requiring enhanced occupational exposure monitoring. Agrochemical formulators in Germany and France are retrofitting vapor recovery systems ahead of formal rulemaking to secure social license for continued operations.
Research-scale buyers are fragmenting procurement into sub-kilogram orders through specialized chemical distributors rather than direct mill relationships. University labs and biotech startups are driving this channel shift, substituting Amazon-like marketplace platforms for traditional three-quote procurement. The pattern is most visible in US coastal research corridors where principal investigators prioritize speed over volume discounts.
2-Iodophenol Market Segmentation
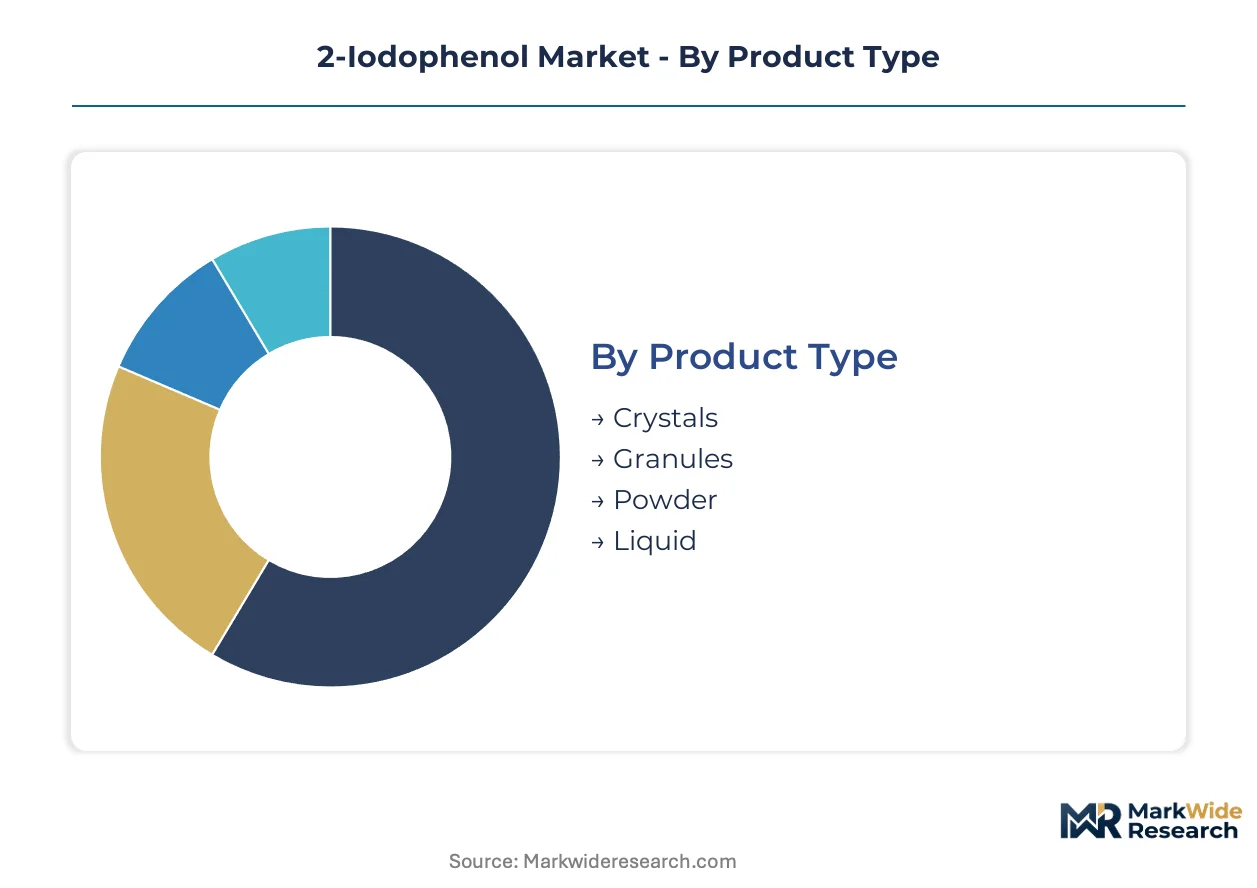
2-Iodophenol procurement patterns diverge sharply across physical forms and end-use contexts, with pharmaceutical intermediates demanding REACH-registered crystal grades while agrochemical formulators prioritize cost-optimized powder in bulk totes. Understanding these segment boundaries clarifies where purification capex concentrates and where margin compression threatens.
Product Type:
Crystal and powder grades carry divergent certification burdens under REACH and China's MEE discharge rules, while liquid formulations face escalating containment mandates from EU F-Gas analog proposals.
- Crystals:High-purity orthorhombic solids meeting EP/USP monograph specifications dominate pharmaceutical intermediate channels. API stockpiling by Jiangsu contract manufacturers pulls volume through this tier despite 15-20% price premiums over powder alternatives.
- Powder:Finely milled material with controlled particle distribution serves azo dye precursor synthesis and agrochemical formulation. Gujarat-based formulators represent the densest demand cluster for standard-grade powder in 25 kg bag configurations.
- Granules:Intermediate particle size reduces dust exposure during handling. Agrochemical blenders in São Paulo state increasingly specify granule morphology for automated dosing lines.
- Liquid:Dissolved formulations in polar aprotic solvents enable just-in-time pharmaceutical workflows. Continuous-flow microreactor outputs are displacing traditional batch liquid production for CMOs with compressed campaign timelines.
Leading the category by volume: Powder. Growing fastest: Liquid formulations for pharmaceutical toll-manufacturing.
Application:
Application segments stratify by regulatory documentation intensity, with pharmaceutical intermediates requiring ECHA dossier maintenance while dye applications operate under lighter notification thresholds.
- Intermediates:Halogenated building blocks for iodinated API synthesis constitute the dominant value pool. Sandmeyer chemistry expertise scarcity is concentrating procurement among registered producers with dedicated regulatory affairs teams.
- Pharmaceuticals:Direct incorporation into final drug substances demands batch-level CoA documentation and stability data. FDA and EMA inspection readiness drives specification tightening beyond standard intermediate grades.
- Dyes:Azo coupling reactions consume crystal-grade material for pigment intermediate production. Xiamen Equation Chemical anchors supply for high-purity dye applications through specialized crystallization protocols.
- Agrochemicals:Seasonal procurement spikes precede northern hemisphere planting cycles. Trifluoromethyl-phenol substitution trials in select herbicide formulations threaten long-term iodophenol offtake in this channel.
Volume leadership: Intermediates. Steepest expansion trajectory: Pharmaceutical direct-use applications with bioequivalence documentation requirements.
End User:
End user categories map to order size thresholds and technical service intensity, with chemical manufacturers consolidating procurement power while research labs fragment demand into sub-kilogram channels.
- Chemical Manufacturers:Integrated fine-chemical producers with captive iodination capacity or long-term offtake agreements. Sancai Industry's Jiangsu base exemplifies this tier's vertical integration advantages.
- Formulators:Agrochemical and specialty chemical blenders without upstream halogenation assets. Skyrun Industrial sustains European export relationships with this customer set through DGFT-compliant documentation.
- Research Labs:Biotech startups and CROs ordering sub-kilogram quantities through distributor marketplaces. Amazon-like procurement platforms are displacing traditional three-quote processes in US coastal research corridors.
- Universities:Academic synthetic organic chemistry programs with intermittent demand and extended payment cycles. Distributor credit terms and small-batch availability determine supplier selection in this tier.
Procurement concentration: Chemical manufacturers. Fastest channel shift: Research labs migrating to marketplace platforms.
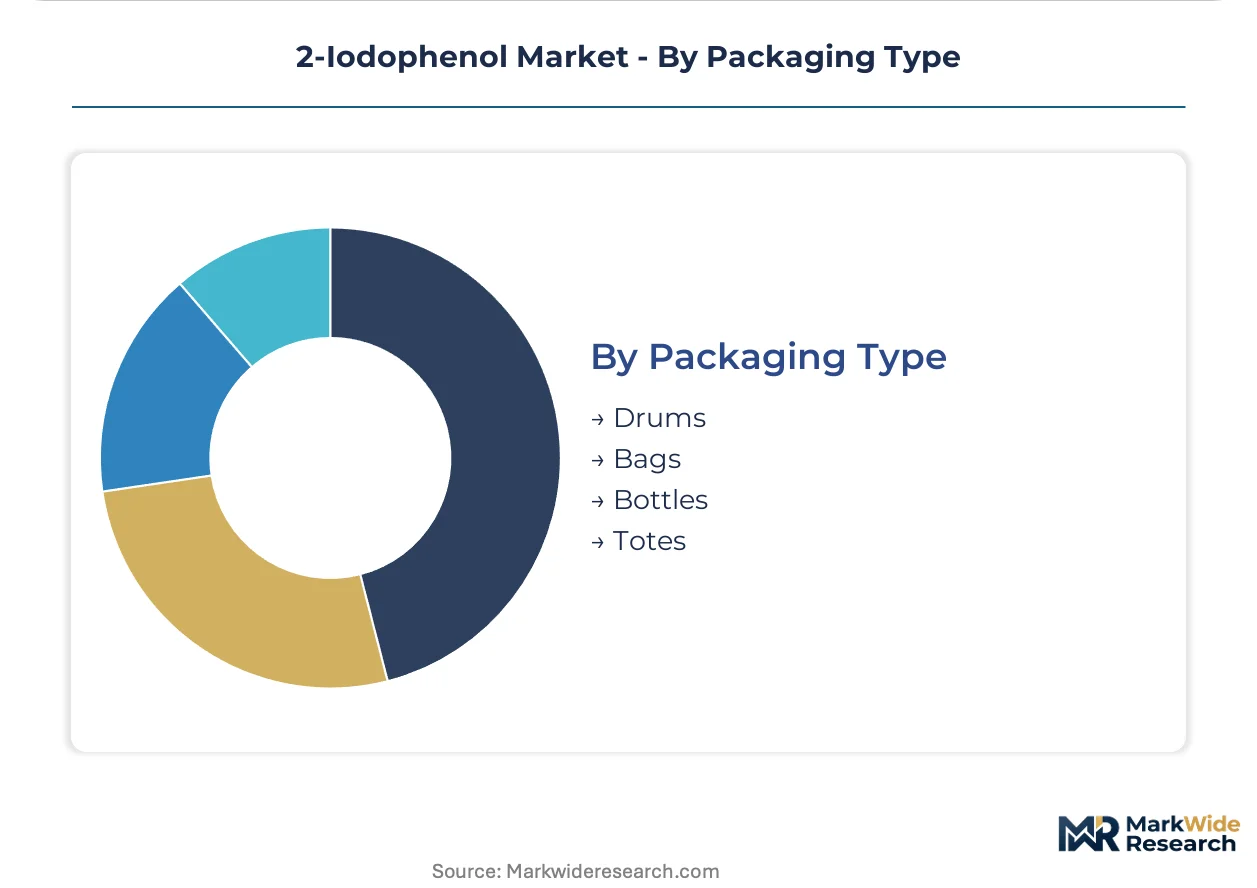
Packaging Type:
Packaging configurations align with shipment economics and handling automation, with drums dominating ocean freight while totes capture margin in regional just-in-time networks.
- Drums:Standard 200-liter steel drums with UN certification for international hazardous material transport. Long-haul shipments from China to European agrochemical formulators default to this configuration.
- Bags:Multi-layer laminated sacks for powder and granule grades. Gujarat production clusters favor 25 kg bag formats for domestic distribution efficiency.
- Bottles:Amber glass containers for liquid formulations and high-purity crystal samples. Research lab procurement through distributors drives volume in this tier.
- Totes:Intermediate bulk containers for regional pharmaceutical CMOs with compressed campaign timelines. Premium pricing reflects reduced handling labor and faster inventory turns.
Dominant format by tonnage: Drums. Gaining share fastest: Totes for pharmaceutical toll-manufacturing networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China and India where bulk fine-chemical production clusters around Jiangsu and Gujarat. Contract manufacturers in these provinces anchor procurement volume for pharmaceutical intermediates. European and North American markets operate under stricter regulatory frameworks that filter supplier participation.
China
API stockpiling by Jiangsu contract manufacturers pulls volume through 18-24 month cycles. MEE wastewater discharge limits on iodination facilities push producers toward closed-loop recovery systems. Sancai Industry leverages its Jiangsu manufacturing base to anchor domestic supply for pharmaceutical intermediates.
India
Gujarat-based formulators serving Latin American soybean belt demand represent underpenetrated volume for crystal-grade suppliers. DGFT-compliant documentation requirements shape export channel access. The state's dense agrochemical formulation cluster drives seasonal procurement spikes tied to pre-planting cycles.
Germany
Agrochemical formulators retrofit vapor recovery systems ahead of formal EU F-Gas analog rulemaking. ECHA substance evaluation updates require ongoing toxicology study commissioning from registered producers. The country's chemical manufacturing base demands REACH-registered crystal grades with batch-level CoA documentation.
United States
Research labs and biotech startups fragment procurement into sub-kilogram orders through marketplace platforms. EPA toxic substance controls shape purity thresholds for cross-border shipments. Coastal research corridors prioritize speed over volume discounts in supplier selection.
Brazil
Agrochemical blenders in São Paulo state increasingly specify granule morphology for automated dosing lines. ANVISA import documentation requirements add friction to halogenated chemical shipments. The country's soybean belt demand anchors South American offtake for Gujarat-based exporters.
2-Iodophenol Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized crystallization and continuous-flow microreactor capabilities. The vendor base stratifies between integrated fine-chemical producers with captive iodination capacity and toll manufacturers serving fragmented research demand. Three archetypes dominate: Jiangsu-based vertical integrators, Xiamen-area crystallization specialists, and export-oriented trading houses with DGFT documentation expertise. Competitive moves concentrate on M&A for regulatory dossier acquisition and electrified reactor upgrades for MEE green process credentials.
Among China-based producers, Sancai Industry occupies a position exemplifying the Jiangsu manufacturing cluster advantage, while Xiamen Equation Chemical Co Ltd represents the specialized crystal-grade output archetype for high-purity applications. Skyrun Industrial Co Ltd anchors the export-channel tier, sustaining European relationships through compliant documentation. These three entities collectively illustrate how geographic concentration and technical specialization stratify competitive positioning.
| Leading Market Players |
|---|
| Sancai Industry |
| Xiamen Equation Chemical Co Ltd |
| Sarex Overseas |
| Fintech Industry Ltd |
| Autech Industry Co Ltd |
| Spec-Chem products Inc |
| Daming Changda Co Ltd |
| Skyrun Industrial Co Ltd |
| Kingreat company Ltd |
| Others |
Value Chain & Pricing Dynamics
Sandmeyer reaction chemist scarcity in Jiangsu Province compresses labor-cost differentials into wide pricing-tier spreads between pharmaceutical-grade crystal outputs and agrochemical powder alternatives. REACH registration burdens and MEE wastewater compliance costs concentrate in premium tiers, while standard grades compete on iodine feedstock efficiency alone.
Pricing Analysis
Volume leadership sits with powder grades serving Gujarat dye formulators, while margin concentrates in liquid formulations for pharmaceutical CMOs with just-in-time workflows. Three-tier pricing structure across premium, standard, and economy levels separates EP/USP-certified crystal from technical-grade powder and unregistered bulk material. Pricing pressure stems from Chilean caliche ore disruptions transmitting directly to iodine input costs, compressing margin for non-integrated producers. Agrochemical blenders in São Paulo state exhibit highest price sensitivity, prioritizing particle-size consistency over certification, whereas FDA-inspection-ready pharmaceutical direct-use buyers accept 15-20% premiums for batch-level CoA documentation.
Supply Chain Analysis
China's dual carbon policy and India's PLI scheme for specialty chemicals are reshaping sourcing patterns toward domestic-content-compliant producers with MEE-certified green credentials. Manufacturing gravity centers on China, India, and Germany, with Jiangsu and Gujarat anchoring bulk output while German formulators retrofit vapor recovery systems ahead of EU F-Gas analog rules. Raw material flows draw from Chilean caliche iodine, Indian bromine derivatives, and European solvent suppliers. Single-province concentration in Jiangsu creates single-point-of-failure exposure to environmental enforcement actions. Distribution runs through DGFT-documented export channels for agrochemical formulators and REACH-registered direct supply for pharmaceutical intermediates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous-flow microreactor technology is displacing legacy batch Sandmeyer systems, compressing campaign changeover from days to hours and enabling toll-manufacturing economics at sub-tonne scale. This transition phase favors producers with modular asset footprints over fixed-plant incumbents.
For Market Incumbents: Hedge against trifluoromethyl-phenol substitution in agrochemical channels by deepening backward integration into iodine recovery systems that capture spent halogen for re-sublimation. Prioritize MEE green process certification to secure dual carbon policy subsidies for electrified reactor upgrades. Consolidate regulatory dossier holdings through targeted acquisition of REACH-registered specialists with dedicated ECHA affairs teams.
For New Entrants and Emerging Players: REACH registration thresholds in Europe open a window for compliant producers to capture volume filtering out from non-registered competitors lacking toxicology study commissioning capacity. Target the Indian agrochemical export channel serving Latin American soybean belt demand, where Gujarat-based formulators seek DGFT-compliant crystal-grade suppliers. Establish toll-manufacturing relationships with pharmaceutical CMOs piloting continuous-flow microreactor campaigns.
For Investors and Strategic Acquirers: The window for entry favors producers with captive iodination capacity and closed-loop solvent recovery systems. Long-term viability hinges on regulatory compliance infrastructure rather than scale alone. Sandmeyer chemist retirement rates outpacing university replenishment signal inflection toward automated flow-chemistry platforms. Monitor ECHA substance evaluation update frequency as indicator of dossier maintenance burden intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Iodine Recovery | Closed-loop capture of spent iodine for re-sublimation cuts raw material cost exposure to Chilean caliche volatility. |
| Continuous-Flow Microreactor Deployment | Sandmeyer chemistry modularization shrinks campaign changeover downtime from days to hours for pharmaceutical CMOs. |
| REACH Dossier Acquisition | ECHA registration holdings filter supplier participation and concentrate volume among compliant producers with dedicated regulatory affairs teams. |
| MEE Green Process Certification | Dual carbon policy subsidies accelerate electrified iodination reactor upgrades for first-mover advantage in Chinese pharmaceutical intermediate supply. |
| Gujarat Export Channel Development | DGFT-compliant documentation unlocks underpenetrated volume from formulators serving Latin American agrochemical demand. |
Study Parameters
Independent corroboration across plant managers at Jiangsu iodination facilities, procurement leads at European agrochemical formulators, and distribution channel partners in Gujarat underwrites the qualitative findings in this study. Primary interviews with technical R&D directors specializing in Sandmeyer chemistry and regulatory affairs leads managing ECHA dossier maintenance were cross-referenced with secondary validation from customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings from listed chemical producers. Bottom-up volume estimates from production facility capacities were triangulated against top-down demand aggregation from end-use application consumption patterns.
Historical reference periods spanning pre-pandemic baseline through recent stockpile cycle extensions anchored the forecast window, with projection horizons reflecting modeled segmentation across physical form grades, end-use industry applications, packaging configurations, and regional production hub clusters. CAGRs were derived from regression analysis of iodinated pharmaceutical intermediate demand trajectories and agrochemical formulation procurement seasonality, incorporating iodine price volatility indices and regulatory enforcement intensity metrics as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for continuous-flow microreactor scale-up would alter the outlook if pharmaceutical CMOs accelerate campaign compression timelines beyond baseline assumptions. Forecasts reflect documented assumptions regarding REACH registration compliance rates, MEE enforcement consistency, and Chilean caliche supply stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Trimethylcyclohexanone Market
Organic Chemicals
Organic Hydrosols Market
Organic Chemicals
Lithium Chemicals Market
Organic Chemicals
2,6-Dichloro Aniline Market
Organic Chemicals
2-Amino-5-Nitrobenzophenone Market
Organic Chemicals
Benzethonium Chloride Market
Organic Chemicals
Para-Tert-Octylphenol (POTP) Market
Organic Chemicals
Global Metal-Organic Framework Market
Organic Chemicals
Oryzenin Market
Organic Chemicals
Crotonic Acid Market
Organic Chemicals
Organic Rheological Modifiers Market
Organic Chemicals
Synthetic Antioxidants Market
Organic Chemicals
Methacrylic Acid Market
Organic Chemicals
2,5-Dimethyl-2,4-Hexadiene Market
Organic Chemicals
Benzyl Cyanide Market
Organic Chemicals
Ethylamine Market