
 L-Lysine Hydrochloride (HCL) Market | 2026-2036
L-Lysine Hydrochloride (HCL) Market Size, Share, and Industry Trends Forecast 2026-2036
L-Lysine Hydrochloride (HCL) Market Foresight
Specialized fermentation engineering talent is redrawing competitive boundaries in amino acid manufacturing. Meihua Holdings Group leverages vertical integration across corn processing and lysine output to control input costs. Fufeng Group Limited anchors its position through massive fermentation scale in Shandong Province. CJ CheilJedang Corporation differentiates via biotechnology leadership in strain development for yield optimization.
L-Lysine Hydrochloride is the crystalline salt form of the essential amino acid lysine, typically manufactured through submerged fermentation of carbohydrate substrates using Corynebacterium glutamicum strains, with a purity threshold exceeding 98.5 percent for pharmaceutical grades and serving primarily as a limiting amino acid supplement in animal feed and human nutritional applications. Feed Grade dominates volume flows as livestock producers seek precise amino acid balancing to reduce crude protein requirements, while Pharmaceutical Grade commands concentrated margin pools due to stringent purity protocols and CDMO qualification cycles. Nutraceuticals represents the fastest-expanding application channel as dietary supplement providers reformulate products toward condition-specific positioning.
China's NMPA enforces Good Manufacturing Practice standards for pharmaceutical-grade lysine that dictate facility audits and batch documentation, while the EU's REACH framework governs industrial chemical registration and the EPA regulates fermentation effluent discharge parameters in US production zones. These overlapping compliance architectures elevate capital barriers for new fermentation entrants and redirect investment toward continuous processing upgrades. Stakeholders must monitor regulatory divergence between pharmaceutical and feed-grade certification pathways to align capacity expansion with the highest-margin demand corridors.
Market Dynamics
Fermentation capacity concentration in China's corn belt is compressing global supply chains as producers consolidate upstream control over carbohydrate feedstock and lysine output within single facility footprints.
Growth Catalysts
- EU F-Gas Regulation:Emission controls on industrial fermentation are accelerating capital deployment toward closed-loop bioreactor systems and carbon capture integration in European production zones.
- Precision livestock nutrition:Swine and poultry integrators are reformulating feed rations to exact amino acid specifications, reducing crude protein waste and expanding lysine inclusion rates.
- Shandong fermentation cluster:Concentrated engineering talent and infrastructure density in this province is sustaining yield optimization leadership and technology transfer velocity.
Market Restraints
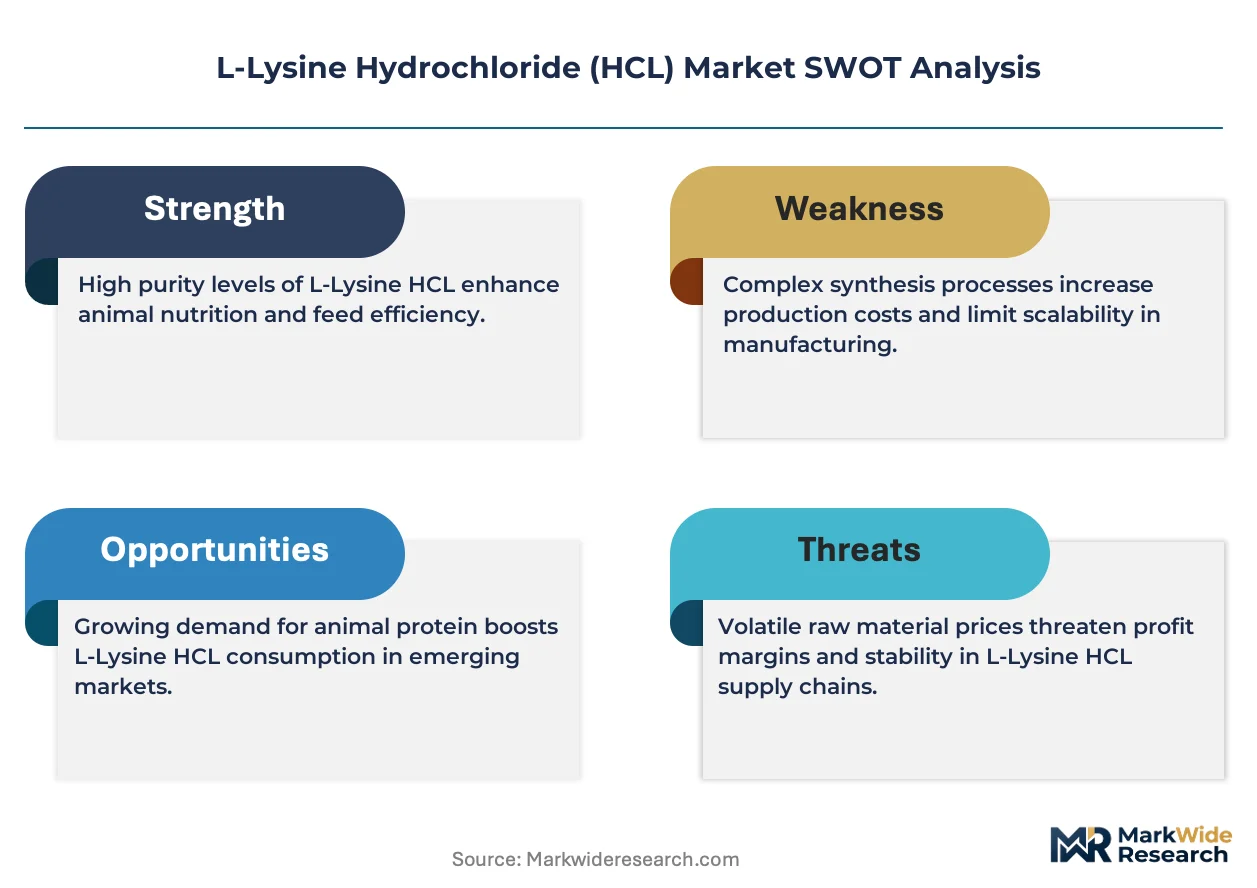
- Corn price volatility:Carbohydrate substrate costs represent the dominant variable in fermentation economics, with drought cycles in major producing regions transmitting directly to margin pressure.
- Single-region supply risk:Overwhelming concentration of fermentation capacity within Chinese provincial boundaries creates exposure to localized regulatory, energy, or logistics disruptions.
- Enzymatic hydrolysis substitution:Alternative lysine production pathways using cell-free systems remain uneconomical at scale but threaten long-term fermentation economics if yield breakthroughs materialize.
Strategic Opportunities
- Nutraceutical channel expansion:Dietary supplement formulators are segmenting products around immune support and athletic recovery positioning, opening premium-grade lysine demand corridors.
- CDMO pharmaceutical qualification:Contract manufacturing relationships with multi-product biologics facilities are creating non-feed revenue streams through GMP-certified lysine for infusion solutions.
- US fermentation effluent standards:EPA discharge parameter enforcement is incentivizing domestic production investment as import-dependent buyers seek supply chain redundancy.
Industry Challenges
- Strain engineering expertise scarcity:Corynebacterium glutamicum metabolic pathway optimization requires specialized synthetic biology talent that concentrates in limited academic and corporate research centers.
- Dual certification complexity:Producers seeking both feed-grade and pharmaceutical-grade output must maintain parallel quality systems, documentation protocols, and audit schedules under divergent regulatory frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | L-Lysine Hydrochloride (HCL) Market |
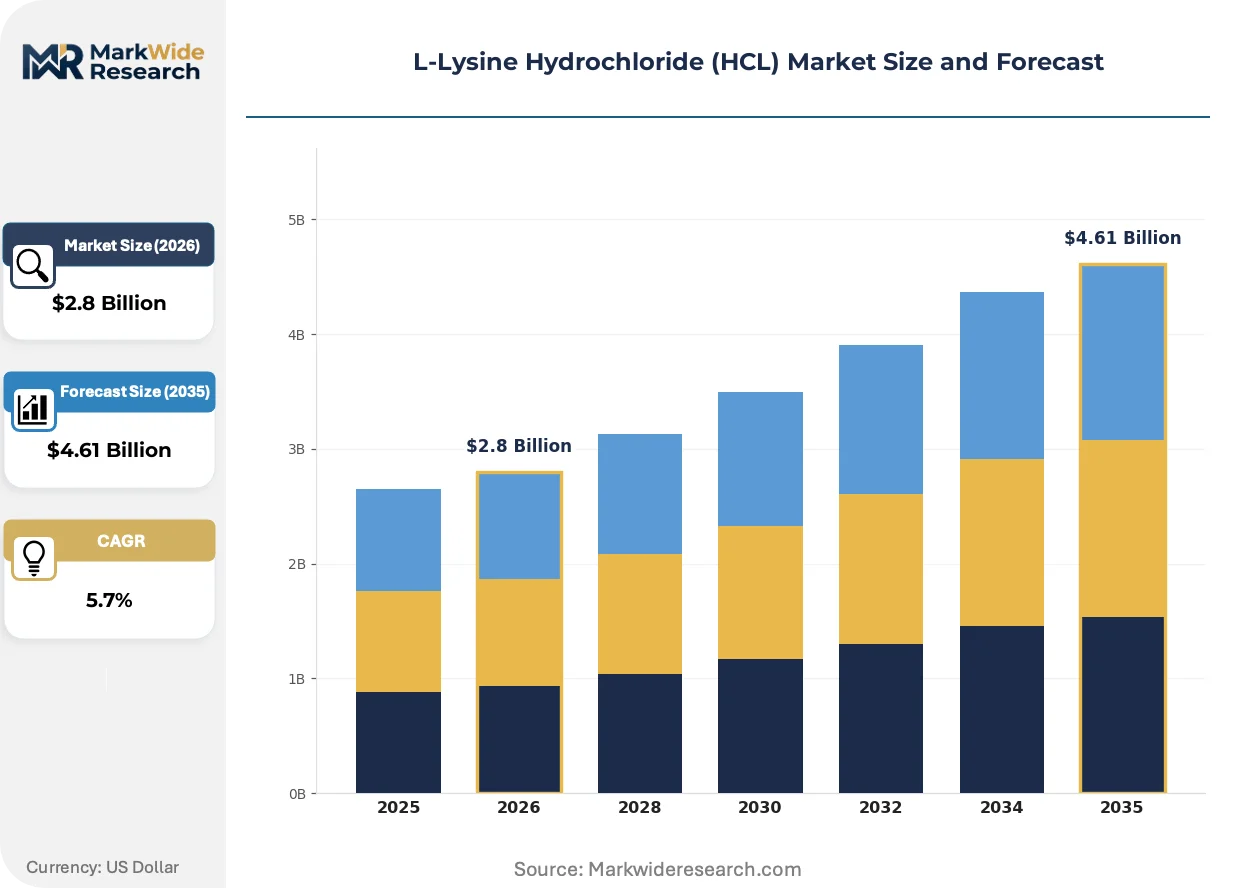
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
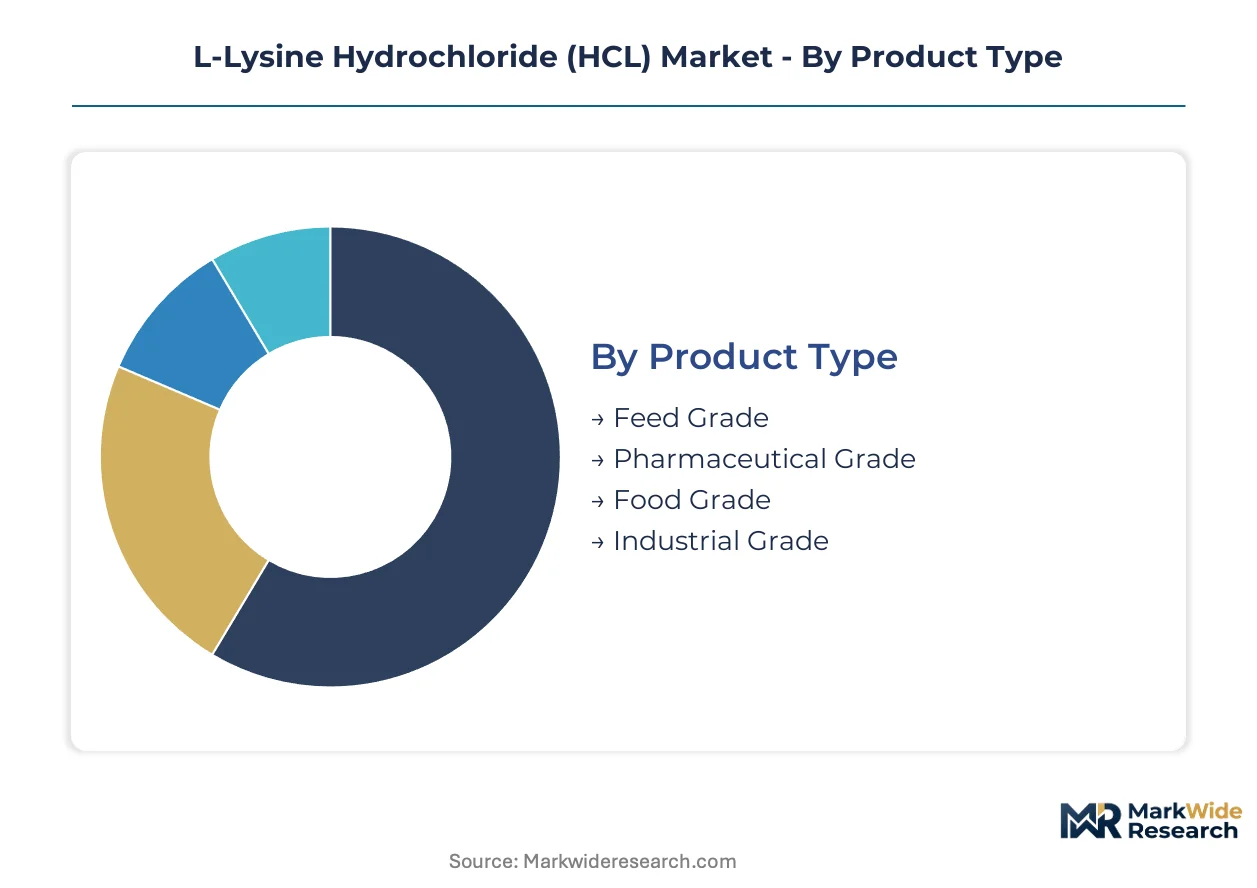
| Segmentation | Product Type: Feed Grade, Pharmaceutical Grade, Food Grade, Industrial Grade Application: Animal Nutrition, Pharmaceutical Formulations, Food Additives, Nutraceuticals End User: Livestock Producers, Pharmaceutical Companies, Food Manufacturers, Dietary Supplement Providers Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Meihua Holdings Group Co., Ltd., Ningxia Eppen Biotech Co., Ltd., Global Bio-Chem Technology Group Company Limited, Ajinomoto Co., Inc., CJ CheilJedang Corporation, Evonik Industries AG, Kyowa Hakko Bio Co., Ltd., Fufeng Group Limited, Archer Daniels Midland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
L-Lysine Hydrochloride (HCL) Market Shifts & Advancements
Continuous processing architectures and digital fermentation control systems are displacing batch manufacturing paradigms, compressing cycle times and enabling real-time quality parameter adjustment throughout the production sequence.
CRISPR-guided strain development is decomposing the traditional yield plateau in Corynebacterium glutamicum fermentation. Biotechnology teams at major amino acid producers are deploying multiplexed genome editing to redirect carbon flux toward lysine biosynthesis pathways. This precision engineering is collapsing the gap between theoretical and achieved yields, forcing capital allocation decisions across legacy batch facilities.
China's NMPA is tightening Good Manufacturing Practice enforcement for pharmaceutical-grade amino acid certification. Facility audit frequency and batch documentation requirements are intensifying, elevating compliance costs for producers serving human nutrition applications. Feed-grade manufacturers are diverging from pharmaceutical qualification pathways, segmenting the supplier base into distinct operational tiers with incompatible capital requirements.
Livestock integrators are consolidating procurement authority through direct contracting relationships with fermentation producers, bypassing traditional distributor intermediaries. Large-scale pork and poultry operations in North America and Europe are negotiating volume commitments and specification guarantees directly with manufacturing entities. This channel compression is most visible in vertically coordinated protein supply chains where feed cost optimization commands procurement priority.
L-Lysine Hydrochloride (HCL) Market Segmentation
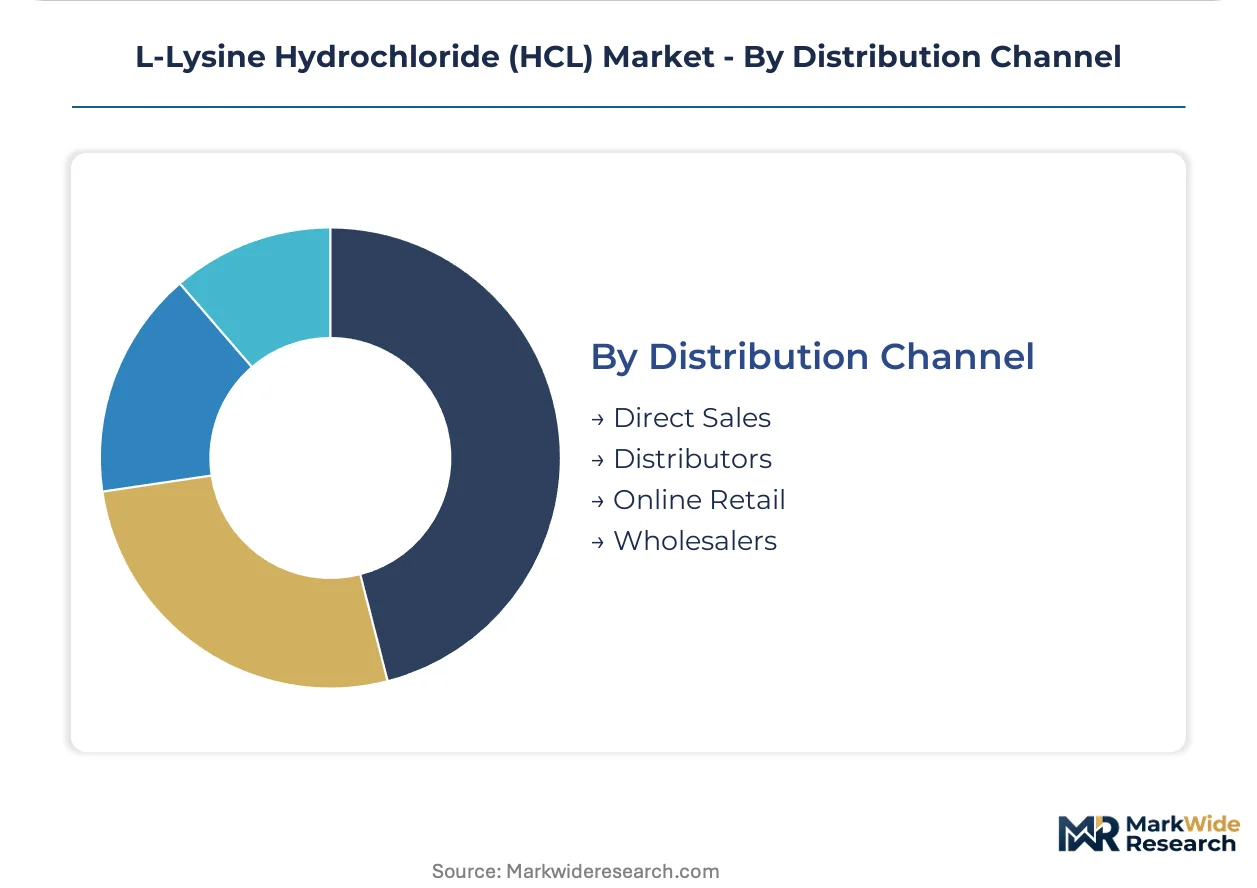
Channel configuration in L-Lysine HCL diverges sharply by grade purity, with feed-grade volumes flowing through bulk procurement contracts while pharmaceutical grades require qualified distributor networks with temperature-controlled logistics and audit documentation capabilities.
Product Type:
Feed Grade channels through direct mill procurement and large-scale distributor contracts, while Pharmaceutical Grade routes through certified chemical distributors with GMP documentation chains and cold-chain integrity guarantees.
- Feed Grade:Crystalline lysine HCL with purity specifications meeting animal nutrition requirements, typically 98 percent minimum. Livestock integrators in Iowa and North Carolina negotiate annual volume commitments directly with fermentation producers to secure feed cost stability. Corn price volatility in the US Midwest transmits immediately to contract renegotiation cycles.
- Pharmaceutical Grade:Purified to 98.5 percent or higher with endotoxin and microbial limits enforced under NMPA or FDA current Good Manufacturing Practice standards. Parenteral nutrition compounders in Germany and infusion solution manufacturers in Japan demand batch-specific certificates of analysis and facility audit reports.
- Food Grade:Intermediate purity tier for fortified food applications with regional safety certifications varying by destination market.
- Industrial Grade:Lowest purity classification for non-nutritional chemical synthesis and industrial biotechnology applications.
By volume, Feed Grade leads. By growth pace, Pharmaceutical Grade is ahead.
Application:
Margin tiering separates commodity amino acid supplementation from condition-specific nutritional positioning, with pharmaceutical and nutraceutical applications commanding price multiples over standard feed inclusion rates.
- Animal Nutrition:Precision amino acid balancing in swine and poultry rations to optimize protein conversion efficiency and reduce nitrogen excretion. Large pork production systems in Denmark and poultry integrators in Thailand drive formulation standardization toward exact lysine specifications.
- Nutraceuticals:Fastest-expanding demand corridor as dietary supplement providers reformulate around immune support, athletic recovery, and metabolic health positioning. Direct-to-consumer brands in California and functional food startups in South Korea are accelerating pharmaceutical-grade lysine incorporation.
- Pharmaceutical Formulations:Parenteral nutrition solutions and infusion therapies requiring endotoxin-controlled lysine HCL with complete supply chain traceability.
- Food Additives:Cereal fortification and processed food enrichment with regional regulatory acceptance determining market access.
By revenue contribution, Animal Nutrition dominates. By expansion trajectory, Nutraceuticals is climbing the fastest.
End User:
Customer scale concentration is compressing channel structures, with top-tier livestock operators and pharmaceutical compounders consolidating procurement authority away from fragmented intermediary layers.
- Livestock Producers:Vertically coordinated pork and poultry operations with in-house nutrition teams specifying exact lysine inclusion rates. Smithfield Foods and JBS USA maintain direct supplier relationships with fermentation producers, bypassing traditional feed additive distributors.
- Dietary Supplement Providers:Contract manufacturers and branded formulators seeking pharmaceutical-grade lysine for capsule, tablet, and powder products. Sports nutrition specialists in Utah and wellness brands in British Columbia are expanding condition-specific product lines.
- Pharmaceutical Companies:Multi-product biologics facilities and parenteral nutrition compounders requiring GMP-certified lysine with drug master file documentation.
- Food Manufacturers:Cereal processors and fortified food producers with regional formulation requirements and cost-sensitive procurement protocols.
By procurement volume, Livestock Producers lead. By specification intensity, Pharmaceutical Companies set the standard.
Distribution Channel:
Channel selection correlates directly with grade certification requirements and customer technical capabilities, with pharmaceutical grades requiring documented custody chains incompatible with commodity wholesaler infrastructure.
- Direct Sales:Volume commitments from livestock integrators and pharmaceutical compounders with technical staff capable of supplier qualification and audit management. This channel captures the majority of feed-grade tonnage and pharmaceutical-grade value.
- Distributors:Certified chemical distributors with GMP warehousing and temperature-controlled logistics serving mid-tier pharmaceutical and food manufacturing customers lacking direct procurement scale.
- Wholesalers:Bulk commodity handlers for feed-grade lysine with limited technical services and standard storage infrastructure.
- Online Retail:Emerging channel for nutraceutical-grade lysine in consumer-packaged formats, currently constrained by pharmaceutical-grade certification requirements.
By tonnage flow, Direct Sales leads. By channel development investment, Distributors are gaining priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry separates Chinese fermentation clusters from European pharmaceutical compounders, with Shandong Province commanding feed-grade volume economics while German parenteral nutrition facilities absorb pharmaceutical-grade premiums.
China
Feed-grade lysine demand concentrates in Shandong and Hebei provinces where vertically integrated corn processors operate captive fermentation facilities. NMPA pharmaceutical-grade certification requirements intensify facility audit frequency for human nutrition applications. The Shandong fermentation cluster sustains yield optimization leadership through concentrated engineering talent pools and infrastructure density.
United States
Livestock integrators in Iowa and North Carolina negotiate direct procurement contracts with fermentation producers to secure feed cost stability. EPA effluent discharge standards for fermentation operations incentivize domestic capacity investment over import dependency. Corn price volatility in the US Midwest transmits immediately to contract renegotiation cycles with lysine suppliers.
Germany
Parenteral nutrition compounders in Bavaria and North Rhine-Westphalia demand endotoxin-controlled lysine with complete supply chain traceability. EU F-Gas Regulation emission controls accelerate capital deployment toward closed-loop bioreactor systems in European production zones. The Rhine-Ruhr chemical corridor hosts qualified distributor networks with GMP warehousing and temperature-controlled logistics.
Japan
Infusion solution manufacturers in Osaka and Tokyo pharmaceutical clusters require batch-specific certificates of analysis and facility audit reports. PMDA enforcement of current Good Manufacturing Practice standards elevates documentation burdens for imported lysine. The Kansai region maintains specialized CDMO relationships for multi-product biologics facilities.
Brazil
Poultry integrators in São Paulo and Paraná states drive formulation standardization toward exact lysine specifications for protein conversion efficiency. ANVISA pharmaceutical regulation creates parallel import pathways for feed-grade versus pharmaceutical-grade certification. The southern agricultural belt concentrates procurement authority through vertically coordinated protein supply chains.
L-Lysine Hydrochloride (HCL) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where biotechnology specialists and commodity-scale fermenters occupy distinct strategic positions. The vendor base separates into strain-engineering innovators, vertically integrated agribusiness conglomerates, and regional fermentation specialists. Two dominant competitive moves define current positioning: backward integration into carbohydrate feedstock control and CDMO qualification for pharmaceutical-grade revenue streams.
Within the scale-driven tier, Meihua Holdings Group Co., Ltd. and Fufeng Group Limited occupy positions anchored in Chinese corn-belt fermentation infrastructure, while CJ CheilJedang Corporation exemplifies biotechnology leadership through metabolic pathway optimization capabilities. These three entities represent the archetype spectrum from upstream agricultural control to synthetic biology yield enhancement, with each concentration forcing capital allocation decisions across legacy batch facilities versus continuous processing architectures.
| Leading Market Players |
|---|
| Meihua Holdings Group Co., Ltd. |
| Ningxia Eppen Biotech Co., Ltd. |
| Global Bio-Chem Technology Group Company Limited |
| Ajinomoto Co., Inc. |
| CJ CheilJedang Corporation |
| Evonik Industries AG |
| Kyowa Hakko Bio Co., Ltd. |
| Fufeng Group Limited |
| Archer Daniels Midland |
| Others |
Supply & Pricing Matrix
Continuous fermentation technology substitution for legacy batch systems is redrawing supply geography toward Shandong Province engineering clusters while compressing pricing economics through yield optimization and cycle time reduction.
Pricing Analysis
The customization-premium spread between pharmaceutical-grade and feed-grade lysine HCL exceeds three-to-one, with parenteral nutrition compounders absorbing endotoxin-controlled pricing while livestock integrators negotiate annual volume commitments against corn price indices. Three-tier pricing structure across pharmaceutical, feed, and industrial grades reflects divergent certification burdens under NMPA, FDA, and feed regulatory frameworks. Cost compression in feed-grade contracts is intensifying because drought cycles in the US Midwest transmit immediately to carbohydrate substrate economics. Livestock producers in Iowa and North Carolina exhibit highest price sensitivity, while German infusion solution manufacturers accept pharmaceutical-grade premiums for batch documentation and cold-chain integrity guarantees.
Supply Chain Analysis
China and the United States anchor global fermentation capacity, with Shandong Province housing vertically integrated corn-to-lysine facilities and EPA-regulated US zones incentivizing domestic investment over import dependency. Corynebacterium glutamicum strain banks, carbohydrate feedstock, and GMP-certified packaging materials constitute critical input dependencies. Single-region concentration risk concentrates in Chinese provincial boundaries, exposing buyers to localized energy disruptions or NMPA regulatory shifts. Distribution runs through direct mill procurement contracts for feed-grade volumes and certified chemical distributors with temperature-controlled logistics for pharmaceutical grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment under NMPA and FDA pharmaceutical-grade certification creates switching costs that protect qualified incumbents from commodity competition.
For Market Incumbents: Compound yield advantages through CRISPR-guided strain engineering investments that collapse the gap between theoretical and achieved fermentation output. Backward integration into corn processing secures carbohydrate feedstock control against drought-driven price volatility. Prioritize pharmaceutical-grade CDMO qualification cycles to capture premium pricing insulated from feed-grade margin compression.
For New Entrants and Emerging Players: Lead with enzymatic hydrolysis pathway development targeting cell-free lysine production as a long-term fermentation substitute. Nutraceutical-grade dietary supplements in North American direct-to-consumer channels offer the most penetrable white space, with condition-specific immune support and athletic recovery positioning commanding price multiples over commodity feed applications. Establish GMP-certified toll manufacturing relationships rather than greenfield fermentation capacity.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors biotechnology specialists with demonstrated strain engineering capabilities over pure-play commodity fermenters. Acquisition targets should demonstrate metabolic pathway optimization IP and existing pharmaceutical-grade audit relationships. Watch EPA effluent standard enforcement intensity as a signal for domestic US capacity investment inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Processing | Shandong-based producers control carbohydrate feedstock costs against Midwest drought volatility. |
| Pharmaceutical-Grade CDMO Qualification | NMPA facility audits enable parenteral nutrition revenue streams with three-to-one pricing premiums. |
| CRISPR Strain Engineering Investment | Multiplexed genome editing redirects carbon flux toward lysine biosynthesis yield breakthroughs. |
| Continuous Fermentation Architecture Deployment | Real-time quality parameter adjustment compresses cycle times versus legacy batch paradigms. |
| Direct Procurement Relationship Consolidation | Smithfield Foods and JBS USA bypass distributors to negotiate specification guarantees with fermenters. |
Research Methodology
Operator-level perspectives from fermentation plant managers, livestock nutrition directors, pharmaceutical procurement leads, and certified chemical distributors anchored the qualitative base. Primary interview findings triangulated against NMPA regulatory filings, EPA effluent discharge records, customs trade data for amino acid imports, and SEC 10-K disclosures from publicly traded agribusiness conglomerates. Bottom-up volume modeling across grade tiers and application channels cross-validated with top-down market sizing from production capacity assessments.
Sensitivity analysis tested forecast robustness across corn price volatility scenarios, regulatory enforcement intensity variations, and strain engineering yield breakthrough timelines. Segmentation dimensions modeled include product grade tier, end-use application, and regional production hub concentration. CAGRs derived from volume trajectory analysis calibrated against historical capacity expansion patterns and demand elasticity parameters from livestock feed formulation optimization trends.
Forecasts assume regulatory continuity in NMPA pharmaceutical-grade certification and EPA effluent discharge regimes; material policy shifts would require re-modeling. Recalibration cycles align with material shifts in corn belt drought frequency, CRISPR yield breakthrough announcements, and pharmaceutical CDMO qualification completion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
Sodium Hexametaphosphate Market
High-Value Chemicals
High-Heat Melamine Foam Market
High-Value Chemicals
High-K Dielectric Material Market
High-Value Chemicals
Barium Hydroxide Monohydrate Market
High-Value Chemicals
High Molecular Ammonium Polyphosphate Market
High-Value Chemicals
Hydroxylamine Sulfate Market
High-Value Chemicals
Global High Purity Oxygen Market
High-Value Chemicals
Sodium Methyl P-Hydroxybenzoate Market
High-Value Chemicals
High Purity MTBE Market
High-Value Chemicals
Hydrogen Isotope Market
High-Value Chemicals
Ammonium Metavanadate Market
High-Value Chemicals
Hydroxynitrile Lyase Market
High-Value Chemicals
Potassium Hydroxide Market
High-Value Chemicals
Global High Dispersible Silica Market
High-Value Chemicals
High Purity Silica Market
High-Value Chemicals
Hydroxyethyl Urea Market