
 High-Nickel NCM Cathode Binder Latex Market | 2026-2036
High-Nickel NCM Cathode Binder Latex Market Size, Share, and Industry Trends Forecast 2026-2036
High-Nickel NCM Cathode Binder Latex Market Insights
Aftermarket technical service revenue for binder formulation optimization is tilting toward cell manufacturers with in-house slurry expertise. Arkema leverages its fluoropolymer heritage to anchor premium binder grades for high-voltage NCM chemistries. Zeon Corporation sustains cost competitiveness through captive butadiene supply and integrated emulsion polymerization assets. JSR Corporation specializes in carboxylated styrene-butadiene variants that dominate Korean battery maker qualification lists.
High-nickel NCM cathode binder latex comprises waterborne polymer dispersions, typically 40-60% solids content, that mechanically bind active cathode particles to aluminum current collectors while maintaining ionic conductivity and electrochemical stability across 4.3-4.5 V operating windows. SBR latex formulations occupy the volume tier for mainstream electric vehicle batteries where cost-per-kWh dominates procurement criteria, while acrylic latex and carboxylated styrene-butadiene grades capture margin pools in energy storage systems requiring extended calendar life. Emulsion polymerization remains the incumbent manufacturing route, though radical polymerization variants are gaining traction for tailored particle size distributions that improve coating uniformity.
Korea's MFDS chemical safety assessments, China's GB/T battery standards, and the EU's REACH authorization framework collectively constrain binder chemistries and accelerate substitution of legacy formulations. Japan's METI circular economy guidelines for batteries are extending producer responsibility to binder material recovery, reshaping formulation design priorities. Stakeholders must monitor qualification timelines at Korean and Chinese cell producers, as binder switching costs and dual-source requirements determine competitive access to volume contracts.
Market Dynamics
Cell manufacturers are consolidating binder specifications around high-voltage NCM chemistries, forcing latex suppliers to accelerate qualification cycles and reformulate for 4.5 V stability thresholds.
Growth Catalysts
- EU Battery Regulation:Mandatory recycled content quotas and carbon footprint declarations are compelling cathode producers to source traceable, waterborne binders with verified supply chain documentation.
- Energy storage systems:Grid-scale battery deployments require 20-year calendar life, driving qualification of carboxylated SBR grades that suppress aluminum current collector corrosion at elevated voltages.
- Gwangju-Ulsan corridor:South Korea's cathode production clusters are expanding captive slurry mixing capacity, creating localized demand pull for just-in-time binder delivery contracts.
Market Restraints
- Butadiene price volatility:SBR latex formulations remain exposed to naphtha-cracker feedstock swings, compressing margin visibility for emulsion polymerization operators without captive butadiene.
- Chinese supply concentration:Over 60% of waterborne acrylic dispersions originate from Zhejiang and Jiangsu provinces, creating single-source vulnerability for non-integrated cell makers.
- REACH authorization:Legacy fluoropolymer additives face sunset dates under EU chemical safety frameworks, forcing costly reformulation of high-voltage binder grades before 2030.
Strategic Opportunities
- Solid-state battery interfaces:Semi-solid and all-solid cell architectures require novel binder chemistries that maintain particle adhesion without liquid electrolyte wetting, opening formulation white space.
- Japan METI circular economy guidelines:Extended producer responsibility mandates are creating service revenue pools for binder recovery and closed-loop polymer regeneration.
- Direct coating equipment:Slot-die and micro-gravure lines are enabling dry-binder deposition trials that could displace wet slurry processes in pilot production lines.
Industry Challenges
- Electrochemical characterization expertise:Cell manufacturers lack in-house polymer science capabilities to validate binder-cathode interface stability, extending qualification timelines.
- Dual-source compliance:Korean and Chinese cell makers require identical binder specifications from geographically separate suppliers, complicating process scale-up.
- Patent thickets around carboxylation:JSR Corporation and Zeon hold overlapping intellectual property on styrene-butadiene acid modification, creating licensing friction for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Nickel NCM Cathode Binder Latex Market |
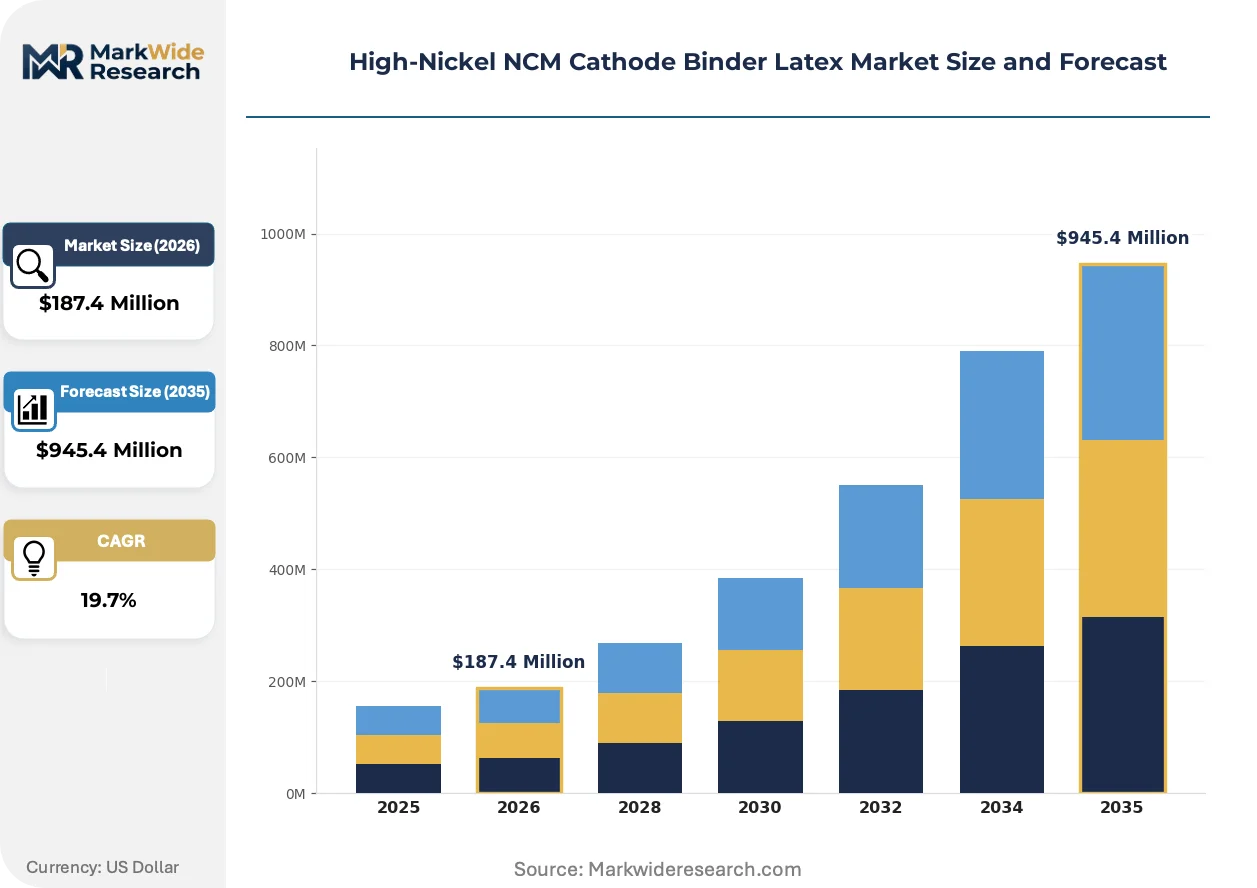
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $945.4 Million |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SBR Latex, NBR Latex, Acrylic Latex, Styrene-Acrylic Copolymer, Carboxylated Styrene-Butadiene, Vinyl Acetate-Ethylene Technology: Emulsion Polymerization, Solution Polymerization, Suspension Polymerization, Bulk Polymerization, Anionic Polymerization, Radical Polymerization Application: Electric Vehicle Batteries, Energy Storage Systems, Consumer Electronics Cells, Grid Storage Batteries, Portable Power Banks, Aerospace Power Units End User: Battery Manufacturers, Power Tool Makers, Consumer Electronics Companies, Aerospace Component Suppliers, Energy Storage Integrators, Specialty Chemical Producers |
| Companies Covered | Arkema, Solvay, Zeon Corporation, Kureha, JSR Corporation, Shin-Etsu Chemical, BASF, Dongyue Group, Orbia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Nickel NCM Cathode Binder Latex Market Trends and Innovations
Binder technology is fragmenting along voltage-class lines, with distinct formulation families emerging for mainstream EV cells, high-nickel premium segments, and next-generation solid-state architectures.
Waterborne acrylic latex is migrating from energy storage system niche applications toward high-voltage EV cathodes, with Korean cell makers adopting 45% solids grades for 4.4 V NCM811 cells. The technology is compressing the traditional SBR-acrylic price gap while enabling thinner coating weights that improve volumetric energy density.
China's NMPA battery safety standards are tightening thermal runaway propagation requirements, compelling binder suppliers to demonstrate flame-retardant performance in composite cathode formulations. Cell makers are responding by qualifying halogen-free SBR grades with phosphorus-modified backbones, particularly for passenger EV platforms targeting domestic certification.
Aftermarket technical service contracts are unbundling from base material supply, with cell manufacturers paying separately for slurry optimization support and coating defect troubleshooting. This model is displacing bundled pricing in South Korea's cathode supply chain, where in-house expertise gaps at second-tier cell makers create consultative revenue opportunities for incumbent latex suppliers.
High-Nickel NCM Cathode Binder Latex Market Segmentation
Binder selection in high-nickel NCM cathodes hinges on voltage stability, coating uniformity, and regulatory compliance across distinct end-use environments. Segmentation reveals how formulation chemistry, manufacturing route, and customer integration depth determine competitive positioning and margin capture in this rapidly expanding market.
Product Type:
Cost tier differentiation separates commodity volume formulations from specialty grades engineered for extended cycle life and high-voltage stability.
- SBR Latex:Styrene-butadiene rubber dispersions at 40-50% solids content dominate mainstream electric vehicle procurement where cost-per-kWh dictates supplier selection. Korean cathode producers around Gwangju and Ulsan are consolidating specifications around halogen-free SBR grades that satisfy China's NMPA thermal runaway propagation standards.
- Acrylic Latex:Waterborne polyacrylate dispersions deliver superior aluminum current collector corrosion suppression at 4.4-4.5 V operating windows. Energy storage system integrators in South Korea are accelerating qualification of 45% solids acrylic grades for 20-year calendar life requirements.
- NBR Latex:Nitrile rubber variants provide oil resistance and mechanical toughness for specialty aerospace applications requiring extreme temperature cycling tolerance.
- Styrene-Acrylic Copolymer:Hybrid backbones balance cost position of SBR with voltage stability of pure acrylics, finding traction in consumer electronics cells with moderate cycle life demands.
- Carboxylated Styrene-Butadiene:Acid-modified SBR grades with enhanced particle adhesion and electrolyte compatibility are climbing Korean battery maker qualification lists for premium EV platforms.
- Vinyl Acetate-Ethylene:VAE copolymers offer low-temperature flexibility and cost advantages in portable power bank applications where energy density requirements are less stringent.
SBR Latex holds installed capacity across Asian cathode supply chains. Carboxylated Styrene-Butadiene is rotating up the share rankings as high-nickel chemistries proliferate.
Technology:
Manufacturing route selection governs particle size distribution precision, production scale economics, and formulation customization latitude.
- Emulsion Polymerization:The incumbent aqueous-phase process produces 100-300 nm latex particles with controlled molecular weight distribution for uniform cathode coating. Zeon Corporation and JSR Corporation operate captive emulsion assets in Japan and Korea that supply qualified volumes to regional cell makers.
- Radical Polymerization:Initiator-controlled chain growth enables tailored particle architectures with narrow size distributions that improve coating defect rates on high-speed electrode lines. Korean equipment suppliers are piloting radical polymerization modules for just-in-time binder production adjacent to cathode coating facilities.
- Solution Polymerization:Homogeneous phase reactions in organic solvents produce high-purity polymers for specialty aerospace power units where metallic contamination must be minimized.
- Suspension Polymerization:Bead-forming processes yield larger particle sizes suitable for thick-film electrode applications in grid storage batteries.
- Bulk Polymerization:Solvent-free mass polymerization offers cost advantages at scale but requires precise thermal control to prevent runaway reactions in high-viscosity media.
- Anionic Polymerization:Living polymerization techniques deliver exceptionally narrow polydispersity for research-grade binder materials used in solid-state battery interface development.
Emulsion Polymerization anchors current supply capacity. Radical Polymerization variants are expanding most quickly as equipment OEMs commercialize modular production systems.
Application:
Voltage class and cycle life requirements fragment demand across mobility, stationary storage, and portable power segments with distinct binder performance thresholds.
- Electric Vehicle Batteries:High-nickel NCM811 and NCM9½½ cathodes for passenger EV platforms require binders maintaining adhesion and ionic conductivity across 4.3-4.5 V charge cycles. EU Battery Regulation carbon footprint declarations are compelling traceable, waterborne binder sourcing with verified supply chain documentation.
- Energy Storage Systems:Grid-scale deployments demand 20-year calendar life with minimal capacity fade, driving adoption of carboxylated SBR and acrylic grades that suppress aluminum corrosion at elevated float voltages.
- Consumer Electronics Cells:Smartphone and laptop batteries prioritize volumetric energy density and fast-charge compatibility over extended cycle life, accepting standard SBR formulations.
- Grid Storage Batteries:Utility-scale installations emphasize capital cost minimization and fire safety certification, favoring halogen-free SBR with phosphorus-modified backbones.
- Portable Power Banks:Cylindrical and pouch cell formats for mobile power prioritize manufacturing throughput and cost compression.
- Aerospace Power Units:Satellite and aircraft applications require radiation-resistant binders with extreme temperature tolerance and outgassing control.
Electric Vehicle Batteries command the dominant demand position. Energy Storage Systems are climbing the fastest as grid deployment accelerates under Japan METI and EU Green Deal policy frameworks.
End User:
Customer integration depth and in-house polymer expertise determine whether binder supply includes technical service components or pure material delivery.
- Battery Manufacturers:Tier-one cell makers in South Korea and China operate captive slurry mixing lines that demand just-in-time binder delivery with batch-to-batch consistency certification. Aftermarket technical service contracts for formulation optimization are unbundling from base material supply as in-house expertise gaps persist at second-tier producers.
- Power Tool Makers:Cordless equipment OEMs require high-discharge-rate cells with mechanical robustness for vibration-intensive applications, specifying toughened SBR grades.
- Consumer Electronics Companies:Smartphone and laptop brands delegate cell procurement to contract manufacturers, exerting indirect pressure on binder specifications through tiered supplier requirements.
- Aerospace Component Suppliers:Satellite and defense contractors impose stringent qualification protocols and traceability documentation that favor established Japanese and European latex producers.
- Energy Storage Integrators:Utility-scale project developers are consolidating procurement around vertically integrated cell suppliers, reducing direct binder sourcing decisions.
- Specialty Chemical Producers:Distributors and compounders serving niche industrial battery applications require small-batch flexibility and rapid formulation customization.
Battery Manufacturers retain the deepest specification influence. Energy Storage Integrators are rotating up the share rankings as project-scale procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in South Korea and Japan exhibit the lowest price elasticity, prioritizing qualification speed and batch consistency over unit cost. Chinese cell manufacturers operate at the opposite extreme, driving hard bargains on SBR latex while tolerating longer qualification cycles for domestic suppliers.
South Korea
Gwangju and Ulsan cathode production clusters are expanding captive slurry mixing capacity at industrial scale. MFDS chemical safety assessments are tightening documentation requirements for imported binder chemistries. Korean cell makers are consolidating procurement around halogen-free SBR grades that satisfy domestic certification protocols.
China
Zhejiang and Jiangsu provinces supply over sixty percent of waterborne acrylic dispersions consumed across Asia. NMPA battery safety standards are mandating flame-retardant performance demonstrations for composite cathode formulations. Domestic cell producers are qualifying phosphorus-modified SBR backbones for passenger EV platforms targeting domestic certification.
Japan
Tokyo and Osaka metropolitan areas host polymer science expertise concentrated at legacy chemical conglomerates. METI circular economy guidelines are extending producer responsibility to binder material recovery and closed-loop regeneration. Japanese equipment suppliers are piloting radical polymerization modules for just-in-time production adjacent to cathode coating lines.
Germany
Automotive OEM supply chain integration is driving demand for traceable, waterborne binders with verified carbon footprint documentation. EU Battery Regulation recycled content quotas and REACH authorization frameworks are constraining legacy fluoropolymer formulations. Industrial clusters in North Rhine-Westphalia are developing qualification protocols for high-voltage acrylic grades.
United States
Domestic cell manufacturing investments under the Inflation Reduction Act are creating localized demand for qualified binder supply. EPA and OSHA frameworks are governing chemical handling standards at electrode production facilities. Michigan and Ohio battery plant developments are attracting technical service contracts from established latex suppliers.
High-Nickel NCM Cathode Binder Latex Market Competitive Landscape
Capability concentration sits with Japanese and Korean specialists possessing decades of emulsion polymerization expertise; scale advantage sits with Chinese state-affiliated chemical groups commanding integrated feedstock positions. The market structure is tiered between premium qualified suppliers serving tier-one cell makers and commodity producers competing on unit economics. Three archetypes dominate: fluoropolymer heritage players, captive butadiene-integrated operators, and carboxylated SBR specialists. Competitive moves center on dual-source qualification facilitation and backward integration into butadiene supply.
Within the Japanese specialist tier, JSR Corporation and Zeon Corporation exemplify contrasting strategic positions. JSR anchors the carboxylated styrene-butadiene segment through acid modification expertise. Zeon occupies a position defined by captive butadiene supply and integrated emulsion assets. Arkema represents the fluoropolymer heritage archetype, leveraging specialty chemical lineage for high-voltage grade positioning.
| Leading Market Players |
|---|
| Arkema |
| Solvay |
| Zeon Corporation |
| Kureha |
| JSR Corporation |
| Shin-Etsu Chemical |
| BASF |
| Dongyue Group |
| Orbia |
| Others |
Pricing and Supply Chain Analysis
Zhejiang and Jiangsu provinces anchor Asian waterborne acrylic dispersion capacity, and their feedstock integration dynamics transmit directly into pricing leverage for qualified SBR latex grades serving Korean cathode producers. Binder suppliers without captive butadiene assets face compressed margin visibility as naphtha-cracker economics swing, while integrated operators extract premium pricing through batch consistency certification demanded by Gwangju-Ulsan cell manufacturing clusters.
Pricing Analysis
Aftermarket technical service revenue streams now drive lifetime value capture beyond base material supply, with Korean cell manufacturers paying separately for slurry optimization and coating defect troubleshooting. Three-tier pricing structure across premium, standard, and economy levels separates carboxylated SBR grades qualified for 4.5 V NCM811 cells from commodity halogen-free formulations and unbundled technical support contracts. Cost compression in standard SBR tiers is intensifying because Chinese state-affiliated chemical groups leverage integrated feedstock positions, while battery manufacturers with in-house polymer expertise exhibit lowest price sensitivity and second-tier Korean producers show highest elasticity.
Supply Chain Analysis
Tariff exposure between China and South Korea dominates supply chain risk calculations for non-integrated cell makers sourcing qualified binder volumes. Over sixty percent of waterborne acrylic dispersions originate from Zhejiang and Jiangsu provinces, and South Korean cathode production clusters draw from Japanese emulsion polymerization assets for acid-modified SBR grades. Single-source vulnerability concentrates around Chinese acrylic supply and Japanese carboxylation expertise, with distribution running through just-in-time delivery contracts anchored to captive slurry mixing capacity at Gwangju and Ulsan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against dry-binder deposition technologies piloted on slot-die and micro-gravure coating lines, where elimination of wet slurry processes would collapse incumbent latex supplier relevance.
For Market Incumbents: Pre-empt qualification displacement by accelerating backward integration into butadiene supply and securing dual-source certification at Chinese cell producers before direct coating equipment reaches commercial scale. Patent licensing friction around carboxylation chemistry demands defensive IP portfolio expansion to block emerging entrant formulation access.
For New Entrants and Emerging Players: Build out radical polymerization module deployment adjacent to Korean cathode coating facilities, targeting the technical service gap at second-tier cell manufacturers lacking in-house slurry expertise. Solid-state battery interface development presents the most penetrable white space, with novel binder chemistries for semi-solid architectures offering qualification runway before incumbent fluoropolymer heritage players adapt.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors captive butadiene-integrated operators with established emulsion assets and Korean qualification relationships over pure-play formulation specialists exposed to feedstock volatility. Acquisition targets should demonstrate active MFDS chemical safety assessment navigation and existing dual-source supply contracts; the inflection signal to watch is dry-binder deposition trial outcomes at pilot production lines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Butadiene Supply | Captive feedstock control insulates margin visibility against naphtha-cracker price swings at emulsion polymerization operators. |
| Dual-Source Qualification Facilitation | Korean and Chinese cell maker procurement requirements demand geographically separated supplier redundancy for volume contract access. |
| Carboxylation Patent Portfolio Expansion | Defensive IP positioning around acid-modified SBR chemistry blocks emerging entrant access to premium EV platform qualifications. |
| Radical Polymerization Module Deployment | Modular production systems adjacent to cathode coating lines enable just-in-time binder delivery with tailored particle size distributions. |
| Solid-State Battery Interface Development | Novel binder chemistries for semi-solid and all-solid architectures open formulation white space before liquid electrolyte elimination. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC and TSE filings, MFDS chemical safety assessment records, and EU REACH authorization documentation. Plant managers at Japanese emulsion polymerization facilities, procurement leads at Korean cathode producers, technical R&D directors at acrylic dispersion specialists, and aftermarket service heads at qualified latex suppliers provided operational perspective. Bottom-up volume modeling triangulates against top-down value estimates derived from disclosed capacity expansions and contract manufacturing relationships.
Segmentation across product type, manufacturing technology, voltage class application, and customer integration depth structures the analytical framework across the analysis window. CAGRs emerge from elasticity-adjusted demand curves incorporating butadiene feedstock cost trajectories, NMPA and EU Battery Regulation compliance cost pass-through assumptions, and solid-state battery commercialization timeline scenarios. Forecast inputs include cathode production capacity buildouts at Gwangju-Ulsan clusters, Chinese state-affiliated chemical group capacity utilization rates, and dry-binder deposition pilot line commissioning announcements.
Practitioners should monitor butadiene price volatility, REACH authorization sunset dates for legacy fluoropolymer additives, and dry-binder deposition trial outcomes for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
High Molecular Ammonium Polyphosphate Market
High-Value Chemicals
Hydroxynitrile Lyase Market
High-Value Chemicals
Asia-Pacific Hydrogen Bromide Market
High-Value Chemicals
Global High Purity AHCL Market
High-Value Chemicals
Global High Potency Apis /HPAPI Market
High-Value Chemicals
Global High Dispersible Silica Market
High-Value Chemicals
Hydroxocobalamin Chloride Market
High-Value Chemicals
L-Lysine Hydrochloride (HCL) Market
High-Value Chemicals
Battery Grade High Purity Lithium Fluoride Market
High-Value Chemicals
High Purity Isobutylene (HPIB) Market
High-Value Chemicals
Hydroxyethyl Urea Market
High-Value Chemicals
High Purity Benzenethiol Market
High-Value Chemicals
High Performance Fluoropolymers Market
High-Value Chemicals
High Methoxyl Pectin Market
High-Value Chemicals
Phenanthroline Monohydrate Market
High-Value Chemicals
Hydroxylamine Sulfate Market