
 High-K Dielectric Material Market | 2026-2036
High-K Dielectric Material Market Size, Share, and Industry Trends Forecast 2026-2036
High-K Dielectric Material Market Analysis
Gate-all-around transistor architecture is reshaping material requirements across advanced semiconductor manufacturing. Applied Materials, Inc. leverages its deposition equipment portfolio to anchor high-k process integration at leading foundries. Samsung Electronics Co., Ltd. sustains captive hafnium oxide supply chains for its vertically integrated memory and logic operations. TSMC dominates leading-edge node demand by controlling specification standards for dielectric thickness and interface quality.
High-K dielectric materials are insulating compounds with dielectric constants substantially exceeding silicon dioxide, typically hafnium oxide with k-values near 25 and thicknesses scaled below 3 nanometers, deposited via atomic layer chemical vapor deposition to minimize gate leakage current in sub-7nm transistors. Hafnium oxide leads product type demand due to its thermodynamic stability on silicon and established integration protocols, while barium titanate captures growing capacitor applications in RF front-end modules. Semiconductor devices anchor application demand, though memory devices represent the fastest-growing segment as DRAM and NAND scaling accelerates replacement of conventional oxides.
The EPA governs hafnium precursor handling and waste discharge from U.S. deposition facilities, while REACH restricts perfluorinated precursor chemistries across European supply chains, and China's MEE enforces dual carbon goals that elevate energy efficiency requirements for high-k manufacturing processes. These frameworks collectively elevate compliance costs and favor suppliers with integrated environmental management systems. Stakeholders must monitor evolving precursor chemistry restrictions and sovereign subsidy qualification criteria to secure long-term supply positions.
Market Dynamics
Gate-all-around transistor migration at sub-3nm nodes is compressing dielectric thickness tolerances below atomic precision, forcing simultaneous advances in deposition equipment and precursor purity standards across semiconductor fabrication networks.
Growth Catalysts
- Sub-7nm Logic Scaling:Leading foundries mandate hafnium oxide gate stacks for FinFET and nanosheet architectures, sustaining precursor demand through node transitions.
- REACH Perfluorinated Restrictions:European supply chain chemistry constraints accelerate qualification of alternative fluorine-free precursors at deposition equipment vendors.
- Taiwan-Korea Cluster Expansion:Concentrated foundry and memory fab buildouts in Hsinchu and Pyeongtaek generate localized high-k material procurement pull.
Market Restraints
- Hafnium Metal Price Volatility:Zirconium co-production dependency and aerospace alloy competition create input cost instability for oxide precursors.
- Deposition Equipment Oligopoly:Atomic layer deposition tool supply concentrates among three equipment vendors, creating capacity bottlenecks for process qualification.
- Silicon Dioxide Persistence:Mature node fabs and power semiconductor manufacturers continue deploying thermally grown oxides below cost-driven switching thresholds.
Strategic Opportunities
- India Semiconductor Mission:PLI scheme incentives for domestic fab construction create virgin high-k material demand from greenfield process qualification.
- RF Front-End Module Integration:Barium titanate and strontium titanate variants penetrate 5G millimeter-wave filter applications through permittivity tuning.
- Atomic Layer Deposition-Etch Convergence:Sequential deposition and selective removal process integration enables new three-dimensional gate stack architectures.
Industry Challenges
- Atomic-Scale Defect Engineering:Interface trap density control at sub-nanometer equivalent oxide thickness demands specialized metrology and process engineering talent pools that remain shallow.
- Multi-Node Process Qualification:Foundry customers require simultaneous high-k stack optimization across five or more node generations, fragmenting R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-K Dielectric Material Market |
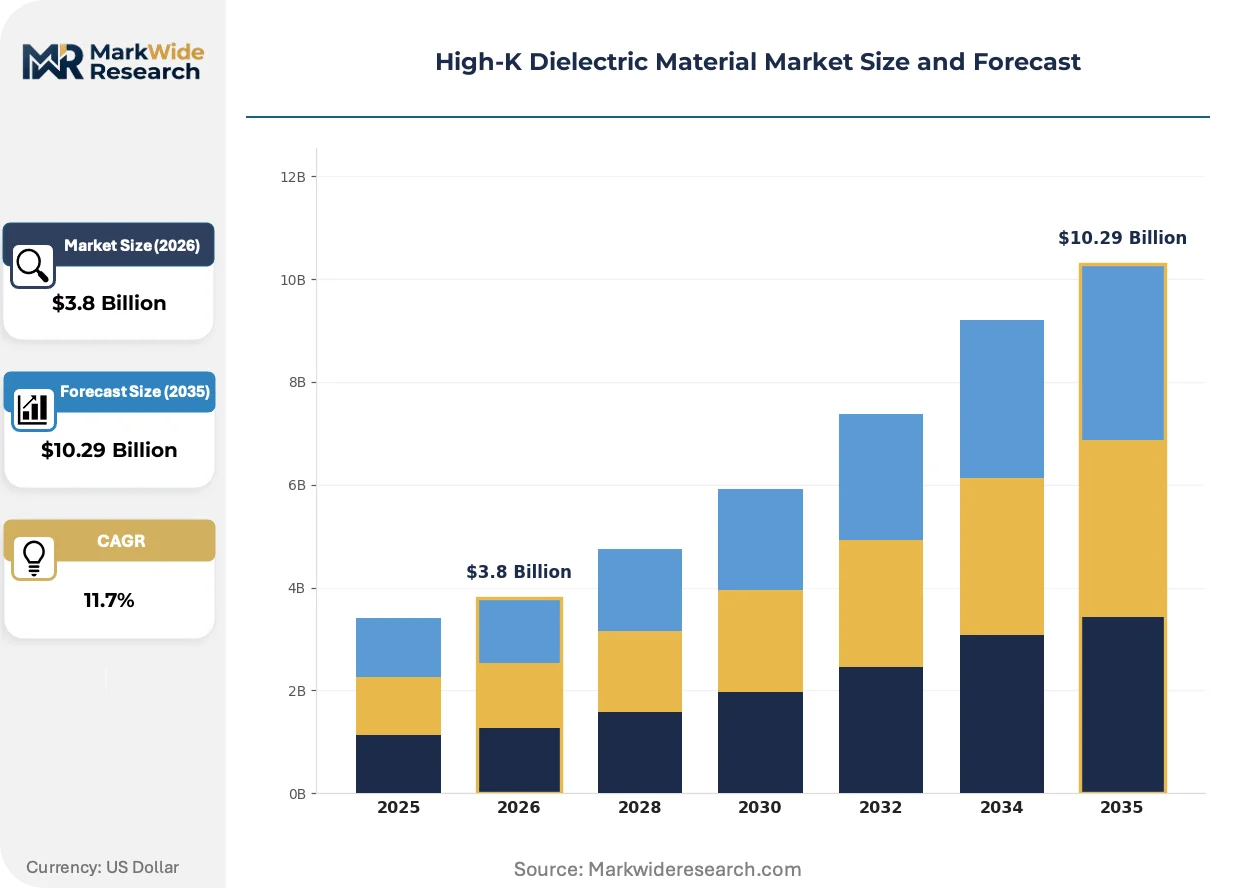
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hafnium Oxide, Barium Titanate, Lanthanum Aluminate, Yttrium Oxide Application: Semiconductor Devices, Capacitors, RF Filters, Memory Devices End User: Consumer Electronics, Automotive, Telecommunications, Aerospace Technology: Chemical Vapor Deposition, Physical Vapor Deposition, Sputtering, Epitaxial Growth |
| Companies Covered | Applied Materials, Inc., Henkel Corporation, Samsung Electronics Co., Ltd., Taiwan Semiconductor Manufacturing Company (TSMC), Intel Corporation, HITEK Electronic Materials Ltd., Master Bond, Inc., Arkema Group, National Magnetics Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-K Dielectric Material Market Emerging Trajectories
Process integration complexity at atomic dimensions is forcing convergence between material science, equipment engineering, and environmental compliance functions across semiconductor supply chains.
Gate dielectric engineering is collapsing toward single-digit angstrom equivalent oxide thickness through hafnium zirconium oxide adoption. Memory manufacturers at 1-alpha and 1-beta DRAM nodes deploy these higher-k compositions to suppress leakage without sacrificing capacitance. This material transition is collapsing the historical separation between logic and memory high-k specifications, forcing unified precursor qualification protocols.
China's MEE dual carbon enforcement tightens energy efficiency benchmarks for deposition process thermal budgets and precursor waste treatment. Facilities in Shanghai and Beijing must demonstrate carbon intensity reductions per wafer processed or face operating permit restrictions. High-k suppliers respond by qualifying lower-temperature plasma-enhanced atomic layer deposition chemistries.
Long-term supply agreements now dominate procurement for leading-edge foundries, displacing spot market precursor purchases. TSMC and Samsung negotiate five-year hafnium precursor contracts directly with chemical suppliers, compressing distributor margins. This concentration is most visible in Taiwan, where foundries account for over half of regional high-k material procurement volume.
High-K Dielectric Material Market Segmentation
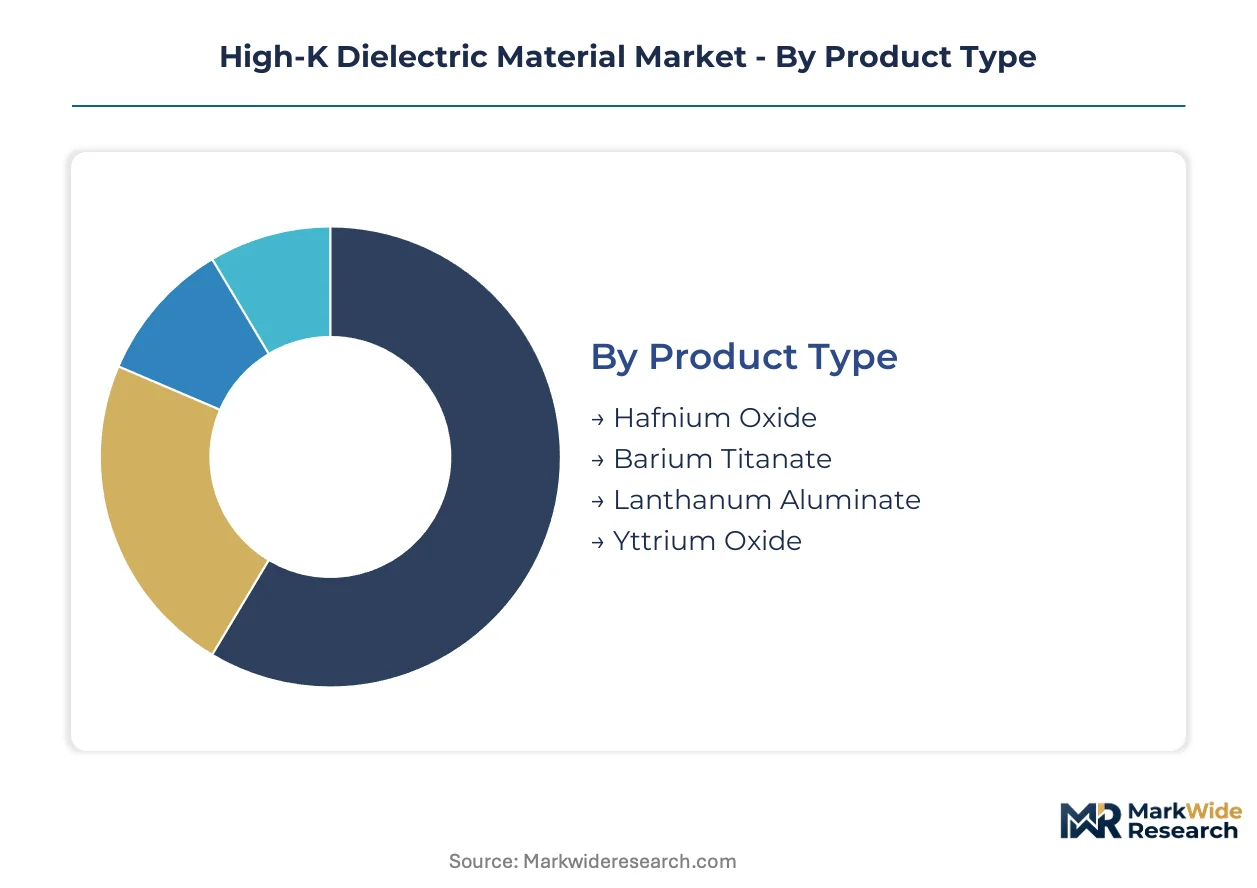
High-k dielectric procurement patterns diverge sharply across material chemistry, deposition technology, and end-use performance requirements. Foundry qualification protocols and automotive reliability standards create distinct specification tiers that reshape supplier positioning.
Product Type:
Cost tier differentiation separates premium hafnium-based formulations from commodity titanate alternatives in wafer-level procurement.
- Hafnium Oxide:Thermodynamically stable on silicon with k-values near 25, this oxide dominates sub-7nm gate stack applications through established atomic layer deposition integration. TSMC and Samsung foundries in Taiwan and South Korea anchor procurement volumes as FinFET and nanosheet architectures displace legacy dielectrics.
- Barium Titanate:Perovskite-structured ferroelectric with permittivity exceeding 1000 enables high-density capacitor integration in 5G RF front-end modules. Smartphone manufacturers in Shenzhen and Seoul drive specification tightening for millimeter-wave filter applications.
- Lanthanum Aluminate:Wide bandgap insulator with moderate k-values serves specialized interface engineering in III-V compound semiconductor devices.
- Yttrium Oxide:Rare-earth oxide alternative offers cost positioning for power electronics and mature node applications where leakage requirements relax.
Hafnium oxide holds installed capacity. Barium titanate is rotating up the share rankings.
Application:
Application focus determines thermal budget constraints and interface quality specifications across deposition process selection.
- Semiconductor Devices:Logic transistors at sub-3nm nodes demand equivalent oxide thickness below single-digit angstroms, forcing hafnium zirconium oxide adoption. Leading foundries in Hsinchu and Pyeongtaek compress qualification timelines as gate-all-around migration accelerates.
- Memory Devices:DRAM capacitor scaling at 1-alpha and 1-beta nodes collapses historical separation between logic and memory high-k specifications. Samsung and SK Hynix captive consumption in South Korea reshapes precursor supply contract structures.
- Capacitors:Embedded passive integration in advanced packaging drives barium strontium titanate demand for decoupling applications.
- RF Filters:5G base station deployment and smartphone millimeter-wave adoption expand permittivity-tuned dielectric requirements.
Semiconductor devices command qualification resources. Memory devices are climbing the fastest in procurement priority.
End User:
Customer type segmentation reflects reliability grade differentiation and volume scale thresholds in material procurement.
- Consumer Electronics:Smartphone and tablet manufacturers drive the steepest expansion trajectory through annual flagship release cycles and foundry capacity reservation. Apple and Android OEMs in Cupertino and Shenzhen concentrate specification influence.
- Automotive:AEC-Q100 qualification requirements and functional safety standards extend high-k material validation timelines. Powertrain electrification in Stuttgart and Toyota City expands silicon carbide gate oxide demand.
- Telecommunications:Base station infrastructure deployment sustains RF component dielectric procurement through Huawei, Ericsson, and Nokia supply chains.
- Aerospace:Radiation-hardened specifications and extreme temperature operation constrain qualified material sources for satellite and defense applications.
Consumer electronics holds procurement volume concentration. Automotive is rotating up the priority rankings.
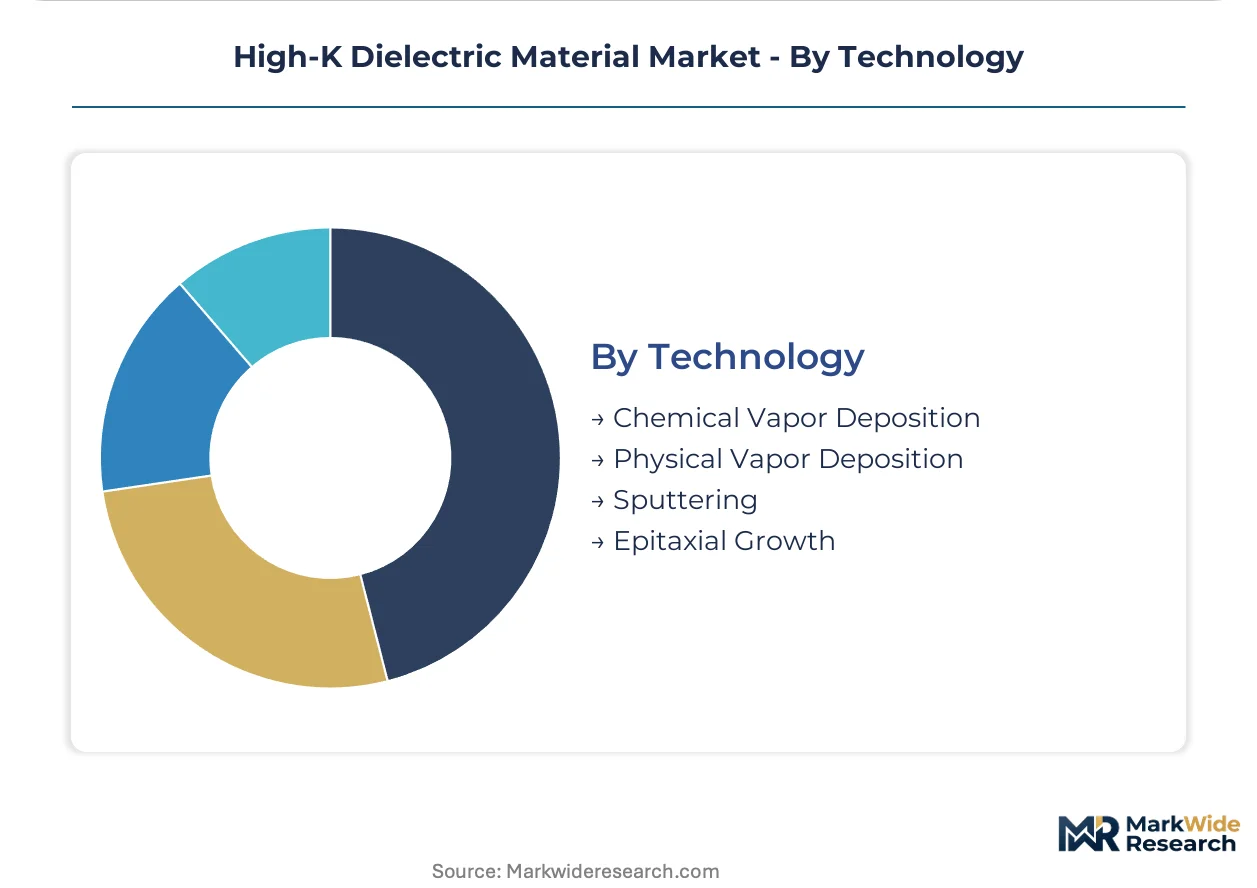
Technology:
Deposition method selection governs thickness uniformity, conformality, and throughput tradeoffs in high-k film formation.
- Chemical Vapor Deposition:Atomic layer deposition variants deliver sub-angstrom thickness control for sub-7nm gate stacks. Applied Materials and Tokyo Electron equipment installations in Taiwan and South Korea constrain qualified precursor supply.
- Physical Vapor Deposition:Sputtering approaches persist in cost-sensitive applications and back-end-of-line integration where conformality requirements relax.
- Sputtering:Magnetron configurations serve RF filter and capacitor electrode deposition with established throughput economics.
- Epitaxial Growth:Molecular beam epitaxy and metal-organic chemical vapor deposition enable crystalline high-k integration in research and specialty device fabrication.
Chemical vapor deposition holds equipment install base. Physical vapor deposition is rotating up for packaging applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Leading-edge foundries in Taiwan and South Korea dominate high-k dielectric procurement volumes through captive precursor supply chains and direct chemical supplier negotiations. Memory manufacturers in South Korea and logic specialists in Taiwan compress qualification timelines as gate-all-around architectures displace legacy dielectrics. Sovereign semiconductor programs in the United States, China, and India are fragmenting historically concentrated supply patterns.
Taiwan
TSMC's foundry operations in Hsinchu and Tainan anchor the world's largest hafnium oxide procurement volumes for sub-3nm nanosheet production. The National Development Council's chip industry incentives reinforce local precursor supply chain deepening. Applied Materials and Tokyo Electron equipment installations across the Hsinchu Science Park constrain qualified chemical supplier access.
South Korea
Samsung Electronics and SK Hynix captive consumption reshapes precursor contract structures through five-year direct supply agreements. The Ministry of Trade, Industry and Energy's K-Semiconductor Belt initiative expands Pyeongtaek and Yongin fab clusters. Seoul-based chemical suppliers negotiate volume commitments tied to DRAM 1-alpha and 1-beta node ramps.
United States
Intel's Oregon and Arizona fab expansions drive EPA-regulated hafnium precursor handling compliance requirements across deposition facilities. The CHIPS and Science Act subsidies accelerate domestic high-k material supply chain localization. Phoenix and Hillsboro clusters attract precursor chemical suppliers seeking qualification partnerships with leading-edge logic manufacturers.
China
SMIC and Hua Hong Semiconductor expand mature-node high-k adoption despite equipment access constraints on leading-edge processes. The Ministry of Ecology and Environment's dual carbon enforcement tightens thermal budget efficiency requirements for Shanghai and Beijing deposition facilities. Yangtze Memory Technologies in Wuhan qualifies hafnium oxide for 3D NAND stack applications.
India
India Semiconductor Mission PLI incentives for Gujarat and Karnataka greenfield fab construction create virgin high-k material demand from process qualification stages. The Ministry of Electronics and Information Technology's design-linked incentive schemes attract deposition equipment vendors to establish local precursor supply partnerships. Dholera and Mysuru clusters represent emerging procurement nodes without established supplier relationships.
High-K Dielectric Material Market Vendor Landscape
Channel-controlling players compete with product-specialist players across deposition equipment, precursor chemicals, and captive foundry supply. Three equipment vendors dominate atomic layer deposition tool supply, constraining process qualification capacity for chemical suppliers. The market structure separates equipment-integrated material providers from independent precursor specialists. Competitive moves concentrate on long-term supply contract capture and geographic qualification expansion.
Within the equipment-integrated tier, Applied Materials, Inc. exemplifies channel control through deposition tool and process chemistry bundling. Among captive foundry operators, Samsung Electronics Co., Ltd. and Taiwan Semiconductor Manufacturing Company (TSMC) occupy positions as specification-setting buyers that compress distributor margins through direct chemical supplier negotiations. These three entities represent distinct competitive archetypes: equipment-chemistry integration, vertical captive supply, and foundry-driven standard control.
| Leading Market Players |
|---|
| Applied Materials, Inc. |
| Henkel Corporation |
| Samsung Electronics Co., Ltd. |
| Taiwan Semiconductor Manufacturing Company (TSMC) |
| Intel Corporation |
| HITEK Electronic Materials Ltd. |
| Master Bond, Inc. |
| Arkema Group |
| National Magnetics Group |
| Others |
Supply Flow & Price Mechanics
Hafnium metal concentration in Australian and American mining operations anchors margin capture at the precursor synthesis tier, forcing oxide manufacturers to absorb zirconium co-production volatility while foundries lock in five-year supply contracts.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate hafnium precursor procurement between chemical suppliers and leading foundries. Pricing stratifies across electronic-grade, industrial-grade, and research-grade purity tiers based on metallic impurity thresholds and batch certification. Cost compression in industrial-grade titanates is intensifying because Chinese suppliers are expanding barium titanate furnace capacity. Memory manufacturers exhibit the sharpest price sensitivity due to DRAM capacitor volume scaling, while aerospace alloy competitors show least sensitivity given dual-use material specifications.
Supply Chain Analysis
Upstream hafnium feedstock draws from Australian zirconium mines and American secondary recovery facilities, with limited alternative sourcing. Critical inputs span hafnium tetrachloride precursors, high-purity nitrogen carrier gases, and quartz reaction chamber components. Single-source vulnerability concentrates in atomic layer deposition equipment where three vendors control qualified tool installations. Distribution runs through direct chemical supplier negotiations with foundry procurement teams, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gate-all-around process integration is shifting this market toward platform-economics dynamics where equipment-chemistry bundling and foundry qualification protocols create winner-take-most structures around deposition tool ecosystems.
For Market Incumbents: Build captive precursor supply moats through backward integration into hafnium metal refining or exclusive offtake agreements with Australian miners. Incumbents must simultaneously lock equipment-chemistry bundling at Applied Materials and Tokyo Electron to forestall independent precursor qualification. Threats concentrate in plasma-enhanced atomic layer deposition chemistry startups seeking lower-temperature process slots.
For New Entrants and Emerging Players: Build out fluorine-free precursor formulation capabilities to capture REACH-driven substitution demand across European supply chains. The most penetrable white-space sits in India Semiconductor Mission greenfield fabs where no incumbent supplier relationships exist. Go-to-market should anchor on deposition equipment vendor co-development partnerships rather than direct foundry sales.
For Investors and Strategic Acquirers: Capital is best deployed toward specialty chemical firms with existing hafnium handling licenses and EPA-compliant waste treatment infrastructure. Long-term viability hinges on qualification velocity at sub-3nm nodes rather than mature node volume scale. Watch for TSMC or Samsung direct precursor contract announcements as inflection signals for distributor margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hafnium Refining | Captures margin pool upstream of precursor synthesis and insulates against zirconium co-production volatility. |
| Fluorine-Free Precursor Qualification | Secures European market access under REACH perfluorinated restrictions while opening substitution revenue. |
| India Greenfield Fab Partnership | Establishes first-mover supplier relationships at Dholera and Mysuru clusters before incumbent lock-in. |
| Equipment-Chemistry Bundling Agreement | Locks process integration roadmap with Applied Materials or Tokyo Electron to forestall independent competitor qualification. |
| Long-Term Foundry Supply Contract | Compresses distributor margins through direct TSMC or Samsung negotiation and secures volume visibility. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, EPA environmental compliance records, and EU REACH substance restriction updates. Interviews with deposition equipment engineers, foundry procurement directors, and specialty chemical plant managers combined with customs trade data and semiconductor capital expenditure disclosures. Bottom-up wafer demand modeling triangulates against top-down foundry capacity expansion announcements.
Forecast inputs span material chemistry segments, deposition technology platforms, end-use device categories, and regional fab construction pipelines across the analysis window. CAGRs derive from node transition timelines and precursor intensity per wafer layer. Industry-specific inputs include gate-all-around architecture ramp schedules and sovereign subsidy qualification criteria affecting localized supply chain development.
Sensitivities concentrate around hafnium metal price shocks, equipment vendor qualification bottlenecks, and precursor chemistry regulatory bans. Forecasts embed assumptions on node migration speed and memory capacitor scaling continuity. Cross-checking against SEMI capital equipment spending benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
Barium Hydroxide Monohydrate Market
High-Value Chemicals
Hydroxynitrile Lyase Market
High-Value Chemicals
Sodium Hexametaphosphate Market
High-Value Chemicals
High-Heat Melamine Foam Market
High-Value Chemicals
Global Epichlorohydrin (ECH) Market
High-Value Chemicals
High Purity Aluminum Hydroxide Market
High-Value Chemicals
High Methoxyl Pectin Market
High-Value Chemicals
Ammonium Metavanadate Market
High-Value Chemicals
Ultra-High Purity Materials Market
High-Value Chemicals
Asia-Pacific Hydrogen Bromide Market
High-Value Chemicals
Hydroxycarboxylic Acids Market
High-Value Chemicals
Hexafluoropropylene Market
High-Value Chemicals
High Purity Lignin Market
High-Value Chemicals
Hydroxylamine Sulfate Market
High-Value Chemicals
Global Hydrofluoric Acid Market
High-Value Chemicals
High Purity Benzenethiol Market