
 High-Purity Acetic Acid Market | 2026-2036
High-Purity Acetic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
High-Purity Acetic Acid Market Outlook
Pharmaceutical manufacturing is broadening its share of high-purity acetic acid consumption as biologics and small-molecule drug pipelines expand. Celanese Corporation leverages its integrated acetyls chain to sustain cost-advantaged pharmaceutical-grade supply. BASF anchors European demand through its Ludwigshafen hub, where purification technology leadership supports contract manufacturing networks. Mitsubishi Gas Chemical Company dominates Asia-Pacific supply for semiconductor-grade derivatives, extending its reach into adjacent high-purity acid categories.
High-purity acetic acid denotes acetic acid refined to contain minimal metallic ions, halides, and organic impurities, typically achieving concentrations above 99.5 percent with parts-per-billion trace contaminant thresholds; manufacturers employ fractional distillation, catalytic oxidation control, and multi-stage filtration to meet these specifications. The substance serves as a critical solvent, pH modifier, and synthesis intermediate in pharmaceutical active ingredient production, semiconductor etching formulations, and food-grade acidulant systems. Pharmaceutical Grade commands premium positioning due to USP and EP compliance burdens, while Analytical Grade occupies a specialized niche serving laboratory calibration and reference standard applications. Food Grade maintains volume leadership in emerging economies where processed food sectors scale rapidly, though margin pools remain thinner than pharmaceutical segments.
The US FDA enforces Current Good Manufacturing Practice standards that mandate validated impurity testing for acetic acid entering drug formulations, effectively screening out non-pharmaceutical grades from regulated supply chains. The European Medicines Agency and REACH framework impose dual constraints: EMA purity specifications for excipient qualification, plus ECHA registration requirements for chemical substance volume thresholds. China's National Medical Products Administration has aligned domestic pharmaceutical-grade standards with ICH Q3D elemental impurity guidelines, tightening market access for uncertified imports. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and Chinese Pharmacopoeia standards, as divergence in heavy metal limits and testing protocols will determine which purification investments yield compliant supply positions.
Market Dynamics
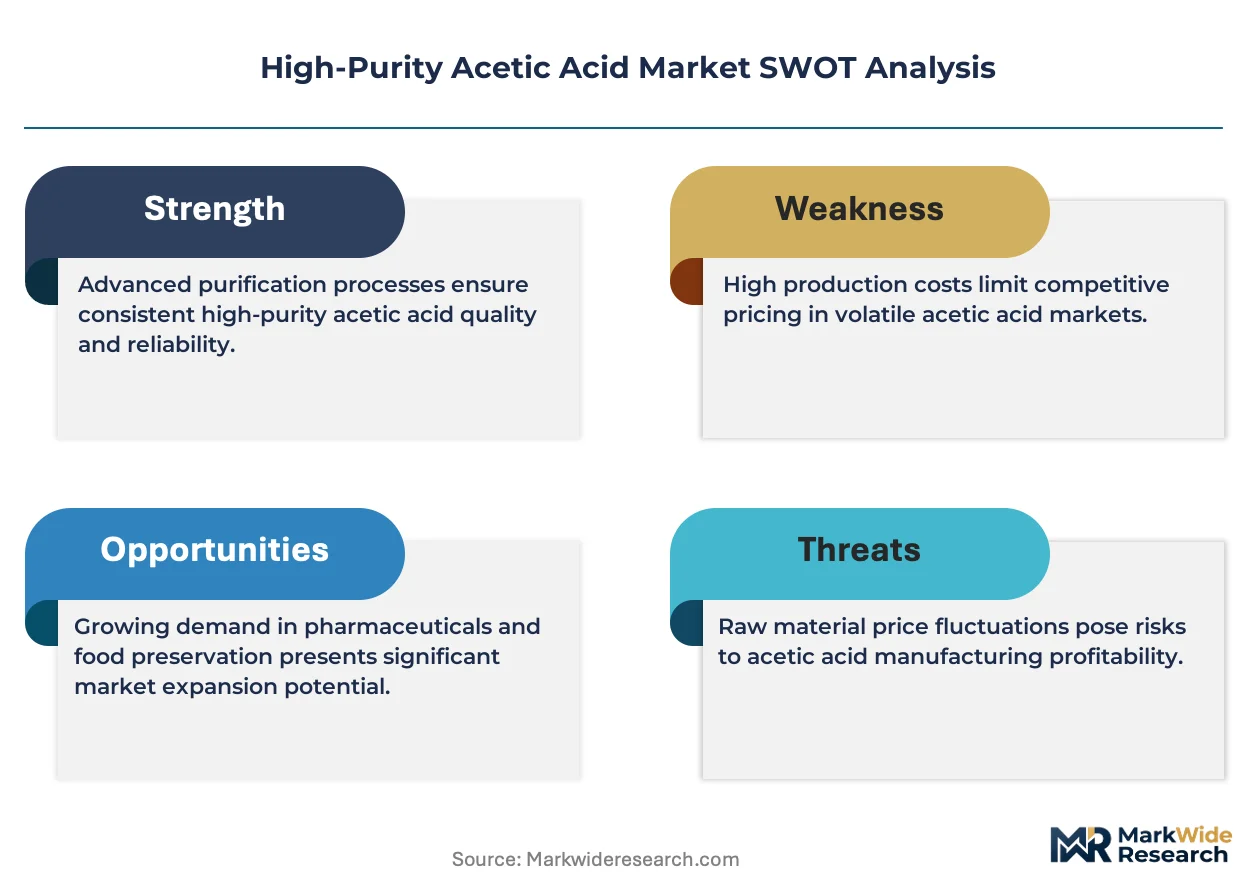
Pharmaceutical-grade specification tightening by US FDA and EMA is compressing supplier margins while concentrating volume among purification-technology leaders with validated impurity-testing infrastructure.
Growth Catalysts
- Semiconductor Etching Demand:Advanced node fabrication below 7nm requires ultra-low metallic ion acetic acid for wafer cleaning, pulling volume from Korean and Taiwanese foundry clusters.
- EMA Excipient Qualification:European Medicines Agency purity specifications for drug formulations are disqualifying uncertified suppliers and locking in qualified incumbents with dedicated pharmaceutical lines.
- Captive Production Investment:Chinese chemical conglomerates are building in-house pharmaceutical-grade capacity to bypass import dependency and capture export certification premiums.
Market Restraints
- Methanol Feedstock Volatility:Acetic acid production depends on methanol carbonylation, exposing margin stability to natural gas and coal price swings in key production basins.
- Specialized Tanker Fleet Concentration:Bulk pharmaceutical-grade transport requires stainless-steel vessels with dedicated cleaning protocols, creating bottlenecks at Rotterdam and Singapore transshipment hubs.
- Fluorinated Solvent Substitution:Perfluorinated etching chemistries in semiconductor manufacturing are displacing acetic acid formulations in select high-aspect-ratio etch applications.
Strategic Opportunities
- Indian Pharmaceutical Manufacturing:CDSCO alignment with ICH Q3D guidelines is creating first-mover advantage for suppliers establishing local purification and analytical testing infrastructure.
- Biologics Buffer Systems:Cell culture media and downstream processing for monoclonal antibodies are adopting acetic acid pH modulation, opening adjacent demand beyond small-molecule synthesis.
- Green Chemistry Mandates:EPA Safer Choice and EU Green Deal solvent substitution programs are elevating bio-based acetic acid pathways to qualifying status for federal procurement preference.
Industry Challenges
- Analytical Chemist Scarcity:Parts-per-billion impurity quantification requires ICP-MS and ion chromatography expertise that outpaces university training pipeline output in manufacturing regions.
- Multi-Pharmacopeia Harmonization Lag:Divergent heavy metal limits between USP, EP, and Chinese Pharmacopeia force redundant testing protocols and inventory segmentation.
- Legacy ERP Integration:Batch record digitization for FDA 21 CFR Part 11 compliance encounters friction with incumbent manufacturing execution systems at mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Purity Acetic Acid Market |
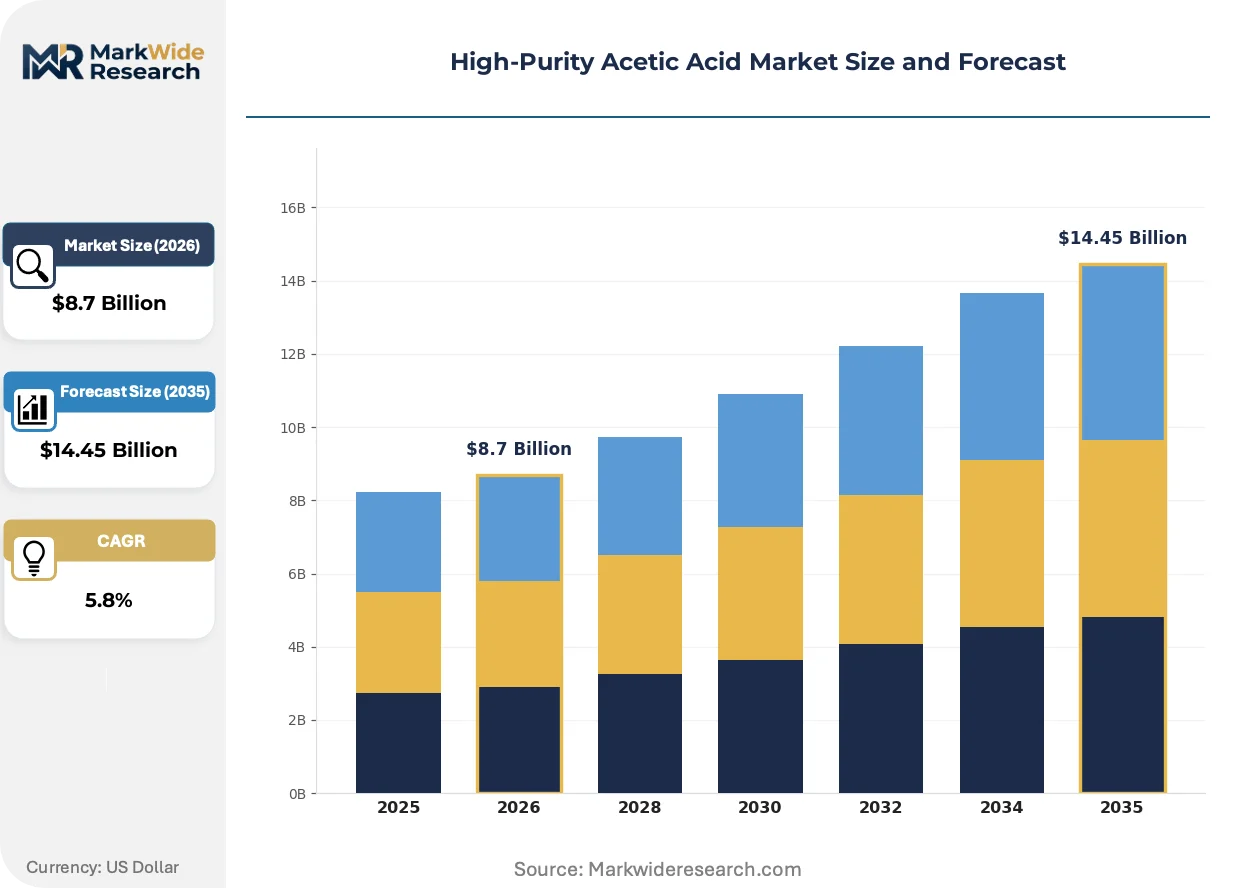
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Food Grade, Pharmaceutical Grade, Analytical Grade End Use Industry: Food & Beverage, Pharmaceuticals, Chemicals, Plastics Packaging Type: Drums, Bulk Containers, Bottles, Carboys Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | Eastman Chemical Company, BASF, Celanese Corporation, INEOS, DAICEL CORPORATION, LyondellBasell Industries Holdings B.V., SABIC, Mitsubishi Gas Chemical Company, Shandong Chemical Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Purity Acetic Acid Market Strategic Shifts
Electrochemical purification and membrane separation technologies are compressing energy intensity while regulatory data integrity mandates are reshaping quality management system investment priorities across supplier tiers.
Membrane pervaporation systems are replacing conventional multi-stage distillation for water-acetic acid separation, cutting thermal energy consumption by half in retrofit installations. Korean and Taiwanese semiconductor chemical suppliers are adopting these units fastest, with full-facility conversions planned over eighteen-month windows. The technology is electrifying process heat substitution strategies and enabling renewable power integration at purification plants.
REACH Annex XVII restrictions on hazardous substance thresholds are tightening trace heavy metal reporting obligations for acetic acid placed on the European market. Manufacturers now face dual registration burdens under ECHA substance volume rules and EMA excipient master file requirements. Pharmaceutical-grade suppliers with pre-submitted dossiers are capturing volume from commodity producers facing compliance timeline compression.
Consolidated procurement consortia among generic drug manufacturers are displacing spot-market purchasing for pharmaceutical-grade acetic acid. Large Indian and Chinese formulation houses now contract directly with purification specialists, bypassing traditional chemical distributors. This channel compression is most visible in Mumbai and Hyderabad, where pharmaceutical clusters have established preferred supplier panels with audited manufacturing sites.
High-Purity Acetic Acid Market Segmentation
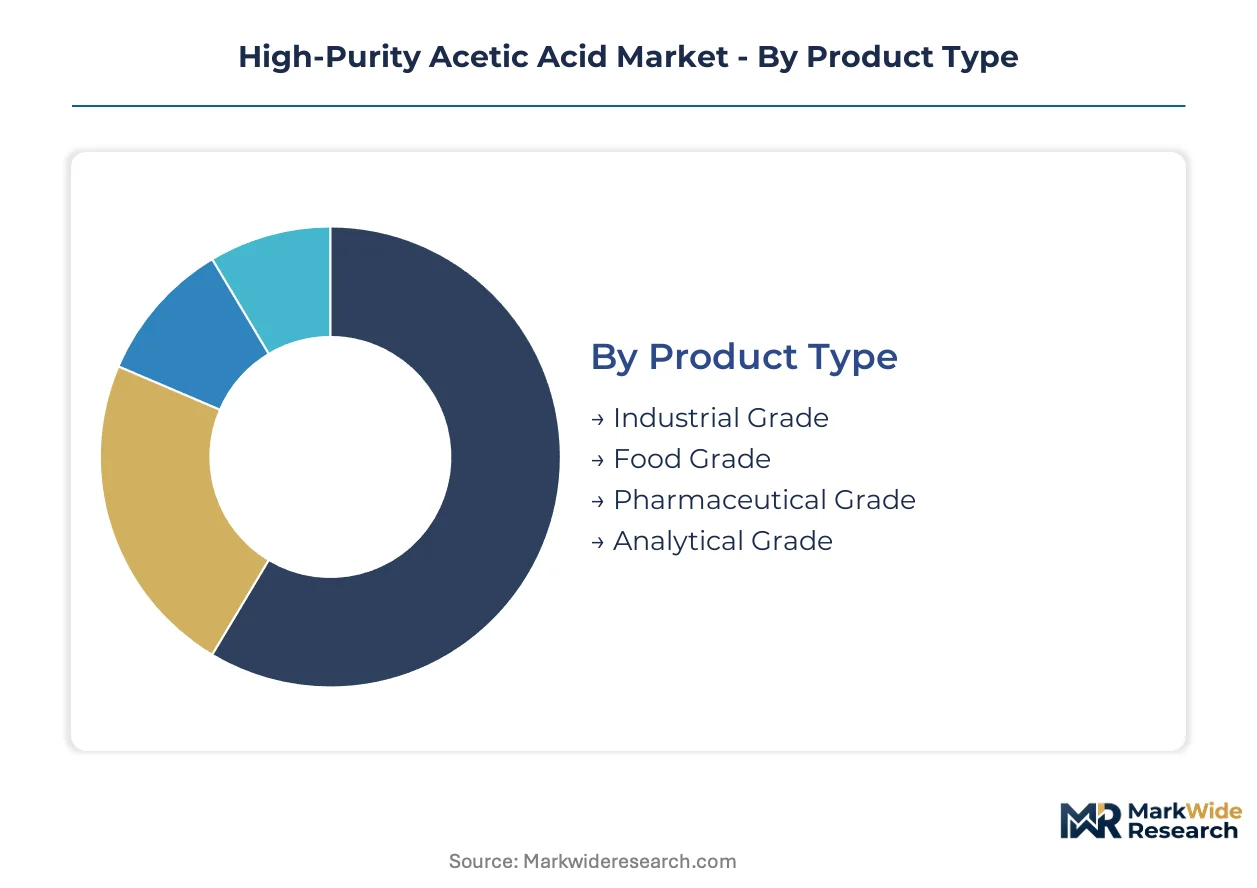
Grade purity thresholds determine compliance pathways and pricing power across buyer categories. Packaging specifications and channel structures reflect the tension between bulk industrial procurement and validated pharmaceutical supply chains.
Product Type:
Facility upgrades and specification tightening are forcing replacement cycles across production lines as buyers migrate toward certified grades.
- Pharmaceutical Grade:Refined to exceed 99.5% concentration with parts-per-billion metallic ion thresholds validated against USP and EP monographs. FDA Current Good Manufacturing Practice enforcement and EMA excipient qualification requirements are concentrating demand among purification-technology leaders with dedicated pharmaceutical lines.
- Food Grade:Meets FCC and FSSAI acidulant specifications for processed food preservation and flavor modulation. Volume concentrates in China and India where domestic chemical conglomerates are building captive production capacity to serve expanding processed food sectors.
- Industrial Grade:Standard purity acetic acid serving chemical synthesis and textile processing with broader impurity tolerances.
- Analytical Grade:Ultra-trace contaminant specifications for laboratory calibration and reference standard applications.
Volume placements concentrate in Food Grade; the faster expansion belongs to Pharmaceutical Grade.
End Use Industry:
Cost tier differentiation separates commodity chemical buyers from premium-grade pharmaceutical and food safety regulated segments.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis, excipient formulation, and biologics buffer systems requiring validated impurity documentation. CDSCO alignment with ICH Q3D guidelines in India and NMPA pharmaceutical-grade standard harmonization in China are reshaping supplier qualification requirements.
- Food & Beverage:Acidulant and preservative applications across processed food manufacturing with national food safety authority compliance burdens. FSSAI tightening of additive specifications and China's SAMR food-grade registration requirements are elevating documentation standards for import suppliers.
- Chemicals:Intermediate for vinyl acetate monomer, acetic anhydride, and ester production with volume-driven procurement.
- Plastics:Catalyst and solvent roles in polymerization processes with specification flexibility relative to regulated end-uses.
Margin pools favor Pharmaceuticals; Chemicals deliver the highest tonnage placements.
Packaging Type:
Customer scale and application sensitivity dictate container selection from single-use laboratory vessels to dedicated stainless-steel bulk transport.
- Bulk Containers:Stainless-steel ISO tanks and dedicated vessels for pharmaceutical-grade transshipment with validated cleaning protocols. Rotterdam and Singapore hub congestion is creating bottlenecks for qualified tanker fleet access.
- Drums:Standard 200-liter steel or HDPE containers for mid-scale chemical and industrial procurement.
- Carboys:High-density polyethylene vessels for laboratory and analytical grade distribution with contamination control features.
- Bottles:Smaller-format glass or fluoropolymer containers for analytical reagent and reference standard applications.
Procurement scale determines packaging selection; Bulk Containers carry the steepest compliance overhead.
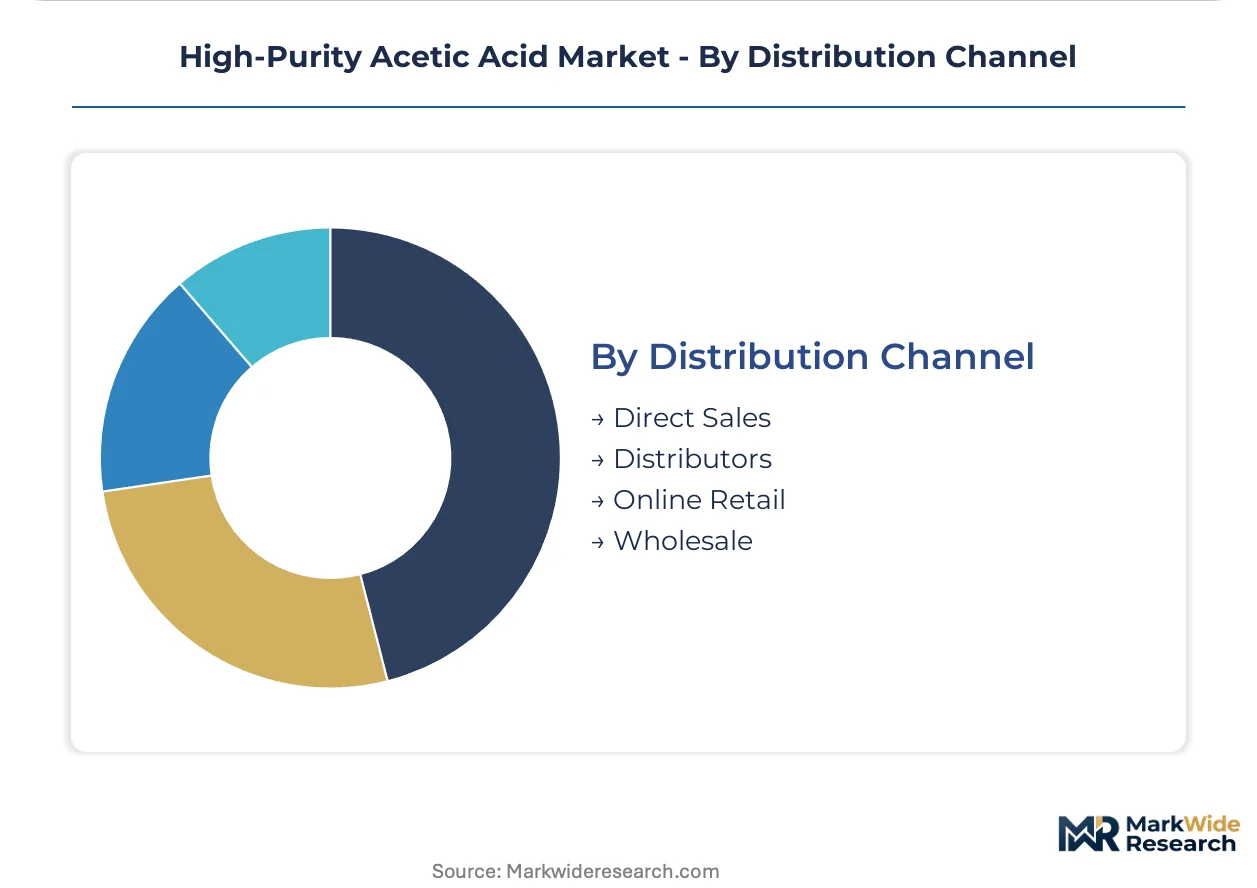
Distribution Channel:
Channel compression is eliminating traditional chemical distributor intermediaries in pharmaceutical supply chains.
- Direct Sales:Consolidated procurement consortia among Indian and Chinese generic drug manufacturers contracting directly with purification specialists. Mumbai and Hyderabad pharmaceutical clusters have established preferred supplier panels with audited manufacturing sites.
- Distributors:Remaining relevant for mid-scale chemical and industrial grade buyers without validated supply chain infrastructure.
- Wholesale:Volume aggregation for food-grade and industrial-grade buyers with less stringent documentation requirements.
- Online Retail:Emerging channel for analytical grade and small-volume laboratory reagent procurement.
Direct Sales is gaining share fastest in pharmaceutical segments; Distributors retain industrial grade relevance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in China's coastal provinces concentrate high-purity acetic acid investment through tax holidays and streamlined NMPA licensing. These zones anchor regional capacity expansion serving both domestic pharmaceutical manufacturing and export certification.
China
Domestic chemical conglomerates are building captive pharmaceutical-grade production lines to reduce import dependency. NMPA alignment with ICH Q3D elemental impurity guidelines tightens market access for uncertified foreign suppliers. The Yangtze River Delta cluster around Shanghai hosts multi-stage filtration facilities serving biologics manufacturers.
United States
Biologics and small-molecule drug pipelines expand consumption for active pharmaceutical ingredient synthesis. FDA Current Good Manufacturing Practice enforcement mandates validated impurity testing that screens out non-pharmaceutical grades. The Greater Boston pharmaceutical corridor contracts directly with purification specialists for buffer system supply.
Germany
Contract manufacturing networks anchor European demand through Ludwigshafen-based purification technology leadership. EMA excipient qualification requirements and ECHA REACH registration impose dual compliance burdens on volume thresholds. The Rhine-Neckar metropolitan region concentrates stainless-steel tanker logistics for pharmaceutical-grade distribution.
India
Generic drug manufacturers consolidate procurement consortia to bypass traditional chemical distributors. CDSCO alignment with ICH Q3D guidelines creates first-mover advantage for suppliers establishing local analytical testing infrastructure. Mumbai and Hyderabad pharmaceutical clusters maintain preferred supplier panels with audited manufacturing sites.
South Korea
Advanced node semiconductor fabrication below 7nm pulls ultra-low metallic ion acetic acid volume from foundry clusters. MFDS pharmaceutical-grade standards and semiconductor chemical purity requirements drive membrane pervaporation adoption for energy reduction. The Seoul Capital Area hosts retrofit installations cutting thermal consumption by half.
High-Purity Acetic Acid Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated acetyls chains commanding pharmaceutical-grade premiums while regional distributors retain industrial-grade relevance. The supplier base concentrates among purification-technology leaders with validated impurity-testing infrastructure, creating tiered access based on pharmacopeial certification. Three archetypes dominate: integrated chemical conglomerates with captive methanol feedstock, specialized purification houses serving regulated end-uses, and regional distributors aggregating spot-market volume. Capacity expansion and backward integration into methanol carbonylation represent the dominant competitive moves, with players securing feedstock stability against natural gas and coal price volatility.
Within the integrated chemical tier, Celanese Corporation and Eastman Chemical Company exemplify acetyls chain control that sustains cost-advantaged pharmaceutical-grade positioning. BASF anchors European contract manufacturing networks through its Ludwigshafen hub structure. Mitsubishi Gas Chemical Company occupies a specialist position in Asia-Pacific semiconductor-grade derivatives, extending reach into adjacent high-purity acid categories through purification technology leadership.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| BASF |
| Celanese Corporation |
| INEOS |
| DAICEL CORPORATION |
| LyondellBasell Industries Holdings B.V. |
| SABIC |
| Mitsubishi Gas Chemical Company |
| Shandong Chemical Group |
| Others |
Value Chain & Pricing Dynamics
Consolidated procurement consortia among Indian and Chinese generic drug manufacturers are compressing supplier margins and forcing purification-technology leaders to absorb validation costs or cede volume to backward-integrated chemical conglomerates building captive pharmaceutical-grade capacity.
Pricing Analysis
Short lead-time premiums for stainless-steel ISO tanker availability at Rotterdam and Singapore hubs command substantial markups over contract-scheduled deliveries. Three-tier pricing structure across pharmaceutical, food, and industrial grade levels separates USP-validated batches from FCC-compliant acidulant and standard synthesis feedstock. Pricing pressure stems from methanol feedstock volatility tied to natural gas and coal price swings in Chinese and US Gulf Coast production basins. Chemical synthesis buyers exhibit highest price sensitivity; biologics manufacturers accept premium positioning for validated impurity documentation.
Supply Chain Analysis
Dual-sourcing mandates from EMA-qualified drug manufacturers and FDA-regulated biologics producers require redundant supplier qualification across at least two pharmacopeial jurisdictions. Supply concentrates in China, the United States, and Germany, with the Yangtze River Delta, US Gulf Coast, and Rhine-Neckar metropolitan region anchoring purification capacity. Production draws from methanol carbonylation feedstock, specialized stainless-steel tanker fleets, and ICP-MS analytical chemist labor pools. Single-source vulnerability pervades qualified pharmaceutical-grade transport infrastructure. Distribution runs through direct sales contracts with audited manufacturing sites bypassing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as FDA and EMA specification tightening forces mid-scale producers without validated impurity-testing infrastructure toward exit or acquisition.
For Market Incumbents: Deploy membrane pervaporation retrofit investments to halve thermal energy consumption and defend margin position against Korean and Taiwanese semiconductor chemical suppliers adopting electrification strategies. Capture biologics buffer system demand through dedicated pH modulation product lines. Backward integration into methanol carbonylation secures feedstock stability against natural gas price volatility threatening margin compression. For New Entrants and Emerging Players: Capture Indian pharmaceutical manufacturing expansion by establishing local ICP-MS analytical testing infrastructure ahead of CDSCO ICH Q3D alignment completion. Target food-grade acidulant segments in emerging economies where documentation burdens remain lighter than pharmaceutical tiers. Green chemistry certification pathways offer qualifying status for federal procurement preference under EPA Safer Choice programs. For Investors and Strategic Acquirers: Re-rating potential sits with specialized purification houses possessing pre-submitted REACH dossiers and EMA excipient master files given compliance timeline compression disqualifying commodity producers. Long-term viability favors suppliers with demonstrated pharmacopeial harmonization capabilities across USP, EP, and Chinese Pharmacopoeia standards. Watch for MFDS pharmaceutical-grade standard tightening in South Korea as inflection indicator for Asia-Pacific regulatory convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methanol Feedstock | Celanese and Eastman Chemical anchor cost-advantaged pharmaceutical-grade positioning through captive acetyls chain control. |
| Membrane Pervaporation Retrofit Installation | Korean and Taiwanese foundry chemical suppliers cut thermal energy consumption by half while enabling renewable power integration. |
| EMA Excipient Master File Submission | Pre-submitted dossiers capture volume from commodity producers facing REACH Annex XVII compliance timeline compression. |
| Dual-Pharmacopeia Harmonization Investment | Suppliers with validated USP and EP testing protocols avoid redundant inventory segmentation forced by divergent heavy metal limits. |
| Direct Sales Channel Establishment | Mumbai and Hyderabad pharmaceutical clusters bypass traditional distributors through audited preferred supplier panels. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs combined with primary interviews across plant managers at purification facilities, procurement leads at Indian and Chinese generic drug manufacturers, distribution channel partners in Rotterdam and Singapore tanker logistics, and technical R&D directors at membrane separation technology providers. Bottom-up volume modeling from grade-tier production capacity and top-down demand validation from end-use industry consumption patterns were cross-referenced for triangulation.
Data-stream reconciliation across pharmaceutical-grade batch records, food-grade acidulant import manifests, and semiconductor chemical foundry procurement disclosures informed the analytical framework. Segmentation dimensions modeled include grade purity tier, end-use industry application, packaging format from bulk ISO tanks to laboratory bottles, and regional production hub concentration. CAGRs were derived from trend extrapolation of validated impurity-testing infrastructure expansion and regulatory harmonization progress. Forecast inputs incorporated methanol feedstock price elasticity and stainless-steel tanker fleet utilization rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pharmacopeial harmonization divergence between USP, EP, and Chinese Pharmacopoeia standards, EMA excipient qualification timeline shifts, and semiconductor node transition acceleration below 3nm displacing acetic acid etching formulations. Deviation in FDA Current Good Manufacturing Practice enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
High Friction Films Market
High-Value Chemicals
Diethylhydroxylamine (DEHA) Market
High-Value Chemicals
Ultra-High Purity Materials Market
High-Value Chemicals
High-Purity Hydrogen Fluoride Market
High-Value Chemicals
High-Silica Zeolite Market
High-Value Chemicals
Global Hydrofluoric Acid Market
High-Value Chemicals
Alpha Hydroxy Acid Market
High-Value Chemicals
Phenanthroline Monohydrate Market
High-Value Chemicals
Hydroquinone Market
High-Value Chemicals
High Performance Mercury Sorbent Market
High-Value Chemicals
Ultra-High-Purity Anhydrous Hydrogen Chloride (Hcl) Gas Market
High-Value Chemicals
Ultra-High Purity Hydrofluoric Acid Market
High-Value Chemicals
High Purity Lignin Market
High-Value Chemicals
P-Hydroxybenzoates (PHB) Market
High-Value Chemicals
Hydroxycarboxylic Acids Market
High-Value Chemicals
Global High Temperature Thermoplastics (Htts) Market