
 High Performance Pigments Market | 2026-2036
High Performance Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
High Performance Pigments Market Intelligence
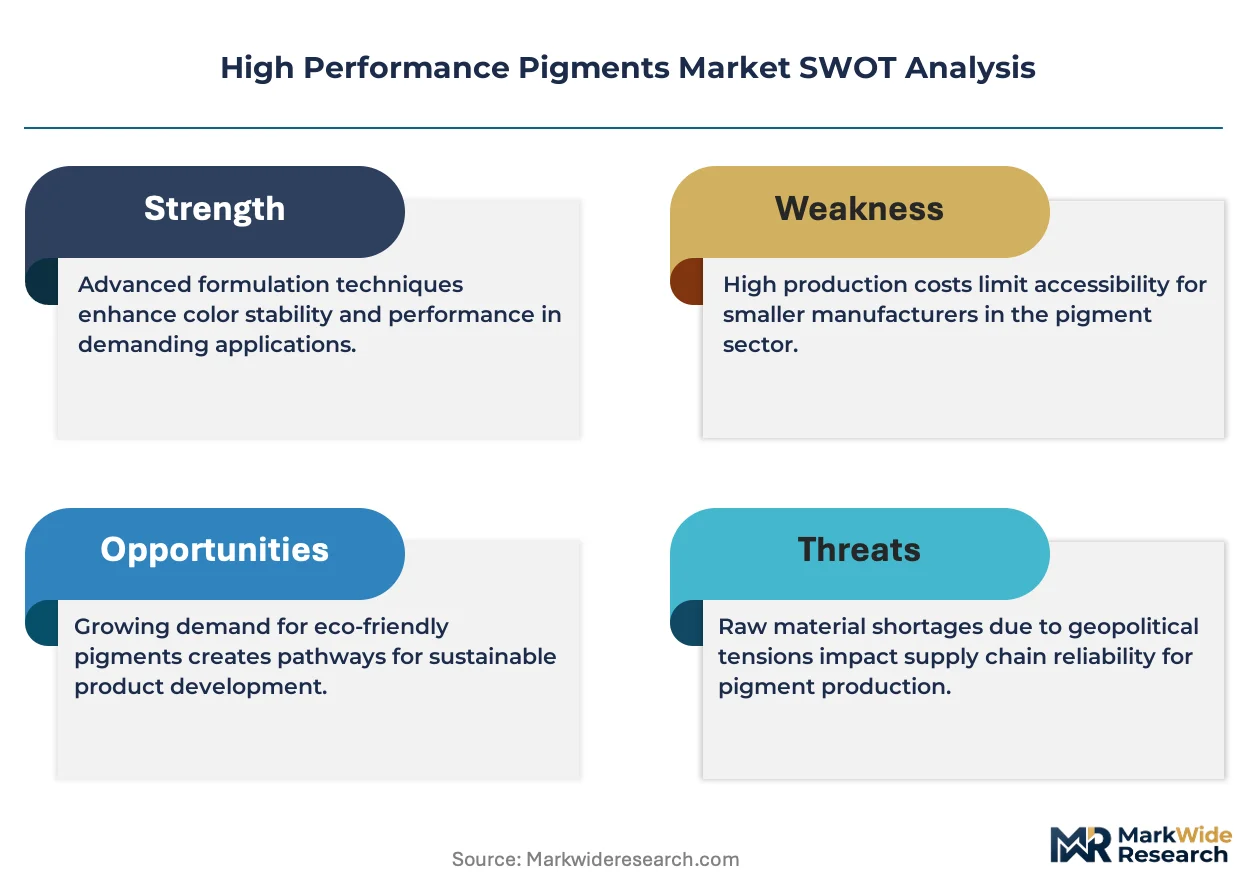
Waterborne and UV-curable formulation technology is fragmenting legacy solvent-based production architectures across the coatings value chain. BASF SE leverages its integrated pigment and additive portfolio to anchor supply relationships with tier-one automotive finishers. Clariant AG specializes in halogen-free organic pigments that sustain premium positioning under tightening chemical safety protocols. Sun Chemical Corporation dominates inkjet and packaging ink segments through controlled distribution networks in North America and Europe.
High performance pigments are colorants engineered to deliver superior lightfastness, thermal stability, chemical resistance, and weathering durability, typically synthesized through complex diazotization, phthalocyanine ring formation, or high-temperature calcination of metal oxide precursors. These properties serve critical functions in automotive basecoats, aerospace exterior finishes, and architectural cladding where aesthetic longevity correlates directly with asset value retention. Inorganic pigments, particularly complex inorganic color pigments based on mixed metal oxides, occupy the mature volume core with stable margins, while special effect pigments command premium pricing in automotive and luxury packaging applications where optical depth and flip-flop color travel differentiate finished goods. Organic pigments face margin compression from regulatory-driven reformulation costs, though high-performance grades in the yellow, red, and violet spectral ranges retain structural demand in plastics and fiber applications.
REACH registration requirements and the EU Green Deal's chemical sustainability targets are forcing reformulation of cadmium, lead, and chromium-based pigment lines across European manufacturing. EPA Toxic Substances Control Act oversight and evolving state-level restrictions in California and New York are extending similar compliance burdens for US-based coatings formulators. China's MEE environmental inspections and GB standards for industrial emissions are tightening production access for smaller domestic pigment manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and qualify alternative chemistries before specification deadlines harden.
Market Dynamics
Waterborne and UV-curable formulation technology is fragmenting legacy solvent-based production architectures across the coatings value chain, forcing capital reallocation toward compliant chemistries.
Growth Catalysts
- Automotive OEM specification tightening:Weather-resistant coating mandates for exterior basecoats and clearcoats are pulling high-performance organic and inorganic pigments into tier-one supply programs.
- REACH chemical registration deadlines:The EU Green Deal's chemical sustainability targets are accelerating substitution of heavy-metal pigments with complex inorganic color pigments and halogen-free alternatives.
- China manufacturing cluster consolidation:MEE environmental inspections and GB standards for industrial emissions are concentrating production among integrated pigment-additive producers with captive wastewater treatment.
Market Restraints
- Raw material volatility in metal oxide precursors:Cobalt, nickel, and titanium feedstock price swings compress margins on complex inorganic color pigments.
- Supply concentration in German and Chinese producers:Mixed metal oxide calcination capacity clusters in Ludwigshafen and Ningbo create single-source risk for automotive finishers.
- Technical ceiling on organic pigment heat stability:Phthalocyanine blues and greens face thermal degradation thresholds above 280°C, limiting engine-compartment plastics applications.
Strategic Opportunities
- Underpenetrated Indian coatings market:BIS certification requirements and PLI scheme incentives for domestic chemical manufacturing are opening specification windows for REACH-compliant pigment imports.
- UV-curable inkjet packaging convergence:Food-contact compliant high-performance pigments for narrow-web label printing represent white space outside traditional automotive and architectural coatings.
- Dual carbon goals in China:SAMR green product certification and carbon-intensity benchmarks favor low-VOC waterborne pigment dispersions in government-procured infrastructure projects.
Industry Challenges
- Specialized formulation chemist scarcity:Diazotization and phthalocyanine synthesis expertise concentrates among retiring European technical workforces, constraining new product development pipelines.
- Multi-jurisdiction registration timeline compression:Parallel EPA TSCA pre-manufacture notices, REACH dossier updates, and China NMPA new chemical registrations strain regulatory affairs bandwidth.
- Legacy solvent-based inventory stranding:Reformulation deadlines in California and New York are forcing write-downs of cadmium and lead-chromate pigment stocks before specification lock-in.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Performance Pigments Market |
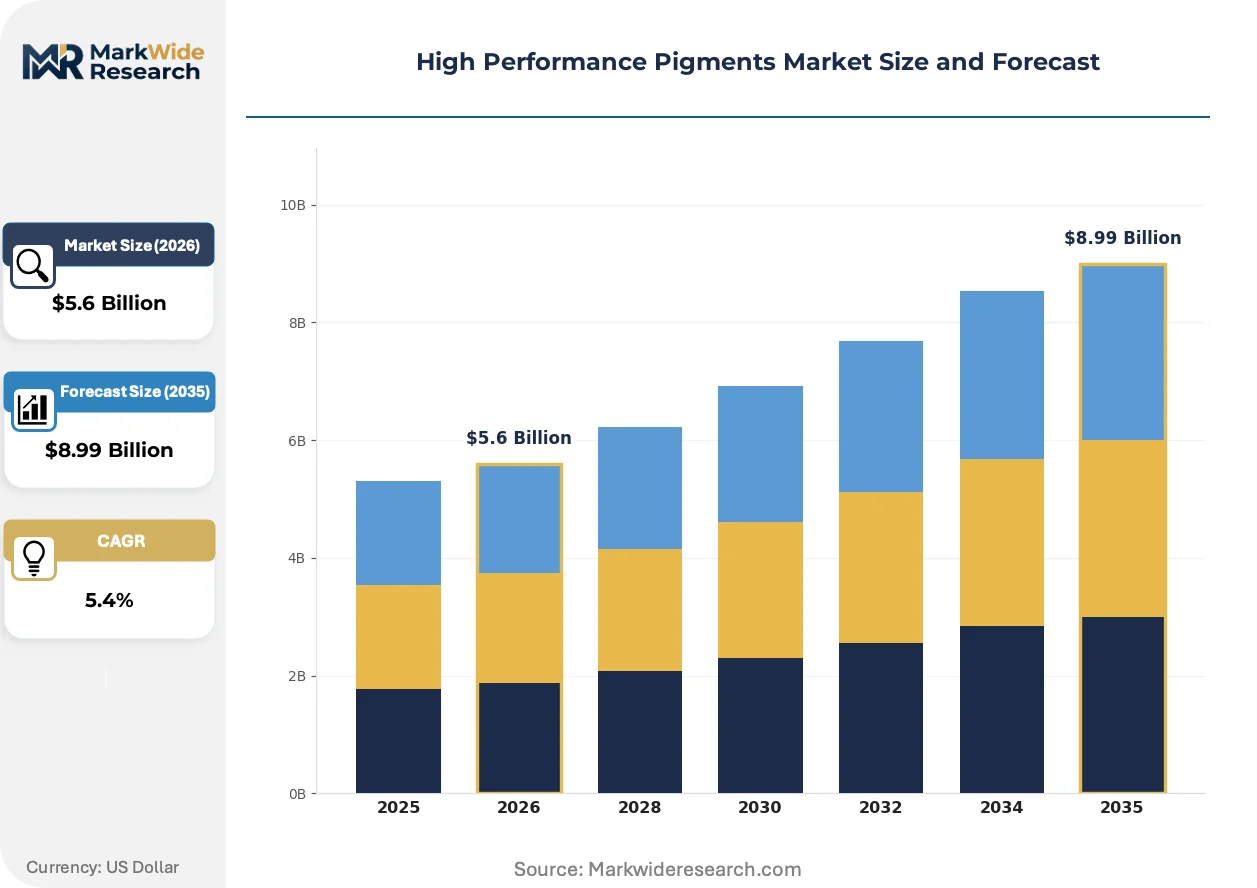
| Market Size in 2026 | $5.6 Billion |
| Market Size in 2035 | $8.99 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inorganic Pigments, Organic Pigments, Special Effect Pigments, Fluorescent Pigments Application: Coatings, Plastics, Inks, Textiles End User: Automotive, Construction, Consumer Goods, Aerospace Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | BASF SE, Clariant AG, Sun Chemical Corporation, Sudarshan Chemical Industries Limited, Venator Materials PLC, Lanxess AG, Huntsman Corporation, Ferro Corporation, Heubach GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performance Pigments Market Strategic Shifts & Innovations
Formulation chemistry is pivoting toward low-carbon, low-toxicity architectures that satisfy overlapping regulatory regimes while preserving optical performance in demanding end-uses.
Photocurable pigment dispersions are migrating from narrow graphic arts applications into industrial wood and plastic coatings. Automotive refinish shops in Germany and the United States are piloting UV-curable basecoats for spot repair, drawn by instant cure times and eliminated baking energy costs. This migration is compressing the installed base of thermal ovens and forcing coatings distributors to reconfigure technical service capabilities.
REACH authorization requirements for chromium trioxide and cadmium pigments are compelling reformulation of corrosion-resistant coatings and high-chroma plastics. The European Chemicals Agency sunset date enforcement is pushing pigment users toward bismuth vanadate yellows and perylene reds with inferior opacity but superior regulatory standing. Aerospace exterior finishers face the steepest substitution costs given qualification timelines for new chemistries on commercial aircraft.
Buyer concentration among consolidated automotive OEMs and multinational packaging printers is compressing supplier negotiation cycles. Tier-one finishers in Stuttgart, Detroit, and Shanghai are unbundling pigment supply from coatings formulators, procuring color concentrates directly to capture margin and lock specification control. This disintermediation is most visible in North American automotive assembly plants where just-in-time color matching requires dedicated on-site pigment blending operations.
High Performance Pigments Market Segmentation
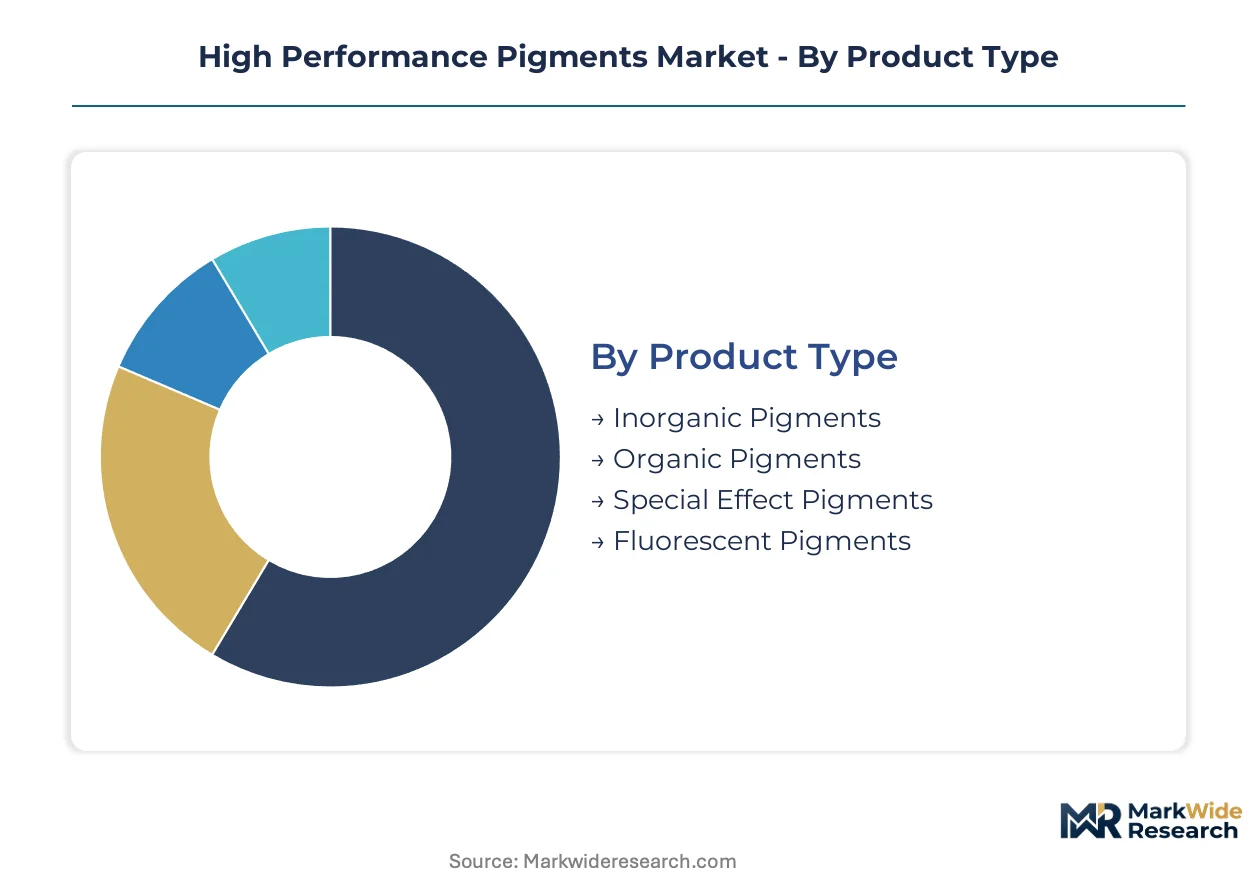
High performance pigments serve heterogeneous durability requirements across automotive, aerospace, and industrial applications. Segmentation reveals where formulation complexity drives premium pricing versus where commodity substitution threatens margins.
Product Type:
After-sales service intensity varies sharply by pigment chemistry, with complex inorganic color pigments requiring technical support for dispersion stability and color matching that organic grades rarely demand.
- Inorganic Pigments:Complex inorganic color pigments synthesized through high-temperature calcination of mixed metal oxides deliver thermal stability above 800°C and UV resistance for automotive basecoats. Demand concentrates in German automotive OEM specification programs where ECHA sunset dates for chromium trioxide are forcing reformulation toward cobalt titanate greens and nickel titanate yellows.
- Organic Pigments:Phthalocyanine blues and greens, plus high-performance azo and quinacridone reds, offer superior chroma but face thermal ceilings near 280°C that restrict under-hood plastics applications. Specification tightening in Chinese automotive manufacturing is pulling REACH-compliant halogen-free grades into tier-one supply programs at premium pricing.
- Special Effect Pigments:Pearlescent and interference pigments based on mica or alumina substrates create optical depth and color travel for luxury automotive and packaging.
- Fluorescent Pigments:Daylight-fluorescent colorants for safety signage and graphic arts applications with limited weatherfastness.
By volume, inorganic pigments lead. By growth pace, special effect pigments are gaining share fastest in automotive exterior finishes.
Application:
Cost tier differentiation separates specification-locked automotive coatings from price-sensitive textile coloration where pigment loadings are minimized.
- Coatings:Automotive OEM basecoats and clearcoats represent the value core, with weathering durability specifications requiring 5-year Florida exposure testing. Waterborne and UV-curable formulation technologies are fragmenting legacy solvent-based production architectures, concentrating demand among integrated pigment-additive producers with captive dispersion capabilities.
- Plastics:Engine-compartment and interior trim applications require heat stability above 300°C for injection molding processes. Phthalocyanine blues face thermal degradation thresholds that limit penetration in nylon and PBT compounds, creating specification windows for complex inorganic alternatives.
- Inks:Narrow-web label and packaging inkjet applications demand food-contact compliance and instant cure compatibility.
- Textiles:Synthetic fiber coloration with disperse pigments for polyester and nylon at lower performance thresholds than coatings.
By volume, coatings lead. By margin expansion, plastics applications are climbing the fastest as automotive lightweighting increases polymer content per vehicle.
End User:
Customer type determines procurement leverage, with consolidated automotive OEMs unbundling pigment supply from coatings formulators to capture margin and lock specification control.
- Automotive:Tier-one finishers in Stuttgart, Detroit, and Shanghai are procuring color concentrates directly, requiring just-in-time color matching with dedicated on-site pigment blending operations. ECHA authorization requirements for cadmium and lead-chromate pigments are forcing reformulation of high-chroma exterior finishes.
- Construction:Architectural cladding and coil coatings prioritize weathering durability over color saturation, favoring complex inorganic pigments with 25-year lifecycle guarantees.
- Consumer Goods:Packaging printers and cosmetics formulators drive demand for special effect and cosmetic-grade pigments with regulatory compliance for skin contact.
- Aerospace:Exterior finishers face steepest substitution costs given qualification timelines for new chemistries on commercial aircraft, with FAA certification requirements extending specification lock-in periods.
By volume, automotive leads. By specification premium, aerospace is expanding most quickly as next-generation aircraft programs multiply exterior surface area per unit.
Distribution Channel:
Supply concentration in German and Chinese producers shapes channel strategy, with direct sales dominating high-volume automotive programs and distributors serving fragmented coatings job shops.
- Direct Sales:Integrated pigment producers maintain technical service teams at major automotive assembly plants for real-time color matching and dispersion troubleshooting. BASF SE and Clariant AG anchor supply relationships through dedicated account management with tier-one finishers.
- Distributors:Regional coatings distributors serve refinish shops and smaller industrial formulators with stocked pigment concentrates and technical support.
- Online Retail:Limited to standard-grade organic pigments for graphic arts and hobbyist applications with minimal technical service requirements.
- Others:Agent-based procurement for specialty pigments in fragmented end-uses.
By volume, direct sales leads. By channel expansion, distributor networks are gaining share fastest in emerging coatings markets where technical service infrastructure remains underdeveloped.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and coatings formulators concentrate procurement leverage in manufacturing clusters across Germany, China, and the United States. Regulatory divergence between REACH, EPA TSCA, and China GB standards fragments compliance architectures. Production capacity clusters in Ludwigshafen, Ningbo, and Detroit anchor supply relationships.
Germany
ECHA sunset dates for chromium trioxide and cadmium pigments force reformulation of automotive basecoats toward complex inorganic alternatives. REACH authorization requirements accelerate substitution timelines for corrosion-resistant coatings. BASF SE anchors supply relationships with tier-one finishers in Ludwigshafen through integrated pigment-additive portfolios.
China
MEE environmental inspections and GB standards for industrial emissions concentrate production among integrated manufacturers with captive wastewater treatment. SAMR green product certification favors low-VOC waterborne pigment dispersions in government-procured infrastructure. Ningbo manufacturing clusters consolidate calcination capacity for mixed metal oxide pigments.
United States
EPA TSCA oversight and California state-level restrictions extend compliance burdens for cadmium and lead-chromate pigment stocks. Tier-one automotive finishers in Detroit unbundle pigment supply from coatings formulators for just-in-time color matching. Refinish shops pilot UV-curable basecoats to eliminate baking energy costs.
India
BIS certification requirements and PLI scheme incentives for domestic chemical manufacturing open specification windows for REACH-compliant pigment imports. Automotive assembly expansion in Pune and Chennai pulls high-performance organic pigments into tier-one supply programs. Formulators face technical service gaps in dispersion stability support.
Japan
METI carbon-intensity benchmarks favor low-VOC formulations in automotive OEM specification programs. Phthalocyanine synthesis expertise concentrates among technical workforces nearing retirement, constraining new product development pipelines. Nagoya industrial clusters maintain qualification relationships with aerospace exterior finishers.
High Performance Pigments Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented coatings value chains. Integrated pigment-additive producers anchor supply relationships with tier-one automotive finishers through captive dispersion capabilities. Three archetypes dominate: diversified chemical conglomerates with cross-portfolio leverage, halogen-free organic pigment specialists, and complex inorganic color pigment manufacturers with calcination expertise. Competitive moves concentrate on M&A for regulatory-compliant technology access and strategic partnerships for just-in-time color matching infrastructure.
Among diversified chemical conglomerates, BASF SE and Lanxess AG exemplify integrated producers with backward control over metal oxide feedstocks and captive additive formulation capabilities. Clariant AG occupies a specialist position within the halogen-free organic pigment tier, representing regulatory-compliant chemistry positioning under tightening chemical safety protocols. Sun Chemical Corporation anchors the inkjet and packaging ink segments through controlled distribution networks in North America and Europe. Sudarshan Chemical Industries Limited and Venator Materials PLC sit within the complex inorganic and specialty effect pigment tiers respectively, reflecting geographic diversification strategies across Asian and European manufacturing bases.
| Leading Market Players |
|---|
| BASF SE |
| Clariant AG |
| Sun Chemical Corporation |
| Sudarshan Chemical Industries Limited |
| Venator Materials PLC |
| Lanxess AG |
| Huntsman Corporation |
| Ferro Corporation |
| Heubach GmbH |
| Others |
Cost & Logistics Intelligence
Rotterdam-Antwerp barge freight corridors feed calcination capacity in Ludwigshafen and Ningbo, concentrating supply leverage among integrated producers while downstream automotive finishers face tiered pricing based on REACH compliance status and dispersion service bundling.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange cobalt and titanium feedstock quotations dominate complex inorganic pigment procurement. Three-tier pricing structure across premium REACH-compliant grades, standard technical grades, and economy solvent-based legacy lines separates specification-locked automotive OEMs from price-sensitive textile formulators. Cost compression in economy tiers is intensifying because Chinese MEE inspections are shuttering unintegrated producers. Packaging inkjet printers exhibit highest price sensitivity due to thin margins on narrow-web label contracts.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for mixed metal oxide importers. Production concentrates in Germany, China, and the United States, with calcination capacity anchored in Ludwigshafen and Ningbo industrial clusters. Feedstock dependencies center on cobalt oxide, titanium dioxide, and nickel sulfate from South African and Australian mining operations. Single-source vulnerability persists for automotive finishers qualified on specific CICP crystal structures. Distribution runs through direct technical service teams at tier-one assembly plants, supplemented by regional distributors for refinish and industrial job shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against bismuth vanadate and perylene chemistries displacing cadmium and lead-chromate pigments under ECHA sunset enforcement.
For Market Incumbents: Harden specification lock-in through captive dispersion operations at Stuttgart, Detroit, and Shanghai assembly plants. Deepen backward integration into metal oxide precursor refining to buffer LME price volatility. Secure halogen-free organic pigment certification ahead of REACH authorization deadlines to defend premium positioning against reformulation-driven margin erosion. For New Entrants and Emerging Players: UV-curable food-contact pigment dispersions for narrow-web packaging in India represent the most penetrable entry point. BIS certification gaps and PLI scheme incentives create specification windows for REACH-compliant imports. Partner with regional coatings distributors to bridge technical service infrastructure deficits in Pune and Chennai automotive clusters. For Investors and Strategic Acquirers: Specialist halogen-free organic pigment producers with ECHA dossier completion and automotive qualification relationships offer the strongest acquisition profile. Long-term viability hinges on regulatory compliance moats widening through 2030. Monitor ECHA authorization sunset date enforcement as the inflection signal for substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metal Oxide Feedstocks | Captive cobalt and titanium sourcing insulates margin from LME volatility. |
| REACH-Compliant Product Line Expansion | Halogen-free organic pigments secure automotive specification ahead of sunset dates. |
| Just-in-Time Color Matching Infrastructure | On-site dispersion operations at tier-one finishers lock procurement relationships. |
| UV-Curable Dispersion Technology Development | Instant-cure compatibility opens packaging inkjet segments outside automotive. |
| Joint Venture in Indian Manufacturing | PLI scheme incentives and BIS certification accelerate market access. |
Research Approach
A spread of perspectives from coatings formulators, automotive OEM procurement leads, pigment plant managers, and regulatory affairs directors converged on the working assumptions. Primary interviews triangulated against customs trade data, ECHA registration dossiers, SEC 10-K chemical segment disclosures, and ACC industry reports. Bottom-up volume modeling by pigment chemistry and end-use application reconciled with top-down macroeconomic overlays.
Demand-supply balance dynamics across the analysis window shaped the analytical framework, with segmentation by inorganic, organic, and special effect chemistries crossed against coatings, plastics, and ink applications. CAGRs derived from regression against automotive production forecasts and construction spending indices. Inputs included ECHA sunset date timelines, MEE inspection intensity, and SAMR green product certification adoption curves.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, construction activity, or metals commodity prices would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement timing and substitution elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Quinacridone Pigments Market
Dyes and Pigments
Acid Violet 43 Market
Dyes and Pigments
Pigment Additive Film Market
Dyes and Pigments
Aluminum Pigments Market
Dyes and Pigments
High Performance Organic Pigments Market
Dyes and Pigments
Cadmium Pigments Market
Dyes and Pigments
Color Retention Agents Market
Dyes and Pigments
Titanium Dioxide Pigment Market
Dyes and Pigments
Plastic Pigments Market
Dyes and Pigments
Global Organic Pigments Market
Dyes and Pigments
Acid Orange Market
Dyes and Pigments
Arylamide Pigments Market
Dyes and Pigments
Global Thermochromic Paint Market
Dyes and Pigments
Water-Based Pigments Market
Dyes and Pigments
Chlorophyll Color Market
Dyes and Pigments
Dyestuff (Black Color) Market