
 Bismuth Vanadate Pigment Market | 2026-2036
Bismuth Vanadate Pigment Market Size, Share, and Industry Trends Forecast 2026-2036
Bismuth Vanadate Pigment Market Insights
Automotive coatings procurement is pivoting toward heavy-metal-free pigment systems as OEMs enforce stricter material compliance across supply chains. BASF leverages its integrated pigment and dispersion technology portfolio to anchor European automotive supply relationships. Vibrantz Technologies competes through specialized colorant expertise in high-performance industrial applications. Heubach sustains manufacturing scale across multiple pigment chemistries, extending its position in regulatory-compliant color solutions.
Bismuth vanadate is a synthetic inorganic pigment with the chemical formula BiVO4, characterized by high tinting strength, excellent lightfastness, and a bright greenish-yellow hue produced through high-temperature solid-state synthesis or precipitation methods. It serves primarily as a non-toxic replacement for lead chromate and cadmium sulfide pigments in coatings, plastics, and printing inks where regulatory restrictions prohibit heavy-metal content. Bright Yellow grades command premium positioning in automotive and coil coating segments where opacity and weathering resistance justify higher formulation costs. Pigment Green variants occupy narrower specialty niches in architectural applications seeking differentiated color spaces. The Construction Materials application remains volume-driven but carries thinner margins due to commoditized specification requirements.
REACH regulations enforced by ECHA prohibit cadmium and lead chromate pigments in most European applications, directly elevating bismuth vanadate substitution demand across coatings and plastics value chains. EPA hazard standards under TSCA Section 6 influence US market access for imported pigment formulations, shaping supplier certification requirements. ISO 787 testing protocols govern dispersion behavior and tinting strength benchmarks that determine qualification for automotive tier-one supply. Stakeholders must monitor evolving chemical restriction lists across multiple jurisdictions to anticipate formulation displacement timelines and secure early-mover positions in compliant pigment supply.
Market Dynamics
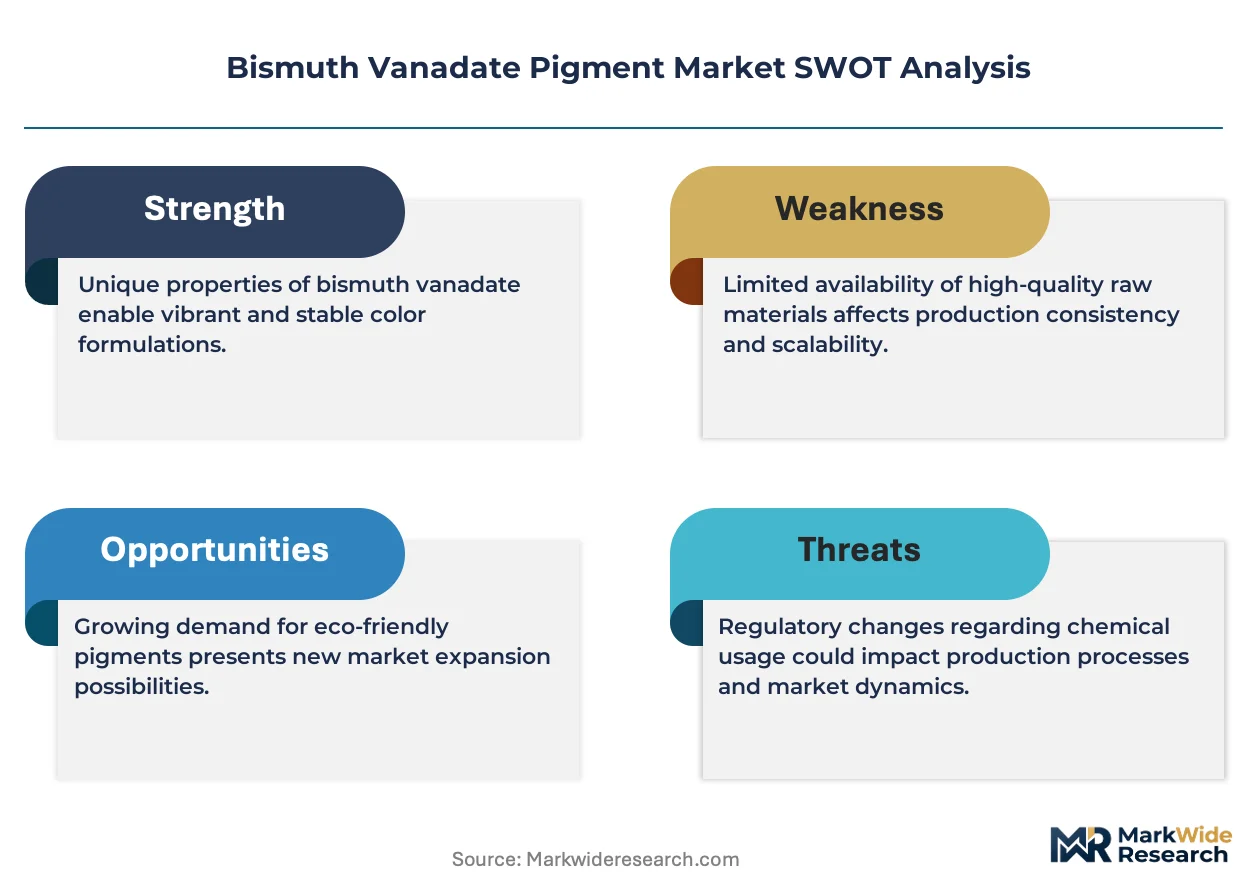
REACH restrictions on cadmium and lead chromate pigments across Europe are redirecting formulation demand toward compliant inorganic yellow pigments, compressing substitution timelines and reshaping procurement specifications across coatings value chains.
Growth Catalysts
- REACH pigment bans:ECHA prohibitions on heavy-metal colorants in European coatings and plastics are eliminating incumbent alternatives and accelerating specification switches to bismuth vanadate in automotive OEM supply chains.
- Automotive compliance mandates:Tier-one coating suppliers to German and French vehicle manufacturers face binding heavy-metal-free material certifications that exclude legacy chromate formulations.
- Coil coating weathering requirements:Architectural metal finishing specifications in Northern Europe demand the lightfastness and UV stability that bismuth vanadate delivers in exterior building applications.
Market Restraints
- Bismuth metal price volatility:Concentrated bismuth refining capacity in China creates raw material cost instability that compresses pigment producer margins during supply disruptions.
- High-temperature synthesis energy intensity:Solid-state production methods require sustained thermal processing that elevates manufacturing costs relative to precipitated organic pigment alternatives.
- Titanium dioxide hybrid dependency:Many coating formulations blend bismuth vanadate with TiO2 for opacity, tying demand to titanium pigment supply fluctuations and pricing.
Strategic Opportunities
- US EPA TSCA Section 6 alignment:Hazard standards for imported pigment formulations are elevating certification barriers that favor qualified suppliers with established compliance documentation.
- Printing ink food-contact expansion:Non-toxic pigment demand for packaging applications is opening formulation opportunities in flexographic and gravure ink segments previously served by cadmium yellows.
- Photocatalytic functionality convergence:Bismuth vanadate's semiconductor properties enable dual-use pigment-plus-photocatalyst products for self-cleaning architectural coatings.
Industry Challenges
- ISO 787 dispersion qualification timelines:Automotive tier-one supply entry requires extended tinting strength and behavior testing protocols that delay revenue recognition for new pigment grades.
- High-performance colorant formulation expertise scarcity:Technical specialists capable of optimizing bismuth vanadate dispersion in waterborne and high-solids coating systems command premium compensation in tight labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bismuth Vanadate Pigment Market |
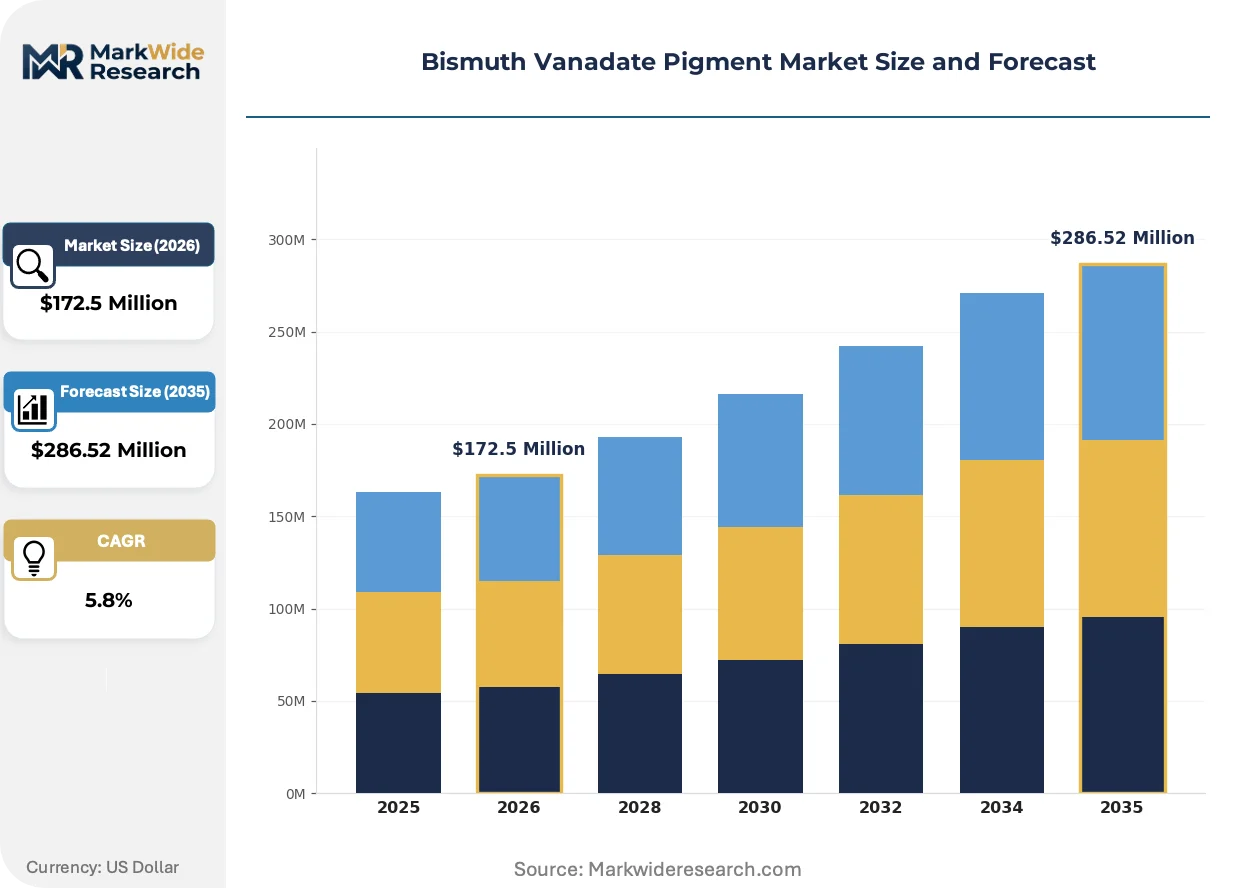
| Market Size in 2026 | $172.5 Million |
| Market Size in 2035 | $286.52 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yellow Bismuth Vanadate, Bright Yellow, Pigment Green, Pigment Blue Application: Coatings, Plastics, Inks, Construction Materials End User: Manufacturers, Construction Companies, Automotive Sector, Consumer Goods Distribution Channel: Direct Sales, Online Sales, Distributors, Retail Stores |
| Companies Covered | Vibrantz Technologies, Bruchsaler Farbenfabrik, BASF, Kremer Pigmente, Shanghai Linhui Chemical, Heubach, Shepherd Color, Stanford Advanced Materials, DCL Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bismuth Vanadate Pigment Market Trends and Innovations
Formulation technology is compressing the performance gap between bismuth vanadate and legacy heavy-metal pigments while regulatory enforcement tightens specification standards across industrial coatings.
Surface-modified bismuth vanadate particles with engineered silane coatings are automating dispersion stability in high-solids automotive clearcoats. German OEM coating houses are adopting these grades at accelerated qualification paces. The technology is automating the reduction of milling time and pigment loading requirements in production-scale batches.
EU F-Gas Regulation phase-down schedules are indirectly pressuring coating producers to eliminate solvent-borne systems that historically masked dispersion deficiencies in conventional pigments. Industrial finishers in Benelux and Northern Italy are reformulating toward waterborne platforms that demand superior pigment dispersibility. Coil coating lines serving architectural metal processors represent the most affected segment, with specification sheets now mandating heavy-metal-free colorant systems.
Coating manufacturers are consolidating pigment supplier relationships around vertically integrated partners capable of delivering certified dispersion concentrates rather than raw powders. Industrial maintenance and protective coatings distributors in the US Midwest are displacing spot-buy pigment procurement with annual framework agreements tied to compliance documentation. This consolidation pattern is most visible in automotive refinish networks where liability exposure from non-compliant color matching drives preference for pre-certified colorant systems.
Bismuth Vanadate Pigment Market Segmentation
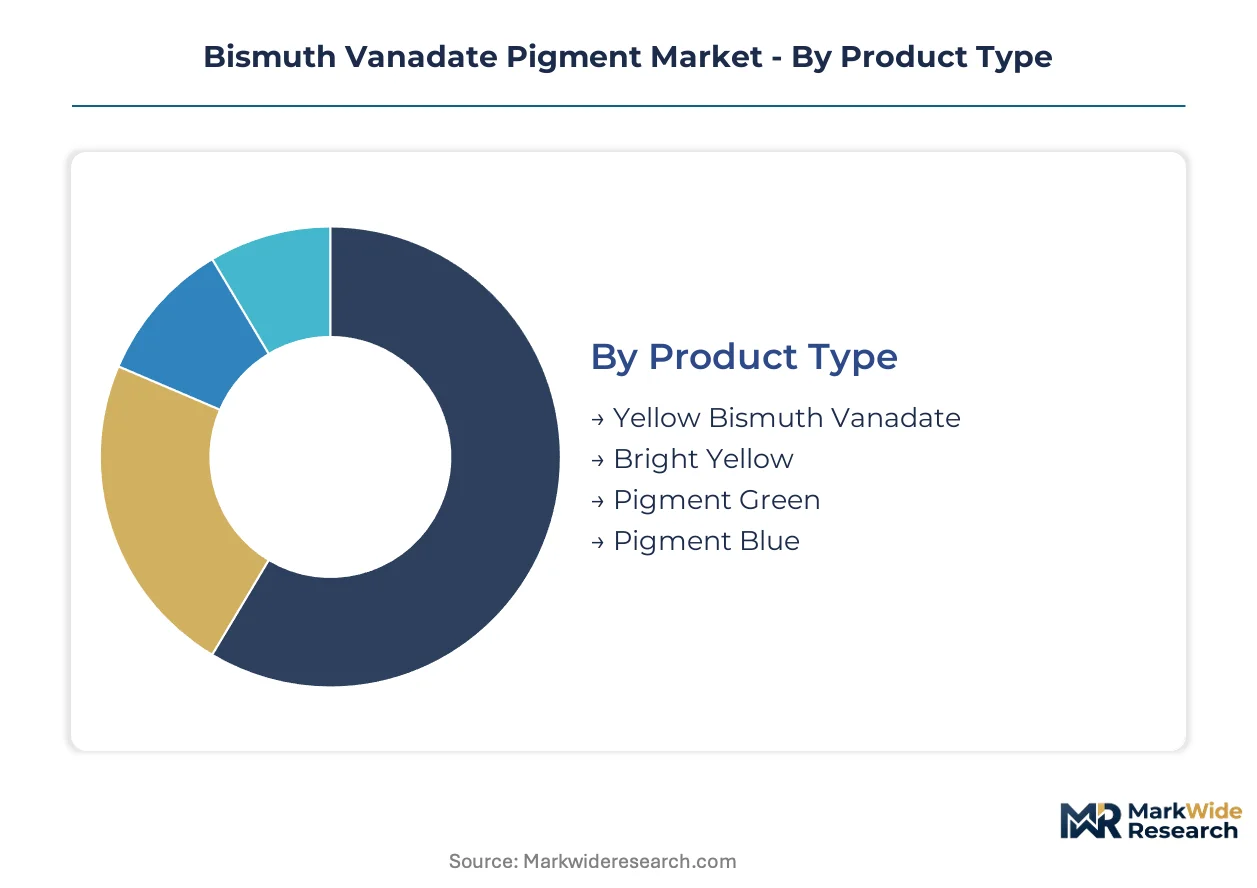
Bismuth vanadate pigment procurement varies sharply across product grades and end-use specifications, with automotive and industrial coatings demanding certified dispersion performance while construction buyers prioritize volume economics. Segmentation reveals where formulation expertise commands premium positioning versus commodity substitution plays.
Product Type:
Customization intensity spans from standardized construction grades to precision-engineered automotive colorants with surface-modified particle architectures.
- Yellow Bismuth Vanadate:The foundational grade delivers medium chroma greenish-yellow tinting with BiVO4 composition processed through solid-state calcination. German automotive OEMs specify this grade for underhood coatings and interior trim where heat resistance and lightfastness must meet KBA material certification requirements.
- Bright Yellow:Surface-treated variants with engineered silane coatings achieve superior dispersion stability in high-solids clearcoats. Coil coating lines across Northern Europe specify Bright Yellow for architectural metal finishes exposed to UV degradation and salt corrosion, justifying formulation cost premiums against commodity alternatives.
- Pigment Green:Modified bismuth vanadate chemistry extends the hue angle toward yellow-green spaces for differentiated architectural color specifications.
- Pigment Blue:Niche formulations incorporating co-precipitated modifiers occupy specialty printing ink segments seeking non-toxic blue-green alternatives.
Most installed capacity flows through Yellow Bismuth Vanadate. Expansion is steepest in Bright Yellow.
Application:
Volume concentration sits in industrial maintenance coatings while value capture concentrates in automotive and coil coating segments with compliance documentation requirements.
- Coatings:Industrial OEM, automotive refinish, and coil coating formulations represent the dominant demand channel. REACH pigment bans have eliminated cadmium and lead chromate alternatives across European automotive supply chains, forcing specification switches to bismuth vanadate in waterborne and high-solids systems. ECHA enforcement actions against non-compliant coating imports are accelerating qualification timelines for certified pigment grades.
- Plastics:Polyolefin and PVC masterbatch applications require heat-stable pigments capable of surviving extrusion temperatures above 280°C. Consumer goods manufacturers in France and Italy specify bismuth vanadate for toys, household items, and electrical enclosures where RoHS compliance prohibits heavy-metal content.
- Inks:Flexographic and gravure packaging inks represent an emerging substitution channel as food-contact regulations displace cadmium yellows from direct substrate applications.
- Construction Materials:Concrete colorants and exterior facade coatings drive volume procurement through distributors serving ready-mix and precast concrete producers, though margin compression from commoditized specifications limits producer profitability.
Coatings absorb the majority of production output. Inks are gaining share fastest.
End User:
Procurement sophistication separates specification-driven OEMs from price-sensitive spot buyers in fragmented construction supply chains.
- Manufacturers:Industrial coating compounders and plastics masterbatch producers maintain the most stringent pigment qualification protocols. These buyers demand ISO 787 dispersion testing documentation, REACH compliance certificates, and batch-to-batch tinting strength consistency that locks in supplier relationships.
- Automotive Sector:Tier-one coating suppliers to German and French vehicle manufacturers face binding heavy-metal-free material certifications. KBA and ANSM regulatory oversight of automotive chemical compliance creates liability exposure that drives preference for pre-certified pigment systems from vertically integrated suppliers.
- Construction Companies:Regional concrete producers and facade contractors purchase through distribution networks with limited technical specification involvement, prioritizing color consistency and delivery reliability over dispersion performance metrics.
- Consumer Goods:Brand owners in toys, cosmetics packaging, and household products specify non-toxic pigments for EFSA and national regulator compliance, though smaller volume scales limit direct procurement relationships.
Manufacturers command the largest volume commitments. The automotive sector shows the steepest specification upgrade trajectory.
Distribution Channel:
Channel selection reflects buyer scale and compliance documentation requirements, with large coating houses bypassing intermediaries while regional players depend on distributor technical support.
- Direct Sales:Major coating manufacturers and automotive tier-one suppliers purchase pigment concentrates and dispersion pastes through annual framework agreements. These relationships bundle compliance documentation, technical service support, and volume pricing mechanisms that displace spot-market procurement.
- Distributors:Regional industrial chemical distributors serve mid-scale coating houses and plastics compounders across Benelux, Northern Italy, and the US Midwest. These intermediaries provide inventory buffering, local technical consultation, and consolidated procurement for buyers lacking direct supplier certification.
- Online Sales:E-commerce platforms capture small-laboratory and R&D sampling demand, though regulatory documentation limitations restrict adoption in production-scale coating applications.
- Retail Stores:Specialty chemical retailers and paint store chains serve architectural coating contractors and small maintenance shops with packaged pigment dispersions.
Direct sales channels handle the majority of volume. Distributor relationships are expanding most quickly among mid-tier coating houses consolidating supplier bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration follows regulatory arbitrage as Chinese bismuth refining capacity supplies European formulation houses facing REACH compliance costs. Pigment synthesis gravitates toward jurisdictions with integrated raw material access and lower energy intensity.
Germany
Automotive OEM coating specifications from Volkswagen, BMW, and Mercedes-Benz enforce KBA-certified heavy-metal-free pigment systems. ECHA REACH enforcement actions against non-compliant imports tighten qualification timelines for bismuth vanadate grades. The Stuttgart-Munich industrial corridor concentrates tier-one coating supplier relationships with pigment houses maintaining ISO 787 documentation.
China
Concentrated bismuth metal refining capacity in Hunan and Jiangxi provinces anchors upstream raw material supply for global pigment synthesis. The country's national chemical regulator maintains export certification requirements that shape supplier qualification for Western markets. Yangtze River Delta pigment manufacturers serve domestic coatings demand while exporting intermediate grades to European compounders.
United States
EPA TSCA Section 6 hazard standards elevate certification barriers for imported pigment formulations entering automotive refinish networks. Midwest industrial maintenance coating distributors consolidate procurement around pre-certified colorant systems with compliance documentation. Michigan and Ohio automotive supplier clusters drive specification upgrades for heavy-metal-free underhood coatings.
France
ANSM oversight of automotive chemical compliance creates liability exposure that accelerates bismuth vanadate adoption in PSA Stellantis supply chains. RoHS enforcement in consumer goods manufacturing displaces cadmium pigments from toys and electrical enclosures. The Lyon-Grenoble chemicals corridor hosts masterbatch compounders serving packaging and household appliance segments.
Italy
Coil coating lines in Northern Italy serving architectural metal processors reformulate toward waterborne platforms demanding superior pigment dispersibility. ECHA F-Gas Regulation phase-down schedules pressure elimination of solvent-borne systems that masked dispersion deficiencies. Benelux-Italy distribution networks consolidate mid-tier coating house procurement around certified dispersion concentrates.
Bismuth Vanadate Pigment Market Competitive Landscape
Capacity expansion dominates the current landscape as pigment houses respond to compressed substitution timelines from REACH pigment bans. The vendor base stratifies between vertically integrated majors with captive bismuth supply and specialized colorant houses competing on formulation expertise. Three archetypes anchor positioning: diversified chemical conglomerates with pigment divisions, pure-play inorganic pigment specialists, and regional synthesis houses serving construction-grade volume. M&A activity and backward integration into bismuth refining represent the dominant competitive vectors as producers defend margin positions against raw material volatility.
Within the diversified chemical tier, BASF and Heubach exemplify integrated positioning spanning multiple pigment chemistries with regulatory-compliant color solutions. Among specialized colorant houses, Vibrantz Technologies occupies a position representing high-performance industrial application expertise. The German-origin archetype clusters around Bruchsaler Farbenfabrik and Kremer Pigmente, reflecting European formulation heritage serving premium coating segments. Chinese synthesis capacity concentrates in Shanghai Linhui Chemical, representing cost-optimized production serving volume-driven construction applications. These five named entities collectively illustrate the geographic and capability segmentation structuring competitive rivalry.
| Leading Market Players |
|---|
| Vibrantz Technologies |
| Bruchsaler Farbenfabrik |
| BASF |
| Kremer Pigmente |
| Shanghai Linhui Chemical |
| Heubach |
| Shepherd Color |
| Stanford Advanced Materials |
| DCL Corporation |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between automotive-compliant Bright Yellow and construction-grade commodity pigment splits the market into parallel pricing architectures. German OEMs pay dispersion-performance premiums for KBA-certified concentrates while concrete colorant buyers negotiate spot-market bismuth metal pass-throughs, creating supply chain configurations that separate vertically integrated pigment houses from regional distributors serving volume buyers.
Pricing Analysis
Distributor margin layers compress as coating houses consolidate procurement around direct annual framework agreements with pigment manufacturers. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 787 certification status, surface-modification technology, and batch-to-batch tinting consistency. Pricing pressure stems from Chinese bismuth metal price volatility that feeds through to pigment producer cost bases. Construction material buyers exhibit highest price sensitivity, while automotive tier-one suppliers accept formulation premiums for liability protection.
Supply Chain Analysis
REACH-compliant sourcing mandates reshape procurement toward European pigment synthesis houses with documented ECHA registration. Raw material supply draws from Chinese bismuth refining capacity in Hunan and Jiangxi provinces, German formulation expertise in Stuttgart-Munich corridor, and US Midwest distribution hubs serving industrial maintenance coatings. Single-source vulnerability concentrates in Chinese upstream metal supply. Distribution runs through direct sales channels for major coating manufacturers and chemical distributors for mid-tier compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bismuth vanadate pigment market compounds steadily as regulatory displacement of heavy-metal alternatives creates durable substitution demand. REACH enforcement and automotive compliance mandates provide predictable volume expansion.
For Market Incumbents: Hedge against Chinese bismuth price volatility through backward integration into metal refining or long-term offtake agreements with Hunan-based suppliers. Invest in surface-modification R&D to defend premium positioning as Bright Yellow grades commoditize. Lock in automotive tier-one relationships through embedded technical service teams that accelerate ISO 787 qualification timelines.
For New Entrants and Emerging Players: Launch via specialized distribution partnerships serving Northern Italy and Benelux coil coating lines reformulating toward waterborne platforms. Target construction-grade Yellow Bismuth Vanadate where certification barriers are lowest and volume scales justify capacity investments. Differentiate through photocatalytic functionality convergence for self-cleaning architectural coatings.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented Chinese synthesis capacity faces REACH documentation barriers for European market access. Five-to-ten-year viability favors vertically integrated players with captive bismuth supply and automotive certification heritage. Monitor EPA TSCA Section 6 enforcement intensity as signal for US market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bismuth Refining | Captive metal supply insulates margin compression from Chinese price volatility. |
| Surface-Modification Technology Investment | Engineered silane coatings command automotive clearcoat formulation premiums. |
| REACH Compliance Documentation Buildout | ECHA registration accelerates qualification for European coatings value chains. |
| Photocatalytic Functionality Development | Dual-use pigment-catalyst products capture self-cleaning architectural demand. |
| Direct Sales Channel Expansion | Annual framework agreements displace distributor markups in automotive supply. |
Research Methodology
Coverage spans Germany, China, United States, France, and Italy, with primary inputs from each market cluster. The analysis combines interviews with pigment plant managers, automotive coating procurement leads, industrial chemical distributors, and technical R&D directors with secondary validation from ECHA regulatory filings, customs trade data, SEC 10-K disclosures, and Cefic industry reports. Bottom-up volume modeling triangulates against top-down market sizing across the analysis window.
Granularity-level modeling operates at product grade, application segment, end-user archetype, and distribution channel dimensions. The analytical framework projects value expansion over the projection horizon by applying CAGRs derived from regulatory substitution timelines, automotive production forecasts, and coating formulation mix shifts. Bismuth metal price trajectories and REACH enforcement intensity serve as key sensitivity inputs.
Several conditions sit outside the modeled scope, including geopolitical disruption of Chinese bismuth supply, breakthrough organic pigment alternatives, and automotive OEM insolvency events. Forecasts reflect assumptions about sustained regulatory enforcement and stable raw material access. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Iron Oxide Pigments Market
Dyes and Pigments
Water-Based Pigments Market
Dyes and Pigments
Natural Colorants Market
Dyes and Pigments
Europe Hair Colorants Market
Dyes and Pigments
Synthetic Dyes Market
Dyes and Pigments
Indigo Carmine Market
Dyes and Pigments
Oil-Dispersible Colors Market
Dyes and Pigments
Riboflavin Pigment Market
Dyes and Pigments
Titanium Dioxide Pigment Market
Dyes and Pigments
Inorganic Cosmetics Pigments Market
Dyes and Pigments
Quinacridone Pigments Market
Dyes and Pigments
Organic Pigment Dispersions Market
Dyes and Pigments
Acid Violet 43 Market
Dyes and Pigments
Thermochromic Labels Market
Dyes and Pigments
Lithol Rubine BK Market
Dyes and Pigments
Reactive Dyes Market