
 Color Retention Agents Market | 2026-2036
Color Retention Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Color Retention Agents Market Insights
Clean-label formulation chemistry is narrowing the gap between synthetic and bio-derived color retention performance. BASF SE leverages its polymer additive portfolio to serve European automotive coating specifications. Zhejiang Longsheng Group Co., Ltd. anchors regional supply through backward integration into azo intermediate production. Clariant AG differentiates via halogen-free pigment stabilization systems for high-temperature plastics processing.
Color retention agents comprise chemical additives—typically polymeric dispersants, chelating compounds, or UV absorbers at 0.5–3.0 wt% loading—that inhibit photodegradation, oxidation, and leaching of colorants across substrate surfaces. These agents function by forming protective matrices around dye molecules or scavenging free radicals generated under thermal and light exposure. Additives command the largest volume share due to universal incorporation across textile finishing and coating formulations. Liquid forms lead in coatings and ink applications where in-line dosing integrates with continuous production, while powder variants dominate textile pad-dry operations in South Asian processing hubs.
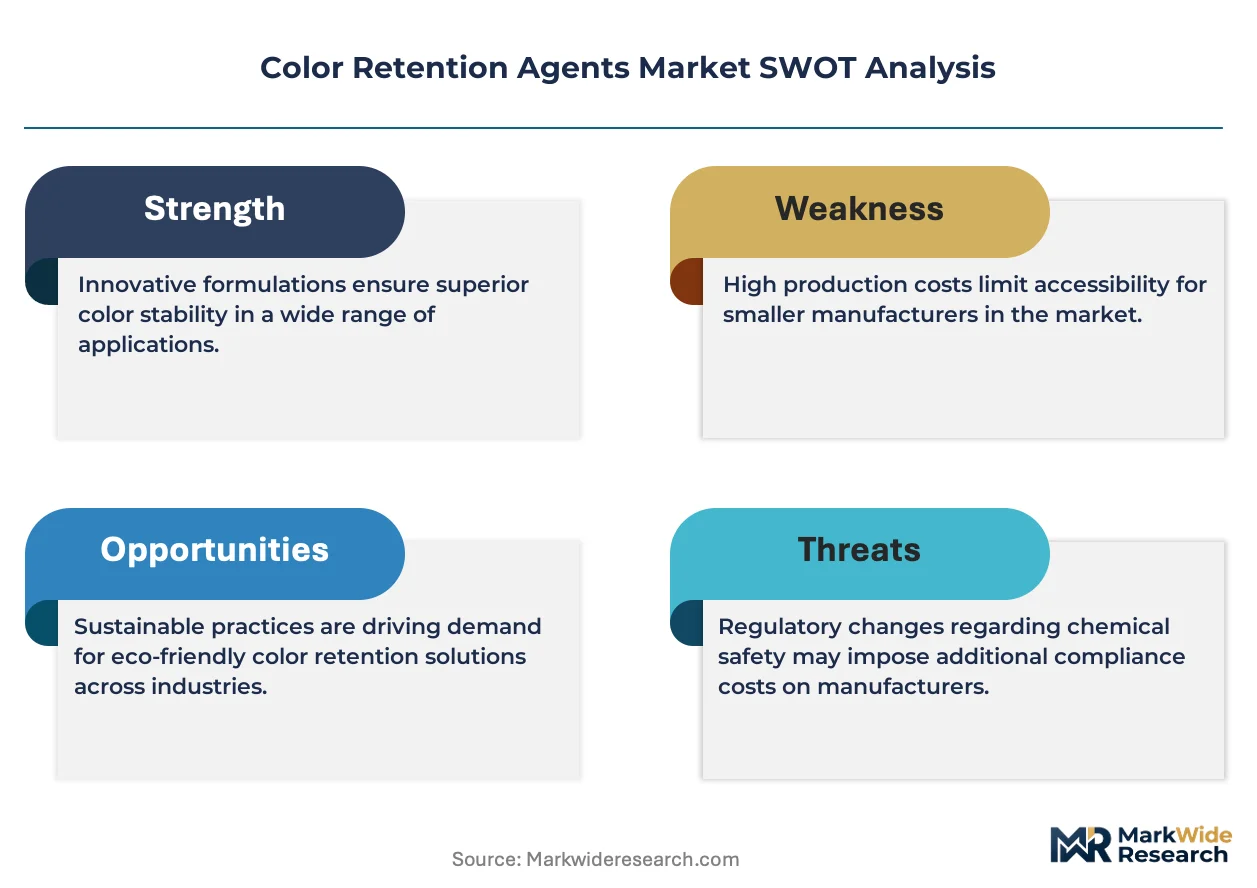
EPA toxics release reporting and REACH substance restriction protocols constrain formaldehyde- and heavy metal-based formulations, redirecting R&D toward aldehyde-free crosslinkers and metal-complex alternatives. China's MEE enforces GB standards on dyehouse effluent COD limits, forcing upgrade cycles in Zhejiang and Jiangsu provinces. Stakeholders must monitor regulatory divergence between EU chemical hazard classifications and emerging ASEAN harmonization frameworks to avoid compliance fragmentation across supply networks.
Market Dynamics
Formaldehyde-free crosslinker chemistry is compressing incumbent supply chains as South Asian textile mills retrofit finishing lines to meet tightened MEE effluent standards. This substitution wave is redistributing value toward bio-based polymer developers with captive intermediate supply.
Growth Catalysts
- REACH substance restrictions:European ECHA enforcement against heavy metal-based stabilizers is accelerating aldehyde-free formulation adoption across automotive coating specifications.
- India's Gujarat-Tamil Nadu corridor:Export-oriented dye house clusters in these states are specifying third-party certified color retention chemistries to secure EU and US apparel brand contracts.
- UV-absorber hybridization:Benzotriazole-benzophenone copolymer systems are penetrating high-performance outdoor textile applications where photostability requirements exceed single-mechanism protection.
Market Restraints
- Petrochemical feedstock volatility:Ethylene oxide and propylene oxide price swings compress margin visibility for polymeric dispersant manufacturers with spot-exposed input contracts.
- China supply concentration:Zhejiang and Jiangsu provinces host over 60 percent of azo intermediate capacity, creating single-geography disruption exposure for downstream color retention agent synthesis.
- Performance gap in natural fiber substrates:Bio-derived agents exhibit 15-30 percent lower wash fastness ratings on unmercerized cotton versus synthetic alternatives, limiting premium positioning.
Strategic Opportunities
- Vietnam's emerging dye house base:EU-Vietnam Free Trade Agreement tariff advantages are attracting FDI in finishing capacity, creating first-mover positioning for compliant color retention chemistry suppliers.
- Digital textile printing convergence:Inkjet pigment stabilization requirements are opening adjacent demand for low-foam dispersants in single-pass printing systems.
- EU Green Deal procurement mandates:Public sector textile purchasing rules are embedding bio-based content thresholds, creating guaranteed offtake for certified sustainable formulations.
Industry Challenges
- Formulation-to-substrate matching complexity:Each fiber type—polyester, cotton, wool, regenerated cellulose—demands distinct chelation chemistry, fragmenting R&D resource allocation across specialty product lines.
- MEE compliance timeline compression:Chinese dye houses face 18-month upgrade windows for COD limit adherence, straining technical service capacity of additive suppliers managing simultaneous retrofit programs.
- Cross-border certification reciprocity gaps:OEKO-TEX and bluesign mutual recognition limitations force duplicate testing expenditures for suppliers serving both European and North American apparel brand specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Color Retention Agents Market |
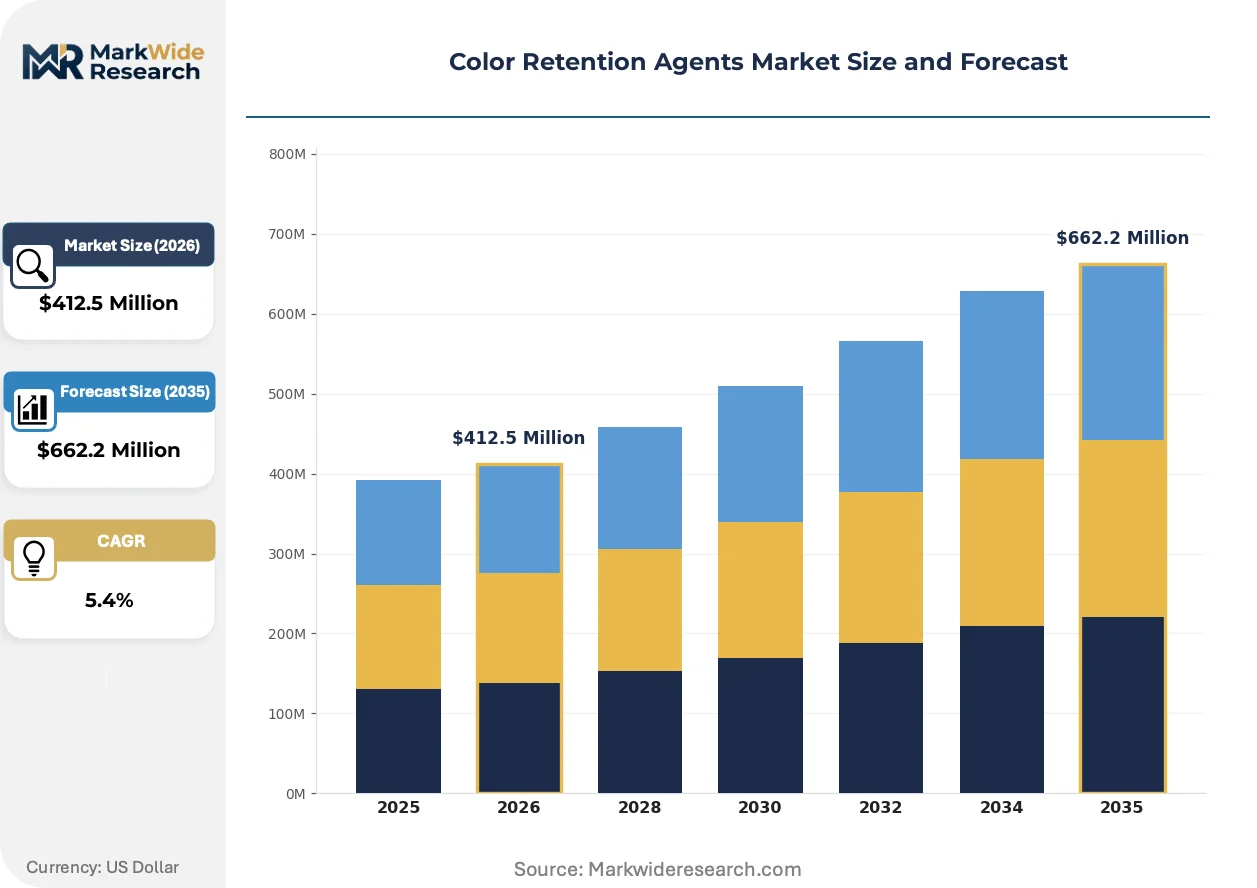
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dyes, Pigments, Additives, Sealants End Use Industry: Textiles, Coatings, Plastics, Inks Application: Automotive, Fibers, Construction, Consumer Goods Form: Liquid, Powder, Concentrate, Granules |
| Companies Covered | BASF SE, Uralchem, Zhejiang Longsheng Group Co., Ltd., Linyi Luguang Chemical Co., Ltd., APAC Chemical Corporation, Clariant AG, Dow Chemical, LANXESS, Croda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Color Retention Agents Market Trends and Innovations
Bio-based polymer stabilization chemistry is converging with conventional synthetic performance benchmarks, collapsing the traditional premium pricing wedge between sustainable and incumbent formulations. This convergence is compressing product development cycles and redrawing competitive boundaries.
Reactive dispersant technology is hybridizing with conventional UV-absorber mechanisms to create single-additive solutions for outdoor textile applications. European automotive seating suppliers are qualifying these hybrid systems for accelerated weathering specifications previously requiring multi-component dosing. The resulting formulation simplification is hybridizing supplier value propositions toward integrated performance packages rather than discrete chemistries.
China's MEE is enforcing GB 4287-2012 effluent standards with unannounced inspection protocols, forcing dye houses toward closed-loop water systems. This regulatory pressure is compressing demand for heavy metal-free chelating agents in Jiangsu and Zhejiang processing clusters. Suppliers with pre-certified metal-complex alternatives are capturing upgrade cycle procurement.
Apparel brand technical audit requirements are compressing supplier qualification timelines from 24 months to 12 months for color retention chemistry approvals. Tier-1 dye houses in India's Tiruppur cluster are consolidating supplier relationships to three preferred partners per chemical category to manage compliance documentation burden. This concentration is visible across export-oriented finishing operations serving US and EU retail brand specifications.
Color Retention Agents Market Segmentation
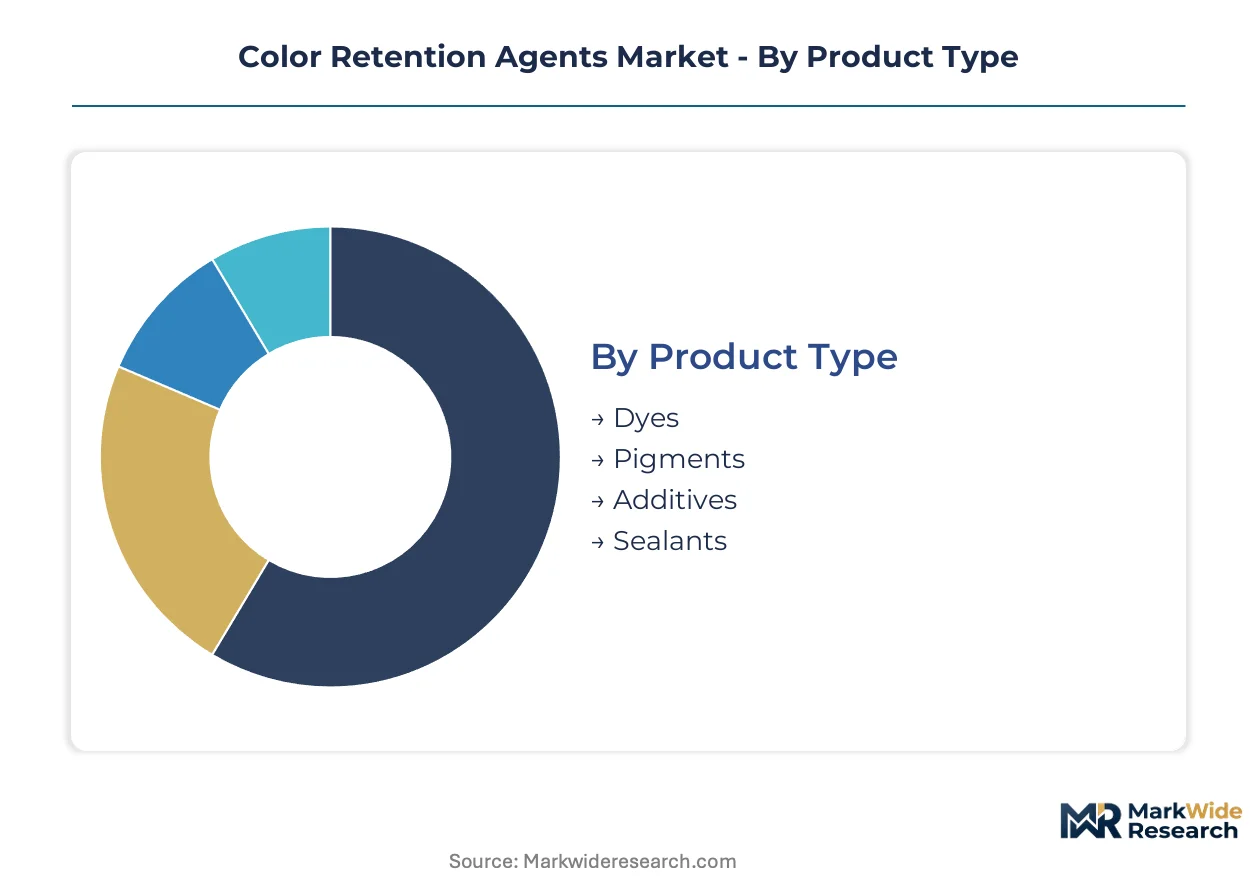
Color retention agents serve distinct performance requirements across substrate chemistries and processing conditions. Segmentation reveals how formulation specifications diverge between high-volume textile finishing and precision coating applications.
Product Type:
After-sales technical service intensity varies sharply across product categories, with complex multi-component systems demanding sustained formulation support.
- Additives:Polymeric dispersants, chelating compounds, and UV absorbers at 0.5–3.0 wt% loading form protective matrices around dye molecules or scavenge free radicals. Demand concentrates in textile finishing and coating formulations across India's Gujarat and Tamil Nadu industrial corridors where export-oriented dye houses cluster.
- Pigments:Halogen-free stabilization systems for high-temperature plastics processing require precise thermal resistance specifications. European automotive coating applications drive qualification protocols, with ECHA enforcement against heavy metal-based stabilizers accelerating aldehyde-free formulation adoption.
- Dyes:Colorant molecules requiring stabilization against photodegradation and oxidation in fiber substrates.
- Sealants:Protective barrier formulations preventing colorant leaching from coated surfaces.
By volume, Additives leads. By growth pace, Pigments is gaining share fastest amid REACH-driven substitution cycles.
End Use Industry:
Cost tier stratification separates commodity textile processing from premium automotive coating specifications.
- Textiles:Pad-dry operations in South Asian processing hubs dominate consumption, with formaldehyde-free crosslinker chemistry compressing incumbent supply chains. Mills across Gujarat and Tamil Nadu specify third-party certified chemistries to secure EU and US apparel brand contracts.
- Coatings:Liquid formulation dosing integrates with continuous production lines. European automotive seating suppliers are qualifying hybrid UV-absorber systems for accelerated weathering specifications.
- Plastics:High-temperature processing demands thermal stability beyond textile applications.
- Inks:Digital textile printing convergence is opening adjacent demand for low-foam dispersants in single-pass printing systems.
Textiles commands the largest volume position. Coatings is climbing the fastest on automotive specification upgrades.
Application:
Customer type fragmentation separates industrial procurement from consumer-facing brand requirements.
- Fibers:Natural and synthetic substrates each demand distinct chelation chemistry, fragmenting R&D resource allocation. Bio-derived agents exhibit performance gaps on unmercerized cotton versus synthetic alternatives.
- Automotive:Accelerated weathering specifications previously requiring multi-component dosing now accept hybrid reactive dispersant systems. EU automotive coating specifications drive stringent qualification timelines.
- Construction:Exterior durability requirements favor UV-absorber hybridization for prolonged color stability.
- Consumer Goods:Apparel brand technical audit requirements are compressing supplier qualification timelines from 24 months to 12 months.
Fibers dominates by volume. Automotive shows the steepest expansion trajectory on seating and exterior component demand.
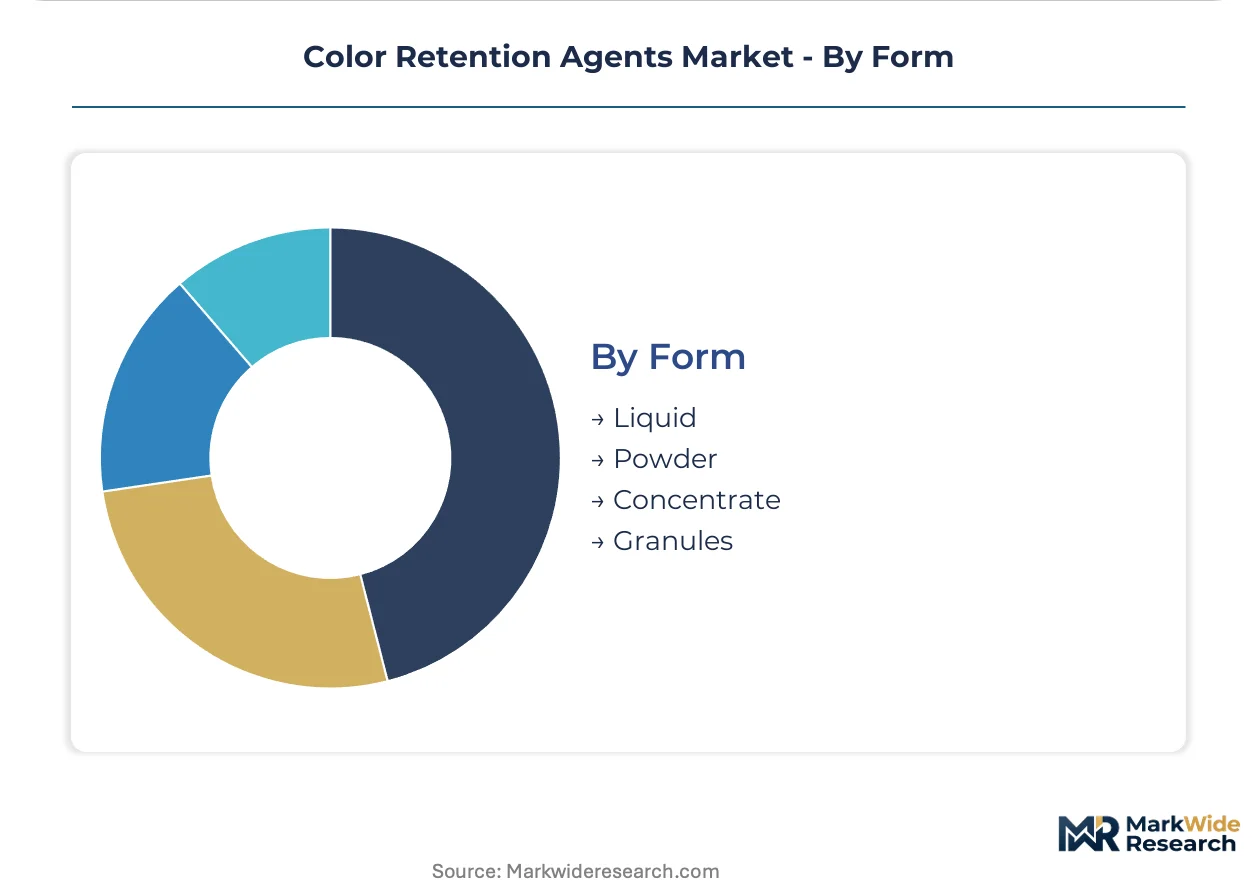
Form:
Supply concentration in liquid production centers on coatings and ink manufacturing corridors.
- Liquid:In-line dosing compatibility with continuous production systems. Dominates coatings and ink applications where process integration outweighs shipping cost considerations.
- Powder:Pad-dry operations in South Asian textile hubs favor dry-form processing. China's Jiangsu and Zhejiang provinces host concentrated powder formulation capacity.
- Concentrate:Reduced logistics costs for remote processing facilities with on-site dilution capability.
- Granules:Dust-free handling properties for automated dosing systems in large-scale operations.
Liquid leads by volume. Concentrate is expanding most quickly on logistics optimization priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Gujarat and Tamil Nadu industrial corridors export finished textiles to EU and US apparel brands, driving formaldehyde-free chemistry specifications through the supply chain.
China
Jiangsu and Zhejiang provinces host over 60 percent of azo intermediate capacity for downstream synthesis. MEE enforces GB 4287-2012 effluent standards with unannounced inspections, forcing dye houses toward closed-loop water systems and heavy metal-free chelating agents.
Germany
Automotive coating specifications from BASF SE and LANXESS drive REACH-compliant aldehyde-free formulation demand. ECHA enforcement against heavy metal-based stabilizers accelerates substitution cycles across European automotive seating supply chains.
United States
EPA toxics release reporting constrains formaldehyde-based formulations in textile finishing. Export-oriented dye houses in North Carolina and Georgia specify third-party certified chemistries to secure apparel brand contracts with stringent audit requirements.
Vietnam
EU-Vietnam Free Trade Agreement tariff advantages attract FDI in finishing capacity. Emerging dye house bases in Ho Chi Minh City and Hanoi industrial zones create first-mover positioning for compliant color retention chemistry suppliers.
Color Retention Agents Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation complexity tiers. The vendor base spans multinational chemical conglomerates with polymer additive portfolios and regional azo intermediate producers with backward integration. Three archetypes dominate: integrated petrochemical players, specialty chemical formulators, and captive intermediate suppliers. M&A activity concentrates on aldehyde-free technology licensing, while capacity expansion targets South Asian textile processing corridors.
Among European-based chemical conglomerates, BASF SE and Clariant AG exemplify the integrated formulation archetype with polymer stabilization portfolios. Zhejiang Longsheng Group Co., Ltd. anchors the regional captive supply tier through azo intermediate production control. These three represent distinct competitive positions: multinational specification-setters, regional supply-chain controllers, and hybrid technology licensors.
| Leading Market Players |
|---|
| BASF SE |
| Uralchem |
| Zhejiang Longsheng Group Co., Ltd. |
| Linyi Luguang Chemical Co., Ltd. |
| APAC Chemical Corporation |
| Clariant AG |
| Dow Chemical |
| LANXESS |
| Croda |
| Others |
Pricing and Supply Chain Analysis
Jiangsu province's azo intermediate concentration grants its producers substantial leverage over downstream color retention agent pricing, particularly as MEE enforcement tightens COD discharge limits and forces dye houses toward certified heavy metal-free alternatives. Buyers in India's Tiruppur cluster face compressed negotiation windows as supplier qualification timelines shrink from twenty-four to twelve months, shifting procurement power toward pre-certified chemistry providers with captive intermediate supply.
Pricing Analysis
Next-generation bio-based polymeric agents command a narrowing premium against incumbent synthetic formulations as performance benchmarks converge. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales technical service intensity. Cost compression in standard-tier liquid dispersants is intensifying because ethylene oxide and propylene oxide feedstock volatility erodes margin visibility for spot-contract manufacturers. Export-oriented dye houses in Gujarat and Tamil Nadu exhibit highest price sensitivity due to apparel brand cost-down mandates, while European automotive coating specifications show lowest sensitivity given qualification-driven switching costs.
Supply Chain Analysis
REACH substance restrictions and evolving ASEAN harmonization frameworks constrain cross-border flows of heavy metal-based stabilizers and formaldehyde-containing crosslinkers. Manufacturing gravity centers on China, India, and Germany, with Jiangsu and Zhejiang provinces hosting over sixty percent of azo intermediate capacity. Synthesis draws from ethylene oxide, propylene oxide, and benzotriazole derivatives as critical inputs. Single-geography disruption exposure in Zhejiang creates vulnerability to unannounced MEE inspection protocols. Distribution runs through regional chemical distributors serving textile processing corridors, with direct supply relationships dominating automotive coating qualifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scalable formulation expertise for formaldehyde-free crosslinker chemistry remains scarce relative to demand from South Asian retrofit cycles, creating asymmetric returns for asset owners with proven MEE compliance pathways and third-party certification infrastructure.
For Market Incumbents: Insulate core margin pools by securing captive azo intermediate supply through backward integration or long-term offtake agreements with Zhejiang-based producers. Accelerate certification investment for bluesign and OEKO-TEX reciprocity to reduce duplicate testing burdens for dual-market suppliers. The threat of bio-based polymer developers collapsing the synthetic premium demands preemptive positioning in hybrid UV-absorber systems for automotive seating specifications. For New Entrants and Emerging Players: Pursue Vietnam's emerging dye house base in Ho Chi Minh City and Hanoi industrial zones, where EU-Vietnam Free Trade Agreement tariff advantages attract FDI in finishing capacity without entrenched supplier relationships. Digital textile printing convergence offers adjacent white-space for low-foam dispersant specialists serving single-pass inkjet systems. A technical service-heavy go-to-market model differentiates against commodity traders in qualification-compressed procurement environments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors aldehyde-free chemistry licensors with demonstrated MEE compliance pathways and scalable bio-based polymer platforms. Long-term viability hinges on regulatory divergence management across EU REACH and emerging ASEAN frameworks. Acquisition targets should display captive intermediate supply or exclusive distribution rights in India's Gujarat-Tamil Nadu corridor. The signal to watch is MEE inspection protocol expansion beyond Jiangsu and Zhejiang into Shandong province, which would accelerate closed-loop water system adoption and reshape chelating agent demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Azo Intermediates | Secures supply continuity for formaldehyde-free crosslinker production amid Zhejiang concentration risk. |
| Green Manufacturing Transition | Aligns with EU Green Deal procurement mandates embedding bio-based content thresholds in public sector textile purchasing. |
| Long-term Supply Agreement | Locks in offtake from India's Tiruppur cluster dye houses consolidating to three preferred partners per chemical category. |
| Joint Venture | Enables first-mover positioning in Vietnam's emerging Ho Chi Minh City finishing capacity under EU-Vietnam FTA tariff advantages. |
| Capacity Expansion | Captures upgrade cycle demand from Chinese dye houses facing eighteen-month MEE compliance windows for COD limit adherence. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC chemical company filings, and European Chemicals Agency substance restriction databases. Primary interviews engaged plant managers at South Asian dye houses, procurement leads at European automotive seating suppliers, technical R&D directors at polymer additive manufacturers, and distribution channel partners serving textile processing corridors. Bottom-up volume estimates from individual facility throughput triangulate against top-down demand aggregation across end-use industries.
Forecast inputs incorporate grade tier stratification across premium certified and standard uncertified formulations, end-use industry segmentation spanning textiles and automotive coatings, packaging format differentiation between liquid and powder variants, and regional production hub concentration in Jiangsu, Gujarat, and Tamil Nadu. CAGRs derive from slope analysis of historical substitution patterns and regulatory enforcement intensity trajectories. Industry-specific inputs include MEE inspection protocol expansion assumptions and EU Green Deal procurement mandate adoption curves.
Sensitivities concentrate around MEE enforcement intensity variations, REACH substance restriction scope expansion, and bio-based polymer performance convergence timelines. Forecasts embed assumptions regarding azo intermediate capacity stability and apparel brand audit requirement continuity. Material shifts in ASEAN harmonization framework alignment with EU hazard classifications would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Europe Natural Dyes and Pigments Market
Dyes and Pigments
Acid Orange Market
Dyes and Pigments
Global Thermochromic Paint Market
Dyes and Pigments
Zinc Oxide Pigments Market
Dyes and Pigments
Chemochromic Material Market
Dyes and Pigments
Synthetic Dyes Market
Dyes and Pigments
Pearl Pigment Market
Dyes and Pigments
Global Organic Pigments Market
Dyes and Pigments
Erythrosine Market
Dyes and Pigments
Acid Stable Blue Market
Dyes and Pigments
Metal Complex Dyes Market
Dyes and Pigments
Plastic Pigments Market
Dyes and Pigments
Fluorescent Brightening Agents Market
Dyes and Pigments
Phthalocyanine Pigments Market
Dyes and Pigments
Thermochromic Pigments Market
Dyes and Pigments
Pigment Dispersion Resin Market