
 Mulch Colorants Market | 2026-2036
Mulch Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
Mulch Colorants Market Foresight
North American pigment manufacturers is rebalancing capacity toward iron oxide and carbon black dispersions as landscaping seasonality lengthens. BASF SE leverages its global pigments portfolio to supply high-purity iron oxides for brown and red mulch applications. Amerimulch anchors its position through integrated production of colorant systems and application equipment for commercial mulch producers. Sun Chemical Corporation competes in water-based dispersion technology, sustaining R&D investment in low-VOC formulations for regulatory-sensitive markets.
Mulch colorants are concentrated pigment dispersions, typically iron oxide, carbon black, or organic azo compounds suspended in water-based or solvent-based carriers, applied at rates of 0.5–2.0% by weight to shredded wood or bark to enhance visual uniformity and UV stability. Their primary commercial purpose is to extend aesthetic appeal between replacement cycles, reducing landfill-bound organic waste volumes. Water-based formulations now lead volume shipments due to EPA VOC regulations and landscaper preference for reduced odor and faster drying, while oil-based systems retain share in premium red and gold segments where colorfastness demands justify higher material costs. Brown colorants occupy the largest demand share aligned with natural hardwood mulch dominance, though black colorants are gaining fastest among municipal and commercial accounts seeking contrast with building facades.
The EPA regulates VOC content under 40 CFR 59, pushing reformulation timelines, while OSHA workplace exposure limits govern mixer and sprayer operator protocols in commercial colorant facilities. State-level regulations in California through CARB impose stricter limits than federal baselines, fragmenting compliance requirements for multi-state suppliers. REACH registration obligations in Europe constrain export eligibility for non-compliant pigment chemistries. Stakeholders must monitor evolving state adoption of California's VOC thresholds and assess backward integration into iron oxide sourcing to defend margin structures against pigment cost volatility.
Market Dynamics
Water-based formulation migration under EPA 40 CFR 59 VOC limits is compressing solvent-based capacity while iron oxide pigment sourcing tightens around southeastern US mulch production clusters.
Growth Catalysts
- Extended Landscaping Seasons:Year-round mulch maintenance cycles in subtropical US states sustain elevated colorant consumption rates per acre versus seasonal northern markets.
- EPA VOC Regulatory Enforcement:Federal emission limits on solvent-based coatings accelerate commercial producer conversion to compliant water-based dispersion systems.
- Municipal Hardscape Contrast Demand:Urban planning departments specify black-dyed mulch for visual separation between green infrastructure and building facades.
Market Restraints
- Iron Oxide Feedstock Volatility:Pigment-grade iron oxide supply concentrates among Chinese and Indian chemical processors, exposing formulators to freight and tariff cost swings.
- CARB Regulatory Fragmentation:California's stricter VOC thresholds than federal baselines force multi-state suppliers to maintain parallel formulation inventories.
- Natural Mulch Substitution:Unprocessed bark and wood chip alternatives compete on upfront material cost in price-sensitive residential segments.
Strategic Opportunities
- Midwest Commercial Landscaping:Ohio and Illinois municipal accounts show underpenetrated adoption of colorant-treated mulch versus saturated southeastern markets.
- UV-Stable Organic Pigment Convergence:Hybrid formulations combining carbon black with novel organic azo compounds address colorfastness gaps in water-based systems.
- Direct-to-Producer Equipment Bundling:Integrated colorant and application machinery packages reduce distributor markup capture in regional mulch yards.
Industry Challenges
- REACH Registration Timelines:European chemical compliance obligations delay export market entry for non-registered pigment chemistries.
- Mixer Operator Exposure Protocols:OSHA workplace limits on dust and vapor exposure require capital investment in enclosed handling systems at commercial facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mulch Colorants Market |
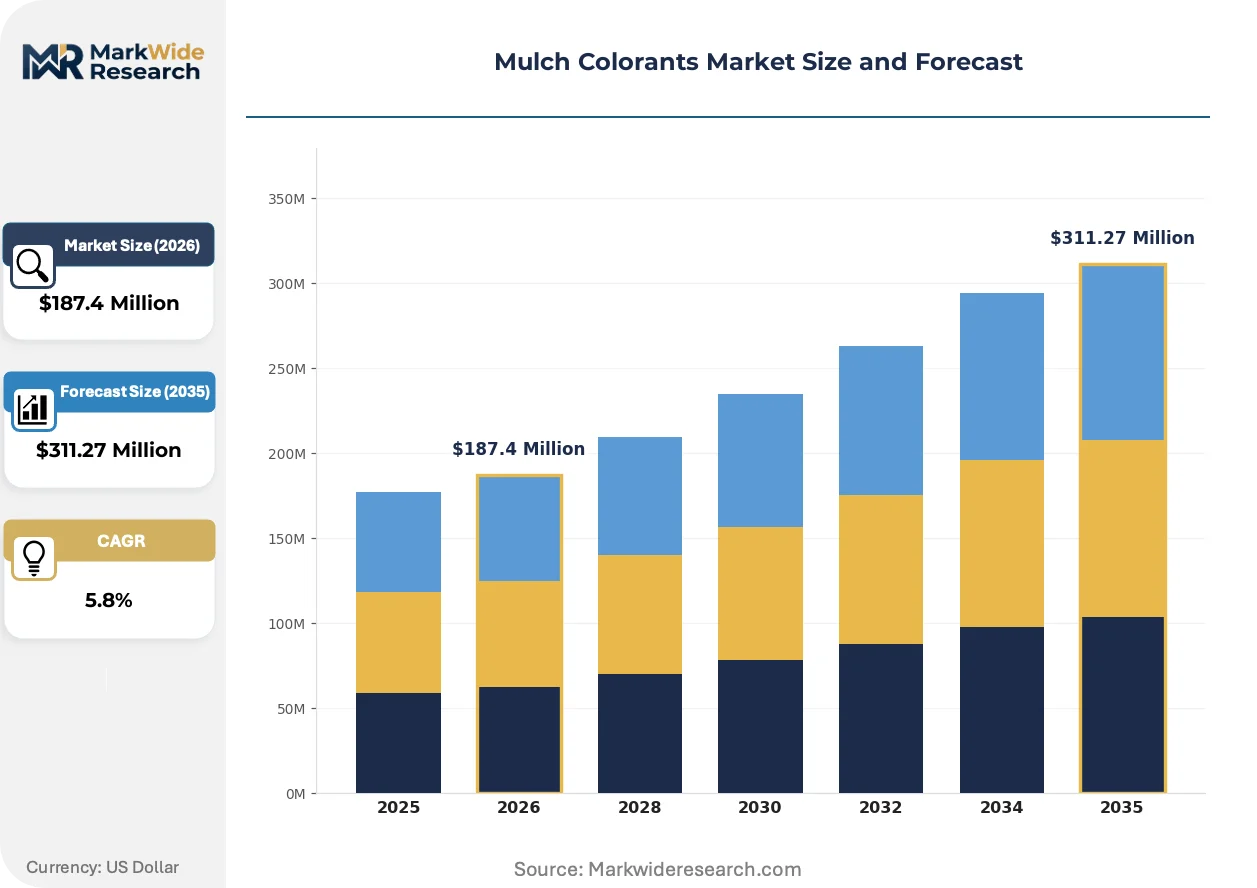
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Color Type: Brown, Black, Red, Gold Formulation: Water-Based, Oil-Based, Solvent-Based, Powder Application Method: Spray, Mix, Dip, Coating End User: Landscapers, Gardeners, Nurseries, Retailers |
| Companies Covered | BASF SE, The Sherwin-Williams Company, Amerimulch, Sun Chemical Corporation, Colorbiotics, AgriCoatings, Sasco Chemical Group, Inc., Drexel Chemical Company, Troy Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mulch Colorants Market Shifts & Advancements
Formulation chemistry and application hardware are converging to reduce operational complexity while regulatory pressure compresses acceptable emission profiles.
Water-based dispersion technology is consolidating market position as the dominant carrier system for iron oxide and carbon black pigments in commercial mulch production. Residential landscaping contractors and municipal maintenance departments are specifying low-odor, fast-drying formulations at accelerating rates. This shift is consolidating solvent-based capacity into premium red and gold niche segments where colorfastness specifications justify higher material costs.
EPA enforcement of 40 CFR 59 VOC content limits is forcing reformulation investments across multi-state suppliers. Commercial colorant facilities face compressed compliance timelines as state-level adoption of California CARB thresholds spreads beyond the West Coast. Water-based brown colorants for hardwood mulch applications absorb the bulk of regulatory-driven product development resources.
Specification authority is migrating from distributors to end-use landscaping contractors seeking bundled colorant and equipment packages. Regional mulch yards are disintermediating traditional supply channels through direct procurement relationships with pigment formulators. This pattern concentrates in the southeastern United States where year-round maintenance contracts sustain higher volume purchasing commitments.
Mulch Colorants Market Segmentation
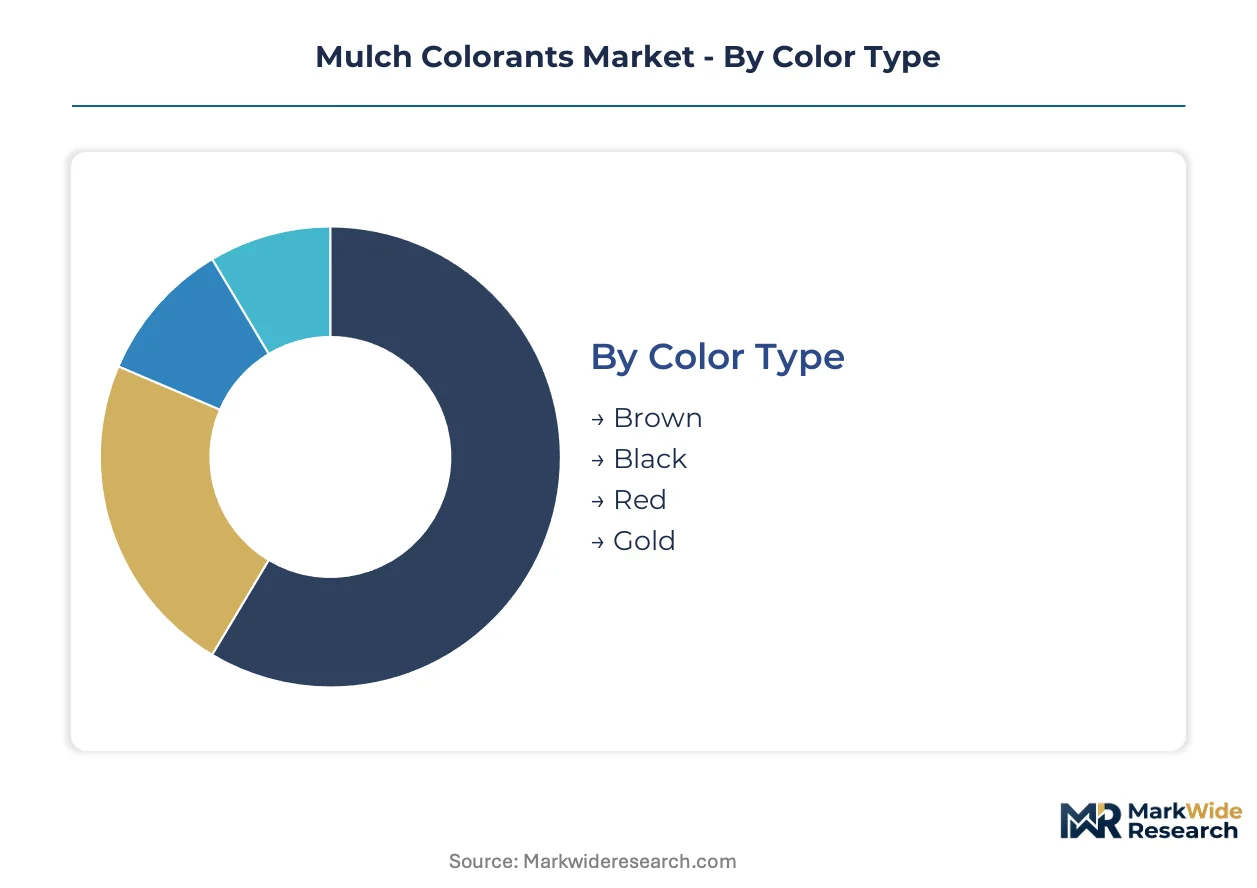
Mulch colorant purchasing decisions cascade through formulation chemistry, color specification, and application infrastructure requirements. Each segment carries distinct regulatory burdens and margin profiles that reshape supplier positioning across commercial and residential channels.
Color Type:
Brown and black colorants face baseline EPA 40 CFR 59 compliance, while red and gold variants trigger additional state-level scrutiny under CARB thresholds due to higher organic pigment content.
- Brown:Iron oxide-based dispersions dominate hardwood mulch applications across southeastern US production clusters. Municipal maintenance contracts in Florida and Georgia specify brown for natural aesthetic alignment with native vegetation, sustaining the highest volume consumption per acre in subtropical climate zones.
- Black:Carbon black formulations deliver maximum UV stability and visual contrast against building facades and hardscape elements. Urban planning departments in Texas and North Carolina are specifying black-dyed mulch at accelerating rates for commercial and institutional landscaping.
- Red:Premium iron oxide and organic azo blends serve niche decorative applications where colorfastness justifies elevated material costs.
- Gold:Specialty pigment systems retain limited share in high-end residential and resort landscaping segments.
Brown sits at the top of the volume ranking, with black climbing the fastest as municipal contrast specifications proliferate.
Formulation:
Cost tier separation runs deepest here, with water-based systems commanding volume leadership while solvent-based alternatives defend premium positioning.
- Water-Based:Low-VOC dispersions now absorb the majority of commercial production volume. EPA enforcement timelines and landscaper preference for reduced odor and faster drying are compressing solvent-based capacity into residual niche segments.
- Oil-Based:Hydrocarbon carrier systems retain foothold in premium red and gold applications where extended color retention justifies higher per-gallon costs and longer drying windows.
- Solvent-Based:VOC-intensive formulations face accelerating regulatory pressure under 40 CFR 59 and spreading CARB adoption, restricting deployment to exempt industrial or export-oriented production.
- Powder:Dry pigment concentrates serve regional mulch yards with in-house dispersion capabilities, reducing freight costs and enabling custom color matching.
Water-Based generates the steepest expansion trajectory as compliance deadlines force conversion, with Powder gaining share among integrated producers seeking supply chain control.
Application Method:
Equipment bundling patterns differentiate customer segments, with spray systems dominating commercial scale and mix methods persisting in smaller yard operations.
- Spray:Automated conveyor-mounted systems achieve uniform coverage at 0.5–2.0% application rates. Commercial mulch producers in Alabama and South Carolina are standardizing spray infrastructure to meet year-round contract volumes.
- Mix:Batch tumbling methods serve mid-size regional yards with variable product lines and lower capital investment thresholds.
- Dip:Immersion systems retain limited use for specialty bark products requiring complete saturation.
- Coating:Surface film applications address premium segments demanding maximum color intensity and weather resistance.
Spray leads absolute volume throughput, with Mix methods expanding most quickly among second-tier regional producers upgrading from manual application.
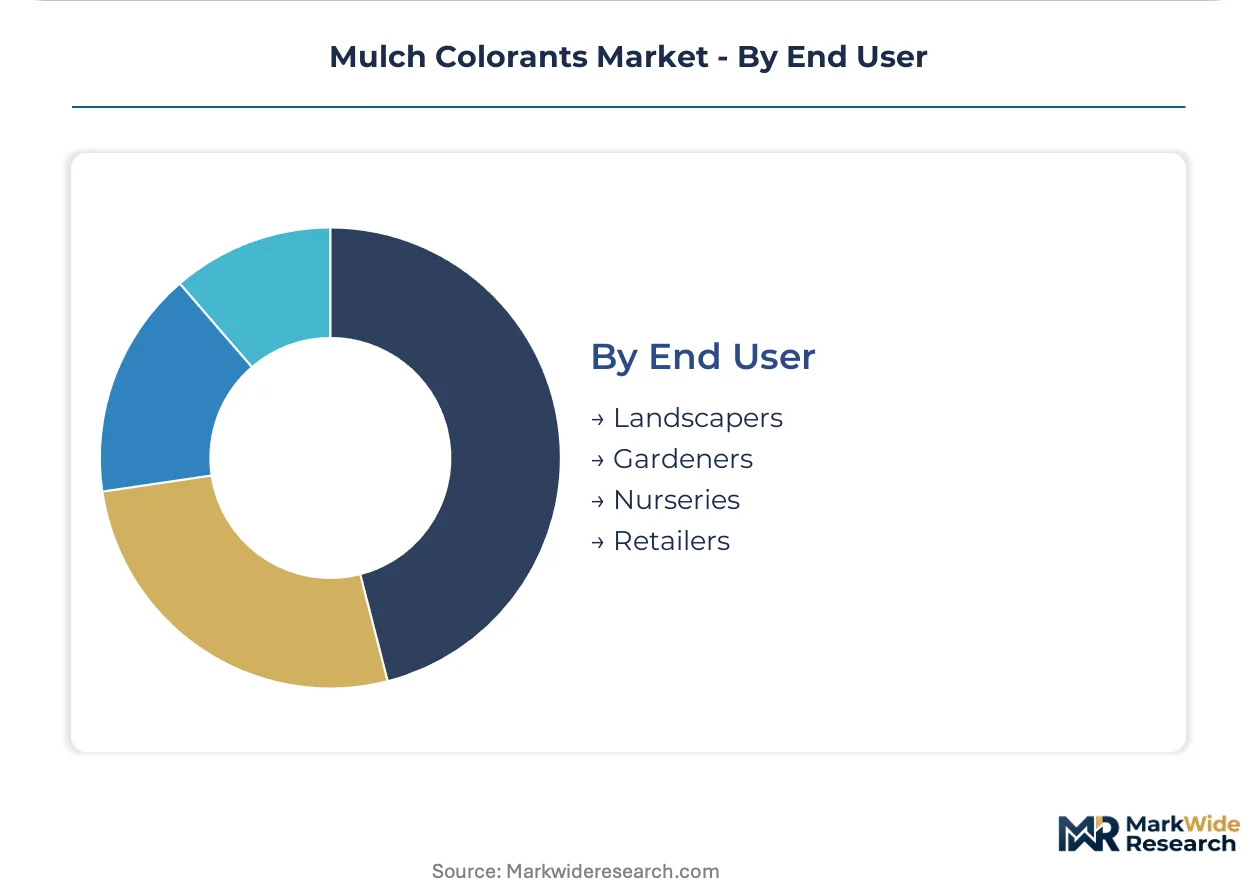
End User:
Procurement authority concentration varies sharply, with landscapers consolidating specification control while retailers remain price-sensitive intermediaries.
- Landscapers:Commercial maintenance contractors in Florida and Texas are consolidating direct procurement relationships with pigment formulators, bypassing traditional distribution. Year-round service contracts sustain bulk purchasing commitments and equipment bundling negotiations.
- Gardeners:Residential DIY purchasers drive smaller-format retail demand, prioritizing convenience and low odor over cost optimization.
- Nurseries:Plant retail operations specify colorant-treated mulch for visual consistency with inventory presentation requirements.
- Retailers:Big-box and garden center chains intermediate volume demand, squeezing margin through private-label sourcing and multi-supplier bidding.
Landscapers anchor volume concentration, with Nurseries gaining share fastest as container-grown plant sales expand visual merchandising requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand for mulch colorants outpaces Canadian consumption by a factor of roughly eight to one, reflecting divergent landscaping season lengths and municipal procurement scales. Subtropical climate zones sustain year-round maintenance cycles that concentrate pigment consumption in specific southern states.
United States
Florida and Georgia municipal contracts specify brown iron oxide colorants for native vegetation alignment, while Texas urban planners accelerate black-dyed mulch adoption for hardscape contrast. EPA 40 CFR 59 VOC enforcement compresses solvent-based formulation timelines across multi-state suppliers. Alabama and South Carolina commercial producers standardize spray application infrastructure to meet sustained contract volumes.
Canada
Ontario and Quebec landscaping contractors concentrate seasonal demand within compressed spring-summer windows, limiting per-acre colorant intensity versus subtropical benchmarks. Health Canada and PMRA regulate pigment environmental release under pesticide-related frameworks, adding compliance layers for cross-border suppliers. British Columbia municipal accounts in Vancouver and Victoria test black colorant specifications for green infrastructure projects.
Germany
REACH registration obligations constrain non-compliant pigment chemistries from market entry, filtering supplier eligibility through ECHA compliance timelines. Bavarian and North Rhine-Westphalia landscaping firms source iron oxide dispersions for commercial maintenance contracts with stricter VOC thresholds than federal German baselines. Stuttgart-area equipment manufacturers develop precision spray systems for European mulch producers.
China
Pigment-grade iron oxide supply concentrates among domestic chemical processors serving export markets, exposing formulators to freight cost volatility and tariff exposure. MIIT and MEE enforce dual carbon goals that redirect capacity investments toward lower-emission production methods. Shandong Peninsula chemical clusters supply raw material feedstock to North American formulators through intermediary traders.
Australia
New South Wales and Victoria municipal landscaping departments specify colorant-treated mulch for drought-resistant green infrastructure programs. TGA-aligned state regulators assess pigment environmental fate under chemical assessment frameworks distinct from North American VOC approaches. Sydney and Melbourne commercial contractors consolidate direct procurement relationships with Asian pigment suppliers, bypassing traditional distribution channels.
Mulch Colorants Market Competitive Landscape
United States producers anchor one tier; German and Swiss chemical specialists hold formulation technology advantages through pigment purity and dispersion expertise. The vendor base separates into three functional layers: multinational chemical conglomerates with integrated pigment portfolios, regional mulch equipment and colorant system integrators, and specialized dispersion technology firms. Consolidation pressure concentrates among mid-scale formulators facing raw material cost volatility and compliance investment burdens. Competitive moves center on backward integration into iron oxide sourcing and direct-to-producer equipment bundling that disintermediates traditional distribution.
Among multinational chemical conglomerates, BASF SE and Sun Chemical Corporation exemplify the integrated pigment portfolio archetype, leveraging global raw material access and dispersion R&D infrastructure. The Sherwin-Williams Company occupies a position bridging industrial coatings expertise with landscaping application requirements. Regional system integrators such as Amerimulch represent the equipment-colorant bundling model, concentrating procurement relationships in southeastern United States production clusters. Specialized dispersion firms including Colorbiotics and Sasco Chemical Group, Inc. sit within technology-focused tiers emphasizing formulation compliance and application efficiency.
| Leading Market Players |
|---|
| BASF SE |
| The Sherwin-Williams Company |
| Amerimulch |
| Sun Chemical Corporation |
| Colorbiotics |
| AgriCoatings |
| Sasco Chemical Group, Inc. |
| Drexel Chemical Company |
| Troy Corporation |
| Others |
Supply & Pricing Matrix
Formulation chemists concentrated in the southeastern United States command wage premiums that widen pricing spreads between premium water-based dispersions and commodity-grade solvent alternatives. Labor-cost differentials between integrated production clusters and distributed mixing operations feed directly into tiered pricing structures across commercial mulch yards.
Pricing Analysis
Capacity additions in Shandong Province are reshaping price floors for pigment-grade iron oxide feedstocks. Three-tier pricing structure across premium, standard, and economy levels separates EPA-compliant water-based formulations from CARB-exempt solvent systems and unregistered import alternatives. Price differentiation stems from certification grade and volume scale, with municipal contractors least sensitive and residential DIY purchasers most responsive to per-gallon fluctuations. Cost compression in mid-tier water-based brown formulations is intensifying because Shandong supply volatility feeds raw material uncertainty.
Supply Chain Analysis
Pigment-grade iron oxide supply rests on Chinese and Indian chemical processors serving North American formulators through intermediary trading networks. Raw material dependencies include iron ore feedstock, sulfuric acid processing inputs, and water-based dispersion polymers. Distribution runs through regional mulch equipment distributors and direct-to-producer relationships in Florida and Georgia production clusters. Tariff exposure on Chinese pigment imports presents structural vulnerability for non-integrated formulators lacking captive supply arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mulch colorant procurement has shifted toward premium water-based specifications as EPA enforcement hardens compliance baselines, positioning quality-focused suppliers for durable margin capture.
For Market Incumbents: Anchor southeastern US production capacity through backward integration into iron oxide sourcing to defend against Shandong supply volatility. Secure CARB-compliant formulation registrations ahead of state-level threshold adoption spreading beyond California. Prioritize enclosed mixing system investments to satisfy OSHA workplace exposure protocols at commercial facilities. For New Entrants and Emerging Players: Direct-to-producer digital procurement platforms offer the lowest-friction entry path for regional mulch yards disintermediating traditional distribution. Target Ohio and Illinois municipal accounts showing underpenetrated colorant adoption versus saturated southeastern benchmarks. Lead with equipment-colorant bundling packages that reduce distributor markup capture. For Investors and Strategic Acquirers: Chemical conglomerates with integrated pigment portfolios are the most active acquirer in this space, seeking dispersion technology capabilities. Mid-scale formulators facing REACH registration burdens and raw material cost volatility present consolidation targets. Watch EPA state-level CARB adoption timelines as the critical inflection signal for water-based formulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Iron Oxide Sourcing | Captive supply from Shandong processors insulates margin structures against tariff volatility. |
| CARB-Compliant Formulation Registration | California thresholds spreading to Texas and Florida municipalities create first-mover compliance advantage. |
| Direct-to-Producer Equipment Bundling | Integrated colorant-spray system packages disintermediate traditional distributor markup layers. |
| Enclosed Mixing System Deployment | OSHA workplace exposure compliance enables commercial facility certification for municipal contracts. |
| UV-Stable Organic Pigment R&D | Hybrid carbon black-azo formulations address colorfastness gaps in water-based regulatory-compliant systems. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with mulch production plant managers, municipal procurement officers, landscaping contractor operations leads, and pigment formulator technical directors with secondary validation against EPA 40 CFR 59 regulatory filings, customs trade data on iron oxide imports, and SEC disclosures from chemical conglomerates. Bottom-up volume estimates from regional production clusters were triangulated against top-down pigment consumption models.
Historical reference periods anchored demand trajectories to subtropical climate zone maintenance cycles and EPA enforcement phase-in timelines across the projection horizon. Segmentation dimensions modeled include color type, formulation chemistry, application method, and end-user procurement authority. CAGRs were derived from regression analysis of pigment intensity per acre against landscaping contract volumes. Forecast inputs incorporated REACH registration timelines and state-level CARB threshold adoption patterns.
The model assumes a particular technology adoption path; alternative pathways for solvent-to-water-based formulation conversion would alter the outlook. Forecasts reflect assumptions about EPA enforcement consistency and Shandong supply stability. A small set of named triggers—CARB threshold geographic spread, iron oxide tariff adjustments, and OSHA workplace rule updates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Titanium Dioxide Pigment Market
Dyes and Pigments
Carmine Market
Dyes and Pigments
Algal Pigments Market
Dyes and Pigments
North America Hair Colorants Market
Dyes and Pigments
High Performance Pigments Market
Dyes and Pigments
Colorants Market
Dyes and Pigments
Thermochromic Labels Market
Dyes and Pigments
Acid Stable Blue Market
Dyes and Pigments
White Pigment Market
Dyes and Pigments
Chlorophyll Color Market
Dyes and Pigments
Resin Pigments Market
Dyes and Pigments
Europe Natural Dyes and Pigments Market
Dyes and Pigments
Cadmium Pigments Market
Dyes and Pigments
Inorganic Color Pigments Market
Dyes and Pigments
Natural Colorants Market
Dyes and Pigments
Global Organic Pigments Market