
 Global Multi Cloud Management Market | 2026-2036
Global Multi Cloud Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Multi Cloud Management Market Foresight
Buyer concentration among large enterprises is hardening as Fortune 500 firms consolidate vendor relationships around integrated management stacks. Microsoft Corp leverages its Azure Arc platform to extend control across rival cloud environments, while IBM Corporation anchors its hybrid cloud strategy through Red Hat OpenShift integrations. VMware Inc competes with a specialized focus on infrastructure abstraction and cross-cloud workload portability.
Multi cloud management encompasses the orchestration, governance, and optimization of workloads distributed across two or more cloud service providers through centralized policy engines and API abstraction layers. These platforms enforce cost allocation rules, security posture consistency, and compliance validation across heterogeneous environments including AWS, Azure, Google Cloud, and private data centers. Hybrid cloud deployment configurations currently dominate enterprise adoption due to data residency requirements and legacy system interdependencies. Security management solutions within the solution type segment command premium positioning as regulatory scrutiny intensifies across jurisdictions. Banking institutions among end users represent the fastest-growing demand pool as financial services regulators mandate operational resilience and audit trail completeness across distributed infrastructure.
The EU AI Act and GDPR impose strict data governance and algorithmic transparency mandates that multi-cloud management platforms must embed by design. The US SEC cybersecurity disclosure rules and HIPAA requirements for healthcare data similarly shape product roadmaps and procurement criteria for vendors serving regulated industries. NIST cloud security frameworks and ISO 27017 standards further define baseline compliance architectures that buyers evaluate during vendor selection processes. Stakeholders must monitor how sovereign cloud requirements in the European Union, India, and China fragment standardization efforts and create compliance complexity that specialized governance vendors can exploit.
Market Dynamics
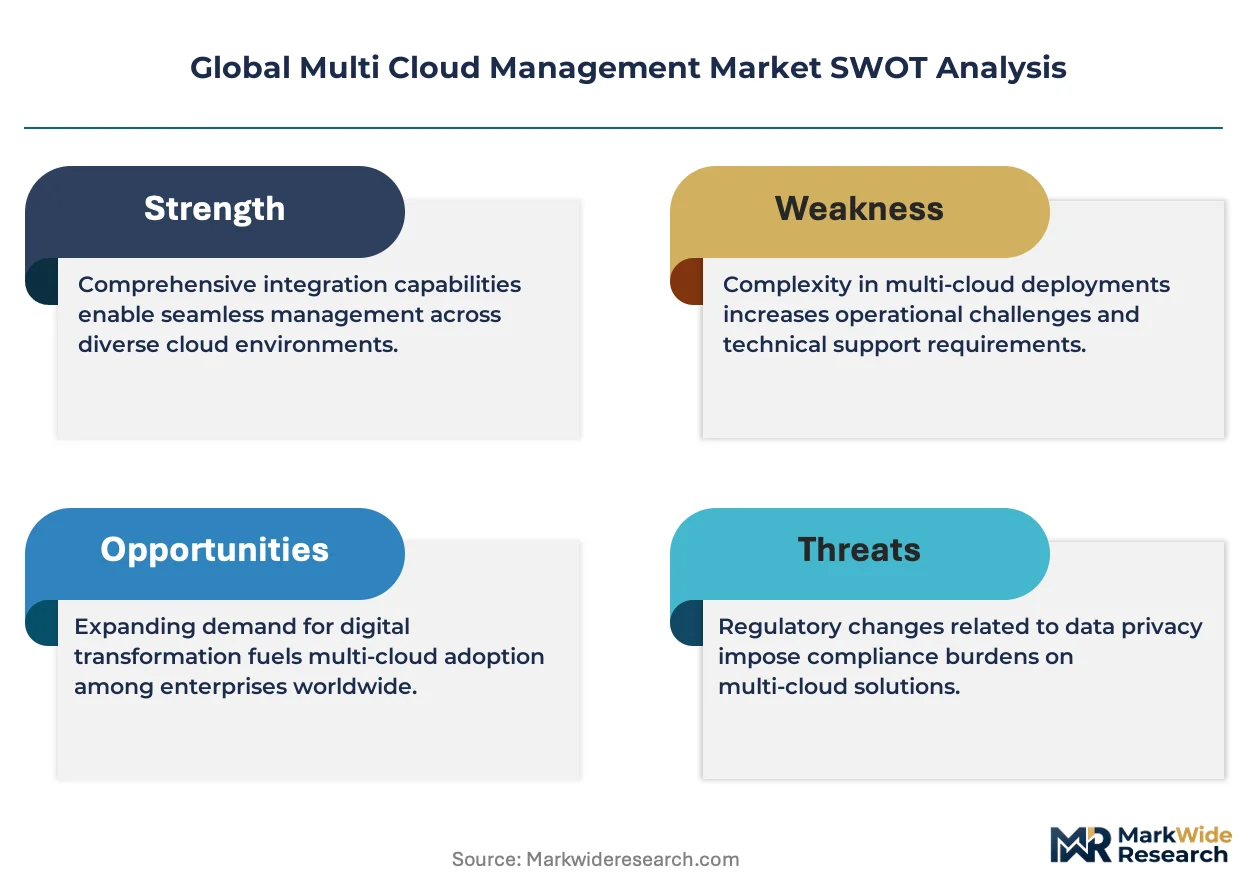
Enterprise workload fragmentation across hyperscaler environments is forcing centralized governance architectures that reconcile policy enforcement with operational autonomy. The EU AI Act mandates algorithmic transparency and audit trail completeness, compelling vendors to embed compliance validation into orchestration layers rather than retrofitting controls.
Growth Catalysts
- EU AI Act mandates:Financial services regulators in the European Union require operational resilience documentation across distributed infrastructure, driving banking institutions toward unified governance platforms that automate compliance validation.
- Hybrid cloud deployment models:Data residency requirements and legacy system interdependencies push enterprises to maintain on-premise workloads alongside public cloud resources, creating demand for abstraction layers that normalize management interfaces.
- API standardization:Kubernetes and container orchestration protocols enable workload portability across AWS, Azure, and Google Cloud environments, reducing vendor lock-in friction and accelerating platform adoption among risk-averse procurement teams.
Market Restraints
- Specialized talent scarcity:Multi-cloud architecture expertise commands premium compensation, constraining implementation velocity for mid-market enterprises unable to match Fortune 500 recruitment budgets.
- Hyperscaler API volatility:Amazon Web Services and Microsoft Azure modify service endpoints with limited deprecation windows, forcing management platform vendors into continuous integration cycles that inflate R&D overhead.
- Sovereign cloud fragmentation:India's data localization requirements and China's cybersecurity review processes fragment standardization efforts, compelling vendors to maintain jurisdiction-specific compliance modules that dilute engineering focus.
Strategic Opportunities
- SME governance automation:Small and medium enterprises in Germany and France remain underserved by enterprise-focused pricing models, creating whitespace for consumption-based platforms that abstract complexity through pre-configured policy templates.
- Healthcare HIPAA expansion:The US Department of Health and Human Services is tightening breach notification timelines, driving healthcare providers toward automated security posture management that spans clinical and administrative cloud workloads.
- FinOps convergence:The integration of cloud cost optimization with carbon accounting tools addresses CSRD disclosure requirements, enabling vendors to capture sustainability procurement budgets alongside traditional IT governance spend.
Industry Challenges
- Cross-functional skill gaps:Platform engineering teams must simultaneously master infrastructure-as-code, regulatory interpretation, and financial operations, creating recruitment bottlenecks that delay implementation timelines.
- Legacy system entanglement:Mainframe and client-server applications in banking and insurance sectors resist containerization, forcing hybrid architectures that complicate orchestration layer design and expand integration testing scope.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Multi Cloud Management Market |
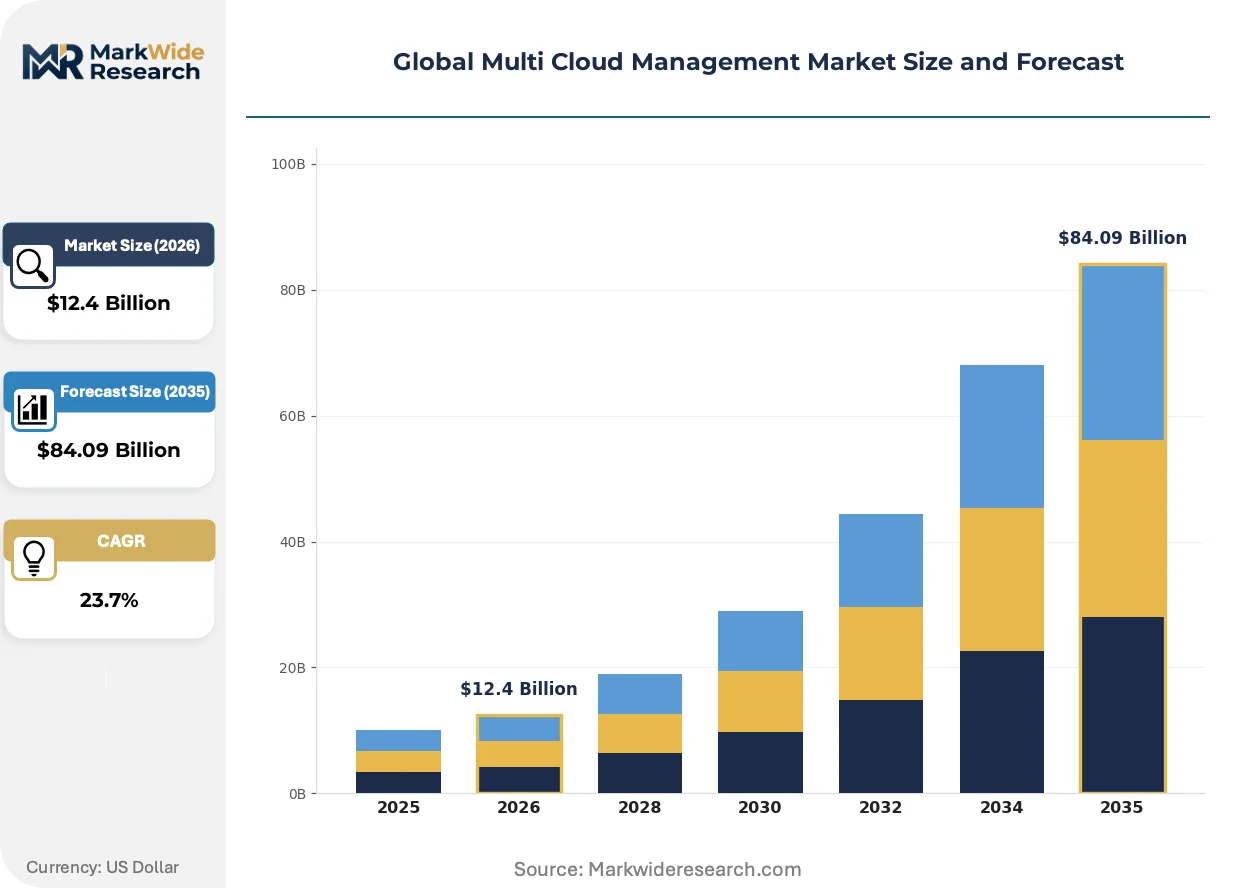
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $84.09 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution Type: Cost Optimization, Security Management, Governance, Automation, Compliance Management Application: Disaster Recovery, Data Analytics, SaaS Management, API Management, Workflow Automation End User: Telecommunications, Banking Institutions, Technology Vendors, Manufacturing Firms, Educational Establishments |
| Companies Covered | VMware Inc, Microsoft Corp, IBM Corporation, Cisco Systems Inc, Dell Technologies Inc, CloudBolt Software Inc, Flexera Software LLC, CoreStack, Accenture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Multi Cloud Management Market Shifts & Advancements
Artificial intelligence is embedding autonomous remediation capabilities into orchestration platforms, compressing incident response timelines from hours to minutes. This shift demands re-architected control planes that separate policy decision logic from execution engines.
Kubernetes-native service meshes are integrating zero-trust security primitives directly into workload orchestration, eliminating the operational friction of standalone network security appliances. Banking institutions in Singapore and Switzerland are deploying these architectures for real-time payment processing environments. The technology is integrating compliance validation into continuous deployment pipelines, collapsing the traditional gap between security review and production release.
The EU AI Act's risk classification framework is compelling vendors to implement algorithmic impact assessment workflows within management consoles. Healthcare and financial services deployments in France and Germany now require documented conformity evaluation before production deployment. High-risk AI workloads must maintain immutable audit trails across cloud boundaries, driving demand for distributed ledger integration in governance platforms.
Enterprise buyers are consolidating vendor relationships around integrated FinOps and SecOps stacks, displacing point solutions that addressed single pain points. Procurement teams in the United States now evaluate total cost of ownership across three-year horizons rather than annual licensing fees. This behavioral shift favors platform vendors with native cost attribution and carbon accounting capabilities, particularly among manufacturing enterprises subject to SEC climate disclosure rules.
Global Multi Cloud Management Market Segmentation
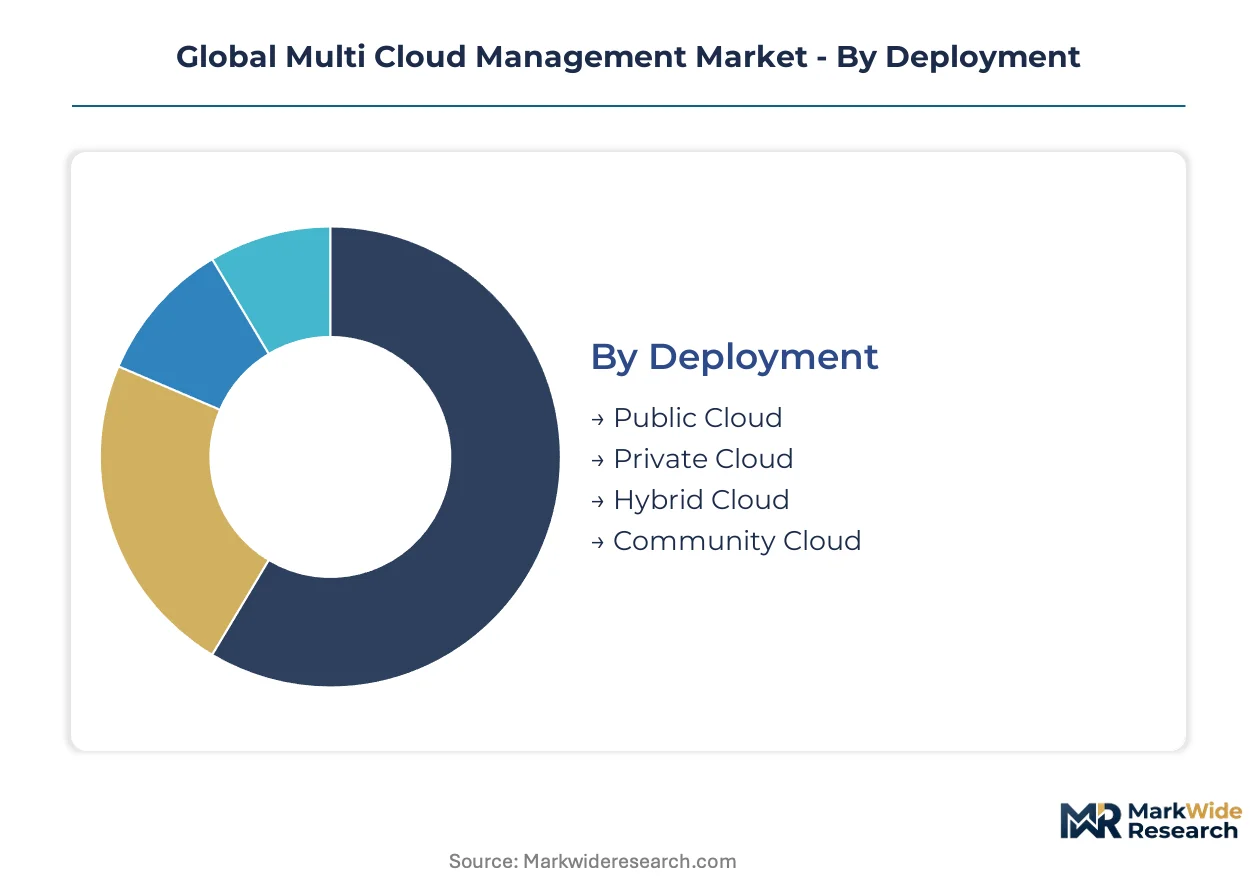
Multi-cloud management platforms must address heterogeneous infrastructure requirements across deployment modes, regulatory regimes, and workload types. Segmentation reveals where engineering investment concentrates and which buyer profiles command premium pricing.
Deployment:
Standardization dominates public cloud deployments while private and community configurations demand extensive customization to accommodate legacy system interdependencies and data residency mandates.
- Public Cloud:Workloads run on shared infrastructure operated by hyperscalers including AWS, Azure, and Google Cloud. Banking institutions in Singapore and Germany deploy these environments for customer-facing applications where latency optimization outweighs sovereignty concerns.
- Private Cloud:Dedicated infrastructure provisioned for single-tenant use, often maintained on-premise or through hosted arrangements. Swiss pharmaceutical manufacturers and French defense contractors favor this model to satisfy ANSM and national security audit requirements.
- Hybrid Cloud:Combines public and private resources with orchestration layers normalizing management interfaces. Japanese automotive suppliers and US healthcare networks leverage this architecture to retain sensitive data on-premise while bursting compute to public clouds.
- Community Cloud:Shared infrastructure serving organizations with common compliance obligations or sector-specific standards. German automotive OEMs and their tier-one suppliers operate these environments to harmonize ISO 27001 certification across supplier networks.
Leading the category by volume: Hybrid Cloud. Expanding most quickly: Community Cloud configurations among sector consortiums.
Solution Type:
Cost-focused modules compete on automation depth while security and governance solutions differentiate through embedded regulatory logic and audit trail completeness.
- Cost Optimization:FinOps platforms attribute cloud spend to business units, projects, and carbon emissions for CSRD disclosure. Manufacturing enterprises in the United States and Germany deploy these tools to reconcile operational budgets with sustainability procurement mandates.
- Security Management:Zero-trust architectures and continuous compliance monitoring protect distributed workloads. HIPAA-covered entities and EU AI Act-regulated financial services firms command premium positioning for solutions with immutable audit logging.
- Governance:Policy engines enforce tagging standards, access controls, and resource provisioning rules across cloud boundaries. Mid-market enterprises in France and Italy adopt these modules to centralize oversight without dedicated platform engineering teams.
- Automation:Infrastructure-as-code pipelines and self-healing orchestration reduce manual intervention. Technology vendors in India and Israel leverage these capabilities to accelerate release cycles for competitive software products.
- Compliance Management:Automated validation against GDPR, HIPAA, and sector-specific frameworks. Healthcare providers in the United States and pharmaceutical manufacturers in Switzerland prioritize these solutions as breach notification timelines tighten.
Dominant by procurement volume: Security Management. Steepest expansion trajectory: Compliance Management driven by regulatory deadline clustering.
Application:
Operational continuity applications command highest urgency while data-intensive workloads drive capacity planning and inter-cloud data transfer economics.
- Disaster Recovery:Cross-cloud replication and automated failover protect against regional outages and ransomware events. Banking institutions in Singapore and Switzerland deploy these architectures for real-time payment system resilience.
- Data Analytics:Federated query engines and data mesh architectures normalize access across siloed repositories. Retail conglomerates in the United States and Germany consolidate customer insights without centralizing sensitive records.
- SaaS Management:Discovery, license optimization, and security posture monitoring for cloud application portfolios. Educational establishments in the United Kingdom and Australia adopt these tools to govern proliferating departmental software subscriptions.
- API Management:Gateway federation, rate limiting, and developer portal consolidation across cloud providers. Telecommunications operators in South Korea and Japan leverage these capabilities for 5G service orchestration.
- Workflow Automation:Cross-cloud business process orchestration integrating SaaS, PaaS, and legacy systems. Insurance carriers in Germany and the United States automate claims processing spanning mainframe and cloud-native components.
Highest deployment incidence: Disaster Recovery. Gaining share fastest: Data Analytics fueled by AI training pipeline proliferation.
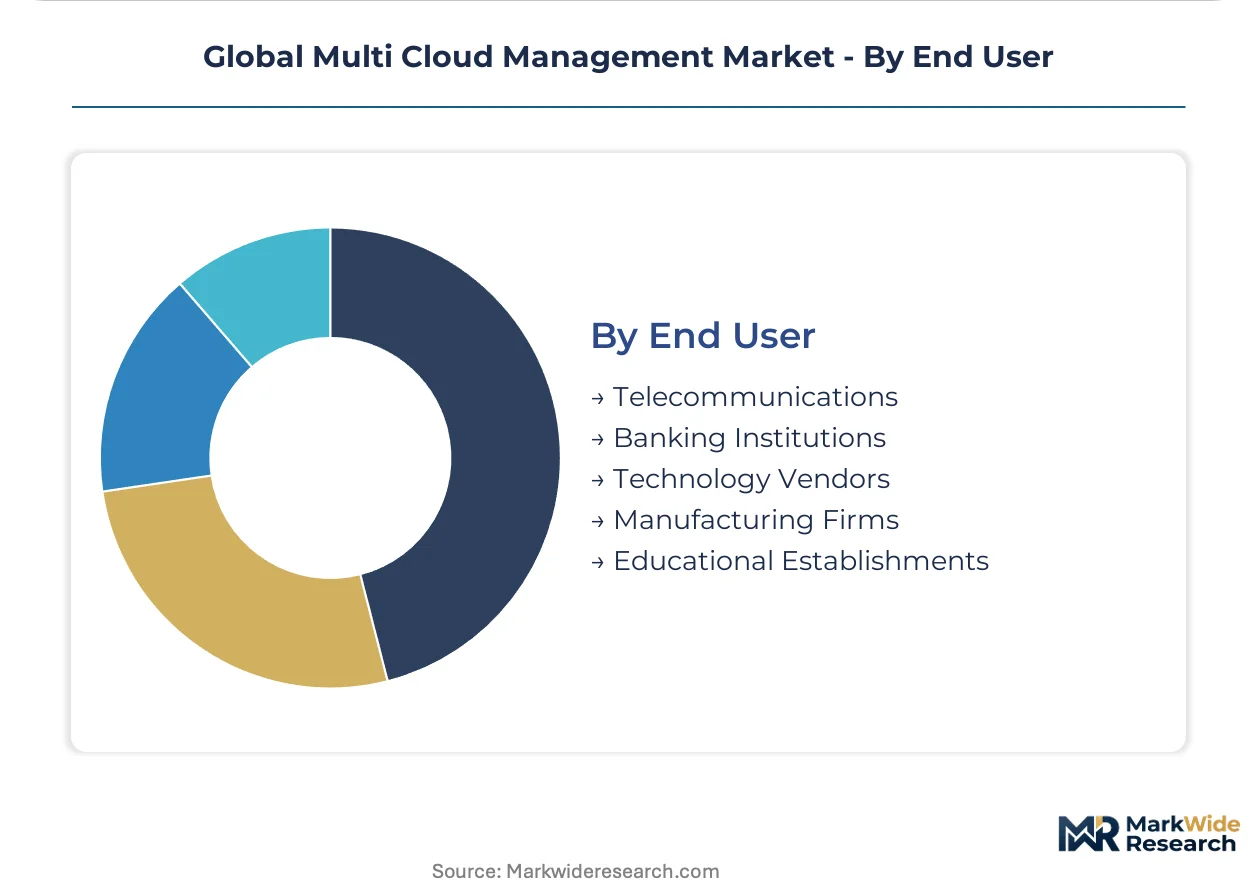
End User:
Regulated industries absorb implementation complexity for compliance assurance while technology vendors and manufacturers prioritize standardization and cost predictability.
- Banking Institutions:Operational resilience mandates from ECB, MAS, and OCC drive unified governance platform adoption. French and German banks lead European procurement for EU AI Act-compliant orchestration layers.
- Telecommunications:5G network slicing and edge computing deployments require multi-cloud orchestration for latency-sensitive workloads. Operators in South Korea, Japan, and the United States anchor regional demand concentration.
- Technology Vendors:SaaS providers and independent software vendors manage development and production environments across hyperscalers for redundancy and customer choice. Israeli and Indian software exporters represent high-volume adopters.
- Manufacturing Firms:Smart factory initiatives and supply chain digitization create distributed workload patterns. German automotive and industrial equipment manufacturers integrate these platforms with existing MES and ERP investments.
- Educational Establishments:Research computing, administrative systems, and learning management platforms span cloud environments. Australian and Canadian universities consolidate vendor relationships to simplify procurement compliance.
Category leader by spend: Banking Institutions. Climbing the fastest: Manufacturing Firms as operational technology-cloud convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States enterprises command the largest procurement budgets for multi-cloud governance platforms, with Fortune 500 consolidation driving vendor relationship rationalization toward integrated stacks. Banking institutions in New York and San Francisco anchor hyperscaler consumption, while healthcare networks in Boston and Chicago navigate HIPAA disclosure tightening.
United States
SEC cybersecurity disclosure rules and healthcare breach notification mandates from HHS propel procurement of automated compliance validation tools. Financial services firms in Manhattan and asset managers in Greenwich deploy unified governance platforms to satisfy OCC operational resilience requirements. Silicon Valley technology vendors integrate FinOps modules to capture sustainability procurement budgets alongside traditional IT spend.
Germany
Automotive OEMs and their tier-one suppliers in Stuttgart and Munich operate community cloud configurations to harmonize ISO 27001 certification across supplier networks. The EU AI Act risk classification framework compels vendors to embed algorithmic impact assessment workflows within management consoles. Manufacturing enterprises in Bavaria consolidate vendor relationships around integrated cost attribution and carbon accounting capabilities.
United Kingdom
Educational establishments in London and Edinburgh adopt SaaS management tools to govern proliferating departmental software subscriptions. Financial services regulators mandate operational resilience documentation across distributed infrastructure, driving banking institutions toward unified governance platforms. Telecommunications operators anchor regional demand concentration for API management capabilities serving 5G service orchestration.
Singapore
Banking institutions deploy disaster recovery architectures for real-time payment system resilience, with MAS operational mandates driving cross-cloud replication investments. Technology vendors manage development and production environments across hyperscalers for redundancy and customer choice. The city-state's financial services cluster commands premium positioning for solutions with immutable audit logging.
Japan
Automotive suppliers in Nagoya and healthcare networks in Tokyo leverage hybrid architectures to retain sensitive data on-premise while bursting compute to public clouds. METI industrial digitization programs accelerate smart factory initiatives creating distributed workload patterns. Telecommunications operators in Osaka require multi-cloud orchestration for latency-sensitive 5G network slicing deployments.
Global Multi Cloud Management Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue consumption-based pricing models for mid-market penetration. The vendor base stratifies across three functional tiers: hyperscaler-agnostic abstraction specialists, integrated platform consolidators, and compliance-focused governance module providers. Dominant competitive moves include strategic partnerships with system integrators and portfolio diversification into FinOps-SecOps convergence offerings.
Among hyperscaler-agnostic specialists, VMware Inc exemplifies infrastructure abstraction and cross-cloud workload portability positioning. Microsoft Corp occupies the integrated platform tier through Azure Arc extension across rival cloud environments. IBM Corporation anchors the hybrid cloud consolidation vector through Red Hat OpenShift integrations, representing the enterprise incumbent archetype that bundles legacy system interoperability with container orchestration capabilities.
| Leading Market Players |
|---|
| VMware Inc |
| Microsoft Corp |
| IBM Corporation |
| Cisco Systems Inc |
| Dell Technologies Inc |
| CloudBolt Software Inc |
| Flexera Software LLC |
| CoreStack |
| Accenture |
| Others |
Supply & Pricing Matrix
Platform engineering talent costs cascade through multi-cloud management pricing tiers, with Fortune 500 procurement budgets absorbing premium rates while mid-market buyers face compressed implementation timelines. This input cost polarization separates subscription tiers serving enterprise governance stacks from consumption-based models targeting underserved SMEs in France and Germany.
Pricing Analysis
Volume concentrates in enterprise SaaS subscriptions with annual commitments exceeding six figures, while margins compress in consumption-based tiers targeting mid-market adoption. Pricing stratifies across premium, standard, and economy tiers based on compliance module depth and API call volume thresholds. Cost compression in standard tiers is intensifying because hyperscaler-agnostic abstraction vendors compete on implementation velocity. Mid-market enterprises in Italy and Spain exhibit highest price sensitivity, whereas banking institutions in Singapore and Switzerland accept premium positioning for immutable audit logging capabilities.
Supply Chain Analysis
Logistics and freight costs remain minimal for software delivery, yet data residency requirements force infrastructure provisioning across distributed geographies. Engineering talent supply concentrates in India, Israel, and the United States, with specialized platform architects commanding compensation premiums that feed into vendor R&D overhead. Raw material dependencies center on compute infrastructure from Taiwan and South Korea, plus proprietary orchestration frameworks from dominant hyperscalers. Single-source vulnerability around Kubernetes distribution channels creates supply chain concentration risk. Distribution runs through direct enterprise sales teams and hyperscaler marketplace integrations, with system integrators anchoring mid-market penetration in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-cloud governance platform supply is constraining around certified platform engineering talent, with EU AI Act compliance expertise propping pricing power for vendors with embedded regulatory logic. This bottleneck justifies premium positioning for incumbents with pre-validated audit trail architectures.
For Market Incumbents: Acquire compliance automation modules to fortify against emerging entrants pursuing consumption-based pricing. Consolidate vendor relationships around integrated FinOps-SecOps stacks before point solutions capture mid-market share in France and Italy. Capacity addition in Singapore and Switzerland reinforces banking sector dominance as MAS and FINMA operational resilience mandates tighten. Certification investment in EU AI Act risk classification workflows creates switching costs that protect recurring revenue streams. For New Entrants and Emerging Players: Enter via SME governance automation in Germany and France, where enterprise-focused pricing models leave whitespace for pre-configured policy templates. Target healthcare providers in the United States facing HIPAA breach notification timeline compression with automated security posture management. Community cloud configurations among German automotive OEM supplier networks offer the most penetrable segment. Consumption-based pricing with rapid time-to-value demonstrations anchors go-to-market positioning against incumbent complexity. For Investors and Strategic Acquirers: Distressed-cycle entries favor compliance-focused governance module providers in the European Union with EU AI Act-validated workflows. Long-term viability across a five-to-ten year window hinges on sovereign cloud fragmentation creating durable demand for jurisdiction-specific compliance architectures. Acquisition targets should demonstrate embedded regulatory logic rather than retrofit control capabilities. Watch for hyperscaler API volatility forcing continuous integration overhead that strains vendor R&D economics as an inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure Arc extension across AWS and Google Cloud environments captures enterprise procurement consolidation. |
| Acquisition of Specialist Firm | FinOps module vendors with carbon accounting capabilities address CSRD disclosure requirements in Germany. |
| Strategic Partnership | System integrator alliances accelerate mid-market penetration in France and Italy without direct sales expansion. |
| Product Launch | Kubernetes-native service meshes with zero-trust primitives target Singapore banking real-time payment resilience. |
| Geographic Expansion | Sovereign cloud compliance modules for India's data localization capture fragmented standardization premiums. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this multi-cloud management market assessment. Primary interviews with platform engineering directors, IT procurement officers at Fortune 500 firms, compliance officers in banking and healthcare, channel partners, and system integrators validated demand patterns. Secondary sources encompassed SEC cybersecurity disclosure filings, EU AI Act implementation guidance, NIST cloud security framework documentation, and hyperscaler capex disclosures. Bottom-up modeling of vendor revenue streams triangulated against top-down enterprise IT spend allocation surveys.
Segmentation-level granularity modeled deployment modes, solution types, applications, and end-user industries across the projection horizon. Organization size and vertical regulatory intensity provided additional analytical dimensions. CAGRs derived from historical adoption curve analysis and policy mandate deadline clustering. Forecast inputs incorporated EU AI Act implementation timelines, HIPAA breach notification rule revisions, and sovereign cloud requirement proliferation across India and China.
Revisions become necessary when hyperscaler API deprecation cycles accelerate, EU AI Act enforcement intensifies beyond current guidance, or platform engineering talent availability shifts dramatically. Forecasts reflect documented assumptions about regulatory deadline adherence and enterprise procurement consolidation velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Israel Cloud Computing Market
Cloud Computing
Hybrid Cloud Computing Market
Cloud Computing
Cloud IT Service Management (ITSM) Market
Cloud Computing
China Cloud Computing Market
Cloud Computing
Brazil Cloud Computing Market
Cloud Computing
Cloud-Based Repository Services Market
Cloud Computing
Japan Cloud Computing Market
Cloud Computing
Latin America Cloud Computing Market
Cloud Computing
Multi-Cloud Optimization Tools Market
Cloud Computing
Global Cloud-Native Software Market
Cloud Computing
Cognitive Cloud Market
Cloud Computing
Cloud Based Backup Services Market
Cloud Computing
South Korea Cloud Computing Market
Cloud Computing
Global Cloud Collaboration Market
Cloud Computing
Saudi Arabia Cloud Computing Market
Cloud Computing
Asia-Pacific Marketing Cloud Platform Market