
 Telecom Cloud Market | 2026-2036
Telecom Cloud Market Size, Share, and Industry Trends Forecast 2026-2036
Telecom Cloud Market Intelligence
Hyperscaler data center buildouts in Northern Virginia are expanding faster than any other telecom infrastructure category worldwide. Amazon Web Services leverages its global fiber backbone to dominate wholesale cloud connectivity for carriers. Microsoft sustains deep integration with enterprise voice and collaboration stacks, anchoring its position in SaaS-layer telecom services. Google competes aggressively on AI-optimized networking silicon, differentiating its cloud through custom TPU-based packet processing.
Telecom Cloud denotes virtualized compute, storage, and network resources delivered via distributed data centers to enable elastic provisioning of telecommunications workloads including IMS cores, policy control, and subscriber databases. These platforms rely on container orchestration atop commodity servers, with latency budgets typically sub-10 milliseconds for edge-native functions and throughput scaling to terabits per second via SDN-controlled backbones. Public Cloud deployments capture the largest revenue pool among deployment models as tier-one carriers offload non-core workloads, while Network Functions Virtualization within the service type dimension represents the fastest structural expansion as 5G standalone cores mandate cloud-native replacements of legacy hardware. Hybrid Cloud architectures concentrate margin pools through bespoke orchestration layers that bridge on-premises telco edge with hyperscaler central cloud.
FCC net neutrality rulings in the United States, combined with GDPR data-localization mandates enforced by European national regulators, and MIIT cloud security assessments in China, collectively fragment architectural standards and force multi-region compliance engineering into every platform design. The EU AI Act adds algorithmic transparency obligations for automated network optimization tools, further complicating product roadmaps. Stakeholders must monitor evolving spectrum auction terms tied to cloud infrastructure commitments, as regulators increasingly condition 5G and 6G licenses on demonstrable virtualization progress rather than hardware procurement alone.
Market Dynamics
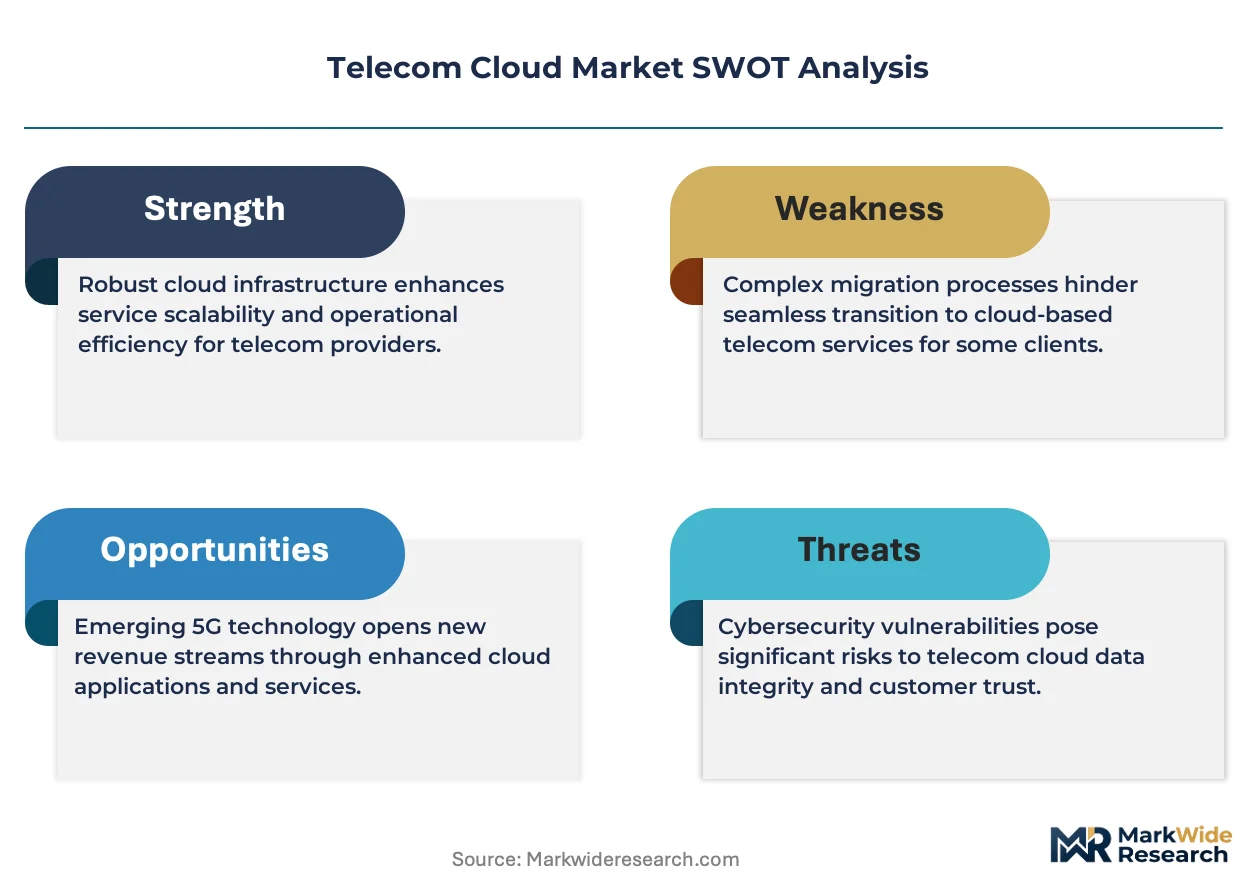
5G standalone core mandates are forcing wholesale replacement of legacy hardware with cloud-native network functions, compressing carrier infrastructure refresh cycles from decade-long horizons to three-year modernization sprints.
Growth Catalysts
- EU AI Act compliance:Algorithmic transparency obligations for automated network optimization tools are accelerating carrier investment in explainable AI infrastructure and audit-ready cloud architectures.
- Edge-native latency requirements:Sub-10 millisecond processing budgets for IMS cores and policy control functions are pulling compute resources toward distributed metro data centers.
- Brazil's 5G spectrum conditions:ANATEL licensing terms tie 5G authorizations to demonstrable virtualization progress, mandating cloud-native core deployments as license prerequisites.
Market Restraints
- GDPR data-localization friction:European national regulators enforce strict territorial data processing requirements that fragment platform architectures and multiply compliance engineering costs.
- Hyperscaler supply concentration:Wholesale cloud connectivity for carriers concentrates in Northern Virginia data center clusters, creating single-region dependency risk for global network resilience.
- NFV orchestration complexity:Container orchestration atop commodity servers introduces performance unpredictability that hardware-based network functions previously eliminated.
Strategic Opportunities
- Germany's core network modernization:Deutsche Telekom and Vodafone Germany are offloading non-core workloads to public cloud, opening multi-year migration contracts for hybrid orchestration providers.
- AI-optimized networking silicon convergence:Custom TPU-based packet processing integrated with SDN-controlled backbones enables terabit-scale throughput with programmable latency profiles.
- Japan's enterprise voice stack integration:Deep Microsoft Teams and Zoom Phone penetration creates attach opportunities for SaaS-layer telecom services bundled with cloud connectivity.
Industry Challenges
- Cloud-native skill scarcity:Container orchestration, Kubernetes networking, and microservices architecture expertise remains concentrated among hyperscaler engineering teams, constraining carrier hiring pipelines.
- MIIT security assessment timelines:China's multi-stage cloud security certification process extends product launch windows by 12-18 months for foreign platform vendors.
- Legacy billing integration friction:Subscriber database migration from on-premises Oracle and SAP systems to cloud-native replacements requires custom middleware development that strains IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecom Cloud Market |
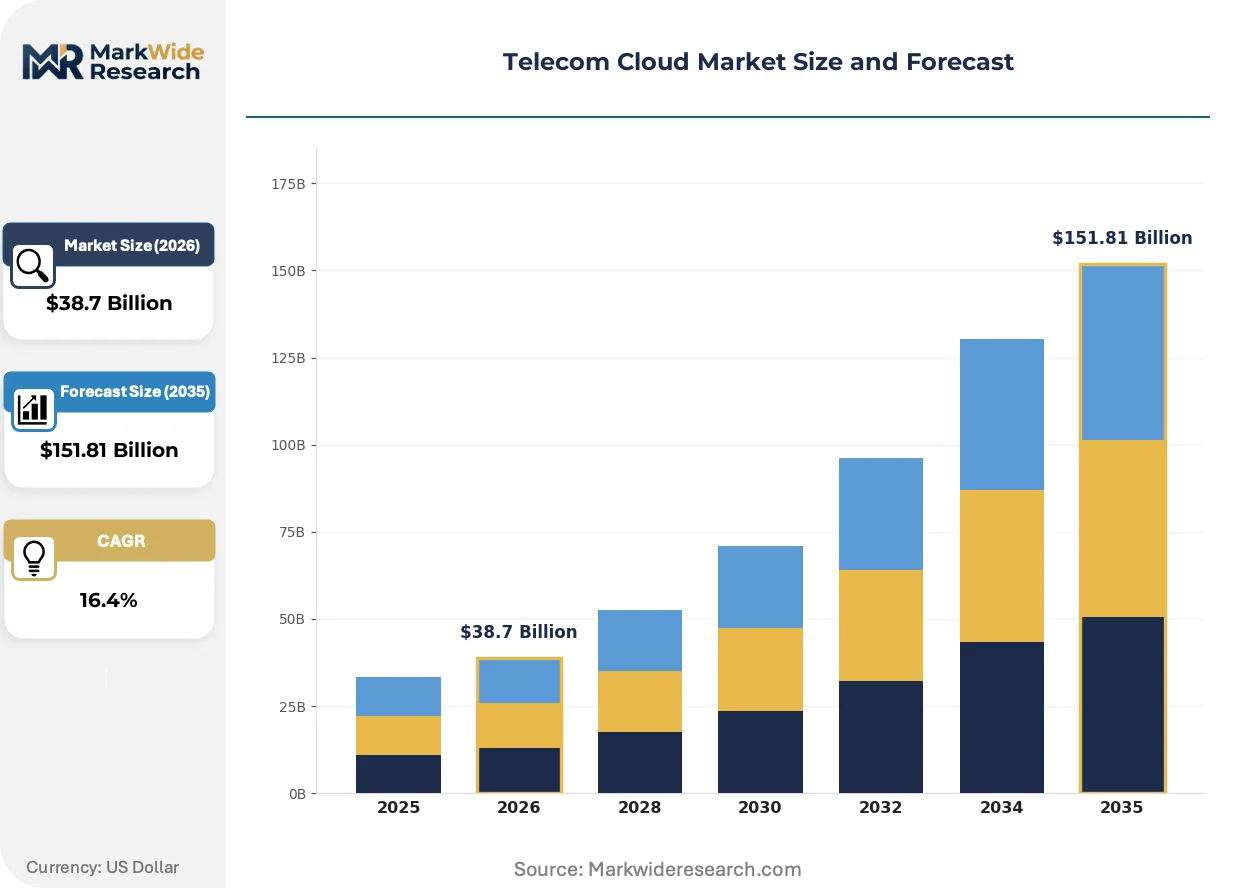
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: IaaS, PaaS, SaaS, Network Functions Virtualization End User: Telecom Operators, Enterprises, Managed Service Providers, System Integrators Technology: SDN, NFV, VoIP, CDN |
| Companies Covered | Amazon Web Services, Microsoft, Google, AT&T Inc., Verizon Communications Inc., IBM, Cisco Systems Inc., Telefonaktiebolaget LM Ericsson, Broadcom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecom Cloud Market Strategic Shifts & Innovations
Distributed compute architectures are fragmenting the traditional centralized cloud model, with carrier edge deployments and hyperscaler central pools forming a two-tier topology that redefines latency engineering and cost allocation.
Containerized network functions are decentralizing telecommunications workload placement across metro edge clusters and regional hyperscaler zones. Tier-one carriers in Germany and Japan are deploying these microservices-based architectures at scale, replacing monolithic virtual machines with Kubernetes-orchestrated service meshes. This topology is decentralizing traffic engineering decisions from core backbone routers to software-defined edge controllers, compressing fault isolation domains from network-wide to zone-specific.
The EU AI Act is imposing algorithmic transparency mandates on automated network optimization tools used for predictive capacity planning and dynamic routing. European national regulators now require documented decision trails for AI-driven traffic management systems, forcing vendors to retrofit explainability layers into black-box machine learning models. NFV orchestration platforms serving EU carriers are most affected, with engineering teams rearchitecting control planes to satisfy audit requirements.
Carrier procurement patterns are fragmenting from single-vendor integrated stacks to multi-cloud workload distribution with bespoke orchestration layers. Wholesale cloud connectivity contracts now span three or more hyperscalers per carrier, with traffic steering based on real-time price and performance arbitrage. This behavior is most visible in Brazil, where Claro, TIM, and Vivo are negotiating parallel AWS, Azure, and Google Cloud agreements to satisfy ANATEL's infrastructure diversification expectations.
Telecom Cloud Market Segmentation
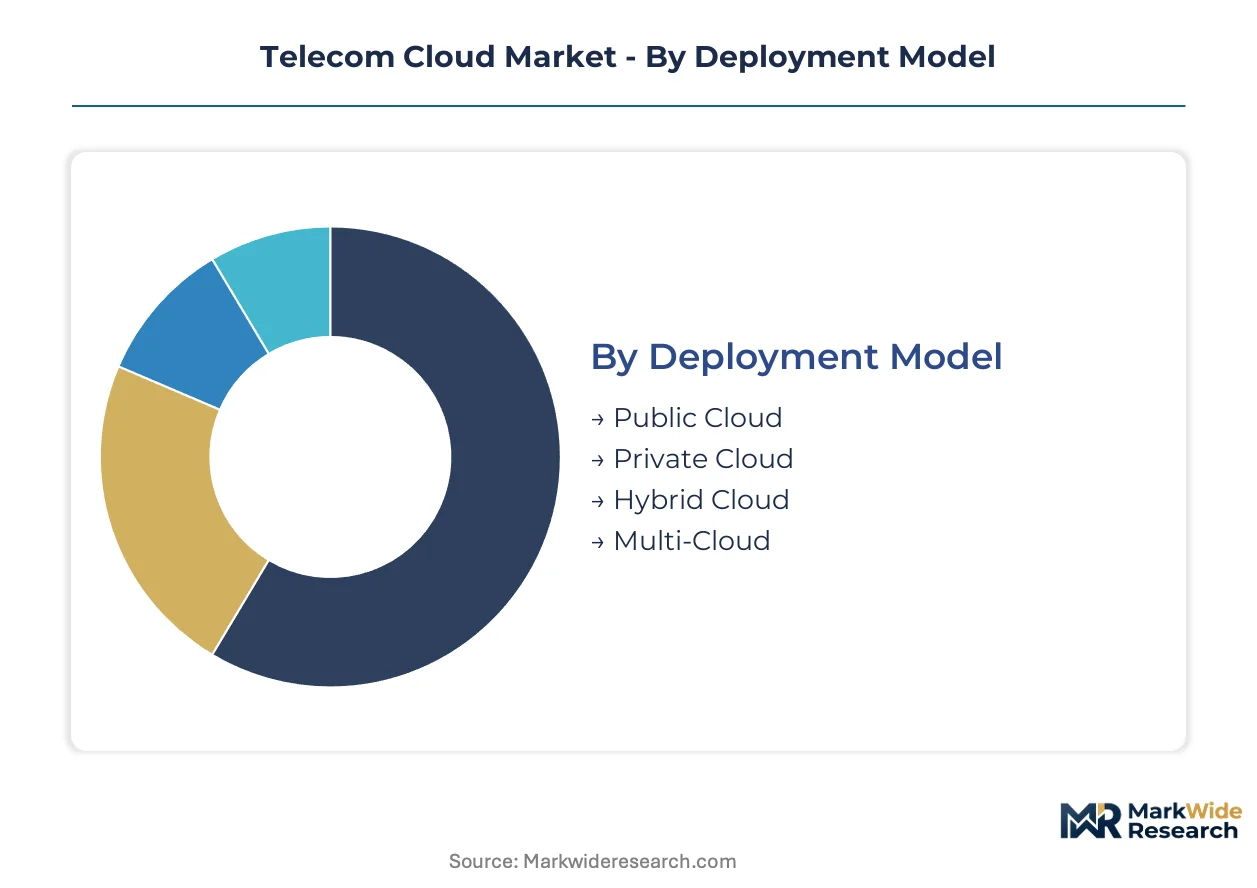
Telecom Cloud segmentation reveals how carrier procurement strategies diverge across infrastructure ownership models and service abstraction layers. Deployment choices reflect risk tolerance toward data sovereignty, while service type selection tracks the pace of network function virtualization mandates.
Deployment Model:
Buyers differentiate primarily by control requirements over subscriber data location and audit trail completeness.
- Public Cloud:Hyperscaler-managed compute pools deliver elastic capacity without capital deployment. Deutsche Telekom and Vodafone Germany are offloading non-core workloads to AWS and Azure regions, driven by ANATEL-style virtualization mandates in multiple jurisdictions.
- Hybrid Cloud:Bespoke orchestration layers bridge on-premises telco edge with hyperscaler central pools, capturing concentrated margin pools through custom integration contracts. Japan's NTT and Germany's carriers favor this model for IMS core latency compliance.
- Private Cloud:Carrier-owned data centers maintain full data sovereignty for subscriber databases and policy control functions.
- Multi-Cloud:Workload distribution across three or more hyperscalers enables real-time price and performance arbitrage.
Public Cloud leads volumes today; Hybrid Cloud is gaining share fastest.
Service Type:
Commercial significance tracks the depth of network function abstraction from physical infrastructure.
- Network Functions Virtualization:Containerized replacements for legacy hardware network functions run atop commodity servers with Kubernetes orchestration. Brazil's 5G standalone core deployments and Japan's Rakuten Mobile infrastructure exemplify carrier urgency here.
- IaaS:Raw compute, storage, and network resources provisioned through APIs form the foundation layer for carrier cloud migrations.
- PaaS:Managed container runtimes and middleware accelerate cloud-native application deployment for telecom DevOps teams.
- SaaS:Microsoft Teams and Zoom Phone integration creates attach opportunities for enterprise voice services bundled with connectivity.
NFV climbs the fastest as 5G standalone mandates compress infrastructure refresh cycles.
End User:
Procurement authority concentrates with entities holding spectrum licenses and direct subscriber relationships.
- Telecom Operators:Mobile network operators and fixed-line carriers drive foundational demand through IMS core virtualization and subscriber database migration projects. Claro, TIM, and Vivo in Brazil negotiate parallel hyperscaler agreements to satisfy regulatory diversification expectations.
- Enterprises:Large corporations consume SaaS-layer telecom services and private network slices for industrial automation.
- Managed Service Providers:Intermediaries aggregate cloud connectivity for mid-market clients lacking direct carrier relationships.
- System Integrators:Professional services firms deliver custom orchestration layers and legacy billing system integration.
Telecom Operators dominate current spending; Enterprises show the steepest expansion trajectory.
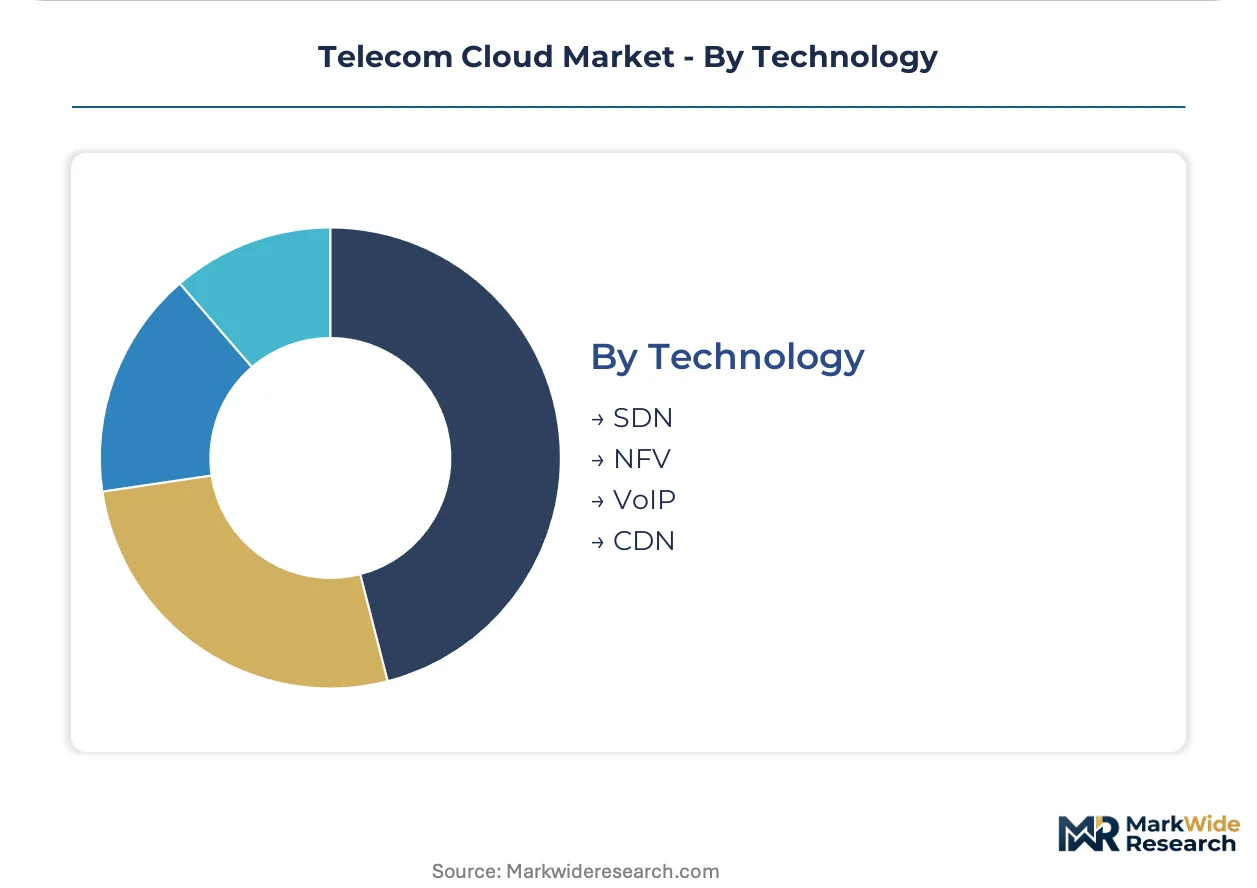
Technology:
Adoption sequencing follows the migration path from control plane virtualization to media plane optimization.
- NFV:Virtualized network functions replace purpose-built hardware with software running on standard servers, enabling elastic scaling of packet core and session border controller capacity.
- SDN:Centralized controllers program data plane behavior through open protocols, compressing traffic engineering decisions from backbone routers to software layers.
- VoIP:Packetized voice transport over IP networks underpins cloud-native unified communications and enterprise voice stacks.
- CDN:Distributed content caches at metro edge reduce backhaul congestion for video streaming and over-the-top media delivery.
NFV anchors current deployment value; SDN integration with AI-optimized silicon is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting cloud infrastructure investment toward jurisdictions with clearer compliance pathways. Carriers migrate workloads to markets where data-sovereignty rules balance territorial processing requirements against operational flexibility.
United States
FCC net neutrality rulings and state-level privacy laws are fragmenting architectural standards for carrier cloud deployments. Northern Virginia's hyperscaler data center clusters concentrate wholesale cloud connectivity capacity. Amazon Web Services leverages its global fiber backbone to dominate carrier-facing infrastructure in this corridor.
Germany
Deutsche Telekom and Vodafone Germany are accelerating core network modernization through public cloud offloading. GDPR data-localization mandates enforced by national regulators multiply compliance engineering costs for platform vendors. Frankfurt's financial services hub drives demand for audit-ready cloud architectures with sub-10 millisecond latency guarantees.
Brazil
ANATEL licensing terms tie 5G authorizations to demonstrable virtualization progress, compressing infrastructure refresh cycles. Claro, TIM, and Vivo negotiate parallel hyperscaler agreements to satisfy regulatory diversification expectations. São Paulo's enterprise density anchors demand for SaaS-layer telecom services bundled with cloud connectivity.
Japan
NTT and Rakuten Mobile deploy containerized network functions at scale across distributed metro edge clusters. METI industrial policy supports cloud-native infrastructure adoption for 5G standalone core mandates. Tokyo-Osaka corridor concentration enables terabit-scale throughput through SDN-controlled backbones with programmable latency profiles.
China
MIIT cloud security assessments extend product launch windows by 12-18 months for foreign platform vendors. Domestic carriers prioritize private cloud architectures to maintain full data sovereignty over subscriber databases. Beijing-Tianjin-Hebei cluster concentration shapes national standards for NFV orchestration platforms serving state-owned operators.
Telecom Cloud Market Key Industry Players
United States-based hyperscalers anchor one tier; European and Asian telecom equipment specialists hold adjacent positions in network function virtualization. The vendor base concentrates around three strategic archetypes: cloud infrastructure providers with global fiber backbones, legacy telecom equipment vendors pivoting to software-defined stacks, and systems integrators delivering bespoke orchestration layers. Competitive moves center on multi-cloud workload distribution contracts and AI-optimized networking silicon development.
Within the hyperscaler tier, Amazon Web Services, Microsoft, and Google occupy positions defined by infrastructure scale and service abstraction depth. Amazon Web Services exemplifies the wholesale connectivity archetype through carrier-facing data center expansion. Microsoft represents the SaaS-layer integration vector with enterprise voice and collaboration stack penetration. Google sits within the AI-optimized silicon specialization, differentiating through custom TPU-based packet processing capabilities.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| AT&T Inc. |
| Verizon Communications Inc. |
| IBM |
| Cisco Systems Inc. |
| Telefonaktiebolaget LM Ericsson |
| Broadcom Inc. |
| Others |
Cost & Logistics Intelligence
Captive fiber infrastructure ownership by hyperscalers in Northern Virginia anchors both supply positioning and pricing power across wholesale cloud connectivity contracts. This vertical integration pattern concentrates procurement leverage with AWS, Microsoft, and Google, compressing distributor margins for carrier-facing resale channels.
Pricing Analysis
Distributor margin compression runs through carrier-facing resale channels as hyperscalers push direct-to-telco contracting. Three-tier pricing structure across premium, standard, and economy levels differentiates by latency guarantee and edge proximity, with Frankfurt and Tokyo commands commanding brand premiums. Cost compression in standard-tier NFV orchestration is intensifying because container orchestration expertise concentrates among hyperscaler engineering teams. Tier-two carriers in Brazil show highest price sensitivity, while Deutsche Telekom and NTT absorb premium pricing for sub-10 millisecond latency compliance.
Supply Chain Analysis
Regional distribution centers in Northern Virginia, Frankfurt, and Tokyo anchor hub-and-spoke patterns for hyperscaler cloud capacity. Server hardware draws from Taiwan, South Korea, and USA fabrication facilities, with custom TPU and networking silicon resting on TSMC advanced node allocation. Single-source vulnerability in submarine cable landing stations creates chokepoint exposure for intercontinental carrier connectivity. Distribution runs through direct hyperscaler contracts with tier-one carriers, bypassing traditional telecom equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act compounds demand for audit-ready cloud architectures, with algorithmic transparency obligations forcing carrier infrastructure refresh cycles. This regulatory milestone creates procurement urgency that vendors must anticipate and serve.
For Market Incumbents: Anticipate multi-cloud workload distribution threats from emerging orchestration specialists by deepening API integration with carrier billing systems. Prioritize certification investment for GDPR and EU AI Act compliance to defend margin position against leaner cloud-native entrants. Lock in three-year modernization contracts with Deutsche Telekom and Vodafone Germany before competitive RFP cycles accelerate.
For New Entrants and Emerging Players: The gap between premium hyperscaler pricing and economy-tier white-box NFV creates entry space for Kubernetes-native orchestration vendors. Target Brazil's ANATEL-mandated virtualization sprint, where Claro, TIM, and Vivo seek alternatives to AWS-Azure-Google concentration. Lead with open-source orchestration layers that reduce carrier lock-in while satisfying regulatory diversification expectations.
For Investors and Strategic Acquirers: Roll-up economics work for hybrid cloud orchestration specialists because carrier procurement fragmentation across three or more hyperscalers demands bespoke integration layers. Target mid-cap firms with proven Kubernetes networking expertise and existing Deutsche Telekom or NTT deployment references. Watch for 5G standalone core completion rates as the inflection signal—accelerated virtualization milestones trigger carrier budget release for adjacent SaaS-layer services.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Optimized Networking Silicon Development | Google's TPU-based packet processing differentiates cloud throughput capabilities against AWS and Azure. |
| Multi-Cloud Orchestration Platform Launch | Bespoke integration layers capture margin pools bridging on-premises telco edge with hyperscaler central pools. |
| GDPR Compliance Certification Program | Audit-ready architectures satisfy EU AI Act transparency mandates for automated network optimization tools. |
| Edge Data Center Expansion | Metro cluster buildouts in São Paulo and Tokyo compress latency budgets for IMS core functions. |
| Legacy Billing System Integration Partnership | Custom middleware development unlocks subscriber database migration contracts from Oracle and SAP environments. |
Research Approach
Coverage spans Germany, Japan, Brazil, United States, and China, with primary inputs from each market's carrier procurement executives and cloud platform engineering leads. The analysis combines structured interviews with network architects at Deutsche Telekom, NTT, and Claro with secondary validation through ANATEL licensing records, MIIT security assessment filings, and hyperscaler capex disclosures. SEC 10-K infrastructure segment reporting, EU regulatory transparency databases, and carrier RFP documentation provided triangulation anchors for bottom-up and top-down reconciliation.
Granularity-level modeling distinguished deployment model, service type abstraction layer, and end-user procurement authority across the projection horizon. Network Functions Virtualization, SDN integration intensity, and edge-native latency compliance were segmented separately from central cloud workload economics. CAGRs were derived from carrier capital commitment patterns and regulatory milestone timing, with 5G standalone core deployment velocity and AI Act compliance engineering costs serving as primary forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for open-source Kubernetes orchestration displacing proprietary NFV platforms would alter the outlook. Forecasts reflect documented assumptions about hyperscaler supply concentration and regulatory enforcement consistency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Public Cloud Application Services Market
Cloud Computing
AI Platform Cloud Service Market
Cloud Computing
Global Grid Computing Market
Cloud Computing
Europe Mobile Cloud Market
Cloud Computing
North America Mobile Cloud Market
Cloud Computing
Commerce Cloud Market
Cloud Computing
UAE Cloud Computing Market
Cloud Computing
Cloud and Data Center Transformation Market
Cloud Computing
Virtual Machines Market
Cloud Computing
Cloud-Managed LAN Market
Cloud Computing
ASEAN Cloud Computing Market
Cloud Computing
Cloud API and Management Platforms and Middleware Market
Cloud Computing
Global Cloud High-Performance Computing Market
Cloud Computing
Cloud Computing in Industrial IoT Market
Cloud Computing
Saudi Arabia Cloud Computing Market
Cloud Computing
Global Cloud Management Software Market