
 Saudi Arabia Cloud Computing Market | 2026-2036
Saudi Arabia Cloud Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Cloud Computing Market Insights
ISO 27001 certification is reorganizing competitive access in Saudi Arabia's cloud sector, with providers now facing mandatory compliance cycles to serve government and regulated industries. Microsoft Azure leverages its regional data centers in Riyadh and Jeddah to anchor enterprise workloads. Amazon Web Services sustains market presence through its AWS Middle East (Bahrain) Region proximity and dedicated Saudi Arabia plans. Saudi Telecom Company dominates through Solutions by stc, its captive cloud subsidiary that controls local enterprise relationships.
Cloud computing in Saudi Arabia encompasses the on-demand delivery of IT resources—compute power, storage, databases, networking, and software—over the internet with metered pricing and elastic scaling, typically operating through hypervisor-virtualized infrastructure distributed across availability zones. Its primary commercial purpose is to replace capital-intensive on-premises data centers with operational expenditure models that accelerate digital transformation timelines. Public Cloud deployment captures the dominant revenue share as hyperscalers expand local regions, while Security Services within Solution Type commands premium margins due to PDPL-driven compliance urgency. Hybrid Cloud architectures are gaining fastest traction among BFSI end users balancing legacy core banking systems with modern analytics workloads.
SAMA, the Saudi Arabian Monetary Authority, imposes strict operational resilience and data governance standards on cloud-adopting financial institutions. SDAIA enforces the Personal Data Protection Law with cross-border transfer restrictions that localize demand. NCA, the National Cybersecurity Authority, mandates Essential Cybersecurity Controls that filter which providers qualify for critical infrastructure contracts. Stakeholders must monitor how upcoming SDAIA executive regulations redefine processor liabilities and whether SAMA issues explicit cloud outsourcing guidance that supersedes current interpretive flexibility.
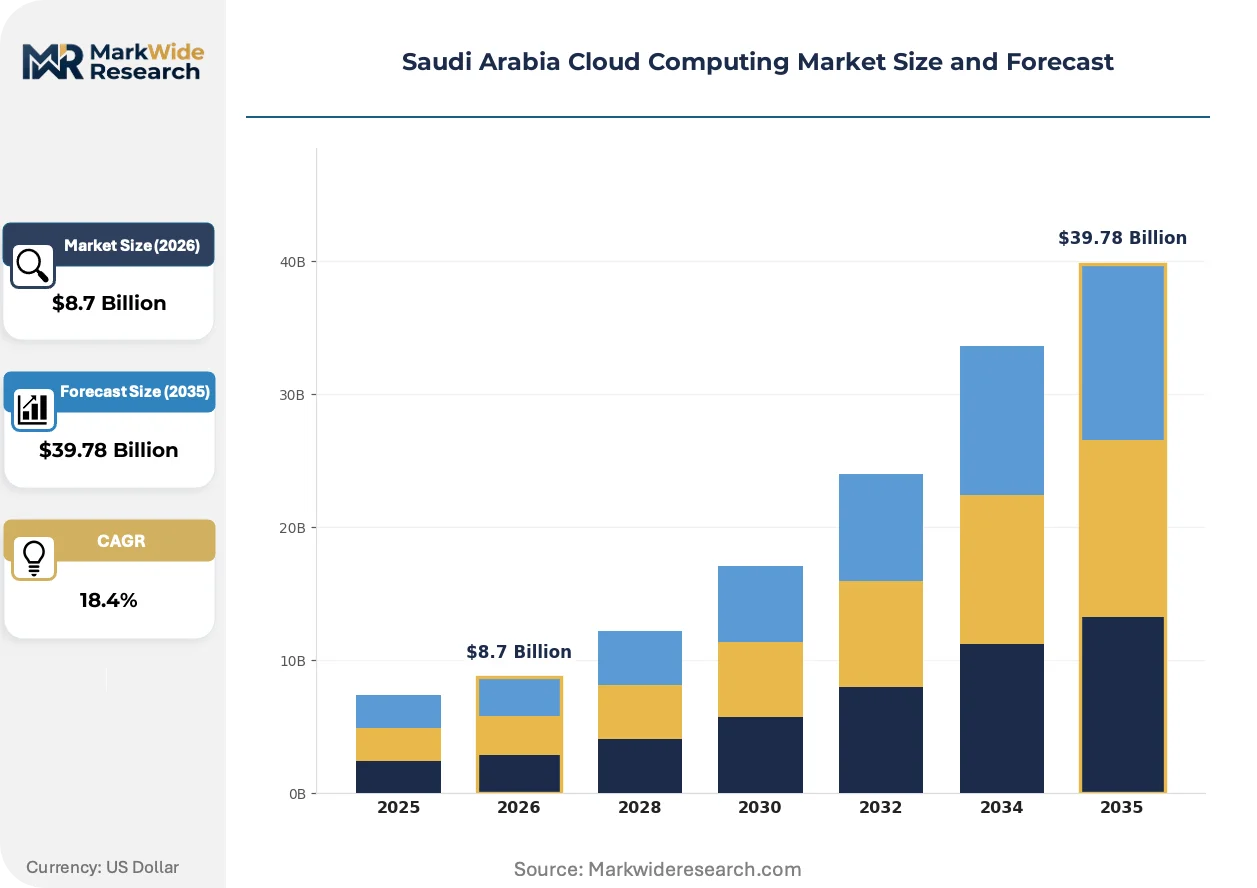
Market Dynamics
SDAIA's Personal Data Protection Law is compressing cloud deployment timelines as enterprises race to achieve data residency compliance before enforcement hardens. This regulatory pressure is restructuring procurement priorities across Saudi Arabia's regulated sectors.
Growth Catalysts
- PDPL Localization Mandate:Cross-border transfer restrictions under SDAIA enforcement are forcing multinational enterprises to migrate workloads to Saudi-based data centers, creating captive demand for domestic cloud infrastructure.
- BFSI Digital Transformation:SAMA's operational resilience requirements are accelerating core banking system modernization, with financial institutions replacing legacy on-premises hardware with elastic cloud architectures.
- Riyadh Digital Hub Concentration:Government smart city investments and NEOM-related data center clustering are concentrating enterprise demand in the capital region, reducing latency and improving service delivery economics.
Market Restraints
- Data Center Land and Power Constraints:Riyadh's limited commercial real estate zoned for hyperscale facilities and grid capacity allocation bottlenecks are extending facility commissioning timelines beyond customer demand curves.
- Specialized Cloud Talent Scarcity:The domestic labor market lacks sufficient certified architects and security engineers, forcing providers to import expensive expatriate expertise or delay service launches.
- Legacy System Integration Friction:Oracle and IBM mainframe dependencies in Saudi banking and oil sectors create technical debt that resists cloud-native refactoring, slowing migration velocity.
Strategic Opportunities
- Eastern Province Industrial Cloud:Aramco and SABIC manufacturing complexes present underpenetrated demand for edge computing and industrial IoT platforms with local processing requirements.
- Hybrid Sovereign Cloud Architectures:Government agencies are mandating air-gapped private cloud deployments for classified workloads, opening specialized infrastructure segments beyond standard public cloud.
- FinOps and Cloud Cost Optimization:Enterprise procurement teams are adopting consumption analytics platforms to manage multi-cloud sprawl, creating adjacent software and services revenue pools.
Industry Challenges
- ISO 27001 Certification Backlogs:Accreditation body capacity constraints are delaying provider certification timelines, freezing government contract eligibility for months.
- Inter-Agency Regulatory Coordination:Overlapping SDAIA, SAMA, and NCA compliance requirements create conflicting data governance interpretations that increase legal review costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Cloud Computing Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Model: IaaS, PaaS, SaaS, DaaS End User Industry: Healthcare, Retail, Education, BFSI Solution Type: Backup & Disaster Recovery, Cloud Storage, Cloud Migration, Security Services |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, Oracle Cloud, Alibaba Cloud, Saudi Telecom Company, IBM, Salesforce, Solutions by stc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Cloud Computing Market Trends and Innovations
Containerization and Kubernetes orchestration are displacing traditional virtualization as the foundational abstraction layer for Saudi enterprise workloads. This shift is compressing deployment cycles and enabling multi-cloud portability that reduces vendor lock-in risk.
Serverless computing architectures are miniaturizing operational overhead for Saudi fintech startups and e-commerce platforms. SAMA-regulated payment processors are adopting function-as-a-service models to handle transaction spikes during Ramadan and holiday periods without permanent infrastructure. This technology is compressing time-to-market for regulated financial products from quarters to weeks.
SDAIA's forthcoming executive regulations on processor liability are tightening contractual frameworks between cloud providers and enterprise customers. Financial institutions are renegotiating service agreements to clarify incident response obligations and data breach notification timelines. BFSI verticals are responding by demanding enhanced audit rights and penetration testing transparency clauses.
Enterprise sourcing patterns are fragmenting across multi-cloud portfolios rather than consolidating with single hyperscalers. Saudi procurement teams are distributing workloads across Azure, AWS, and stc Cloud to optimize price-performance and satisfy redundancy requirements. This behavior is most visible in Riyadh-based conglomerates with diversified subsidiary operations spanning retail, logistics, and construction verticals.
Saudi Arabia Cloud Computing Market Segmentation
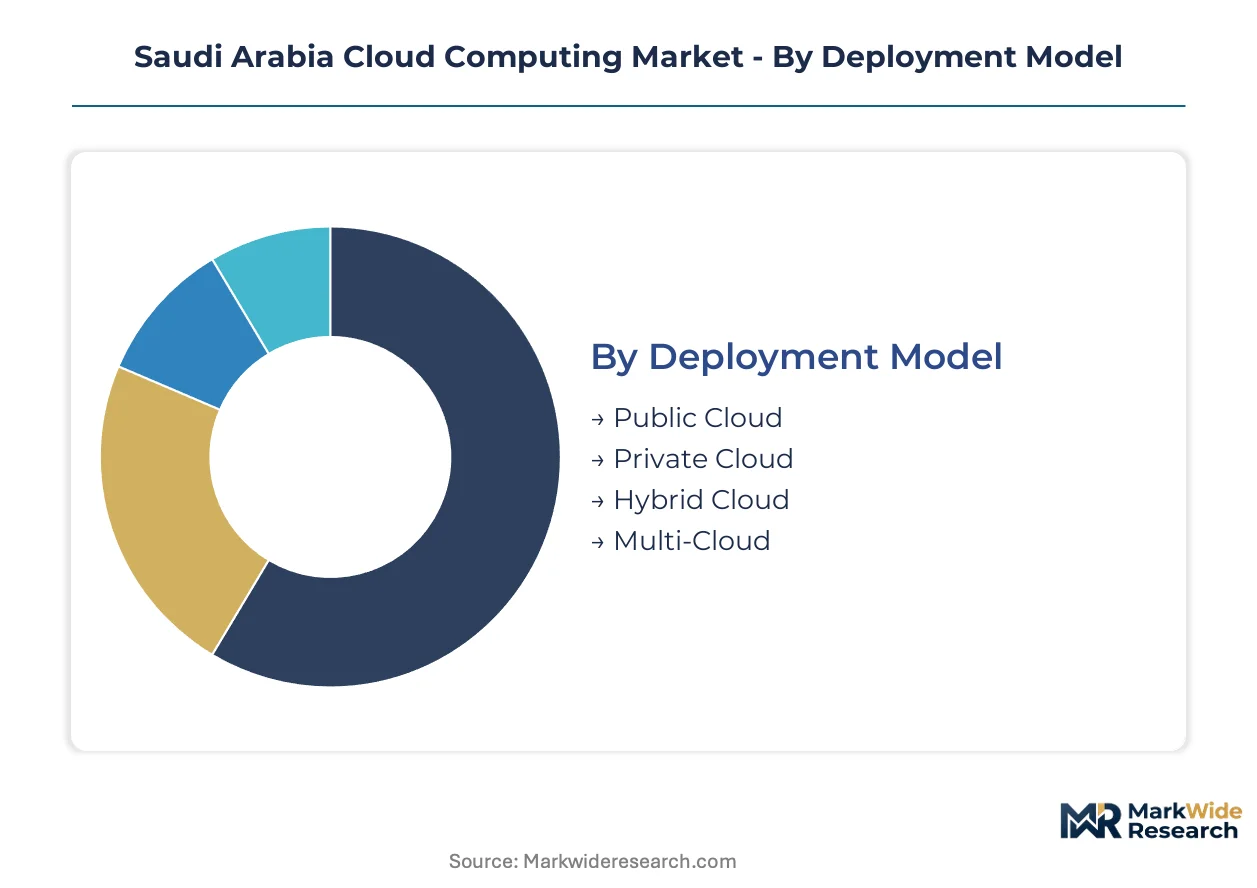
Segmentation in Saudi Arabia's cloud market reveals how PDPL compliance, BFSI modernization, and sovereign infrastructure requirements are fragmenting procurement patterns across deployment architectures and service tiers.
Deployment Model:
Margin pools concentrate in architectures that balance elasticity with data residency guarantees, reflecting SDAIA's cross-border transfer restrictions.
- Public Cloud:Hyperscale infrastructure delivered through shared tenancy with metered consumption and automatic scaling. Demand concentrates in Riyadh-based financial services firms modernizing customer-facing applications under SAMA operational resilience timelines. Azure and AWS regional zones capture enterprise workloads requiring low-latency access to sovereign data centers.
- Hybrid Cloud:Interconnected public and private environments enabling workload portability across security boundaries. Aramco and SABIC manufacturing complexes in the Eastern Province are deploying edge-connected hybrid stacks for industrial IoT analytics with local preprocessing. This architecture addresses air-gapped requirements for classified operational technology networks.
- Private Cloud:Single-tenant infrastructure dedicated to individual organizations with full control over hardware and virtualization layers.
- Multi-Cloud:Distributed workloads across two or more hyperscale providers to optimize price-performance and eliminate single-vendor dependency.
Public Cloud holds installed capacity. Hybrid Cloud is rotating up the share rankings.
Service Model:
Revenue concentration tracks enterprise maturity, with established organizations prioritizing infrastructure control while startups consume higher abstraction layers.
- SaaS:Fully managed applications delivered through web browsers with zero infrastructure administration. Saudi fintech startups and SME retail chains are adopting CRM, ERP, and collaboration suites to bypass capital expenditure cycles. SAMA-regulated payment processors favor SaaS models for rapid product deployment during seasonal demand spikes.
- IaaS:Virtualized compute, storage, and networking resources provisioned through APIs and management consoles. NEOM infrastructure projects and Riyadh smart city initiatives are anchoring IaaS demand for scalable foundational layers. Government tenders specify IaaS for workloads requiring direct OS-level control.
- PaaS:Developer-centric environments abstracting infrastructure management through container orchestration and managed databases.
- DaaS:Cloud-hosted virtual desktops streamed to endpoint devices with centralized security policy enforcement.
IaaS anchors current procurement volumes. SaaS is climbing the fastest as procurement teams prioritize operational simplicity.
End User Industry:
Compliance intensity and digital transformation budgets determine segment profitability, with regulated verticals commanding premium security attach rates.
- BFSI:Banks, insurers, and investment firms subject to SAMA operational resilience and data governance mandates. Core banking modernization projects in Riyadh and Jeddah are replacing IBM and Oracle mainframes with cloud-native architectures. Financial institutions are negotiating enhanced audit rights and penetration testing transparency in provider contracts.
- Healthcare:Hospitals, clinics, and pharmaceutical distributors managing patient records and clinical systems. MOH and SFDA data localization requirements are compressing migration timelines for electronic health record platforms. Telemedicine expansion post-pandemic is driving storage and compute demand for medical imaging archives.
- Retail:E-commerce platforms, supermarket chains, and logistics operators with seasonal transaction volatility.
- Education:Universities and K-12 institutions deploying learning management systems and research computing environments.
BFSI dominates current contract values. Healthcare is gaining share fastest as SFDA enforcement hardens.
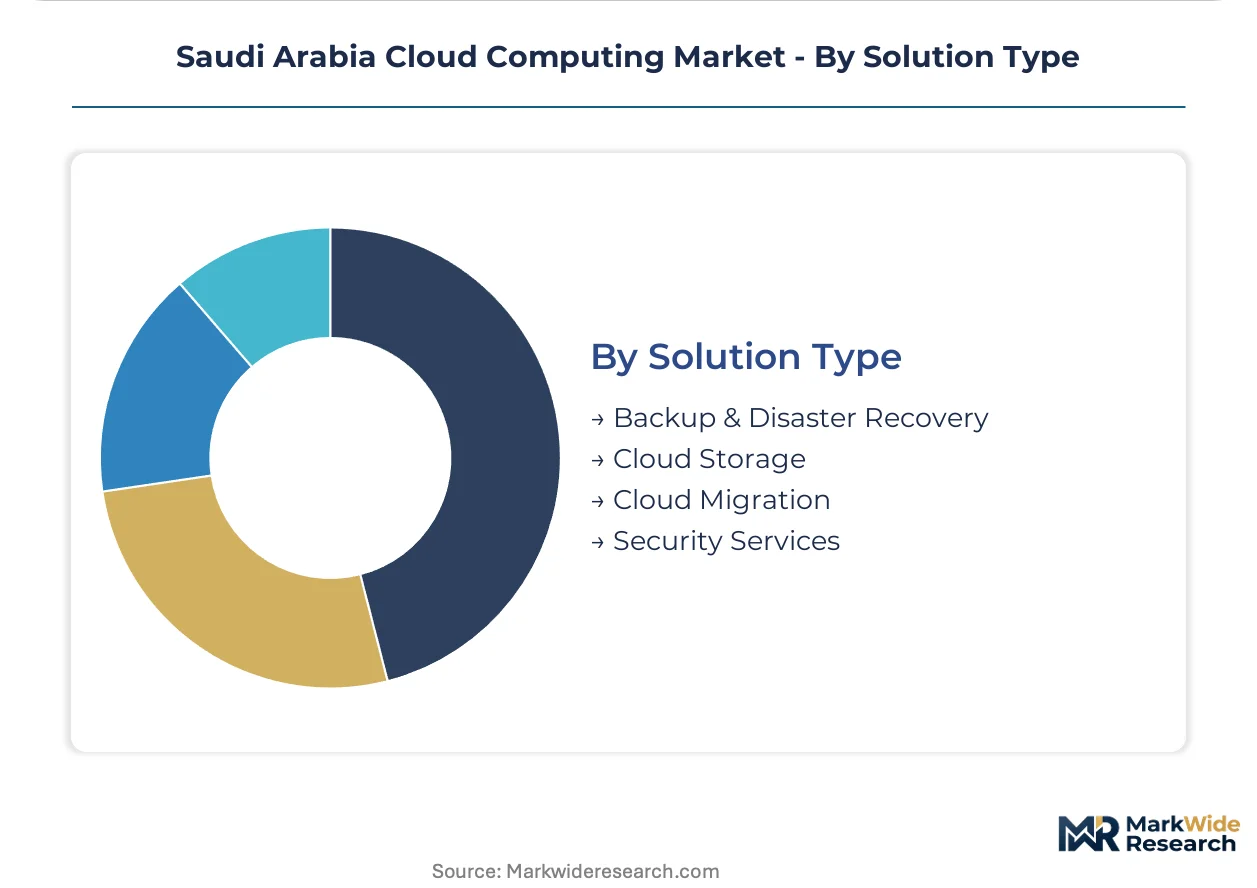
Solution Type:
Premium pricing attaches to capabilities that directly address PDPL liability exposure and operational continuity requirements.
- Security Services:Identity management, encryption, threat detection, and compliance monitoring delivered as cloud-native functions. SDAIA processor liability regulations are forcing renegotiation of incident response obligations and breach notification timelines. BFSI procurement teams are mandating ISO 27001-certified providers with in-country security operations centers.
- Cloud Migration:Assessment, refactoring, and workload transfer services from on-premises to cloud environments. Legacy Oracle and IBM dependencies in Saudi banking and oil sectors create technical debt resisting cloud-native transformation. Specialized system integrators are capturing multi-year modernization contracts.
- Backup & Disaster Recovery:Automated replication and failover capabilities ensuring business continuity across availability zones.
- Cloud Storage:Object, block, and file storage tiers with tiered durability and access latency specifications.
Security Services commands margin premiums. Cloud Migration is rotating up the share rankings as technical debt deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement teams in Saudi Arabia cluster around three distinct buyer archetypes: SAMA-regulated financial institutions prioritizing operational resilience, SDAIA-compliant multinationals racing data residency deadlines, and NEOM-linked infrastructure developers demanding sovereign infrastructure. These archetypes concentrate demand in specific sub-regions with differentiated compliance intensities.
Riyadh
BFSI modernization projects and smart city investments dominate Riyadh's cloud consumption, with banks replacing IBM and Oracle mainframes under SAMA-mandated timelines. SDAIA's PDPL enforcement has compressed migration schedules for multinational headquarters located in the capital's King Abdullah Financial District. The Riyadh Digital Hub clustering reduces latency for enterprise workloads while straining commercial real estate zoned for hyperscale facilities.
Eastern Province
Aramco and SABIC manufacturing complexes generate specialized demand for edge computing and industrial IoT platforms with air-gapped operational technology requirements. NCA Essential Cybersecurity Controls filter provider eligibility for critical infrastructure contracts in this hydrocarbon-heavy zone. Dammam and Jubail Industrial City anchor the Kingdom's underpenetrated industrial cloud segment, where hybrid architectures preprocess sensor data before cloud transfer.
Western Region
Jeddah's commercial port and logistics corridors drive cloud demand from retail and e-commerce platforms managing seasonal transaction volatility. The region's healthcare clusters face MOH and SFDA data localization mandates for electronic health record platforms. King Abdullah Economic City represents an emerging concentration for fintech startups adopting serverless architectures to compress product deployment cycles.
NEOM Northwest
The giga-project's cognitive city infrastructure requires sovereign cloud deployments with classified workload segregation beyond standard public cloud offerings. Government tenders specify IaaS with direct OS-level control for this experimental zone. NEOM's data center clustering is attracting hyperscaler regional investments that will reshape northern Saudi Arabia's cloud economics upon commissioning.
Saudi Arabia Cloud Computing Market Competitive Landscape
Player mix skews toward hyperscale multinationals with regional data center investments and captive telecom subsidiaries controlling local enterprise relationships. The market exhibits tiered concentration with three distinct strategic layers: global hyperscalers leveraging regional zone proximity, domestic telecom-cloud hybrids exploiting sovereign data requirements, and specialized system integrators capturing multi-year modernization contracts. Competitive dynamics center on certification velocity for ISO 27001 compliance and strategic partnerships with government entities for smart city and NEOM-linked infrastructure tenders.
Within the hyperscaler tier, Microsoft Azure and Amazon Web Services anchor enterprise workload capture through regional data center presence in Riyadh and Jeddah or proximity via Bahrain. Solutions by stc exemplifies the telecom-captive archetype, leveraging Saudi Telecom Company's entrenched local relationships to dominate government and regulated industry procurement. Among specialized integrators, IBM occupies a position serving legacy mainframe-dependent banking and oil sector clients resisting cloud-native refactoring.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| Oracle Cloud |
| Alibaba Cloud |
| Saudi Telecom Company |
| IBM |
| Salesforce |
| Solutions by stc |
| Others |
Pricing and Supply Chain Analysis
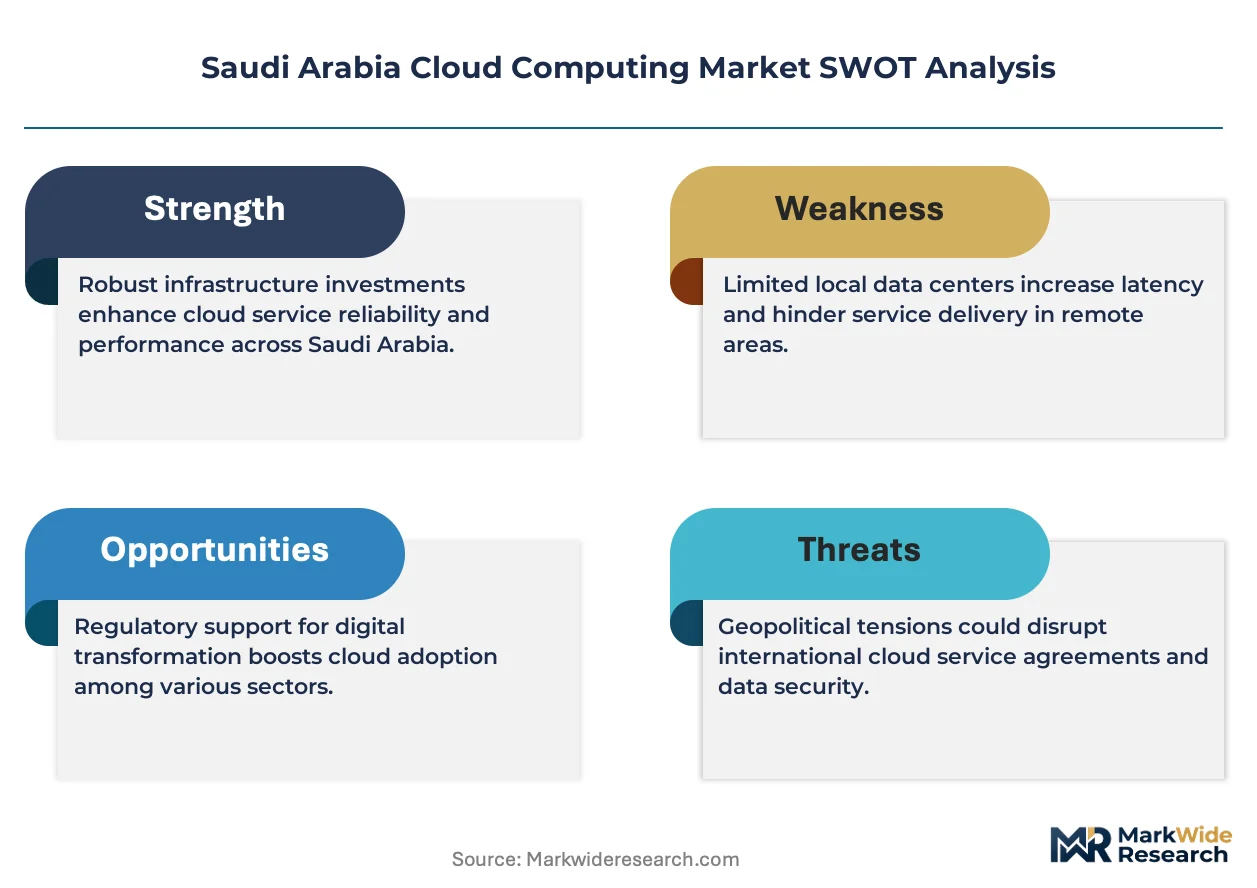
ISO 27001 certification gates both supplier qualification and price differentiation in Saudi Arabia's cloud sector, with accredited providers commanding premium positioning while uncertified competitors face exclusion from government and BFSI procurement cycles. This dual-filter mechanism concentrates pricing power among hyperscalers with regional data center investments and telecom-captive subsidiaries that control local enterprise relationships.
Pricing Analysis
Cost-plus contracts with power-indexation clauses dominate hyperscale facility agreements, linking data center pricing to Saudi Electricity Company tariff adjustments and diesel backup fuel costs. Three-tier pricing structure across premium, standard, and economy levels separates ISO 27001-certified sovereign cloud deployments from uncertified public cloud tiers and commodity colocation. Pricing pressure stems from Riyadh land scarcity extending facility commissioning timelines beyond demand curves. SAMA-regulated banks exhibit lowest price sensitivity due to operational resilience mandates, while retail SMEs drive cost compression in standard tiers.
Supply Chain Analysis
Inbound logistics costs through Jeddah Islamic Port and King Abdulaziz Port in Dammam constrain server hardware delivery timelines, with container availability fluctuations affecting hyperscaler capacity expansion schedules. Supply concentrates in China, Taiwan, and the United States for server hardware, with Intel and AMD processor dependencies creating single-source vulnerability. Flash storage and networking equipment draw from South Korean and Japanese manufacturers. Distribution runs through Solutions by stc and hyperscaler direct sales teams to enterprise procurement officers in Riyadh's King Abdullah Financial District.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's cloud market represents early-cycle expansion with PDPL enforcement compressing enterprise migration timelines and creating captive demand for compliant infrastructure. Sovereign data requirements and BFSI modernization are accelerating penetration beyond historical laggard patterns in the Middle East.
For Market Incumbents: Fortify certification velocity by pre-positioning ISO 27001 audit resources and expanding Riyadh-Jeddah data center interconnect capacity before SDAIA enforcement hardens. Threats from Alibaba Cloud and Google Cloud regional investments demand localized security operations center buildouts. Vertical integration into managed security services captures PDPL-driven compliance spending. For New Entrants and Emerging Players: Anchor in the Eastern Province industrial corridor where Aramco and SABIC manufacturing complexes present underpenetrated edge computing demand with air-gapped operational technology requirements. Hybrid sovereign cloud architectures for classified workloads offer the most penetrable segment beyond hyperscaler dominance. Go-to-market through NEOM infrastructure consortium partnerships bypasses entrenched stc relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hyperscale data center construction, favoring asset-light managed services and cloud migration specialists over facility ownership. Long-term viability centers on recurring revenue models with SAMA-regulated BFSI clients. Acquisition targets should demonstrate ISO 27001 certification and existing government contract eligibility. The signal to watch is SDAIA executive regulation release timing on processor liability frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 27001 Certification Acceleration | SDAIA enforcement hardens compliance requirements, freezing uncertified providers from government tenders. |
| Regional Data Center Expansion | Azure and AWS Riyadh-Jeddah zones reduce latency for SAMA-regulated financial workloads. |
| Managed Security Services Buildout | PDPL processor liability creates adjacent revenue from incident response and breach notification. |
| Hybrid Sovereign Cloud Architecture | NEOM and NCA mandates open specialized segments beyond standard public cloud offerings. |
| Cloud Migration Specialist Acquisition | Oracle and IBM mainframe technical debt in banking and oil sectors demands refactoring expertise. |
Research Methodology
The analysis maps public cloud, hybrid cloud, private cloud, and multi-cloud deployment architectures, each validated through cloud procurement officers, SAMA regulatory affairs leads, data center operations directors, and enterprise IT architects. Primary fieldwork combined structured interviews with hyperscaler account executives and Solutions by stc commercial teams. Secondary sources encompassed SDAIA regulatory filings, SAMA circulars on operational resilience, NCA Essential Cybersecurity Controls documentation, and hyperscaler regional capex disclosures. Bottom-up facility capacity modeling triangulated against top-down enterprise IT spending surveys.
Consistency checks validated volume and value outputs against hyperscaler regional revenue disclosures and Saudi Telecom Company segment reporting across the projection horizon. Segmentation dimensions modeled include deployment model, service tier, end-user industry vertical, and solution type with compliance intensity overlays. CAGRs derived from facility commissioning timelines, enterprise migration velocity surveys, and regulatory deadline proximity analysis. Forecast inputs incorporated PDPL enforcement phase-in assumptions and NEOM infrastructure procurement schedules.
Decision-makers should treat outputs as directional under sustained SDAIA enforcement and SAMA operational resilience timelines; material regulatory delay or hyperscaler capacity constraint would warrant model refresh. Practitioners should keep alternative scenarios live as SDAIA processor liability regulations and NCA critical infrastructure designations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud Applications Market
Cloud Computing
Cloud Microservices Market
Cloud Computing
Japan Cloud Computing Market
Cloud Computing
Serverless Computing Market
Cloud Computing
UAE Cloud Computing Market
Cloud Computing
Cloud Based-Batch Processing Market
Cloud Computing
Global Cloud Based ITSM Market
Cloud Computing
Philippines ICT Market
Cloud Computing
Asia Pacific Cloud Computing Market
Cloud Computing
Middle East and Africa Cloud Infrastructure Services Market
Cloud Computing
Application Hosting Market
Cloud Computing
Brazil Cloud Computing Market
Cloud Computing
Cloudifier Market
Cloud Computing
Asia-Pacific Mobile Cloud Market
Cloud Computing
Industrial Cloud Market
Cloud Computing
Cloud-Based Repository Services Market