
 Global Cloud Dictation Solution Market | 2026-2036
Global Cloud Dictation Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud Dictation Solution Market Foresight
North American speech recognition infrastructure is shifting toward cloud-native architectures with embedded natural language processing. Nuance Communications leverages deep clinical vocabularies to anchor its position in medical documentation workflows. 3M Company sustains competitive differentiation through proprietary acoustic modeling tailored for legal and healthcare transcription. Dolbey Systems specializes in enterprise-grade deployment flexibility across hybrid cloud environments.
Cloud dictation solutions integrate automatic speech recognition engines with real-time audio streaming protocols to convert spoken language into structured text output for enterprise documentation workflows. These systems process variable sampling rates between 8 kHz and 48 kHz while supporting speaker diarization and domain-specific vocabulary adaptation for medical, legal, and media applications. Speech recognition and natural language processing components command the largest solution offering share due to their foundational role in transcription accuracy and workflow integration. Medical documentation and legal transcription applications exhibit the strongest structural momentum as regulated industries prioritize audit-ready record generation and clinician time recovery.
FDA guidance on clinical decision support software intersects with HIPAA security rule requirements to mandate encrypted data handling and access logging for healthcare-facing dictation platforms. EMA's medical device regulation framework and the EU AI Act risk classification system impose conformity assessment obligations on vendors deploying voice biometrics for patient identification. Stakeholders must monitor evolving cross-border data localization rules and algorithmic transparency mandates that will determine which deployment architectures qualify for institutional procurement.
Market Dynamics
HIPAA security rule enforcement and the EU AI Act risk classification system are forcing healthcare-facing dictation vendors to rearchitect data handling pipelines, compressing procurement cycles for compliant platforms while disqualifying legacy on-premise deployments from institutional tenders.
Growth Catalysts
- Hospital digitization mandates:Germany's hospital digitization programs are accelerating medical transcription outsourcing contracts. Federal procurement frameworks now prioritize cloud-native documentation tools.
- Clinical time recovery:Speech recognition with embedded natural language processing is converging with electronic health record workflows. Clinicians in the United States are reclaiming administrative hours through automated documentation.
- EU AI Act compliance:The risk classification system for biometric identification is creating certified vendor tiers. Healthcare institutions in France and the Netherlands are restricting procurement to conformity-assessed platforms.
Market Restraints
- Cross-border data localization:Divergent sovereignty requirements between the United States, Germany, and France are fragmenting deployment architectures. Vendors must maintain region-specific infrastructure instances.
- GPU compute cost volatility:Real-time speech recognition inference depends on specialized cloud hardware. Pricing instability for NVIDIA H100 clusters is compressing gross margins for mid-tier service providers.
- Legacy system entrenchment:Decades-old on-premise dictation hardware in legal and medical practices creates switching friction. Integration costs often exceed platform licensing fees.
Strategic Opportunities
- Underpenetrated ambulatory care:Small physician practices in India and Brazil lack structured documentation tools. Cloud-based pay-per-use models bypass capital expenditure barriers.
- Voice biometric patient identification:The EU AI Act's high-risk system classification is creating a compliance moat. Early-certified vendors capture multi-hospital system contracts.
- Edge-cloud hybrid architectures:Automatic speech recognition is converging with on-device processing for low-latency clinical workflows. German hospital networks are piloting split-inference models.
Industry Challenges
- Clinical informatics talent scarcity:Healthcare organizations lack personnel who bridge medical terminology expertise with NLP pipeline configuration. Vendor professional services costs are inflating.
- Multi-jurisdiction certification timelines:Simultaneous FDA clinical decision support guidance, HIPAA security rule audits, and EU AI Act conformity assessments extend product launch cycles by months.
- Interoperability standard fragmentation:HL7 FHIR implementation varies across United States health systems. Custom integration work consumes engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud Dictation Solution Market |
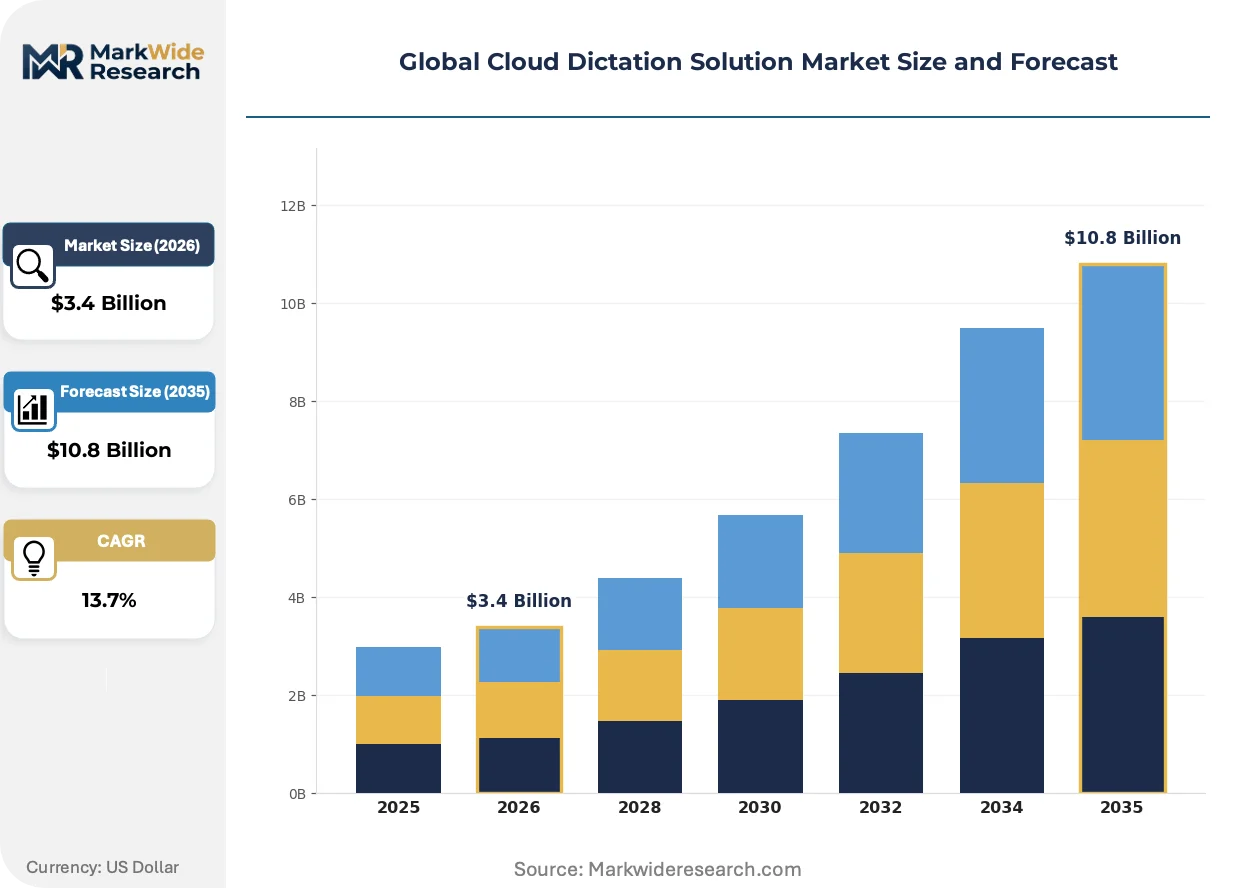
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $10.8 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution Offering: Speech Recognition, Natural Language Processing, Voice Biometrics, Audio Analytics, Language Translation Application: Legal Transcription, Medical Documentation, Customer Service Automation, Media Subtitling, Educational Content Development End User: Law Firms, Medical Practitioners, Call Centers, Broadcasting Companies, Educational Institutions |
| Companies Covered | Nuance Communications, Inc., 3M Company, Dolbey Systems, Inc., Speech Processing Solutions GmbH, Voicepoint AG, Crescendo Systems Ltd., Arrendale Associates, Inc., SpeechWrite Ltd., Otter.ai Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud Dictation Solution Market Shifts & Advancements
Architectural shifts in speech recognition infrastructure are compressing the boundary between audio capture and structured data output, with regulatory compliance emerging as the primary vendor selection filter rather than transcription accuracy alone.
Large language models fine-tuned on clinical corpora are converging with real-time streaming protocols to generate encounter documentation drafts during patient visits. United States health systems are deploying these systems in emergency departments and specialty clinics. The structural consequence is a compression of documentation burden from hours to minutes, displacing traditional transcription service contracts.
The EU AI Act's risk-based classification for biometric identification systems is mandating algorithmic transparency documentation and human oversight protocols for voice authentication in patient-facing workflows. Vendors must submit technical documentation to notified bodies before commercial deployment. Medical device manufacturers in Germany and the Netherlands are prioritizing low-risk classification pathways by limiting voiceprint storage duration.
Subscription-based procurement with usage-tier pricing is displacing perpetual licensing for enterprise dictation platforms. Legal transcription departments in the United Kingdom and Australia are consolidating vendor relationships around outcome-based contracts tied to turnaround time guarantees. Healthcare procurement teams in Canada are unbundling implementation services from software subscriptions to improve cost visibility.
Global Cloud Dictation Solution Market Segmentation
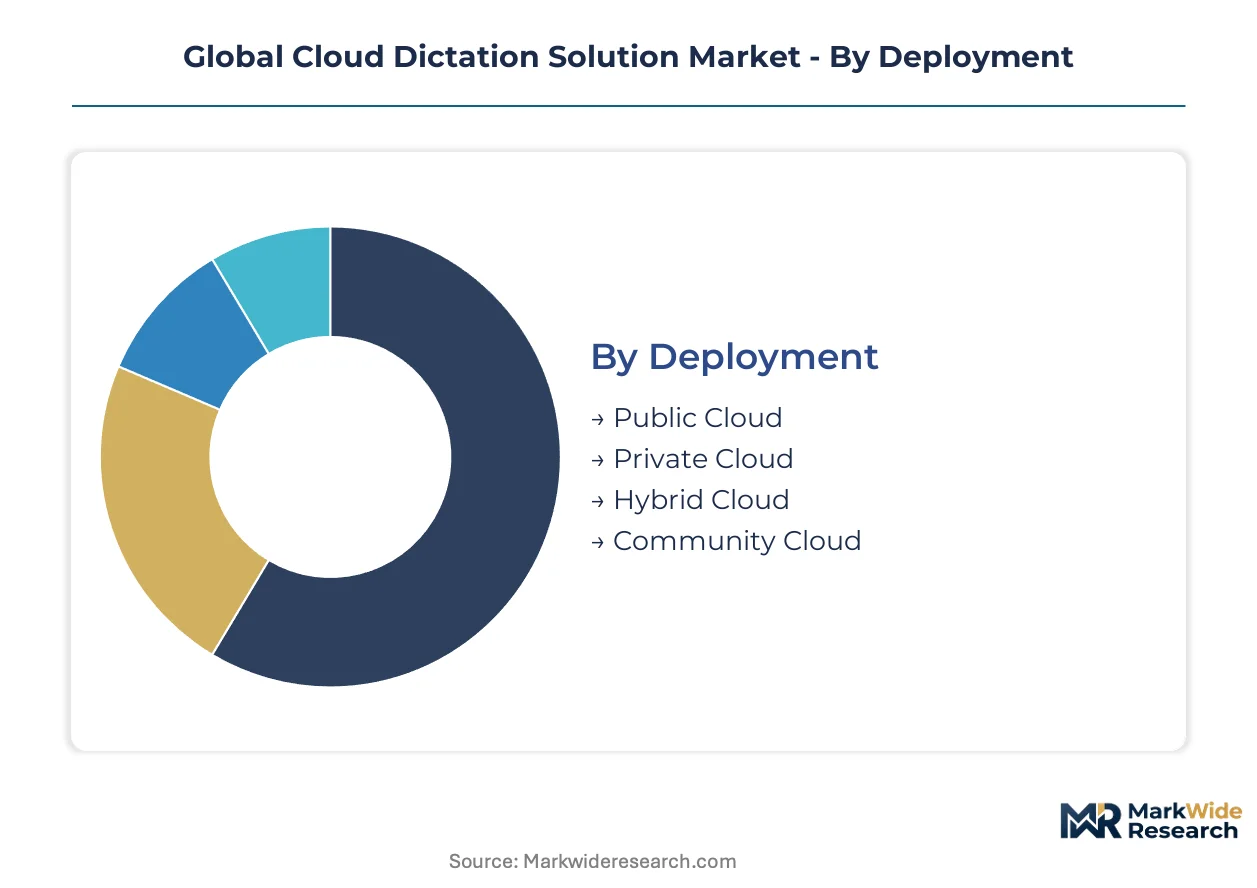
Cloud dictation architectures fragment across deployment models, solution layers, and vertical applications. Procurement patterns diverge sharply between embedded enterprise systems and standalone transcription services. Understanding these segment boundaries clarifies where vendor specialization creates sustainable margin pools.
Deployment:
Integration depth varies dramatically: public and community cloud segments serve standalone use cases with minimal IT dependency, while private and hybrid deployments embed deeply into institutional security architectures.
- Public Cloud:Multi-tenant infrastructure delivers on-demand scaling without capital expenditure. United States health systems with limited IT staff favor this model for rapid deployment of medical documentation tools.
- Private Cloud:Single-tenant environments isolate data flows for regulated workloads. German hospital digitization programs mandate this architecture for patient data sovereignty compliance.
- Hybrid Cloud:Split-inference models process sensitive audio on-premise while leveraging cloud NLP for structured output. Pilot deployments in Netherlands healthcare networks validate this approach for EU AI Act conformity.
- Community Cloud:Shared infrastructure serving specific industry verticals with common compliance requirements. Legal transcription consortia in the United Kingdom utilize this model for cost-pooled security certifications.
Volume placements concentrate in Public Cloud; the faster expansion belongs to Hybrid Cloud.
Solution Offering:
Cost tiering separates commodity transcription engines from premium compliance-layer services, with biometric and analytics modules commanding implementation premiums.
- Speech Recognition:Acoustic modeling engines convert variable sampling rates between 8 kHz and 48 kHz into phonetic sequences. This foundational layer anchors every deployment but faces margin compression from open-source alternatives.
- Natural Language Processing:Clinical corpus fine-tuning transforms raw transcription into structured encounter documentation. United States emergency departments deploy these systems for real-time draft generation during patient visits.
- Voice Biometrics:Speaker identification algorithms fall under EU AI Act high-risk classification. Conformity-assessed vendors capture multi-hospital contracts in France and the Netherlands.
- Audio Analytics:Sentiment and compliance scoring from recorded interactions. Call centers in India deploy these tools for quality assurance automation.
- Language Translation:Real-time multilingual output for cross-border documentation. Media subtitling workflows in Brazil leverage this capability for export content localization.
Revenue concentrates in Natural Language Processing; Voice Biometrics climbs the fastest as regulatory moats thicken.
Application:
Vertical maturity determines whether segments operate as replacement markets or greenfield expansion opportunities, with regulated industries showing stickier vendor relationships.
- Legal Transcription:Court-admissible documentation requires chain-of-custody audit trails. United Kingdom law firms consolidate vendor relationships around outcome-based contracts with turnaround guarantees.
- Medical Documentation:HIPAA security rule and FDA clinical decision support guidance mandate encrypted pipelines. Clinician time recovery drives replacement of traditional transcription service contracts in United States health systems.
- Customer Service Automation:Real-time agent assistance and post-call summarization. Indian BPO operations adopt pay-per-use models to bypass capital barriers.
- Media Subtitling:Automated caption generation with timing synchronization. Broadcasting companies in Australia deploy these tools for live event coverage cost reduction.
- Educational Content Development:Lecture transcription and accessibility compliance. Brazilian universities pilot these systems for remote learning infrastructure.
Contract value concentrates in Medical Documentation; Customer Service Automation expands most quickly in emerging markets.
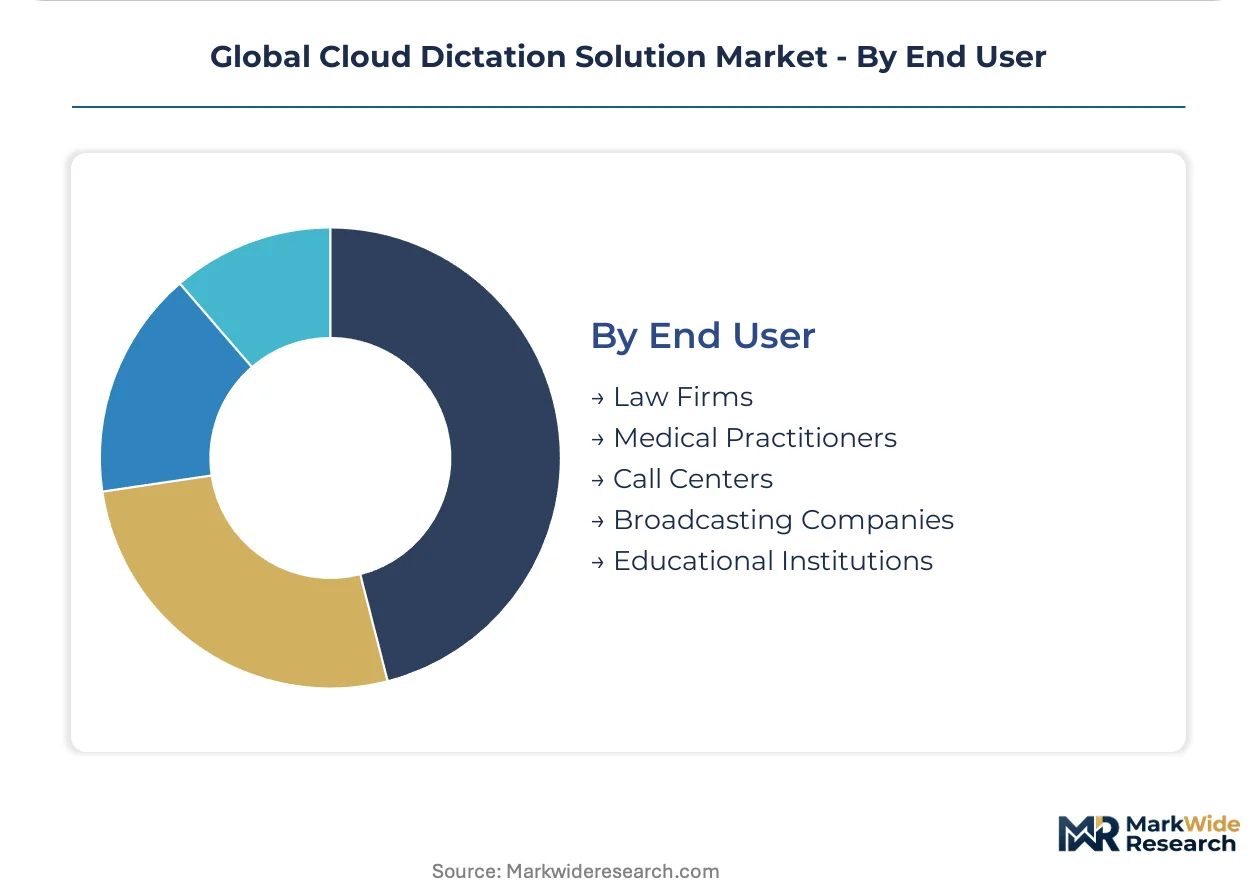
End User:
Customer type dictates procurement sophistication, with enterprise buyers unbundling implementation services while smaller practices accept bundled offerings.
- Law Firms:Partnership structures create fragmented purchasing authority. Mid-size United States practices represent the sweet spot for cloud migration away from legacy dictation hardware.
- Medical Practitioners:Hospital systems and ambulatory networks diverge in integration requirements. German federal procurement frameworks now prioritize cloud-native tools for hospital digitization programs.
- Call Centers:Volume-based pricing with latency-sensitive real-time requirements. Outsourcing hubs in India and the Philippines drive demand for low-cost inference tiers.
- Broadcasting Companies:Live production workflows demand sub-second transcription latency. Australian networks pilot edge-cloud hybrid architectures for sports coverage.
- Educational Institutions:Accessibility mandates and hybrid learning infrastructure. Canadian universities unbundle implementation services from software subscriptions for cost visibility.
Seat count concentrates in Medical Practitioners; Call Centers gain share fastest through outsourcing contract expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GPU fabrication clusters in Taiwan and South Korea supply the specialized inference hardware that powers real-time speech recognition pipelines. Cloud service regions in these localities anchor latency-sensitive medical documentation workloads for Asia-Pacific health systems.
United States
Hospital digitization mandates and clinician burnout reduction programs drive enterprise procurement. FDA clinical decision support software guidance intersects with HIPAA security rule enforcement to mandate encrypted data handling and access logging. Health systems in Boston and the Research Triangle pilot large language model integration for emergency department documentation.
Germany
Federal hospital digitization programs accelerate medical transcription outsourcing contracts. The EU AI Act risk classification system for biometric identification imposes conformity assessment obligations on voice authentication vendors. Hospital networks in Bavaria and North Rhine-Westphalia mandate private cloud architectures for patient data sovereignty compliance.
United Kingdom
Legal transcription consortia consolidate vendor relationships around outcome-based contracts with turnaround time guarantees. The Information Commissioner's Office enforces GDPR-derived accountability requirements for voice data processing. London-based law firms and Manchester legal services clusters drive cloud migration away from legacy dictation hardware.
India
Business process outsourcing hubs demand low-cost inference tiers for call center automation. The country's national data protection authority draft framework signals forthcoming localization requirements for biometric voice data. Bangalore and Hyderabad technology parks host pilot deployments of pay-per-use documentation tools for ambulatory care networks.
Australia
Broadcasting networks pilot edge-cloud hybrid architectures for live sports coverage with sub-second transcription latency. The Therapeutic Goods Administration regulates clinical decision support software with increasing scrutiny. Sydney and Melbourne media production clusters deploy automated caption generation for export content localization.
Global Cloud Dictation Solution Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue ambient clinical intelligence and voice biometric certification. The vendor base stratifies across three maturity levels: legacy transcription service providers, cloud-native platform specialists, and large language model integrators. Two dominant competitive moves define current positioning: strategic partnerships with electronic health record vendors for workflow embedding, and geographic expansion through regional cloud infrastructure deployment to satisfy data sovereignty requirements.
Within the clinical documentation tier, Nuance Communications and 3M Company exemplify entrenched positioning through deep domain specialization. Dolbey Systems occupies a position among hybrid cloud deployment specialists serving regulated industries with complex security architectures. These three anchors represent distinct strategic archetypes: the first leverages longitudinal clinical vocabulary accumulation, the second sustains proprietary acoustic modeling differentiation, and the third emphasizes enterprise-grade deployment flexibility across infrastructure configurations.
| Leading Market Players |
|---|
| Nuance Communications, Inc. |
| 3M Company |
| Dolbey Systems, Inc. |
| Speech Processing Solutions GmbH |
| Voicepoint AG |
| Crescendo Systems Ltd. |
| Arrendale Associates, Inc. |
| SpeechWrite Ltd. |
| Otter.ai Inc. |
| Others |
Supply & Pricing Matrix
Private-equity-backed platform consolidators dominate the vendor landscape, concentrating pricing discipline through subscription standardization while compressing legacy service margins through cloud-native infrastructure economics. Their ownership structures prioritize recurring revenue predictability over transactional project fees, reshaping procurement negotiations across hospital systems and legal transcription departments.
Pricing Analysis
Warranty and implementation service bundling separates premium vendor tiers from unbundled economy offerings. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by EU AI Act certification status and HIPAA audit documentation depth. Price differentiation hinges on acoustic model customization scope and real-time latency guarantees. Cost compression in mid-tier subscriptions intensifies because open-source speech recognition engines commoditize foundational transcription layers. Small physician practices in emerging markets exhibit highest price sensitivity; hospital systems with GPO contracts demonstrate lowest.
Supply Chain Analysis
Freight and data transit costs for GPU cluster provisioning anchor regional pricing variations across Taiwan, South Korea, and United States cloud regions. NVIDIA H100 inference hardware draws from TSMC fabrication facilities in Taiwan and Samsung foundry capacity in South Korea. Supply chain vulnerability centers on single-source dependency for advanced GPU accelerators. Distribution runs through hyperscaler marketplaces and direct enterprise sales channels with regional data residency compliance overlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Large language model integration is displacing traditional transcription service contracts, compressing documentation workflows from hours to minutes and rendering legacy hardware-dependent vendors structurally obsolete.
For Market Incumbents: Deepen clinical vocabulary accumulation through longitudinal EHR data partnerships to defend against ambient intelligence entrants. Accelerate EU AI Act conformity assessment investments to capture restricted procurement tiers in France and Netherlands. Prioritize hybrid cloud deployment flexibility as German hospital digitization programs mandate private infrastructure. For New Entrants and Emerging Players: The premium-economy price gap in medical documentation creates entry opportunity through pay-per-use models targeting ambulatory networks in India and Brazil. Voice biometric certification white space in EU high-risk system classification offers fastest path to contracted revenue. Pursue channel partnerships with regional electronic health record vendors rather than direct enterprise sales. For Investors and Strategic Acquirers: First EU AI Act conformity certificate issuance for voice authentication is the leading indicator that regulatory moat value will crystallize within the analysis window. Target acquisition profiles center on mid-tier platform specialists with hybrid cloud deployment capabilities and existing HIPAA audit documentation. Monitor NVIDIA GPU allocation priority shifts as inflection signal for mid-tier provider margin stress.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Certification | Unlocks restricted procurement in French and Dutch hospital systems requiring high-risk biometric system compliance. |
| Hybrid Cloud Architecture Deployment | Satisfies German federal data sovereignty mandates while preserving cloud NLP scalability for clinical workflows. |
| EHR Workflow Integration Partnership | Embeds transcription capabilities directly into Cerner and Epic documentation modules, reducing switching friction. |
| Voice Biometric Patient Identification | Captures multi-hospital system contracts under EU high-risk classification compliance moat. |
| Edge-Cloud Split Inference Pilot | Validates low-latency clinical documentation for emergency department real-time draft generation use cases. |
Research Methodology
Document review covered FDA clinical decision support guidance, EU AI Act technical documentation requirements, and hospital procurement database records, complemented by interviews with chief medical information officers, health system purchasing committee members, cloud platform engineers, and medical transcription service directors. Secondary validation drew from SEC filings of publicly traded healthcare IT vendors, hyperscaler capex disclosure reports, and German federal digitization program tender documents. Bottom-up deployment estimates triangulated against top-down market sizing across public, private, hybrid, and community cloud architectures.
Model outputs span value and volume projections across deployment model, solution layer, vertical application, and end-user organization size dimensions throughout the forecast period. CAGRs derive from segment-specific adoption curve analysis calibrated against historical EHR penetration patterns and regulatory compliance deadline impacts. Forecast inputs incorporate GPU cluster pricing volatility indices and hospital digitization program budget allocation disclosures.
Underlying measurement precision varies by segment; medical documentation and legal transcription verticals carry tighter precision than emerging educational content applications. Forecasts reflect documented assumptions regarding HIPAA enforcement intensity and EU AI Act implementation timeline adherence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Multi-Cloud Optimization Tools Market
Cloud Computing
Global Server Virtualization Market
Cloud Computing
Cloud Computing Stack Layers Market
Cloud Computing
UK Cloud Backup Market
Cloud Computing
Cloud API and Management Platforms and Middleware Market
Cloud Computing
Cloud IDE Market
Cloud Computing
Consumer Cloud Subscription Market
Cloud Computing
Web Scale IT Market
Cloud Computing
Cloud Calling Market
Cloud Computing
Cloud Orchestration Market
Cloud Computing
Telecom Cloud Market
Cloud Computing
Cloud Migration Services Market
Cloud Computing
Global Public Cloud Service Market
Cloud Computing
Global Cloud Business Email Market
Cloud Computing
Public Cloud in BFSI Market
Cloud Computing
Virtual Machines Market