
 Automotive Cloud Based Solutions Market | 2026-2036
Automotive Cloud Based Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Cloud Based Solutions Market Intelligence
The distinction between basic telematics and AI-powered predictive maintenance platforms is collapsing as automakers embed advanced analytics capabilities directly into vehicle architectures. Amazon Web Services leverages its highly scalable infrastructure to support massive data ingestion from millions of connected vehicles. Microsoft Corporation positions its Azure platform for complex digital twin creation and extensive vehicle simulation use cases. Meanwhile, Bosch differentiates itself through its deep integration of proprietary hardware sensors with cloud-based diagnostic software suites.
Automotive cloud based solutions are off-board computing services that process vehicle-generated data, often leveraging APIs for seamless third-party application integration. These sophisticated platforms enable functions like over-the-air (OTA) software updates, remote vehicle diagnostics, and personalized infotainment services. Hybrid cloud deployments are gaining favor with OEMs who need to balance sensitive data security with public cloud scalability and cost-effectiveness. Among solution offerings, fleet management generates consistent revenue streams, while infotainment is a critical battleground for consumer-facing brand differentiation.
Data sovereignty and privacy rules, such as the EU's General Data Protection Regulation (GDPR) and China's Cybersecurity Law, dictate where and how sensitive vehicle data can be stored and processed. Concurrently, evolving guidelines from bodies like the U.S. National Highway Traffic Safety Administration (NHTSA) on vehicle cybersecurity are shaping platform architecture and security protocols. The critical strategic decision for automakers and their Tier-1 suppliers is whether to build proprietary cloud platforms or deepen partnerships with established hyperscale providers.
Market Dynamics
The central structural force shaping the automotive cloud market is the strategic dilemma facing OEMs: whether to build proprietary, brand-differentiating cloud platforms or deepen partnerships with hyperscale providers to accelerate time-to-market and manage costs amid complex data sovereignty rules.
Growth Catalysts
- Fleet Management Adoption:The commercial logistics sector's drive for operational efficiency and lower total cost of ownership accelerates the deployment of cloud-based telematics for route optimization, fuel management, and driver behavior monitoring.
- 5G Network Proliferation:Expanding 5G infrastructure enables the high-bandwidth, low-latency communication required for advanced functionalities like vehicle-to-everything (V2X) communication, high-definition map streaming, and large-scale over-the-air (OTA) software updates.
- Regulatory Compliance:Mandates such as the EU's General Data Protection Regulation (GDPR) create demand for sophisticated cloud solutions that can manage data consent, ensure privacy, and support regional data storage requirements.
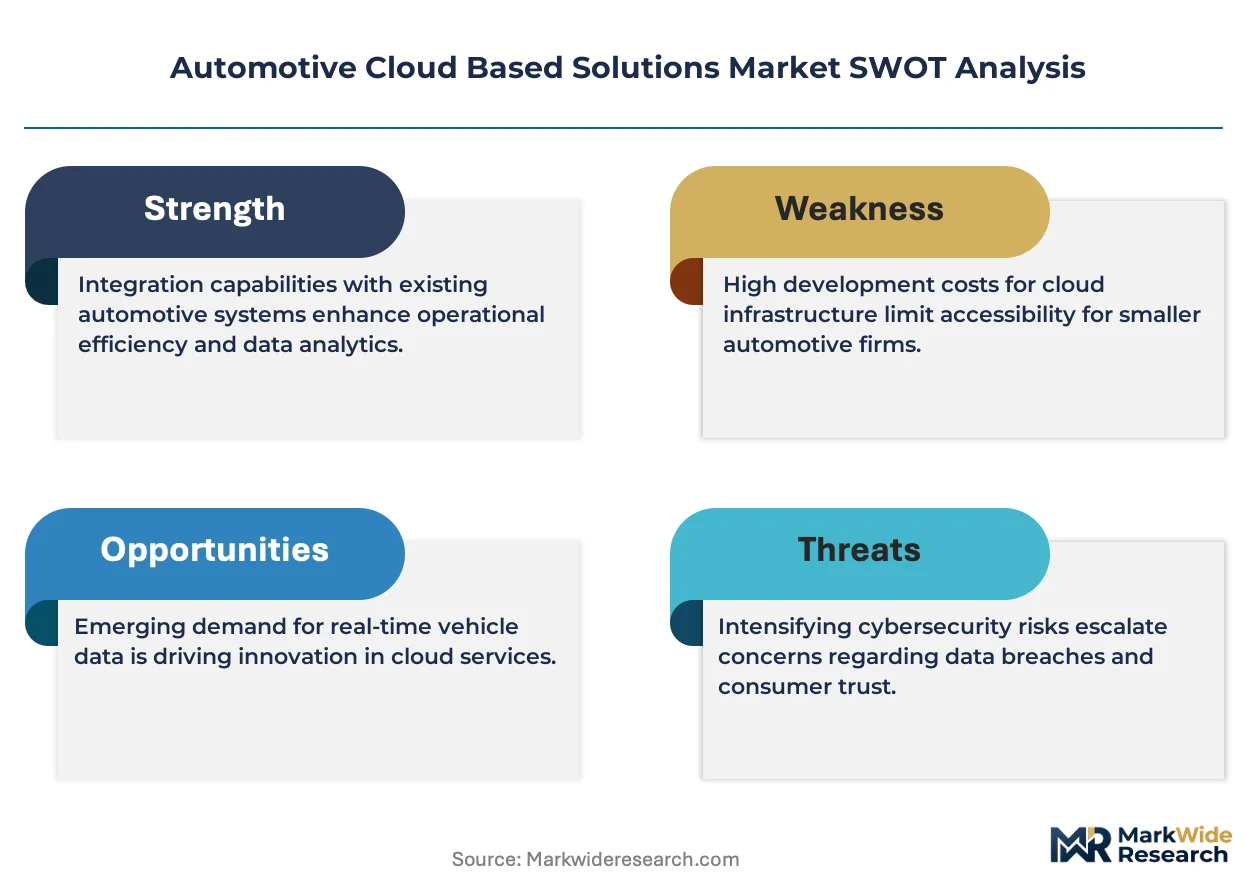
Market Restraints
- Data Format Standardization Gaps:A lack of universal standards for vehicle-generated data formats across different original equipment manufacturers (OEMs) creates significant integration complexity and raises costs for third-party application developers.
- Data Sovereignty Laws:Strict data localization rules, exemplified by China's Cybersecurity Law, force global automakers to develop region-specific cloud architectures, fragmenting their global platforms and increasing operational overhead.
- High Infrastructure Costs:The significant capital expenditure required to build and maintain secure, scalable, and resilient hybrid cloud environments presents a substantial financial barrier, particularly for smaller automakers or Tier-1 suppliers.
Strategic Opportunities
- Insurance Telematics Services:The growth of usage-based insurance (UBI) models creates an opportunity for cloud platforms to provide insurers with verified driving data, enabling new revenue streams for automakers through data monetization partnerships.
- Digital Twin Simulation:The convergence of AI and cloud computing allows for the creation of sophisticated digital twins of entire vehicles, enabling extensive virtual testing and validation of new software features before deployment.
- Emerging Market Penetration:Developing automotive markets, such as India and Brazil, represent significant growth potential as connected car features transition from luxury options to standard offerings in mass-market vehicles.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of software engineers and data scientists who possess dual expertise in both automotive engineering principles and enterprise-grade cloud security protocols hinders platform development and innovation.
- Legacy System Integration:Integrating modern cloud services with automakers' and dealerships' entrenched legacy IT systems and older vehicle electronic architectures proves to be a complex, costly, and time-consuming operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Cloud Based Solutions Market |
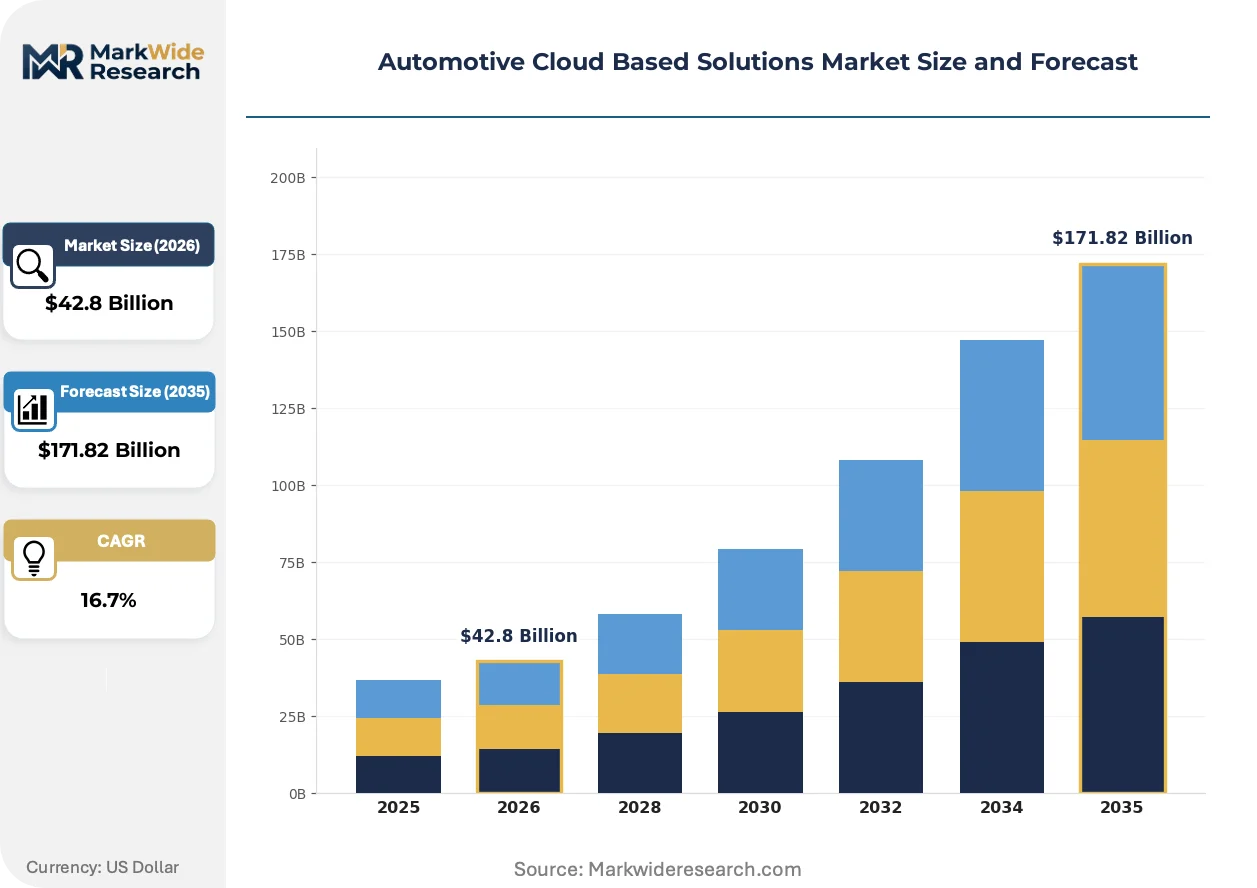
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $171.82 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud, Community Cloud Solution Offering: Fleet Management, Telematics, Vehicle Diagnostics, Infotainment, Navigation Systems Use Case: Predictive Maintenance, Remote Monitoring, Driver Behavior Analysis, Route Optimization, Vehicle Security End User Type: OEMs, Tier-1 Suppliers, Dealerships, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Amazon Web Services, Microsoft Corporation, Google LLC, Continental AG, Denso Corporation, BlackBerry, Bosch, Ericsson, Verizon Wireless, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Cloud Based Solutions Market Strategic Shifts & Innovations
The evolution of the vehicle into a software-defined platform, where functionality is continuously updated via the cloud, is fundamentally altering automotive value chains. This shift prioritizes software development capabilities and data management as core competitive differentiators for automakers.
Edge computing hardware provides on-board processing to analyze sensor data locally within the vehicle. Automakers are rapidly adopting these powerful processors to reduce latency for critical advanced driver-assistance systems (ADAS) and autonomous driving functions. This technology trend is miniaturizing the platform's reliance on continuous cloud connectivity for time-sensitive decisions, creating a more resilient and responsive distributed computing architecture.
Evolving cybersecurity guidelines from the U.S. National Highway Traffic Safety Administration (NHTSA) are influencing platform design. These recommendations compel automakers to implement more rigorous security measures, such as end-to-end encryption and intrusion detection systems, for all vehicle-to-cloud communications. The over-the-air (OTA) update and remote diagnostics segments are most affected, requiring a security-first approach throughout the software development lifecycle.
A significant behavioral shift is the consumer expectation for an in-car experience that mirrors the seamless, personalized ecosystem of their smartphones. This disrupts the traditional OEM model of static, factory-installed infotainment systems, creating demand for platforms that support third-party application stores and personalized user profiles. This trend is most prominent in the premium vehicle segments of Germany and the United States.
Automotive Cloud Based Solutions Market Segmentation
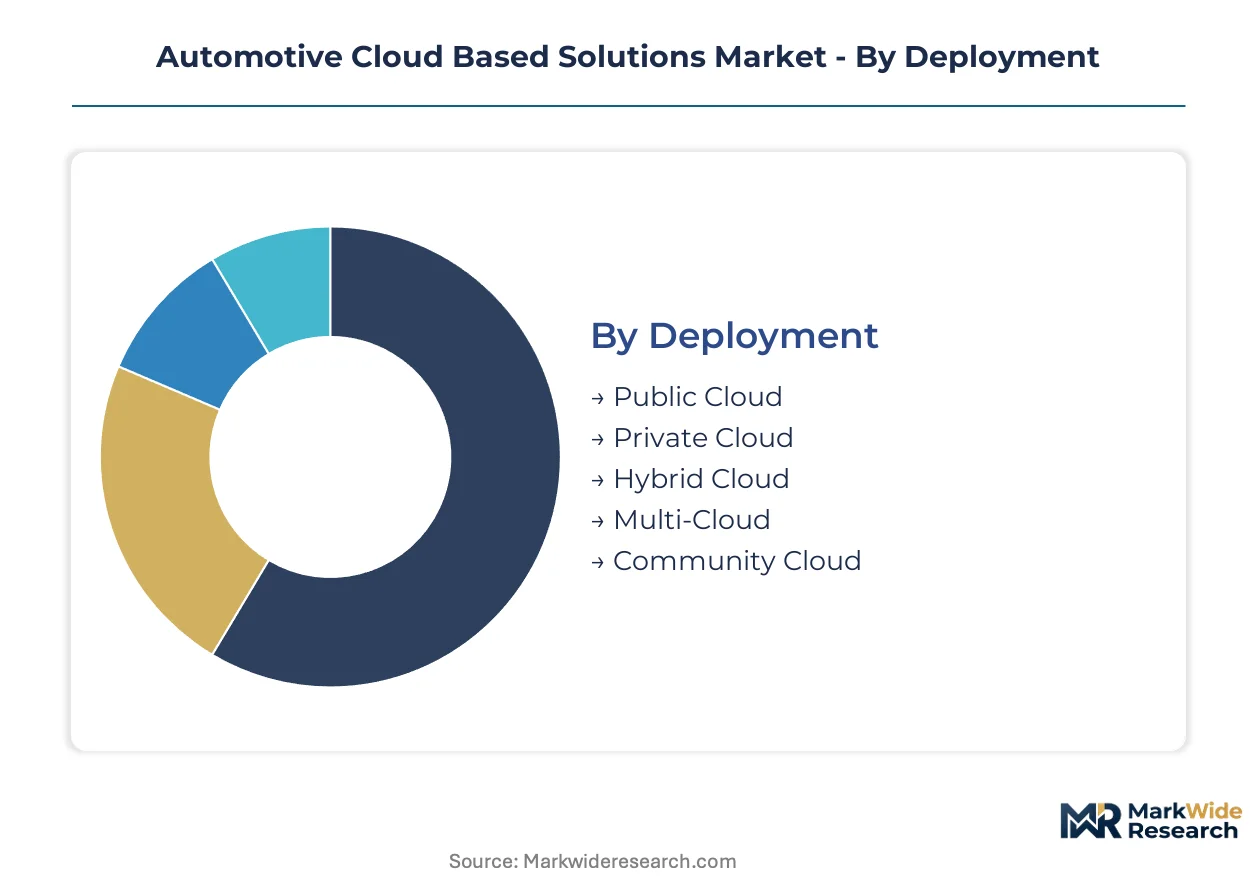
Understanding the Automotive Cloud Based Solutions Market through segmentation reveals critical structural forces shaping its evolution. This analysis highlights distinct technology adoption patterns, varied solution demands, and the diverse strategic priorities across different end-user groups. Market dynamics are driven by specific needs within each segment.
Deployment:
Margin pools within the deployment category concentrate around hybrid cloud solutions, balancing security with scalability for automotive applications.
- Hybrid Cloud:This model integrates on-premises private cloud infrastructure with public cloud services, orchestrating workloads between environments. Demand is high among OEMs in Germany and the United States, driven by the need to secure sensitive vehicle data.
- Public Cloud:Public cloud services are delivered over the internet by third-party providers, offering massive scalability and operational flexibility. Its adoption accelerates for less sensitive data processing and infotainment in markets like Japan.
- Private Cloud:Dedicated cloud infrastructure serves a single organization, providing enhanced control and security. Automakers use private clouds for mission-critical applications.
- Multi-Cloud:Utilizing multiple public cloud providers simultaneously mitigates vendor lock-in and optimizes specific service offerings. This strategy gains traction for resilience.
- Community Cloud:Shared cloud infrastructure supports a specific community with common concerns, such as security. This model applies among consortiums or industry-specific groups.
Public Cloud holds installed capacity. Hybrid Cloud is rotating up the share rankings.
Solution Offering:
The solution offering category is segmented by its primary application focus within the automotive ecosystem.
- Fleet Management:These solutions provide tools for monitoring, managing, and optimizing commercial vehicle fleets, including route optimization and fuel efficiency tracking. Demand is consistently high in the commercial logistics sector across the United States, driven by operational efficiency.
- Infotainment:Infotainment systems deliver personalized media, navigation, and connectivity services directly to vehicle occupants. This segment is a critical battleground for consumer-facing brand differentiation in premium vehicle segments in Germany.
- Telematics:Telematics encompasses vehicle tracking, emergency assistance, and remote diagnostics through integrated communication technologies.
- Vehicle Diagnostics:These services remotely monitor vehicle health, identify malfunctions, and predict maintenance needs using cloud-based analytics.
- Navigation Systems:Cloud-connected navigation offers real-time traffic updates, dynamic routing, and location-based services.
Fleet Management maintains consistent revenue streams. Infotainment solutions are gaining share fastest among consumer-facing applications.
Use Case:
This category delineates solutions based on the specific operational challenges or customer needs they address.
- Predictive Maintenance:This use case leverages AI and machine learning to forecast equipment failures before they occur, optimizing vehicle uptime and reducing repair costs. Automakers and fleet operators in Japan adopt these platforms to enhance vehicle reliability.
- Route Optimization:Cloud-based algorithms analyze traffic, weather, and delivery schedules to determine the most efficient routes for commercial vehicles. This capability is critical for logistics companies in India, minimizing fuel consumption and delivery times.
- Remote Monitoring:Real-time tracking of vehicle location, status, and performance provides oversight for fleet managers and enhances security.
- Driver Behavior Analysis:Systems analyze driving patterns to improve safety, identify training needs, and reduce insurance premiums.
- Vehicle Security:Cloud solutions enable features like remote locking, vehicle tracking after theft, and cybersecurity threat detection.
Remote Monitoring remains a foundational use case. Predictive Maintenance is exhibiting rapid expansion.
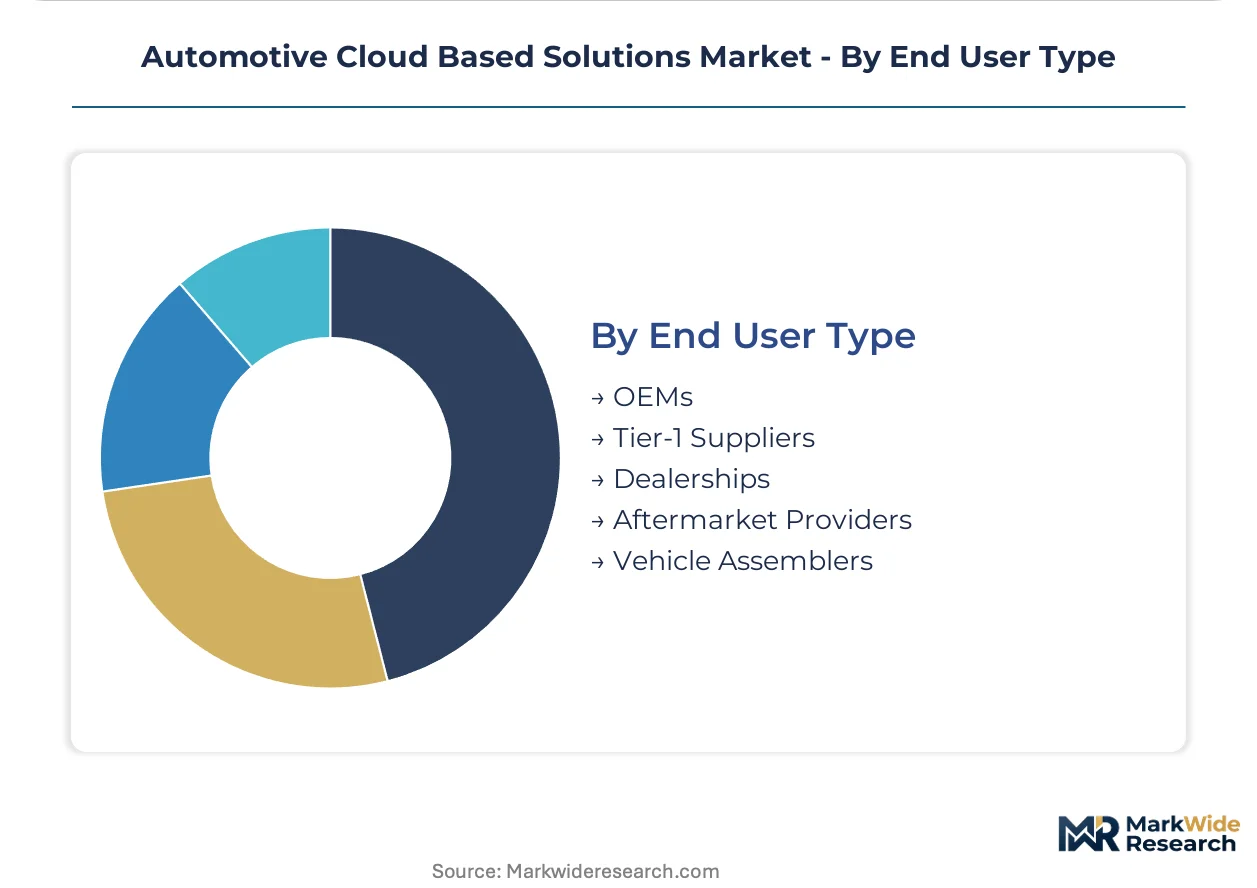
End User Type:
The end-user type category highlights where strategic decision-making and influence over cloud solution adoption are concentrated.
- OEMs:Original Equipment Manufacturers integrate cloud solutions directly into vehicle design and manufacturing processes, often developing proprietary platforms or partnering with hyperscalers. Their strategic decisions in Germany and the United States dictate broad market adoption.
- Tier-1 Suppliers:These suppliers provide major sub-assemblies and systems to OEMs, incorporating cloud-enabled components like advanced telematics units or sensor suites. Their integration capabilities are vital for delivering complex cloud functionalities.
- Dealerships:Dealerships utilize cloud solutions for customer relationship management, inventory tracking, and remote diagnostic services for vehicle maintenance.
- Aftermarket Providers:These entities offer cloud-based services and devices for vehicles post-sale, including telematics dongles and diagnostic tools.
- Vehicle Assemblers:Assemblers focus on the physical construction of vehicles, leveraging cloud solutions for manufacturing optimization and supply chain management.
OEMs drive initial platform development. Aftermarket Providers are climbing fastest in solution integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentration in automotive cloud solutions gravitates towards regions with strong automotive manufacturing bases and advanced digital infrastructure. These areas drive both the supply of sophisticated platforms and the demand for connected vehicle services. Key economies such as the United States, Germany, and Japan anchor significant development and deployment.
United States
Demand for fleet management solutions and advanced infotainment services drives cloud adoption. The U.S. National Highway Traffic Safety Administration (NHTSA) guides cybersecurity protocols for vehicle-to-cloud communications. Silicon Valley and Detroit are centers for software development and integration into vehicle architectures.
Germany
OEMs in Germany prioritize hybrid cloud deployments for sensitive vehicle data and premium infotainment. The EU's General Data Protection Regulation (GDPR) mandates strict data privacy and storage requirements. Munich and Stuttgart feature robust automotive R&D hubs focusing on digital twin creation and predictive maintenance.
Japan
Predictive maintenance platforms and public cloud adoption for less sensitive data processing are key drivers. The Ministry of Economy, Trade and Industry (METI) supports initiatives for connected car data utilization. Tokyo and Nagoya concentrate automotive electronics suppliers and cloud service integrators.
China
The vast automotive market generates demand for localized cloud solutions, particularly for fleet management. China's Cybersecurity Law dictates strict data localization and processing rules for vehicle data. Shanghai and Beijing are emerging as centers for smart mobility platforms and autonomous driving development.
India
Route optimization for commercial logistics and emerging market penetration for connected features fuel cloud growth. The Indian government's "Digital India" initiative promotes digital infrastructure expansion. Bengaluru and Chennai are developing as software and automotive manufacturing hubs.
Automotive Cloud Based Solutions Market Key Industry Players
Concentration sits with hyperscale cloud providers and established automotive technology companies. The market structure exhibits a tiered approach, with major tech firms offering foundational infrastructure and automotive players building specialized applications on top. Several strategic archetypes emerge, including infrastructure giants, automotive software specialists, and integrated hardware-software solution providers. Key competitive moves involve deepening strategic partnerships between technology firms and automakers, alongside portfolio diversification into analytics and AI-driven services.
Hyperscale cloud providers like Amazon Web Services and Microsoft Corporation exemplify the foundational layer, offering highly scalable infrastructure and advanced analytics capabilities for automotive data. Google LLC also occupies a significant position, providing robust cloud services and AI-driven solutions tailored for connected vehicles. These technology companies enable the massive data ingestion and processing required for modern automotive cloud solutions. Their offerings support diverse use cases, ranging from complex digital twin creation and extensive vehicle simulation to remote diagnostics and over-the-air updates.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Corporation |
| Google LLC |
| Continental AG |
| Denso Corporation |
| BlackBerry |
| Bosch |
| Ericsson |
| Verizon Wireless |
Cost & Logistics Intelligence
The migration from dedicated on-premise hardware to flexible cloud computing services reshapes both the geographic distribution of processing power and the underlying pricing models for automotive software. This fundamental substitution drives new value propositions and cost structures across the ecosystem.
Pricing Analysis
The EU's General Data Protection Regulation (GDPR) dictates the pricing tier structure for data storage and processing, particularly for sensitive vehicle data. Automotive cloud solutions primarily utilize a SaaS-tiered subscription model, with price differentiation stemming from customization levels for OEMs and the bundling of after-sales support services. Pricing softness emerges from intense competition among hyperscale providers seeking to capture enterprise workloads. Aftermarket providers exhibit the highest price sensitivity, while large OEMs demonstrate less flexibility due to proprietary platform integration needs.
Supply Chain Analysis
Just-in-time provisioning of cloud resources, rather than strategic stockpiling of physical hardware, characterizes the automotive cloud supply chain. Core infrastructure components like high-performance servers and networking hardware originate from concentrated hubs in the United States, Taiwan, and China. Data sovereignty laws, such as China's Cybersecurity Law, introduce significant structural risk by fragmenting global platforms. Distribution runs directly to OEMs and Tier-1 suppliers, often facilitated through API-driven integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a significant fragmentation opportunity, driven by the consumer demand for highly personalized in-car experiences that mirror smartphone ecosystems. This behavioral shift creates numerous niches for specialized cloud-based applications and services.
For Market Incumbents:Fortify core platform capabilities by deepening strategic partnerships with hyperscale providers like Amazon Web Services and Microsoft Corporation. Invest heavily in proprietary cybersecurity measures to counter evolving threats and comply with regulations like NHTSA guidelines. The persistent scarcity of specialized cloud and automotive software talent represents a significant threat. Leverage R&D into AI-driven predictive maintenance platforms to differentiate offerings.
For New Entrants and Emerging Players:Integration complexity with automakers' legacy IT systems represents a significant service-layer gap where incumbents under-serve. Target specialized data analytics solutions for smaller commercial fleets and niche personalized infotainment applications. The aftermarket provider segment in emerging markets like India offers the most penetrable entry point. An API-first development approach enables seamless third-party application integration, accelerating market adoption.
For Investors and Strategic Acquirers:The market sits at an early growth phase that favors vertically integrated software specialists with deep automotive domain expertise. Long-term viability remains strong, projecting high growth over the next decade as connected car features become ubiquitous. Target acquisition profiles include firms with proven AI/ML capabilities for advanced digital twin creation and predictive analytics. A key signal to watch is the broader industry adoption of standardized vehicle data formats, indicating reduced integration friction.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces integration complexity for OEMs and third-party developers across diverse vehicle architectures. |
| Cybersecurity Protocol Development | Builds essential trust for secure vehicle-to-cloud communications and OTA updates under NHTSA guidelines. |
| AI-powered Predictive Maintenance Investment | Optimizes vehicle uptime and reduces operational costs for fleet operators and individual consumers. |
| Hybrid Cloud Architecture Adoption | Balances sensitive data security requirements with public cloud scalability for global automotive deployments. |
| 5G V2X Integration | Enables high-bandwidth, low-latency communication crucial for advanced driver-assistance systems and autonomous driving. |
Research Approach
A spread of perspectives from OEM platform engineers, Tier-1 software architects, commercial fleet managers, and cloud service integrators converged on the working assumptions for this analysis. This involved combining insights from primary interviews with extensive secondary validation from sources like SEC 10-K filings, vehicle production databases, and government cybersecurity reports. The study employed a rigorous bottom-up and top-down triangulation approach to ensure data consistency.
Deployment model, solution offering, use case, end-user type, and regional adoption patterns formed the core segmentation dimensions modeled across the analysis window. The analytical framework integrated historical growth trends with projected technological roadmaps and regulatory impacts to derive compound annual growth rates. Forecast inputs included connected vehicle penetration rates and global 5G network rollout schedules.
Forecasts assume regulatory continuity in the EU, US, and China; material policy shifts in data privacy or cybersecurity would require re-modeling. Unforeseen major cybersecurity breaches or rapid technological obsolescence of current cloud architectures represent key risk factors. Revision becomes warranted when new, disruptive V2X communication standards emerge.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Community Cloud Market
Cloud Computing
Nigeria Cloud Computing Market
Cloud Computing
Hybrid Cloud Services Market
Cloud Computing
Cloud Backup Market
Cloud Computing
Cloud Data Quality Monitoring Market
Cloud Computing
Cloud Banking Solutions Market
Cloud Computing
United States Cloud Computing Market
Cloud Computing
Latin America Cloud Computing Market
Cloud Computing
Global Marketing Cloud Platform Market
Cloud Computing
Multi-Cloud Optimization Tools Market
Cloud Computing
Asia Pacific Cloud Computing Market
Cloud Computing
Global Cloud Office Services Market
Cloud Computing
Global Mobile Cloud Market
Cloud Computing
Cloud Identity Management Market
Cloud Computing
Global Cloud Migration Market
Cloud Computing
Public Cloud Application Infrastructure Services Market