
 Cloud Management Platform Market | 2026-2036
Cloud Management Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Management Platform Market Analysis
Platform licensing revenue is narrowing as vendors shift toward recurring service models. VMware sustains technology leadership through deep integration with enterprise virtualization stacks. IBM anchors its position via Red Hat's OpenShift hybrid cloud orchestration capabilities.
A cloud management platform is a software framework that aggregates provisioning, monitoring, cost optimization, and policy governance across distributed infrastructure environments, typically supporting API-driven automation and role-based access control at sub-second response thresholds. Its primary purpose is to enable enterprises to operate workloads consistently across heterogeneous cloud estates without sacrificing visibility or compliance. Hybrid cloud deployment configurations command the widest addressable base as organizations retain on-premises assets while expanding public cloud consumption. Security management solutions within the platform stack carry the strongest margin profile due to mandatory audit requirements and zero-trust architecture mandates.
The EU AI Act, GDPR, and ISO 27001 standards collectively shape product roadmaps by mandating explainable automation, data residency controls, and certified security management frameworks. The US Federal Risk and Authorization Management Program and SEC cybersecurity disclosure rules impose additional compliance layers on vendors serving regulated industries. Stakeholders must evaluate whether their current tooling chains can absorb emerging sovereign cloud requirements without fragmenting operational workflows.
Market Dynamics
Multi-cloud governance complexity is compressing vendor consolidation timelines as enterprises demand unified control planes spanning on-premises, public, and sovereign cloud estates. The EU AI Act's explainability mandates and GDPR data residency requirements are forcing platform architectures toward policy-as-code automation.
Growth Catalysts
- EU AI Act compliance automation:Financial services firms in Frankfurt and Paris are deploying explainable AI governance modules to satisfy algorithmic accountability requirements. Automated policy enforcement reduces manual audit preparation by standardizing documentation workflows.
- Hybrid workload migration:US healthcare systems are transferring electronic health records from legacy data centers to orchestrated multi-cloud environments. HIPAA-compliant encryption management drives demand for unified key lifecycle platforms.
- FinOps tooling integration:Kubernetes-native cost visibility is virtualizing chargeback processes for platform engineering teams. Real-time spend attribution aligns cloud consumption with departmental budgets.
Market Restraints
- Specialized talent scarcity:Certified cloud architects with multi-platform policy engineering skills command premium compensation. Training pipelines cannot satisfy enterprise demand for ISO 27001 auditors with infrastructure-as-code expertise.
- API dependency concentration:Hyperscaler control plane outages in US East and US West regions cascade through third-party management layers. Vendor-specific SDK fragmentation complicates failover architecture design.
- On-premises sunk cost inertia:Capitalized virtualization investments in enterprise data centers delay full-stack cloud migration decisions. Amortization schedules extend hardware refresh cycles beyond platform contract terms.
Strategic Opportunities
- Sovereign cloud expansion in France:ANSSI-certified providers are building Gaia-X compliant infrastructure for defense and public sector workloads. Data localization requirements exclude non-EU control plane operators from sensitive procurement.
- Edge-to-cloud orchestration convergence:5G network slicing and containerized micro-datacenters are merging operational technology monitoring with centralized governance. Manufacturing facilities in Stuttgart and Toyota City pilot unified visibility stacks.
- SEC cybersecurity disclosure rules:Material incident reporting mandates are accelerating board-level investment in continuous compliance dashboards. Automated evidence collection satisfies quarterly attestation requirements.
Industry Challenges
- Legacy identity system entanglement:Active Directory forests with decades of nested group policies resist seamless federation with cloud-native IAM. Migration projects stall on privilege recertification workflows.
- Cross-cloud network topology complexity:MPLS and SD-WAN configurations fragment connectivity visibility between AWS, Azure, and private infrastructure. Troubleshooting latency requires specialized multi-vendor expertise.
- Certificate lifecycle automation gaps:Shortened TLS validity periods strain manual renewal processes. Expired certificates trigger cascading service outages in interconnected microservice architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Management Platform Market |
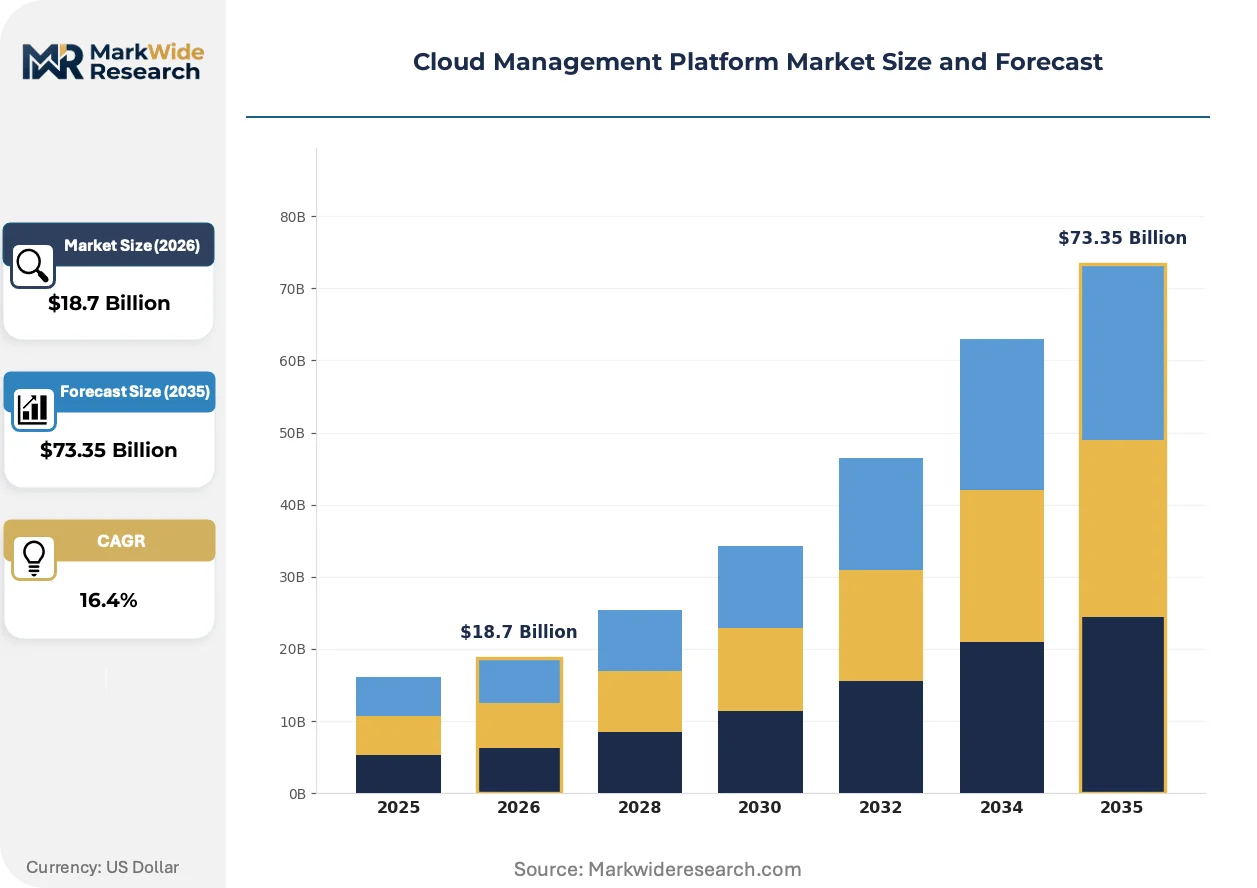
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution: Cost Management, Performance Monitoring, Security Management, Automation End User: IT Services, Financial Services, Healthcare, Educational Institutions Service Type: Consulting, Integration, Support, Training |
| Companies Covered | CloudBolt, VMware, Holori, Flexera, IBM, Red Hat, Nutanix, CloudHealth, Morpheus Data, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Management Platform Market Emerging Trajectories
Policy-as-code automation is virtualizing governance enforcement across heterogeneous infrastructure estates. This shift compresses audit cycles and enables real-time compliance posture verification.
Software-defined perimeter technology is virtualizing network access control for distributed workforces. Large pharmaceutical manufacturers in Basel and Boston are replacing VPN concentrators with identity-aware proxy architectures. Zero-trust segmentation is virtualizing east-west traffic inspection inside container clusters.
REACH chemical safety documentation and the EU AI Act's risk classification system are converging compliance data models. Industrial software vendors must embed substance traceability alongside algorithmic impact assessments. Medical device manufacturers in Ireland and the Netherlands face dual reporting obligations to ECHA and notified bodies.
Platform engineering teams are consolidating procurement authority previously dispersed across infrastructure, security, and finance functions. Centralized internal marketplaces with pre-approved service catalogs are displacing direct cloud console access. This concentration is most visible among Fortune 500 enterprises in Texas and California streamlining vendor relationships.
Cloud Management Platform Market Segmentation
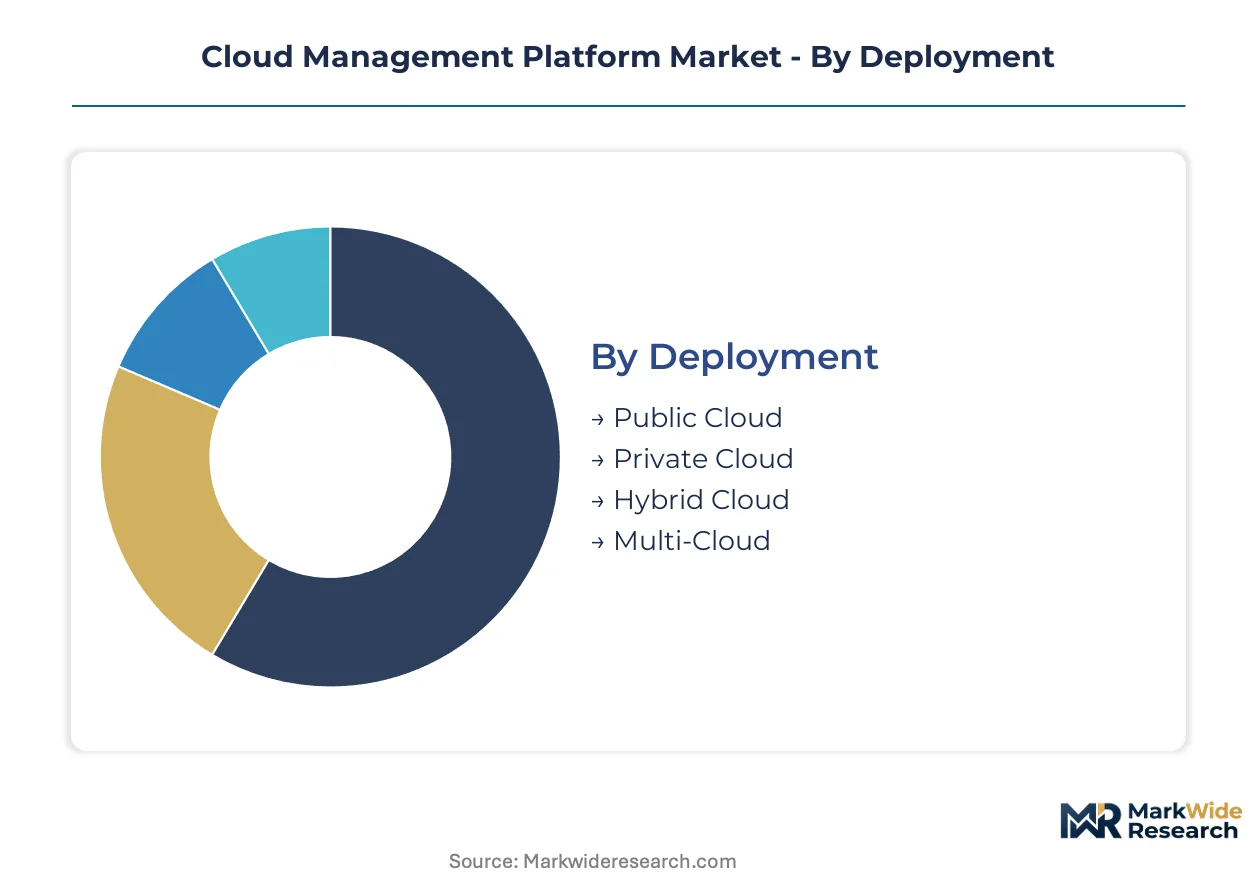
Cloud management platform architectures must map precisely to infrastructure topology, regulatory exposure, and operational maturity. Segmentation reveals where governance complexity concentrates and which deployment patterns absorb premium tooling investment.
Deployment:
Enterprises select deployment modes based on data sovereignty requirements, latency constraints, and existing virtualization commitments across their compute estates.
- Public Cloud:Native API integration with hyperscaler control planes enables rapid provisioning without capital expenditure. Financial services firms in Singapore and Sydney deploy public cloud management layers for non-sensitive development environments, though GDPR data residency rules constrain EU workload placement.
- Private Cloud:Dedicated infrastructure with tenant-isolated orchestration stacks satisfies classified workload requirements. Defense contractors in Arlington and Canberra mandate private cloud management for systems processing security-cleared information, driving demand for air-gapped policy enforcement engines.
- Hybrid Cloud:Unified control planes spanning on-premises virtualization and public cloud resources. US healthcare systems in Nashville and Cleveland orchestrate electronic health records across hybrid estates to maintain HIPAA-compliant encryption boundaries.
- Multi-Cloud:Cross-platform governance spanning AWS, Azure, Google Cloud, and sovereign alternatives. German automotive manufacturers in Stuttgart and Wolfsburg deploy multi-cloud management to avoid single-vendor lock-in while satisfying EU AI Act algorithmic accountability mandates.
Established volume favors Hybrid Cloud; emerging adoption favors Multi-Cloud.
Solution:
Functional modules align with distinct operational pain points—cost visibility, reliability assurance, compliance enforcement, and velocity acceleration.
- Cost Management:FinOps tooling with Kubernetes-native chargeback and reserved instance optimization. Platform engineering teams at Fortune 500 enterprises in Texas virtualize departmental budget attribution through real-time spend dashboards.
- Performance Monitoring:Distributed tracing and infrastructure telemetry with sub-second alerting thresholds. E-commerce operators in Seattle and London prioritize performance modules to maintain transaction latency SLAs during demand spikes.
- Security Management:Zero-trust segmentation with automated certificate lifecycle and secrets rotation. This segment carries the strongest margin profile due to mandatory audit requirements and ISO 27001 certification workflows.
- Automation:Policy-as-code orchestration with infrastructure-as-code pipeline integration. CI/CD-native automation is climbing the fastest as platform engineering teams displace manual provisioning workflows.
Security Management commands premium pricing; Automation is gaining share fastest.
End User:
Vertical-specific compliance regimes and workload characteristics reshape platform requirements across buyer categories.
- IT Services:Multi-tenant management with client-isolated governance boundaries. Managed service providers in Bangalore and Dublin aggregate platform licensing across hundreds of downstream customers.
- Financial Services:Algorithmic accountability tooling for EU AI Act compliance and SEC cybersecurity disclosure. Frankfurt and Paris banks deploy explainable AI governance modules to satisfy regulatory audit preparation.
- Healthcare:HIPAA-compliant encryption management with unified key lifecycle platforms. Hospital systems in Boston and Houston migrate electronic health records to orchestrated cloud environments.
- Educational Institutions:Cost-optimized research computing with grant-attributed spend tracking. Universities in California and Massachusetts prioritize cost management modules for NSF and NIH workload accounting.
Financial Services drives premium module adoption; Educational Institutions represent price-sensitive volume.
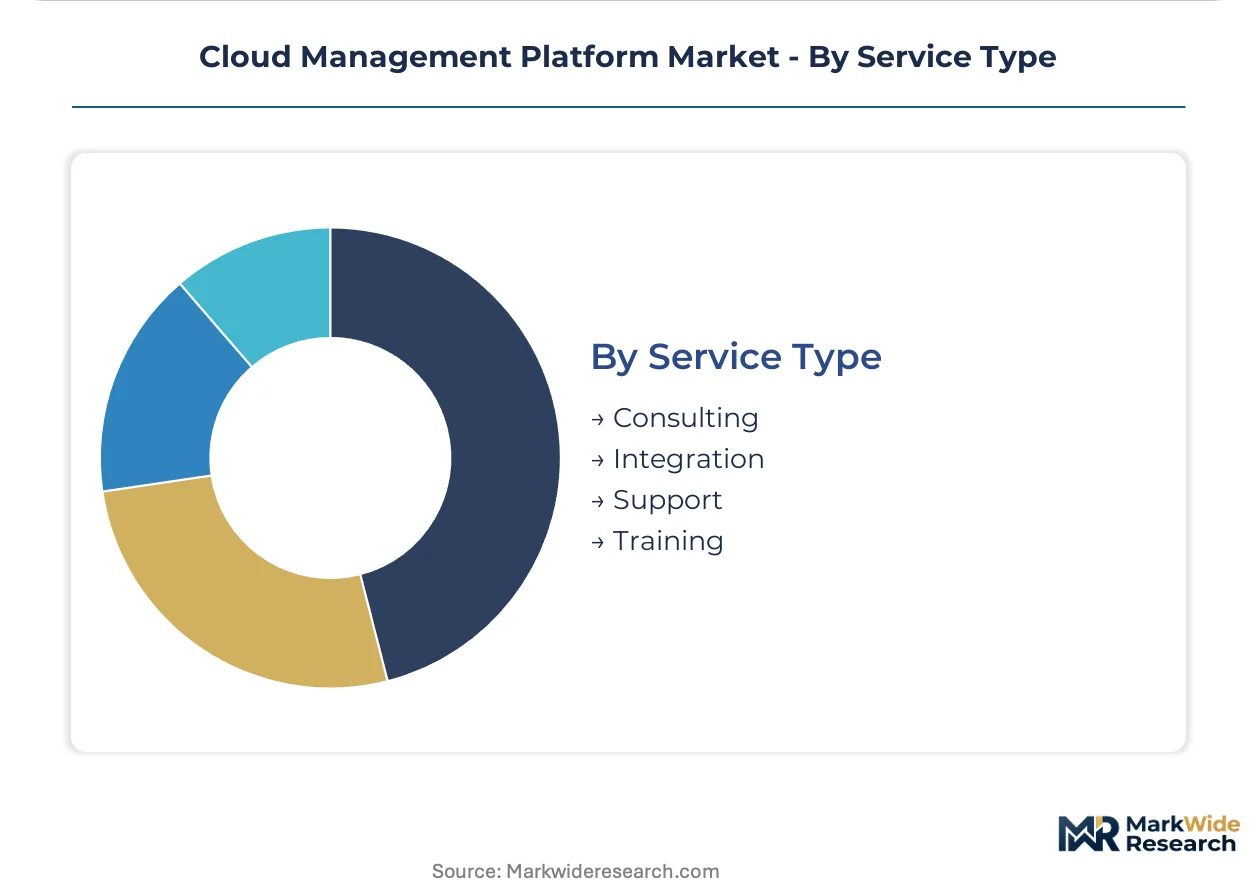
Service Type:
Professional services attach rates correlate with deployment complexity and internal platform engineering maturity.
- Consulting:Architecture design and multi-cloud governance strategy. Enterprises in Chicago and Munich engage consultants for Active Directory federation and legacy identity system migration.
- Integration:Control plane deployment with existing ITSM and SIEM toolchain connectivity. Integration services expand most quickly as fragmented monitoring stacks consolidate.
- Support:Tiered response with escalation paths to vendor engineering. Manufacturing facilities in Toyota City and Stuttgart demand 24/7 support for edge-to-cloud orchestration stacks.
- Training:Certification programs for platform engineering and policy-as-code development. Training revenue concentrates where certified cloud architect scarcity drives internal upskilling investment.
Consulting anchors project-based revenue; Integration exhibits steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud management platform vendors concentrate engineering resources near hyperscaler availability zones and enterprise data center clusters. The United States absorbs the largest share of platform deployment spend, followed by Germany and Japan where manufacturing digitization drives hybrid orchestration demand. Regulatory fragmentation across jurisdictions forces multi-region compliance architecture.
United States
Financial services firms in New York and Chicago deploy multi-cloud governance tools to satisfy SEC cybersecurity disclosure rules. HIPAA-compliant encryption management propels healthcare systems in Nashville toward unified key lifecycle platforms. Texas-based Fortune 500 enterprises consolidate procurement authority through centralized internal marketplaces with pre-approved service catalogs.
Germany
Automotive manufacturers in Stuttgart and Wolfsburg mandate algorithmic accountability tooling to satisfy EU AI Act requirements. The Gaia-X initiative excludes non-EU control plane operators from defense and public sector procurement. Industrial software vendors in Munich embed policy-as-code automation to virtualize governance enforcement across heterogeneous infrastructure estates.
Japan
Manufacturing facilities in Toyota City pilot edge-to-cloud orchestration stacks merging operational technology monitoring with centralized governance. METI standards for data sovereignty accelerate sovereign cloud investment among defense contractors. Platform engineering teams in Osaka demand 24/7 support for containerized micro-datacenter deployments.
United Kingdom
Managed service providers in London aggregate platform licensing across hundreds of downstream financial services customers. GDPR data residency rules constrain EU workload placement for firms operating cross-border data flows. Research universities in Cambridge and Oxford prioritize cost management modules for grant-attributed spend tracking on NSF and NIH workloads.
France
ANSSI-certified providers in Paris build Gaia-X compliant infrastructure for defense and public sector workloads. CNIL enforcement actions accelerate investment in automated policy enforcement and explainable AI governance modules. Banks in the Île-de-France region deploy unified control planes to standardize documentation workflows for algorithmic accountability audits.
Cloud Management Platform Market Vendor Landscape
Enterprise virtualization incumbents and open-source orchestration specialists split the market into distinct capability tiers. VMware sustains technology leadership through deep integration with existing virtualization stacks, while IBM anchors its position via Red Hat's OpenShift hybrid cloud orchestration capabilities. The vendor base organizes around three strategic archetypes: legacy infrastructure extenders, cloud-native platform builders, and cost-optimization pure-plays. Competitive dynamics center on M&A activity consolidating policy-as-code capabilities and strategic partnerships embedding management layers into hyperscaler marketplaces.
Within the legacy extender tier, VMware and IBM occupy positions defined by enterprise data center entrenchment and hybrid cloud orchestration depth. CloudBolt and Flexera exemplify the cost-optimization archetype, representing vendors that virtualize FinOps tooling and Kubernetes-native chargeback processes. Morpheus Data sits within the cloud-native platform builder category, anchoring a position around infrastructure-as-code pipeline integration and CI/CD-native automation. Nutanix and Holori represent alternative architectural approaches to unified control plane deployment.
| Leading Market Players |
|---|
| CloudBolt |
| VMware |
| Holori |
| Flexera |
| IBM |
| Red Hat |
| Nutanix |
| CloudHealth |
| Morpheus Data |
| Others |
Supply Flow & Price Mechanics
Hyperscaler API licensing concentration in the United States and Ireland concentrates margin pools within policy-as-code automation modules and sovereign cloud certification tiers. Platform vendors pass through infrastructure costs while capturing premium pricing on compliance-native feature sets.
Pricing Analysis
The EU AI Act and GDPR dictate the pricing tier structure across explainable governance and data residency modules. Three-tier pricing structure across premium, standard, and economy levels separates ANSSI-certified sovereign deployments from multi-tenant SaaS and open-source community editions. Cost compression in standard tiers is intensifying because hyperscaler marketplace listings commoditize baseline orchestration. Educational institutions represent the most price-sensitive buyers, while defense contractors in France and Germany absorb premium certification surcharges without elasticity.
Supply Chain Analysis
Extended payment terms from hyperscaler infrastructure providers and supply-chain finance facilities anchor working capital requirements for platform vendors. Engineering talent concentrates in the United States, Germany, and India, with policy-as-code expertise commanding scarcity premiums. The supply chain draws from open-source orchestration projects, proprietary virtualization stacks, and API abstraction layers. Single-source vulnerability around hyperscaler control plane stability threatens third-party management layer reliability. Distribution runs through direct enterprise sales, hyperscaler marketplaces, and managed service provider aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cloud management platform market is a high-growth disruption justified by the EU AI Act's algorithmic accountability mandates forcing enterprise procurement cycles. Policy-as-code automation is displacing manual governance workflows across regulated industries.
For Market Incumbents: Entrench hybrid cloud orchestration dominance through deeper OpenShift and VMware vSphere integration, countering cloud-native challengers. Acquire policy-as-code specialists to preempt FinOps tooling consolidation. Defend margin position by embedding zero-trust segmentation into existing virtualization renewals before standalone security vendors capture budget. For New Entrants and Emerging Players: Build out sovereign cloud compliance modules for ANSSI and BSI certification pathways, the most penetrable white-space in European defense procurement. Target mid-market manufacturers in Stuttgart and Toyota City with edge-to-cloud orchestration bundles. Lead with Kubernetes-native cost visibility to bypass incumbent sales cycles through platform engineering self-service adoption. For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native platform builders with infrastructure-as-code pipeline integration and CI/CD-native automation capabilities. Long-term viability rests on policy-as-code engine differentiation rather than cost-optimization feature parity. Watch hyperscaler marketplace revenue share negotiations as the inflection signal for vendor margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Policy-as-Code Engine Acquisition | Consolidates algorithmic accountability tooling for EU AI Act compliance automation. |
| Sovereign Cloud Certification Pathway | Unlocks ANSSI and BSI procurement for defense and public sector workloads. |
| Hyperscaler Marketplace Integration | Embeds management layers into AWS and Azure procurement workflows for frictionless adoption. |
| Edge-to-Cloud Orchestration Platform | Merges operational technology monitoring with centralized governance for manufacturing digitization. |
| FinOps Tooling Consolidation | Virtualizes departmental chargeback through Kubernetes-native spend attribution dashboards. |
Methodological Framework
Desk research of hyperscaler capex disclosures, SEC filings, and open-source project commit histories preceded structured interviews with platform engineering directors, cloud architects, and IT procurement officers at Fortune 500 enterprises. Primary fieldwork with managed service providers in Bangalore and Dublin validated multi-tenant governance requirements. Secondary sources included EU regulatory filings, ANSSI certification databases, and ISO 27001 audit frameworks. Bottom-up deployment modeling and top-down market sizing triangulated volume estimates across the analysis window.
The forecast framework holds macroeconomic conditions, regulatory enforcement timelines, and hyperscaler pricing stability as fixed assumptions while varying enterprise cloud migration velocity and sovereign cloud adoption rates. Segmentation dimensions modeled include deployment topology, solution module type, vertical end-use, and regional regulatory cluster. CAGRs derive from fitted adoption curves against historical virtualization spend patterns, with inputs from Kubernetes distribution growth and policy-as-code repository activity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native challengers or hyperscaler vertical integration would shift outcomes. Macroeconomic contraction, delayed EU AI Act enforcement, or breakthrough quantum encryption standards would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud CDN Market
Cloud Computing
Cloud Microservice and Application Market
Cloud Computing
Virtual Private Cloud (VPC) Market
Cloud Computing
India Cloud Computing Market
Cloud Computing
Global Personal Cloud Market
Cloud Computing
Cloud Directory Services Market
Cloud Computing
Cloud Load Balancers Market
Cloud Computing
France Cloud Computing Market
Cloud Computing
Global Server Virtualization Market
Cloud Computing
Asia Pacific Multi-Cloud Management Market
Cloud Computing
Cognitive Cloud Market
Cloud Computing
Automotive Cloud Based System Market
Cloud Computing
Cloud API and Management Platforms and Middleware Market
Cloud Computing
Hybrid Cloud Market
Cloud Computing
Cloud Systems Management Software Market
Cloud Computing
Cloud Enterprise Content Management Market