
 High-Durability Exterior Reflective Marking and Decal Systems Market | 2026-2036
High-Durability Exterior Reflective Marking and Decal Systems Market Size, Share, and Industry Trends Forecast 2026-2036
High-Durability Exterior Reflective Marking and Decal Systems Market Insights
Software-defined color calibration and remote reflectivity monitoring is restructuring how fleet operators contract for marking systems over multi-year service agreements. 3M leverages its captive polymer research to sustain premium positioning in prismatic sheeting across North American transportation networks. Avery Dennison anchors European demand through direct supply relationships with German automotive OEMs and French municipal fleets. ORAFOL Europe specializes in microprismatic solutions that dominate Nordic markets where low-angle winter sun demands extreme-durability specifications.
High-durability exterior reflective marking and decal systems combine glass bead or microprismatic retroreflective layers with pressure-sensitive adhesives and UV-stabilized top films, engineered to maintain coefficient of retroreflection above 100 cd/lx/m² after years of weathering exposure. The primary purpose is to ensure nighttime visibility of vehicles, road infrastructure, and safety equipment under headlamp illumination. Diamond grade microprismatic sheeting commands the highest margin pools due to its 3x reflectivity advantage over engineer grade products and limited qualified supply base. Road signage applications lead volume globally, while safety equipment for construction firms represents the fastest-growing demand segment as work-zone fatality regulations tighten across multiple jurisdictions.
Federal Highway Administration retroreflectivity minimums, ECE R104 vehicle conspicuity mandates, and ASTM D4956 sheeting classifications collectively define product qualification pathways and procurement specifications across the United States and Europe. China's GB/T 18833 national standard for retroreflective film adds a third compliance layer that shapes export competitiveness for Asian manufacturers. Stakeholders must monitor evolving minimum maintained retroreflectivity thresholds, as regulatory bodies on both sides of the Atlantic signal intention to tighten performance floors within the current forecast horizon.
Market Dynamics
Microprismatic film production capacity concentrates among three polymer science specialists, locking in supply-side power while highway agencies in Germany, the United States, and China simultaneously tighten retroreflectivity minimums. This squeeze between concentrated supply and ratcheting performance mandates defines competitive positioning.
Growth Catalysts
- ECE R104 vehicle conspicuity mandates:European commercial fleet operators must replace marking systems on accelerated cycles, creating recurring demand pools for compliant sheeting.
- Microprismatic retroreflective layers:These engineered films deliver 3x the coefficient of retroreflection of glass bead alternatives, justifying premium positioning in Nordic and Alpine applications.
- China:Highway infrastructure investment and domestic manufacturing scaling for GB/T 18833 certified films are expanding both demand and supply capability.
Market Restraints
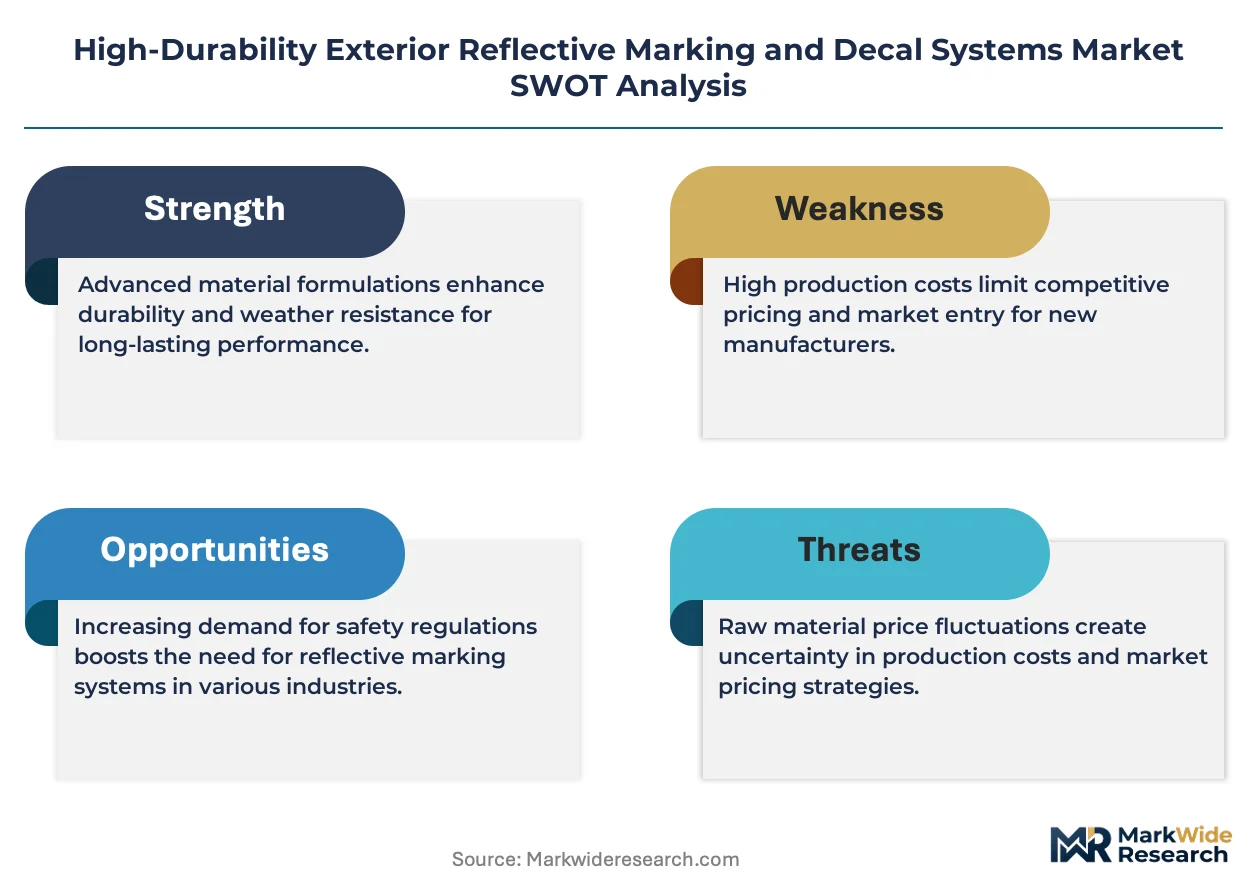
- Petrochemical input volatility:UV-stabilized polycarbonate and acrylic top films face price pressure from propylene and MMA supply fluctuations.
- Qualified supplier concentration:Diamond grade microprismatic sheeting relies on captive polymer research capabilities held by fewer than five integrated manufacturers.
- ASTM D4956 certification timelines:Extended weathering test protocols delay new entrant qualification by 24-36 months.
Strategic Opportunities
- Software-defined color calibration:Remote reflectivity monitoring enables fleet operators to contract for marking systems through multi-year service agreements rather than spot purchases.
- Construction work-zone safety equipment:Tightening fatality regulations across multiple US states and German Länder is opening fastest-growing demand verticals.
- India:National highway expansion under BIS certification pathways remains underpenetrated by microprismatic specialists.
Industry Challenges
- Optical engineer scarcity:Design of microprismatic corner-cube geometries requires specialized photonics expertise concentrated in German and Japanese research clusters.
- Multi-jurisdiction compliance:Simultaneous adherence to ASTM D4956, ECE R104, and GB/T 18833 strains product development bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Durability Exterior Reflective Marking and Decal Systems Market |
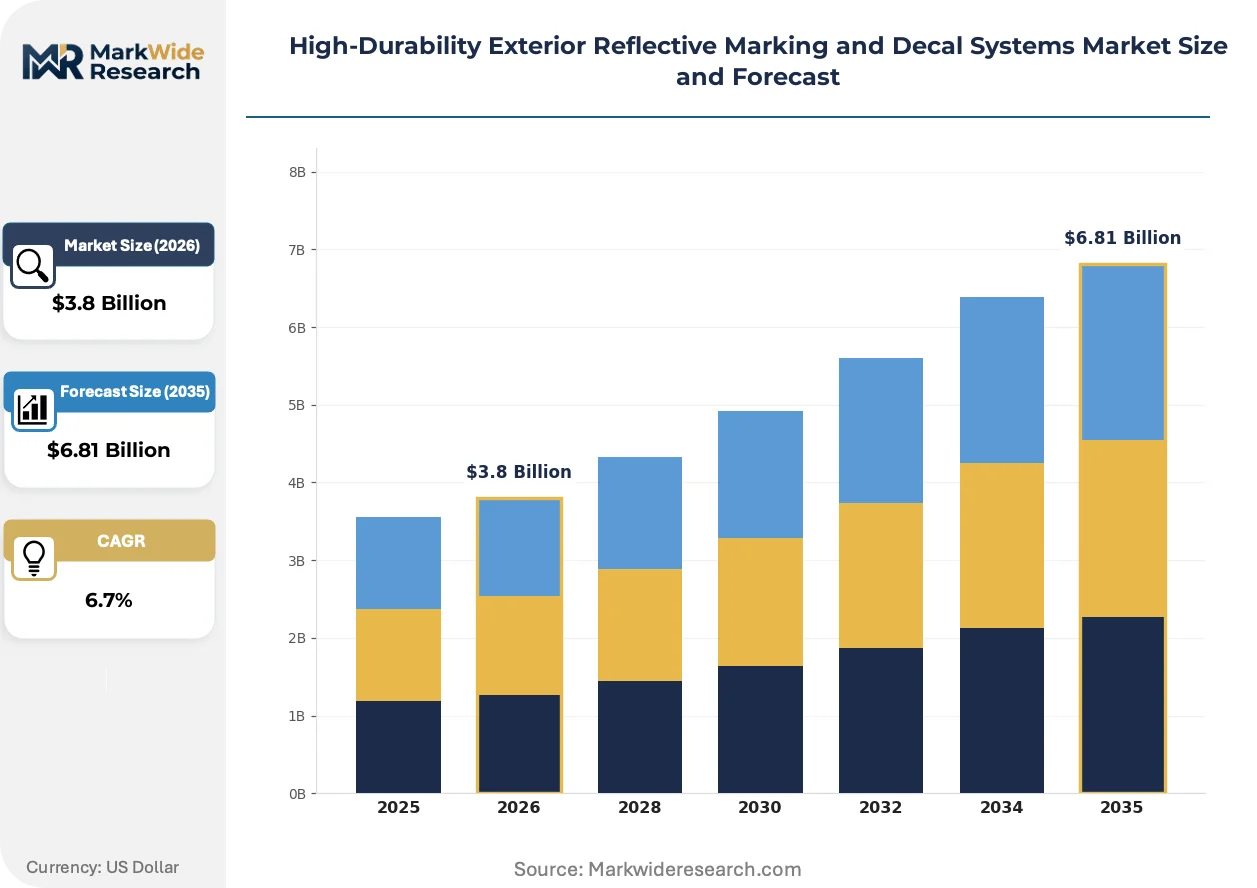
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engineer Grade, High Intensity Prismatic, Diamond Grade, Microprismatic, Glass Bead Application: Road Signage, Vehicle Identification, Safety Equipment, Advertising Panels, Traffic Control Material Technology: Polyvinyl Chloride, Acrylic, Polycarbonate, Polyester, Fluoropolymer End User: Transportation Fleet, Municipal Authorities, Construction Firms, Event Management, Public Safety Agencies |
| Companies Covered | 3M, Avery Dennison, ORAFOL Europe, Nippon Carbide Industries, Coats Group, Daoming Optics & Chemical, Changzhou Hua R Sheng Reflective Material, SKC, Reflomax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Durability Exterior Reflective Marking and Decal Systems Market Trends and Innovations
Retroreflective marking systems are transitioning from passive hardware to digitally monitored infrastructure assets, with embedded sensors and calibration software restructuring how visibility performance is validated and maintained across fleet and roadway applications.
Polymer-stabilized microprismatic sheeting is absorbing market share from encapsulated glass bead technologies in high-performance road signage. State departments of transportation in Texas and California specify diamond grade films for interstate corridor replacement programs. The technology is absorbing margin pools previously captured by engineer grade suppliers as procurement specifications ratchet upward.
REACH substance restrictions and EU Green Deal circularity requirements are pressuring solvent-based adhesive formulations in European supply chains. Manufacturers reformulate pressure-sensitive layers to eliminate classified substances ahead of sunset dates. French municipal fleets and German automotive OEMs now require environmental product declarations alongside optical performance certificates.
Fleet maintenance departments compress replacement cycles for conspicuity markings from reactive failure-based schedules to predictive reflectivity monitoring. Third-party service providers install remote sensing equipment and contract for guaranteed performance levels. This model is displacing spot purchasing most visibly in North American long-haul trucking and Nordic municipal vehicle pools.
High-Durability Exterior Reflective Marking and Decal Systems Market Segmentation
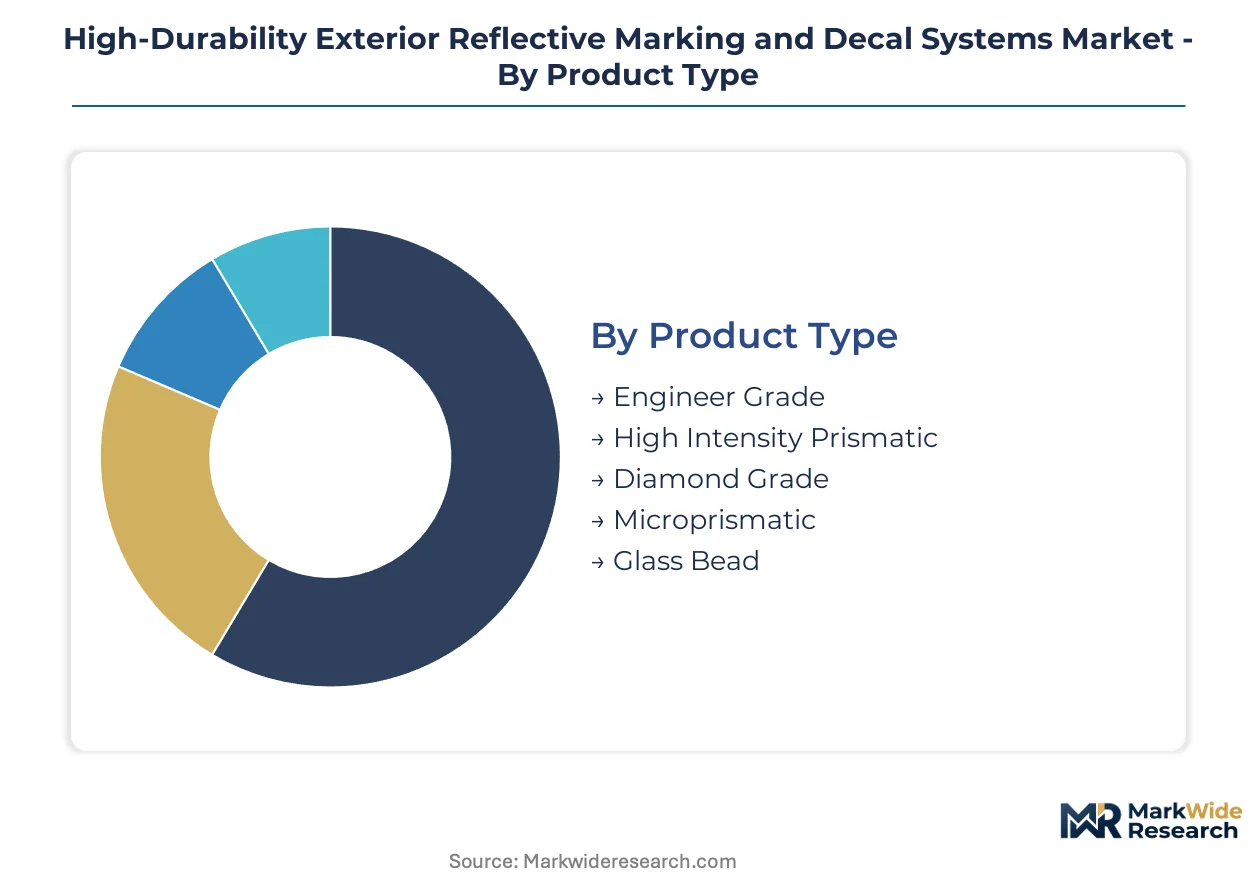
Segmentation in reflective marking systems reveals how procurement specifications diverge across end-use environments. Upgrade cycles and replacement mandates vary dramatically between highway infrastructure and mobile fleet applications, reshaping supplier engagement models.
Product Type:
Replacement cycles accelerate where regulatory minimums for coefficient of retroreflection tighten, forcing upgrades from legacy glass bead formulations to engineered microprismatic films.
- Diamond Grade:Corner-cube microprismatic arrays deliver the highest coefficient of retroreflection, specified by state departments of transportation in Texas and California for interstate corridor programs. Procurement concentrates in North American highway infrastructure where FHWA retroreflectivity mandates drive specification upgrades.
- Microprismatic:Engineered polymer films with precise geometric arrays outperform glass bead alternatives by 3x on reflectivity metrics. Nordic municipal authorities specify these for extreme low-angle winter sun conditions where visibility persistence determines safety outcomes.
- High Intensity Prismatic:Mid-tier performance sheeting balances optical output against material cost for secondary road networks.
- Engineer Grade:Encapsulated glass bead technology retains position in budget-constrained municipal fleets.
- Glass Bead:Legacy technology faces displacement as ASTM D4956 specifications ratchet upward across jurisdictions.
Volume placements concentrate in Engineer Grade for cost-sensitive applications; the faster expansion belongs to Diamond Grade as procurement specifications escalate.
Application:
Cost tier differentiation separates infrastructure assets with decade-long depreciation schedules from consumable fleet markings requiring annual refresh cycles.
- Road Signage:Permanent infrastructure installations demand weathering resistance exceeding 10 years under ASTM D4956 protocols. German Autobahn maintenance programs and Chinese highway expansion under GB/T 18833 drive specification intensity.
- Safety Equipment:Construction work-zone deployments require rapid-deployment retroreflectivity for temporary traffic control. Tightening fatality regulations across multiple US states and German Länder accelerate specification upgrades for high-visibility apparel and barrier markings.
- Vehicle Identification:Commercial fleet markings face ECE R104 conspicuity mandates with accelerated replacement timelines.
- Traffic Control:Temporary signage for roadwork and events demands balance between optical performance and portability.
- Advertising Panels:Commercial signage prioritizes color fidelity and brand consistency over extreme durability specifications.
Revenue concentration sits with Road Signage; Safety Equipment is climbing the fastest as work-zone liability frameworks tighten.
Material Technology:
Supply concentration in polymer science capabilities locks in margin structures for UV-stabilized film substrates.
- Polycarbonate:High-impact resistance and optical clarity position this substrate for diamond grade microprismatic sheeting. Captive polymer research capabilities at integrated manufacturers limit qualified supply sources.
- Acrylic:Superior weathering performance and UV stability support premium positioning in European markets where REACH substance restrictions pressure adhesive formulations.
- Polyester:Cost-effective substrate for high-volume engineer grade applications with moderate durability requirements.
- Polyvinyl Chloride:Flexible film properties suit conformable vehicle markings and curved signage substrates.
- Fluoropolymer:Extreme chemical and UV resistance commands niche positioning in harsh industrial environments.
Procurement volume clusters in Acrylic for balanced performance-cost positioning; Polycarbonate captures the steepest expansion trajectory as microprismatic specifications proliferate.
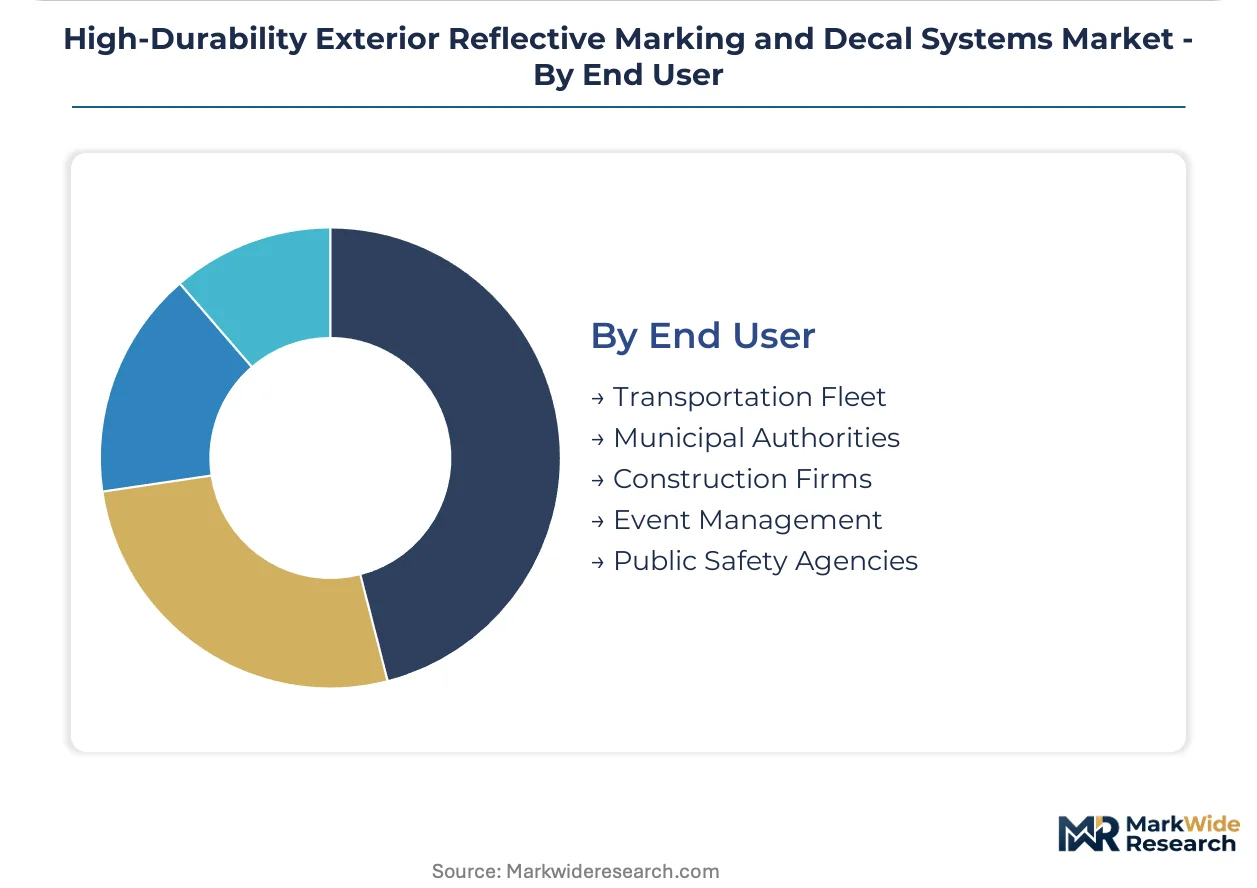
End User:
Customer type determines contracting structure, from municipal RFP processes to fleet service agreements with embedded reflectivity monitoring.
- Municipal Authorities:Highway departments and city transportation bureaus specify retroreflective materials through multi-year infrastructure programs. German municipal procurement and Chinese provincial highway bureaus dominate volume placement.
- Transportation Fleet:Commercial trucking and logistics operators contract for conspicuity marking systems through outcome-based service agreements with remote monitoring provisions.
- Construction Firms:Work-zone safety equipment procurement responds to OSHA and state-level fatality prevention mandates with accelerating specification intensity.
- Public Safety Agencies:Emergency vehicle markings require color-coded retroreflectivity with law enforcement and fire service specific standards.
- Event Management:Temporary signage and crowd control applications prioritize rapid deployment over extended weathering performance.
Contract value aggregates heaviest with Municipal Authorities; Construction Firms are gaining share fastest as work-zone safety regulations expand across jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detroit's automotive corridor drives North American demand for ECE R104-compliant vehicle conspicuity systems, while Shanghai's polymer research clusters anchor Asian microprismatic film production. Procurement specifications diverge sharply across regulatory jurisdictions.
United States
State departments of transportation in Texas and California specify diamond grade microprismatic sheeting for interstate corridor replacement programs. The Federal Highway Administration maintains retroreflectivity minimums under 23 CFR 655. The FHWA's research facility in McLean, Virginia validates weathering performance protocols for ASTM D4956 certification.
Germany
Autobahn maintenance programs and municipal fleet procurement in Bavaria and North Rhine-Westphalia enforce ECE R104 vehicle marking mandates. The KBA oversees type approval for commercial vehicle conspicuity systems. Cologne's polymer research institutes supply optical engineering talent for corner-cube geometry design.
China
Provincial highway bureaus under the Ministry of Transport expand procurement of GB/T 18833 certified retroreflective films. The Yangtze River Delta concentrates domestic manufacturing capacity for microprismatic substrates. Shanghai's chemical industrial parks scale UV-stabilized polycarbonate film production for export markets.
Japan
Metropolitan expressway authorities in Tokyo and Osaka specify high-durability markings for tunnel and elevated roadway assets. METI oversees JIS standards alignment with international retroreflectivity protocols. Nagoya's automotive supplier corridor demands precision-engineered vehicle identification systems.
India
National highway expansion under the Ministry of Road Transport and Highways creates procurement volume for BIS-certified reflective materials. The Delhi-Mumbai Industrial Corridor concentrates infrastructure investment. Gujarat's chemical manufacturing belt develops domestic adhesive formulation capabilities for pressure-sensitive marking systems.
High-Durability Exterior Reflective Marking and Decal Systems Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the reflective marking systems value chain. Integrated polymer science specialists with captive film extrusion capabilities command premium positioning in diamond grade microprismatic sheeting. Three strategic archetypes dominate: diversified materials conglomerates with transportation sector verticals, specialized retroreflective film manufacturers, and regional adhesive converters. Capacity expansion in Asian polymer research clusters and strategic partnerships for remote reflectivity monitoring platforms constitute the primary competitive vectors.
Within the integrated materials tier, 3M and Avery Dennison occupy positions anchored by polymer research capabilities and direct supply relationships with transportation authorities. ORAFOL Europe represents the specialized manufacturer archetype with concentrated expertise in microprismatic corner-cube geometries. Daoming Optics & Chemical exemplifies the Asian-scale producer model with domestic supply chain integration for GB/T 18833 certified films. These three entities collectively illustrate how geographic regulatory alignment shapes competitive positioning across North American, European, and Asian procurement channels.
| Leading Market Players |
|---|
| 3M |
| Avery Dennison |
| ORAFOL Europe |
| Nippon Carbide Industries |
| Coats Group |
| Daoming Optics & Chemical |
| Changzhou Hua R Sheng Reflective Material |
| SKC |
| Reflomax |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists with captive polymer extrusion capabilities in Germany and Japan anchor supply discipline, translating limited qualified manufacturing sources into sustained premium capture for diamond-grade microprismatic sheeting. Their ownership structures resist short-term margin compression, reinforcing pricing power as ASTM D4956 certification timelines stretch to 36 months.
Pricing Analysis
Value-based pricing anchored to guaranteed coefficient of retroreflection outcomes dominates fleet service agreements, displacing per-unit spot purchasing. Three-tier pricing structure across diamond-grade, microprismatic, and engineer-grade certification levels separates procurement pools, with Texas and California highway departments showing lowest price sensitivity due to FHWA mandate compliance deadlines. Cost compression in engineer-grade tiers is intensifying as Chinese manufacturers scale GB/T 18833 certified capacity.
Supply Chain Analysis
Domestic-content mandates under China's GB/T 18833 standard and India's BIS certification pathways are reshaping sourcing patterns for multinational fleet operators. UV-stabilized polycarbonate substrates and pressure-sensitive adhesive formulations draw from concentrated polymer science clusters in Germany, the United States, and Japan. Single-source vulnerability persists for corner-cube microprismatic films where fewer than five qualified manufacturers operate captive extrusion lines. Distribution runs through direct supply relationships with state transportation departments and automotive OEMs, bypassing commodity distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ASTM D4956 weathering test protocols create a 24-36 month barrier-to-entry moat protecting incumbent positions.
For Market Incumbents: Hedge against optical engineer scarcity by securing talent pipelines from Cologne and Nagoya research clusters before corner-cube geometry design capabilities concentrate further. Defensive consolidation of adhesive formulation assets in European supply chains addresses REACH substance restriction pressure while locking in environmental product declaration credentials required by French municipal fleets and German automotive OEMs. For New Entrants and Emerging Players: ECE R104 vehicle conspicuity mandates in Europe open a window for construction work-zone safety equipment specialization, the fastest-climbing demand vertical as OSHA and German Länder fatality regulations tighten. White-space concentration sits with Nordic municipal vehicle pools where extreme low-angle winter sun specifications favor microprismatic performance tiers underserved by engineer-grade legacy suppliers. Go-to-market positioning through third-party reflectivity monitoring service providers bypasses incumbent direct-supply relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized microprismatic manufacturers with demonstrated GB/T 18833 certification in China's Yangtze River Delta production corridor. Long-term viability hinges on polymer research integration rather than adhesive conversion capabilities. The signal to watch is FHWA signaling on maintained retroreflectivity threshold tightening, which would force accelerated replacement cycles across North American highway infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into UV-Stabilized Polycarbonate | Captive substrate supply secures diamond-grade microprismatic capacity against petrochemical input volatility. |
| Remote Reflectivity Monitoring Platform Deployment | Software-defined service contracts with Texas and California DOTs displace spot purchasing models. |
| REACH-Compliant Adhesive Reformulation | Elimination of classified substances ahead of EU Green Deal sunset dates preserves European municipal access. |
| GB/T 18833 Certification Investment | Domestic qualification unlocks Chinese provincial highway bureau procurement under domestic-content rules. |
| Construction Work-Zone Safety Equipment Specialization | OSHA and German Länder fatality prevention mandates accelerate specification intensity in fastest-growing segment. |
Research Methodology
Document review covered regulatory filings with FHWA, KBA, and METI, complemented by interviews with polymer research directors at integrated manufacturers, procurement leads at German automotive OEMs, fleet maintenance managers at North American long-haul operators, and technical directors at French municipal transportation bureaus. Secondary validation drew from ASTM D4956 certification databases, ECE R104 type approval registries, SEC 10-K disclosures from listed materials conglomerates, and customs trade data on retroreflective film imports. Bottom-up segment sizing triangulated against top-down infrastructure spending forecasts.
Output modeling produced volume and value trajectories across product type, application, material technology, and end-user dimensions over the projection horizon. CAGRs derived from regression analysis of historical procurement cycles against regulatory mandate implementation timelines, incorporating highway infrastructure depreciation schedules and fleet replacement velocity assumptions. Specific inputs included FHWA retroreflectivity minimum enforcement patterns and Chinese provincial highway bureau expansion budgets.
The model assumes a particular technology adoption path; alternative pathways for embedded sensor integration and predictive reflectivity monitoring would alter the outlook if fleet operators accelerate service-contract adoption faster than base-case assumptions. Forecasts reflect documented regulatory implementation schedules and petrochemical input cost assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals & Materials
Hybrid Paint Cans Market
Chemicals & Materials
Global Lubricant Antioxidants Market
Chemicals & Materials
Global Polyolefin Powders Market
Chemicals & Materials
Dynamic Glazing Market
Chemicals & Materials
Inorganic Oxides Market
Chemicals & Materials
Asia-Pacific Wax Market
Chemicals & Materials
North America Epoxy Resins Market
Chemicals & Materials
Global Sodium Chlorate Market
Chemicals & Materials
3D Glass Market
Chemicals & Materials
Furosemide Market
Chemicals & Materials
Global Molded FRP Grating Market
Chemicals & Materials
Global Carbon Fiber Reinforced Plastic Market
Chemicals & Materials
Uncoated White Top Testliner Market
Chemicals & Materials
Global Lubricating Oil Additives Market
Chemicals & Materials
Linear Mercaptans Market
Chemicals & Materials
RDX and HMX Market