
 Inorganic Oxides Market | 2026-2036
Inorganic Oxides Market Size, Share, and Industry Trends Forecast 2026-2036
Inorganic Oxides Market Foresight
Chinese state-owned chemical producers is consolidating upstream bauxite and ilmenite access ahead of planned environmental audits. BASF SE leverages integrated refining complexes in Germany and Belgium to sustain premium pigment output. Sinopec Corp. anchors domestic supply of metallurgical alumina through captive refinery networks. Dow Chemical Company differentiates via high-purity silica for semiconductor applications.
Inorganic oxides comprise crystalline or amorphous compounds of metallic and non-metallic elements with oxygen, typically synthesized through thermal decomposition, precipitation, or vapor-phase oxidation at temperatures exceeding 800°C. These materials function as pigments, catalyst supports, dielectric layers, and refractory components across industrial manufacturing. Titanium dioxide dominates pigment revenue pools due to irreplaceable opacity in architectural coatings. Electronics applications represent the fastest-expanding segment as silica and alumina advance wafer polishing and substrate fabrication. Construction-grade zinc oxide remains mature with stable volume but compressed margin structures.
China's MEE enforces emissions caps on sulfate-process titanium dioxide plants, while REACH in Europe mandates registration of nano-scale oxide forms. The US EPA regulates heavy-metal leaching from ceramic glazes under TSCA. Stakeholders must monitor how carbon-border adjustments and evolving purity specifications reshape sourcing decisions for battery and photovoltaic applications.
Market Dynamics
China's dual carbon goals and tightening MEE emissions standards are redirecting sulfate-process titanium dioxide capacity toward chloride-route production, compressing regional supply availability while elevating capital requirements for compliance.
Growth Catalysts
- Electronics-grade alumina demand:Semiconductor substrate fabrication in Taiwan and South Korea is pulling high-purity alumina volumes. Wafer polishing applications require sub-50 ppm impurity thresholds.
- MEE emissions enforcement:China's Ministry of Ecology and Environment is shuttering legacy sulfate-process plants. Surviving producers capture pricing power from constrained domestic supply.
- Photovoltaic encapsulant growth:Silica fume for solar panel backsheet coatings is accelerating. Module manufacturers in Vietnam and Malaysia are qualifying new oxide suppliers.
Market Restraints
- Ilmenite supply concentration:Australian and South African ore deposits dominate titanium feedstock. Geographic concentration exposes pigment producers to shipping cost volatility and geopolitical disruption.
- REACH nano-registration burden:ECHA mandates extensive toxicity dossiers for nano-scale oxide forms. Compliance costs disproportionately burden mid-scale European specialty producers.
- Organic pigment substitution:High-performance azo and phthalocyanine pigments are displacing titanium dioxide in select plastic and ink applications where opacity requirements moderate.
Strategic Opportunities
- Battery-grade alumina white space:Separator coating applications for lithium-ion cells remain underpenetrated. Korean and Japanese battery manufacturers are qualifying new oxide purity grades.
- India electronics manufacturing:PLI scheme incentives for semiconductor and display fabrication are creating localized demand for electronics-grade silica and alumina.
- Chloride-route technology convergence:Fluidized-bed chlorination combined with oxygen-enrichment is enabling lower-carbon titanium dioxide production. Early adopters secure carbon-border adjustment advantages.
Industry Challenges
- Process engineering talent scarcity:Chloride-route plant operations require specialized metallurgical expertise. Retirement waves at established producers are thinning the experienced workforce.
- Legacy refinery retrofit capex:Converting sulfate-process assets to chloride-route production demands nine-figure capital commitments. Financing timelines stretch 24-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inorganic Oxides Market |
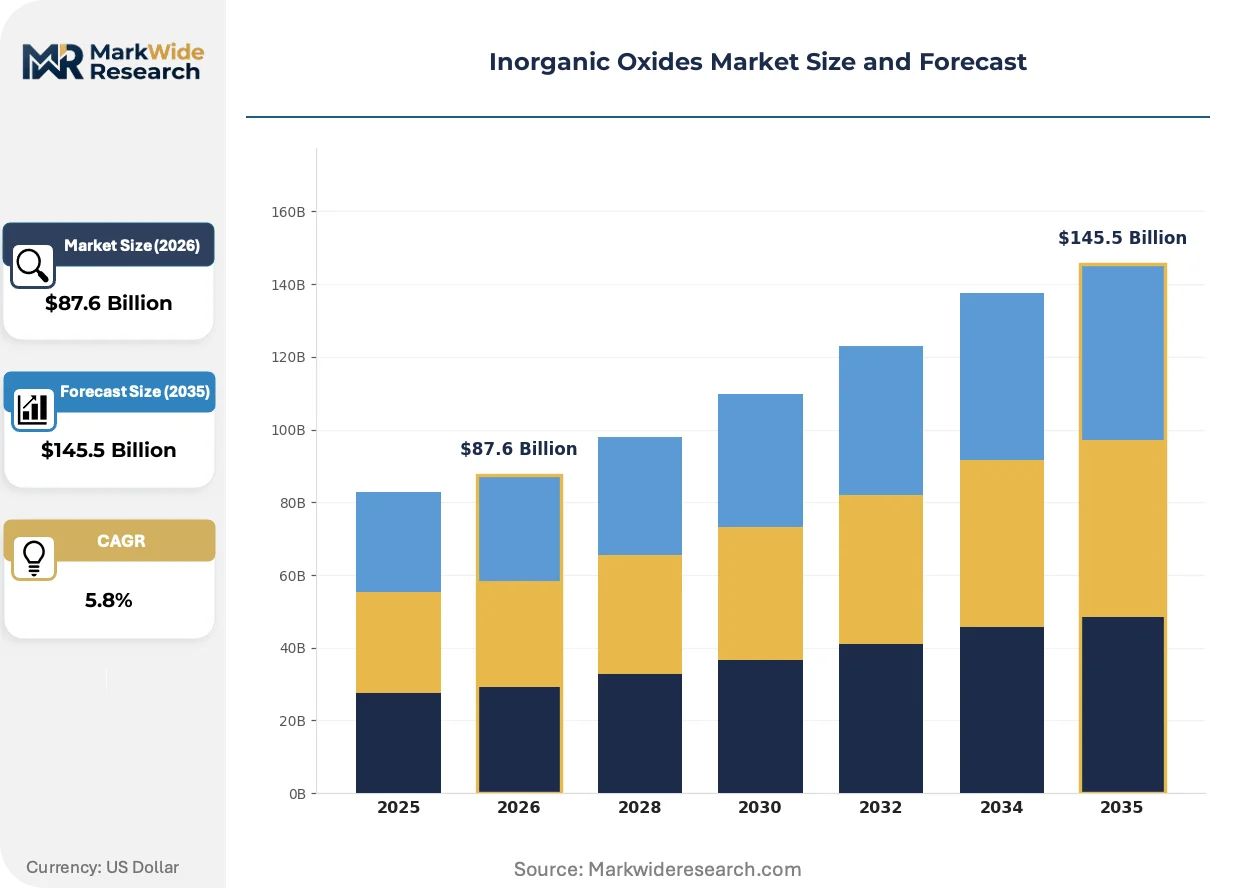
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $145.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alumina, Silica, Zinc Oxide, Titanium Dioxide Application: Ceramics, Coatings, Electronics, Cosmetics End Use Industry: Aerospace, Healthcare, Automotive, Construction Packaging Type: Bags, Drums, Boxes, Bulk Containers |
| Companies Covered | BASF SE, Sinopec Corp., Dow Chemical Company, Exxon Mobil Corporation, DuPont, Mitsubishi Chemical Corporation, SABIC, Cathay Industries, Incos srl P.I., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inorganic Oxides Market Shifts & Advancements
Plasma-enhanced synthesis routes and closed-loop chlorine recovery systems are compressing the cost gap between environmental compliance and profitability. Process intensification and digital twin deployment are reshaping plant economics.
Continuous-flow hydrothermal synthesis is decentralizing specialty oxide production. Pharmaceutical and cosmetic formulators are adopting modular reactor systems for customized particle size distributions. Distributed manufacturing is enabling just-in-time pigment supply without bulk inventory carrying costs.
REACH nano-scale registration deadlines are forcing reformulation across European coatings and personal care sectors. ECHA's 2024-2025 dossier requirements are accelerating substitution toward non-nano oxide grades in skin-contact applications. German and French cosmetic houses are redesigning supply specifications to preempt regulatory friction.
Specification-driven procurement is fragmenting supplier relationships across the construction sector. Large coatings formulators are unbundling technical service from material supply, contracting directly with oxide producers while bypassing traditional distributor markups. This disintermediation is most pronounced in German and Dutch industrial coatings procurement.
Inorganic Oxides Market Segmentation
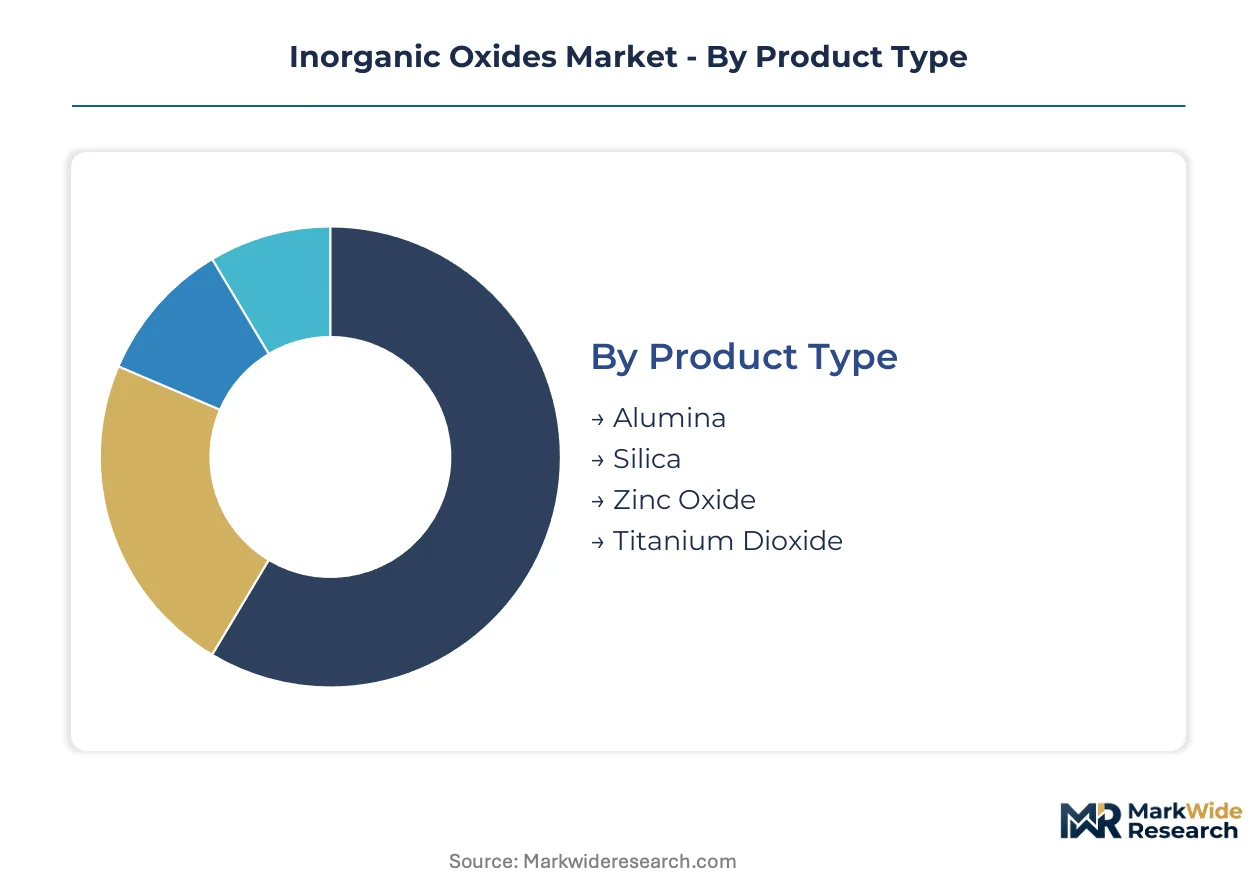
Product differentiation across purity grades and particle size distributions determines pricing power in inorganic oxides. Certification requirements for REACH nano-registration, MEE emissions compliance, and semiconductor-grade specifications fragment supplier capabilities across segments.
Product Type:
REACH nano-registration deadlines from ECHA impose divergent compliance burdens: titanium dioxide and silica face mandatory toxicity dossiers, while alumina and zinc oxide navigate lighter regulatory thresholds.
- Titanium Dioxide:Crystalline oxide synthesized via sulfate or chloride routes, with rutile and anatase polymorphs serving distinct opacity requirements. Architectural coatings in China absorb the dominant volume share, though MEE emissions caps on sulfate-process plants are constraining domestic supply availability.
- Silica:Amorphous or crystalline silicon dioxide spanning fumed, precipitated, and colloidal grades. Semiconductor wafer polishing in Taiwan and South Korea pulls high-purity volumes requiring sub-50 ppm metal impurity thresholds.
- Alumina:Alpha and gamma phases differentiated by calcination temperature, with smelter-grade and specialty ceramics applications.
- Zinc Oxide:French process or direct method production for rubber vulcanization and pharmaceutical grades.
Titanium Dioxide sits at the top of the volume ranking, with Silica climbing the fastest.
Application:
Cost tier stratification separates commodity construction applications from premium electronics and medical grades, with purity specifications driving tenfold price differentials.
- Electronics:Substrate fabrication and dielectric layers demand sub-micron particle distributions with controlled surface chemistry. Taiwan Semiconductor Manufacturing and Samsung Foundry are qualifying new alumina and silica suppliers for advanced packaging nodes.
- Coatings:Architectural, industrial, and automotive finishes leverage titanium dioxide for opacity and zinc oxide for UV stabilization. Waterborne formulations in Germany and the Netherlands are reformulating to preempt REACH nano-registration friction.
- Ceramics:Refractory and structural applications spanning kiln furniture and advanced ceramics.
- Cosmetics:Sunscreen and personal care formulations requiring non-nano oxide grades for skin-contact compliance.
Coatings maintains the largest installed demand base, while Electronics expands most quickly.
End Use Industry:
Customer type fragmentation separates spot-market construction buyers from long-term contracted aerospace and healthcare purchasers with stringent audit requirements.
- Construction:Cement, concrete, and architectural finishes consume construction-grade alumina and titanium dioxide pigments. China's property sector consolidation is redirecting volume toward infrastructure and industrial coatings.
- Automotive:OEM and refinish coatings, tire manufacturing, and ceramic brake components. BASF SE and PPG Industries are unbundling technical service from material supply, contracting directly with oxide producers.
- Aerospace:Thermal barrier coatings and structural ceramics requiring traceability documentation.
- Healthcare:Pharmaceutical excipients and medical device ceramics with USP and EP certification requirements.
Construction leads absolute volume consumption, with Automotive gaining share fastest.
Packaging Type:
Supply concentration in bulk logistics favors integrated producers with captive container fleets, while specialty grades require contamination-controlled smaller formats.
- Bulk Containers:Intermediate bulk containers and tanker shipments for high-volume titanium dioxide and alumina. Sinopec Corp. and Chinese state-owned producers leverage dedicated rail and port infrastructure.
- Drums:Steel and fiber drums for moisture-sensitive silica and zinc oxide grades. Electronics manufacturers in Malaysia and Vietnam are qualifying new suppliers with drum-level traceability systems.
- Bags:Multi-wall paper and woven polypropylene for construction-grade shipments.
- Boxes:Corrugated and composite containers for cosmetic and pharmaceutical samples.
Bulk Containers dominates tonnage shipped, with Drums expanding fastest on electronics-grade demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting titanium dioxide capacity toward jurisdictions with clearer chloride-route approval pathways, as China's MEE emissions enforcement raises compliance costs for legacy sulfate-process plants.
China
Construction-grade pigment consumption absorbs dominant volume shares, though property sector consolidation is redirecting demand toward infrastructure coatings. MEE emissions caps on sulfate-process plants are shuttering legacy capacity in Shandong and Jiangsu provinces. Qingdao and Zhenjiang industrial clusters are pivoting toward chloride-route technology retrofits to sustain operations.
Germany
Automotive OEM and industrial coatings procurement sustains premium titanium dioxide and alumina demand. REACH nano-registration requirements from ECHA are forcing reformulation across waterborne architectural coatings. BASF SE leverages integrated refining complexes in Ludwigshafen and Antwerp to maintain pigment output.
United States
Semiconductor substrate fabrication in Arizona and Texas pulls high-purity silica and alumina volumes for wafer polishing applications. EPA regulation under TSCA governs heavy-metal leaching from ceramic glazes. Dow Chemical Company anchors specialty oxide supply through Gulf Coast production assets.
South Korea
Electronics-grade alumina demand from Samsung Foundry and SK Hynix is accelerating separator coating qualification for lithium-ion battery applications. MFDS pharmaceutical-grade certification requirements structure zinc oxide procurement for medical devices. Gyeonggi-do and Chungcheongnam-do industrial corridors concentrate oxide refining capacity.
India
PLI scheme incentives for semiconductor and display fabrication are creating localized demand for electronics-grade silica and alumina. BIS certification requirements govern construction-grade pigment imports. Gujarat and Maharashtra industrial zones are qualifying new oxide suppliers for electronics manufacturing clusters.
Inorganic Oxides Market Competitive Landscape
Chinese state-owned producers anchor one tier through captive refinery networks and upstream bauxite access; European integrated chemical groups hold premium pigment positioning through chlor-alkali integration. Market structure concentrates around three strategic archetypes: state-backed upstream integrators, diversified multinational chemical conglomerates, and specialty electronics-grade refiners. Capacity expansion and direct procurement contracting with coatings formulators represent dominant competitive vectors.
Within the state-backed upstream tier, Sinopec Corp. exemplifies vertical control through captive metallurgical alumina supply chains. Among diversified multinational chemical groups, BASF SE and Dow Chemical Company occupy positions spanning construction pigments through semiconductor-grade materials. These three anchors represent divergent strategic postures: state-resource leverage, integrated refining scale, and high-purity specialty differentiation.
| Leading Market Players |
|---|
| BASF SE |
| Sinopec Corp. |
| Dow Chemical Company |
| Exxon Mobil Corporation |
| DuPont |
| Mitsubishi Chemical Corporation |
| SABIC |
| Cathay Industries |
| Incossrl P.I. |
| Others |
Supply & Pricing Matrix
Ilmenite ore freight from Australian and South African ports cascades through sulfate-process titanium dioxide production into three distinct pricing tiers: electronics-grade alumina commands semiconductor-level premiums, construction-grade pigments absorb volume discounts, and specialty nano-registered oxides carry REACH compliance markups.
Pricing Analysis
Distributor margins compress as coatings formulators in Germany and the Netherlands unbundle technical service from material supply, contracting directly with oxide producers. Three-tier pricing structure across premium, standard, and economy levels reflects purity grade and certification status, with sub-50 ppm impurity thresholds separating semiconductor-grade alumina from construction applications. Price erosion runs through construction-grade titanium dioxide as China's property sector consolidation redirects volume toward infrastructure coatings. Spot-market construction buyers exhibit highest price sensitivity, while long-term contracted aerospace purchasers with stringent audit requirements accept premium positioning.
Supply Chain Analysis
Container shipping rates from Australian ilmenite terminals to Chinese pigment plants in Shandong and Jiangsu provinces feed directly into sulfate-process cost structures. Supply concentrates in China, Australia, and South Africa for titanium feedstock, with South Korea and Taiwan anchoring electronics-grade alumina refining. Raw material dependencies span ilmenite ore, metallurgical-grade bauxite, and high-purity silica sand. Single-source vulnerability from Australian ore deposit concentration exposes pigment producers to geopolitical disruption. Distribution runs through integrated producers with captive rail and port infrastructure, though drum-level traceability systems are penetrating electronics manufacturing clusters in Malaysia and Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chloride-route titanium dioxide production in China faces capital cost premiums of roughly one-third versus sulfate-process legacy assets, creating arbitrage windows for early adopters securing carbon-border adjustment advantages into European coatings markets.
For Market Incumbents: Cement chloride-route technology positions ahead of MEE emissions enforcement waves shuttering legacy sulfate-process capacity. BASF SE and Dow Chemical Company should deepen backward integration into high-purity silica feedstocks for semiconductor applications, defending against emerging specialty refiners in South Korea. Captive refinery networks and upstream bauxite access remain the priority lever against state-backed Chinese producers consolidating ilmenite supply. For New Entrants and Emerging Players: Electronics distributors in India offer the most penetrable channel partner type for battery-grade alumina separator coatings, given PLI scheme incentives localizing semiconductor and display fabrication demand. Target white-space opportunities in Vietnam and Malaysia solar panel backsheet encapsulant qualification, where module manufacturers seek new oxide suppliers. Continuous-flow hydrothermal synthesis enables modular entry without nine-figure refinery capex commitments. For Investors and Strategic Acquirers: Roll-up economics work for specialty electronics-grade refiners because semiconductor substrate fabrication in Taiwan and South Korea demands sub-50 ppm impurity thresholds that commodity producers cannot meet. Platform consolidation across mid-scale European specialty producers facing REACH nano-registration burdens offers 5-10 year viability. Watch for chloride-route technology adoption rates as inflection indicator, particularly oxygen-enriched fluidized-bed chlorination deployments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ilmenite Mining | Secures feedstock supply against Australian and South African geographic concentration risks. |
| Chloride-Route Technology Retrofit | Enables MEE compliance in Shandong and Jiangsu while capturing carbon-border adjustment premiums. |
| Electronics-Grade Purity Certification | Unlocks Samsung Foundry and TSMC supplier qualification for wafer polishing applications. |
| Direct Procurement Contracting | Bypasses distributor markups in German and Dutch industrial coatings procurement. |
| Modular Hydrothermal Synthesis Deployment | Decentralizes specialty oxide production for pharmaceutical and cosmetic formulators. |
Research Methodology
Direct dialogue with plant managers at sulfate and chloride-route facilities, procurement leads at downstream coatings formulators, distribution channel partners in European construction markets, and technical R&D directors at semiconductor materials suppliers grounded qualitative findings. Secondary validation drew from customs and trade data tracking ilmenite and bauxite flows, ACC and Cefic industry reports, SEC 10-K filings from diversified chemical conglomerates, and MEE emissions enforcement disclosures. Bottom-up capacity modeling triangulated against top-down end-use consumption estimates across the analysis window.
Segmented outputs spanning product type, application, end-use industry, and packaging format reflect granular demand decomposition. Modeled variables included grade tier purity thresholds, regional production hub regulatory clusters, and packaging format contamination control requirements. CAGRs derived from fitted growth curves incorporating electronics manufacturing expansion rates, construction sector pigment intensity coefficients, and photovoltaic module deployment trajectories. Industry-specific forecast inputs captured PLI scheme incentive effects on Indian electronics manufacturing and REACH nano-registration deadline impacts on European coatings reformulation.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to chloride-route technology adoption timelines, MEE enforcement stringency variations, and carbon-border adjustment implementation scope. Forecasts reflect assumptions about regulatory trajectory continuity and feedstock supply concentration persistence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals & Materials
Plastic Color Sorter Market
Chemicals & Materials
Aluminum Flat Products Market
Chemicals & Materials
Antimicrobial Ingredients Market
Chemicals & Materials
Global Glycidol Market
Chemicals & Materials
Global Lubricating Oil Additives Market
Chemicals & Materials
Thermal Inkjet Inks Market
Chemicals & Materials
US Esters Market
Chemicals & Materials
Laboratory Ware Market
Chemicals & Materials
Pharmaceutical Fine Chemicals Market
Chemicals & Materials
Textile Machine Lubricants Market
Chemicals & Materials
Europe Waterborne Polyurethane Coatings Market
Chemicals & Materials
SBS Modified Bitumen Membrane Market
Chemicals & Materials
Pharmaceutical Grade Hyaluronic Acid Market
Chemicals & Materials
Global Plating on Plastics Market
Chemicals & Materials
Carbon Fiber Reinforced Thermoplastic (CFRTP) Composite Market
Chemicals & Materials
Global Thin Papers Market