
 Asia-Pacific Wax Market | 2026-2036
Asia-Pacific Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Wax Market Insights
Plant-based wax alternatives are recalibrating product economics across candle and cosmetics applications as tallow and palm-derived inputs face cost volatility. Sinopec Group leverages its integrated refinery operations to sustain bulk paraffin supply contracts across East Asian packaging converters. Nippon Seiro Co., Ltd. anchors specialty microcrystalline wax production for Japanese automotive and electronics sealant markets. Sasol Limited competes through Fischer-Tropsch synthetic wax capacity positioned for high-performance coatings in Australia and Southeast Asia.
Asia-Pacific wax comprises hydrocarbon or ester-based solids with melt points typically spanning 46°C to 68°C, manufactured via solvent deoiling, hydrogenation, or biomass extraction for lubrication, barrier formation, or surface modification roles. Paraffin wax dominates volume flows through mature candle and packaging channels where margin compression is routine. Synthetic wax captures expanding share in coatings and automotive applications where thermal stability specifications exceed natural wax performance ceilings. Natural wax, including carnauba and beeswax variants, occupies premium cosmetics and food-grade segments where clean-label positioning commands price premiums.
China's SAMR enforces GB standards governing food-contact wax purity and additive migration limits, while Japan's METI administers JIS quality benchmarks for industrial wax grades across automotive and electronics supply chains. India's BIS certification requirements for packaging materials and personal care inputs are raising compliance barriers for unqualified imports. Stakeholders must monitor regulatory divergence between national standards regimes as formulation specifications harden and cross-border certification costs escalate.
Market Dynamics
China's SAMR enforcement of GB standards on food-contact wax purity is forcing reformulation investments across the Asia-Pacific supplier base, while plant-based alternatives recalibrate input economics for candle and cosmetics manufacturers.
Growth Catalysts
- India's BIS certification requirements:India's BIS certification requirements for packaging materials are raising compliance barriers for unqualified imports, creating captive demand for domestic wax suppliers around Mumbai and Ahmedabad manufacturing corridors.
- Automotive sealant specifications:Japanese automotive OEMs are expanding microcrystalline wax procurement for underbody coatings and electronics sealants as thermal stability requirements exceed natural wax performance ceilings.
- Cosmetics formulator expansion:Southeast Asian cosmetics formulators are expanding wax procurement for color cosmetics and skincare emulsions, concentrating demand in Thailand and Indonesia production hubs.
Market Restraints
- Tallow and palm input volatility:Animal-derived and palm-based wax feedstocks face price swings tied to agricultural commodity cycles, compressing margin predictability for candle manufacturers.
- Refinery supply concentration:Bulk paraffin supply concentrates among integrated petrochemical operators in China and South Korea, creating dependency risk for independent packaging converters.
- Natural wax performance ceilings:Carnauba and beeswax variants cannot meet thermal stability specifications above 80°C, limiting penetration into high-performance coatings and automotive applications.
Strategic Opportunities
- Vietnam packaging corridor:Vietnam's export-oriented packaging industry remains underpenetrated by specialty wax suppliers, offering first-mover positioning for synthetic wax producers serving corrugated and flexible film converters.
- Fischer-Tropsch synthetic wax:Fischer-Tropsch synthetic wax capacity is capturing share in Australian mining equipment lubricants where extreme pressure and thermal stability specifications exceed conventional paraffin limits.
- Japan's METI quality benchmarks:Japan's METI administration of JIS quality benchmarks for industrial wax grades creates premium positioning opportunities for suppliers achieving certification across automotive and electronics supply chains.
Industry Challenges
- Cross-border certification complexity:Divergence between China's GB standards, Japan's JIS benchmarks, and India's BIS requirements escalates compliance costs for multi-country suppliers.
- Biomass extraction scale-up:Plant-based wax alternatives require capital-intensive solvent extraction and hydrogenation infrastructure that mid-scale producers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Wax Market |
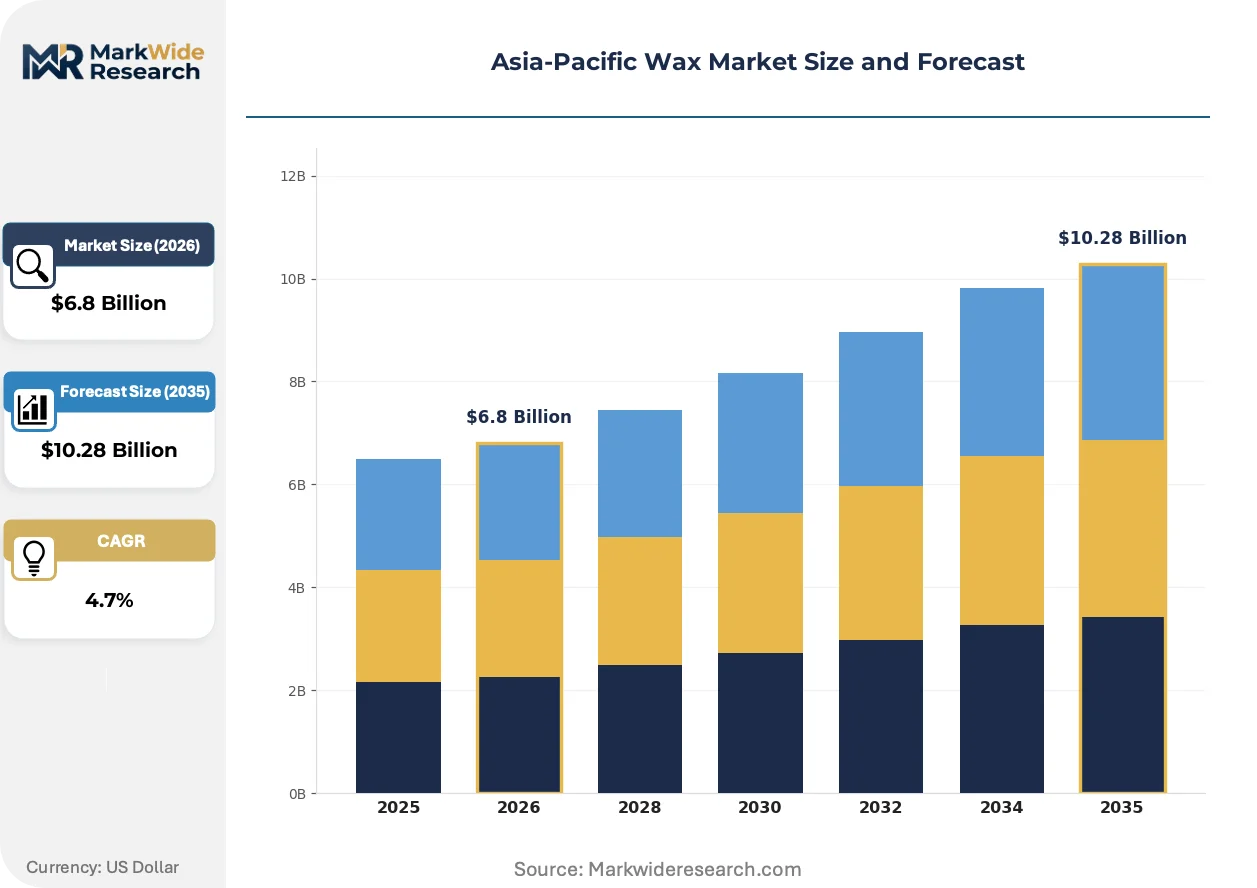
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paraffin Wax, Microcrystalline Wax, Natural Wax, Synthetic Wax Application: Candles, Packaging, Coatings, Cosmetics End User: Food Industry, Pharmaceutical, Personal Care, Automotive Form: Solid, Liquid, Emulsion, Gel |
| Companies Covered | Sinopec Group, Petro China Company Limited, Nippon Seiro Co., Ltd., Sasol Limited, Exxon Mobil Corporation, The Dow Chemical Company, BASF SE, Evonik Industries AG, The International Group, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Wax Market Trends and Innovations
Technology convergence between synthetic wax production and bio-based feedstock processing is rewriting cost structures across the Asia-Pacific value chain, while regulatory fragmentation accelerates specialization.
Enzymatic esterification of fatty acid distillates is converging with traditional hydrogenation pathways to produce mid-range melt-point waxes. Indonesian oleochemical producers are adopting this hybrid approach at commercial scale. The technology is converging with established paraffin infrastructure, enabling integrated refiners to serve both premium cosmetics and industrial coatings segments without dedicated biomass facilities.
China's MEE enforcement of dual carbon goals is tightening emissions standards for solvent deoiling operations in Shandong and Jiangsu provinces. Industrial wax producers must retrofit facilities with carbon capture or switch to hydrogenation-heavy processes. Synthetic wax manufacturers with Fischer-Tropsch capacity are gaining regulatory preference in high-specification coatings procurement.
Direct procurement contracts between Japanese automotive OEMs and specialty wax producers are displacing distributor-mediated supply in sealant and underbody coating applications. Tier-1 suppliers in Nagoya and Hiroshima clusters now specify JIS-certified microcrystalline grades through annual volume agreements. This pattern concentrates most visibly in electronics and electric vehicle battery thermal management applications.
Asia-Pacific Wax Market Segmentation
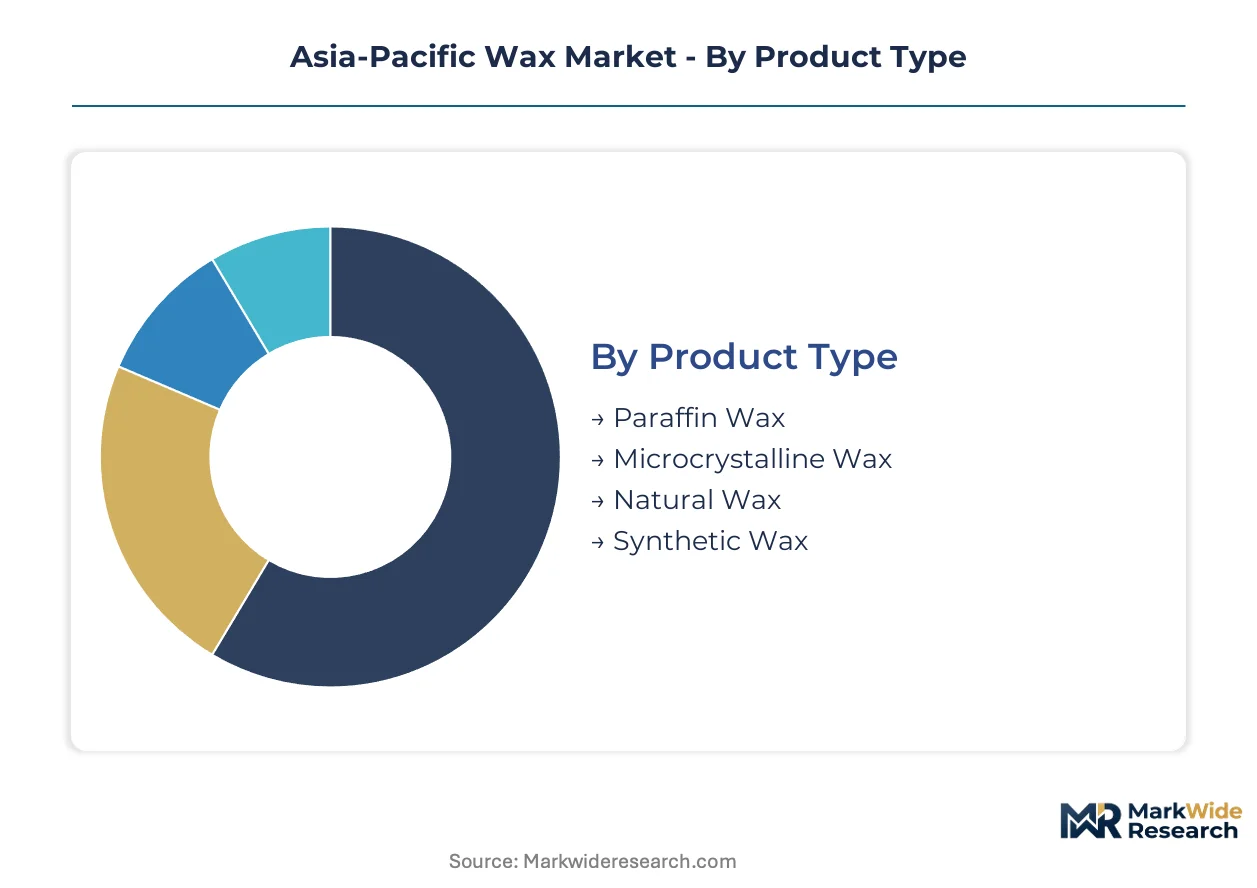
Wax segmentation across Asia-Pacific reflects divergent technical specifications and regulatory compliance burdens. Each category channels procurement decisions toward distinct supplier capabilities and certification requirements.
Product Type:
Customization intensity varies from commodity paraffin to precision-engineered synthetic grades, with formulation flexibility determining margin capture across the spectrum.
- Paraffin Wax:Straight-chain alkanes refined via solvent deoiling from slack wax feedstock dominate volume flows through candle and corrugated packaging channels. China's integrated refiners in Shandong and Jiangsu provinces anchor bulk supply contracts, though MEE emissions enforcement is forcing hydrogenation retrofits that compress margins for independent processors.
- Synthetic Wax:Fischer-Tropsch and polyethylene-derived structures deliver thermal stability above 100°C for automotive underbody coatings and mining equipment lubricants. Sasol's capacity positioning serves Australian extreme-pressure applications where natural wax performance ceilings exclude incumbent suppliers.
- Microcrystalline Wax:Branched and cyclic hydrocarbons with higher melt viscosity anchor Japanese electronics sealants and battery thermal management systems under METI-administered JIS benchmarks.
- Natural Wax:Carnauba, beeswax, and rice bran variants command clean-label premiums in Thai and Indonesian cosmetics formulation despite agricultural yield volatility constraining supply security.
Most installed capacity flows through Paraffin Wax. Expansion is steepest in Synthetic Wax.
Application:
Volume concentration in mature channels contrasts with value migration toward performance-specified industrial coatings.
- Coatings:Synthetic and microcrystalline grades with controlled melt viscosity enable corrosion-resistant films for automotive OEMs in Nagoya and Hiroshima clusters. Direct procurement contracts between Japanese manufacturers and certified suppliers are displacing distributor channels, concentrating annual volume agreements among JIS-qualified producers.
- Cosmetics:Southeast Asian formulators in Bangkok and Jakarta are expanding procurement for color cosmetics and skincare emulsions, with plant-based alternatives recalibrating input economics as tallow and palm face cost volatility.
- Candles:Paraffin remains dominant though margin compression is routine; Indian manufacturers around Mumbai face BIS certification barriers on imported feedstocks.
- Packaging:Food-contact wax coatings for corrugated and flexible film converters must comply with China's SAMR GB standards on additive migration limits, raising reformulation investments across the supplier base.
Volume leadership sits with Candles. Value expansion is climbing fastest in Coatings.
End User:
Regulatory stringency fragments procurement requirements across food safety, pharmaceutical purity, and automotive thermal specifications.
- Food Industry:GB standards on food-contact material purity and migration limits enforced by China's SAMR are tightening formulation requirements, disqualifying unqualified imports from regional supply chains.
- Automotive:Japanese OEMs specify microcrystalline grades for sealant and battery thermal management applications where thermal cycling resistance exceeds 80°C.
- Personal Care:India's BIS certification for packaging materials and personal care inputs concentrates demand around Mumbai and Ahmedabad manufacturing corridors.
- Pharmaceutical:Excipient-grade wax requirements for tablet coatings and controlled-release matrices demand documented purity certificates from CDSCO-registered suppliers.
Procurement scale concentrates in Food Industry. Certification complexity is expanding most quickly in Pharmaceutical.
Form:
Physical state determines handling infrastructure and formulation integration costs across downstream processing.
- Solid:Slab and pellet forms dominate bulk logistics for candle manufacturers and packaging converters with established melting and blending equipment.
- Emulsion:Aqueous dispersions enable direct incorporation into water-based cosmetics and coatings without solvent handling, penetrating Thai and Indonesian personal care production hubs.
- Liquid:Molten bulk delivery reduces energy costs for high-volume automotive sealant processors with heated storage infrastructure.
- Gel:Structured formulations with controlled thixotropy serve specialty pharmaceutical and personal care applications requiring precise rheological behavior.
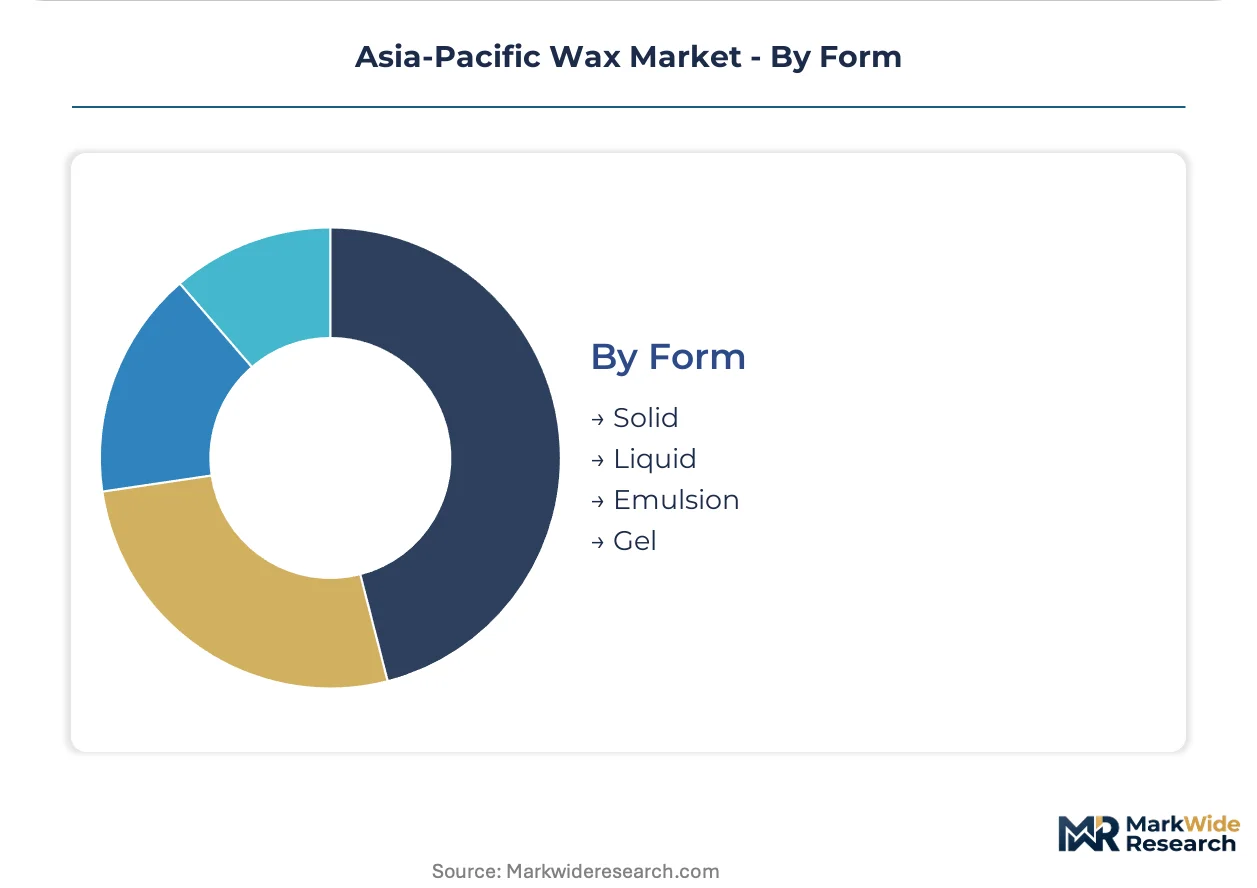
Logistics infrastructure favors Solid. Formulation flexibility is gaining share fastest in Emulsion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong and Jiangsu provinces anchor Asia-Pacific wax production through integrated refinery complexes supplying bulk paraffin to packaging converters across East Asia. China's SAMR enforcement of GB standards on food-contact material purity is forcing reformulation investments among suppliers serving corrugated and flexible film channels. Japanese automotive OEMs in Nagoya and Hiroshima clusters are expanding microcrystalline wax procurement for sealant and battery thermal management applications.
China
Integrated petrochemical operators in Shandong and Jiangsu provinces sustain bulk paraffin supply contracts for domestic packaging converters. MEE enforcement of dual carbon goals is tightening emissions standards for solvent deoiling operations, forcing hydrogenation retrofits. Wax producers in these coastal provinces face margin compression as they adapt to cleaner production mandates.
Japan
Automotive OEMs specify METI-administered JIS-certified microcrystalline grades for underbody coatings and electronics sealants. Direct procurement contracts between manufacturers and certified suppliers are displacing distributor channels. Tier-1 suppliers in Nagoya and Hiroshima clusters now anchor annual volume agreements for thermal management applications.
India
BIS certification requirements for packaging materials and personal care inputs are raising compliance barriers for unqualified imports. Domestic wax suppliers around Mumbai and Ahmedabad manufacturing corridors capture captive demand from pharmaceutical and cosmetics formulators. CDSCO-registered suppliers dominate excipient-grade wax procurement for tablet coatings.
South Korea
Integrated refinery operations sustain bulk paraffin supply to regional packaging converters, creating dependency concentration for independent processors. The country's industrial wax producers serve both domestic coatings manufacturers and export markets across Southeast Asia. Busan-Ulsan petrochemical clusters anchor synthetic wax capacity for high-specification applications.
Vietnam
Export-oriented packaging industry remains underpenetrated by specialty wax suppliers despite expanding corrugated and flexible film production. First-mover positioning is available for synthetic wax producers serving converters in Ho Chi Minh City and Hanoi industrial zones. Local formulators lack access to JIS-certified or GB-compliant specialty grades.
Asia-Pacific Wax Market Competitive Landscape
Global majors compete with regional champions across certification requirements and feedstock integration levels. The vendor base organizes around three tiers: integrated petrochemical operators with captive refinery supply, specialty synthetic wax producers with Fischer-Tropsch or hydrogenation assets, and natural wax processors serving premium cosmetics segments. Dominant competitive moves include backward integration into slack wax feedstock and pursuit of multi-jurisdiction certification portfolios spanning China's GB standards, Japan's JIS benchmarks, and India's BIS requirements.
Among China-based integrated operators, Sinopec Group and Petro China Company Limited exemplify the refinery-anchored archetype with captive paraffin supply chains. Nippon Seiro Co., Ltd. occupies a position within the specialty microcrystalline tier serving Japanese automotive and electronics certification requirements. Sasol Limited represents the Fischer-Tropsch synthetic wax archetype positioned for extreme-pressure applications in Australian mining equipment lubricants.
| Leading Market Players |
|---|
| Sinopec Group |
| Petro China Company Limited |
| Nippon Seiro Co., Ltd. |
| Sasol Limited |
| Exxon Mobil Corporation |
| The Dow Chemical Company |
| BASF SE |
| Evonik Industries AG |
| The International Group, Inc. |
| Others |
Pricing and Supply Chain Analysis
Slack wax feedstock costs from Shandong and Jiangsu refineries cascade through three distinct pricing tiers, with hydrogenation-heavy processing premiums separating JIS-certified microcrystalline grades for Japanese automotive OEMs from commodity paraffin slabs serving Indian candle manufacturers facing BIS compliance barriers.
Pricing Analysis
Input-cost pass-through from petroleum-derived slack wax and palm fatty acid distillates shapes tiered pricing across the value chain. Price differentiation hinges on certification grade—GB-compliant food-contact coatings command premiums over industrial grades—and volume scale, with annual offtake agreements anchoring Japanese automotive procurement. Pricing pressure stems from MEE emissions enforcement forcing hydrogenation retrofits among independent Chinese processors. Small-scale Indian candle manufacturers exhibit highest price sensitivity, while Japanese Tier-1 sealant suppliers prioritize thermal stability specifications over unit cost.
Supply Chain Analysis
India's BIS domestic-content mandates for packaging materials and personal care inputs are reshaping sourcing patterns, redirecting procurement toward Mumbai and Ahmedabad manufacturing corridors. Geographic supply concentration centers on China, South Korea, and Japan, with integrated refinery operations in Shandong and Busan-Ulsan clusters feeding regional packaging converters. Raw material dependencies span petroleum slack wax, palm kernel stearin, and Fischer-Tropsch synthetic feedstocks. Single-source vulnerability concentrates around Sinopec and PetroChina paraffin dominance. Distribution runs through direct procurement contracts displacing distributor channels in Japanese automotive and electronics segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific Wax Market functions as a geographic-arbitrage play where India's BIS certification costs for unqualified imports create 15-20% effective price wedges against Chinese commodity grades, rewarding localized production investments.
For Market Incumbents: Deepen backward integration into slack wax feedstock through captive refinery relationships or long-term offtake agreements with Shandong and Jiangsu operators. Expand JIS certification coverage across Nagoya and Hiroshima automotive clusters to defend against Sasol's Fischer-Tropsch encroachment in Australian mining lubricants. Prioritize hydrogenation capacity additions ahead of MEE emissions enforcement deadlines.
For New Entrants and Emerging Players: Enter via Vietnam's underpenetrated packaging corridor, where Ho Chi Minh City and Hanoi converters lack access to GB-compliant or JIS-certified specialty grades. Target synthetic wax supply for corrugated and flexible film applications. Pursue direct technical service partnerships with Vietnamese converters rather than distributor-mediated channels.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale hydrogenation specialists because MEE compliance investments are fragmenting Chinese independent processors into sub-scale, distressed sellers. Five-to-ten-year viability hinges on certification portfolio breadth spanning GB, JIS, and BIS requirements. Watch for CDSCO registration acceleration among Indian excipient-grade suppliers as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Slack Wax Feedstock | Sinopec's captive refinery supply secures margin control against volatile petroleum input costs. |
| JIS Certification Investment | Nippon Seiro's METI-qualified microcrystalline grades lock in annual volume agreements with Nagoya automotive OEMs. |
| Hydrogenation Capacity Retrofit | MEE emissions enforcement in Shandong forces solvent deoiling phaseout, raising barriers for independent processors. |
| Vietnam Packaging Corridor Entry | First-mover synthetic wax suppliers capture Ho Chi Minh City converters lacking GB-compliant specialty grades. |
| Fischer-Tropsch Capacity Expansion | Sasol's synthetic wax positioning serves Australian mining equipment lubricants where thermal stability exceeds paraffin limits. |
Research Methodology
Bottom-up coatings and cosmetics modeling reconciled against top-down refinery output tracking forms the analytical core of this study. Primary interviews with procurement managers at Japanese automotive OEMs, technical directors at Indian pharmaceutical formulators, plant managers at Shandong hydrogenation facilities, and channel partners in Bangkok and Jakarta personal care clusters were validated against secondary sources including China customs trade data, METI industrial production statistics, BIS certification registries, and SEC filings from listed petrochemical operators.
Input-output matrices mapping slack wax feedstock availability through hydrogenation and solvent deoiling capacity to end-use demand across candles, packaging, coatings, and cosmetics segments structured the projection framework. Segmentation dimensions encompassed product type, application, end user, and physical form, with melt-point specifications and certification requirements as cross-cutting variables. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion timelines across the analysis window.
Inputs from Chinese refinery operators and Japanese automotive procurement officers were available through the study window; gaps in real-time Fischer-Tropsch capacity utilization data introduce uncertainty bands around synthetic wax share projections. Forecasts reflect documented assumptions on MEE enforcement timing and BIS certification adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Octylphenol Ethoxylate Market
Oleochemicals
Isopropyl Esters Market
Oleochemicals
Lauryl Betaine Market
Oleochemicals
Global Fatty Amides Market
Oleochemicals
Global White Oil Market
Oleochemicals
Octyl Octanoate Market
Oleochemicals
Isodecyl Pelargonate Market
Oleochemicals
Stearic Acid Market
Oleochemicals
Sodium Stearoyl Lactylate Market
Oleochemicals
Global Emollient Esters Market
Oleochemicals
Butyl Stearate Market
Oleochemicals
Ethylhexyl Palmitate Market
Oleochemicals
Oleochemicals Market
Oleochemicals
Aminoethylethanolamine Market
Oleochemicals
Oxo-Octyl Acetate Market
Oleochemicals
Iso-Octene Market