
 Global Lubricant Antioxidants Market | 2026-2036
Global Lubricant Antioxidants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lubricant Antioxidants Market Outlook
API Group III and above base oil compatibility standards are redrawing procurement priorities across the lubricant antioxidants value chain. BASF SE leverages its phenolic antioxidant technology leadership to anchor European automotive OEM supply contracts. ADEKA Corporation sustains its position in aminic antioxidant specialization through integrated manufacturing complexes in Japan and Singapore. Evonik Industries AG differentiates via high-purity phosphite esters designed for hydrocracked base oil stability.
Lubricant antioxidants are chemical additives that inhibit oxidative degradation of hydrocarbon-based oils through radical scavenging and peroxide decomposition mechanisms, typically formulated at treat rates between 0.1% and 5.0% by weight depending on base oil quality and operating severity. Their primary purpose is to extend fluid service life, reduce sludge formation, and maintain viscosity stability in high-temperature mechanical systems. Phenolic antioxidants occupy the largest volume share due to cost-effective performance in general industrial oils, while phosphite variants represent the fastest-expanding category driven by synergistic hydroperoxide decomposition demand in Group II and III automotive formulations. Aminic chemistry retains margin concentration in aerospace and marine applications where thermal stress thresholds exceed phenolic decomposition temperatures.
EPA emissions regulations and REACH substance restrictions are jointly constraining traditional ZDDP-dependent antioxidant systems and accelerating organo-phosphite and hindered phenol adoption in North American and European lubricant markets. China's MEE dual carbon targets and India's BIS automotive lubricant standards are creating parallel compliance pathways that favor low-sulfur, low-ash antioxidant packages in Asia-Pacific manufacturing hubs. Stakeholders must monitor evolving OEM factory-fill specifications and regional chemical registration requirements to align R&D pipelines with diverging regulatory timelines.
Market Dynamics
API Group III base oil migration is compressing treat rate tolerance windows and forcing antioxidant suppliers to reformulate for hydrocracked hydrocarbon stability at lower sulfur thresholds. This structural shift is redrawing procurement specifications across automotive OEM factory-fill contracts.
Growth Catalysts
- Extended-drain engine oil specifications:Automotive OEMs in Germany and Japan now mandate 15,000+ kilometer service intervals. This specification inflation requires higher-performance phenolic and aminic antioxidant packages.
- China MEE dual carbon enforcement:China's Ministry of Ecology and Environment is tightening industrial emissions benchmarks. Domestic lubricant blenders must source low-sulfur, low-ash antioxidant systems to maintain operating licenses.
- Marine cylinder oil thermal stress:Two-stroke marine engines operating on ultra-low-sulfur fuel generate elevated combustion chamber temperatures. Aminic antioxidant chemistry retains performance advantage where phenolic systems thermally degrade.
Market Restraints
- Alkylphenol feedstock volatility:Hindered phenol production depends on propylene dimer and phenol derivatives. Petrochemical feedstock price swings compress formulation margin predictability for additive suppliers.
- Phosphite ester supply concentration:High-purity phosphite manufacturing clusters in Japan and Singapore. Geopolitical friction or logistics disruption threatens hydroperoxide decomposition chemistry availability.
- ZDDP substitution technical ceiling:Zinc dialkyldithiophosphate retains anti-wear synergy that organo-phosphite systems cannot fully replicate. Complete ZDDP displacement remains formulation-constrained in high-load automotive applications.
Strategic Opportunities
- India BIS lubricant standardization:India's Bureau of Indian Standards is implementing mandatory performance tiers for automotive and industrial lubricants. Domestic blending capacity expansion creates specification-grade antioxidant demand.
- Wind turbine gearbox fluid longevity:Offshore wind installations require 7-10 year fluid service life. Synthetic ester base oils paired with ashless antioxidant systems address this emerging application.
- Digital additive dosing integration:Real-time treat rate optimization via in-line spectroscopy enables precision antioxidant consumption. This technology convergence reduces over-treatment waste and extends fluid monitoring intervals.
Industry Challenges
- REACH substance registration timelines:New antioxidant chemistries face 18-36 month European Chemicals Agency evaluation windows. Product launch delays compress commercialization runway against specification deadlines.
- Base oil-antioxidant compatibility testing:Group III and GTL base oil polarity shifts require reformulation validation. Each OEM factory-fill approval demands 12-18 month engine and field test cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lubricant Antioxidants Market |
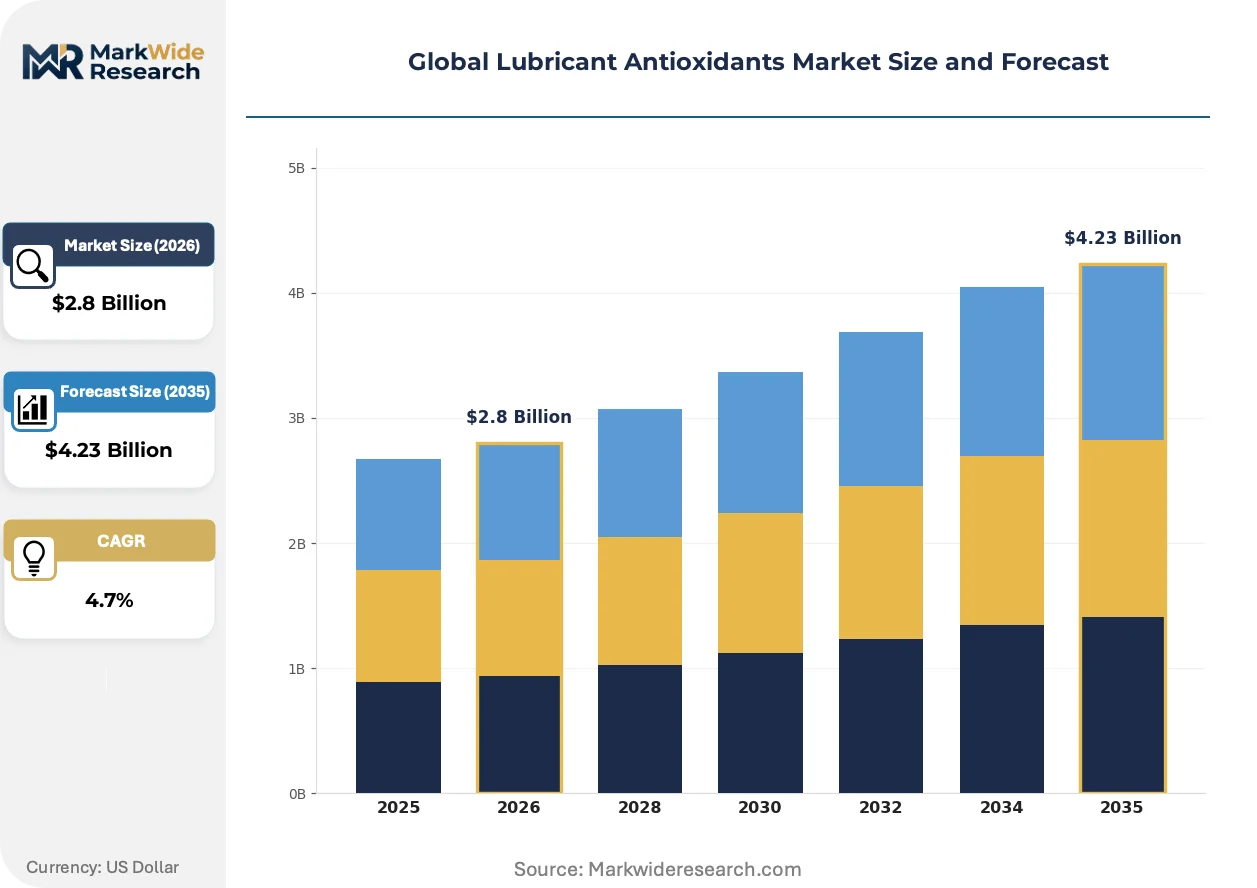
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phenolic, Aminic, Phosphite, Thioester Application: Automotive Oils, Industrial Oils, Greases, Metalworking Fluids End User: Automotive, Aerospace, Marine, Manufacturing Distribution Channel: Direct Sales, Distributors, Online Retailers, Others |
| Companies Covered | Evonik Industries AG, ADEKA Corporation, BASF SE, Dover Chemical Corporation, SI Group Inc., SONGWON Industrial Group, Clariant AG, 3V Sigma USA Inc., Solvay S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lubricant Antioxidants Market Strategic Shifts
Hindered phenol and phosphite ester co-additive systems are displacing legacy ZDDP-dependent packages as thermal stability and emissions compliance harden in parallel. Formulation science is converging on ashless chemistry to satisfy diverging regional mandates.
Organo-phosphite antioxidants are decomposing hydroperoxides in Group II and III base oils without introducing sulfur or metallic ash. Automotive OEMs in Germany and Japan are accelerating factory-fill adoption of these systems. This chemistry transition is decomposing traditional ZDDP market share in passenger car motor oils.
EPA Tier 3 and California LEV III standards are tightening particulate emissions thresholds for gasoline direct injection engines. Lubricant formulators must reduce phosphorus content to protect exhaust aftertreatment systems. North American automotive lubricant specifications are responding with phosphorus caps that favor alternative antioxidant architectures.
Long-term service contracts now bundle fluid analysis with antioxidant replenishment scheduling. Industrial fleet operators in the United States and Germany are displacing spot procurement with integrated fluid management programs. This procurement evolution concentrates buyer power among large-scale maintenance providers and compresses distributor margins.
Global Lubricant Antioxidants Market Segmentation
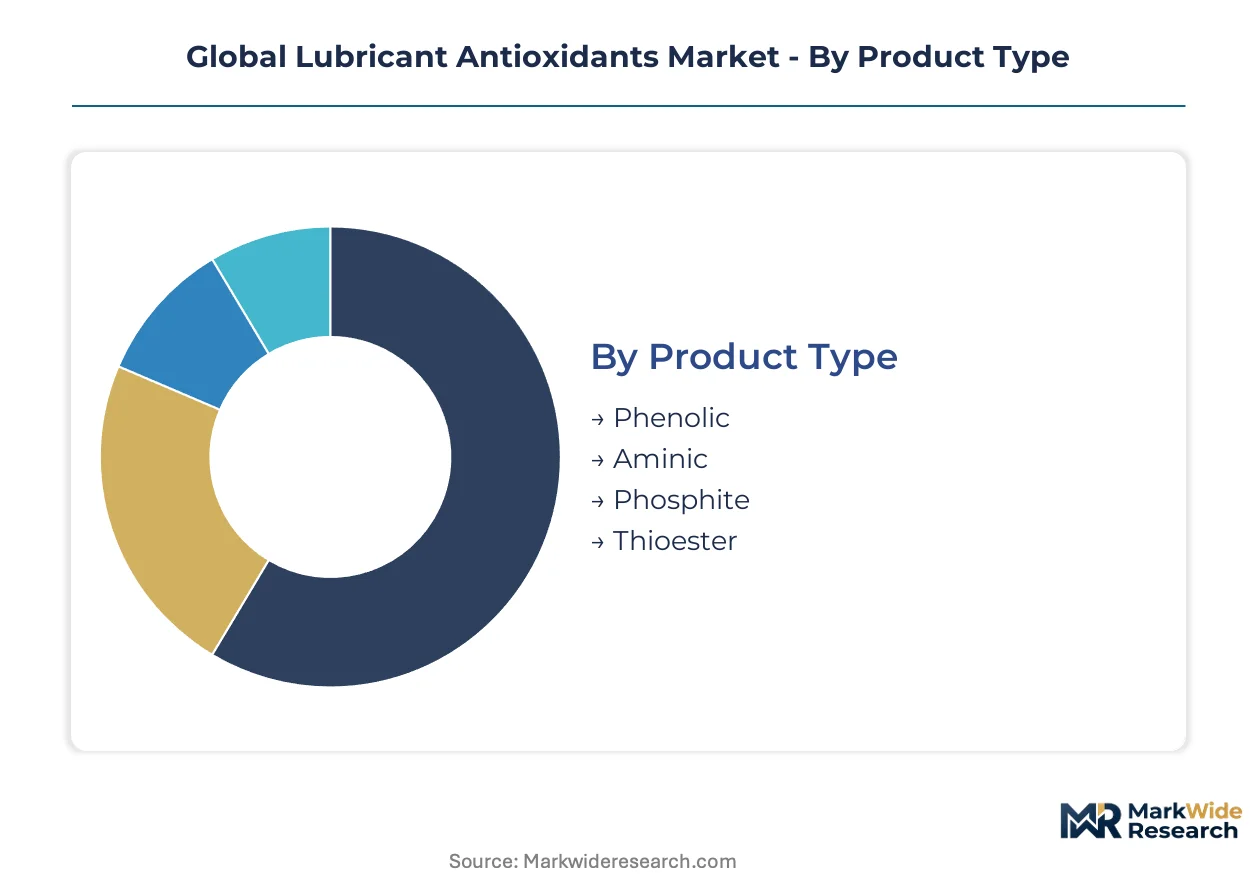
Antioxidant segmentation determines formulation economics and regulatory compliance pathways. Product chemistry governs treat rate requirements and base oil compatibility. Application and end-use dimensions shape procurement specifications and margin structures across automotive and industrial lubricant value chains.
Product Type:
Phenolic systems face intensifying substitution pressure from phosphite and aminic alternatives as sulfur thresholds tighten across automotive specifications.
- Phenolic:Hindered phenol derivatives deliver cost-effective radical scavenging in general industrial and automotive engine oils. Demand concentrates in Germany and China where domestic additive blenders prioritize treat rate economy for high-volume passenger car motor oil production.
- Aminic:Aromatic amine chemistry sustains thermal stability above phenolic decomposition temperatures, anchoring aerospace and marine cylinder oil formulations. Japan's marine engine manufacturers specify aminic packages for two-stroke systems operating on ultra-low-sulfur fuel.
- Phosphite:Organo-phosphite esters decompose hydroperoxides without metallic ash, satisfying EPA Tier 3 phosphorus caps for gasoline direct injection engines.
- Thioester:Sulfur-containing peroxide decomposers retain niche positioning in extreme-pressure industrial gear oils where load-carrying capacity outweighs emissions constraints.
Phenolic chemistry retains volume leadership; phosphite systems hold the steepest expansion curve.
Application:
Cost tier differentiation separates specification-grade automotive formulations from commodity industrial fluid categories.
- Automotive Oils:Factory-fill and service-fill engine oils demand ashless antioxidant architectures to protect exhaust aftertreatment systems. OEM specifications in Japan and Germany mandate extended-drain intervals exceeding 15,000 kilometers, requiring higher-performance phenolic-aminic synergistic packages.
- Industrial Oils:Hydraulic and turbine fluids prioritize cost-efficient phenolic treat rates over thermal extremes. India's manufacturing sector drives volume procurement as domestic blending capacity scales under BIS standardization mandates.
- Greases:Thickener compatibility constraints limit antioxidant selection to phenolic and aminic systems with demonstrated performance in lithium and polyurea soap structures.
- Metalworking Fluids:Water-miscible and neat cutting oils require emulsion-stable antioxidant chemistries resistant to alkaline hydrolysis and microbial degradation.
Automotive Oils command premium formulation values; Industrial Oils anchor absolute volume consumption.
End User:
Customer type concentration elevates procurement sophistication among fleet operators and OEM factory-fill channels.
- Automotive:Passenger car and commercial vehicle OEMs specify antioxidant packages through approved supplier lists. China's automotive production concentration drives regional procurement gravity for specification-grade phenolic and phosphite systems.
- Aerospace:Jet engine and auxiliary power unit lubricants demand aminic chemistry with demonstrated performance above 200°C bulk oil temperatures. Regulatory oversight from FAA and EASA constrains formulation changes to 24-36 month certification cycles.
- Marine:Two-stroke crosshead engine cylinder oils and four-stroke trunk piston systems operate under divergent thermal and sulfur exposure profiles.
- Manufacturing:Discrete and process industry maintenance departments procure industrial lubricants through distributor networks with limited technical specification influence.
Automotive end users dominate value capture; Aerospace maintains the most stringent qualification barriers.
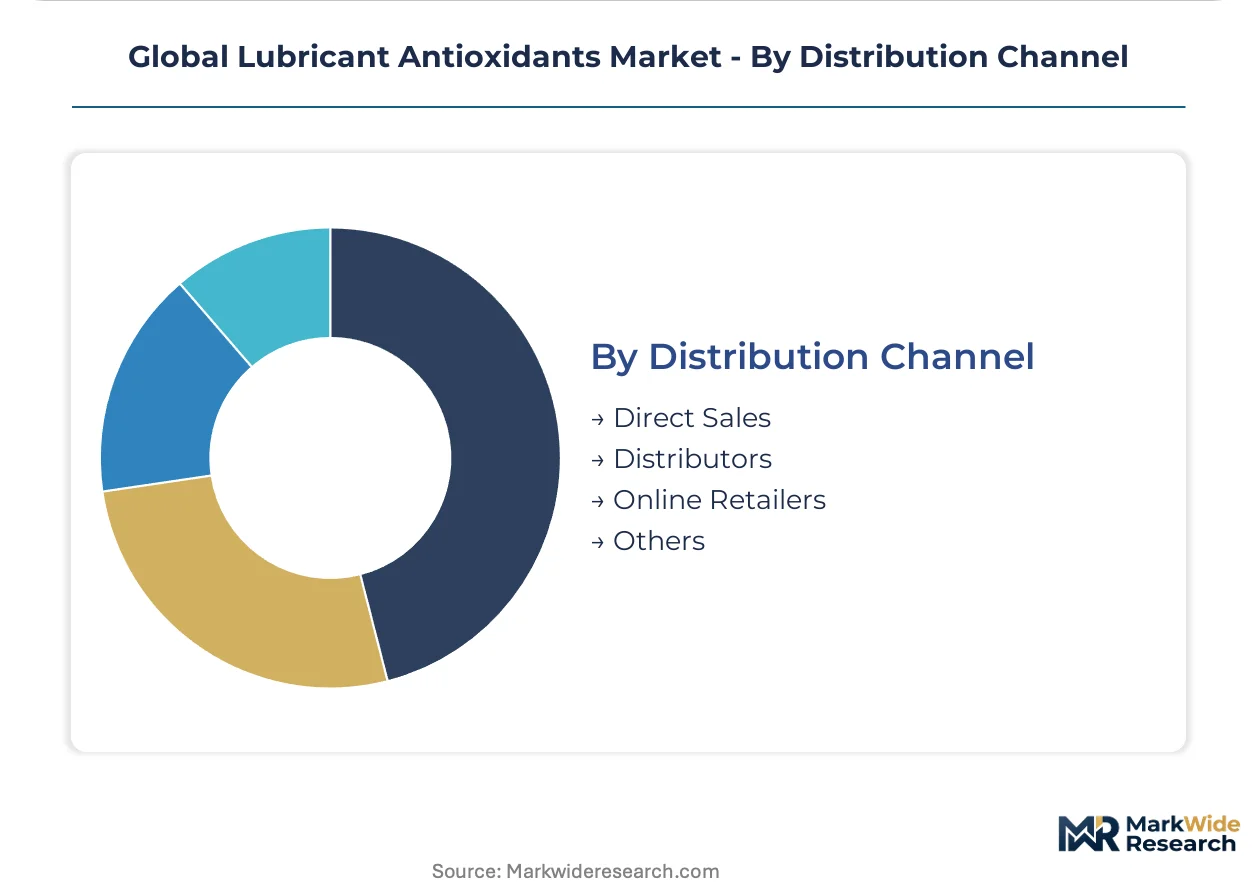
Distribution Channel:
Supply concentration in Japan and Singapore shapes channel economics for phosphite-dependent formulations.
- Direct Sales:Antioxidant suppliers maintain dedicated technical service relationships with multinational lubricant blenders and automotive OEMs. BASF and Evonik deploy direct channels for European and North American automotive factory-fill approvals.
- Distributors:Regional chemical distributors stock phenolic and aminic commodities for mid-tier industrial lubricant blenders. India's domestic market expansion concentrates distributor investment in Mumbai and Gujarat additive hubs.
- Online Retailers:E-commerce penetration remains limited to small-volume maintenance chemicals and aftermarket automotive additives.
- Others:Toll manufacturing and contract blending arrangements serve specialty lubricant formulators without captive antioxidant synthesis.
Direct Sales retains margin concentration; Distributors handle the broadest geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics are reshaping regional procurement patterns for lubricant antioxidants. China and Germany maintain additive formulation surpluses while India and the United States expand domestic blending capacity to reduce import dependency.
China
Domestic additive manufacturing is scaling rapidly under MEE dual carbon enforcement. The Ministry of Ecology and Environment mandates low-sulfur antioxidant systems for industrial lubricant blenders seeking operating licenses. Shandong Province hosts concentrated phenolic antioxidant production complexes serving both domestic automotive OEMs and export markets.
Germany
Automotive OEM factory-fill specifications demand 15,000+ kilometer extended-drain intervals requiring high-performance phenolic-aminic packages. REACH substance restrictions constrain traditional ZDDP-dependent formulations and accelerate ashless chemistry adoption. The Rhine-Ruhr industrial corridor anchors European antioxidant R&D and technical service infrastructure for multinational lubricant blenders.
United States
EPA Tier 3 particulate emissions standards tighten phosphorus thresholds for gasoline direct injection engines. North American lubricant formulators source organo-phosphite alternatives to protect exhaust aftertreatment systems. Texas and Louisiana petrochemical corridors supply hindered phenol feedstocks while Midwest automotive manufacturing clusters drive specification-grade procurement.
India
Bureau of Indian Standards lubricant standardization mandates performance tiers for automotive and industrial fluids. Domestic blending capacity expansion in Maharashtra and Gujarat creates specification-grade antioxidant demand. Mumbai additive hubs concentrate distributor investment serving mid-tier industrial lubricant manufacturers.
Japan
Marine engine manufacturers specify aminic antioxidant packages for two-stroke systems operating on ultra-low-sulfur fuel. METI industrial emissions guidelines align with international maritime organization sulfur caps. Singapore-Japan phosphite manufacturing corridors supply hydroperoxide decomposition chemistry for Group II and III base oil formulations.
Global Lubricant Antioxidants Market Competitive Environment
Concentration sits with integrated chemical conglomerates possessing captive phenol and phosphite synthesis capabilities. The vendor base separates into three tiers: multinational additive suppliers with automotive OEM approval networks, regional specialists in aminic or thioester chemistries, and commodity phenolic distributors serving industrial blenders. Dominant competitive moves include backward integration into alkylphenol feedstocks and technology licensing partnerships for phosphite ester manufacturing.
Within the integrated chemical conglomerate tier, BASF SE, Evonik Industries AG, and ADEKA Corporation exemplify divergent geographic and technological positioning. BASF SE anchors European automotive supply relationships through its Ludwigshafen headquarters proximity to German OEM technical centers. Evonik Industries AG occupies a position in high-purity phosphite specialization serving North American emissions-compliant formulations. ADEKA Corporation represents Asia-Pacific manufacturing concentration with integrated complexes in Japan and Singapore.
| Leading Market Players |
|---|
| Evonik Industries AG |
| ADEKA Corporation |
| BASF SE |
| Dover Chemical Corporation |
| SI Group Inc. |
| SONGWON Industrial Group |
| Clariant AG |
| 3V Sigma USA Inc. |
| Solvay S.A. |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Shandong Province phenolic antioxidant complexes determines regional price floors for industrial-grade formulations. Scale advantages in China's domestic additive manufacturing compress margins for mid-tier suppliers serving India's BIS-standardized blending sector, while REACH-compliant ashless packages command premium positioning in German automotive factory-fill channels.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the lubricant antioxidants market. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified ashless systems from commodity phenolic grades and unbranded industrial formulations. Price differentiation rests on certification grade alignment with OEM factory-fill approvals and volume scale thresholds above ten-thousand-metric-ton annual commitments. Cost compression in aminic marine cylinder oil grades is intensifying because Singapore-Japan phosphite manufacturing corridors face feedstock volatility. Fleet operators and automotive OEM procurement teams exhibit lowest price sensitivity, while mid-tier industrial lubricant blenders in India's Maharashtra and Gujarat hubs drive spot-market negotiation pressure.
Supply Chain Analysis
Strategic stockpile preferences dominate antioxidant procurement for marine and aerospace applications where aminic chemistry certification cycles extend twenty-four to thirty-six months. Geographic supply concentration centers on China, Japan, and Germany, with Shandong Province phenolic complexes, Singapore-Japan phosphite manufacturing corridors, and Rhine-Ruhr technical service infrastructure anchoring global availability. Raw material dependencies draw from propylene dimer and phenol derivatives for hindered phenol production, phosphite ester intermediates for hydroperoxide decomposition chemistry, and aromatic amine precursors for high-temperature aerospace formulations. Single-source vulnerability threatens phosphite-dependent formulators given manufacturing concentration in Japan and Singapore. Distribution runs through direct technical service relationships for automotive OEM approvals and regional chemical distributors for mid-tier industrial blenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Tier 3 phosphorus caps and REACH substance restrictions are jointly accelerating ashless chemistry displacement of legacy ZDDP-dependent systems, creating a high-growth disruption window for antioxidant suppliers with regulatory-aligned R&D pipelines.
For Market Incumbents: Secure backward integration into alkylphenol feedstocks to defend formulation margin predictability against propylene dimer price volatility. Lock in twelve-to-eighteen-month OEM factory-fill approval cycles for Group III base oil compatibility validation before specification deadlines compress commercialization runways. Capacity addition in India's Maharashtra and Gujarat additive hubs addresses BIS lubricant standardization mandates. For New Entrants and Emerging Players: Anchor in India's domestic blending capacity expansion under Bureau of Indian Standards performance tier mandates, the most penetrable geography for specification-grade antioxidant market entry. Target wind turbine gearbox fluid longevity applications requiring seven-to-ten-year synthetic ester service life, where ashless antioxidant systems face limited incumbent saturation. Pursue toll manufacturing partnerships with established phosphite ester producers to bypass eighteen-to-thirty-six-month European Chemicals Agency registration timelines. For Investors and Strategic Acquirers: Regional specialists with aminic chemistry certification for aerospace and marine thermal stress applications present acquisition targets with durable margin structures. Long-term viability over the five-to-ten-year window hinges on regulatory alignment with diverging regional emissions mandates rather than commodity phenolic volume positioning. Watch EPA Tier 3 enforcement intensity and China MEE dual carbon license revocation patterns as inflection indicators for ashless chemistry adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alkylphenol Feedstocks | Captive propylene dimer supply shields BASF and Evonik from petrochemical volatility compressing formulation margins. |
| REACH-Compliant Ashless Chemistry R&D | Organo-phosphite development addresses EPA phosphorus caps tightening across North American gasoline direct injection engines. |
| India Domestic Blending Capacity Expansion | Maharashtra and Gujarat additive hubs capture BIS-mandated specification-grade demand from automotive and industrial lubricant manufacturers. |
| Long-term Supply Agreements with Marine OEMs | Aminic antioxidant packages for ultra-low-sulfur fuel two-stroke engines lock in Japan's METI-aligned emissions compliance pathways. |
| Digital Additive Dosing Integration | Real-time treat rate optimization via in-line spectroscopy reduces over-treatment waste for industrial fleet operators in Germany and the United States. |
Study Parameters
A spread of perspectives from lubricant formulators, automotive OEM procurement leads, additive plant managers, and marine engine manufacturers converged on the working assumptions driving this analysis. Primary interviews with technical R&D directors at integrated chemical conglomerates and distribution channel partners in India and Germany combined with secondary validation from customs and trade data, American Chemistry Council and Cefic sector reports, and SEC 10-K filings from publicly traded additive suppliers. Bottom-up treat rate modeling across phenolic, aminic, phosphite, and thioester chemistries triangulated against top-down automotive production and industrial lubricant consumption estimates.
Segmentation dimensions modeled include antioxidant chemistry type, application category spanning automotive oils, industrial fluids, greases, and metalworking fluids, end-user industry concentration, and regional production hub clustering across the analysis window. CAGRs derived from weighted average of historical volume trajectories and specification-driven demand elasticity for extended-drain and emissions-compliant formulations. Industry-specific forecast inputs incorporate API Group III base oil migration rates and REACH substance registration timeline probabilities.
Underlying assumptions cover regulatory enforcement continuity for EPA Tier 3 and China MEE dual carbon mandates, with deviation risk concentrated in alkylphenol feedstock price volatility and phosphite manufacturing corridor logistics disruption. Forecasts reflect these assumptions without guarantee of realization. Revision becomes warranted when OEM factory-fill specification timelines or European Chemicals Agency evaluation windows cross thresholds that compress commercialization runways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Vietnam Lubricants Market
Lubricants
Food Grade Lubricant Market
Lubricants
Mexico Lubricants Market
Lubricants
Italy Lubricants Market
Lubricants
Aviation Lubricants Market
Lubricants
Qatar Automotive Engine Oils Market
Lubricants
Qatar Lubricants Market
Lubricants
Construction Lubricants Market
Lubricants
China Commercial Vehicles Lubricants Market
Lubricants
United Arab Emirates Lubricants Market
Lubricants
Iraq Lubricants Market
Lubricants
Wire Rope Lubricants Market
Lubricants
Poland Lubricants Market
Lubricants
Italy Commercial Vehicles Lubricants Market
Lubricants
Bulgaria Lubricants Market
Lubricants
North America and Europe Forestry Lubricants Market