
 Advanced Polymer Composites Market | 2026-2036
Advanced Polymer Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Polymer Composites Market Analysis
The EU Green Deal is expanding the addressable market for low-carbon reinforcement fibers across European aerospace and automotive supply chains. Toray Industries dominates carbon fiber precursor technology through integrated PAN-to-fiber operations. Hexcel Corporation anchors North American defense and commercial aviation programs with qualified prepreg systems. BASF SE leverages its polyamide and thermoplastic polyurethane portfolio to compete in automotive structural hybrid solutions.
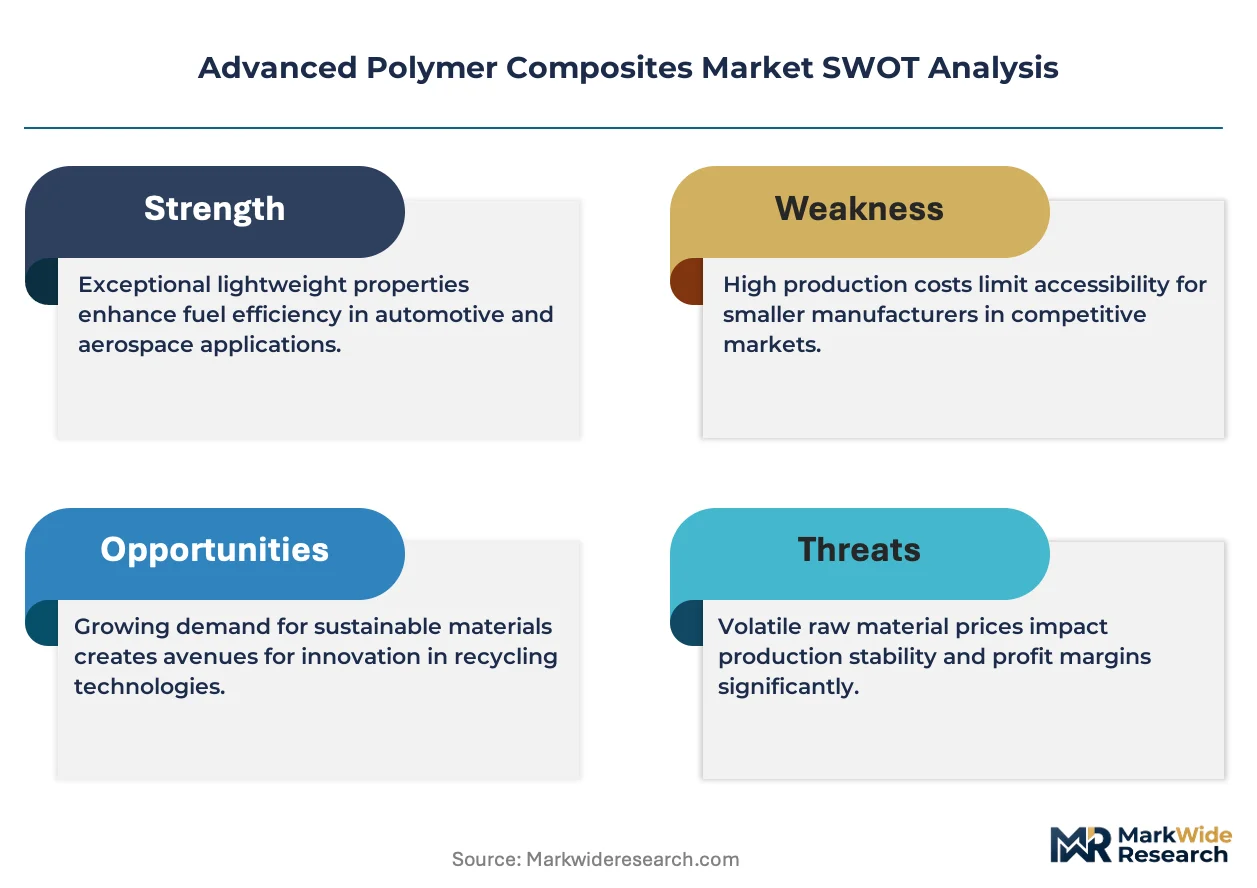
Advanced polymer composites combine high-performance polymer matrices with continuous or discontinuous reinforcement fibers to achieve specific strength-to-weight ratios exceeding conventional metals. These materials typically incorporate epoxy, polyetheretherketone, or polyphenylene sulfide matrices reinforced with carbon, glass, or aramid fibers at fiber volume fractions of 50-70%, serving applications where mass reduction directly translates to fuel efficiency or payload capacity. Thermoplastics command premium positioning in aerospace secondary structures due to weldability and recyclability advantages over thermosetting alternatives. Carbon fiber reinforcement leads value generation despite higher raw material costs, while automated fiber placement displaces hand lay-up in high-rate production environments.
FAA certification requirements for composite primary structure damage tolerance govern market access for North American aerospace suppliers. EASA maintains parallel standards through CS-25 airworthiness codes that European manufacturers must satisfy for type certification. REACH chemical registration obligations constrain resin formulation choices available to producers serving European end users. Stakeholders must monitor evolving battery enclosure standards from NHTSA and China's MIIT as electric vehicle platforms drive the next wave of structural composite specification.
Market Dynamics
Automated fiber placement systems are compressing production cycle times for aerospace primary structures, forcing hand lay-up operations into obsolescence and redrawing capital allocation across the supply base. This equipment transition concentrates manufacturing capability among suppliers with qualified high-rate production lines.
Growth Catalysts
- EU Green Deal industrial emissions benchmarks:Tightening specifications across European aerospace and automotive supply chains are mandating low-carbon reinforcement fibers in structural applications.
- Thermoplastic weldability advantages:Carbon fiber-reinforced thermoplastics enable fusion bonding for aerospace secondary structures, eliminating mechanical fasteners and reducing assembly labor.
- Germany's automotive lightweighting clusters:Stuttgart and Munich anchor concentrated demand for structural hybrid solutions in electric vehicle platforms.
Market Restraints
- Acrylonitrile price volatility:PAN precursor costs fluctuate with propylene feedstock markets, squeezing margin stability for carbon fiber producers.
- Japanese precursor supply concentration:Integrated PAN-to-fiber operations dominate upstream feedstock, creating single-source vulnerability for non-integrated weavers.
- Thermoset recyclability limitations:Epoxy matrix composites face landfill restrictions under REACH chemical registration obligations, constraining end-of-life options for European end users.
Strategic Opportunities
- NHTSA battery enclosure standards evolution:Electric vehicle platform safety mandates are opening specification opportunities for flame-retardant thermoplastic composites in crash-protective housings.
- Automated fiber placement and inline inspection convergence:Real-time defect detection during tow placement is enabling first-time-right production for high-rate aerospace programs.
- India's PLI scheme for advanced materials:Production-linked incentives are attracting prepreg qualification investments for domestic aerospace and defense supply chain localization.
Industry Challenges
- FAA damage tolerance certification timelines:Composite primary structure qualification for transport category aircraft requires extensive test article programs, stretching development schedules.
- Out-of-autoclave process scale-up:OOA curing technologies demand specialized tooling and thermal management expertise that remains scarce across the workforce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Polymer Composites Market |
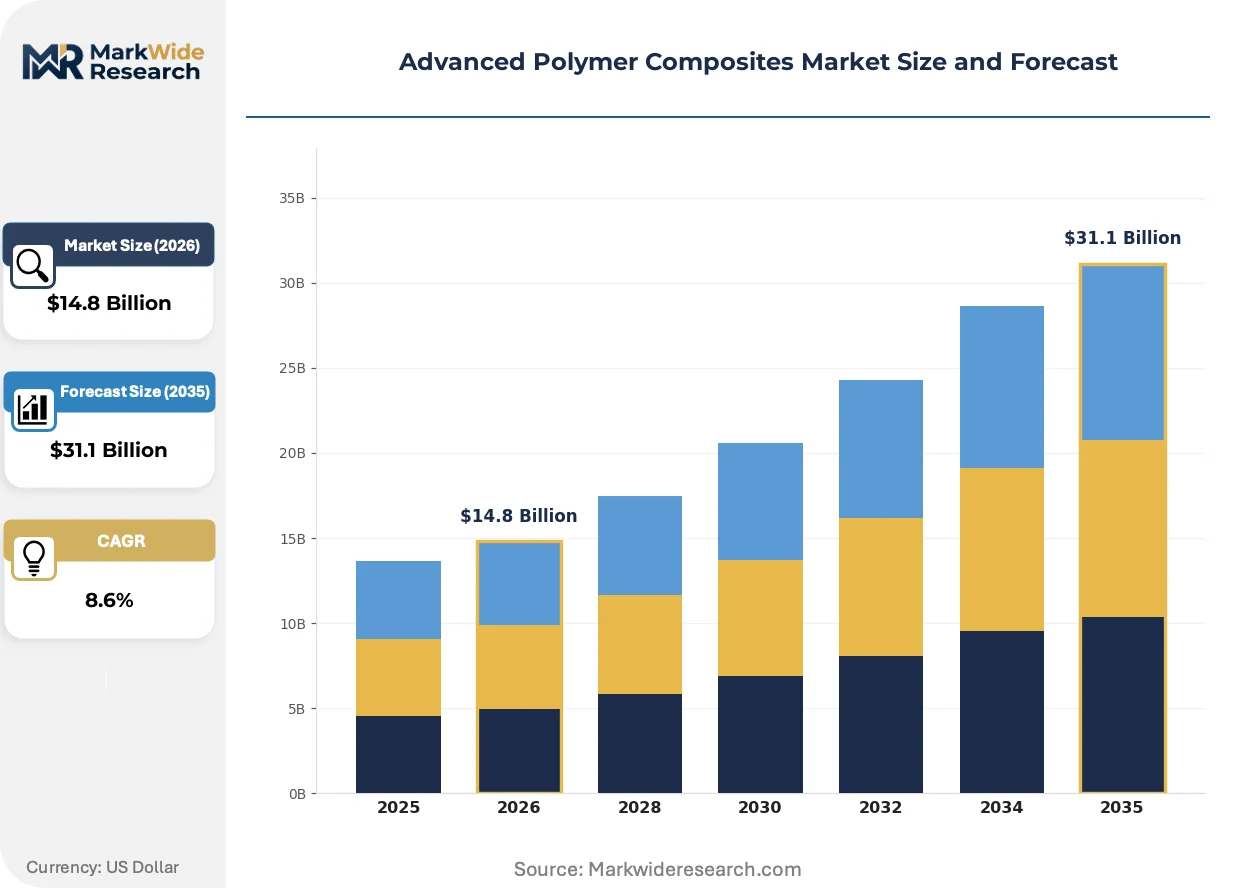
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastics, Thermosetting, Bio-based Composites, Nanocomposites End Use Industry: Aerospace, Automotive, Construction, Marine Reinforcement Type: Glass Fiber, Carbon Fiber, Aramid Fiber, Natural Fiber Manufacturing Process: Hand Lay-Up, Automated Fiber Placement, Resin Transfer Molding, Compression Molding |
| Companies Covered | Teijin Limited, SGL Carbon SE, Toray Industries Inc., BASF SE, Owens Corning, Hexcel Corporation, Mitsubishi Chemical Group Corporation, Huntsman Corporation, Solvay S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Polymer Composites Market Emerging Trajectories
Thermoplastic matrix systems are overtaking thermosets in aerospace secondary structures, enabled by automated fiber placement advances and recyclability mandates. This materials transition is compressing the qualified supplier base while opening new application categories.
Continuous fiber-reinforced thermoplastic tapes are rewriting the economics of aerospace structural assembly. Boeing and Airbus tier suppliers are adopting these materials for fuselage clips and floor beams. The technology is compressing part counts and enabling welded joints that eliminate drilled holes and sealing compounds.
REACH chemical registration obligations are constraining resin formulation choices for producers serving European end users. ECHA substance evaluation processes are extending approval timelines for novel hardener chemistries. Automotive suppliers are responding by qualifying bio-based epoxy alternatives ahead of anticipated restriction expansions.
Buyer consolidation among tier-one aerospace contractors is compressing supplier negotiation cycles and unbundling technical service from material supply contracts. Long-term agreement structures are displacing spot purchasing for carbon fiber prepreg. This shift is most visible in Germany and France, where Airbus supply chain integration has concentrated procurement authority with single-source program managers.
Advanced Polymer Composites Market Segmentation
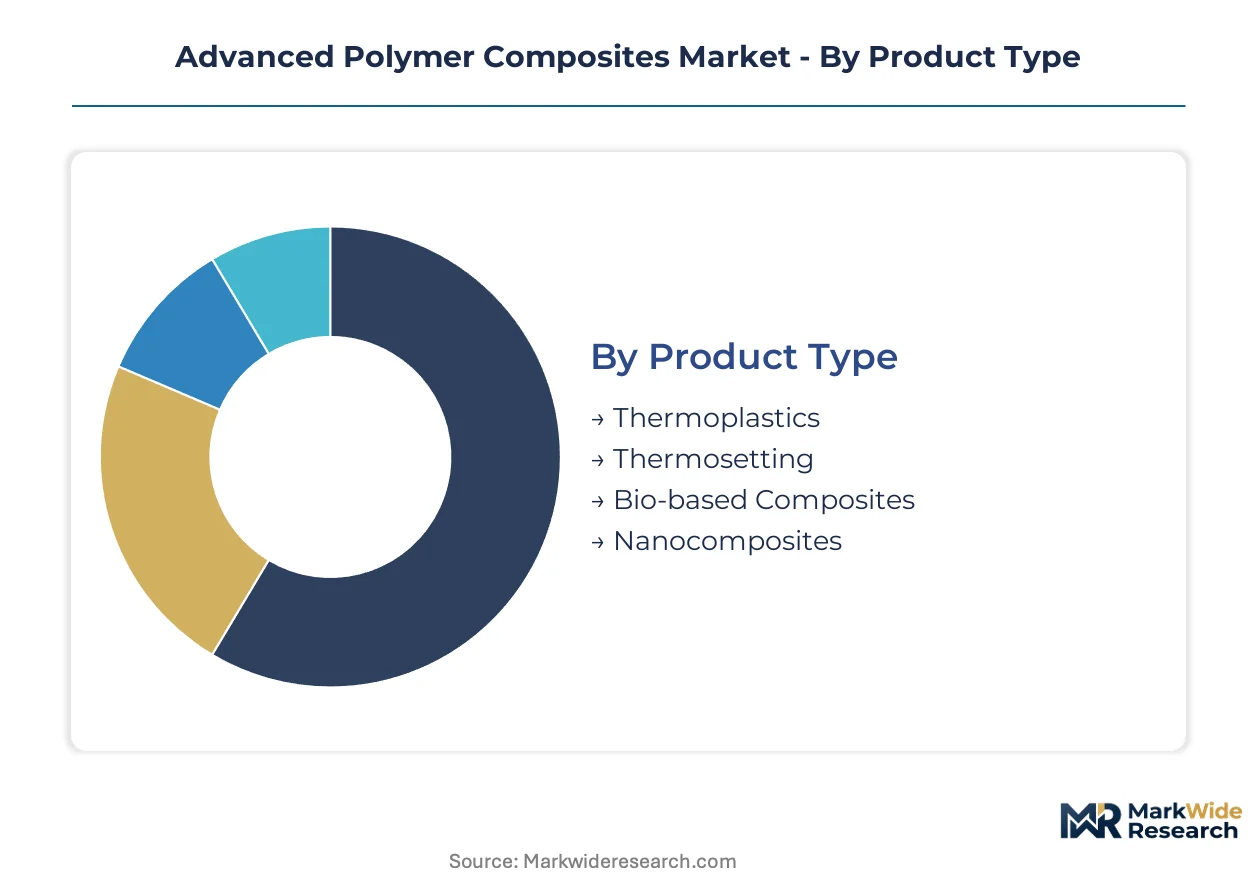
Segmentation in advanced polymer composites reflects divergent technical requirements across aerospace certification grades, automotive crash-performance specifications, and marine corrosion-resistance demands. Buyers select matrix systems and reinforcement architectures based on specific strength-to-weight thresholds, regulatory compliance obligations, and manufacturing throughput constraints.
Product Type:
Buyers prioritize weldability, recyclability mandates, and cycle time economics when selecting matrix chemistry for structural applications.
- Thermoplastics:Polyetheretherketone and polyphenylene sulfide matrices enable fusion bonding and eliminate autoclave curing. Airbus tier suppliers in Germany and France specify carbon fiber-reinforced thermoplastic tapes for fuselage clips to satisfy EASA CS-25 damage tolerance requirements while reducing assembly labor.
- Thermosetting:Epoxy and bismaleimide systems dominate primary aerospace structures requiring elevated temperature performance. Boeing defense programs and Gulfstream business jets rely on qualified prepreg systems with established FAA certification histories, though REACH chemical registration obligations constrain hardener formulation choices for European end users.
- Bio-based Composites:Flax and hemp fiber reinforcements with bio-epoxy matrices address automotive sustainability scoring requirements.
- Nanocomposites:Graphene and carbon nanotube additives enhance electrical conductivity and thermal management for battery enclosures.
Thermosetting leads on scale; thermoplastics lead on momentum.
End Use Industry:
Application-specific certification timelines and performance thresholds segment demand by structural criticality and volume economics.
- Aerospace:Primary and secondary structures demand fiber volume fractions of 55-65% with qualified damage tolerance per FAA and EASA airworthiness codes. Commercial aviation programs in the United States and European Union specify carbon fiber prepreg for wing boxes and empennage structures where mass reduction directly improves fuel efficiency metrics.
- Automotive:Structural hybrid solutions concentrate in Germany's Stuttgart and Munich clusters for electric vehicle platforms. Battery enclosure specifications from NHTSA and China's MIIT drive flame-retardant thermoplastic composite demand for crash-protective housings requiring 10-minute fire resistance.
- Construction:Glass fiber-reinforced polymer rebar and bridge decks address corrosion resistance in coastal infrastructure.
- Marine:Hull structures and superyacht components specify vinylester and epoxy glass laminates for osmotic blister resistance.
Automotive applications are expanding most quickly; aerospace retains premium positioning.
Reinforcement Type:
Raw material cost structures and supply chain concentration determine reinforcement selection for volume-manufactured components.
- Carbon Fiber:PAN-based continuous fibers deliver specific stiffness exceeding aluminum alloys by 3-4x. Japanese integrated producers dominate precursor supply, creating single-source vulnerability for non-integrated weavers serving aerospace programs in the United States and European Union.
- Glass Fiber:E-glass and S-glass rovings provide cost-effective reinforcement for automotive underbody panels and construction profiles. Owens Corning and Jushi Group supply chopped strand mat and direct roving to compression molding operations in China's Jiangsu province and India's Gujarat state.
- Aramid Fiber:Ballistic protection and pressure vessel applications specify Kevlar and Twaron for impact energy absorption.
- Natural Fiber:Jute and kenaf reinforcements serve interior automotive panels with reduced embodied carbon.
Glass fiber leads on scale; carbon fiber leads on value generation.
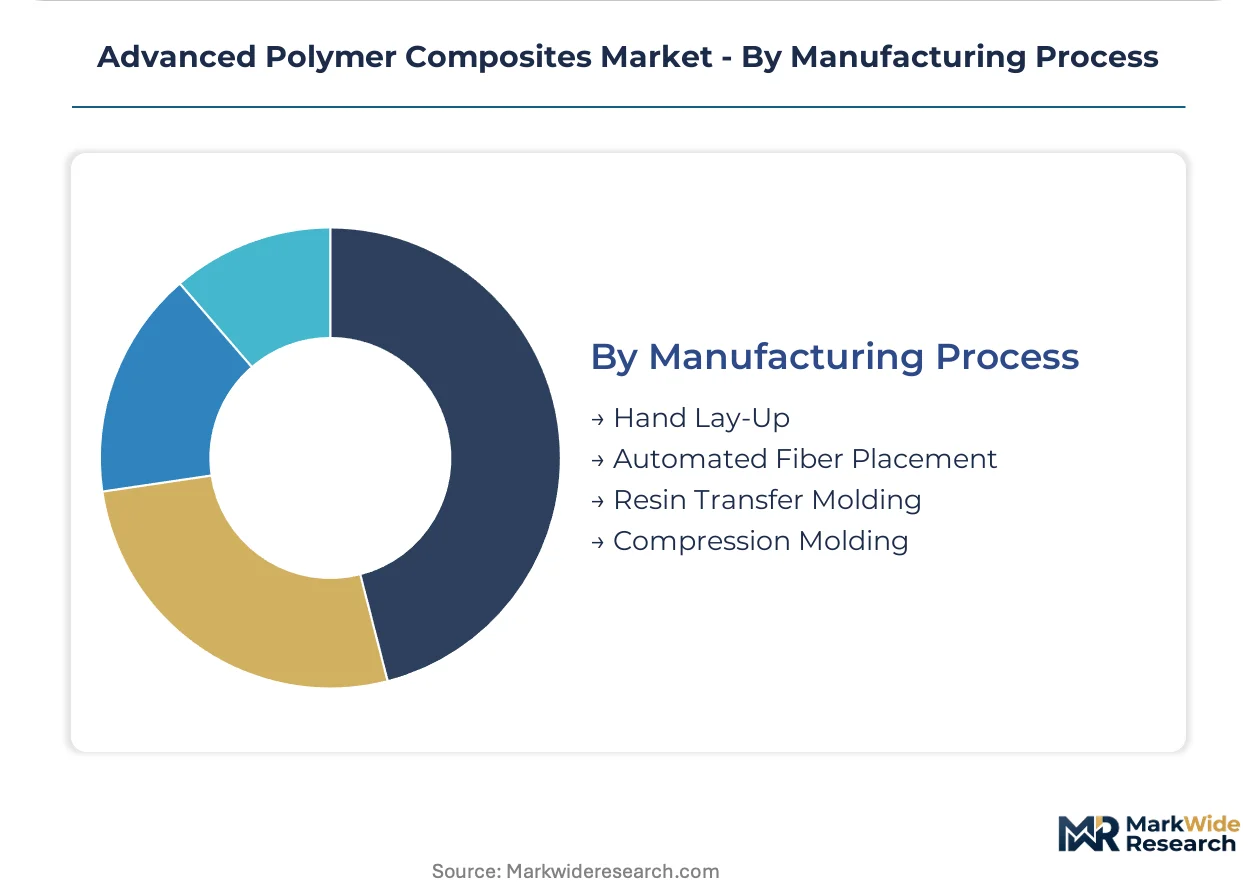
Manufacturing Process:
Capital equipment requirements and labor content differentiate process selection by production rate and part complexity.
- Automated Fiber Placement:Robotic tow placement systems compress aerospace primary structure cycle times from weeks to days. Spirit AeroSystems and GKN Aerospace operate qualified high-rate production lines for Boeing 787 and Airbus A350 fuselage sections, displacing hand lay-up operations into obsolescence.
- Resin Transfer Molding:Closed-mold infusion enables complex automotive structural components with Class A surface finishes. BMW's Leipzig and Spartanburg plants specify RTM for carbon fiber roof panels and body-in-white reinforcements.
- Hand Lay-Up:Tooling flexibility supports low-volume marine and construction applications with skilled labor dependency.
- Compression Molding:High-rate thermoplastic sheet forming serves automotive bumper beams and seat structures.
Automated fiber placement leads on technical advancement; compression molding leads on volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized composites engineers and materials scientists concentrate in aerospace corridors and automotive engineering clusters across four major economies. These talent pools anchor regional competitive advantages in high-performance manufacturing.
United States
Defense aviation programs and commercial space launch platforms drive carbon fiber prepreg demand. FAA damage tolerance certification requirements under Part 25 airworthiness standards govern market access for primary structure suppliers. Wichita, Kansas and Seattle, Washington host concentrated aerospace composites manufacturing for Boeing programs.
Germany
Automotive lightweighting for electric vehicle platforms and Airbus supply chain integration concentrate demand. EU Green Deal industrial emissions benchmarks mandate low-carbon reinforcement fibers across structural applications. Stuttgart and Munich anchor automotive engineering clusters specifying structural hybrid solutions for battery enclosures.
Japan
Integrated PAN-to-carbon-fiber operations and precision manufacturing equipment supply dominate upstream value capture. METI industrial policy supports advanced materials R&D through coordinated industry-academia programs. Nagoya and Tokyo metropolitan areas concentrate aerospace tier suppliers serving Boeing and Airbus programs.
China
Domestic commercial aircraft programs and electric vehicle platform expansion drive thermoplastic composite specification. MIIT battery enclosure standards for new energy vehicles mandate flame-retardant structural materials. Jiangsu province and Shanghai-Pudong host growing automated fiber placement capacity for aviation manufacturing.
India
Aerospace defense localization and automotive component export manufacturing attract prepreg qualification investments. PLI scheme production-linked incentives for advanced materials support domestic supply chain development. Bangalore and Hyderabad anchor composites engineering talent for defense aviation programs.
Advanced Polymer Composites Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures in advanced polymer composites. Integrated PAN-to-fiber operators command upstream pricing power while specialized prepreg formulators compete on qualification speed. Three archetypes dominate: Japanese integrated fiber producers, European chemical conglomerates with matrix portfolios, and North American aerospace-qualified prepreg specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers position for high-rate aerospace programs.
Among Japanese integrated producers, Toray Industries and Mitsubishi Chemical Group occupy positions anchoring global carbon fiber precursor supply. Teijin Limited exemplifies the diversified materials conglomerate archetype with operations spanning aramid and carbon fiber reinforcements. European chemical groups including BASF SE and Solvay S.A. represent matrix chemistry specialists competing through thermoplastic and thermoset resin portfolios. These named entities illustrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Teijin Limited |
| SGL Carbon SE |
| Toray Industries Inc. |
| BASF SE |
| Owens Corning |
| Hexcel Corporation |
| Mitsubishi Chemical Group Corporation |
| Huntsman Corporation |
| Solvay S.A. |
| Others |
Supply Flow & Price Mechanics
EU Green Deal industrial emissions benchmarks are gating qualified supply access and premium-tier pricing power for carbon fiber-reinforced thermoplastics across European aerospace and automotive procurement channels. Buyers without verified low-carbon reinforcement fiber documentation face exclusion from Airbus tier supplier networks and BMW structural hybrid programs, compressing negotiable volume into certified supply pools.
Pricing Analysis
The unbundling of technical service from material supply contracts is separating premium-tier prepreg pricing from standard-grade commodity offerings. Price differentiation separates FAA-qualified primary structure systems from uncertified secondary applications, with volume-scale discounts concentrating among single-source program managers. Pricing pressure stems from acrylonitrile feedstock volatility squeezing carbon fiber precursor margins. Automotive OEM procurement teams in Germany exhibit highest price sensitivity, while defense aviation programs in the United States retain lowest sensitivity due to qualification lock-in.
Supply Chain Analysis
India's PLI scheme for advanced materials is reshaping sourcing patterns by mandating domestic prepreg qualification investments for incentive eligibility. Upstream supply draws from Japanese integrated PAN-to-fiber operations, Chinese glass fiber roving capacity, and German automotive engineering clusters. Single-source vulnerability concentrates in Japanese precursor supply for non-integrated weavers. Distribution runs through qualified tier-one aerospace contractors and automotive OEM direct procurement channels with long-term agreement structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced polymer composites represent a margin-expansion opportunity as automated fiber placement compresses production cycle times and thermoplastic recyclability mandates shift procurement toward premium-tier qualified supply.
For Market Incumbents: Extend qualification portfolios into thermoplastic tape systems for fuselage clips and floor beams to capture Airbus secondary structure demand. Deepen backward integration into PAN precursor supply to defend against Japanese feedstock concentration risk. Anchor capacity expansion in Germany's Stuttgart and Munich automotive clusters where battery enclosure specifications are tightening. For New Entrants and Emerging Players: Automated fiber placement equipment with inline inspection convergence offers a technology-first wedge into aerospace tier supplier qualification backlogs. Target India's domestic aerospace and defense supply chain localization where PLI scheme incentives are attracting prepreg investments. Pursue qualification partnerships with Spirit AeroSystems or GKN Aerospace rather than direct OEM engagement. For Investors and Strategic Acquirers: Roll-up economics work for specialized prepreg formulators because buyer consolidation among tier-one aerospace contractors is compressing supplier negotiation cycles and unbundling technical service from material supply. The 5-10 year viability window favors qualified European chemical groups with thermoplastic resin portfolios. Monitor NHTSA battery enclosure standards evolution as inflection indicator for flame-retardant thermoplastic composite demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PAN Precursor | Toray Industries' integrated operations demonstrate upstream pricing power capture across aerospace supply chains. |
| Automated Fiber Placement Capacity Expansion | Spirit AeroSystems' qualified high-rate production lines displace hand lay-up for Boeing 787 fuselage sections. |
| Thermoplastic Qualification Investment | Airbus tier suppliers in Germany specify carbon fiber-reinforced thermoplastic tapes for EASA CS-25 damage tolerance compliance. |
| Long-term Supply Agreement Restructuring | Buyer consolidation in France and Germany concentrates procurement authority with single-source program managers. |
| Joint Venture for Local Content Compliance | India's PLI scheme mandates domestic prepreg qualification investments for aerospace defense localization incentives. |
Methodological Framework
Direct dialogue with aerospace procurement directors, automotive platform engineers, carbon fiber plant managers, and resin formulation R&D heads grounded qualitative findings in operational reality. Secondary validation drew from FAA Part 25 airworthiness filings, EASA CS-25 certification databases, EU Green Deal industrial emissions benchmark documentation, and REACH chemical registration obligations. Trade data from customs authorities and SEC 10-K disclosures from publicly listed materials conglomerates provided volume and value anchors. Bottom-up segment sizing triangulated against top-down macroeconomic drivers.
Bottom-up modeling aggregated individual product category trajectories across thermoplastic, thermosetting, bio-based, and nanocomposite matrix systems. Top-down validation cross-checked against electric vehicle platform deployment schedules, commercial aircraft delivery backlogs, and defense aviation program budgets. Segmentation dimensions included matrix chemistry, end-use industry certification grade, reinforcement fiber type, and manufacturing process capital intensity. CAGRs derived from slope-intercept analysis of historical shipment data projected through forecast period endpoint assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to acrylonitrile price volatility, REACH chemical registration restriction expansions, and battery enclosure standard evolution timelines. Forecasts reflect documented assumptions regarding qualified supplier base stability and certification timeline continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Bioactive Glass Market
Advanced Materials
Boron Nitride Market
Advanced Materials
Cold Plasma Market
Advanced Materials
Global Glass Filled Nylon Market
Advanced Materials
Advanced Composite Materials Market
Advanced Materials
Long-Range Ordered Porous Carbon (LOPC) Market
Advanced Materials
Curable Materials Market
Advanced Materials
Electromagnetic Shielding Market
Advanced Materials
Nanofibrillar Cellulose Market
Advanced Materials
Carbon Prepreg Market
Advanced Materials
Inorganic Non-Metallic Materials Market
Advanced Materials
Thermal Spray Materials Market
Advanced Materials
Europe Blanket Aerogel Market
Advanced Materials
Chemistry 4.0 Market
Advanced Materials
Lithium Hydride Market
Advanced Materials
Global Electrochromic Materials Market