

Orthopedic Bone Defect Repair Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopedic Bone Defect Repair Materials Market Insights
The capital-intensity divergence between integrated multinationals and focused biomaterial specialists is unwinding competitive dynamics across the sector. Stryker leverages its captive manufacturing infrastructure to control costs across implantable mesh and putty formats. Biocomposites specializes in proprietary calcium compound formulations that anchor its position in synthetic bone substitutes. Jiangsu Yenssen Biotech competes on regional cost structures while extending distribution into Southeast Asian orthopedic clinics.
Orthopedic bone defect repair materials encompass biocompatible substances engineered to restore structural integrity and promote osteogenesis at skeletal defect sites, typically formulated from demineralized bone matrix, hydroxyapatite, tricalcium phosphate, or recombinant human bone morphogenetic proteins with porosity specifications exceeding 70% to facilitate vascular infiltration. These materials serve primarily to eliminate donor-site morbidity associated with autograft harvesting while reducing immunogenic risk relative to allograft implantation. Synthetic bone substitutes now command the fastest expansion trajectory as surgeons seek off-the-shelf alternatives with predictable resorption kinetics. Spinal fusion applications generate the deepest margin pools given procedural volume and reimbursement profiles, while injectable pastes are gaining share in minimally invasive trauma repair protocols.
The FDA's 510(k) framework and the EU Medical Device Regulation impose divergent evidentiary demands that fragment product launch sequencing across major markets. ISO 10993 biocompatibility standards and ASTM F2889 for calcium phosphate coatings further condition material selection and surface engineering investments. Stakeholders must monitor how regulatory convergence around biological safety evaluation reshapes R&D allocation between synthetic platforms and next-generation growth factor delivery systems.
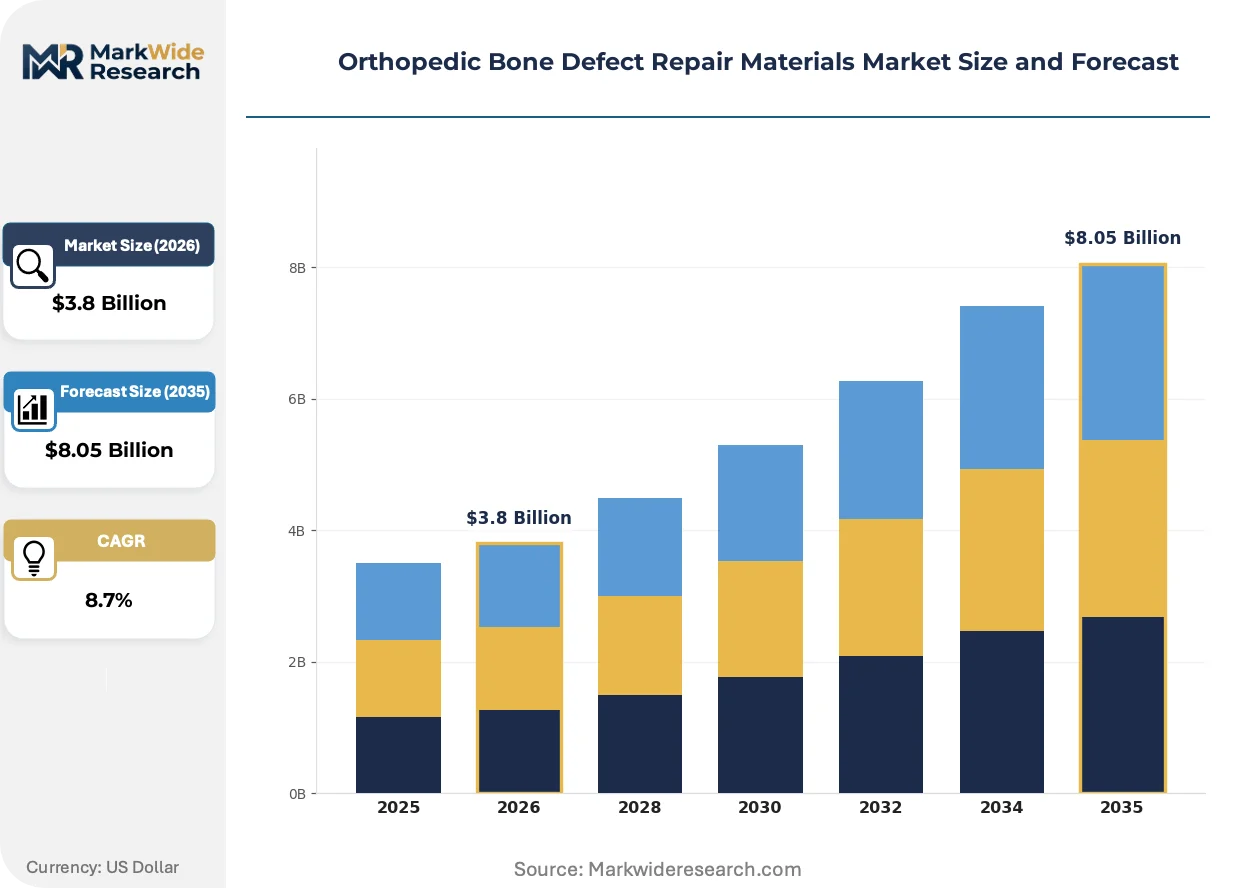
Market Dynamics
FDA's streamlined 510(k) pathways for combination products are compressing development timelines and forcing competitors to accelerate bioceramic-growth factor integration programs or cede procedural share to synthetic-first innovators.
Growth Catalysts
- Outpatient spinal migration:Ambulatory surgery centers now perform 40% of elective lumbar fusions in the United States, creating pull-through demand for pre-mixed injectable pastes with sub-20 minute preparation windows.
- Demineralized bone matrix standardization:ASTM F2889 calcium phosphate coating specifications are harmonizing quality benchmarks across hydroxyapatite suppliers, reducing batch rejection rates and accelerating OEM qualification cycles.
- Bioceramic formulation advances:Tricalcium phosphate scaffolds exceeding 80% porosity with controlled 6-18 month resorption profiles are eliminating autograft morbidity concerns in complex trauma reconstruction.
Market Restraints
- Allograft supply concentration:Tissue bank consolidation in the southeastern United States has reduced viable donor matrix sources, forcing manufacturers toward higher-cost synthetic alternatives with inferior osteoinductive properties.
- Reimbursement compression:CMS hospital outpatient prospective payment system bundles are compressing standalone bone graft add-on codes, eroding margin capture for premium putty formats.
- Growth factor safety scrutiny:FDA black-box warnings on recombinant human bone morphogenetic protein-2 in cervical spine applications have chilled surgeon adoption and extended informed consent protocols.
Strategic Opportunities
- Vietnam orthopedic expansion:Jiangsu Yenssen Biotech's distributor network in Ho Chi Minh City and Hanoi is unlocking demand for cost-optimized calcium phosphate granules in trauma centers underserved by multinational supply chains.
- EU MDR transition arbitrage:Notified body bottlenecks under the Medical Device Regulation are freezing smaller competitors' CE mark renewals, creating 18-24 month windows for pre-certified synthetic platforms to capture shelf space.
- 3D-printed patient-specific implants:Convergence of computed tomography segmentation software with selective laser sintering of β-tricalcium phosphate is enabling anatomically matched craniomaxillofacial reconstructions at tertiary academic centers.
Industry Challenges
- Bioengineer talent scarcity:Osteoimmunology and vascularized tissue integration expertise remains concentrated at Massachusetts Institute of Technology, University of Pennsylvania, and ETH Zurich pipelines, constraining R&D scaling for mid-tier biomaterial firms.
- Dual regulatory dossier complexity:Combination products requiring simultaneous FDA Center for Devices and Radiological Health and Center for Biologics Evaluation and Research reviews are extending approval timelines by 14-22 months versus pure device pathways.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedic Bone Defect Repair Materials Market Trends and Innovations
Bioresorbable synthetic matrices are displacing structural autograft dependence across trauma and spinal applications, while regulatory convergence and procurement centralization reshape how manufacturers prioritize formulation investments.
Injectable calcium phosphate cements with self-setting kinetics under 10 minutes are decomposing the traditional distinction between operating room mixing and point-of-care preparation. Orthopedic trauma teams at Level I centers are adopting these pre-loaded syringe formats for tibial plateau and calcaneal fractures. The technology is decomposing capital equipment dependencies and enabling procedure migration to outpatient settings previously reserved for hardware-only fixation.
EU Medical Device Regulation Article 117 requirements for notified body involvement in all Class III implantable reviews are fragmenting launch sequencing between European and United States markets. Manufacturers now face 12-18 month delays for bioceramic-growth factor combinations versus legacy CE self-certification pathways. Spinal fusion kits with rhBMP-2 delivery systems are most affected, with several firms prioritizing FDA 510(k) clearance ahead of MDR technical documentation submission.
Hospital value analysis committees have consolidated bone graft purchasing decisions from individual surgeons to centralized procurement functions with standardized formularies. Academic medical centers in the United States are replacing open vendor contracts with two-source agreements favoring suppliers offering volume-based rebates and consignment inventory. This concentration is most visible in the Midwest, where Catholic health system alliances now control 34% of spinal fusion case volumes and demand 90-day payment terms.
Orthopedic Bone Defect Repair Materials Market Segmentation
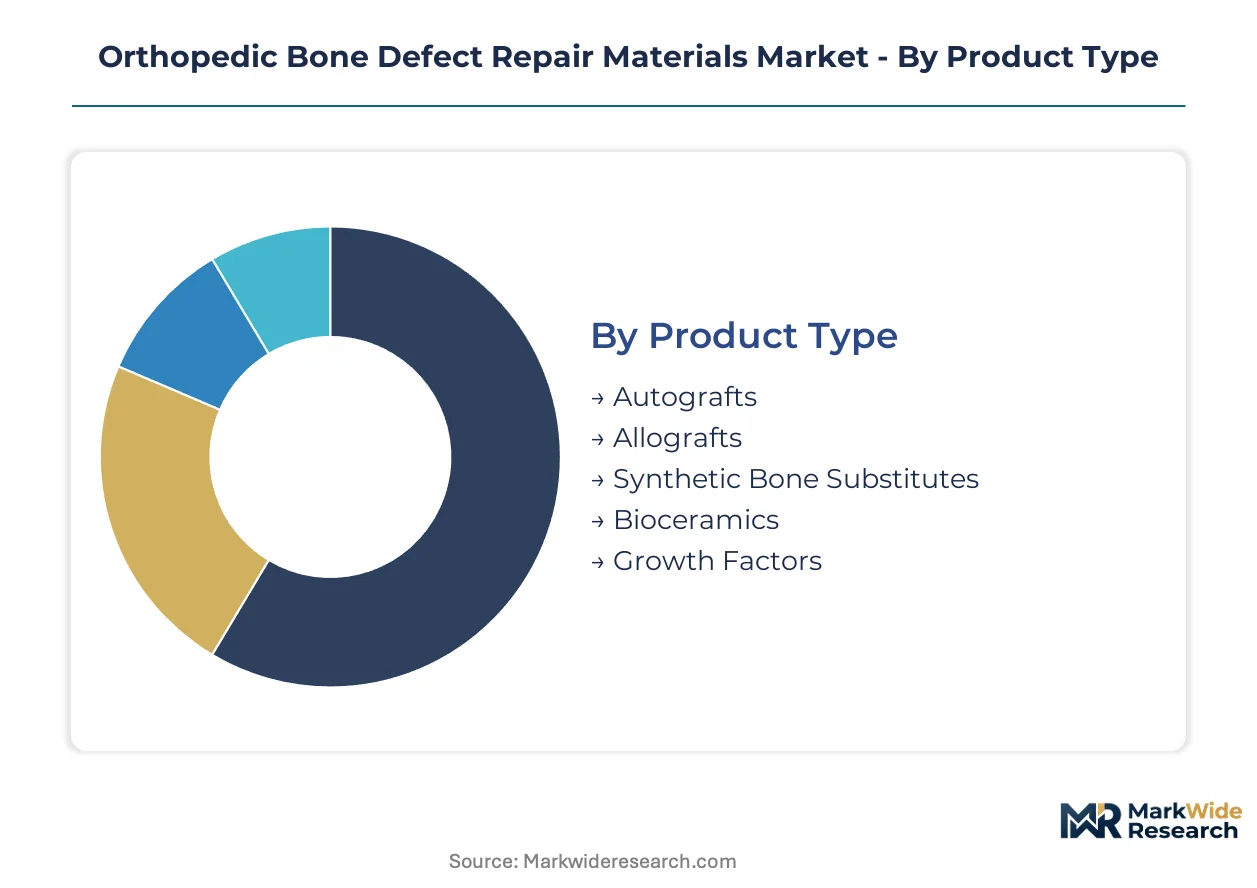
Orthopedic bone defect repair materials fragment across four critical dimensions that determine reimbursement pathways, regulatory complexity, and procurement behavior. Product type governs FDA Center jurisdiction and clinical evidence requirements, while therapy area dictates hospital purchasing power and surgeon preference profiles.
Product Type:
FDA's bifurcated review structure between CDRH and CBER creates divergent approval timelines that reshape competitive positioning across material categories.
- Synthetic Bone Substitutes:Engineered from hydroxyapatite and tricalcium phosphate with porosity exceeding 70% to enable vascular infiltration. Demand concentrates in ambulatory surgery centers across the United States where 40% of elective lumbar fusions now occur, driven by predictable resorption kinetics and elimination of donor-site morbidity.
- Growth Factors:Recombinant human bone morphogenetic protein formulations delivered via collagen sponges or ceramic carriers. Academic medical centers in Boston and Philadelphia sustain adoption despite FDA black-box warnings for cervical applications, constrained by extended informed consent protocols and reimbursement scrutiny.
- Autografts:Harvested cancellous bone from iliac crest or distal radius, retaining osteogenic, osteoinductive, and osteoconductive properties.
- Allografts:Cadaveric demineralized bone matrix processed by tissue banks, facing supply concentration risks from southeastern United States donor pool consolidation.
- Bioceramics:Calcium phosphate and bioactive glass formulations with tunable degradation rates matched to bone remodeling timelines.
Established volume favors allografts; emerging adoption favors synthetic bone substitutes.
Therapy Area:
Procedure reimbursement tiers and hardware bundling arrangements create margin dispersion across orthopedic specialties.
- Spinal Fusion:Instrumented procedures generating premium pricing pools through add-on graft codes, though CMS outpatient prospective payment system bundles are compressing standalone reimbursement. Midwest Catholic health system alliances now control 34% of United States case volumes and demand 90-day payment terms.
- Trauma Repair:Open reduction and internal fixation protocols for tibial plateau and calcaneal fractures. Level I trauma centers in Houston and Los Angeles are migrating to injectable formats with sub-20 minute preparation windows, enabling procedure shift to outpatient settings.
- Joint Reconstruction:Revision arthroplasty applications requiring structural grafts for acetabular or tibial defects.
- Craniofacial Surgery:Maxillofacial reconstructions leveraging 3D-printed patient-specific implants from CT segmentation and selective laser sintering.
- Dental Applications:Alveolar ridge preservation and sinus lift procedures with smaller volume requirements.
Revenue concentration sits with spinal fusion; steepest expansion trajectory belongs to trauma repair.
End User:
Procurement centralization and value analysis committee authority are reconfiguring vendor relationships across care settings.
- Ambulatory Surgery Centers:Outpatient facilities performing 40% of United States elective lumbar fusions, demanding pre-mixed injectable pastes and consignment inventory arrangements. Two-source agreements with volume-based rebates are replacing open vendor contracts.
- Academic Medical Centers:Tertiary institutions in Boston, Philadelphia, and Stanford driving adoption of bioceramic-growth factor combinations and 3D-printed patient-specific implants, prioritizing clinical trial access and innovation prestige over unit cost.
- Orthopedic Clinics:Private practice settings with limited capital equipment for intraoperative mixing.
- Specialized Bone Clinics:Niche facilities focused on complex reconstruction and limb salvage procedures.
Purchasing power aggregates at ambulatory surgery centers; clinical influence persists at academic medical centers.
Delivery Mode:
Preparation time and capital equipment requirements determine point-of-care feasibility across surgical workflows.
- Injectable Pastes:Self-setting calcium phosphate cements with sub-10 minute setting kinetics delivered in pre-loaded syringe formats. Orthopedic trauma teams are adopting these for minimally invasive applications, decomposing traditional distinctions between operating room mixing and point-of-care preparation.
- Implantable Meshes:Flexible sheets of demineralized bone matrix or collagen combined with ceramic granules, requiring hydration and contouring prior to placement.
- Preformed Blocks:Rigid cortical or cancellous allograft segments for structural defects.
- Moldable Putty:Demineralized bone matrix combined with carriers for hand-molding to defect geometry.
- Scaffold Matrices:Three-dimensional porous structures exceeding 80% porosity with controlled 6-18 month resorption profiles.
Operational simplicity favors injectable pastes; structural load-bearing favors preformed blocks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in orthopedic bone defect repair materials tilt toward import dependence in emerging markets and captive supply chains in established manufacturing hubs. The United States maintains a substantial trade surplus in high-value bioceramic formulations, while China and India remain net importers of precision-processed synthetic matrices despite expanding domestic production capacity.
United States
Specialized bone clinics in Boston and Philadelphia drive premium demand for growth factor formulations. FDA's streamlined 510(k) pathways for combination products compress development timelines for domestic innovators. The Midwest corridor hosts concentrated purchasing power, with Catholic health system alliances controlling substantial spinal fusion case volumes and demanding extended payment terms.
Germany
Academic medical centers in Munich and Heidelberg sustain adoption of patient-specific 3D-printed implants from CT segmentation workflows. EU Medical Device Regulation notified body bottlenecks freeze smaller competitors' CE mark renewals, creating windows for pre-certified synthetic platforms. The Baden-Württemberg cluster anchors precision bioceramic manufacturing for export across European markets.
China
Provincial trauma centers in Shanghai and Guangzhou expand utilization of cost-optimized calcium phosphate granules for complex reconstruction. NMPA regulatory harmonization with international standards accelerates qualification cycles for domestic hydroxyapatite suppliers. Yangtze River Delta manufacturing hubs scale production of porous scaffolds exceeding 80% porosity specifications.
Japan
Metropolitan Tokyo hospitals prioritize injectable paste formats with sub-10 minute setting kinetics for minimally invasive protocols. PMDA review timelines for combination products extend 14-22 months versus pure device pathways, favoring synthetic-first innovators. The Osaka-Kobe corridor concentrates orthopedic biomaterial R&D investment from integrated medical device conglomerates.
Vietnam
Trauma centers in Ho Chi Minh City and Hanoi unlock demand for cost-optimized synthetic substitutes underserved by multinational distribution. Rapid orthopedic infrastructure expansion outpaces regulatory capacity, creating informal pathways for regional suppliers. Jiangsu Yenssen Biotech's distributor network captures market share through price-competitive calcium phosphate formulations.
Orthopedic Bone Defect Repair Materials Market Competitive Landscape
Concentration sits with integrated multinationals wielding captive manufacturing infrastructure and regulatory dossier expertise. Tiered competitive structure separates premium innovators commanding academic medical center formulary placement from regional cost competitors penetrating price-sensitive trauma markets. Dominant competitive moves include backward integration into bioceramic raw material supply and strategic partnerships with 3D-printing platform developers for patient-specific implant fabrication.
Among diversified orthopedic conglomerates, Stryker, Medtronic, and Johnson & Johnson exemplify the integrated multinational archetype with end-to-end control across implantable mesh and putty formats. Biocomposites and NovaBone Products occupy specialist positions anchored in proprietary calcium compound formulations. Jiangsu Yenssen Biotech represents the regional cost-optimized tier, leveraging Southeast Asian distribution networks to serve underserved trauma centers.
| Leading Market Players |
|---|
| Stryker |
| Medtronic |
| Johnson & Johnson |
| Zimmer Biomet |
| Globus Medical |
| Biocomposites |
| NovaBone Products |
| Olympus Terumo Biomaterials Corp |
| Jiangsu Yenssen Biotech |
| Others |
Pricing and Supply Chain Analysis
Ninety-day payment terms demanded by Catholic health system alliances in the Midwest compress working capital cycles and force suppliers to price for liquidity risk rather than pure product value. This inventory financing burden interacts with raw material concentration in hydroxyapatite precursors to create tiered margin structures where captive manufacturers extract premiums while contract-dependent specialists absorb cost volatility.
Pricing Analysis
The customization-premium spread between patient-specific 3D-printed implants and standard putty formats exceeds three-to-one at academic medical centers in Boston and Philadelphia. Contract-based long-term offtake agreements dominate procurement, with volume scale and FDA 510(k) clearance tier as primary price differentiation drivers. Pricing pressure stems from CMS outpatient prospective payment system bundling that erodes standalone graft add-on codes. Ambulatory surgery centers exhibit highest price sensitivity, while tertiary academic centers prioritize clinical trial access over unit cost.
Supply Chain Analysis
China and Germany anchor hydroxyapatite precursor production, with the Yangtze River Delta scaling porous scaffold manufacturing and Baden-Württemberg concentrating precision bioceramic fabrication for European export. Supply chains draw from phosphate rock deposits, synthetic calcium compound refiners, and collagen sponge processors. Single-source vulnerability concentrates in southeastern United States tissue banks where donor pool consolidation has reduced viable allograft matrix sources. Distribution runs through hospital value analysis committees that have consolidated purchasing from individual surgeons to centralized procurement functions with standardized formularies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution threat from synthetic bone substitutes displacing structural autograft dependence across trauma and spinal applications, requiring active portfolio repositioning.
For Market Incumbents: Consolidate backward integration into bioceramic raw material supply to offset phosphate precursor cost volatility and defend margin position against Jiangsu Yenssen Biotech's regional cost structures. Lock hospital system partnerships through consignment inventory arrangements before EU MDR notified body bottlenecks freeze smaller competitors' CE mark renewals and create shelf space windows.
For New Entrants and Emerging Players: Lead with cost-optimized calcium phosphate granules targeting trauma centers in Ho Chi Minh City and Hanoi where multinational distribution remains underserved. Exploit the 18-24 month regulatory arbitrage window created by MDR technical documentation delays to establish synthetic-first platforms before growth factor combinations clear dual FDA CDRH-CBER review pathways.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because hospital procurement centralization and Catholic health system alliance purchasing power will compress vendor counts to two-source agreements favoring integrated multinationals with captive manufacturing. Target acquisition archetypes include mid-tier biomaterial specialists with proprietary calcium compound formulations and established OEM qualification cycles. Watch FDA 510(k) clearance velocity for combination products as inflection signal for bioceramic-growth factor integration program viability.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Streamlined review for combination products compresses development timelines against CBER dual-track alternatives. |
| Hospital System Partnership | Consignment inventory arrangements with Midwest Catholic health alliances secure 34% spinal fusion case volume access. |
| CE Marking Pathway | Pre-certified synthetic platforms capture shelf space during MDR notified body bottlenecks freezing competitor renewals. |
| Backward Integration | Captive hydroxyapatite precursor production insulates margin from phosphate rock cost volatility and supply concentration. |
| Software Companion Development | CT segmentation workflows for 3D-printed patient-specific implants differentiate premium tier at academic medical centers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, CMS Medicare reimbursement databases, and EU MDR notified body registration records. Orthopedic surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided qualitative input across Boston, Philadelphia, and Midwest corridor institutions. Bottom-up demand modeling from procedure volume data triangulates against top-down market sizing from manufacturer revenue disclosures and trade flow analysis.
Segmentation dimensions modeled include product type jurisdiction split, therapy area reimbursement tier, end-user procurement centralization level, and delivery mode preparation complexity. CAGRs derive from regression analysis of historical adoption curves and elasticity estimates across the projection horizon. Industry-specific forecast inputs incorporate ASTM F2889 coating specification harmonization effects and ambulatory surgery center spinal fusion migration rates.
The analysis sits within stated boundaries; outcomes outside FDA regulatory pathway stability or tissue bank donor pool availability would require recalibration. Forecasts reflect assumptions about surgeon preference evolution and reimbursement bundling persistence. Recalibration cycles align with material shifts in EU MDR implementation velocity and CMS outpatient prospective payment system update schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.