
 Global Bioactive Materials Market | 2026-2036
Global Bioactive Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bioactive Materials Market Intelligence
Asset-light contract manufacturing and royalty-based licensing is reshaping how mid-sized firms enter bioactive materials production without owning cleanroom infrastructure. Johnson & Johnson (DePuy Synthes) leverages its orthopedic implant installed base to pull through proprietary bioceramic formulations. Zimmer Biomet Holdings anchors its competitive position through captive supply agreements with specialized bioactive glass foundries. Evonik Industries differentiates via polymer-based resorbable scaffolds that integrate with its existing pharmaceutical excipient distribution network.
Bioactive materials comprise synthetic or naturally derived substances—primarily bioactive glasses, calcium phosphates, and surface-reactive ceramics—that elicit specific biological responses at the material-tissue interface, typically forming hydroxyapatite layers within hours of implantation. These materials serve to bond with living tissue, stimulate cellular differentiation, or modulate drug release kinetics in implantable and injectable formats. Bioceramics and bioactive glass dominate current revenue owing to decades of clinical validation in spinal fusion and dental grafting, while composite materials represent the fastest-expanding margin pool as manufacturers blend osteoconductive minerals with resorbable polymers to tune degradation rates. Tissue engineering applications attract disproportionate R&D investment relative to current sales, reflecting venture capital interest in organoid scaffolds and regenerative platforms.
FDA 510(k) and PMA pathways govern U.S. market access for implantable bioactives, while the EU MDR and CE marking requirements impose strengthened clinical evidence standards for long-term implantable devices. Japan's PMDA maintains distinct biocompatibility testing protocols that create incremental compliance costs for foreign entrants. ISO 10993 standards for biological evaluation of medical devices provide the harmonized baseline that most manufacturers target across jurisdictions. Stakeholders must monitor how evolving regenerative medicine frameworks in the United States, Europe, and Japan redefine the evidentiary threshold for novel bioactive formulations.
Market Dynamics
EU MDR's strengthened clinical evidence requirements for long-term implantables are compressing development timelines and forcing manufacturers to front-load biocompatibility testing budgets before commercialization.
Growth Catalysts
- Japan's aging surgical population:Hospital procurement of spinal fusion and dental graft materials accelerates as PMDA reimbursement pathways clarify for regenerative implants.
- ISO 10993 harmonization:Streamlined biological evaluation standards reduce redundant testing costs for manufacturers targeting multiple jurisdictions simultaneously.
- Resorbable polymer integration:Composite scaffolds blending osteoconductive minerals with degradable polymers enable tunable degradation rates for personalized tissue engineering.
Market Restraints
- High-purity precursor scarcity:Medical-grade calcium phosphate and bioactive glass precursors concentrate among specialty chemical suppliers in Germany and Japan, creating input cost volatility.
- EU MDR transition friction:Legacy devices face recertification bottlenecks as notified body capacity constraints extend approval timelines for bioceramic implant modifications.
- Metal implant substitution:Titanium and cobalt-chrome alloys retain cost advantages in load-bearing orthopedic applications, limiting bioactive penetration in joint replacement.
Strategic Opportunities
- India's underserved trauma segment:CDSCO's streamlined medical device rules and expanding private hospital networks create entry points for bioactive bone void fillers.
- 3D bioprinting convergence:Integration of bioactive ink formulations with extrusion-based and light-based additive manufacturing enables patient-specific scaffold geometries.
- Japan's regenerative medicine framework:Conditional approval pathways for tissue-engineered products accelerate commercialization timelines for organoid scaffold developers.
Industry Challenges
- Cleanroom manufacturing scale-up:ISO 14644-compliant production facilities for bioactive glasses require capital-intensive ion exchange and controlled atmosphere processing equipment.
- Cross-jurisdiction dossier divergence:FDA 510(k) substantial equivalence standards and PMDA biocompatibility protocols demand parallel but non-identical clinical data packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bioactive Materials Market |
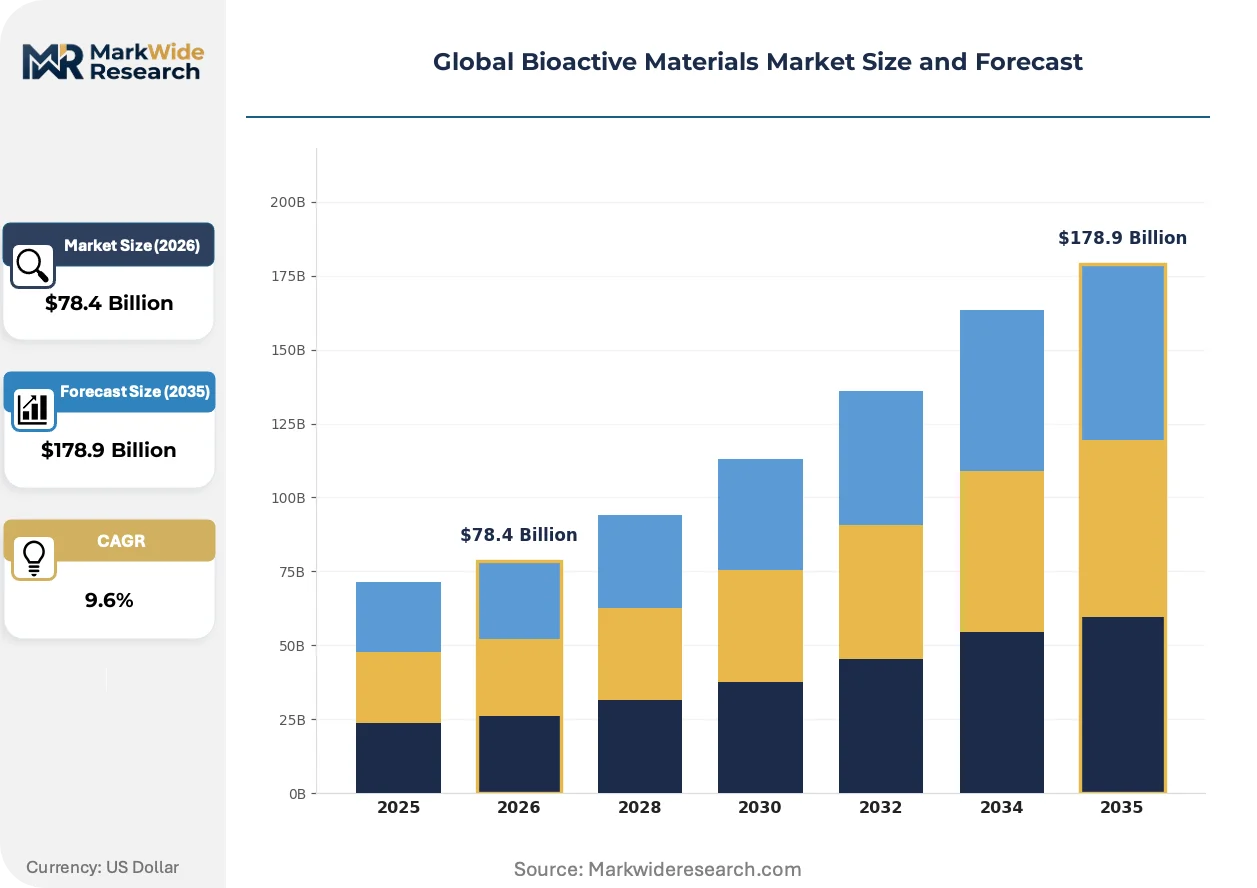
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $178.9 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioactive Glass, Bioceramics, Polymer-based, Composite Materials, Biomineral Coatings Application: Tissue Engineering, Drug Delivery, Orthopedic Devices, Dental Restoration, Wound Care End User: Research Institutes, Medical Device Manufacturers, Pharmaceutical Companies, Biotechnology Firms, Academic Laboratories Packaging Type: Bulk Containers, Vacuum Packaging, Sterile Packs, Blister Packs, Custom Kits |
| Companies Covered | Arthrex Inc., Boston Scientific, Johnson & Johnson (DePuy Synthes), DSM Firmenich, Berkeley Advanced Biomaterials, Zimmer Biomet Holdings, Evonik Industries, BASF SE, Straumann Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bioactive Materials Market Strategic Shifts & Innovations
Computational materials design and digital manufacturing workflows are compressing development cycles for patient-matched implant surfaces while regulatory frameworks race to accommodate novel bioactive formulations.
Digital twin platforms for bioactive material degradation modeling are virtualizing preclinical validation workflows. Orthopedic device manufacturers deploy these simulations to predict hydroxyapatite formation kinetics and mechanical property evolution before physical prototyping. The technology compresses iterative design cycles from months to weeks.
REACH authorization requirements for novel silicate-based bioactive glasses are tightening substance safety documentation obligations. Manufacturers must generate extended one-generation reproductive toxicity data for compositions exceeding 1 ton annual production. Specialty glass foundries in Germany and France face disproportionate compliance cost burdens relative to Asian competitors.
Hospital procurement committees increasingly mandate ISO 13485 certification as a threshold qualification for bioactive material suppliers. Distributors serving United States and German acute care networks report certification-driven vendor consolidation. Smaller bioceramic producers without dedicated quality management infrastructure lose shelf access.
Global Bioactive Materials Market Segmentation
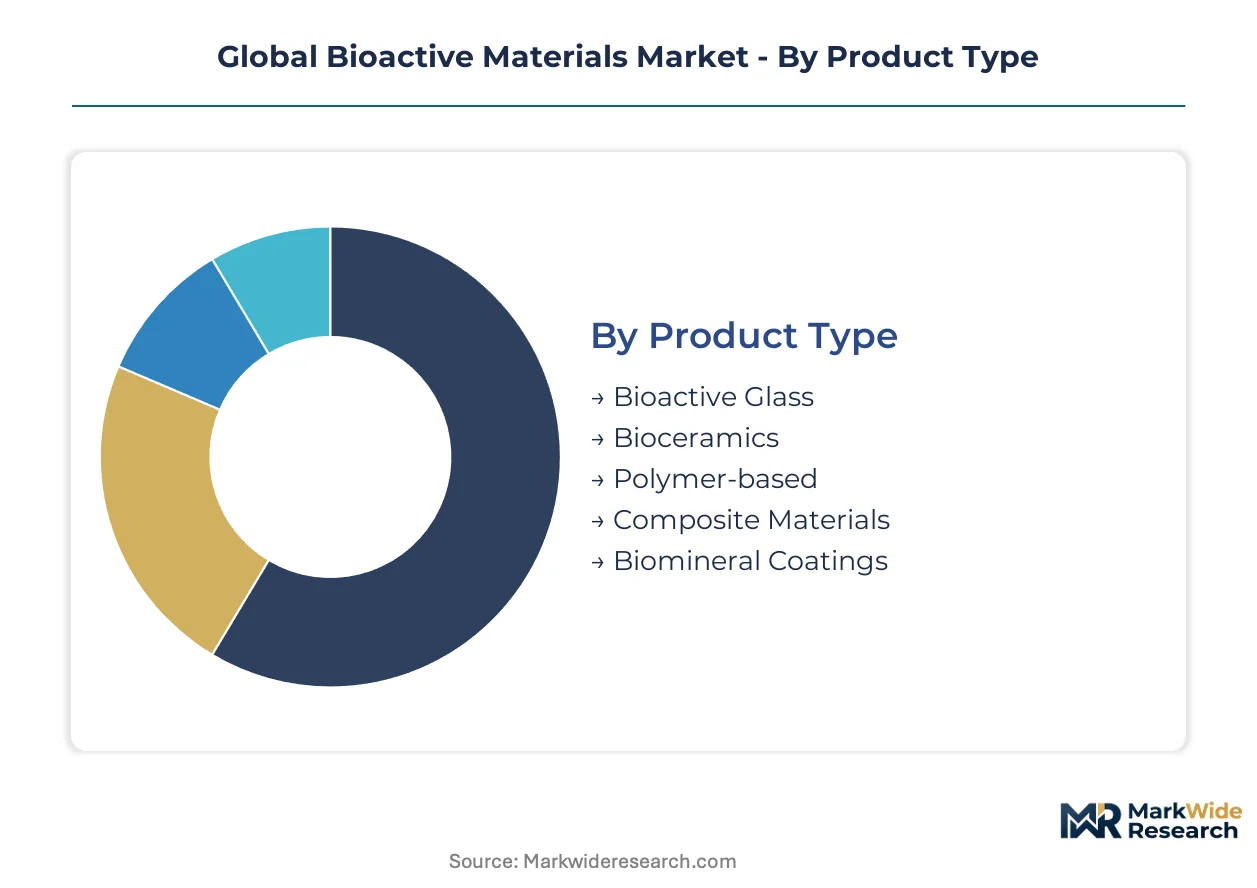
Segmentation reveals how bioactive materials traverse distinct technical specifications, clinical environments, and supply chain configurations. Product chemistry determines regulatory pathway complexity, while end-user sophistication shapes packaging and service requirements.
Product Type:
Clinical use-cases span from permanent osseointegration to fully resorbable tissue scaffolding, with each chemistry demanding specialized manufacturing infrastructure and biocompatibility validation protocols.
- Bioceramics:Hydroxyapatite and tricalcium phosphate formulations dominate spinal fusion and dental grafting applications across United States and German hospital procurement networks. Manufacturers face ISO 10993-5 cytotoxicity testing requirements for every batch release.
- Bioactive Glass:Silicate-based compositions elicit rapid hydroxyapatite formation at tissue interfaces, commanding premium positioning in craniofacial reconstruction. REACH authorization obligations in Europe constrain production scale for compositions exceeding volume thresholds.
- Composite Materials:Mineral-polymer blends enable tunable degradation kinetics for personalized tissue engineering scaffolds. Japan's PMDA conditional approval pathways accelerate commercialization timelines for these hybrid formulations.
- Polymer-based:Resorbable scaffolds integrate with pharmaceutical excipient distribution networks for controlled drug release applications.
- Biomineral Coatings:Surface-functionalized layers enhance osseointegration on titanium implant substrates.
Established volume favors bioceramics; emerging adoption favors composite materials.
Application:
Revenue concentration tracks surgical procedure volumes and reimbursement clarity, with orthopedic and dental applications anchoring near-term procurement while tissue engineering attracts disproportionate R&D investment.
- Orthopedic Devices:Spinal fusion cages and bone void fillers represent the largest procurement category by value, with United States hospital systems driving specification standardization. FDA 510(k) substantial equivalence pathways dominate regulatory access for these permanent implants.
- Tissue Engineering:Organoid scaffolds and regenerative platforms command development-stage investment multiples far exceeding current sales, reflecting venture capital interest in Japan's conditional approval framework and 3D bioprinting convergence.
- Dental Restoration:Ridge augmentation and periodontal grafting applications concentrate demand in German and Japanese private practice networks.
- Drug Delivery:Bioactive carriers modulate release kinetics for localized therapeutic administration.
- Wound Care:Bioactive dressings accelerate healing in chronic ulcer management.
Procurement scale concentrates in orthopedic devices; innovation investment concentrates in tissue engineering.
End User:
Customer sophistication determines service intensity, with medical device manufacturers demanding captive supply agreements while research institutes prioritize batch flexibility and technical documentation.
- Medical Device Manufacturers:Johnson & Johnson and Zimmer Biomet anchor demand through proprietary formulation partnerships and ISO 13485-mandated supplier qualification. These customers require dedicated quality management infrastructure and audit transparency.
- Research Institutes:Academic and government laboratories drive early-stage material validation, with procurement concentrated in United States National Institutes of Health funding corridors and German Max Planck Institute networks. Batch customization and publication-grade characterization data command premium pricing.
- Pharmaceutical Companies:Excipient integration and drug-biomaterial compatibility testing shape purchasing criteria.
- Biotechnology Firms:Cell therapy developers seek scaffold materials with defined porosity and degradation profiles.
- Academic Laboratories:Smaller-volume procurement with emphasis on material reproducibility and protocol publication support.
Contract value concentrates with medical device manufacturers; specification diversity concentrates with research institutes.
Packaging Type:
Sterility assurance level and handling protocols vary dramatically between bulk industrial supply and point-of-care implantable formats.
- Sterile Packs:Terminal sterilization with gamma irradiation or ethylene oxide dominates implantable bioactive glass and bioceramic distribution to United States and German acute care networks. ISO 11607 compliance for sterile barrier systems is non-negotiable for shelf access.
- Vacuum Packaging:Moisture-sensitive resorbable polymers require controlled atmosphere sealing with oxygen and humidity indicators. Japan's humidity-sensitive logistics infrastructure shapes regional packaging specifications.
- Bulk Containers:Industrial-scale bioceramic precursor supply to manufacturing customers.
- Blister Packs:Unit-dose formats for dental grafting and wound care applications.
- Custom Kits:Procedure-specific configurations combining multiple bioactive components.
Regulatory compliance cost concentrates in sterile packs; supply chain flexibility concentrates in vacuum packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's conditional approval pathways for regenerative medicine products are accelerating commercialization timelines for tissue-engineered scaffolds. Germany's REACH authorization requirements for novel silicate-based bioactive glasses impose substance safety documentation obligations that constrain production scale. Hospital procurement committees in the United States increasingly mandate ISO 13485 certification as a threshold qualification for suppliers.
United States
FDA 510(k) substantial equivalence pathways govern market access for implantable bioactives in spinal fusion and dental grafting. Hospital systems in the Northeast and California corridors drive specification standardization for bioceramic bone void fillers. The National Institutes of Health funding concentration in Maryland and Massachusetts sustains early-stage material validation by academic laboratories.
Germany
Specialty glass foundries in Bavaria and Baden-Württemberg face disproportionate REACH compliance cost burdens for compositions exceeding annual production thresholds. EU MDR strengthened clinical evidence requirements compress development timelines for long-term implantables. The Max Planck Institute network concentrates research procurement in Munich and Stuttgart metropolitan clusters.
Japan
PMDA reimbursement pathway clarification accelerates hospital procurement of spinal fusion materials for the aging surgical population. METI's regenerative medicine framework enables conditional approval for tissue-engineered products. The Kanto region surrounding Tokyo anchors demand from private practice networks and acute care systems.
India
CDSCO's streamlined medical device rules create entry points for bioactive bone void fillers in the underserved trauma segment. Expanding private hospital networks in Maharashtra and Karnataka drive procurement growth. Mumbai and Bangalore metropolitan areas concentrate distributor infrastructure for medical device supply chains.
Switzerland
Swissmedic maintains distinct biocompatibility testing protocols that create incremental compliance costs for foreign entrants. The Basel pharmaceutical cluster drives demand for polymer-based resorbable scaffolds integrated with excipient distribution networks. Zurich and Geneva research institutes prioritize batch customization and publication-grade characterization data.
Global Bioactive Materials Market Key Industry Players
On the supply side, the industry is consolidating around three strategic tiers: diversified healthcare conglomerates with captive orthopedic implant bases, specialized chemical producers leveraging pharmaceutical distribution networks, and emerging biomaterial foundries focused on custom scaffold geometries. Dominant competitive moves include strategic partnerships between device manufacturers and bioactive glass foundries, plus portfolio diversification into composite mineral-polymer formulations.
Within the diversified healthcare tier, Johnson & Johnson and Zimmer Biomet occupy positions that exemplify supply chain control through proprietary formulation partnerships. Evonik Industries represents the specialized chemical producer archetype, anchoring competitive positioning through integration with existing pharmaceutical excipient networks. These three entities collectively illustrate how market access depends on either implant installed base leverage or distribution infrastructure ownership rather than standalone material science capabilities.
| Leading Market Players |
|---|
| Arthrex Inc. |
| Boston Scientific |
| Johnson & Johnson (DePuy Synthes) |
| DSM Firmenich |
| Berkeley Advanced Biomaterials |
| Zimmer Biomet Holdings |
| Evonik Industries |
| BASF SE |
| Straumann Group |
| Others |
Cost & Logistics Intelligence
Single-source dependency on German and Japanese specialty glass foundries for medical-grade bioactive glass precursors compresses pricing power for mid-tier manufacturers while forcing supply chain consolidation around vertically integrated incumbents. This chokepoint widens spreads between ISO 13485-certified premium tiers and uncertified commodity supply.
Pricing Analysis
Certification level (ISO 13485/FDA-grade/CE-marked) creates the primary spread between premium and standard tiers, with sterile-packaged implantable formats commanding substantial premiums over bulk industrial supply. Pricing stratifies across premium certified, standard compliant, and economy unvalidated tiers based on batch-release documentation depth. Cost compression in mid-tier bioceramics is intensifying because REACH authorization obligations for novel silicate compositions front-load compliance spending. Hospital procurement committees demonstrate lowest price sensitivity, while research institutes exhibit highest elasticity to certification-driven premiums.
Supply Chain Analysis
Tariff exposure between Germany and Switzerland dominates supply chain risk planning for European orthopedic device manufacturers sourcing specialty bioactive glasses. Production gravity centers on Germany, Japan, and the United States, with medical-grade calcium phosphate and silicate precursors drawing from concentrated specialty chemical suppliers. Single-source vulnerability persists for ion-exchange processed bioactive glass formulations. Distribution runs through medical device manufacturer captive supply agreements and pharmaceutical excipient networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bioactive materials market rewards service-attach strategies, with sterilization validation and batch-customization services expanding faster than raw material supply. Recurring revenue from technical documentation and regulatory dossier support outpaces hardware margins.
For Market Incumbents: Build regulatory dossier libraries as the primary moat against emerging biomaterial foundries. Consolidate backward integration into high-purity precursor supply through captive agreements with German and Japanese specialty chemical suppliers. Deepen ISO 13485 audit transparency to defend hospital procurement committee shelf access against uncertified competitors. For New Entrants and Emerging Players: India's underserved trauma segment offers the most penetrable entry point, with CDSCO's streamlined device rules reducing regulatory friction for bone void filler introductions. Target Maharashtra and Karnataka private hospital networks through distributor partnerships offering sterile-packaged formats with localized technical support. Lead with cost-competitive bioceramic precursors before advancing to composite scaffold development. For Investors and Strategic Acquirers: EU MDR recertification bottlenecks reshape the acquisition landscape toward targets with notified body relationships and legacy device transition experience. Five-to-ten year viability favors specialized biomaterial foundries with 3D bioprinting ink capabilities over commodity bioceramic producers. Monitor PMDA conditional approval pathway utilization rates as the signal for regenerative medicine platform readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Partnership | EU MDR recertification capacity constraints make notified body relationships the scarce resource for legacy device transitions. |
| 3D Bioprinting Ink Development | Patient-specific scaffold geometries command premium positioning in craniofacial reconstruction applications. |
| Captive Precursor Supply Agreement | German and Japanese specialty chemical suppliers concentrate high-purity input access among vertically integrated incumbents. |
| ISO 13485 Certification Investment | Hospital procurement committees mandate certification as threshold qualification, driving vendor consolidation. |
| Regenerative Medicine Framework Alignment | Japan's PMDA conditional approval pathways accelerate commercialization timelines for tissue-engineered products. |
Research Approach
Desk research of FDA 510(k) filings, EU MDR technical documentation databases, and ISO 10993 biocompatibility standards preceded structured interviews with orthopedic device procurement managers, biomedical engineers at German Max Planck Institutes, and regulatory affairs leads at notified bodies. Primary fieldwork with hospital purchasing committees and GPO contracts managers combined with secondary validation from customs trade data and pharmaceutical excipient distribution records. Bottom-up volume modeling and top-down value triangulation converged on segment-level estimates.
Assumptions held surgical procedure volume growth, reimbursement pathway clarity, and regulatory framework stability fixed across the projection horizon, while varying raw material input cost trajectories and competitive entry intensity. Segmentation dimensions modeled include product chemistry tier, application clinical environment, end-user sophistication level, and regional regulatory cluster. CAGRs derived from procedure volume elasticity to demographic aging and hospital capital expenditure cycles, with bioactive glass formulation adoption curves and composite scaffold penetration rates as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese specialty chemical producers or sudden REACH authorization requirement relaxations would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Global Hydroxyapatite Market
Biomaterials
Hemostatic Gels Market
Biomaterials
Orthopedic Bone Defect Repair Materials Market
Biomaterials
Hydrogel Face Mask Market
Biomaterials
Calcium Phosphate Market
Biomaterials
Brazil Bone Graft and Substitutes Market
Biomaterials
Biomaterial Wound Dressing Market
Biomaterials
Chitosan Oligosaccharides and Glucosamine Market
Biomaterials
Chitosan Supplements Market
Biomaterials
Bone Distractors Market
Biomaterials
Biomimetic Peptides Market
Biomaterials
US Heparin Market
Biomaterials
Hydrogel Market
Biomaterials
Global Extracellular Matrix Patches Market
Biomaterials
Mushroom Materials Market
Biomaterials
Global Collagen Meniscus Implants Market