
 Bone Distractors Market | 2026-2036
Bone Distractors Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Distractors Market Analysis
The EU Medical Device Regulation is expanding pre-market clinical evidence requirements for implantable orthopedic devices, raising capital barriers for new entrants. Stryker Corporation leverages its vertically integrated manufacturing network to sustain cost advantages across mechanical and electrical distraction platforms. Zimmer Biomet anchors its position through deep specialization in limb lengthening systems. Johnson & Johnson competes via its broad hospital channel control and surgeon training infrastructure.
Bone distractors are implantable or external mechanical devices engineered to apply controlled tensile force across osteotomized bone segments, typically achieving distraction rates of 0.5 to 1.0 millimeters per day to stimulate regenerate formation in the widening gap. Their primary purpose is to enable limb lengthening, correct congenital deformities, and reconstruct bone defects through the biological process of distraction osteogenesis. Mechanical distraction devices occupy the largest installed base due to decades of clinical validation and lower per-procedure cost, while smart systems incorporating real-time force sensing represent the fastest-growing technology category as hospitals pursue outcome-based reimbursement models. Pins and plate systems concentrate margin pools in trauma surgery applications where acute fracture management demands immediate mechanical stability.
The FDA governs bone distractors as Class II or Class III medical devices requiring 510(k) clearance or PMA approval, with post-market surveillance expanding under the FDA Sentinel Initiative. The EU MDR and ISO 13485 quality management standards shape design documentation, clinical evaluation, and notified body conformity assessment pathways for market access. Stakeholders must monitor evolving FDA guidance on patient-specific instrumentation and the EU's impending EUDAMED database requirements for traceability.
Market Dynamics
The EU Medical Device Regulation is compressing market entry timelines for implantable orthopedic devices, forcing manufacturers to restructure clinical evidence generation and notified body engagement strategies.
Growth Catalysts
- Trauma surgery procedural expansion:Hospital orthopedic departments are scaling limb reconstruction programs to address congenital deformity correction and post-traumatic bone defect management.
- ISO 13485 quality system harmonization:Standardized design documentation and risk management frameworks are reducing regulatory friction for multi-market device submissions.
- Smart sensing technology maturation:Real-time force monitoring systems are enabling precise distraction rate control and reducing regenerate formation complications.
Market Restraints
- Titanium alloy input volatility:Raw material cost fluctuations for implant-grade metals compress margin stability for mechanical distraction device producers.
- EU MDR clinical evidence requirements:Expanded pre-market study mandates for Class III implantables extend capital lock-up periods before commercialization.
- External fixation substitution:Ring fixator systems retain cost advantages in emerging markets, limiting electrical distractor penetration.
Strategic Opportunities
- Pediatric orthopedic specialization:Dedicated children's hospitals in Germany and France are establishing limb lengthening centers of excellence.
- Patient-specific instrumentation convergence:3D-printed surgical guides combined with pre-operative planning software are reducing operative time and pin tract complications.
- Outpatient surgical facility expansion:Ambulatory surgery centers in the United States are adding orthopedic trauma capabilities to capture shifting reimbursement flows.
Industry Challenges
- Distraction osteogenesis surgical training:The specialized skill set for precise osteotomy execution and post-operative monitoring creates bottlenecks in program expansion.
- 510(k) to PMA pathway navigation:FDA device classification ambiguity for smart distractor systems generates regulatory strategy uncertainty and timeline risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Distractors Market |
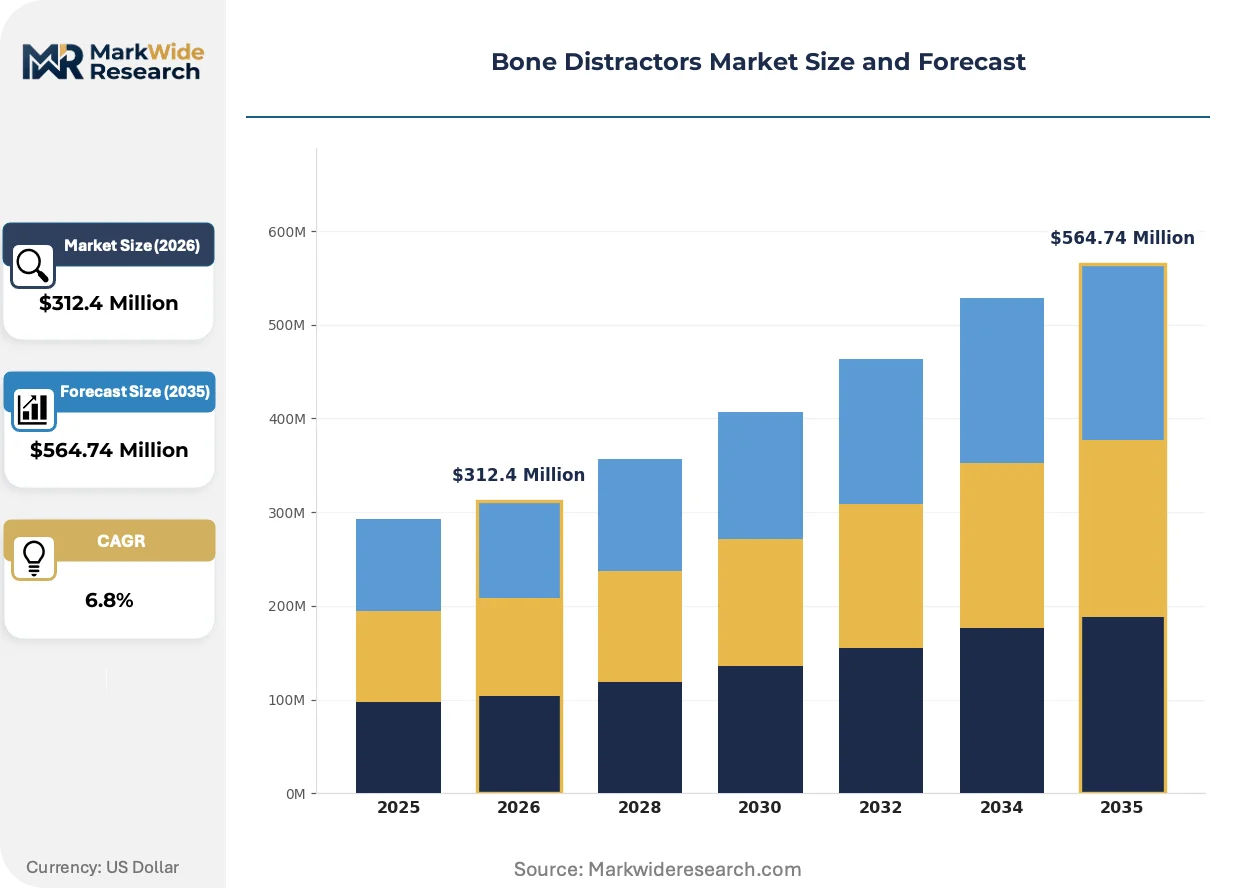
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Distraction Devices, Orthopedic Screws, Pins, Plate Systems End User: Hospitals, Clinics, Rehabilitation Centers, Specialized Ortho Facilities Application: Trauma Surgery, Limb Lengthening, Bone Reconstruction, Maxillofacial Surgery Technology: Mechanical Distraction, Electrical Distraction, Bioactive Materials, Smart Systems |
| Companies Covered | Stryker Corporation, Johnson & Johnson, Zimmer Biomet, Acumed, KLS Martin Group, Arthrex, Innomed, OsteoMed, Ningbo Cibei Medical Treatment Appliance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Distractors Market Emerging Trajectories
Electromechanical integration is transforming bone distraction from mechanical craftsmanship into data-driven therapy, with sensor networks and predictive algorithms compressing complication rates and enabling remote patient management.
Smart distractor systems incorporating strain gauges and wireless telemetry are unifying intraoperative precision with post-discharge monitoring. Academic medical centers in the United States and university hospitals in Switzerland are piloting these platforms for complex limb reconstruction cases. The technology is unifying surgical planning, real-time adjustment, and long-term outcome tracking into continuous care protocols that reduce revision surgery incidence.
MDR Article 10 clinical evaluation requirements are mandating systematic post-market clinical follow-up for implantable orthopedic devices. Manufacturers must now maintain active surveillance registries and periodic safety update reports across all EU member states. High-risk mechanical distractors and novel electrical systems face the steepest compliance burden, with notified body capacity constraints extending certification timelines.
Hospital procurement committees are consolidating orthopedic implant vendor lists to reduce supply chain complexity and standardize surgeon training pathways. Large integrated delivery networks in the United States are replacing fragmented supplier relationships with single-source contracts spanning trauma, spine, and limb reconstruction portfolios. This concentration is most visible in metropolitan hospital systems where orthopedic service line directors negotiate enterprise-wide pricing agreements.
Bone Distractors Market Segmentation
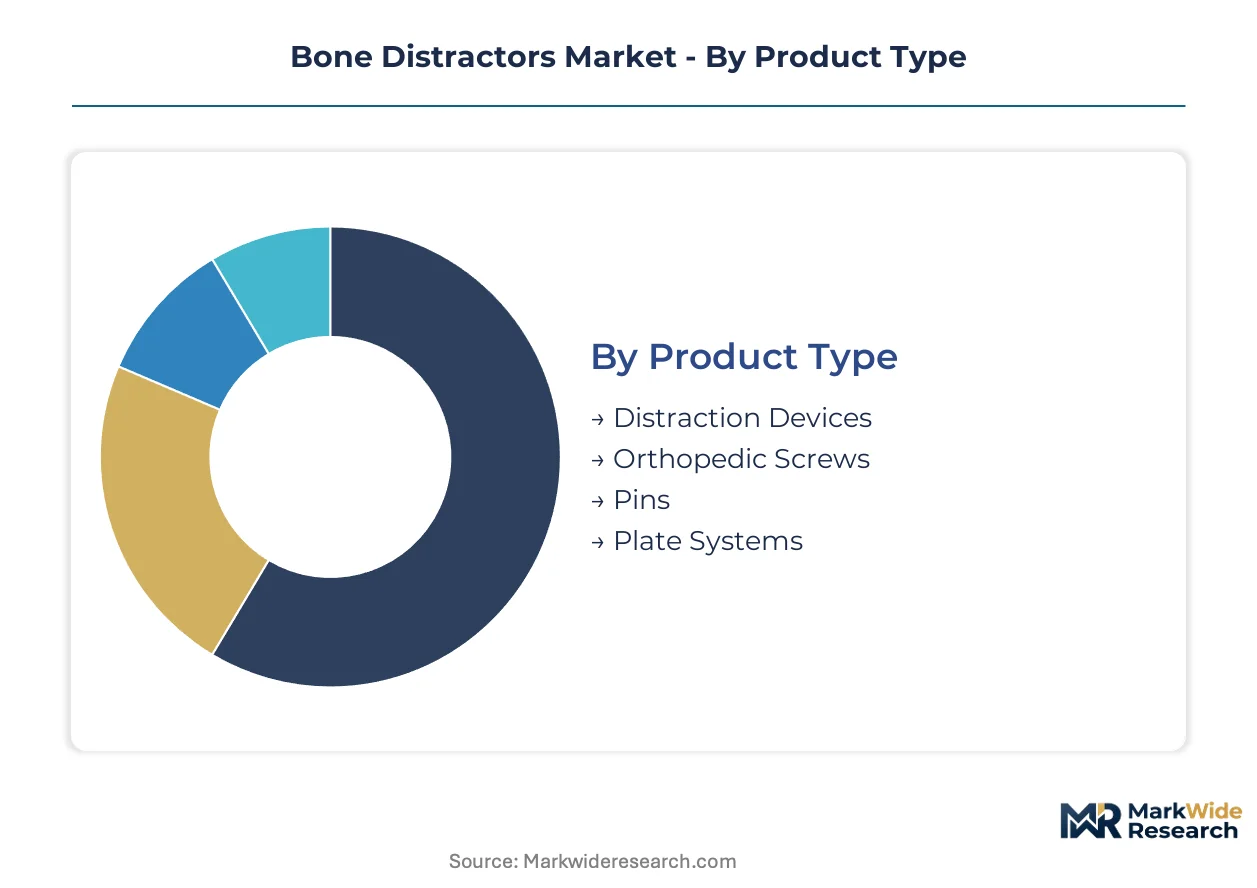
Segmentation in bone distractors reveals how supply chain specialization, regulatory pathways, and clinical training infrastructure fragment commercial opportunity across distinct product architectures and care delivery settings.
Product Type:
Supply concentration in mechanical platforms dominates manufacturing capacity, with titanium alloy forging networks and CNC machining clusters shaping regional production economics.
- Distraction Devices:External and internal mechanical assemblies generate tensile force through threaded rods or telescoping mechanisms. Hospital orthopedic departments in the United States concentrate demand for these systems as limb lengthening programs expand procedural volumes.
- Orthopedic Screws:Cortical and cancellous bone screws anchor external fixators and internal distraction plates. German trauma centers drive specification requirements for self-tapping and locking screw variants in complex fracture management.
- Pins:Smooth and threaded transfixion pins penetrate bone segments to transfer distraction loads through soft tissue.
- Plate Systems:Reconstruction plates and specialized distraction plates provide rigid fixation across osteotomy sites.
Distraction devices absorb the bulk of installed capacity; smart-enabled distraction platforms are expanding most quickly.
End User:
Procurement authority concentrates in integrated delivery networks, with purchasing committees consolidating vendor relationships across trauma and reconstructive service lines.
- Hospitals:Academic medical centers and community hospital systems perform the majority of complex limb reconstruction procedures. The FDA's 510(k) and PMA pathways shape device selection criteria in these settings, with surgeon preference cards driving standardization.
- Specialized Ortho Facilities:Dedicated limb lengthening centers and orthopedic institutes concentrate surgical expertise and post-operative monitoring capabilities. Swiss university hospitals and French pediatric orthopedic centers are establishing referral networks for complex deformity correction.
- Clinics:Outpatient settings handle post-distractor removal follow-up and minor adjustment procedures.
- Rehabilitation Centers:Physical therapy facilities manage regenerate maturation protocols and functional recovery programs.
Hospitals command the dominant share of capital equipment procurement; specialized ortho facilities are gaining share fastest as centers of excellence consolidate complex cases.
Application:
Reimbursement coding differentiation between trauma and elective reconstruction creates distinct margin profiles across clinical indications.
- Trauma Surgery:Acute fracture management and post-traumatic bone defect reconstruction demand immediate mechanical stabilization. United States Level I trauma centers drive volume for external fixation systems in polytrauma cases.
- Limb Lengthening:Elective and congenital limb length discrepancy correction requires precise distraction rate control. German and Austrian pediatric orthopedic centers specialize in these procedures, with the EU MDR's clinical evidence requirements shaping device selection.
- Bone Reconstruction:Segmental bone defect management and non-union treatment apply distraction osteogenesis principles to salvage scenarios.
- Maxillofacial Surgery:Craniofacial distraction addresses mandibular hypoplasia and midface deficiencies through specialized small-scale devices.
Trauma surgery absorbs the bulk of installed capacity; limb lengthening is expanding most quickly as specialized programs proliferate.
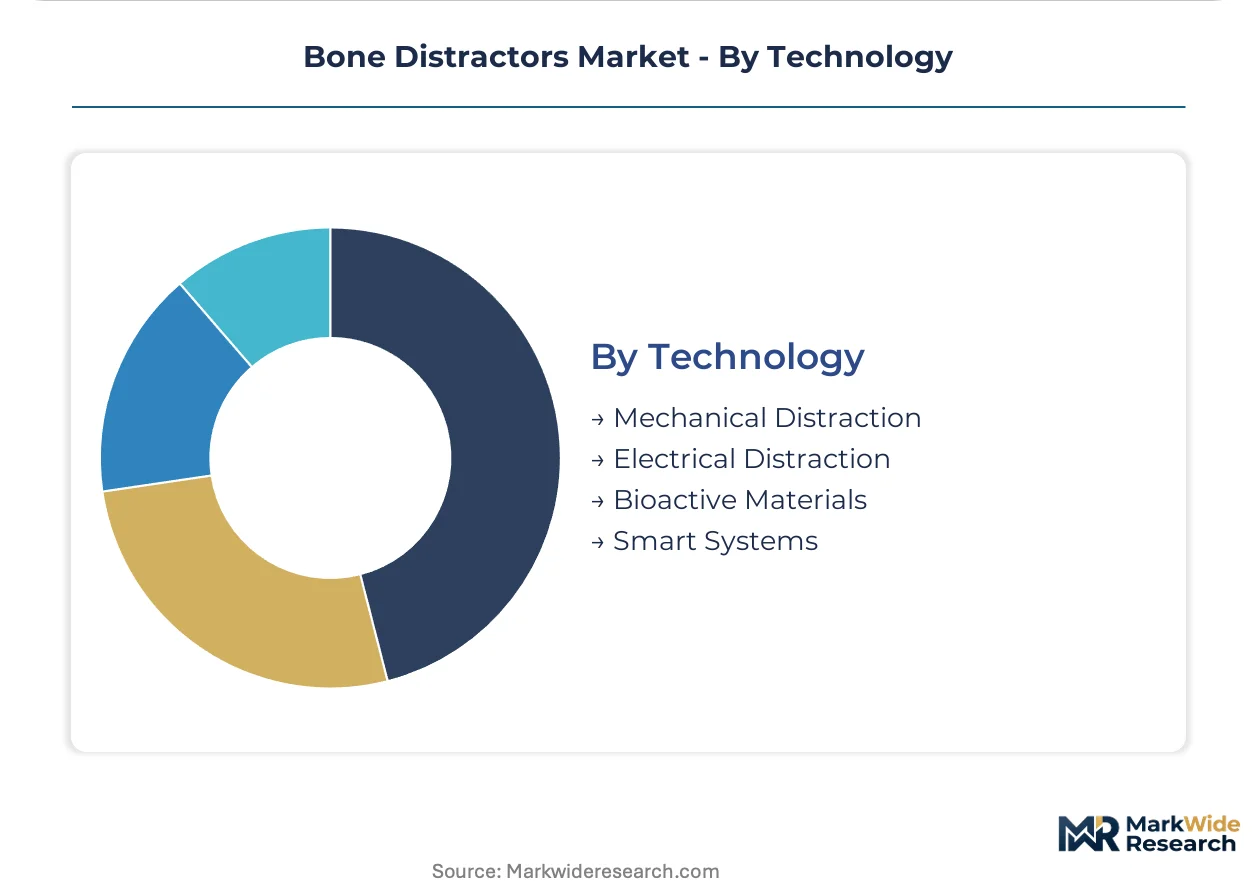
Technology:
Cost tier stratification separates validated mechanical platforms from emerging sensor-integrated systems, with reimbursement parity lagging technology advancement.
- Mechanical Distraction:Hand-operated and motorized mechanical systems achieve controlled separation through calibrated screw advancement. These platforms retain cost advantages in emerging markets where ring fixator substitution limits electrical system penetration.
- Smart Systems:Wireless telemetry and strain gauge networks enable real-time force monitoring and automated rate adjustment. Academic medical centers in Switzerland and the United States pilot these platforms for remote patient management and complication reduction.
- Electrical Distraction:Motorized internal and external devices reduce manual adjustment burden and improve patient compliance.
- Bioactive Materials:Surface-modified implants and bioresorbable components aim to accelerate osseointegration and regenerate formation.
Mechanical distraction retains the dominant installed base; smart systems are climbing the fastest as outcome-based reimbursement models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized orthopedic economic zones in Bavaria and the Research Triangle Park corridor concentrate bone distractor development, attracting venture funding for limb reconstruction technology.
United States
Level I trauma centers in Baltimore and Houston drive external fixation volumes for polytrauma management. The FDA's 510(k) pathway shapes device selection criteria across hospital systems. Academic medical centers in Boston and Philadelphia pilot smart distraction systems for remote patient monitoring.
Germany
Pediatric orthopedic centers in Munich and Hamburg specialize in congenital limb lengthening procedures. The EU MDR's Article 10 clinical evaluation requirements extend certification timelines for implantable devices. The Baden-Württemberg medical technology cluster hosts precision machining networks for titanium alloy components.
Switzerland
University hospitals in Zurich and Geneva establish referral networks for complex deformity correction. Swissmedic maintains stringent conformity assessment pathways for Class III implantables. The Basel pharmaceutical corridor extends into orthopedic device manufacturing through materials science partnerships.
France
ANSM oversight governs post-market surveillance for high-risk mechanical distractors. Pediatric orthopedic centers of excellence in Paris and Lyon consolidate complex limb reconstruction cases. The Île-de-France region concentrates surgeon training infrastructure for distraction osteogenesis protocols.
China
NMPA regulatory harmonization accelerates domestic device approvals for trauma surgery applications. Manufacturing clusters in Jiangsu and Zhejiang provinces scale CNC machining capacity for pin and plate systems. Shanghai teaching hospitals expand limb lengthening programs for congenital deformity correction.
Bone Distractors Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across mechanical and electrical distraction platforms. The vendor base stratifies into three tiers: multinational orthopedic conglomerates with hospital channel control, mid-cap device specialists with regional manufacturing depth, and emerging players with cost-positioned mechanical systems. Dominant competitive moves include backward integration into titanium alloy forging networks and strategic partnerships with academic medical centers for clinical evidence generation.
Among diversified orthopedic conglomerates, Stryker Corporation and Johnson & Johnson exemplify scale-driven archetypes with broad hospital procurement relationships. Zimmer Biomet occupies a position within the specialized limb reconstruction tier. These three entities represent the premium-tier competitive vector where surgeon training infrastructure and regulatory compliance capabilities determine market access.
| Leading Market Players |
|---|
| Stryker Corporation |
| Johnson & Johnson |
| Zimmer Biomet |
| Acumed |
| KLS Martin Group |
| Arthrex |
| Innomed |
| OsteoMed |
| Ningbo Cibei Medical Treatment Appliance |
| Others |
Supply Flow & Price Mechanics
Titanium alloy spot indices and implant-grade metal benchmarks cascade through bone distractor supply chains into three-tier pricing structures across premium, standard, and economy levels. Manufacturers in Germany and the United States absorb commodity volatility differentially, with vertically integrated forging networks buffering margin compression while spot-dependent assemblers pass through cost fluctuations.
Pricing Analysis
Lead-time premiums command pricing separation between spot inventory and engineered-to-order configurations across mechanical and electrical distraction platforms. Pricing stratifies across premium, standard, and economy tiers according to FDA PMA versus 510(k) certification status and volume commitment scale. Pricing pressure stems from EU MDR clinical evidence requirements extending capital lock-up periods before commercialization. Academic medical centers in Switzerland exhibit lowest price sensitivity due to outcome-based procurement mandates, while community hospital systems in the United States face acute budget constraints.
Supply Chain Analysis
Precision machining workforce availability in Baden-Württemberg, Jiangsu province, and the Research Triangle Park corridor anchors titanium component fabrication capacity for distraction devices. Supply chains draw from implant-grade titanium alloy forging networks, CNC machining clusters, and sterilization packaging operations. Single-source vulnerability concentrates in European notified body capacity for EU MDR conformity assessments. Distribution runs through integrated delivery network procurement committees consolidating vendor relationships across trauma and reconstructive service lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bone distractor market functions as a vertical-integration race where captive control over titanium alloy forging networks separates margin-defensible incumbents from assembly-dependent challengers.
For Market Incumbents: Hedge titanium input exposure through long-term offtake agreements with German and Chinese alloy producers. Fortify regulatory compliance infrastructure against EU MDR Article 10 clinical evaluation extensions that threaten competitor timelines. Deepen surgeon training partnerships with academic medical centers to lock in preference card standardization before smart distraction platforms mature.
For New Entrants and Emerging Players: Launch via direct-to-specialist-ortho-facility distribution bypassing consolidated hospital procurement committees. Target pediatric limb lengthening centers in France and Germany where procedure volume expansion outpaces incumbent service coverage. Emphasize cost-positioned mechanical systems with rapid CE marking pathways to exploit MDR transition bottlenecks affecting premium-tier competitors.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap device specialists with dormant FDA 510(k) portfolios and underutilized precision machining capacity in Bavaria or Switzerland. Five-to-ten year viability hinges on smart distraction technology maturation and reimbursement parity achievement. Monitor EU notified body capacity expansion as the decisive inflection signal for MDR compliance timeline normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Engagement | Early notified body selection compresses certification timelines for Class III implantables facing Article 10 requirements. |
| Smart Distraction Platform Development | Wireless telemetry integration enables remote patient monitoring pilot programs at Swiss university hospitals. |
| Surgeon Training Infrastructure Investment | Dedicated distraction osteogenesis certification programs lock in preference card standardization across hospital systems. |
| Titanium Alloy Backward Integration | Captive forging capacity insulates margin stability against implant-grade metal spot price volatility. |
| Pediatric Orthopedic Center Partnerships | Referral network consolidation in Germany and France captures congenital limb lengthening procedure expansion. |
Methodological Framework
Independent corroboration across orthopedic device regulatory filings, hospital procurement databases, and titanium alloy trade flow records underwrites the qualitative findings. Primary interviews with distraction osteogenesis surgeons, biomedical engineers, GPO contracts managers, and notified body auditors combined with secondary validation from FDA 510(k) and PMA databases, EU MDR Article 10 clinical evaluation summaries, and ISO 13485 certification registries. Bottom-up procedure volume estimates and top-down manufacturer capacity assessments triangulate market sizing.
Rate-of-change decomposition across mechanical distraction, electrical systems, and smart-enabled platforms structures the analytical framework over the projection horizon. Segmentation dimensions include product architecture, end-user procurement authority, clinical application, and technology sophistication tier. CAGRs derive from procedure volume trajectories, reimbursement code valuation trends, and capital equipment replacement cycles. Forecast inputs incorporate EU MDR implementation pace and smart distraction pilot program expansion at academic medical centers.
EU notified body capacity constraints, titanium alloy price volatility, and distraction osteogenesis surgical training bottlenecks are the dominant revision risks. Forecasts reflect documented assumptions regarding regulatory timeline normalization and reimbursement parity for sensor-integrated systems. Material deviation in MDR implementation pace or smart technology clinical evidence generation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Scaffold Materials Market
Biomaterials
Biodegradable Bone Graft Polymers Market
Biomaterials
Bone Substitutes Market
Biomaterials
Polysaccharide Hemostatic System Market
Biomaterials
Spine Surgery Gels Market
Biomaterials
Biomimetic Peptides Market
Biomaterials
Global Collagen Meniscus Implants Market
Biomaterials
Chitosan Market
Biomaterials
Mushroom Materials Market
Biomaterials
Self-Healing Hydrogels Market
Biomaterials
Chitosan Oligosaccharides and Glucosamine Market
Biomaterials
Hydrogel Face Mask Market
Biomaterials
Global Biocompatible Materials Market
Biomaterials
Biomaterial in Surgical Mesh Market
Biomaterials
Self-Healing Materials Market
Biomaterials
Global Absorbable Tissue Spacer Market