
 Nerve Repair Biomaterials Market | 2026-2036
Nerve Repair Biomaterials Market Size, Share, and Industry Trends Forecast 2026-2036
Nerve Repair Biomaterials Market Analysis
Bioresorbable polymer synthesis is rewriting the manufacturing economics of nerve repair scaffolds, shifting production from passive collagen extrusion toward programmable degradation kinetics. Axogen Inc. leverages allograft tissue processing to sustain dominance in off-the-shelf nerve graft supply. Integra LifeSciences anchors its position through porcine-derived matrix specialization across trauma and reconstructive applications. Medtronic Plc competes by extending neurostimulation hardware into adjacent biomaterial delivery systems.
Nerve repair biomaterials comprise implantable scaffolds, conduits, wraps, and grafts engineered from natural or synthetic polymers to bridge neural gaps and guide axonal regeneration across lesion sites. Collagen conduits typically present pore sizes of 20-100 micrometers and degrade within 12-24 months to match Schwann cell infiltration timelines. Nerve conduits command the largest revenue pool due to reproducible manufacturing and broad surgical applicability, while nerve grafts capture premium pricing in complex multi-gap reconstructions. Silk and polycaprolactone segments are gaining fastest as material scientists demonstrate superior tensile strength and tunable resorption profiles in preclinical models.
FDA 510(k) and PMA pathways govern U.S. market entry, with the agency scrutinizing long-term biocompatibility data for resorbable synthetics. EMA MDR requirements and REACH chemical safety standards shape European product development timelines and material selection. Japan's PMDA enforces stringent QMS inspections for imported nerve repair devices, creating compliance barriers for Western suppliers. Stakeholders must monitor evolving biodegradability testing protocols across FDA, EMA, and PMDA jurisdictions to anticipate reformulation costs and registration delays.
Market Dynamics
Bioresorbable polymer synthesis is collapsing manufacturing timelines for nerve repair scaffolds, compressing production cycles from collagen extrusion toward programmable degradation kinetics that match Schwann cell infiltration windows.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated U.S. market entry pathways compress regulatory review periods for novel biomaterial platforms, pulling synthetic grafts into hospital procurement pipelines faster than standard PMA tracks.
- Rising Peripheral Nerve Repair Volumes:Trauma centers and reconstructive surgical units in tertiary neurosurgical centers are expanding nerve conduit utilization as microsurgical techniques standardize across teaching hospitals.
- EU MDR Accelerated Pathways:Streamlined conformity assessment procedures for regenerative medicine devices enable earlier European commercialization for collagen-based and synthetic hybrid scaffolds.
Market Restraints
- Porcine-Derived Input Volatility:Supply concentration in porcine tissue sourcing exposes manufacturers to zoonotic disease screening protocols and agricultural commodity price swings that destabilize allograft processing economics.
- Japan PMDA QMS Inspection Barriers:Stringent quality management system audits for imported nerve repair devices create compliance friction and registration delays for Western suppliers targeting Japanese tertiary centers.
- Long-Term Biocompatibility Data Requirements:FDA scrutiny of resorbable synthetic degradation byproducts demands extended preclinical timelines that strain R&D budgets for polycaprolactone and silk-based platforms.
Strategic Opportunities
- Silk-Polycaprolactone Hybrid Convergence:Material science advances combining silk fibroin tensile strength with tunable PCL resorption kinetics open premium positioning in complex multi-gap reconstructions previously served by autografts.
- Underpenetrated German Outpatient Surgical Centers:Ambulatory nerve repair procedures in specialized German clinics remain underserved by current distribution models focused on inpatient tertiary centers.
- Outcome-Based Reimbursement Pilots:Emerging U.S. bundled payment models for peripheral nerve reconstruction create procurement incentives for biomaterials with demonstrated axonal regeneration metrics.
Industry Challenges
- Schwann Cell Biology Talent Scarcity:Shortage of specialists bridging polymer chemistry and peripheral nerve regeneration biology constrains product development teams and slows iterative scaffold optimization cycles.
- REACH Chemical Safety Reformulation Costs:Evolving ECHA biodegradability testing protocols for synthetic polymers force unplanned material substitutions and dossier resubmissions mid-development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nerve Repair Biomaterials Market |
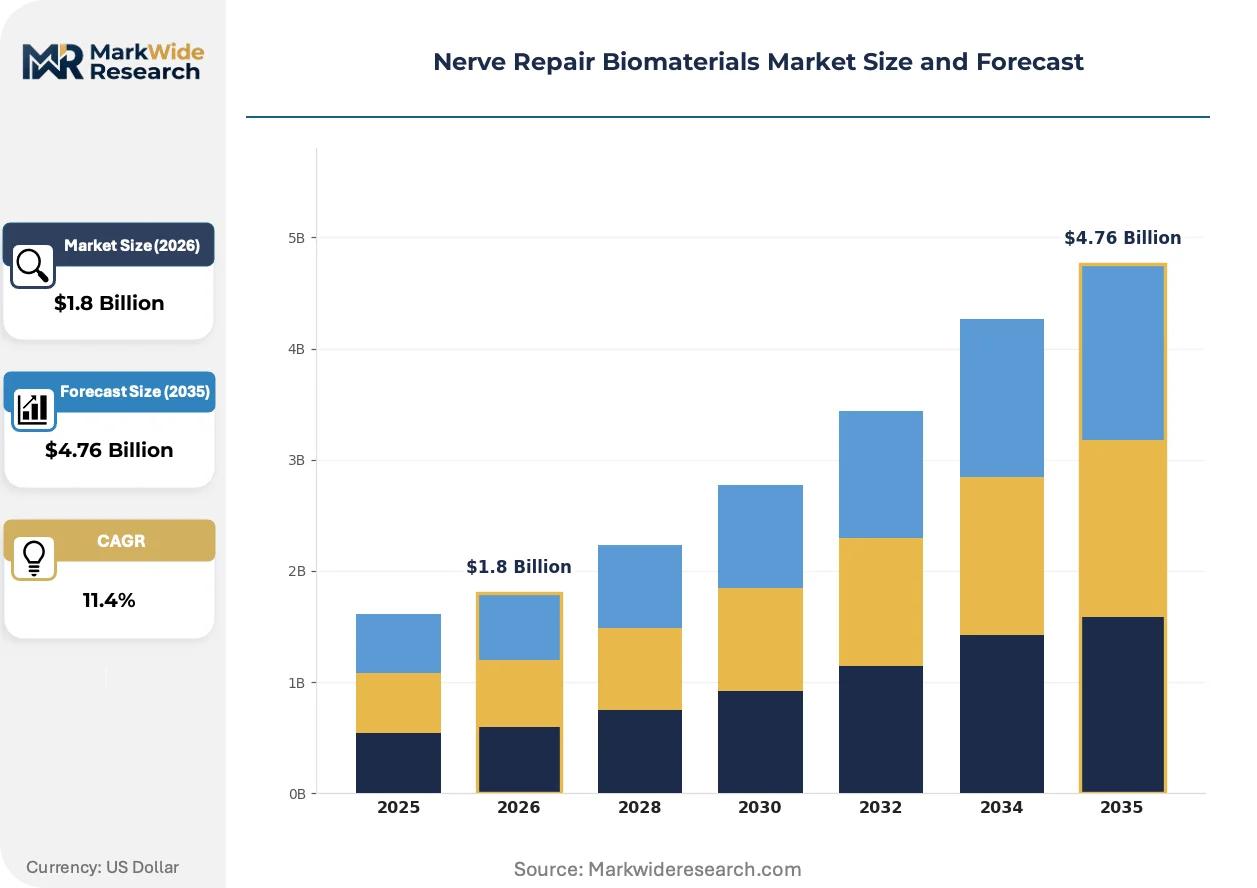
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nerve Conduits, Nerve Grafts, Neurostimulation Devices, Nerve Repair Patch Material: Silk, Collagen, Polycaprolactone, Gelatin Application: Neurological Disorders, Injury Repair, Peripheral Nerve Repair, Spinal Cord Injury End User: Hospitals, Clinics, Research Centers, Rehabilitation Facilities |
| Companies Covered | Abbott Laboratories, Smith & Nephew Plc, Axogen Inc., B. Braun SE, Polyganics B.V., Integra LifeSciences, Boston Scientific Corporation, Orthocell Ltd., Medtronic Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nerve Repair Biomaterials Market Emerging Trajectories
Programmable degradation kinetics in synthetic scaffolds is collapsing the historical trade-off between mechanical support duration and immune response minimization, enabling next-generation conduits that synchronize structural integrity loss with functional nerve recovery milestones.
Electrospun nanofiber architectures are collapsing the performance gap between synthetic conduits and autologous grafts by mimicking native extracellular matrix topography at sub-micron scales. Academic medical centers in the United States and Germany are piloting these platforms in brachial plexus reconstructions where off-the-shelf alternatives previously failed. The technology is compressing time-to-functional-recovery endpoints that determine hospital reimbursement and surgical referral patterns.
EMA MDR requirements for biological safety evaluation are tightening material traceability standards across European supply chains. Manufacturers must now document polymer monomer provenance and cross-linking agent residuals with batch-level specificity previously reserved for pharmaceutical active ingredients. Synthetic scaffold developers with captive polymer synthesis capabilities are responding faster than competitors dependent on merchant resin suppliers.
Hospital procurement committees are consolidating vendor relationships around suppliers offering bundled nerve repair portfolios spanning conduits, wraps, and adjunctive fixation devices. This consolidation is displacing single-product vendors in United States group purchasing organization negotiations and favoring integrated platform providers. German university hospitals are pioneering multi-year framework agreements that lock in biomaterial supply alongside surgical training commitments.
Nerve Repair Biomaterials Market Segmentation
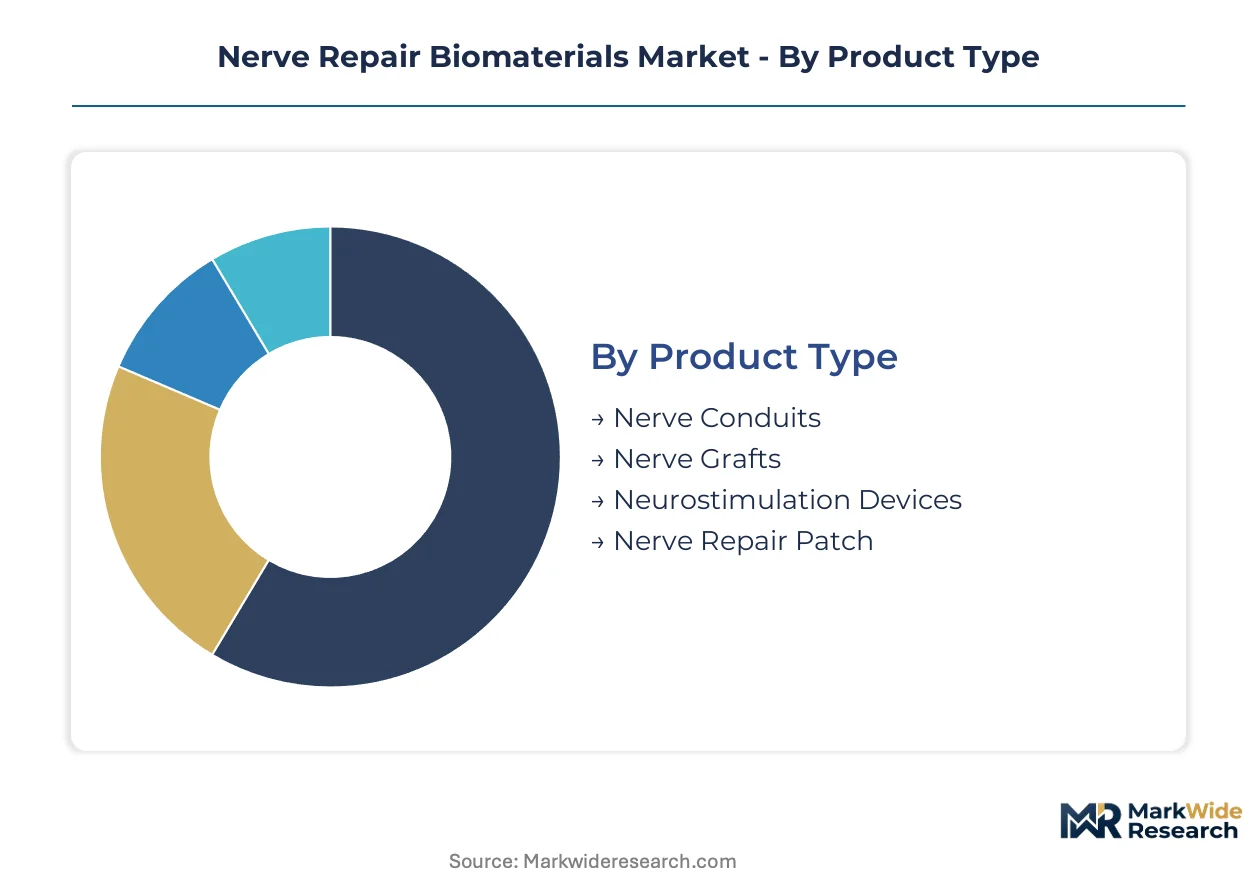
Nerve repair biomaterials segment across four critical dimensions that shape procurement workflows and R&D prioritization. Product type determines reimbursement coding and surgical workflow integration. Material selection governs regulatory pathway complexity and manufacturing economics. Application and end-user splits reveal where clinical evidence requirements concentrate versus where volume scales fastest.
Product Type:
Cycle times vary dramatically: conduits turn inventory fastest due to standardized sizing and broad surgical applicability, while neurostimulation devices face extended validation timelines for electrical safety and biocompatibility.
- Nerve Conduits:Tubular scaffolds engineered from collagen or synthetic polymers with pore architectures of 20-100 micrometers. Demand concentrates in United States trauma centers where microsurgical technique standardization drives reproducible utilization patterns and group purchasing organization consolidation.
- Nerve Grafts:Processed allograft or xenograft tissue segments bridging multi-gap lesions exceeding 30 millimeters. German and Japanese tertiary neurosurgical centers anchor adoption for complex brachial plexus reconstructions where autograft harvest morbidity is unacceptable.
- Neurostimulation Devices:Implantable electrical systems delivering targeted impulses to accelerate axonal regeneration.
- Nerve Repair Patch:Flat matrix constructs for wrapping injured nerve segments without circumferential conduit enclosure.
Nerve conduits dominate installed base across hospital procurement pipelines. Nerve grafts are where expansion concentrates as allograft processing capabilities mature.
Material:
Cost tiers stratify sharply: collagen commands premium pricing for established clinical track records, while silk and polycaprolactone occupy emerging technology positioning with unproven long-term reimbursement.
- Silk:Silk fibroin matrices offering superior tensile strength and programmable degradation through beta-sheet crystallinity modulation. United States academic medical centers pilot electrospun silk architectures in preclinical models targeting Schwann cell alignment optimization.
- Polycaprolactone:Aliphatic polyester with tunable resorption timelines from 24-36 months matching extended nerve regeneration windows. German manufacturers leverage captive polymer synthesis to accelerate EMA MDR compliance and batch-level traceability documentation.
- Collagen:Porcine- or bovine-derived extracellular matrix with established FDA 510(k) predicates and broad surgeon familiarity.
- Gelatin:Denatured collagen variant offering lower immunogenicity profile and simplified cross-linking chemistry for research-scale production.
Collagen dominates installed base through decades of clinical validation and reimbursement precedent. Silk and polycaprolactone are where expansion concentrates as material scientists demonstrate superior mechanical-degradation trade-offs.
Application:
Volume scales fastest in trauma applications where surgical decision windows compress product selection to off-the-shelf availability, while spinal cord injury applications face extended preclinical timelines and regulatory uncertainty.
- Peripheral Nerve Repair:Digital nerve, median nerve, and sciatic nerve reconstructions following traumatic laceration or compression injury. United States hand surgery centers and German outpatient microsurgical clinics drive utilization scaling as ambulatory procedure volumes expand.
- Injury Repair:Acute traumatic nerve disruptions requiring immediate surgical intervention with standardized conduit or graft deployment protocols.
- Neurological Disorders:Entrapment neuropathies including carpal tunnel and cubital tunnel syndrome where biomaterial adjuncts supplement decompression.
- Spinal Cord Injury:Catastrophic central nervous system trauma where biomaterial scaffolds bridge lesion cavities and modulate inflammatory microenvironments.
Peripheral nerve repair dominates installed base through reproducible surgical workflows and established reimbursement. Injury repair is where expansion concentrates as trauma center networks standardize microsurgical response protocols.
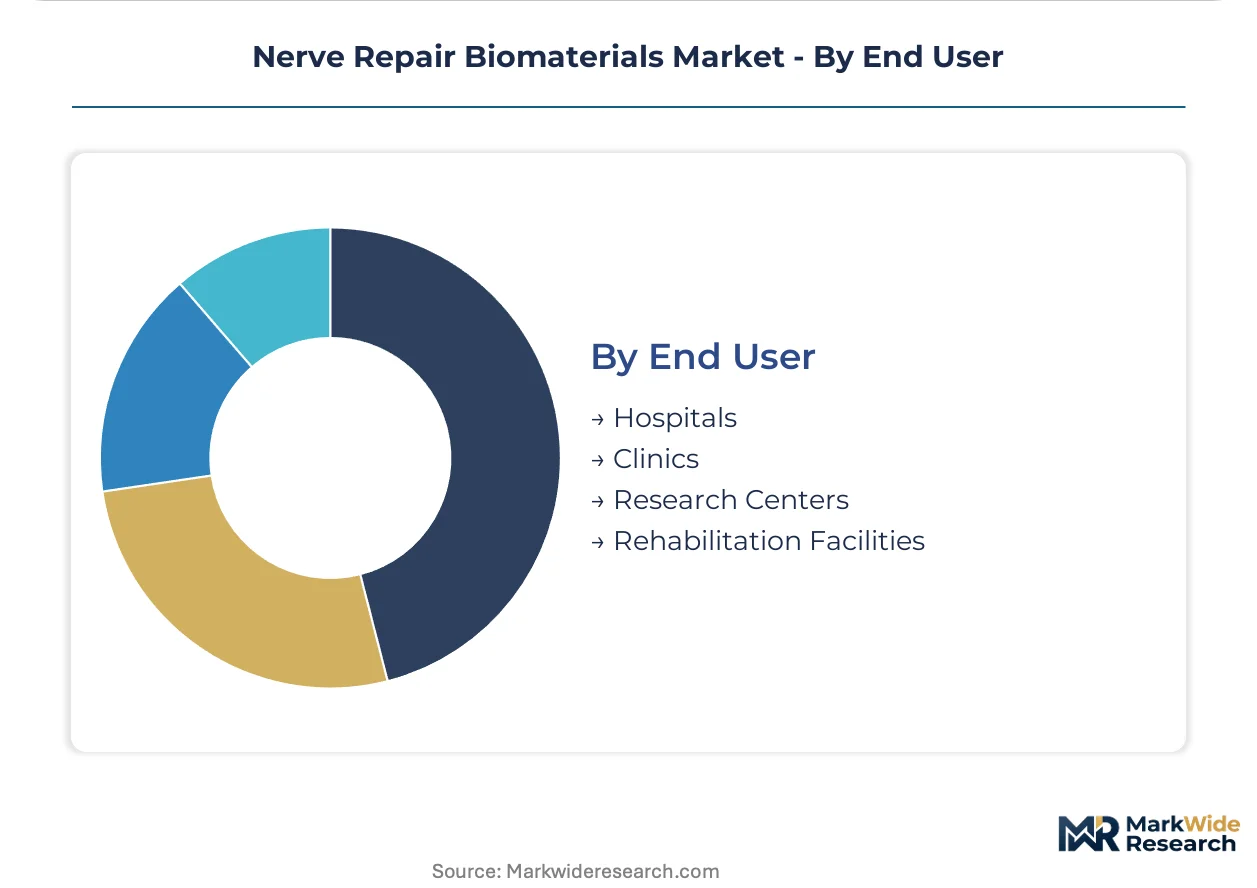
End User:
Customer type determines purchasing authority and evidence requirements: hospitals consolidate procurement through value analysis committees, while research centers drive early adoption of unproven material platforms.
- Hospitals:Tertiary academic medical centers and community hospitals with neurosurgical, orthopedic, or plastic surgery service lines. United States group purchasing organizations and German university hospital framework agreements consolidate vendor relationships around bundled nerve repair portfolios.
- Clinics:Ambulatory surgical centers and specialized hand surgery clinics performing peripheral nerve repair under local or regional anesthesia.
- Research Centers:Academic laboratories and contract research organizations generating preclinical safety and efficacy data for regulatory submissions.
- Rehabilitation Facilities:Post-acute care settings monitoring functional recovery endpoints that determine bundled payment reconciliation.
Hospitals dominate installed base through capital equipment integration and surgeon training infrastructure. Clinics are where expansion concentrates as ambulatory surgical migration accelerates and microsurgical technique dissemination broadens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export processed collagen conduits to United States trauma centers, while Japanese medical device distributors import synthetic scaffolds from Dutch polymer specialists to supply Tokyo's tertiary neurosurgical networks.
United States
FDA breakthrough device designations accelerate market entry for polycaprolactone-based platforms, compressing review timelines against standard PMA tracks. The agency's scrutiny of long-term biocompatibility data for resorbable synthetics shapes R&D prioritization across Boston and San Diego clusters. Tertiary academic medical centers in these coastal hubs anchor procurement consolidation through group purchasing organization frameworks.
Germany
EMA MDR requirements and REACH chemical safety standards govern material selection and batch-level traceability documentation for collagen and synthetic hybrid scaffolds. Captive polymer synthesis capabilities in Baden-Württemberg enable faster regulatory response than competitors dependent on merchant resin suppliers. University hospital framework agreements in Bavaria and North Rhine-Westphalia pioneer multi-year supply contracts bundled with surgical training commitments.
Japan
PMDA enforces stringent quality management system inspections for imported nerve repair devices, creating compliance barriers for Western suppliers targeting Tokyo and Osaka tertiary centers. Domestic manufacturers leverage JIS standards familiarity to defend market position against European and American entrants. Kanto region neurosurgical centers concentrate demand for complex brachial plexus reconstruction products.
United Kingdom
MHRA post-Brexit regulatory autonomy permits divergence from EMA MDR timelines, though most manufacturers maintain CE marking alignment for continental market access. London and Southeast England academic hospitals drive early adoption of electrospun nanofiber architectures in peripheral nerve repair protocols. The cluster attracts preclinical validation partnerships from silk-based scaffold developers seeking NHS procurement pathway entry.
Netherlands
Eindhoven Region polymer science infrastructure supports synthetic scaffold manufacturing with integrated monomer-to-device traceability meeting EMA MDR biological safety evaluation standards. Dutch manufacturers export electrospun platforms to German outpatient surgical centers underserved by current distribution models. Randstad medical technology clusters concentrate regulatory affairs expertise for pan-European market access.
Nerve Repair Biomaterials Market Vendor Landscape
On the supply side, the industry is consolidating around integrated platform providers capable of offering bundled nerve repair portfolios spanning conduits, wraps, and adjunctive fixation devices. The vendor base stratifies into three archetypes: allograft tissue processors leveraging biological material expertise, synthetic polymer specialists with captive manufacturing capabilities, and diversified medical technology conglomerates extending hardware into adjacent biomaterial delivery systems. Dominant competitive moves include strategic partnerships between scaffold developers and microsurgical training institutions, plus backward integration into polymer synthesis to secure supply chain control over degradation kinetics.
Within the diversified medical technology tier, Medtronic Plc and Abbott Laboratories occupy positions exemplifying hardware-to-biomaterial extension strategies, while Axogen Inc. anchors the allograft processing specialist archetype with focused biological platform development. Among European-based competitors, B. Braun SE and Polyganics B.V. represent synthetic scaffold manufacturing approaches differentiated by regional regulatory expertise.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Smith & Nephew Plc |
| Axogen Inc. |
| B. Braun SE |
| Polyganics B.V. |
| Integra LifeSciences |
| Boston Scientific Corporation |
| Orthocell Ltd. |
| Medtronic Plc |
| Others |
Supply Flow & Price Mechanics
Overcapacity in German synthetic polymer production lines is compressing unit economics for polycaprolactone nerve conduit manufacturers, forcing suppliers to absorb margin erosion or cede hospital procurement contracts to collagen-based competitors with tighter cost structures.
Pricing Analysis
Next-generation silk-polycaprolactone hybrid platforms command 40-60% premiums over established collagen conduits, while prior-generation allograft grafts face commoditization pressure from standardized synthetic alternatives. Three-tier pricing structure across premium, standard, and economy levels separates electrospun nanofiber architectures from extruded collagen tubes and basic gelatin wraps. Pricing pressure stems from REACH chemical safety reformulation costs that force unplanned material substitutions mid-development. Ambulatory surgical centers exhibit highest price sensitivity due to thin reimbursement margins, while Japanese tertiary neurosurgical centers prioritize clinical track records over acquisition cost.
Supply Chain Analysis
Export-control restrictions on advanced electrospinning equipment limit technology transfer to Chinese manufacturers, constraining domestic scaffold production capacity. Supply concentrates in Germany, the Netherlands, and the United States for synthetic polymer synthesis, while porcine-derived collagen inputs draw from Spanish and Danish agricultural processing hubs. Raw material dependencies span medical-grade silk fibroin from Thai sericulture operations, pharmaceutical-grade polycaprolactone monomers from BASF and Evonik facilities, and cross-linking agents subject to ECHA authorization delays. Single-source vulnerability in merchant resin supply creates formulation bottlenecks for mid-tier scaffold developers. Distribution runs through hospital group purchasing organizations in the United States and university hospital framework agreements in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where surgical training contracts and post-operative monitoring subscriptions expand faster than conduit hardware sales, embedding suppliers within hospital revenue cycles beyond the initial implant transaction.
For Market Incumbents: Insulate market position by deepening captive polymer synthesis capabilities in Baden-Württemberg and San Diego clusters to offset REACH-driven reformulation costs, while locking Japanese tertiary centers through PMDA QMS pre-certification investments that delay Western competitor entry. Consolidation around bundled nerve repair portfolios spanning conduits, wraps, and fixation devices displaces single-product vendors in United States group purchasing negotiations. For New Entrants and Emerging Players: Build out ambulatory surgical center penetration in German outpatient microsurgical clinics, where current distribution models remain fixated on inpatient tertiary networks. Electrospun nanofiber platforms offer the most penetrable white-space target given their preclinical momentum in brachial plexus reconstructions. Go-to-market execution should anchor on academic medical center pilot partnerships that generate outcome data for bundled payment qualification. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among synthetic scaffold developers with integrated polymer synthesis capabilities, as batch-level traceability documentation creates switching costs that sustain multi-year supply contracts. Long-term viability over a 5-10 year window favors platforms with demonstrated EMA MDR compliance and FDA breakthrough device designation momentum. Acquisition targets should display captive manufacturing control over degradation kinetics. The critical inflection signal to monitor is Japan PMDA approval acceleration for Western suppliers, which would validate regulatory pathway de-risking strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Synthesis | Captive production of polycaprolactone monomers accelerates EMA MDR batch-traceability compliance. |
| Hospital System Partnership | Multi-year framework agreements with German university hospitals bundle biomaterial supply with surgical training. |
| FDA Breakthrough Device Pathway | Accelerated review timelines compress commercialization cycles for silk-PCL hybrid platforms. |
| Software Companion Development | Post-operative monitoring applications embed conduit suppliers within bundled payment reconciliation workflows. |
| CE Marking Pathway | EMA MDR biological safety evaluation standards govern European commercialization for resorbable synthetics. |
Methodological Framework
Cross-validation between primary interviews with peripheral nerve surgeons, hospital procurement managers, biomedical engineers, and GPO contracts managers anchors the qualitative findings, while secondary sources including FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and CMS Medicare reimbursement data provide quantitative grounding. Bottom-up segmentation modeling triangulates against top-down market sizing across product type, material composition, application setting, and end-user category dimensions.
Calibration against historical adoption curves for collagen conduits and synthetic grafts shapes the projection framework across the analysis window. Segmentation dimensions modeled include product architecture, material degradation kinetics, surgical setting complexity, and regional regulatory cluster. CAGRs derive from fitted growth curves adjusted for procedure volume elasticity and reimbursement pathway maturity. Forecast inputs incorporate Schwann cell infiltration timelines and hospital procurement committee consolidation patterns.
Stress conditions across FDA long-term biocompatibility data requirements, REACH chemical safety reformulation mandates, and Japan PMDA QMS inspection intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding microsurgical technique standardization and group purchasing organization vendor consolidation. Material shifts in biodegradability testing protocols across FDA, EMA, and PMDA jurisdictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Global Collagen and HA Based Biomaterial Market
Biomaterials
Polysaccharide Hemostatic System Market
Biomaterials
Atelocollagen Market
Biomaterials
Hydrogel Face Mask Market
Biomaterials
Biomaterial in Surgical Mesh Market
Biomaterials
Global Collagen Meniscus Implants Market
Biomaterials
Global Absorbable Tissue Spacer Market
Biomaterials
Hemostatic Gels Market
Biomaterials
Global Hydroxyapatite Market
Biomaterials
North America Chitosan Market
Biomaterials
Hydrogel Market
Biomaterials
Global Biomaterials Market
Biomaterials
Orthopedic Bone Defect Repair Materials Market
Biomaterials
Mushroom Materials Market
Biomaterials
Calcium Phosphate Market
Biomaterials
Self-Healing Materials Market