
 Hemocytometer Market | 2026-2036
Hemocytometer Market Size, Share, and Industry Trends Forecast 2026-2036
Hemocytometer Market Analysis
Leasing arrangements for automated cell-counting platforms is tilting competitive dynamics toward vendors with strong service infrastructure. Hausser Scientific leverages its specialized glass-manufacturing heritage to sustain dominance in manual counting chambers for educational and reference laboratories. BRAND GmbH and Co. KG anchors European market presence through precision-molded disposable formats that reduce cross-contamination risk in high-throughput settings. Merck Millipore competes by extending life-science distribution networks into emerging bioproduction clusters.
A hemocytometer is a precision-etched glass chamber with defined volume boundaries, typically featuring a Neubauer-improved grid pattern at 0.1 mm depth, designed for manual or assisted enumeration of cells in suspension samples. The device serves fundamental quality-control functions across clinical diagnostics, bioprocessing, and reproductive medicine by enabling direct visual or image-based cell concentration and viability assessment. Automated hemocytometers command expanding placement in biopharmaceutical manufacturing due to 21 CFR Part 11 compliance demands and reduced operator variability. Manual variants retain substantial share in resource-limited clinical laboratories and academic training environments where capital constraints predominate. Fluorescent technology integration represents the fastest-expanding segment, driven by simultaneous viability and apoptosis detection requirements in cell therapy development.
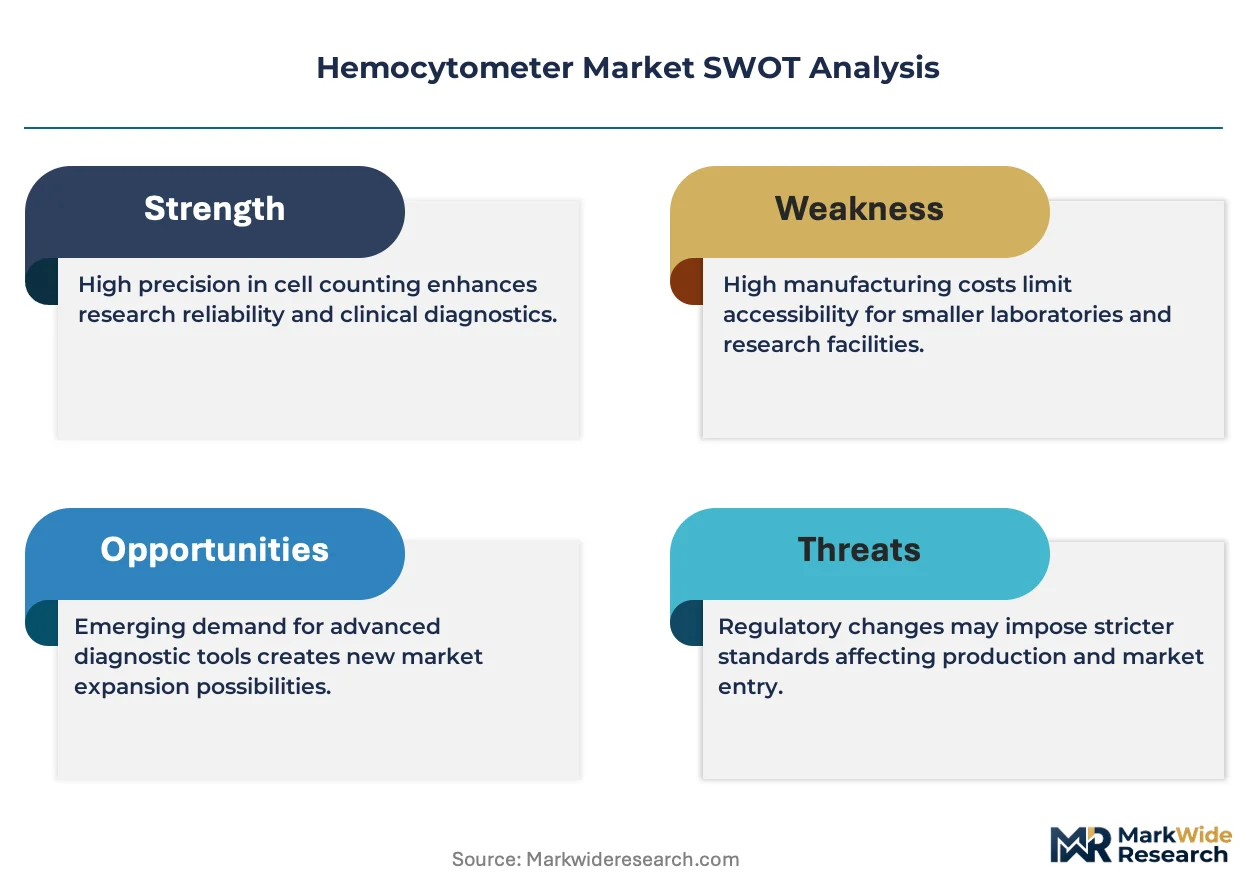
FDA quality-system regulations and ISO 13485 medical-device standards govern instrument validation protocols in United States markets, while the EU In Vitro Diagnostic Regulation imposes stricter clinical-evidence requirements on automated counting systems sold in Europe. The European Medicines Agency and national competent authorities coordinate post-market surveillance that elevates documentation burdens for non-EU manufacturers. China's National Medical Products Administration accelerates local-type testing mandates that favor domestic or jointly developed platforms. Stakeholders must monitor evolving harmonization between FDA guidance on cell therapy analytical procedures and EMA reflection papers on automated cell-counting validation to anticipate instrument qualification requirements.
Market Dynamics
The transition from manual counting chambers to fluorescence-integrated automated platforms is compressing placement timelines for legacy instruments while elevating service-contract values across biopharmaceutical manufacturing facilities.
Growth Catalysts
- Cell therapy manufacturing scale-up:Commercialization of CAR-T and stem cell therapies in the United States, Germany, and China is creating dedicated quality-control workflows that demand validated automated counting systems with 21 CFR Part 11 compliance.
- ISO 15189 laboratory accreditation:Clinical diagnostic laboratories pursuing international quality standards require documented traceability in cell enumeration, driving replacement of uncalibrated manual methods with certified automated platforms.
- Fluorescence detection integration:Simultaneous viability and apoptosis assessment in a single measurement run eliminates sequential workflow steps, accelerating adoption in contract development and manufacturing organizations.
Market Restraints
- Capital intensity of automated platforms:Initial instrument acquisition costs exceed manual chamber systems by an order of magnitude, restricting placement in academic and resource-limited clinical settings.
- Specialized borosilicate glass supply concentration:Precision-etched counting chambers rely on German and Japanese glass-manufacturing expertise, creating vulnerability to input material bottlenecks.
- EU In Vitro Diagnostic Regulation clinical-evidence requirements:Stricter documentation burdens for automated counting systems sold in Europe elevate compliance costs and extend market-entry timelines for non-EU manufacturers.
Strategic Opportunities
- India biopharmaceutical manufacturing expansion:CDSCO regulatory alignment with international standards and government production-linked incentives are attracting contract manufacturing investment that requires quality-control instrumentation.
- Point-of-care fertility diagnostics:Sperm concentration assessment in reproductive medicine clinics represents an underpenetrated application segment where portable automated counters address workflow constraints.
- Leasing and reagent-rental business models:Service infrastructure capabilities enable vendors to capture recurring revenue streams while lowering capital barriers for mid-sized bioproduction facilities.
Industry Challenges
- Multiplex assay validation complexity:Simultaneous detection of cell concentration, viability, and apoptosis markers requires extensive method-validation documentation that strains quality-assurance resources.
- Legacy LIMS integration friction:Automated platforms must interface with established laboratory information management systems, creating implementation delays and customization costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemocytometer Market |
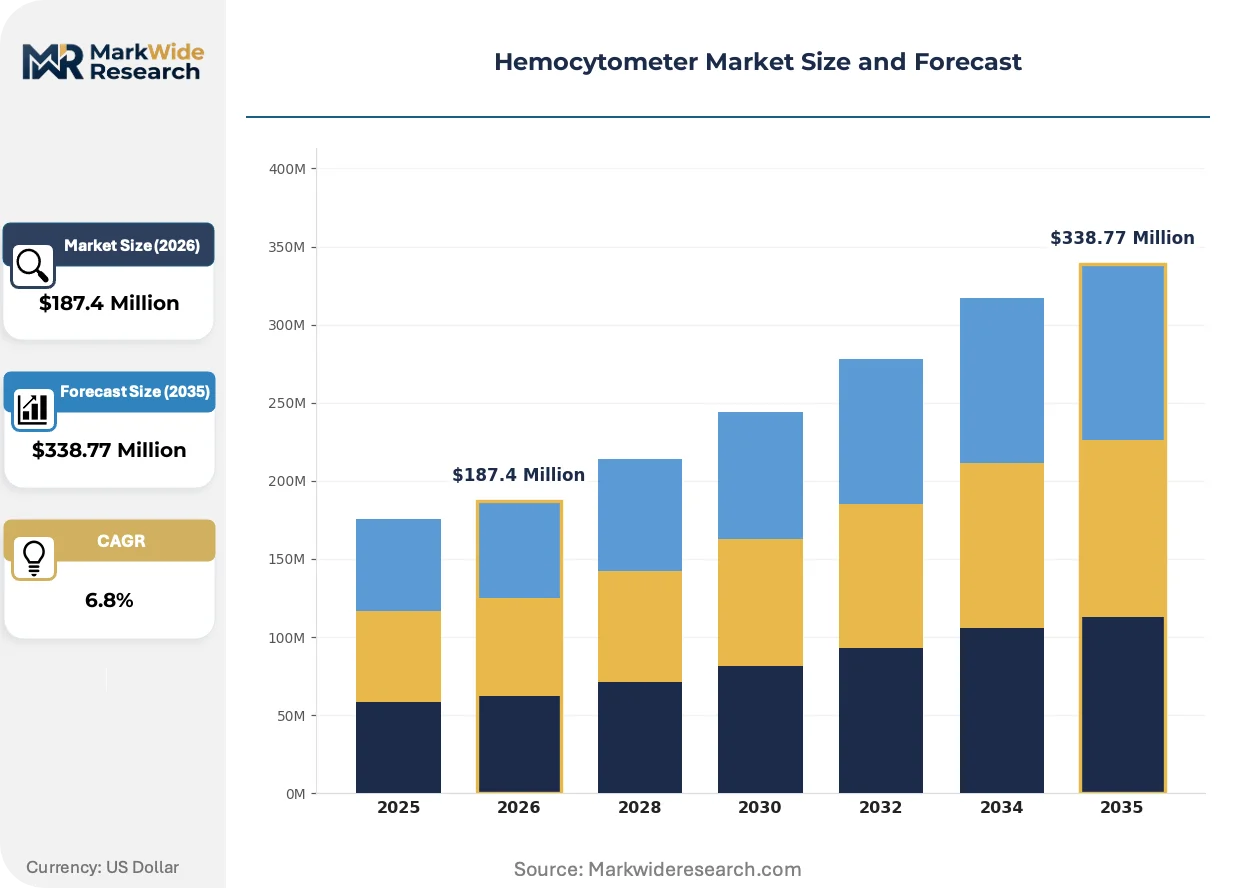
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Hemocytometers, Automated Hemocytometers, Disposable Hemocytometers, Digital Hemocytometers Application: Cell Counting, Hemoglobin Testing, Blood Analysis, Sperm Analysis End User: Hospitals, Diagnostic Laboratories, Research Institutes, Veterinary Clinics Technology: Optical, Electronic, Fluorescent, Microscope-Based |
| Companies Covered | Paul Marienfeld GmbH and Co. KG, Innovatek Medical, Thomas Scientific, Hausser Scientific, PHYWE Systems GmbH and Co. KG, BRAND GmbH and Co. KG, Merck Millipore, Abcam PLC, PerkinElmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemocytometer Market Emerging Trajectories
Digital image analysis and artificial intelligence classification are redefining performance benchmarks for cell enumeration accuracy while regulatory harmonization efforts reshape instrument qualification protocols across major manufacturing jurisdictions.
Bright-field imaging with machine-learning cell classification is rendering obsolete manual operator-dependent counting in high-throughput bioprocessing environments. Contract development and manufacturing organizations in the United States and China are adopting these platforms at accelerated replacement cycles. The technology is compressing analytical variability from inter-operator differences while enabling real-time process analytical technology integration.
The EU In Vitro Diagnostic Regulation's clinical-evidence requirements for automated cell-counting systems are elevating documentation burdens for manufacturers seeking European market access. Post-market surveillance coordination between the European Medicines Agency and national competent authorities is intensifying quality-system scrutiny. Automated platform vendors are responding by expanding regulatory-affairs capabilities and pre-submission engagement with notified bodies.
Service-unbundling and reagent-rental contracts are displacing traditional capital-equipment sales in mid-sized biopharmaceutical manufacturing facilities. Instrument vendors are establishing direct field-service organizations to capture recurring revenue and defend placement against competitors. This shift is most visible in the United States and Germany, where cell therapy manufacturing hubs prioritize uptime guarantees and rapid technical response over upfront purchase price.
Hemocytometer Market Segmentation
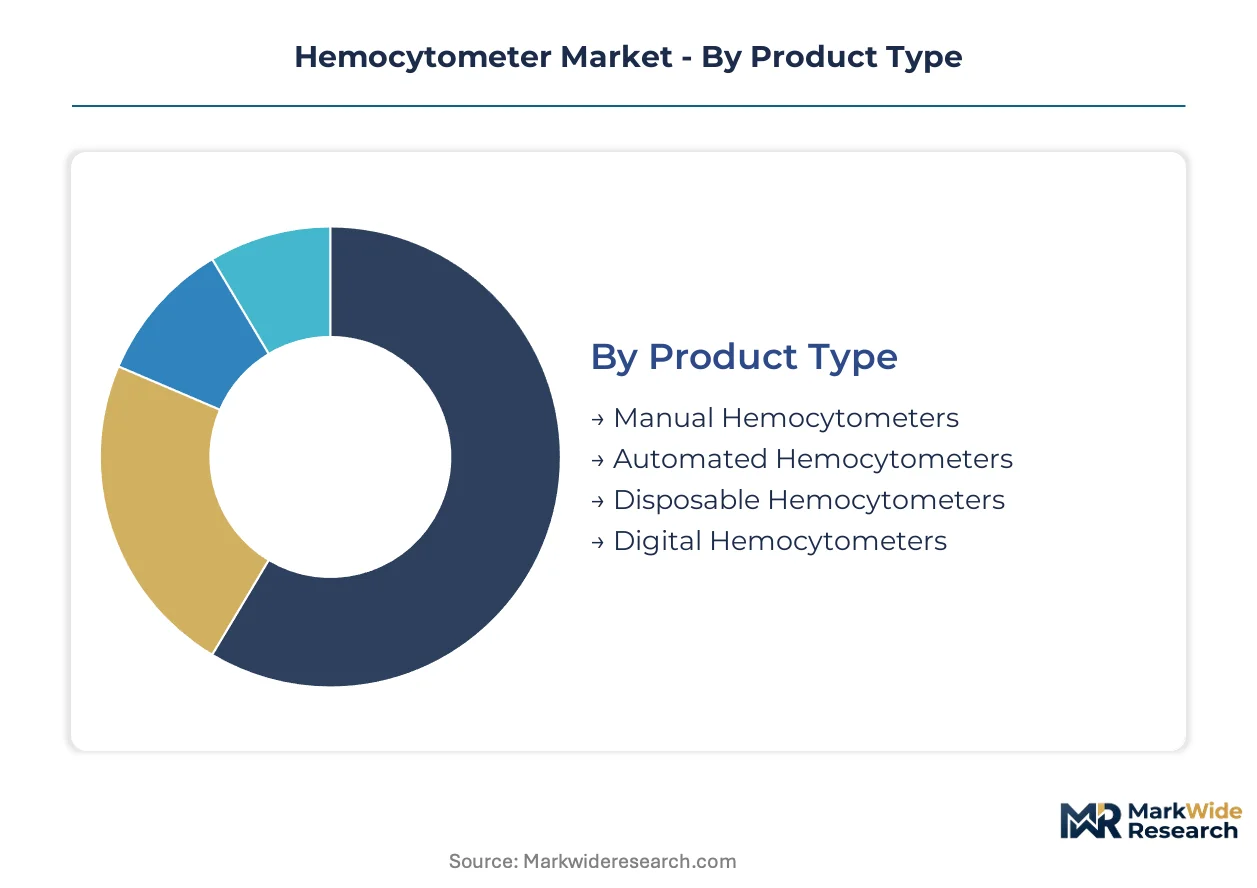
Segmentation in the hemocytometer market reveals divergent equipment lifecycles across product categories, with automated platforms turning over every 4-6 years while manual chambers persist for 15-20 years in educational settings. Understanding these replacement dynamics helps vendors align service contracts and reagent supply strategies to actual utilization patterns rather than nominal segment boundaries.
Product Type:
Replacement cycles vary dramatically across this category, with automated platforms refreshing fastest due to software obsolescence and compliance updates, while manual chambers exhibit the longest equipment persistence.
- Manual Hemocytometers:Precision-etched borosilicate glass chambers with Neubauer-improved grids at 0.1 mm depth remain standard equipment in university training laboratories across Germany and Japan where capital budgets constrain automation adoption. Educational institutions in these markets prioritize optical clarity and grid durability over throughput, sustaining demand for German-manufactured glass despite automated alternatives.
- Automated Hemocytometers:Image-analysis platforms with 21 CFR Part 11 compliance dominate quality-control workflows in United States cell therapy manufacturing facilities operated by contract development organizations. FDA validation requirements and reduced operator variability drive replacement of legacy bright-field systems with fluorescence-integrated models in CAR-T production hubs.
- Disposable Hemocytometers:Single-use polymer chambers eliminate cross-contamination risk in high-throughput diagnostic laboratories processing infectious samples.
- Digital Hemocytometers:USB-connected counting systems with cloud data export serve point-of-care fertility clinics requiring immediate sperm concentration results.
Manual hemocytometers dominate installed base across academic and resource-limited clinical settings. Automated hemocytometers represent where expansion concentrates in commercial bioproduction.
Application:
Volume concentration varies sharply by application, with cell counting commanding the largest absolute transaction flow while sperm analysis offers the steepest expansion trajectory in specialized reproductive medicine clinics.
- Cell Counting:Viability and concentration assessment in mammalian cell cultures constitutes the core workload for automated platforms in Chinese biopharmaceutical manufacturing facilities. NMPA-type testing mandates for locally produced cell therapies accelerate placement of validated counting systems with documented traceability.
- Sperm Analysis:Computer-assisted semen analysis in fertility clinics and andrology laboratories drives demand for portable automated counters with WHO-compliant morphology assessment. Reproductive medicine centers in the United States and Germany deploy these systems to reduce embryologist workload and standardize concentration reporting for IVF procedures.
- Hemoglobin Testing:Point-of-care hemoglobin quantification in blood donation centers and rural clinics utilizes simplified photometric adapters on manual chambers.
- Blood Analysis:Complete blood count verification in resource-limited settings employs manual chambers as backup to automated hematology analyzers.
Cell counting commands the largest equipment installed base. Sperm analysis is gaining share fastest in specialized reproductive medicine segments.
End User:
Procurement authority and budget scale differentiate this category, with hospitals consolidating purchasing through group procurement organizations while research institutes maintain fragmented acquisition patterns.
- Hospitals:Clinical laboratories within integrated health systems in the United States deploy automated platforms for STAT cell counts in oncology and transplant units. Joint Commission accreditation requirements and CAP proficiency testing mandates drive standardization on validated instruments with comprehensive service contracts.
- Diagnostic Laboratories:Independent reference laboratories processing high-volume cell enumeration for pharmaceutical trials prioritize throughput and LIMS connectivity in the United States and Germany. ISO 15189 accreditation requirements compel documented instrument calibration and operator competency records.
- Research Institutes:Academic cell biology laboratories balance capital constraints against experimental flexibility, sustaining manual chamber use for protocol development.
- Veterinary Clinics:Companion animal diagnostic practices utilize simplified automated counters for rapid complete blood count screening in clinical settings.
Diagnostic laboratories concentrate the highest-value automated platform placements. Research institutes sustain manual chamber demand through budget-constrained fragmentation.
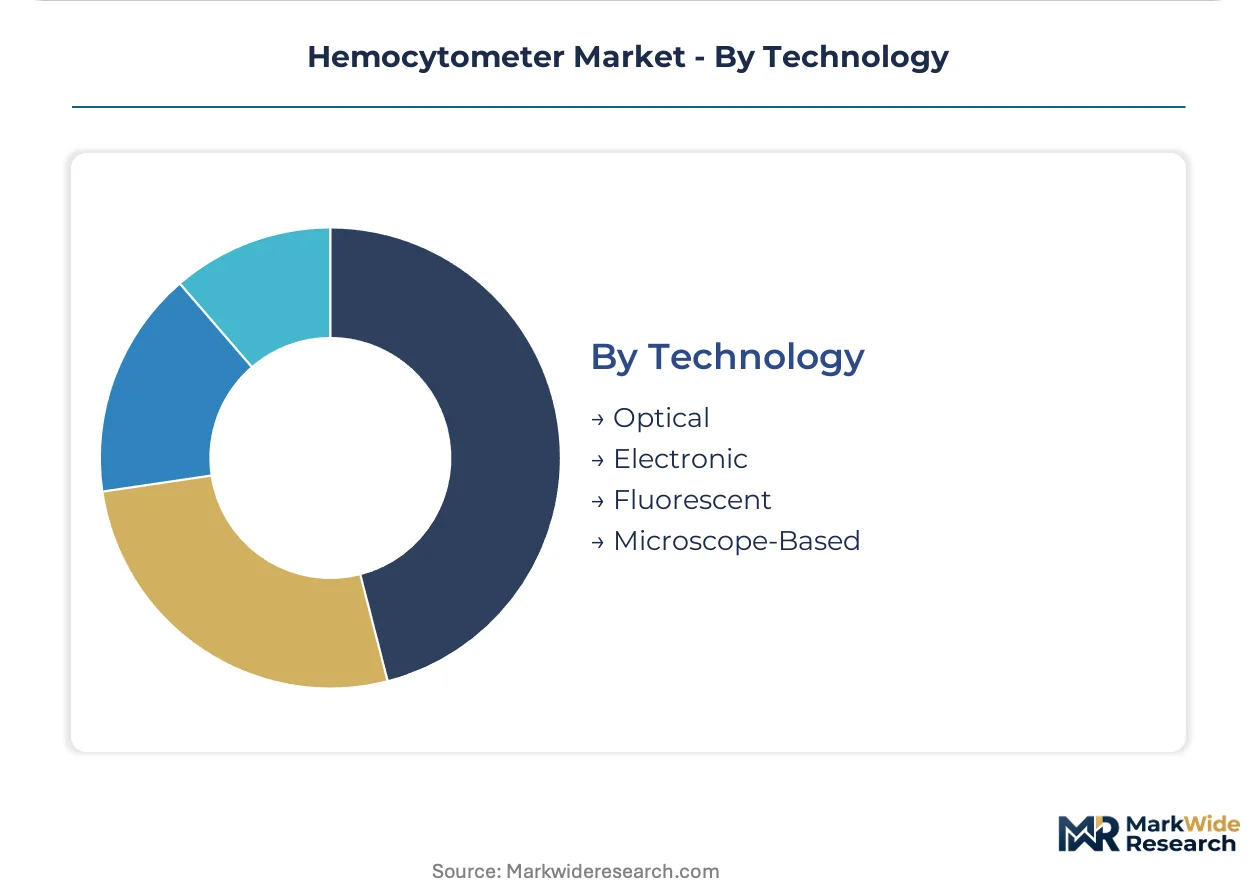
Technology:
Performance tier and regulatory validation burden stratify this category, with fluorescent systems commanding premium pricing and documentation requirements while optical platforms serve cost-sensitive applications.
- Fluorescent:Simultaneous detection of live, dead, and apoptotic cells through acridine orange/propidium iodide staining enables single-run viability assessment in cell therapy manufacturing. Contract development organizations in the United States and China adopt these platforms to eliminate sequential workflow steps in CAR-T quality control.
- Optical:Bright-field imaging with trypan blue exclusion remains standard for routine cell culture monitoring in research laboratories across Germany and Japan. Lower capital cost and simplified maintenance sustain placement in facilities without fluorescence microscopy infrastructure.
- Electronic:Impedance-based cell counting in portable devices serves point-of-care applications requiring battery operation and minimal sample preparation.
- Microscope-Based:Traditional manual counting with calibrated eyepiece reticles persists in regulatory reference laboratories performing standardized method comparisons.
Optical technology dominates current installed base. Fluorescent platforms are expanding most quickly in cell therapy manufacturing quality control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal concentrated manufacturing in Germany and Japan for precision glass chambers, while the United States and China absorb the majority of automated platform imports for cell therapy manufacturing. Trade flows favor specialized component exports from European glass fabricators toward Asian bioproduction clusters.
United States
FDA 21 CFR Part 11 validation requirements and CAR-T commercialization drive automated hemocytometer placement in Boston and San Francisco biotech corridors. The agency's quality-system regulations mandate documented traceability for cell enumeration in regenerative medicine applications. Contract development organizations in Massachusetts and California operate dedicated quality-control workflows requiring compliant counting systems.
Germany
Precision borosilicate glass manufacturing expertise and ISO 13485 medical-device standards sustain export leadership in manual counting chambers. The EU In Vitro Diagnostic Regulation imposes clinical-evidence documentation that elevates compliance costs for automated systems. Industrial clusters in Baden-Württemberg and Bavaria host specialized etching facilities serving global educational and reference laboratory demand.
China
NMPA local-type testing mandates and government bioproduction incentives accelerate domestic platform development for cell therapy quality control. National Medical Products Administration regulatory alignment pressures multinational vendors toward joint-development partnerships. Manufacturing hubs in Shanghai and Suzhou integrate automated counting into CAR-T and stem cell production workflows.
Japan
PMDA pharmaceutical manufacturing guidelines and METI industrial policy support precision instrument development for bioprocessing applications. Japanese glass-manufacturing heritage supplies specialized substrates for high-end manual chambers. Tokyo-Osaka industrial corridors maintain demand for both educational-grade glassware and research-automation platforms.
India
CDSCO regulatory harmonization and government production-linked incentives attract contract manufacturing investment requiring quality-control instrumentation. Central Drugs Standard Control Organization alignment with international standards enables instrument qualification for export-oriented bioproduction. Hyderabad and Bangalore clusters emerge as cell therapy manufacturing locations driving automated platform procurement.
Hemocytometer Market Vendor Landscape
On the supply side, the industry is bifurcated between heritage glass-manufacturing specialists and diversified life-science conglomerates competing through service infrastructure rather than hardware differentiation alone. Two strategic archetypes dominate: precision-etched glass fabricators leveraging generational manufacturing expertise, and distribution-integrated multinationals extending reagent-rental business models. Competitive moves concentrate on field-service organization expansion and regulatory-affairs capability building to accelerate instrument qualification timelines.
Among German precision manufacturers, Paul Marienfeld GmbH and Co. KG and BRAND GmbH and Co. KG exemplify the heritage glass-fabrication archetype, while Merck Millipore occupies a position representing distribution-integrated life-science conglomerates. Hausser Scientific anchors North American manual chamber supply through specialized manufacturing heritage. These named entities represent distinct competitive positioning vectors rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Paul Marienfeld GmbH and Co. KG |
| Innovatek Medical |
| Thomas Scientific |
| Hausser Scientific |
| PHYWE Systems GmbH and Co. KG |
| BRAND GmbH and Co. KG |
| Merck Millipore |
| Abcam PLC |
| PerkinElmer |
| Others |
Supply Flow & Price Mechanics
Frankfurt-Shanghai air freight corridors carry precision-etched borosilicate glass chambers at rates that amplify cost differentials between German-manufactured manual hemocytometers and Chinese-assembled automated platforms, compressing margins for mid-tier optical instrument vendors while reinforcing premium pricing power among heritage glass fabricators.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the hemocytometer market. Price differentiation rests on ISO 13485 certification grade and fluorescence detection capability, with automated platforms commanding substantial premiums over manual chambers. Cost compression in the standard tier intensifies because contract development organizations consolidate procurement volumes. Academic laboratories exhibit the highest price sensitivity, while cell therapy manufacturers prioritize compliance documentation over acquisition cost.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk planning for precision glass component sourcing. Manufacturing concentrates in Germany, Japan, and China, with specialized borosilicate glass drawing from Schott AG and Nippon Electric Glass captive supply. Single-source vulnerability persists for Neubauer-improved grid etching equipment. Distribution runs through life-science distributors in the United States and direct field-service organizations in European bioproduction clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized regulatory-affairs expertise for FDA 21 CFR Part 11 and EU In Vitro Diagnostic Regulation compliance represents the critical capability gap constraining market expansion, separating vendors who capture cell therapy manufacturing contracts from those relegated to educational segments.
For Market Incumbents: Build switching-cost moats through reagent-rental contracts and embedded LIMS integration. Deepen field-service density in Boston and San Francisco biotech corridors to defend placement against emerging fluorescence-platform competitors. Prioritize backward integration into borosilicate glass supply to insulate margin structure from German-Japanese substrate bottlenecks. For New Entrants and Emerging Players: Indian biopharmaceutical manufacturing clusters offer the most penetrable geography for automated platform entry. Target CDSCO-aligned contract manufacturing organizations in Hyderabad and Bangalore with leasing models that circumvent capital intensity barriers. Pursue point-of-care fertility diagnostics as a channel to establish brand presence before scaling into cell therapy quality control. For Investors and Strategic Acquirers: Heritage glass-fabrication specialists with ISO 13485 certification and established educational distribution represent the optimal acquisition target archetype. Long-term viability over the next decade hinges on fluorescence-integration capability and regulatory-affairs scale. Monitor FDA guidance harmonization with EMA reflection papers on automated cell-counting validation as the decisive inflection signal for platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorescence Detection Integration | Enables simultaneous viability-apoptosis assessment for CAR-T quality control workflows. |
| Reagent-Rental Business Model | Converts capital equipment sales into recurring revenue streams with embedded service contracts. |
| Regulatory-Affairs Capability Expansion | Accelerates EU In Vitro Diagnostic Regulation compliance timelines for automated platform entry. |
| Backward Integration into Glass Supply | Secures captive borosilicate substrate access against German-Japanese supply concentration. |
| LIMS Connectivity Development | Reduces implementation friction in diagnostic laboratories pursuing ISO 15189 accreditation. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU notified body documentation, and NMPA type-testing records. Interviews with biopharmaceutical quality-control directors, clinical laboratory accreditation officers, and hemocytometer product managers informed demand-side segmentation. Secondary sources include ISO 13485 audit databases, GPO contract repositories, and customs trade flows for precision glass components. Bottom-up instrument placement estimates triangulate against top-down bioproduction capacity expansion projections.
Forecast inputs incorporate technology adoption curves across fluorescent, optical, and electronic detection platforms over the projection horizon. Segmentation dimensions span product type, application workflow, end-user procurement authority, and regional regulatory cluster. CAGRs derive from replacement cycle analysis and penetration rate modeling in cell therapy manufacturing. Cell therapy commercialization timelines and ISO 15189 accreditation momentum serve as industry-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in biopharmaceutical capital expenditure cycles or trade policy affecting German-Chinese glass component flows would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization pace and fluorescence-platform cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Sickle Cell Disease Market
Hematology
Sickle-Cell Anemia Therapeutics Market
Hematology
Anemia Drugs Market
Hematology
AL Amyloidosis Therapeutics Market
Hematology
Follicular Lymphoma Treatment Market
Hematology
Polycythemia Vera Market
Hematology
Haematocrit Centrifuge Market
Hematology
Venous Blood Collection Market
Hematology
Hemoglobinopathy Treatment Drug Market
Hematology
Thalassemia Treatment Market
Hematology
Heparin-Induced Thrombocytopenia (HIT) Treatment Market
Hematology
Apheresis Market
Hematology
Febrile Neutropenia Market
Hematology
Patient Blood Management Market
Hematology
Global Bleeding Disorders Market
Hematology
Lymphopenia Therapeutics Market