
 Global Sickle Cell Disease Treatment Market | 2026-2036
Global Sickle Cell Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sickle Cell Disease Treatment Market Foresight
Modular therapy bundling—pairing chronic disease management with acute crisis protocols—is rebalancing how payers evaluate total cost of care. Novartis AG leverages its established hematology infrastructure to anchor commercial access across multiple continents. Bluebird bio, Inc. specializes in gene therapy manufacturing complexity, while CRISPR Therapeutics competes on editing platform breadth.
Sickle cell disease treatment encompasses pharmacologic agents, transfusion protocols, and curative gene-modifying therapies designed to modulate hemoglobin polymerization, reduce vaso-occlusive events, and prevent end-organ damage in patients with inherited hemoglobinopathies. Hydroxyurea and voxelotor represent the established oral maintenance segment, whereas crizanlizumab infusion commands premium positioning in crisis prevention. Vaso-occlusive crisis management absorbs the largest current spend, but anemia management protocols are expanding fastest as providers integrate patient-reported outcome metrics into reimbursement frameworks.
The FDA maintains accelerated approval pathways for sickle cell innovations, while the EMA's orphan drug incentives shape European commercial strategy. Brazil's ANVISA and national health technology assessment bodies in England and France determine market access timelines for novel therapies. Stakeholders must monitor how gene therapy durability data influences payer willingness to shift from chronic pharmacologic spending toward one-time curative interventions.
Market Dynamics
The transition from chronic pharmacologic management toward one-time curative gene-modifying interventions is restructuring payer evaluation frameworks and provider capacity planning across major health systems.
Growth Catalysts
- EMA Orphan Drug Incentives:Accelerated market access pathways in Europe reduce development-to-commercialization timelines for novel hemoglobinopathies therapies, attracting pipeline investment.
- Brazil Newborn Screening:ANVISA-mandated universal screening protocols identify patients within weeks of birth, expanding addressable populations for early-intervention protocols.
- CRISPR Platform Maturation:Base editing and prime editing refinements enable more precise HBB gene modifications with reduced off-target risks, broadening eligible patient pools.
Market Restraints
- Vector Manufacturing Bottlenecks:Lentiviral and AAV production capacity concentrates at fewer than ten contract manufacturing organizations globally, creating queue delays for commercial-scale gene therapy supply.
- Reimbursement Uncertainty:CMS and national health technology assessment bodies in England lack established frameworks for single-administration curative therapies with multi-million dollar price points.
- Allogeneic Transplant Substitution:Matched sibling donor bone marrow transplantation remains available at select academic medical centers, competing for curative-intent patient segments.
Strategic Opportunities
- Sub-Saharan Africa Penetration:Nigeria and the Democratic Republic of Congo host the world's largest untreated sickle cell populations, presenting partnership opportunities with national malaria control programs.
- Patient-Reported Outcome Integration:FDA's guidance on PRO-based endpoints creates pathways for therapies demonstrating quality-of-life improvements beyond traditional clinical biomarkers.
- Telemedicine-Infusion Hybrid Models:Remote monitoring platforms paired with regional infusion centers reduce travel burden for patients requiring recurrent crizanlizumab administration.
Industry Challenges
- Gene Therapy Workforce Scarcity:Qualified cell processing specialists and vector quality-control analysts remain concentrated at established academic centers, constraining site expansion.
- Long-Term Durability Surveillance:Post-marketing commitment requirements for fifteen-year follow-up protocols impose sustained data infrastructure costs on commercial sponsors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sickle Cell Disease Treatment Market |
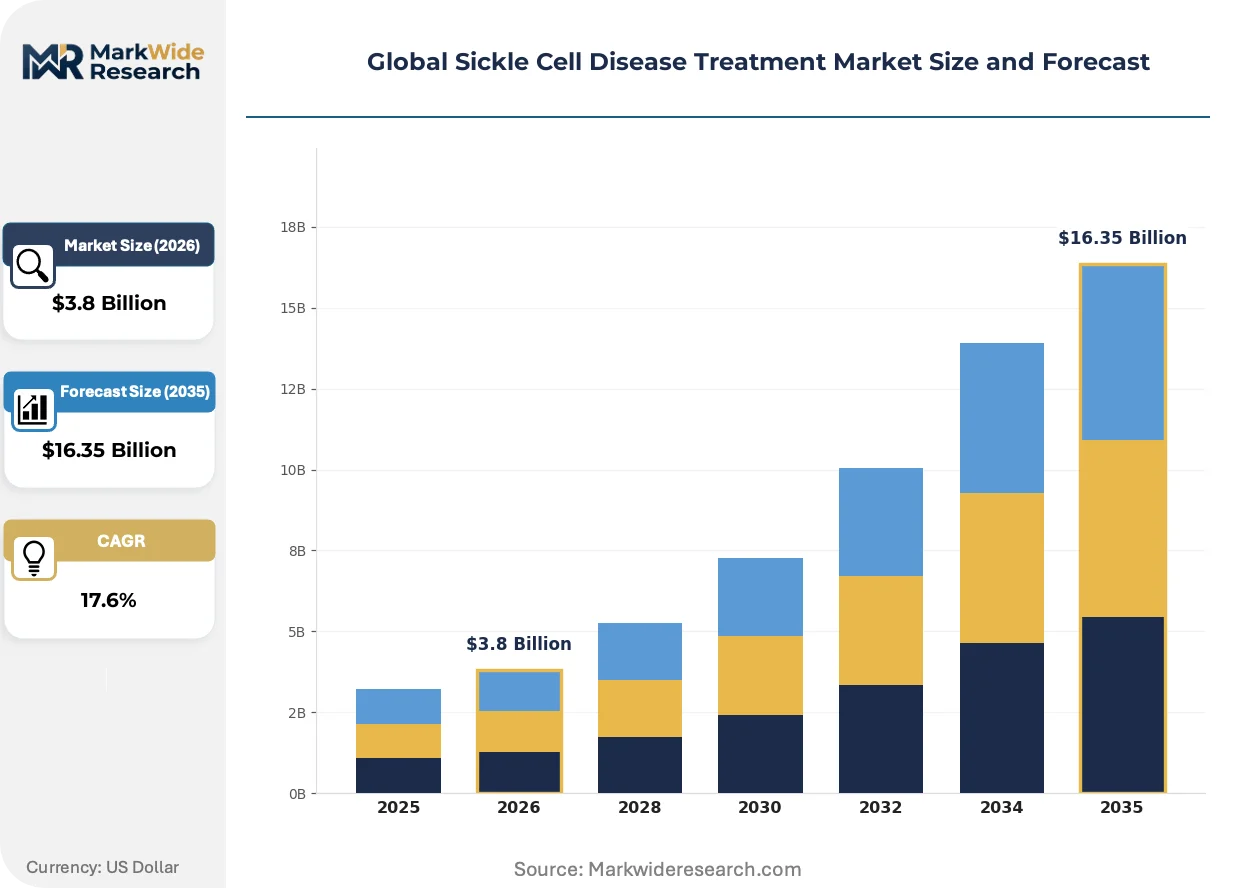
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.35 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydroxyurea, L-Glutamine, Crizanlizumab, Voxelotor Therapy Area: Vaso-Occlusive Crisis, Anemia Management, Stroke Prevention, Organ Damage Reduction End User: Specialty Clinics, Research Institutes, Diagnostic Laboratories, Home Care Providers Delivery Mode: Oral, Injectable, Infusion, Transfusion Therapy |
| Companies Covered | Novartis AG, Pfizer Inc., Bristol-Myers Squibb Company, Emmaus Medical, Inc., Bluebird bio, Inc., Global Blood Therapeutics, Inc., Vertex Pharmaceuticals, CRISPR Therapeutics, Agios Pharmaceuticals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sickle Cell Disease Treatment Market Shifts & Advancements
Convergence of gene editing platforms with real-world evidence generation is compressing traditional clinical development timelines while forcing adaptation across manufacturing and reimbursement infrastructure.
CRISPR-Cas12a systems are integrating into commercial pipelines as next-generation editing tools offering smaller guide RNA requirements and expanded PAM sequence targeting. Academic medical centers in Boston and London are adopting these platforms for investigator-initiated trials. The technology is integrating with automated cell processing workflows, reducing manual manipulation steps and improving batch consistency for autologous therapies.
FDA's accelerated approval pathway for regenerative medicine advanced therapies is compressing Phase II-to-launch intervals for qualifying sickle cell interventions. The framework permits approval based on surrogate endpoints with confirmatory trials required post-market. Gene therapy developers are responding by structuring rolling submissions and building real-world evidence capture infrastructure during pivotal studies.
Hospital-at-home protocols for vaso-occlusive crisis management are displacing emergency department reliance among commercially insured populations in the United States. Virtual nursing platforms coordinate home opioid administration and hydration monitoring. This shift concentrates in southeastern states where dedicated sickle cell centers have established remote monitoring capabilities.
Global Sickle Cell Disease Treatment Market Segmentation
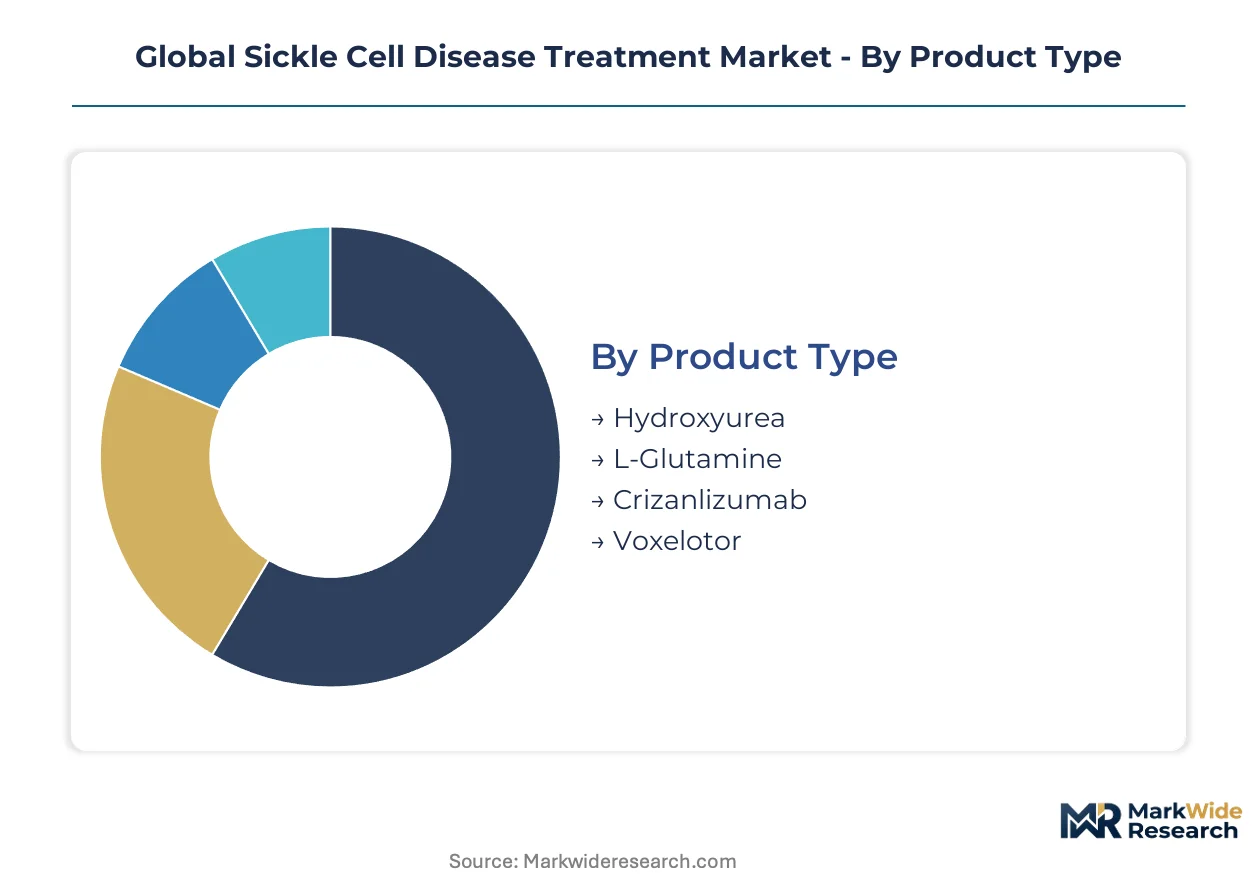
Sickle cell disease treatment segments diverge sharply between chronic pharmacologic maintenance and curative gene-modifying interventions. Payer reimbursement frameworks and provider infrastructure requirements differ fundamentally across these boundaries, forcing distinct commercial strategies for each segment cluster.
Product Type:
Volume concentrates in oral maintenance agents, while premium pricing attaches to monoclonal antibody infusions and emerging gene therapies.
- Hydroxyurea:The first FDA-approved oral agent increases fetal hemoglobin production through ribonucleotide reductase inhibition. Demand concentrates in Brazil's SUS network and Medicaid programs across southeastern United States, driven by decades of safety data and generic cost structures. Mature deployment sits with Hydroxyurea. Newer deployment is concentrated in Voxelotor.
- Voxelotor:A hemoglobin oxygen-affinity modulator that polymerizes sickled hemoglobin through covalent binding to the alpha-chain. Adoption clusters at academic medical centers in Boston and London with integrated pharmacy benefit management, constrained by prior authorization requirements from national health technology assessment bodies. Expanding most quickly among commercially insured adolescents transitioning from pediatric care.
- Crizanlizumab:P-selectin inhibitor delivered via monthly infusion to reduce vaso-occlusive crisis frequency.
- L-Glutamine:Oral amino acid supplement reducing oxidative stress in red blood cell membranes.
Oral agents dominate prescription volumes. Infusion therapies capture disproportionate revenue per treated patient.
Therapy Area:
Application focus shifts from acute crisis intervention toward preventive organ protection as biomarker surveillance improves.
- Vaso-Occlusive Crisis:Acute pain episodes requiring emergency department or infusion center management represent the historical treatment anchor. Demand localizes at dedicated sickle cell centers in Atlanta, Baltimore, and London with 24-hour crisis protocols, pressured by hospital-at-home substitution among commercially insured populations. Stroke Prevention commands the steepest expansion trajectory as transcranial Doppler screening protocols expand.
- Stroke Prevention:Chronic transfusion programs for children with abnormal cerebral blood flow velocities. Concentration at pediatric hematology centers in São Paulo and Philadelphia, driven by STOP trial evidence and ANVISA-mandated newborn screening follow-up protocols. Transcranial Doppler surveillance infrastructure determines regional penetration.
- Anemia Management:Transfusion-dependent protocols and emerging agents targeting hemolysis reduction.
- Organ Damage Reduction:Nephroprotective and cardioprotective interventions for end-organ preservation.
Crisis management absorbs current capacity. Organ protection protocols are gaining share fastest among integrated delivery networks.
End User:
Care site selection depends on therapy complexity, with oral agents decentralizing toward community settings and gene therapies concentrating at quaternary centers.
- Specialty Clinics:Dedicated sickle cell centers with multidisciplinary teams including hematology, pain management, and social work. Concentration in southeastern United States and urban Brazil, serving as anchor sites for clinical trial enrollment and gene therapy referral networks. Research Institutes concentrate novel therapy development. Specialty Clinics capture routine chronic care.
- Research Institutes:Academic medical centers in Boston, London, and São Paulo conducting investigator-initiated trials and gene therapy manufacturing qualification. CRISPR platform development and real-world evidence infrastructure deployment occur at these sites, constrained by workforce scarcity in cell processing specialization.
- Diagnostic Laboratories:Newborn screening and confirmatory hemoglobinopathy testing.
- Home Care Providers:Virtual nursing platforms coordinating crisis management and oral therapy adherence.
Institutional sites dominate complex therapy delivery. Home-based models are penetrating crisis management among commercially insured cohorts.
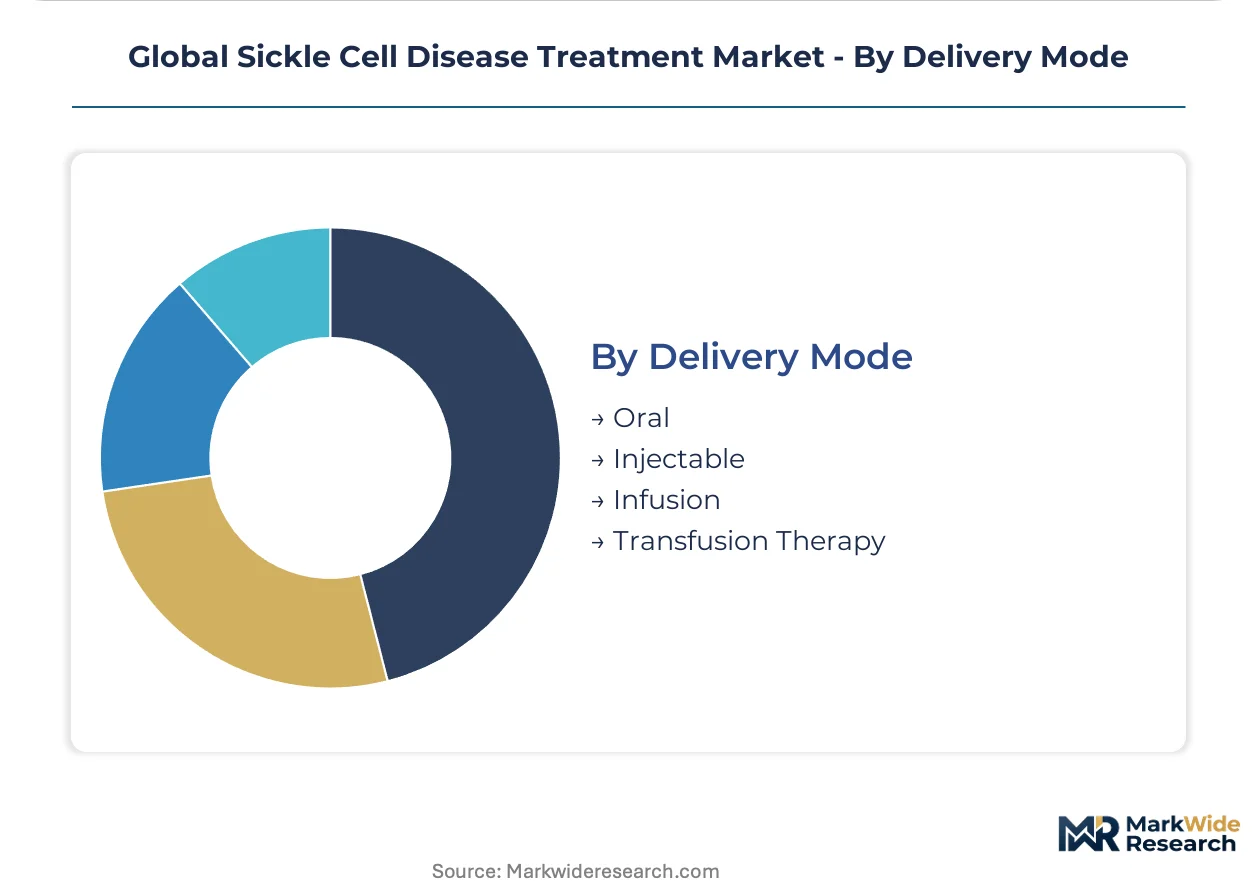
Delivery Mode:
Route selection constrains patient eligibility and reimbursement pathways, with infusion and transfusion requiring specialized infrastructure.
- Oral:Hydroxyurea and L-glutamine enable decentralized prescribing across primary care and community hematology practices. Penetration extends to rural southeastern United States and Brazil's interior states through telemedicine-supported protocols, limited by adherence monitoring capabilities. Infusion commands premium positioning. Oral captures volume scale.
- Infusion:Crizanlizumab and gene therapy preparation require apheresis-capable centers with vector handling certification. Concentration at fewer than fifty qualified sites across United States and Europe, creating geographic access barriers and queue delays for commercial-scale gene therapy supply.
- Injectable:Subcutaneous and intramuscular formulations in development for crisis prevention.
- Transfusion Therapy:Chronic exchange programs for stroke prevention and acute red cell exchange for crisis management.
Oral routes dominate patient reach. Infusion and transfusion modes constrain capacity expansion at qualified centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gene therapy manufacturing capacity concentrates at academic medical centers in Boston and London, while patient demand clusters in Brazil, Nigeria, and the southeastern United States where newborn screening programs expand treatable populations.
United States
Hospital systems in Atlanta, Baltimore, and Philadelphia operate dedicated sickle cell infusion centers with 24-hour crisis protocols. FDA's accelerated approval pathway for regenerative medicine advanced therapies compresses development timelines for gene-modifying interventions. The National Institutes of Health funds investigator-initiated trials at Boston-area academic medical centers where CRISPR platform development occurs.
Brazil
ANVISA-mandated universal newborn screening identifies patients within weeks of birth, expanding addressable populations for early-intervention protocols across São Paulo and Rio de Janeiro. The national SUS network drives hydroxyurea volume through decades of safety data and generic cost structures. Pediatric hematology centers in São Paulo anchor chronic transfusion programs for stroke prevention.
United Kingdom
NHS England's health technology assessment bodies determine market access timelines for novel therapies with multi-million dollar price points. London academic medical centers qualify for gene therapy manufacturing certification, though workforce scarcity in cell processing specialization constrains site expansion. The National Institute for Health and Care Excellence evaluates voxelotor adoption through integrated pharmacy benefit frameworks.
Nigeria
The country hosts the world's largest untreated sickle cell population, presenting partnership opportunities with national malaria control programs for integrated disease management. General functional descriptors for pharmaceutical regulation apply as specific framework names remain outside standard knowledge bases. Lagos and Abuja concentrate diagnostic laboratory capacity for newborn screening expansion.
Germany
EMA orphan drug incentives attract pipeline investment for hemoglobinopathy therapies through reduced development-to-commercialization timelines. Berlin and Munich academic centers participate in European gene therapy referral networks. Federal joint committee health technology assessment processes evaluate one-time curative interventions against chronic pharmacologic spending benchmarks.
Global Sickle Cell Disease Treatment Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with established hematology infrastructure. Large-cap developers anchor commercial access across multiple continents through existing hospital system relationships. Mid-tier gene therapy specialists concentrate manufacturing complexity capabilities at qualified academic centers. Strategic moves center on vector manufacturing capacity expansion and real-world evidence infrastructure deployment to support payer negotiations.
Among the named developers, Novartis AG and Pfizer Inc. represent established pharmaceutical infrastructure archetypes with broad hematology portfolios, while Bluebird bio, Inc. occupies a position exemplifying gene therapy manufacturing specialization. Bristol-Myers Squibb Company anchors immunology-oncology crossover capabilities relevant to cell processing workflows. CRISPR Therapeutics sits within the platform technology tier where editing breadth determines competitive positioning against base editing alternatives.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| Emmaus Medical, Inc. |
| Bluebird bio, Inc. |
| Global Blood Therapeutics, Inc. |
| Vertex Pharmaceuticals |
| CRISPR Therapeutics |
| Agios Pharmaceuticals, Inc. |
| Others |
Supply & Pricing Matrix
Gene therapy manufacturing specialists backed by venture capital and strategic pharmaceutical investors dominate production capacity, concentrating pricing power at fewer than fifty qualified apheresis-capable centers worldwide while constraining supply expansion through workforce scarcity in cell processing specialization.
Pricing Analysis
Cost-down pressure on gene therapy tiers accelerates because CMS and England's NICE lack established reimbursement frameworks for single-administration curative interventions with multi-million dollar price points. Three-tier pricing structure across premium gene-modifying, standard monoclonal antibody infusion, and economy oral maintenance levels separates crizanlizumab from voxelotor from hydroxyurea. Price differentiation hinges on FDA accelerated approval status and manufacturing complexity certification. Commercially insured populations show least price sensitivity for crisis prevention protocols, while Medicaid programs and Brazil's SUS network drive volume at generic oral price points.
Supply Chain Analysis
Domestic-content mandates for vector manufacturing qualification in the United States and United Kingdom are reshaping sourcing patterns for lentiviral and AAV production. Supply concentrates at contract manufacturing organizations in the United States, Germany, and Switzerland, with raw material dependencies on plasmid DNA, cell culture media, and chromatography resins. Single-source vulnerability in qualified cell processing specialists constrains site expansion. Distribution runs through academic medical center networks with apheresis and vector handling certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vector manufacturing bottlenecks at fewer than ten global contract manufacturing organizations prop pricing discipline across gene therapy tiers, creating sustained supply-constrained conditions favoring incumbents with captive production capacity.
For Market Incumbents: Deploy backward integration into lentiviral vector manufacturing to secure commercial-scale supply queues against emerging CRISPR platform competitors. Anchor hospital system relationships through dedicated sickle cell infusion center partnerships in Atlanta, Baltimore, and São Paulo. Lock in reimbursement pathways with CMS and NICE through real-world evidence infrastructure deployment during pivotal studies. For New Entrants and Emerging Players: CRISPR-Cas12a base editing platforms offer entry wedge into investigator-initiated trial networks at Boston and London academic centers with reduced off-target risk profiles. Target Nigeria and the Democratic Republic of Congo through partnership with national malaria control programs for integrated disease management. Pursue telemedicine-infusion hybrid models to reduce geographic access barriers for recurrent crizanlizumab administration. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier gene therapy specialists with manufacturing complexity capabilities in the United States and Europe over platform-technology pure-plays. Monitor FDA post-marketing commitment requirements for fifteen-year follow-up protocols as signal of sustained data infrastructure cost burdens. Watch EMA orphan drug incentive utilization rates as inflection indicator for pipeline investment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Vector Manufacturing Scale-Up | Expands commercial supply capacity at FDA-qualified academic medical centers. |
| Real-World Evidence Infrastructure | Supports payer negotiations with CMS and NICE through post-market surveillance. |
| Telemedicine-Infusion Hybrid Models | Reduces travel burden for crizanlizumab patients in southeastern United States. |
| Sub-Saharan Africa Partnership | Accesses untreated populations in Nigeria through malaria control integration. |
| CRISPR Platform Advancement | Enables precise HBB gene modifications with expanded PAM targeting at Boston centers. |
Research Methodology
Multi-period observation of FDA accelerated approval pathways, EMA orphan drug incentive utilization, and ANVISA newborn screening expansion anchored the trend analysis, supplemented by interviews with gene therapy development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population modeling triangulated against top-down pharmaceutical revenue estimates.
Segment-weighting across therapy area, delivery mode, and regional regulatory cluster dimensions shaped the analytical framework across the analysis window. CAGRs derived from patient volume projections by treatment line and pricing tier assumptions. Forecast inputs incorporated vector manufacturing capacity expansion timelines and newborn screening program penetration rates.
Several conditions sit outside the modeled scope, including long-term gene therapy durability data beyond fifteen-year surveillance commitments and regulatory framework evolution for allogeneic transplant substitution. Forecasts reflect assumptions regarding payer willingness to shift from chronic pharmacologic spending. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Blood Disorder Therapeutics Market
Hematology
Congenital Amegakaryocytic Thrombocytopenia (CAMT) Market
Hematology
Bone Marrow Transplant Market
Hematology
Warm Autoimmune Hemolytic Anemia Market
Hematology
Graft Versus Host Disease (Gvhd) Treatment Market
Hematology
Rare Hematology Market
Hematology
Multiple Myeloma Therapeutics Market
Hematology
Patient Blood Management Market
Hematology
Mantle Cell Lymphoma Treatment Market
Hematology
Global Hematopoietic Stem Cell Transplantation Market
Hematology
Warm Autoimmune Hemolytic Anemia (WAIHA) Treatment Market
Hematology
Hematologic Malignancies Market
Hematology
Thrombocytopenia Treatment Market
Hematology
Acute Myeloid Leukemia Treatment Market
Hematology
Erythropoietic Protoporphyria (EPP) Treatment Market
Hematology
Hematology Analyzers Market