
 Manure Separator Market | 2026-2036
Manure Separator Market Size, Share, and Industry Trends Forecast 2026-2036
Manure Separator Market Analytics
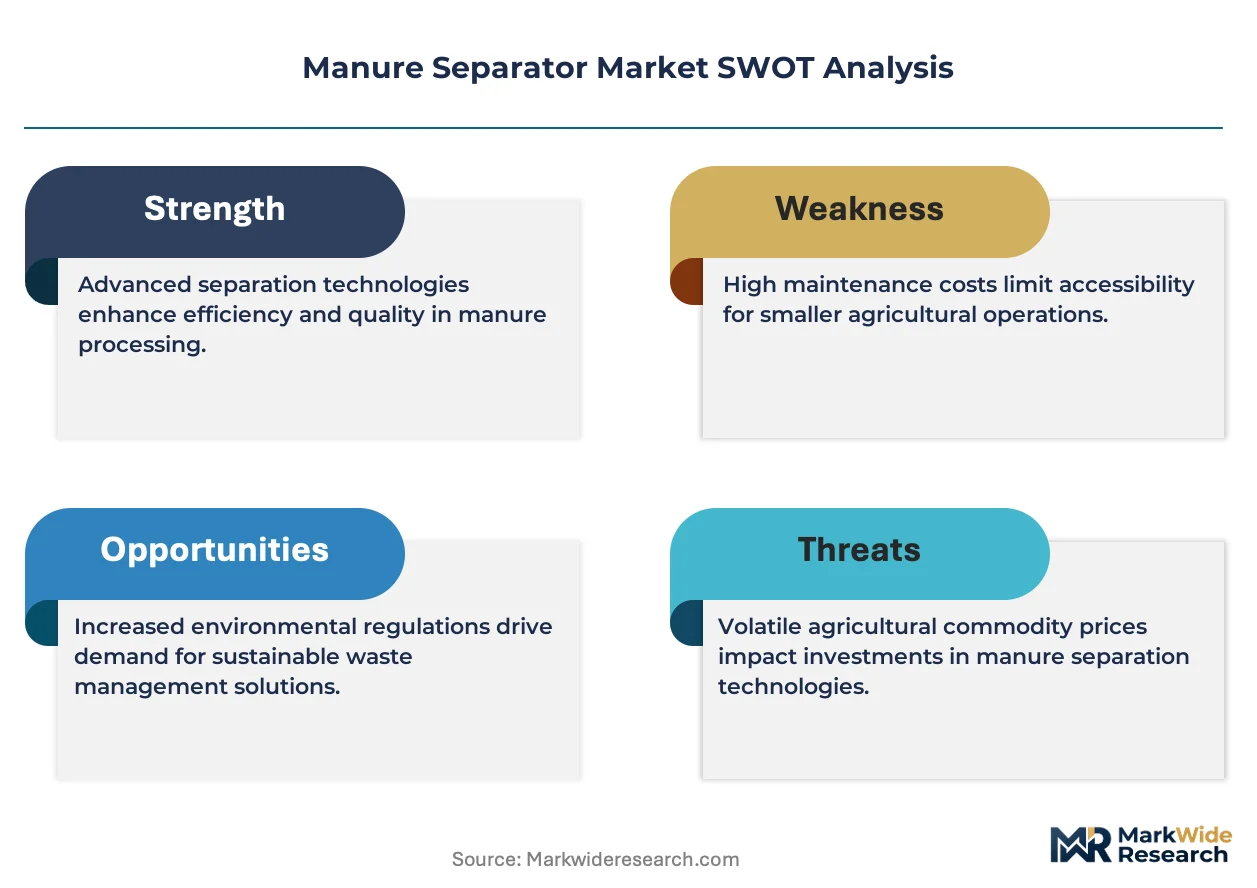
Skilled technician availability across rural dairy regions is bifurcating the competitive landscape between full-service providers and equipment-only vendors. GEA Group leverages its global service footprint to sustain long-term contracts with large integrated operations. Bauer Group anchors its position through specialized screw press engineering for high-fiber manure streams. Daritech competes aggressively on upfront system cost for mid-sized herd installations in the Great Lakes corridor.
A manure separator is a solids-liquid processing unit that applies mechanical force—typically via screw press, centrifugal, or belt-driven mechanisms—to extract fibrous organic matter from livestock effluent, producing stackable solids and reduced-volume liquid fractions for storage or land application. The equipment serves the primary industrial purpose of enabling farms to comply with nutrient management regulations while generating saleable compost or bedding material. Mechanical separators occupy the mature volume tier where replacement cycles drive recurring revenue, while centrifugal systems command premium positioning in biogas pre-treatment applications where fine solids removal determines digester efficiency. Belt separators are gaining ground in poultry operations where lower moisture feedstocks reduce energy intensity relative to hydraulic alternatives.
EPA enforcement of Clean Water Act Concentrated Animal Feeding Operation permits is accelerating separator adoption among dairies above one thousand head, while USDA Environmental Quality Incentives Program cost-share funding shapes equipment specifications through eligible practice standards. ISO 14001-aligned environmental management systems increasingly gate supplier qualification for corporate-backed farm networks. Stakeholders must weigh capital deployment timing against evolving state-level phosphorus runoff rules and the pace of biogas infrastructure buildout.
Market Dynamics
EPA nutrient management enforcement is compressing replacement cycles for mechanical separators across the upper Midwest, forcing dairies above one thousand head to treat equipment procurement as compliance infrastructure rather than discretionary capital.
Growth Catalysts
- Clean Water Act CAFO permits:EPA enforcement is mandating solids separation for dairies above regulatory thresholds, converting voluntary adoption into permit compliance across Wisconsin, Minnesota, and Iowa.
- Screw press automation:Labor-scarce operations are specifying self-cleaning screw press systems that reduce operator intervention from four hours to thirty minutes per day.
- USDA EQIP cost-share:The Environmental Quality Incentives Program covers up to seventy-five percent of eligible separator costs, lowering effective capital barriers for mid-sized herd operators.
Market Restraints
- Stainless steel input volatility:Separator fabrication depends on grade 304 and 316 stainless supply chains concentrated in Chinese and Indonesian nickel processing.
- Rural technician scarcity:Service networks for centrifugal systems require specialized hydraulic expertise unavailable outside metropolitan dairy engineering clusters.
- Phosphorus runoff rule fragmentation:State-level nutrient management standards in Vermont, New York, and Pennsylvania create specification conflicts that complicate manufacturer platform standardization.
Strategic Opportunities
- Biogas pre-treatment integration:Centrifugal separators paired with anaerobic digesters are opening premium positioning in California and New York where renewable natural gas offtake contracts reward fine solids removal efficiency.
- Poultry belt separator penetration:Lower-moisture layer manure in the Southeast is creating addressable volume for belt-driven systems previously confined to European broiler operations.
- ISO 14001 supplier qualification:Corporate-backed farm networks are gating vendor access through environmental management system certification, favoring full-service providers with documented audit trails.
Industry Challenges
- Electrohydraulic technician shortage:Centrifugal separator maintenance requires skills at the intersection of mechanical drive systems and programmable logic controllers that agricultural vocational programs no longer produce.
- Legacy lagoon retrofit complexity:Existing storage infrastructure in the Great Lakes corridor was engineered for unseparated effluent, forcing expensive civil work to accommodate reduced liquid volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manure Separator Market |
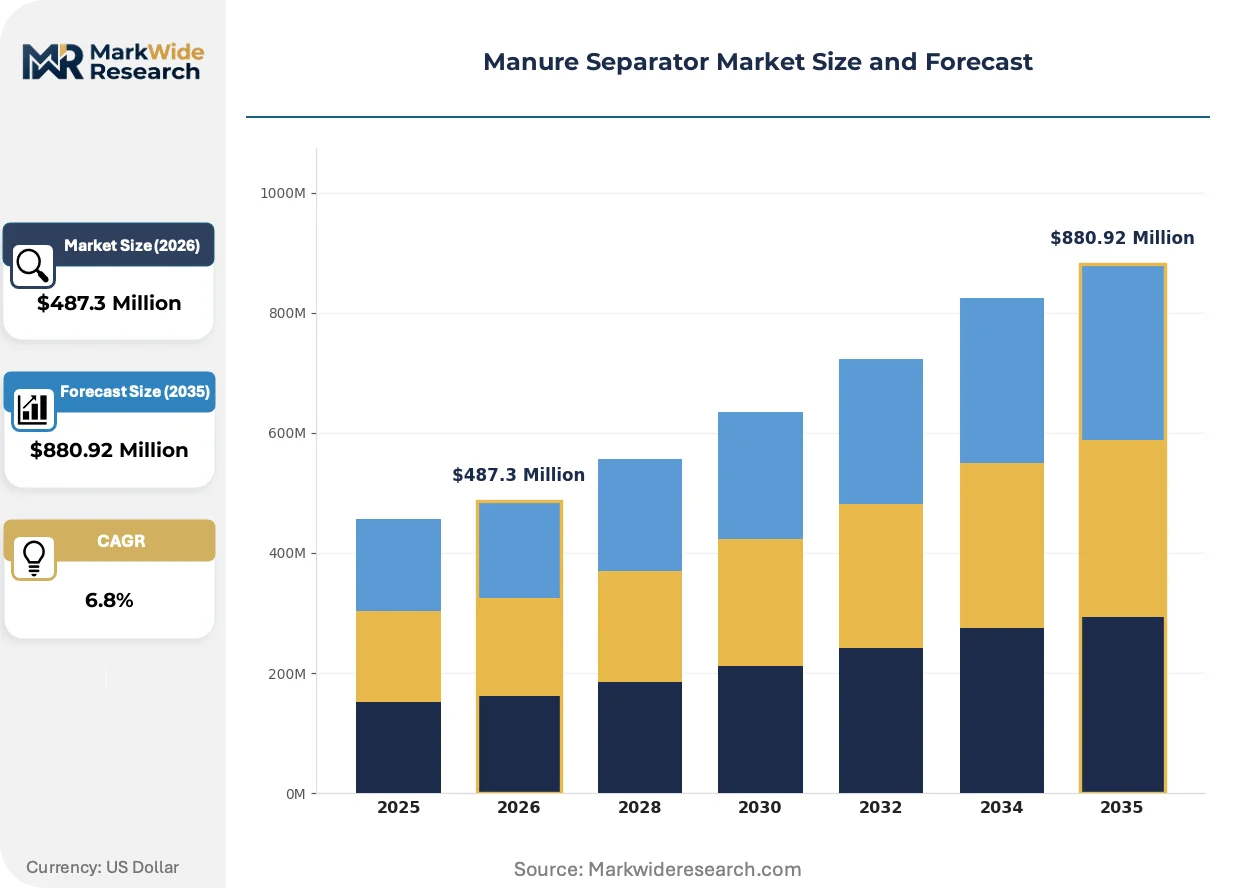
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Separator, Centrifugal Separator, Belt Separator, Gravity Separator End User: Dairy Farms, Poultry Farms, Swine Operations, Biogas Plants Application: Nutrient Recovery, Waste Management, Composting, Irrigation Technology: Rotary Technology, Hydraulic Technology, Screw Press Technology, Filtration Technology |
| Companies Covered | GEA Group, Bauer Group, Daritech, DeLaval, Patz Corporation, CRI-MAN SpA, McLanahan, Vogelsang GmbH & Co. KG, FAN Separator GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manure Separator Market Evolving Landscape
Automation and regulatory precision are converging to transform manure separation from mechanical commodity to integrated environmental compliance infrastructure, with implications for equipment specification, service contracting, and supplier qualification protocols.
Advanced screw press systems with integrated torque sensing and automated screen cleaning are decomposing the historical trade-off between fiber capture efficiency and operator labor requirements. Dairies in labor-constrained regions of Wisconsin and Minnesota are specifying these platforms for twenty-four-hour unmanned operation. The technology is decomposing price-based competition among equipment-only vendors by embedding predictive maintenance contracts that lock in decade-long service relationships.
EPA's renewed enforcement of Concentrated Animal Feeding Operation permits is tightening discharge monitoring requirements for phosphorus and nitrogen loading. The agency's 2023 compliance initiative has triggered permit revocation threats against non-compliant facilities in the Chesapeake Bay watershed. Large integrated operations are responding by specifying centrifugal separators with real-time solids concentration feedback loops that generate auditable compliance documentation.
After-sales service unbundling is fragmenting traditional full-service contracts across the upper Midwest. Mid-sized dairies in Michigan and Ohio are procuring equipment through agricultural cooperatives while sourcing maintenance through independent hydraulic technicians found via digital platforms. This pattern is most visible in counties where dealer service territories overlap and cooperative buying groups have achieved sufficient scale to negotiate direct manufacturer pricing.
Manure Separator Market Segmentation
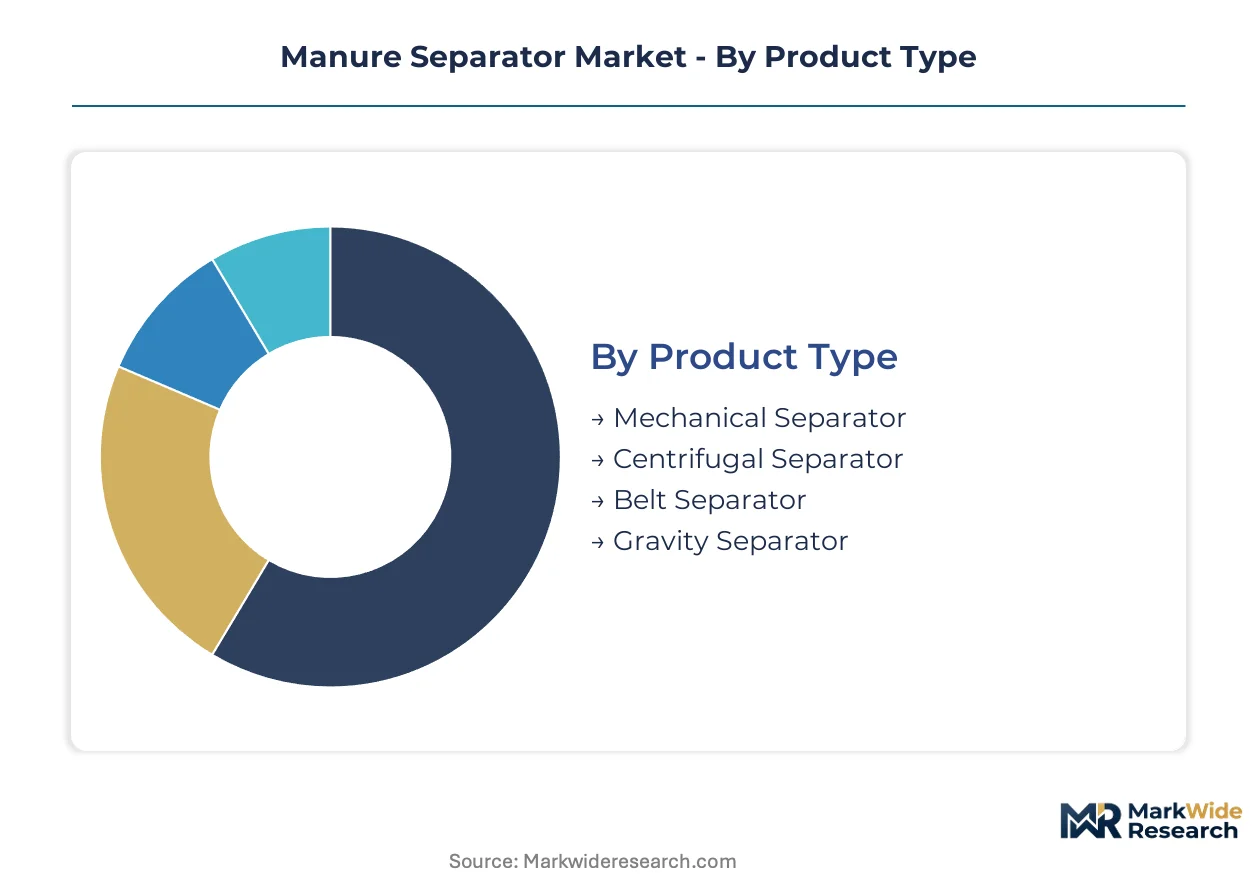
Technology choice and end-use application determine capital recovery timelines and service contract structures across manure separator procurement. Equipment specification varies sharply by livestock type, regional labor availability, and nutrient management compliance intensity.
Product Type:
Margin pools concentrate in centrifugal systems for biogas pre-treatment, while mechanical separators generate recurring replacement revenue at volume scale.
- Mechanical Separator:Screw press and screen-based units process high-fiber dairy manure through rotating augers that compress solids against perforated cylinders. Demand concentrates in Wisconsin and Minnesota dairies above one thousand head where USDA EQIP cost-share funding covers up to seventy-five percent of capital costs, though stainless steel input volatility squeezes fabrication margins.
- Centrifugal Separator:High-speed rotational force separates fine solids from liquid fractions, achieving phosphorus capture rates critical for EPA permit compliance. California and New York biogas facilities specify these systems where renewable natural gas offtake contracts reward pre-treatment efficiency, creating premium positioning despite electrohydraulic technician scarcity.
- Belt Separator:Continuous mesh belts dewater lower-moisture poultry manure with reduced energy intensity versus hydraulic alternatives.
- Gravity Separator:Passive settling tanks separate solids through density differentiation without mechanical force, serving small-scale operations with minimal operator requirements.
Mechanical separators hold installed capacity across the upper Midwest. Centrifugal separators are rotating up the share rankings in biogas-integrated operations.
End User:
Customer type shapes specification complexity and service contract duration, with large integrated operations demanding predictive maintenance platforms.
- Dairy Farms:Concentrated animal feeding operations above regulatory thresholds deploy screw press automation to reduce daily operator intervention from four hours to thirty minutes. Tightening EPA nutrient management enforcement across Iowa, Minnesota, and Wisconsin treats equipment procurement as compliance infrastructure rather than discretionary capital.
- Biogas Plants:Anaerobic digester operators require fine solids removal to protect digester biology and maximize methane yield. Centrifugal pre-treatment systems in California and New York command premium positioning where renewable natural gas offtake agreements create returns on efficiency documentation.
- Poultry Farms:Layer and broiler operations in the Southeast generate lower-moisture manure suited to belt separator energy profiles.
- Swine Operations:North Carolina and Iowa hog farms face distinct phosphorus runoff constraints that influence separator specification and lagoon retrofit requirements.
Dairy farms anchor current installed base. Biogas plants are climbing the fastest as renewable natural gas infrastructure expands.
Application:
Application focus determines regulatory documentation requirements and revenue model structure across equipment and service contracts.
- Nutrient Recovery:Phosphorus and nitrogen capture systems generate compliance documentation for EPA discharge permits while producing saleable fertilizer products. Chesapeake Bay watershed facilities specify real-time solids concentration feedback loops following permit revocation threats.
- Waste Management:Volume reduction for storage and land application dominates mid-sized herd procurement where legacy lagoon infrastructure requires expensive civil retrofit to accommodate separated liquid fractions.
- Composting:Fiber-dense solids output serves bedding and compost markets with stackable material specifications.
- Irrigation:Reduced-solids liquid fractions enable precision application equipment compatibility and reduced nozzle clogging.
Waste management holds historical application share. Nutrient recovery is gaining share fastest under intensifying EPA enforcement.
Technology:
Technology selection trades labor substitution against capital intensity and maintenance complexity across rural service network availability.
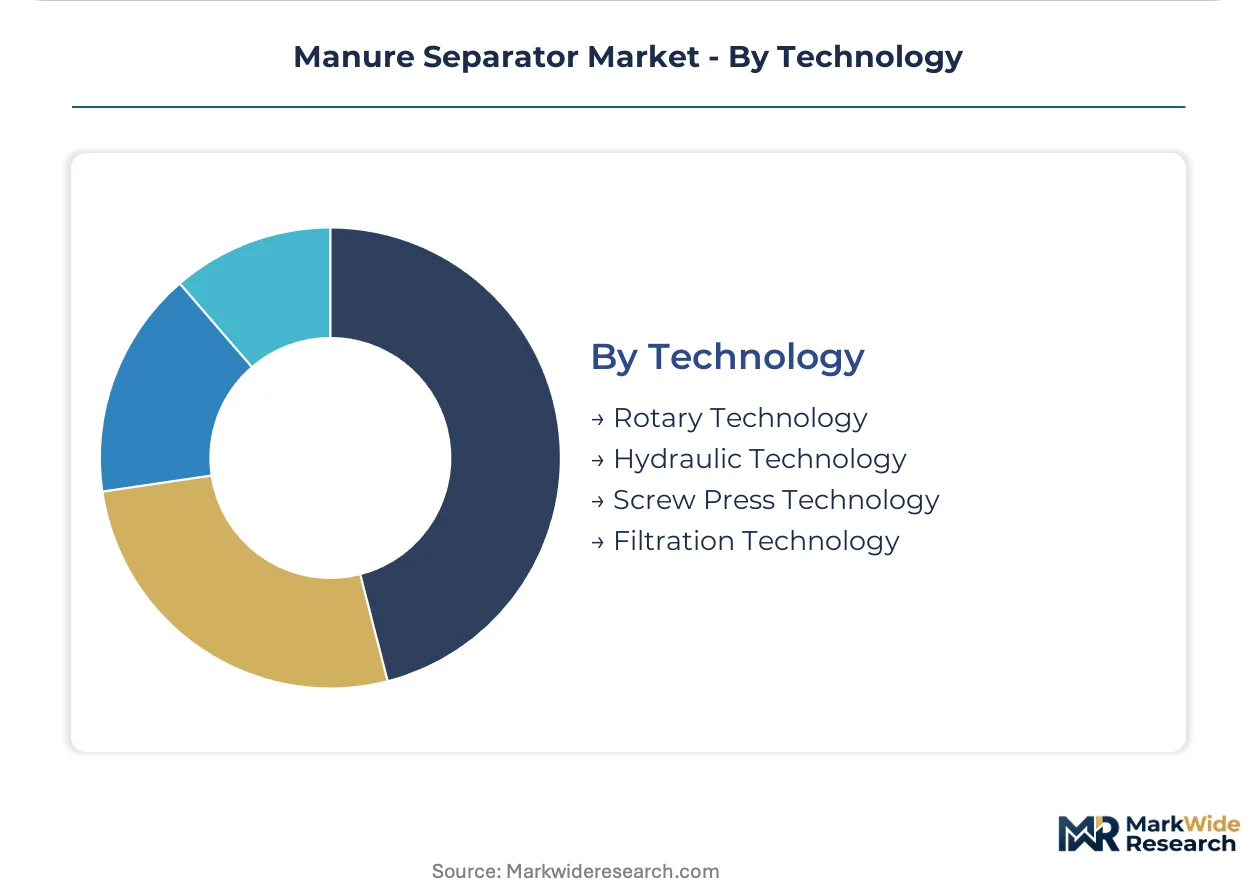
- Screw Press Technology:Self-cleaning auger systems with integrated torque sensing enable twenty-four-hour unmanned operation in labor-constrained Wisconsin and Minnesota dairy regions. Predictive maintenance contracts embed decade-long service relationships, decomposing price-based competition among equipment-only vendors.
- Rotary Technology:Drum-style separators process high-throughput manure streams with continuous screen cleaning mechanisms. Large integrated operations specify these platforms where throughput requirements exceed screw press capacity limits.
- Hydraulic Technology:Pressure-driven separation systems serve applications requiring precise moisture content control in final solids output.
- Filtration Technology:Membrane and screen-based fine filtration targets biogas pre-treatment where digester protection demands sub-millimeter solids removal.
Screw press technology holds installed capacity leadership. Rotary technology is expanding most quickly in large-scale integrated operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manure separator deployment patterns diverge sharply between North American dairy-intensive regions and European biogas corridors. The United States concentrates screw press installations for CAFO compliance, while Germany and the Netherlands prioritize centrifugal systems for anaerobic digester integration.
United States
Dairy operations across Wisconsin and Minnesota drive mechanical separator demand as EPA CAFO enforcement tightens discharge permits. The USDA Environmental Quality Incentives Program covers up to seventy-five percent of eligible equipment costs for mid-sized herds. The Great Lakes corridor anchors installation activity where legacy lagoon retrofits force civil engineering coordination.
Germany
Biogas plant operators specify centrifugal pre-treatment systems to maximize methane yield and protect digester biology. The country's national environmental regulator enforces strict nutrient management standards under the Fertilizer Ordinance. Bavaria's agricultural cooperatives cluster procurement power for technology-integrated service contracts.
Netherlands
Intensive livestock operations face phosphorus runoff constraints that mandate fine solids capture for land application permits. The country's national environmental agency enforces manure surplus regulations that prohibit unprocessed effluent spreading. The Gelderland province concentrates belt separator trials for poultry layer operations.
Canada
Dairy farms in Ontario and Quebec scale separator installations to meet provincial nutrient management plan requirements. Health Canada and PMRA coordinate agricultural water quality standards with provincial environmental ministries. The St. Lawrence Valley corridor sees cooperative buying groups negotiate direct manufacturer pricing for mid-sized herd equipment.
China
Large-scale pig farming provinces deploy gravity and mechanical separators to address water pollution from concentrated animal operations. The Ministry of Ecology and Environment enforces discharge standards under the Water Pollution Prevention and Control Law. Sichuan's livestock clusters trial automated screw press systems for unmanned operation in labor-scarce regions.
Manure Separator Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the manure separator market. Full-service providers with global service footprints capture long-term contracts from large integrated operations, while equipment-only vendors compete on upfront system cost for mid-sized installations. Two strategic archetypes dominate: diversified agricultural technology conglomerates with captive distribution networks, and specialized engineering firms with deep screw press or centrifugal expertise. Competitive moves concentrate on predictive maintenance contract bundling and biogas pre-treatment technology licensing.
Within the full-service tier, GEA Group and DeLaval represent integrated agricultural technology providers with established service infrastructures. Bauer Group and FAN Separator GmbH exemplify specialized European engineering firms with concentrated expertise in mechanical separation technologies. Daritech occupies a position among North American equipment specialists targeting cost-sensitive mid-market dairy operations. These three archetypes—integrated conglomerate, specialized European engineer, and regional cost competitor—structure competitive dynamics across procurement segments.
| Leading Market Players |
|---|
| GEA Group |
| Bauer Group |
| Daritech |
| DeLaval |
| Patz Corporation |
| CRI-MAN SpA |
| McLanahan |
| Vogelsang GmbH & Co. KG |
| FAN Separator GmbH |
| Others |
Value Network & Pricing Analysis
Grade 316 stainless steel displacing grade 304 in centrifugal separator fabrication simultaneously redraws procurement geography toward Indonesian nickel processors and compresses margin structures for European fabricators serving biogas pre-treatment markets.
Pricing Analysis
Long-term service contracts with predictive maintenance bundling dominate the pricing architecture for large integrated dairy operations, while mid-sized herds transact through equipment-only spot purchases shaped by USDA EQIP cost-share eligibility. Price differentiation rests on after-sales service depth and ISO 14001 certification status, with full-service providers commanding premiums against equipment-only vendors. Cost compression in the mechanical separator tier intensifies as Chinese fabrication capacity expands, though electrohydraulic technician scarcity protects centrifugal system margins. Cooperative buying groups in the Great Lakes corridor exhibit highest price sensitivity; California biogas operators show lowest sensitivity due to renewable natural gas offtake contract economics.
Supply Chain Analysis
Inventory buffers for precision-machined screw press components stretch to sixteen weeks as rural equipment dealers carry minimal finished goods stock. Fabrication concentrates in Germany, China, and the upper Midwest United States, with grade 304 and 316 stainless steel supply chains anchored in Indonesian and Chinese nickel processing. Raw material dependencies include nickel alloys, precision bearings, and programmable logic controller modules. Single-source vulnerability in hydraulic drive systems creates exposure for centrifugal separator OEMs. Distribution runs through agricultural equipment dealer networks and direct manufacturer relationships with cooperative buying groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of electrohydraulic technicians capable of maintaining centrifugal separator systems constrains expansion velocity and creates defensive moats for incumbents with captive training pipelines.
For Market Incumbents: Consolidate service network density in Wisconsin and Minnesota through acquisition of independent hydraulic technicians, locking in predictive maintenance relationships before cooperative buying groups unbundle after-sales contracts. Vertical integration into stainless steel fabrication hedges nickel price volatility threatening screw press margins. Prioritize ISO 14001 certification investment to gate corporate-backed farm network procurement. For New Entrants and Emerging Players: After-sales service unbundling in Michigan and Ohio counties with overlapping dealer territories creates white-space for platform-based technician dispatch models targeting mid-sized dairies. Poultry belt separator penetration in the Southeast offers lowest competitive intensity versus saturated dairy screw press markets. Pursue direct manufacturer pricing agreements with agricultural cooperatives that have achieved sufficient procurement scale. For Investors and Strategic Acquirers: EPA's renewed CAFO permit enforcement reshapes the acquisition landscape toward centrifugal pre-treatment specialists with documented biogas integration capabilities. Five-to-ten year viability favors full-service providers with environmental management system certification and captive technician training infrastructure. Monitor renewable natural gas offtake contract velocity in California and New York as inflection signal for premium separator demand.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Contract Bundling | GEA Group and Bauer Group embed decade-long service relationships that decompose price-based competition. |
| Biogas Pre-Treatment Technology Licensing | Centrifugal separator IP partnerships unlock California and New York renewable natural gas infrastructure buildout. |
| ISO 14001 Supplier Qualification Investment | Environmental management system certification gates access to corporate-backed farm network procurement channels. |
| Screw Press Automation Development | Self-cleaning auger systems with torque sensing reduce operator intervention from four hours to thirty minutes daily. |
| Cooperative Buying Group Direct Pricing | Mid-sized herds in Michigan and Ohio negotiate manufacturer-direct contracts bypassing traditional dealer markups. |
Research Methodology
Operator-level perspectives from dairy farm managers, biogas plant engineers, agricultural cooperative procurement officers, and aftermarket service technicians anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with equipment specification decision-makers and secondary validation through EPA enforcement action databases, USDA EQIP program documentation, and state-level nutrient management rule filings. Bottom-up installation data triangulated against top-down market sizing derived from stainless steel trade flows and agricultural equipment import records.
Sensitivity analysis across stainless steel price volatility scenarios, EPA enforcement intensity assumptions, and biogas infrastructure buildout pacing shaped the projection framework. Segmentation dimensions modeled include technology type, end-user category, application focus, and regional regulatory cluster. CAGRs were derived through regression analysis of historical equipment procurement patterns against nutrient management policy implementation timelines. Forecast inputs incorporated USDA cost-share funding availability and renewable natural gas offtake contract formation rates.
Forecasts assume regulatory continuity in EPA CAFO permit enforcement and state-level phosphorus runoff standards; material policy shifts would require re-modeling. Stainless supply disruption, electrohydraulic technician training program expansion, or biogas tax credit modification represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Global Precision Harvesting Market
Agricultural Equipment
Cordless Sprayer Market
Agricultural Equipment
Grain Mill Grinder Market
Agricultural Equipment
Smart Egg Incubators Market
Agricultural Equipment
Tree Trimmers Market
Agricultural Equipment
Green Beans Harvester Market
Agricultural Equipment
Grafting Knives Market
Agricultural Equipment
Agriculture Container and Tank Cleaning Market
Agricultural Equipment
Heavy Tooth Drag Harrows Market
Agricultural Equipment
Battery Powered Cultivators Market
Agricultural Equipment
Feed Mixer Market
Agricultural Equipment
Agricultural Rake Market
Agricultural Equipment
Aquarium Pumps and Filters Market
Agricultural Equipment
Wheelbarrow Market
Agricultural Equipment
Agricultural Pumps Market
Agricultural Equipment
Global Rice Transplanter Market