
 Israel Agriculture Market | 2026-2036
Israel Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Israel Agriculture Market Insights
The Negev Desert is reconfiguring Israel's agricultural production map through solar-powered greenhouse complexes and brackish-water desalination for irrigation. Netafim leverages its drip irrigation heritage to anchor premium system sales across arid zones. CropX competes through soil sensor analytics that reduce water application rates. ICL Group sustains phosphate fertilizer supply chains from its Dead Sea extraction operations.
Israel agriculture encompasses crop cultivation, input manufacturing, and equipment deployment across controlled-environment and open-field systems, with drip irrigation achieving 90-95% water-use efficiency versus 50-70% for conventional flood methods. The sector serves domestic food security, export markets, and agritech licensing revenue streams. Precision Agriculture leads technology adoption as satellite imagery and IoT sensors displace visual crop scouting across cooperative farms. Hydroponics occupies the fastest-expanding production segment, with vertical farms near Tel Aviv supplying herbs to restaurant distributors year-round. Equipment margins concentrate in automated harvesting robotics, where mechanical-labor substitution commands premium pricing from large vegetable cooperatives.
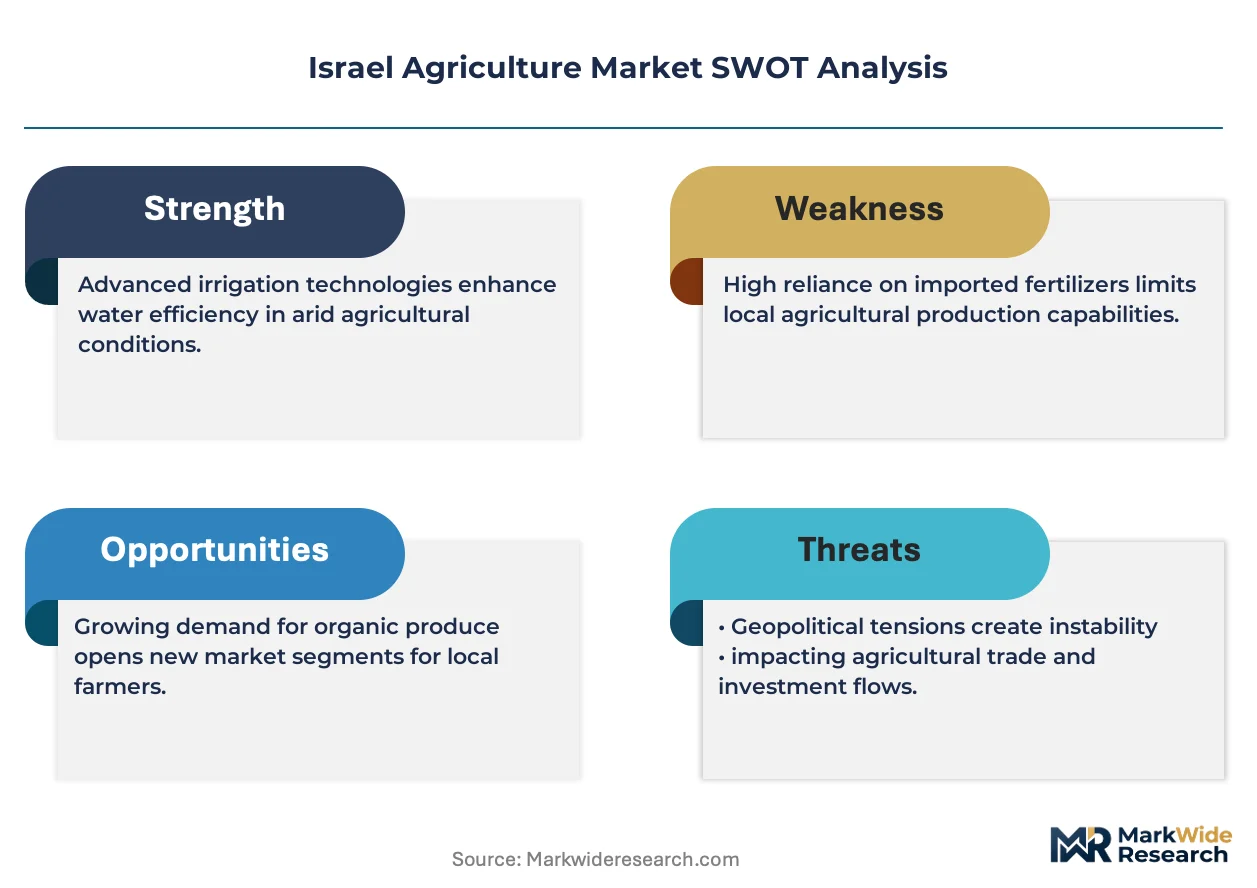
Israel's Ministry of Agriculture and Rural Development sets crop rotation standards and pesticide residue limits, while the Israel Standards Institute certifies equipment safety and water quality for food-contact irrigation. These frameworks shape import substitution patterns, as foreign equipment must undergo local adaptation testing before commercial deployment. Stakeholders must monitor groundwater salinity thresholds and wastewater reuse permits, as regulatory tightening on aquifer protection will determine which production zones retain expansion licenses.
Market Dynamics
Israel's agriculture sector confronts a structural squeeze between the Israel Water Authority's tightening drip irrigation quotas and the export-driven imperative for precision-harvested produce. This tension forces capital allocation toward sensor-based efficiency tools and automated greenhouse systems.
Growth Catalysts
- Desalinated brackish water infrastructure:The national water authority's quota system pushes Arava Valley farms toward closed-loop hydroponic systems that maximize output per cubic meter.
- European retail chain procurement standards:Northern European supermarket groups now mandate residue traceability and harvest-date precision, favoring Israeli greenhouse clusters with integrated logistics.
- Netafim's localized R&D partnerships:Drip irrigation heritage firms collaborate with kibbutz cooperatives to field-test sensor-integrated fertigation, accelerating adoption curves.
Market Restraints
- Phosphate input cost volatility:ICL Group's Dead Sea extraction operations face energy price swings that transmit directly into fertilizer pricing for vegetable cooperatives.
- Groundwater salinity thresholds:The Ministry of Agriculture and Rural Development's aquifer protection rules threaten expansion licenses in the northern Negev production belt.
- Mechanical harvesting substitution limits:Soft-fruit robotics remain technically immature, trapping labor-intensive segments in wage-cost spirals.
Strategic Opportunities
- Jordan Valley wastewater reuse permits:Regulatory tightening on freshwater allocation creates first-mover advantage for farms securing treated effluent contracts.
- Tel Aviv vertical farm channel expansion:Restaurant distributor consolidation opens year-round herb supply contracts previously served by seasonal imports.
- Solar-greenhouse convergence:Photovoltaic canopy integration over desert greenhouses enables net-positive energy production while shading crops.
Industry Challenges
- Sensor-legacy system integration:Kibbutz cooperatives with decades-old flood irrigation infrastructure face capex barriers to retrofitting IoT analytics layers.
- Agritech talent pipeline gaps:The shortage of irrigation engineers trained in both hydrology and data science slows deployment of precision agriculture platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel Agriculture Market |
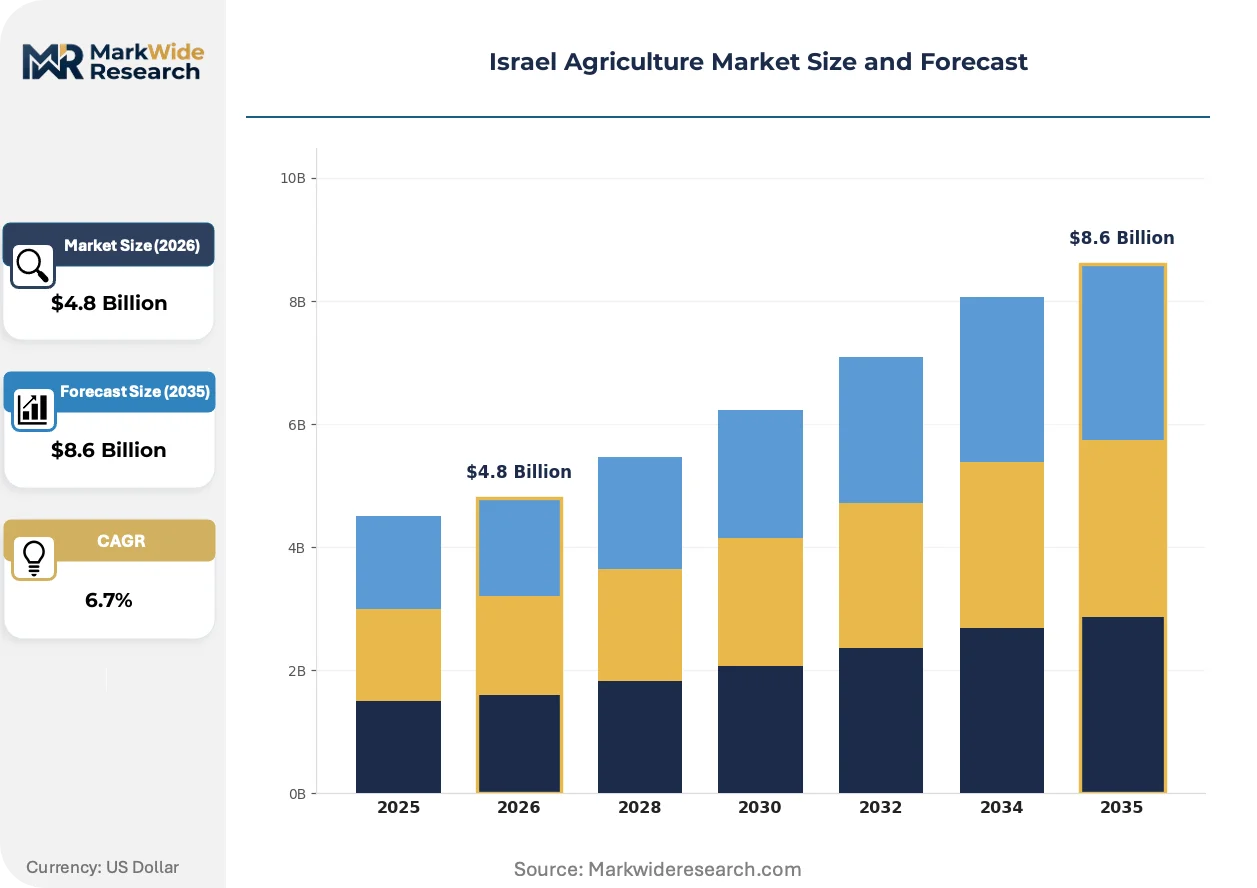
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crops, Pesticides, Fertilizers, Equipment End Use Industry: Organic Farming, Greenhouse, Aquaculture, Horticulture Technology: Precision Agriculture, Hydroponics, Irrigation Systems, Biotechnology Distribution Channel: Retail, Wholesale, Direct Sales, E-commerce |
| Companies Covered | CropX, SupPlant, ICL Group, Taranis, Prospera, Netafim, BioBee, Groundwork BioAg, ADAMA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel Agriculture Market Trends and Innovations
Israeli agriculture is pivoting from hardware-centric irrigation exports toward integrated data-services platforms. This shift reconfigures revenue models and competitive moats across the sector.
Computer vision systems for crop stress detection is hybridizing spectral imaging with soil moisture telemetry. Large vegetable cooperatives in the Arava Valley deploy these platforms to automate harvest-timing decisions. The technology compresses the gap between agronomic insight and operational response, reducing water waste from delayed irrigation adjustments.
The Israel Standards Institute's certification protocols for food-contact irrigation equipment are tightening testing timelines for imported machinery. Foreign equipment vendors must now complete local adaptation trials before commercial deployment. This regulatory friction favors domestic manufacturers with established testing relationships and accelerates import substitution in the precision-harvesting segment.
European retail procurement teams now unbundle after-sales agronomic support from equipment purchases, treating irrigation system vendors as ongoing service providers rather than one-time suppliers. Tel Aviv-based greenhouse operators lead this shift, demanding subscription-based analytics rather than capital-heavy hardware deals. The Negev Desert solar-greenhouse clusters represent the most visible geography where outcome-based contracts displace traditional equipment sales.
Israel Agriculture Market Segmentation
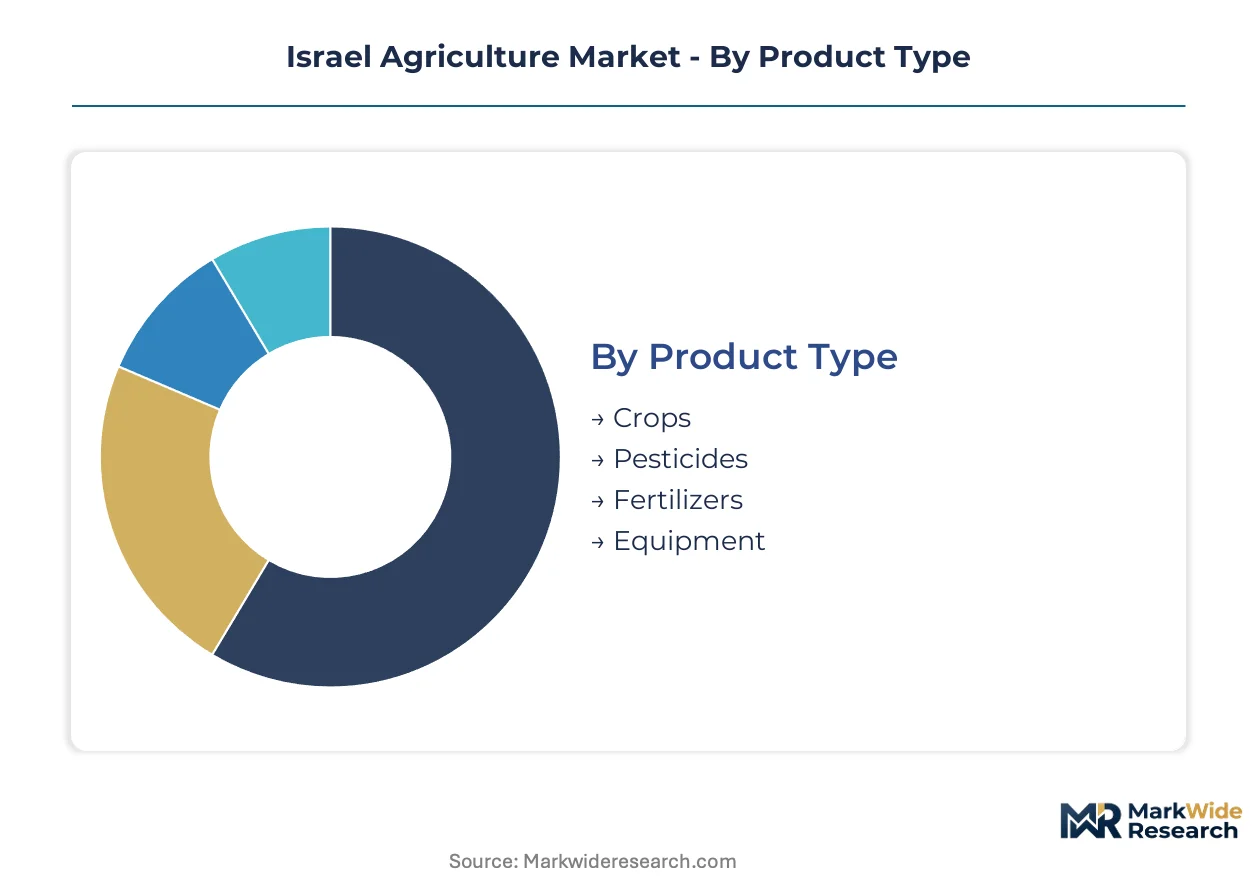
Segmentation in Israeli agriculture reveals how capital allocation splits between asset-heavy infrastructure and recurring input purchases. Equipment and technology cycles differ sharply from consumable fertilizers and pesticides, shaping vendor cash flow profiles and customer retention strategies.
Product Type:
Crops turn over fastest as harvest cycles complete, while equipment amortizes across multiple seasons and technology refresh rates fall somewhere between.
- Crops:Fresh vegetables and fruits dominate export revenue to Northern European retail chains. Arava Valley greenhouse clusters supply out-of-season tomatoes and peppers under residue-traceability contracts mandated by supermarket procurement teams.
- Pesticides:Application frequency tracks pest pressure cycles in the Jordan Valley and coastal plains. The Ministry of Agriculture and Rural Development's tightening residue limits push cooperatives toward biological alternatives with shorter re-entry intervals.
- Fertilizers:Phosphate-based products from Dead Sea extraction operations anchor domestic supply. ICL Group's energy-cost exposure transmits directly into vegetable cooperative input budgets.
- Equipment:Drip irrigation systems and automated harvesting robotics carry the longest replacement cycles. Netafim's sensor-integrated fertigation platforms command premium pricing from large kibbutz operations seeking mechanical-labor substitution.
Crops anchor the volume base while equipment gains share at the steepest rate as precision-harvesting mandates intensify.
End Use Industry:
Capital intensity separates controlled-environment systems from open-field operations, with each segment demanding distinct technology stacks and regulatory compliance pathways.
- Greenhouse:Desert complexes in the Negev and Arava deploy solar-powered climate control and brackish-water desalination. These facilities supply year-round herbs and vegetables to Tel Aviv restaurant distributors under fixed-volume contracts.
- Organic Farming:Certification requirements from the Israel Standards Institute restrict synthetic input use. Northern Negev operations face groundwater salinity thresholds that threaten expansion licenses under aquifer protection rules.
- Horticulture:Ornamental and nursery stock production concentrates in the coastal plain. Shorter production cycles than tree crops allow faster response to European export demand shifts.
- Aquaculture:Recirculating systems in the Jordan Valley and Eilat region produce sea bream and sea bass. Wastewater reuse permits create first-mover advantage as freshwater allocation tightens.
Greenhouse operations command the highest capital per hectare while organic farming expands most quickly on export price premiums.
Technology:
Adoption velocity varies by data infrastructure maturity, with sensor networks requiring more customer-side integration than standalone hardware.
- Precision Agriculture:Satellite imagery and IoT soil sensors displace visual crop scouting across cooperative farms. CropX competes through analytics platforms that reduce water application rates in line with Israel Water Authority quotas.
- Irrigation Systems:Drip technology achieves 90-95% water-use efficiency versus 50-70% for legacy flood methods. Netafim's localized R&D partnerships with kibbutz cooperatives accelerate field-testing of sensor-integrated fertigation.
- Hydroponics:Closed-loop systems maximize output per cubic meter under quota constraints. Vertical farms near Tel Aviv supply herbs to restaurant distributors year-round, displacing seasonal imports.
- Biotechnology:Seed breeding and biological pest control products face extended regulatory timelines. The Ministry of Agriculture and Rural Development's crop rotation standards shape deployment patterns.
Irrigation systems generate the most recurring service revenue while hydroponics climbs the fastest on water-efficiency mandates.
Distribution Channel:
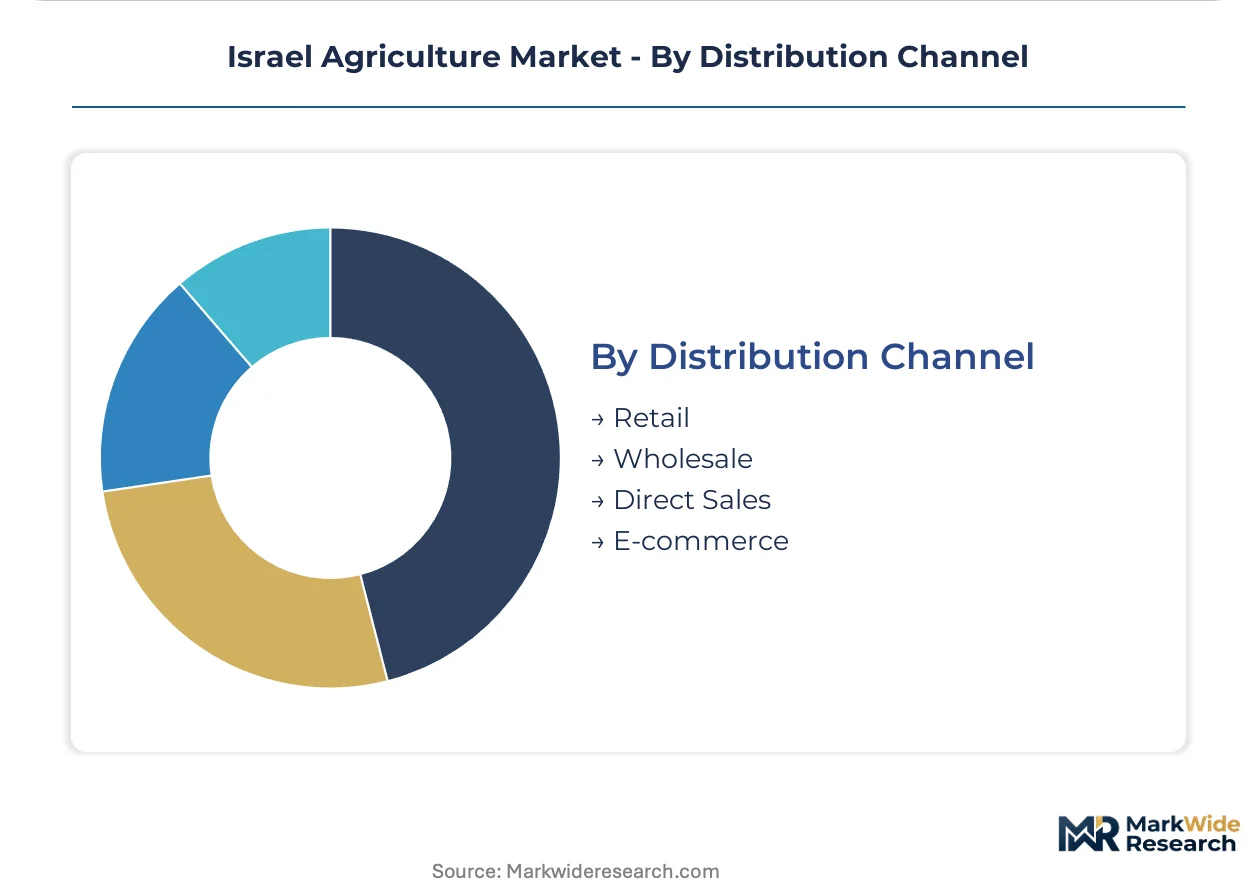
Customer scale and technical complexity determine channel selection, with large cooperatives bypassing intermediaries for direct manufacturer relationships.
- Direct Sales:Netafim and CropX deploy agronomic support teams to large vegetable cooperatives. Subscription-based analytics contracts displace traditional equipment sales in the Negev solar-greenhouse clusters.
- Wholesale:Input distributors serve mid-sized farms in the northern Negev and coastal plains. Phosphate fertilizer volumes from ICL Group move through established agricultural supply cooperatives.
- Retail:Garden centers and farm supply stores target smallholders and hobby operations. Pesticide and fertilizer SKUs concentrate here with shorter purchase cycles than capital equipment.
- E-commerce:Spare parts and consumables increasingly route through digital platforms. The Israel Standards Institute's certification delays for imported machinery limit equipment sales through this channel.
Direct sales capture the highest contract values while e-commerce expands most quickly on spare parts convenience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israel's agricultural output concentrates in five distinct production belts, each shaped by water access, export logistics, and regulatory boundaries. The Arava Valley and Negev Desert anchor high-value greenhouse exports, while the coastal plains and northern valleys sustain diversified crop rotations.
Arava Valley
Desert greenhouse clusters supply out-of-season tomatoes and peppers to Northern European retail chains under residue-traceability contracts. The Israel Water Authority's drip irrigation quotas push farms toward closed-loop hydroponic systems that maximize output per cubic meter. Eilat-area packing houses integrate directly with maritime cold-chain logistics for Rotterdam and Hamburg delivery windows.
Negev Desert
Solar-powered greenhouse complexes and brackish-water desalination plants reconfigure production economics in this zone. The Ministry of Agriculture and Rural Development's aquifer protection rules threaten expansion licenses where groundwater salinity thresholds approach regulatory limits. Beersheba-based cooperatives field-test sensor-integrated fertigation platforms with Netafim's localized R&D partnerships.
Jordan Valley
Wastewater reuse permits create first-mover advantage for farms securing treated effluent contracts as freshwater allocation tightens. Regulatory frameworks from the Israel Water Authority prioritize recycled water for agriculture over municipal or industrial use. Date palm plantations and vegetable cooperatives cluster near Kibbutzim with established tertiary treatment infrastructure.
Coastal Plain
Horticulture and nursery stock production concentrates here with shorter cycles than tree crops, enabling faster response to European export demand shifts. The Israel Standards Institute certifies equipment safety and water quality for food-contact irrigation, shaping import substitution patterns. Tel Aviv metropolitan vertical farms supply year-round herbs to restaurant distributors under fixed-volume contracts.
Northern Valleys
Organic farming operations expand on export price premiums, though certification requirements restrict synthetic input use. Groundwater salinity monitoring from the Ministry of Agriculture and Rural Development determines which production zones retain expansion licenses. Kibbutzim in the Hula Valley and Galilee region deploy precision agriculture platforms to automate harvest-timing decisions.
Israel Agriculture Market Competitive Landscape
Irrigation heritage specialists and precision analytics providers split the market between hardware-centric equipment sales and subscription-based data services. The vendor base clusters around three strategic archetypes: drip-irrigation incumbents with localized R&D partnerships, soil-sensor analytics competitors, and biological-input specialists. Dominant competitive moves include technology licensing agreements with kibbutz cooperatives and backward integration into captive fertilizer supply chains.
Within the irrigation-system tier, Netafim anchors premium positioning through sensor-integrated fertigation platforms. CropX and SupPlant occupy the analytics-provider segment, exemplifying the shift toward subscription-based soil-moisture telemetry. ICL Group represents the input-manufacturing archetype, sustaining phosphate supply chains from extraction operations.
| Leading Market Players |
|---|
| CropX |
| SupPlant |
| ICL Group |
| Taranis |
| Prospera |
| Netafim |
| BioBee |
| Groundwork BioAg |
| ADAMA |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Arava Valley greenhouse complexes is compressing supplier margins while amplifying pricing power for sensor-integrated fertigation vendors. The Israel Water Authority's drip irrigation quotas force capital-light cooperatives toward subscription-based efficiency tools, restructuring how equipment vendors capture value across the production belt.
Pricing Analysis
The Israel Standards Institute's certification protocols dictate the pricing tier structure for food-contact irrigation equipment across Israeli agriculture. Three-tier pricing structure across premium, standard, and economy levels separates Netafim's sensor-integrated platforms from mid-tier drip systems and basic flood infrastructure. Price differentiation hinges on certification grade and after-sales agronomic support bundling. Cost compression in standard-tier hardware is intensifying because European retail procurement teams now unbundle equipment from ongoing service contracts. Smallholder retail channels exhibit highest price sensitivity, while large kibbutz cooperatives prioritize outcome-based analytics subscriptions over capital expenditure minimization.
Supply Chain Analysis
Export-control regimes on precision sensor technology limit flows of advanced IoT components into Israeli agritech manufacturing. Supply concentration centers on China for microcontroller assemblies, Germany for spectral imaging sensors, and the United States for satellite data analytics platforms. Raw material dependencies include Dead Sea phosphate rock, desalination membrane polymers, and photovoltaic cells for solar-greenhouse integration. Single-source vulnerability runs through tertiary desalination membrane suppliers. Distribution runs through direct manufacturer relationships with large cooperatives, wholesale agricultural supply networks for mid-sized farms, and retail farm supply stores serving smallholders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Israeli agriculture is fragmenting into specialized service niches as European retail procurement standards diverge from domestic food security requirements. This demand-side polarization creates protected pockets for differentiated positioning.
For Market Incumbents: Entrench sensor-integrated platform dominance through backward integration into captive desalination infrastructure partnerships. Deepen kibbutz cooperative R&D lock-in with exclusive field-testing arrangements for brackish-water crop varieties. The emerging threat of Jordan Valley wastewater reuse permit holders gaining first-mover advantage in freshwater-constrained expansion zones demands preemptive capacity positioning in treated effluent treatment technology.
For New Entrants and Emerging Players: Establish a beachhead in Tel Aviv metropolitan vertical farm channels where restaurant distributor consolidation has displaced seasonal import suppliers. Target organic certification consulting and biological input supply to northern Negev operations facing groundwater salinity threshold enforcement. A direct-to-cooperative subscription model for harvest-timing analytics bypasses Netafim's established equipment financing relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across hydroponics and vertical farm sub-segments as modular system designs reduce per-hectare infrastructure requirements. Long-term viability favors platforms combining hardware deployment with recurring data service revenue over pure equipment manufacturers. Acquisition target archetypes include soil-sensor analytics specialists with proven water reduction metrics and biological pest control firms with shortened re-entry interval certifications. The signal to watch is Israel Water Authority quota tightening velocity, which accelerates subscription-model adoption curves.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Integrated Fertigation Platform Deployment | Netafim's localized R&D partnerships with kibbutz cooperatives accelerate adoption curves for precision-harvested crop supply. |
| Wastewater Reuse Permit Securement | Jordan Valley farms with treated effluent contracts gain expansion licenses as freshwater allocation tightens under Israel Water Authority rules. |
| Solar-Greenhouse Photovoltaic Integration | Negev Desert clusters achieve net-positive energy production while shading crops under Ministry of Agriculture aquifer protection frameworks. |
| Biological Input Certification Investment | Organic farming operations in northern valleys secure export price premiums through Israel Standards Institute residue compliance. |
| Vertical Farm Channel Expansion | Tel Aviv metropolitan herb suppliers displace seasonal imports through fixed-volume contracts with consolidated restaurant distributors. |
Research Methodology
Desk research of customs trade records, Israel Water Authority quota filings, and kibbutz cooperative annual reports preceded structured interviews with drip irrigation system engineers, agronomic data platform product managers, vegetable cooperative procurement directors, and Israel Standards Institute certification officers. Secondary validation drew from Ministry of Agriculture crop rotation databases, Dead Sea extraction operation energy cost disclosures, and European retail chain procurement requirement documentation. Bottom-up equipment shipment tracking and top-down agricultural output value estimates were triangulated against sensor deployment metrics.
Assumptions held fixed include Israel Water Authority quota enforcement intensity, European retail residue-traceability mandate stability, and Dead Sea phosphate extraction cost structures. Variables modeled across the projection horizon encompass hydroponics adoption velocity, solar-greenhouse photovoltaic integration rates, and wastewater reuse permit issuance timelines. Segmentation dimensions include product type, end-use industry, technology adoption tier, and distribution channel structure. CAGRs were derived from equipment replacement cycle analysis and input consumption intensity modeling. Industry-specific forecast inputs include brackish-water desalination capacity expansion schedules and kibbutz cooperative capital expenditure survey data.
Stress conditions across groundwater salinity threshold enforcement, European retail procurement standard acceleration, and phosphate energy cost volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and variable ranges. Material shifts in Israel Water Authority regulatory tightening velocity or European supermarket group consolidation patterns would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Plows Market
Agricultural Equipment
Wet Fertilizer Spreaders Market
Agricultural Equipment
Fishing Net Market
Agricultural Equipment
Cotton Picker Market
Agricultural Equipment
Belt Feeders Market
Agricultural Equipment
Commercial Grain Mill Market
Agricultural Equipment
Feller Buncher Market
Agricultural Equipment
Global Precision Harvesting Market
Agricultural Equipment
Heavy Tooth Drag Harrows Market
Agricultural Equipment
Global Rice Transplanter Market
Agricultural Equipment
Smart Rice Transplanter Market
Agricultural Equipment
United States Grain Storage Silos Market
Agricultural Equipment
Floating Covers Market
Agricultural Equipment
Bird Scarer and Repellent Market
Agricultural Equipment
Battery Powered Cultivators Market
Agricultural Equipment
Gardening Equipment Market