
 Cordless Sprayer Market | 2026-2036
Cordless Sprayer Market Size, Share, and Industry Trends Forecast 2026-2036
Cordless Sprayer Market Insights
Aftermarket battery replacement and accessory revenue is rewriting profit architecture for cordless sprayer incumbents. Graco leverages its industrial coating heritage to dominate professional-tier handheld distribution. Wagner sustains brand strength across North American home improvement retail channels. EGO Power anchors premium lithium-ion platform loyalty through interchangeable battery ecosystems.
A cordless sprayer is a portable, electrically powered fluid-dispensing device utilizing battery-driven piston or diaphragm pumps to atomize and project coatings, chemicals, or biological agents at pressures typically ranging from 40 to 500 PSI, designed for mobility without tethered power or compressed air supply. Handheld sprayers occupy the highest volume tier among product types, though backpack configurations capture expanding share in commercial groundskeeping. Lithium-ion batteries have displaced NiCad chemistry across power source segments due to energy density advantages and reduced memory effect degradation. Professional end users generate the most durable demand, while homeowner segments exhibit higher price sensitivity and shorter replacement intervals.
EPA pesticide application regulations and OSHA Hazard Communication Standards shape product labeling, operator training mandates, and chemical compatibility requirements for cordless sprayer manufacturers. CE marking under EU machinery directives governs electrical safety and electromagnetic compatibility for European market access. Stakeholders must monitor evolving battery transport regulations and chemical registration requirements as jurisdictions tighten environmental compliance frameworks.
Market Dynamics
Lithium-ion battery platform standardization is compressing replacement cycles and locking professional users into captive ecosystems. Municipal procurement departments now mandate cordless equipment for park maintenance contracts, while EPA emissions enforcement accelerates gasoline sprayer phase-outs across commercial landscaping fleets.
Growth Catalysts
- OSHA Hazard Communication Standards:Chemical exposure limits are forcing commercial operators to abandon engine-driven sprayers with higher fume emissions. Workplace safety audits now prioritize battery-powered alternatives.
- Interchangeable battery ecosystems:Professional crews standardize on single-platform tools to reduce field inventory. Shared power sources across mowers, blowers, and sprayers streamline logistics.
- Municipal park maintenance:Cities in Germany, Australia, and the United States are rewriting landscaping RFPs to exclude gasoline equipment. Noise ordinances in urban centers amplify this specification shift.
Market Restraints
- Lithium carbonate price volatility:Battery pack costs swing with commodity markets. Manufacturers absorb margin pressure or risk volume loss to gasoline alternatives.
- Single-source cell suppliers:Concentrated Asian cathode material production creates supply vulnerability. Geopolitical friction threatens just-in-time battery assembly.
- Runtime ceiling in high-pressure applications:Diaphragm pump loads drain packs faster than homeowner use cases. Professional users carry backup batteries, adding weight and cost.
Strategic Opportunities
- Indian commercial horticulture:Orchard and vineyard operators remain tethered to manual or engine sprayers. Battery platform education and dealer training can unlock this latent demand.
- CE marking convergence with machinery directives:Harmonized EU electrical safety standards reduce certification fragmentation. Compliant products gain automatic passporting across member states.
- Telematics-integrated fleet management:GPS-tracked sprayer pools with usage-based billing reshape municipal procurement. Equipment-as-a-service models displace capital purchase cycles.
Industry Challenges
- Certification timeline compression:EPA pesticide application equipment registration now overlaps with state-level chemical licensing. Multi-jurisdiction approval stretches product launch windows.
- Cross-platform battery incompatibility:Proprietary connector standards fragment the installed base. Users resist second-platform adoption despite superior tool performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cordless Sprayer Market |
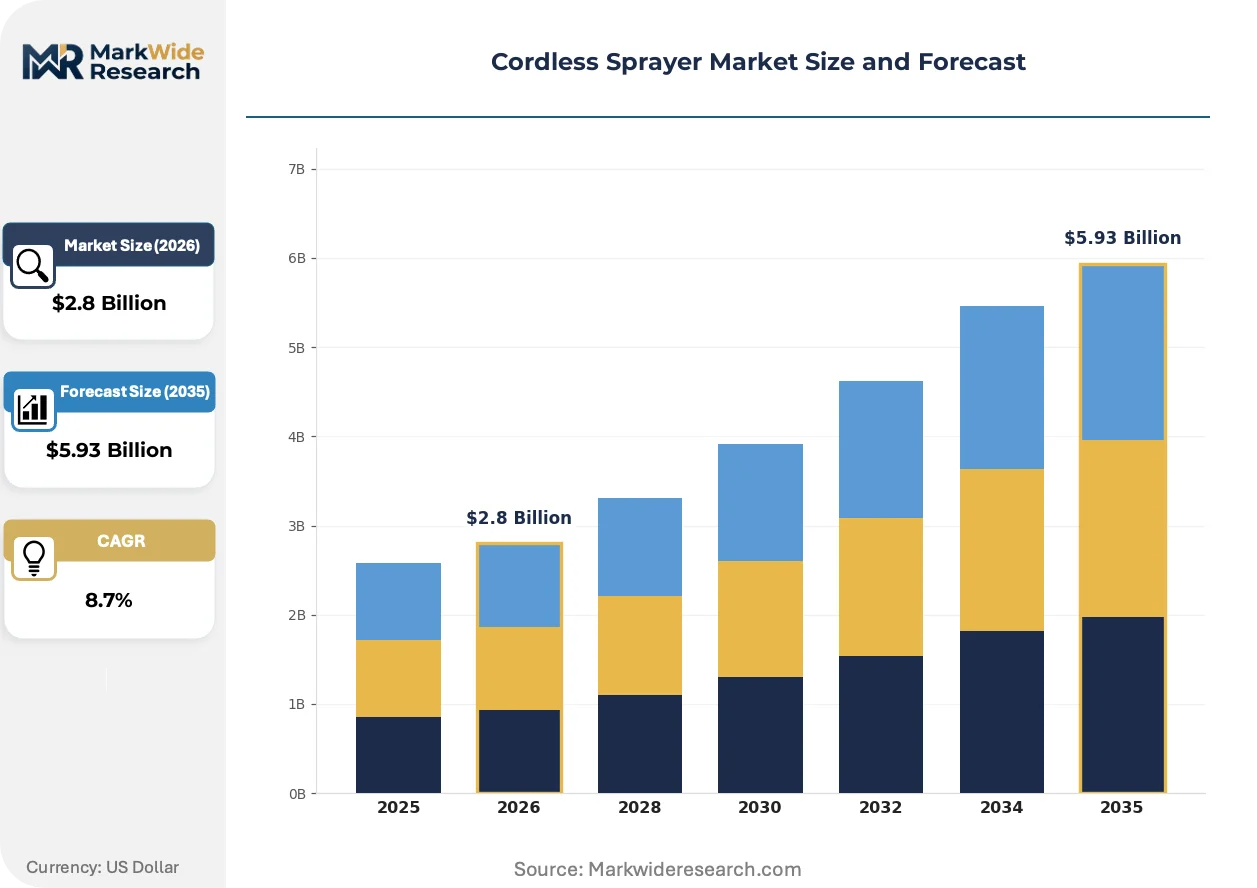
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Sprayers, Backpack Sprayers, Stationary Sprayers, Atomizers End User: Homeowners, Gardeners, Professionals, Agriculturalists Power Source: Lithium-Ion Batteries, NiCad Batteries, Solar Power, Others Application: Pest Control, Lawn Care, Disinfection, Fertilization |
| Companies Covered | Graco, Wagner, Ryobi, Sun Joe, Neu Master, HomeRight, EGO Power, Lemmer Spray Systems, Rongpeng Air Tools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cordless Sprayer Market Trends and Innovations
Smart pressure modulation and connected fleet management are redefining how professional crews deploy cordless spraying equipment. These capabilities transform asset utilization from intermittent ownership to continuous service models.
Brushless DC motor controllers with real-time pressure feedback are collapsing the performance gap between battery and gasoline sprayers. Municipal maintenance departments in the United States are specifying these units for uniform chemical application across irregular terrain. The technology is collapsing demand for mid-tier engine-driven alternatives that previously dominated commercial price points.
EPA emissions guidelines for small off-road engines are tightening certification requirements for any new gasoline-powered equipment entering the market. Manufacturers face parallel compliance burdens for exhaust after-treatment and evaporative emissions containment. Professional landscaping fleets in California and New York are responding fastest, accelerating cordless conversion to preempt regulatory sunset dates.
Equipment pooling through landscaping cooperatives is displacing individual ownership among mid-size commercial operators. Shared battery banks and centralized maintenance reduce capital exposure for seasonal businesses. This pattern concentrates most visibly in Australian regional centers where contractor networks coordinate across municipal and agricultural contract boundaries.
Cordless Sprayer Market Segmentation
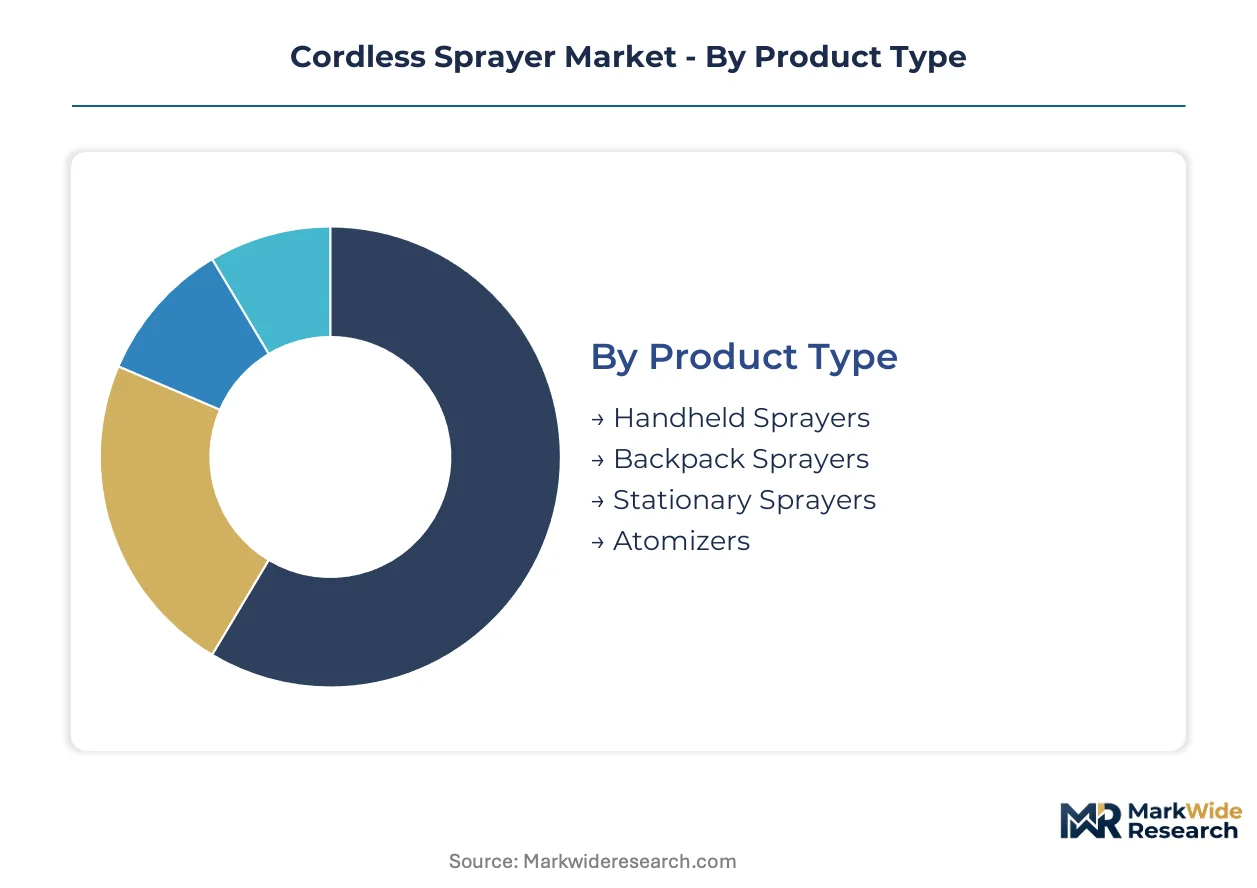
Cordless sprayer segmentation reveals divergent service intensity and margin profiles across product configurations. Battery platform compatibility and replacement part availability now shape vendor selection more than initial purchase price.
Product Type:
After-sales-service intensity varies sharply across form factors, with backpack units demanding field repair networks while handheld models rely on retail exchange programs.
- Handheld Sprayers:Compact piston-pump units weighing under 8 pounds dominate residential volume. Demand concentrates in United States home improvement retail channels where EGO Power and Ryobi interchangeable battery ecosystems drive repeat purchases. EPA disinfectant application guidelines during health emergencies accelerated household penetration.
- Backpack Sprayers:Diaphragm-pump systems with 15-20 liter tanks serve municipal groundskeeping crews. Germany's federal environmental procurement standards now mandate cordless specification for park maintenance contracts, locking out gasoline alternatives.
- Stationary Sprayers:Fixed-mount battery units for greenhouse and nursery operations.
- Atomizers:Ultra-low volume fogging devices for precision biological agent dispersal.
By volume, Handheld Sprayers leads. By growth pace, Backpack Sprayers is ahead.
End User:
Cost tier separation between amateur and professional users determines pricing architecture and distribution channel selection.
- Professionals:Landscaping contractors and municipal maintenance departments generate recurring equipment refresh cycles. OSHA workplace chemical exposure audits in United States commercial operations now document sprayer emission profiles, accelerating battery-powered fleet conversion.
- Agriculturalists:Orchard and vineyard operators require extended runtime for canopy penetration. Australian wine region cooperatives are pooling battery banks across contractor networks to reduce individual capital exposure.
- Homeowners:Seasonal intermittent users with high price elasticity.
- Gardeners:Semi-professional enthusiasts seeking commercial-grade durability.
By installed base, Homeowners leads. By revenue per unit, Professionals is ahead.
Power Source:
Technology maturity curves and supply chain concentration reshape competitive positioning across battery chemistries.
- Lithium-Ion Batteries:18650 and 21700 cylindrical cells with brushless DC motor controllers deliver 40-500 PSI output ranges. Lithium carbonate price volatility from Chilean and Australian mining operations compresses manufacturer margins unpredictably.
- NiCad Batteries:Legacy nickel-cadmium chemistry persists in price-sensitive developing markets. Memory effect degradation and EU battery directive disposal restrictions constrain European adoption.
- Solar Power:Photovoltaic panel integration for remote agricultural stations.
- Others:Emerging solid-state and sodium-ion experimental platforms.
By deployment share, Lithium-Ion Batteries leads. By technology transition risk, NiCad Batteries is ahead.
Application:
Geographic regulatory divergence creates application-specific certification burdens and market access barriers.
- Pest Control:Precision pesticide delivery systems require EPA equipment registration overlapping with state-level chemical licensing. California Department of Pesticide Regulation maintains separate approval timelines from federal EPA processes.
- Disinfection:Post-pandemic institutional demand from schools and healthcare facilities stabilized at elevated baselines. German infection protection ordinances specify equipment standards for surface decontamination protocols.
- Lawn Care:Residential and commercial turf maintenance with fertilizer and herbicide formulations.
- Fertilization:Precision nutrient delivery for greenhouse and field crop operations.
By regulatory complexity, Pest Control leads. By demand elasticity, Disinfection is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Homeowners in suburban United States markets exhibit the highest price elasticity, deferring replacement cycles during commodity inflation. Professional landscaping contractors in Germany and municipal fleets in Australia demonstrate inelastic demand, refreshing equipment on fixed depreciation schedules regardless of battery cost fluctuations.
United States
Commercial landscaping contractors drive professional-tier volume through fleet standardization on interchangeable battery platforms. OSHA Hazard Communication Standards enforcement in California and New York accelerates gasoline equipment phase-outs. Municipal procurement departments in Los Angeles and Seattle now mandate cordless specifications for park maintenance contracts.
Germany
Federal environmental procurement standards lock out gasoline alternatives from public landscaping tenders nationwide. CE marking convergence with EU machinery directives streamlines electrical safety certification across member states. Bavarian municipal maintenance crews in Munich and Nuremberg anchor backpack sprayer deployment density.
Australia
Wine region cooperatives pool battery banks across contractor networks to reduce individual capital exposure. State-level noise ordinances in urban centers amplify cordless specification shifts. Victorian agricultural clusters around Melbourne and regional Queensland horticulture operations concentrate demand for extended-runtime backpack configurations.
China
Commercial horticulture expansion in orchard and vineyard sectors creates latent demand for battery platform education. GB standards for electrical safety govern domestic market access and export certification. Yangtze River Delta manufacturing clusters supply cylindrical lithium-ion cells to global cordless sprayer assemblers.
India
Orchard and vineyard operators remain tethered to manual or engine sprayers, presenting platform education opportunities. BIS certification requirements for electrical equipment create market entry barriers for unbranded imports. Maharashtra commercial horticulture belts around Nashik and Pune concentrate prospective professional-tier demand.
Cordless Sprayer Market Competitive Landscape
Industrial coating heritage specialists and consumer battery platform incumbents split the market into distinct competitive spheres. Consolidation pressure concentrates at the professional tier where municipal procurement scale rewards single-source fleet contracts. Three archetypes dominate: legacy industrial fluid handling multinationals, interchangeable battery ecosystem platforms, and regional fabrication specialists serving price-sensitive developing markets. Dominant competitive moves include backward integration into battery pack assembly and strategic partnerships with municipal procurement consortiums.
Within the industrial heritage tier, Graco and Wagner exemplify divergent channel strategies despite shared professional-tier positioning. Graco leverages distribution infrastructure inherited from protective coatings markets. Wagner sustains presence across North American home improvement retail. EGO Power anchors the interchangeable battery ecosystem archetype, representing platform loyalty strategies that lock professional crews into multi-tool standardization. Chinese fabrication specialists including Rongpeng Air Tools occupy the regional supply tier, serving price-sensitive markets through established pneumatic tool channels.
| Leading Market Players |
|---|
| Graco |
| Wagner |
| Ryobi |
| Sun Joe |
| Neu Master |
| HomeRight |
| EGO Power |
| Lemmer Spray Systems |
| Rongpeng Air Tools |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta container freight corridors feed cylindrical lithium-ion cell assembly plants in China, compressing landed costs for battery pack integrators while amplifying margin pressure on brands lacking captive cathode sourcing. This logistics concentration enables three-tier pricing stratification across premium, standard, and economy levels, with freight cost differentials separating vendor tiers more sharply than hardware specifications alone.
Pricing Analysis
Aftermarket battery replacement and field service contracts now generate lifetime value multiples exceeding original equipment margins. Pricing stratifies across premium, standard, and economy tiers based on brushless motor controller sophistication and EPA equipment registration tier. Cost compression in entry-level handheld units is intensifying because lithium carbonate volatility forces contract manufacturers to absorb margin erosion. Homeowners exhibit highest price sensitivity, deferring replacement cycles during commodity spikes, while municipal procurement departments demonstrate inelastic demand anchored to fixed depreciation schedules.
Supply Chain Analysis
Export control restrictions on advanced cathode coating equipment limit technology transfer to emerging battery assembly hubs, concentrating premium cell production in China, South Korea, and Japan. Cylindrical 18650 and 21700 formats, brushless DC motor controllers, and diaphragm pump assemblies feed from concentrated Asian manufacturing clusters. Single-source vulnerability in Chilean and Australian lithium mining operations threatens just-in-time cathode material flows. Distribution runs through home improvement retail chains for residential tiers and municipal procurement consortiums for professional fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cordless sprayer market functions as a service-attach opportunity where battery platform subscription and fleet telematics revenue layers expand faster than hardware replacement cycles. Aftermarket parts availability and usage-based billing models now command valuation premiums over unit shipment growth.
For Market Incumbents: Insulate professional-tier margin pools through backward integration into battery pack assembly, capturing cathode cost volatility rather than absorbing it. Lock municipal procurement departments into multi-year fleet refresh contracts with embedded telemetry service tiers to preempt competitive displacement by interchangeable battery ecosystem platforms.
For New Entrants and Emerging Players: Build out dealer training and battery platform education infrastructure in Indian commercial horticulture belts around Nashik and Pune, where orchard operators remain tethered to manual application methods. Target vineyard cooperatives in emerging wine regions with pooled battery bank financing to reduce individual capital exposure.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial fluid handling multinationals seeking to divest non-core consumer-facing sprayer divisions. Long-term viability hinges on telematics integration and equipment-as-a-service model adoption. Watch for municipal RFP language mandating cordless specification as inflection signal for accelerated gasoline equipment phase-out.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Interchangeable ecosystems lock professional crews into multi-tool loyalty, reducing field inventory complexity. |
| Telematics Fleet Integration | GPS-tracked sprayer pools enable usage-based billing models that displace capital purchase cycles. |
| Backward Integration into Cells | Captive cathode sourcing insulates margins from lithium carbonate volatility in Chilean and Australian mining. |
| Municipal Procurement Partnership | Exclusive fleet contracts with Los Angeles and Seattle park departments secure multi-year revenue visibility. |
| Dealer Training Infrastructure | Platform education unlocks latent demand among Indian orchard operators tethered to manual application. |
Research Methodology
Desk research of customs trade databases, EPA equipment registration filings, and municipal procurement RFP archives preceded structured interviews with commercial landscaping fleet managers, battery pack assembly engineers, and home improvement retail category buyers. Primary fieldwork with OEM procurement teams and aftermarket service heads validated secondary estimates. Bottom-up unit shipment modeling triangulated against top-down addressable market sizing across product type, end user, and power source segments.
Forecast assumptions held lithium carbonate price bands within observed volatility ranges while varying municipal cordless mandate adoption curves across the analysis window. Segmentation dimensions modeled include product configuration, professional versus residential end use, battery chemistry tier, and geographic regulatory cluster. CAGRs derived from logistic diffusion curves fitted to equipment replacement cycle data and EPA enforcement trajectory indicators. Brushless motor controller cost curves and battery energy density improvement rates served as technology-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by battery cell manufacturers into downstream sprayer assembly would shift outcomes. Material shifts in OSHA Hazard Communication Standards enforcement intensity or EPA small off-road engine emissions sunset timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Aquarium Pumps and Filters Market
Agricultural Equipment
Agriculture Seeder Market
Agricultural Equipment
Global Yield Monitoring Devices Market
Agricultural Equipment
Gardening Tools Market
Agricultural Equipment
Greenhouse Kit Market
Agricultural Equipment
Forestry Equipment Market
Agricultural Equipment
Global Fishing Equipments Market
Agricultural Equipment
Australia Bird Feeder Market
Agricultural Equipment
Agriculture Container and Tank Cleaning Market
Agricultural Equipment
Livestock Grow Lights Market
Agricultural Equipment
India Color Sorter Market
Agricultural Equipment
Vegetable Sorting Machines Market
Agricultural Equipment
Agriculture Evaporative Cooling Pad Market
Agricultural Equipment
Aquatic Weed Harvester Market
Agricultural Equipment
Global Infrared Heater for Agriculture Market
Agricultural Equipment
Pistol Grip Sprayer Market