
 Belt Feeders Market | 2026-2036
Belt Feeders Market Size, Share, and Industry Trends Forecast 2026-2036
Belt Feeders Market Outlook
ISO 9001 quality management certification is rotating as a baseline gate for tier-one procurement eligibility in heavy bulk handling. FLSmidth leverages its integrated mining technology portfolio to anchor large-scale project delivery across copper and iron ore belts. Schenck Process Group sustains differentiation through precision weighing feeder systems that compete on dosing accuracy in cement and steel applications. Metso dominates aftermarket service networks that extend equipment life cycles across Nordic and South American installations.
A belt feeder is a continuous conveying device comprising a reinforced fabric or steel-cord belt trained over head and tail pulleys, driven through a motorized gearbox arrangement, designed to extract, regulate, and discharge bulk solids from hoppers or bins at controlled volumetric or gravimetric rates. Belt widths typically span 500 mm to 2,400 mm with throughput capacities from 10 to over 10,000 tonnes per hour depending on material density and surcharge angle. Electromechanical configurations lead installed base volumes due to simpler maintenance profiles and lower energy intensity compared to hydraulic alternatives, while variable speed drive technology captures expanding share as plant automation upgrades accelerate. Mining end users represent the most entrenched demand pool, though recycling applications show structural momentum driven by circular economy mandates and construction debris processing scale-up.
The EU Machinery Directive 2006/42/EC and OSHA workplace safety standards in the United States enforce guarding, emergency stop, and noise emission requirements that shape feeder design and retrofit obligations. China's GB/T national standards for continuous handling equipment mandate localization testing that conditions market access for imported systems. Stakeholders must monitor convergence between functional safety certification demands and carbon border adjustment mechanisms as these frameworks increasingly filter equipment procurement specifications.
Market Dynamics
Electromechanical drive systems are compressing hydraulic alternatives across bulk handling installations as energy efficiency mandates harden and maintenance cost differentials widen. Variable frequency drive integration now conditions competitive viability in greenfield mining and steel projects.
Growth Catalysts
- Australia-Chile mining automation:Copper and iron ore operators in Western Australia and Chile's Antofagasta region deploy automated belt feeder arrays to reduce labor exposure and stabilize throughput. Bulk material handling robotics integration accelerates replacement cycles.
- EU F-Gas Regulation:The 2024 phasedown of hydrofluorocarbon-based hydraulic systems forces electromechanical retrofits in European cement and steel plants. IEC 61508 functional safety certification becomes mandatory for new installations.
- China steel throughput expansion:Hebei and Jiangsu province steel mills require high-capacity belt feeders exceeding 5,000 tonnes per hour for sinter plant raw material delivery. GB/T national standards mandate localized testing protocols.
Market Restraints
- Steel-cord belt input volatility:Reinforced fabric and steel-cord conveyor belt materials face price instability tied to carbon steel coil markets. Procurement exposure concentrates in East Asian rubber-steel composite suppliers.
- Functional safety certification burden:IEC 61508 SIL compliance requires 18-24 month validation timelines for electromechanical drive systems. Smaller manufacturers lack capitalized testing infrastructure.
- Pneumatic conveying substitution:Dense-phase pneumatic systems capture pharmaceutical and food-grade powder handling where contamination risk outweighs belt feeder energy efficiency.
Strategic Opportunities
- India recycling infrastructure buildout:Construction and demolition debris processing plants in Gujarat and Maharashtra require modular belt feeder configurations. The country's PLI scheme for waste-to-energy equipment reduces import duty exposure.
- Digital twin integration:Predictive maintenance algorithms fused with belt tension monitoring and motor current signature analysis enable condition-based overhaul scheduling. Mining operators in Brazil's Carajás district pilot these convergent systems.
- Carbon border adjustment alignment:EU CBAM scope expansion to steel and cement imports incentivizes low-emission feeder procurement in Turkish and Ukrainian export-oriented plants. Electromechanical systems qualify for embedded carbon reduction credits.
Industry Challenges
- Mechatronics skill scarcity:Belt feeder commissioning requires cross-trained technicians fluent in gearbox diagnostics, PLC programming, and belt splice vulcanization. Mining regions in Western Australia and northern Chile report 15-20% vacancy rates in these hybrid roles.
- Legacy DCS integration friction:Variable speed drive retrofits into 1990s-era distributed control systems demand custom protocol gateways. Cement plants in Egypt and Vietnam face 6-9 month commissioning delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belt Feeders Market |
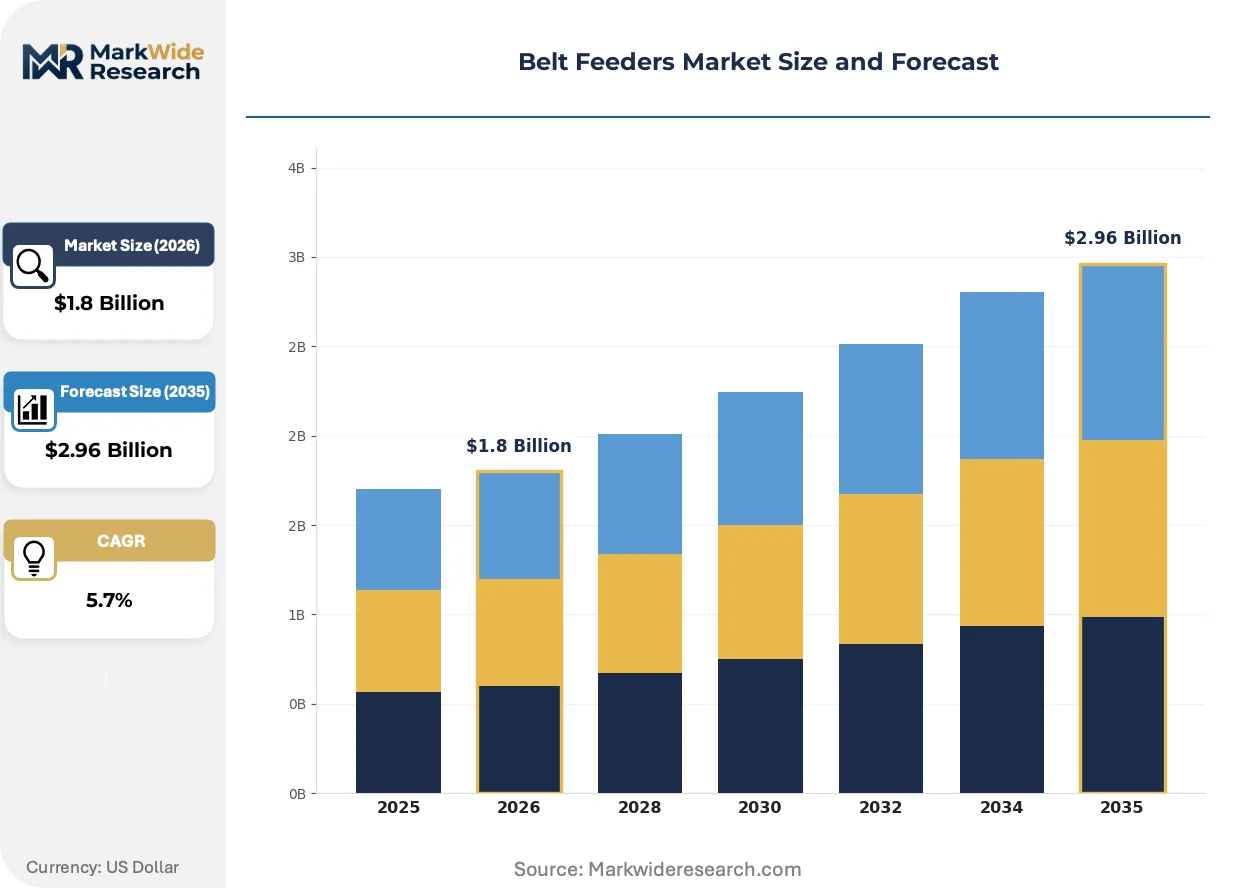
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical, Hydraulic, Pneumatic, Mechanical End User: Mining, Construction, Recycling, Food Processing Application: Material Handling, Bulk Processing, Aggregate Distribution, Granular Transfer Technology: Variable Speed Drive, Belt Tracking, Load Cells, Industrial Automation |
| Companies Covered | FLSmidth, Schenck Process Group, Merrick Industries, Metso, Sandvik, Siemens AG, ABB Ltd, Thayer Scale, Acrison, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belt Feeders Market Strategic Shifts
Digital instrumentation and closed-loop control architectures are redefining belt feeder performance benchmarks. Precision weighing integration and edge-computing diagnostics now separate competitive tiers in heavy bulk handling procurement.
Direct torque control variable frequency drives are supplanting traditional V/Hz control methods in high-inertia mining applications. Copper concentrators in Chile and Peru adopt these systems for their 0.5% speed regulation accuracy under load surge conditions. The technology is supplanting fluid coupling soft-start arrangements that previously dominated installations above 250 kW motor ratings.
The EU Machinery Directive 2006/42/EC amendment on autonomous operation mandates redundant emergency stop architectures and wireless safety circuit validation. Belt feeder OEMs serving European cement and steel markets must recertify guarding designs by 2026. German and Polish manufacturers are consolidating SIL-certified component supply chains to preempt compliance bottlenecks.
Buyer organizations now unbundle aftermarket service contracts from initial equipment procurement. Mining operators in Australia's Pilbara region negotiate separate multi-year maintenance agreements with specialized service providers. This unbundling compresses OEM service margins while expanding independent technician networks across Western Australia and Queensland coal belts.
Belt Feeders Market Segmentation
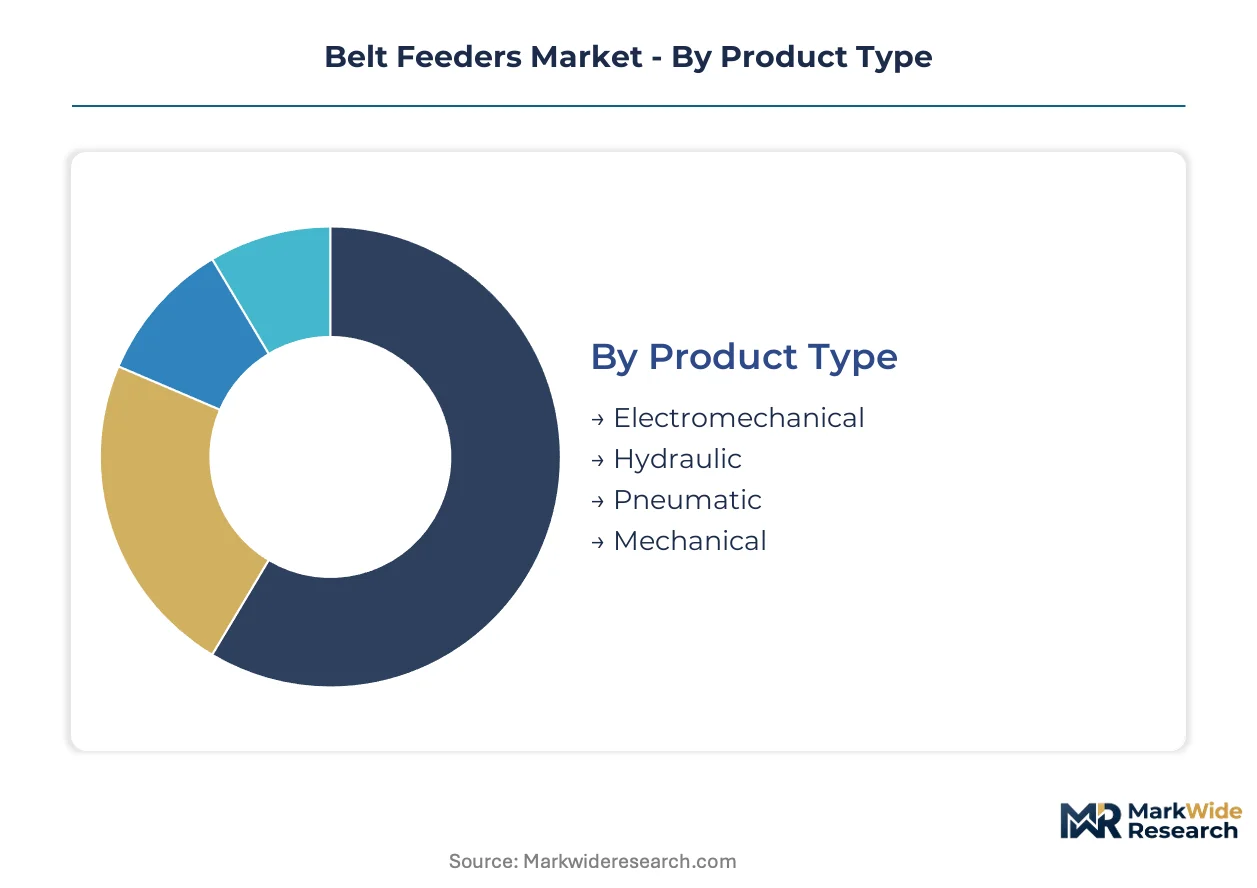
Belt feeder procurement channels diverge sharply by segment, with mining contractors favoring integrated electromechanical systems through direct OEM relationships while food processors source pneumatic units via specialized distributors. Segmentation discipline separates volume-driven commodity suppliers from precision-engineering specialists serving regulated end-uses.
Product Type:
Channel mix varies dramatically across drive technologies, with electromechanical systems flowing through manufacturer-direct mining contracts and hydraulic units increasingly constrained to aftermarket retrofit channels amid EU F-Gas phasedown.
- Electromechanical:Motorized gearbox arrangements with variable frequency drives dominate greenfield mining installations. Australian iron ore operators in Western Australia's Pilbara region specify these systems for their 5-15% energy efficiency advantage over hydraulic alternatives and simplified maintenance protocols.
- Hydraulic:Fluid power drive systems retain position in high-torque startup applications above 400 kW. Chilean copper concentrators in the Antofagasta region continue limited procurement where existing infrastructure and technician familiarity delay electromechanical conversion timelines.
- Pneumatic:Compressed air-driven feeders serve explosive atmosphere zones and food-grade powder handling where contamination isolation outweighs energy cost considerations.
- Mechanical:Direct-coupled fixed-speed arrangements persist in low-automation cement and aggregate plants with limited capital budgets and minimal throughput variability requirements.
Electromechanical systems dominate installed base. Hydraulic is where expansion concentrates as F-Gas Regulation forces accelerated replacement cycles.
End User:
Cost tier stratification separates capital-intensive mining procurement from price-sensitive construction equipment sourcing, with recycling applications commanding mid-tier positioning as circular economy mandates reshape specification requirements.
- Mining:Copper, iron ore, and coal extraction operations drive specification intensity for belt widths exceeding 1,800 mm and throughput above 5,000 tonnes per hour. Brazil's Carajás iron ore district and Western Australia's Pilbara region anchor demand for SIL-certified electromechanical arrays with integrated weighing systems.
- Recycling:Construction and demolition debris processing plants in Gujarat and Maharashtra, India require modular configurations with quick belt change capabilities. The country's PLI scheme for waste-to-energy equipment reduces import duty exposure for domestic assembly operations.
- Construction:Mobile crushing and screening contractors prioritize compact footprints and rapid deployment over precision control, sourcing through rental fleet channels with standardized maintenance intervals.
- Food Processing:Grain handling and packaged goods operations specify stainless steel construction and washdown-rated components to satisfy FDA and FSSAI hygiene mandates.
Mining commands premium pricing tiers. Recycling is climbing the fastest as infrastructure buildouts accelerate across South Asia.
Application:
Volume concentration maps directly to material density and particle size distribution, with high-tonnage bulk processing commanding dedicated engineering resources while granular transfer applications tolerate standardized catalog configurations.
- Material Handling:Continuous extraction from hoppers and bins at controlled discharge rates represents the core functional specification across all product categories. Chinese steel mills in Hebei province deploy high-capacity units exceeding 7,000 tonnes per hour for sinter plant raw material delivery under GB/T national standards.
- Bulk Processing:Intermediate storage and blending operations in cement manufacturing require precision volumetric control to maintain kiln feed consistency. Turkish export-oriented plants prioritize electromechanical systems to qualify for EU CBAM embedded carbon reduction credits.
- Aggregate Distribution:Quarry and sand-gravel operations emphasize durability in abrasive environments with reinforced fabric belts and heavy-duty impact cradles.
- Granular Transfer:Fertilizer, chemical, and specialty mineral handling demands sealed skirtboard designs and dust suppression integration to satisfy OSHA and workplace exposure limits.
Material handling anchors volume share. Bulk processing is where specification intensity is expanding most quickly as carbon border mechanisms filter procurement.
Technology:
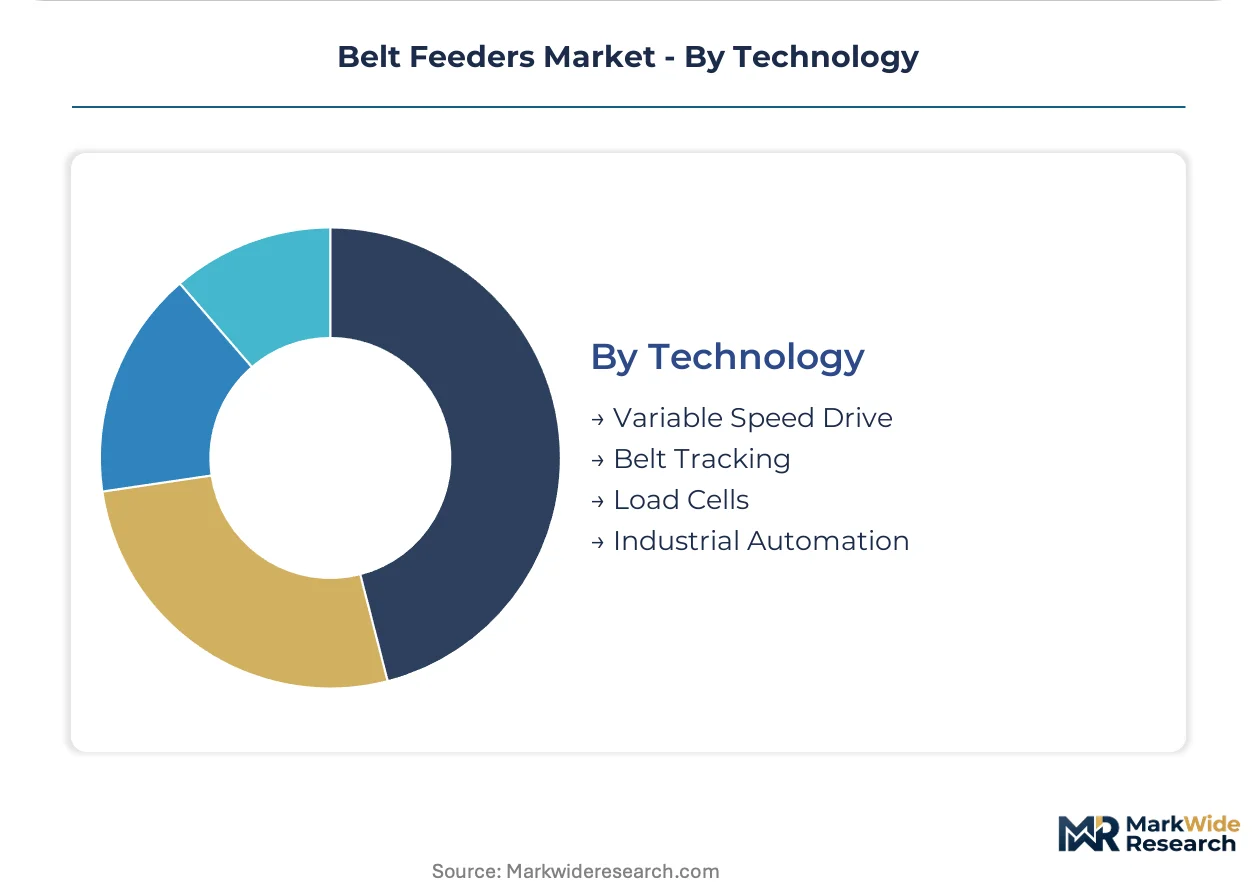
Customer type segmentation separates automation-forward mining majors investing in predictive maintenance platforms from price-focused contractors selecting basic belt tracking without digital instrumentation.
- Variable Speed Drive:Direct torque control VFD systems achieve 0.5% speed regulation accuracy under load surge conditions. Peruvian copper concentrators adopt these to replace fluid coupling soft-start arrangements previously standard above 250 kW ratings.
- Industrial Automation:PLC-integrated control architectures with edge-computing diagnostics enable condition-based overhaul scheduling. Brazilian mining operators pilot digital twin integration fusing belt tension monitoring with motor current signature analysis.
- Belt Tracking:Self-aligning idler and pivoting frame mechanisms reduce edge wear and spillage in misalignment-prone installations with limited maintenance access.
- Load Cells:Precision gravimetric weighing integration supports real-time mass flow measurement for process control in cement and steel dosing applications.
Variable speed drive holds largest installed base. Industrial automation is where technology investment concentrates as predictive maintenance contracts unbundle from equipment procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated mining contractors in Western Australia and Chile's Antofagasta region anchor procurement intensity for high-capacity electromechanical systems. Steel producers in China's Hebei province and recycling operators in India's western states complete the buyer concentration map.
Australia
Iron ore majors in Western Australia's Pilbara region specify belt widths exceeding 1,800 mm for automated bulk handling arrays. The country's workplace safety regulator enforces strict guarding and emergency stop protocols under national mining safety frameworks. Perth-based engineering clusters coordinate aftermarket service networks across Queensland coal belts.
Chile
Copper concentrators in the Antofagasta region drive demand for SIL-certified electromechanical feeders with integrated weighing systems. Chile's national mining regulator mandates progressive automation to reduce labor exposure in open-pit operations. Santiago-based technology providers pilot digital twin integration for predictive maintenance in the Atacama Desert mining corridor.
China
Steel mills in Hebei and Jiangsu provinces require throughput capacities above 5,000 tonnes per hour for sinter plant raw material delivery. GB/T national standards for continuous handling equipment mandate localization testing that conditions market access. Tangshan industrial clusters concentrate domestic fabrication capacity for heavy-duty belt feeder assemblies.
India
Construction and demolition debris processing plants in Gujarat and Maharashtra require modular configurations with rapid belt change capabilities. The country's production-linked incentive scheme for waste-to-energy equipment reduces import duty exposure for domestic assembly. Ahmedabad manufacturing hubs scale fabrication capacity to serve South Asian recycling infrastructure buildouts.
Germany
Cement and steel plants prioritize electromechanical retrofits to satisfy EU F-Gas Regulation phasedown timelines for hydraulic systems. The EU Machinery Directive enforces redundant emergency stop architectures and wireless safety circuit validation by 2026. Ruhr Valley industrial clusters consolidate SIL-certified component supply chains to preempt compliance bottlenecks.
Belt Feeders Market Competitive Environment
Player mix skews toward diversified heavy machinery conglomerates with integrated mining technology portfolios. Market structure concentrates around three to four vertically integrated groups controlling large-scale project delivery channels. Strategic archetypes separate precision weighing specialists, aftermarket service network operators, and automation-forward electromechanical system providers. Competitive moves center on unbundling aftermarket contracts from equipment procurement and consolidating SIL-certified component supply chains.
Among European-based industrial technology groups, FLSmidth and Schenck Process Group occupy positions anchoring premium-tier procurement channels. Metso represents the aftermarket service archetype with extensive life-cycle extension networks. Siemens AG sits within the automation-integrated tier, supplying variable frequency drive and control system components that condition competitive viability in greenfield projects.
| Leading Market Players |
|---|
| FLSmidth |
| Schenck Process Group |
| Merrick Industries |
| Metso |
| Sandvik |
| Siemens AG |
| ABB Ltd |
| Thayer Scale |
| Acrison |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts with steel-cord belt suppliers lock in both supply access and price visibility for Australian and Chilean mining operators facing volatile carbon steel coil markets. These arrangements transfer procurement risk to East Asian rubber-steel composite manufacturers while stabilizing input costs for tier-one OEMs serving Western Australia's Pilbara region.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate procurement for steel-cord belt assemblies. Three-tier pricing structure across SIL-certified premium, standard electromechanical, and economy mechanical tiers reflects certification burden and automation integration depth. Pricing pressure stems from F-Gas Regulation compliance costs compressing hydraulic system margins. Construction contractors exhibit highest price sensitivity, while mining majors prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Port congestion along Shanghai-Singapore and Busan-Los Angeles trade lanes elevates inbound logistics costs for European and North American OEMs sourcing from East Asian belt manufacturers. Supply concentrates in China, South Korea, and Japan for reinforced fabric and steel-cord composites. Raw material dependencies include carbon steel coil, synthetic rubber compounds, and vulcanization chemicals. Single-source vulnerability concentrates in specialized steel-cord weaving capacity. Distribution runs through manufacturer-direct channels for mining projects and specialized distributors for food-grade and recycling applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Belt feeder procurement is shifting toward platform economics as digital twin integration and predictive maintenance algorithms create interoperability dependencies between OEMs and mining operator IT systems.
For Market Incumbents: Compound aftermarket service network density in Western Australia and Chile's Antofagasta region to preempt unbundling trends. Deepen captive supply of SIL-certified variable frequency drive components to defend against automation-integrated competitors. Acquire specialized weighing technology providers to anchor precision dosing segments in cement and steel applications. For New Entrants and Emerging Players: Differentiate on rapid-deployment modular configurations targeting India's Gujarat and Maharashtra recycling infrastructure buildout. Capture construction and demolition debris processing white space through domestic assembly partnerships leveraging PLI scheme benefits. Pursue digital-native go-to-market positioning with edge-computing diagnostics bundled as subscription service tiers. For Investors and Strategic Acquirers: Capital is best deployed toward precision weighing specialists with cement and steel vertical penetration and established GB/T localization capabilities for China market access. Long-term viability hinges on automation-forward electromechanical system providers with IEC 61508 certification infrastructure. Monitor EU CBAM scope expansion signals as inflection indicator for low-emission feeder procurement acceleration in Turkish and Ukrainian export-oriented plants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel-Cord Belt Manufacturing | Captive supply secures margin control against LME-indexed input volatility for Pilbara mining contracts. |
| SIL Certification Infrastructure Investment | IEC 61508 compliance capacity unlocks EU F-Gas Regulation retrofit opportunities in German cement plants. |
| Digital Twin Platform Development | Predictive maintenance algorithms fuse belt tension monitoring with motor current signature analysis for Brazilian operators. |
| GB/T Localization Partnership | Domestic testing protocols satisfy Hebei province steel mill procurement mandates under Chinese national standards. |
| Aftermarket Service Network Expansion | Perth-based engineering clusters coordinate life-cycle extension across Queensland coal belts to capture unbundled maintenance contracts. |
Study Parameters
A standing panel of maintenance directors at Australian iron ore operations, plant engineers at Chilean copper concentrators, OEM procurement teams in Germany and China, and aftermarket service heads across Nordic installations provided ongoing calibration. Primary interviews combined with secondary validation from customs and trade data, SEC filings of listed heavy machinery conglomerates, IEC certification registries, and GB/T standard documentation. Bottom-up equipment shipment analysis triangulated against top-down mining capital expenditure tracking.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including drive technology type, end-use industry vertical, automation integration tier, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis, greenfield project pipeline assessment, and retrofit conversion rate modeling. Industry-specific forecast inputs incorporated F-Gas Regulation compliance timelines and China's dual carbon policy implementation pace.
Forecasts assume regulatory continuity in EU F-Gas phasedown schedules and China's GB/T localization mandates; material policy shifts would require re-modeling. Steel-cord input price volatility and mechatronics skill scarcity in Western Australia represent specific risk factors that could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Smart Rice Transplanter Market
Agricultural Equipment
Horse Drawn Farming Equipment Market
Agricultural Equipment
Australia Bird Feeder Market
Agricultural Equipment
Cotton Picker Market
Agricultural Equipment
Pump Feeder Market
Agricultural Equipment
Solar Insect Trap Market
Agricultural Equipment
Israel Agriculture Market
Agricultural Equipment
Aquarium Pumps and Filters Market
Agricultural Equipment
Garden Tools Market
Agricultural Equipment
Global Fishing Equipments Market
Agricultural Equipment
Greenhouse Heaters Market
Agricultural Equipment
Harrows Market
Agricultural Equipment
Lawn Shredder Market
Agricultural Equipment
Global Infrared Heater for Agriculture Market
Agricultural Equipment
India Color Sorter Market
Agricultural Equipment
Commercial Grain Mill Market