
 Feller Buncher Market | 2026-2036
Feller Buncher Market Size, Share, and Industry Trends Forecast 2026-2036
Feller Buncher Market Analysis
Canada's forestry equipment manufacturing corridor is reconfiguring supply chain priorities for North American contractors. John Deere Forestry leverages its dealer network density to sustain parts availability across remote logging camps. Komatsu Forest AB anchors its position through tracked platform specialization in steep-slope terrain. Ponsse Plc differentiates via cut-to-length integration that extends beyond feller buncher units alone.
A feller buncher is a self-propelled forestry machine that cuts, grips, and accumulates multiple trees before placing them in a bunch for extraction, typically employing a disc saw or shear head with grapple arms and operating at boom reaches exceeding 9 meters to serve mechanized clearcut and thinning operations. Tracked feller bunchers dominate steep-grade applications where ground pressure and slope stability govern equipment selection, while wheeled variants lead on gentler terrain where transport speed between blocks reduces non-productive time. Hydraulic technology remains the installed base majority, though electronic control architectures are displacing mechanical pilot circuits in new builds as precision felling demands tighter head positioning accuracy.
EPA Tier 4 Final standards and the EU F-Gas Regulation constrain engine and hydraulic fluid specifications for equipment sold in North America and Europe, while OSHA logging safety directives shape operator protection and remote operation enablement requirements in the United States. The EU Machinery Directive and CE marking requirements govern market access for European deployments, with national regulators in Finland and Sweden adding supplemental forest road weight limit enforcement. Stakeholders must monitor how automation technology maturation intersects with evolving operator certification frameworks to determine capital deployment timing for next-generation fleets.
Market Dynamics
Mechanized clearcut and thinning operations are reconfiguring fleet replacement cycles as EPA Tier 4 Final emission standards force engine architecture redesigns across North American softwood harvesting corridors.
Growth Catalysts
- Pine plantation intensification:Southeastern United States timberland managers are expanding mechanized harvesting footprints to optimize rotation cycles on plantation-grade acreage.
- EU F-Gas Regulation:Hydraulic fluid specification upgrades for European deployments are accelerating replacement demand for older feller buncher fleets.
- Tracked platform specialization:Steep-slope terrain applications in Pacific Northwest operations are pulling demand for high-flotation undercarriage configurations.
Market Restraints
- Steel and hydraulic component volatility:Input cost swings for boom fabrication and high-pressure cylinder assemblies compress margin visibility for equipment manufacturers.
- Dealer network concentration:Parts availability in remote Canadian logging camps depends on sparse distribution infrastructure across northern Ontario and British Columbia.
- Diesel-electric hybrid technical immaturity:Power density limitations in battery-electric prototypes constrain all-day operation in high-cycle felling applications.
Strategic Opportunities
- Cut-to-length integration:Forwarder-feller buncher system bundling creates stickier contractor relationships beyond standalone unit sales.
- Remote operation enablement:OSHA logging safety directives are opening capital deployment paths for cab-forward and teleoperation architectures.
- Quebec and Maritime Provinces:Undermechanized hardwood operations in eastern Canada present fleet expansion potential as labor availability tightens.
Industry Challenges
- Mechatronics technician scarcity:Electronic control architecture maintenance requires skills absent from traditional heavy equipment mechanic training pipelines.
- EPA certification timeline compression:Engine validation cycles for Tier 4 Final compliance extend new model introduction windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feller Buncher Market |
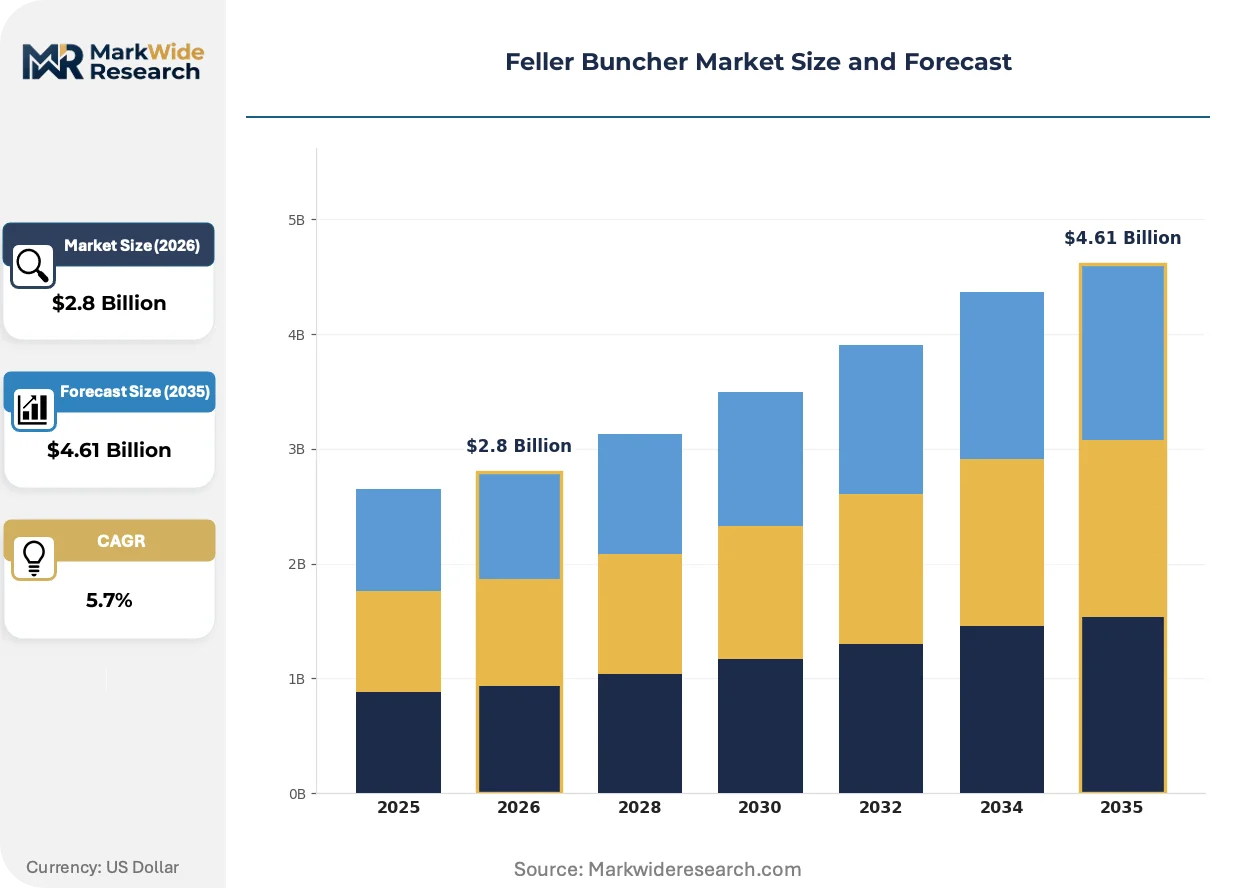
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tracked Feller Bunchers, Wheeled Feller Bunchers, Hybrid Feller Bunchers, Modular Feller Bunchers Technology: Hydraulic, Mechanized, Electronic, Automation End User: Commercial Timber Harvesters, Logging Companies, Construction Firms, Land Management Agencies Application: Forestry, Land Clearing, Road Maintenance, Reforestation |
| Companies Covered | Komatsu Forest AB, TimberPro Inc., John Deere Forestry, Barko Hydraulics LLC, Weiler Forestry, Tigercat Industries, Ponsse Plc, Dougherty Forestry Manufacturing, Caterpillar Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feller Buncher Market Emerging Trajectories
Electronic control architectures are displacing mechanical pilot circuits as precision felling demands tighter head positioning accuracy across mechanized harvesting operations.
Teleoperation and semi-autonomous control systems are virtualizing operator presence in hazardous felling zones. Large-scale contractors in British Columbia and Washington State are piloting remote-capable units for roadside processing applications. This virtualization is compressing the trade-off between operator safety premiums and productive hour availability in steep-slope terrain.
EPA Tier 4 Final emission standards are constraining engine and hydraulic fluid specifications for equipment sold in North America. The regulation forces aftertreatment system integration that adds weight and thermal management complexity to compact machine envelopes. Southeastern United States contractors are responding by extending rebuild cycles on pre-Tier 4 Final units to defer capital deployment.
Service contract unbundling is fragmenting the traditional dealer-package model. Independent maintenance providers in Alberta and Montana are capturing preventive service volume through mobile technician fleets equipped with proprietary diagnostic tools. This shift is most visible among mid-scale contractors operating mixed-brand fleets who prioritize parts interoperability over single-source loyalty.
Feller Buncher Market Segmentation
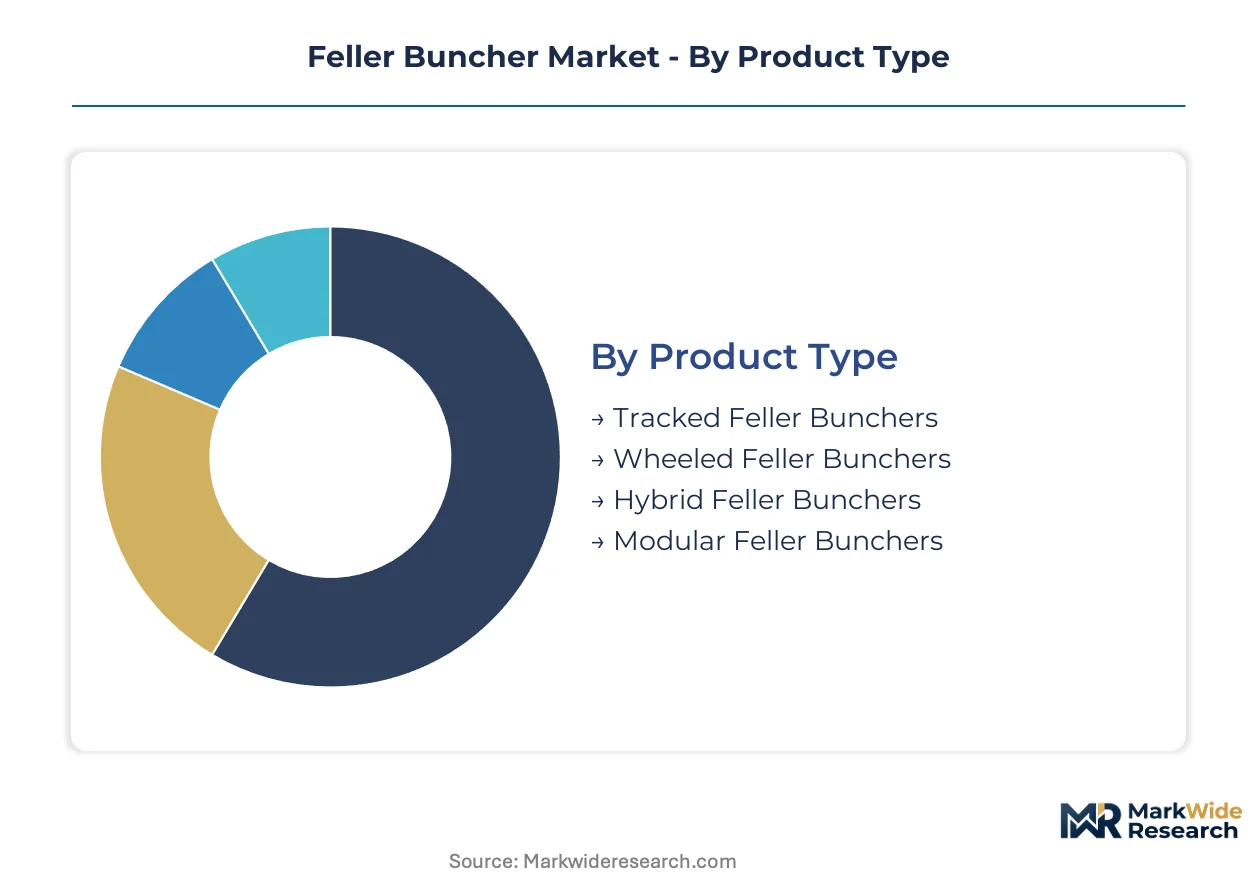
Feller buncher segmentation reveals how terrain constraints, emission regulations, and contractor scale reshape equipment procurement across mechanized harvesting operations. Understanding these divisions clarifies why tracked platforms dominate Pacific Northwest steep-slope contracts while wheeled variants capture southeastern plantation thinning work.
Product Type:
Contractors select undercarriage configurations based on ground pressure limits, transport logistics, and slope stability requirements across their operating territories.
- Tracked Feller Bunchers:High-flotation steel or rubber-track undercarriages distribute machine weight across soft or steep terrain. Demand concentrates in Washington State and British Columbia coastal operations where slope grades exceed 35% and soil bearing capacity limits wheeled alternatives.
- Wheeled Feller Bunchers:Articulated chassis with forestry tires enable rapid block-to-block transit on improved woods roads. Southeastern United States pine plantation contractors prioritize these units for rotation-cycle efficiency on gentler topography.
- Hybrid Feller Bunchers:Dual-power architectures combining diesel prime movers with electric drive motors.
- Modular Feller Bunchers:Componentized designs permitting field-swapped heads and power units for seasonal application shifts.
The dominant share belongs to Tracked Feller Bunchers, while Wheeled Feller Bunchers is closing the gap fastest.
Technology:
Control system architecture determines precision capabilities, maintenance skill requirements, and compliance with evolving emission and safety mandates.
- Hydraulic:Conventional pilot-operated valve circuits remain prevalent in legacy fleets and cost-sensitive contractor segments.
- Mechanized:Integrated felling head mechanics with fixed kinematic relationships between saw, grapple, and accumulator arms.
- Electronic:CAN-bus distributed control architectures enable closed-loop head positioning and diagnostic telemetry. Pacific Northwest contractors deploying these systems achieve tighter stump height consistency for sawlog grade recovery.
- Automation:Semi-autonomous felling sequences and teleoperation interfaces separate operators from falling timber hazards. British Columbia roadside processing pilots demonstrate how this technology compresses the safety-productivity trade-off in steep terrain.
Hydraulic systems retain the largest installed base, though Electronic architectures are expanding most quickly as Tier 4 Final engine integration demands sophisticated thermal and power management.
End User:
Procurement scale and equipment utilization patterns vary sharply between integrated timberland owners and independent harvesting contractors.
- Commercial Timber Harvesters:Large-scale operators with dedicated equipment fleets and in-house maintenance infrastructure. These entities dominate replacement demand in the southeastern United States as plantation rotation intensification accelerates mechanization.
- Logging Companies:Independent contractors serving multiple timberland owners on seasonal or project-based agreements.
- Construction Firms:Diversified earthmoving contractors deploying feller bunchers for land clearing ahead of infrastructure development.
- Land Management Agencies:Federal and state forestry services conducting hazardous fuel reduction and restoration thinning.
Commercial Timber Harvesters command the dominant procurement volume, while Land Management Agencies are gaining share fastest as wildfire mitigation funding expands federal fleet modernization.
Application:
Operational purpose dictates head specification, boom reach requirements, and auxiliary equipment pairing.
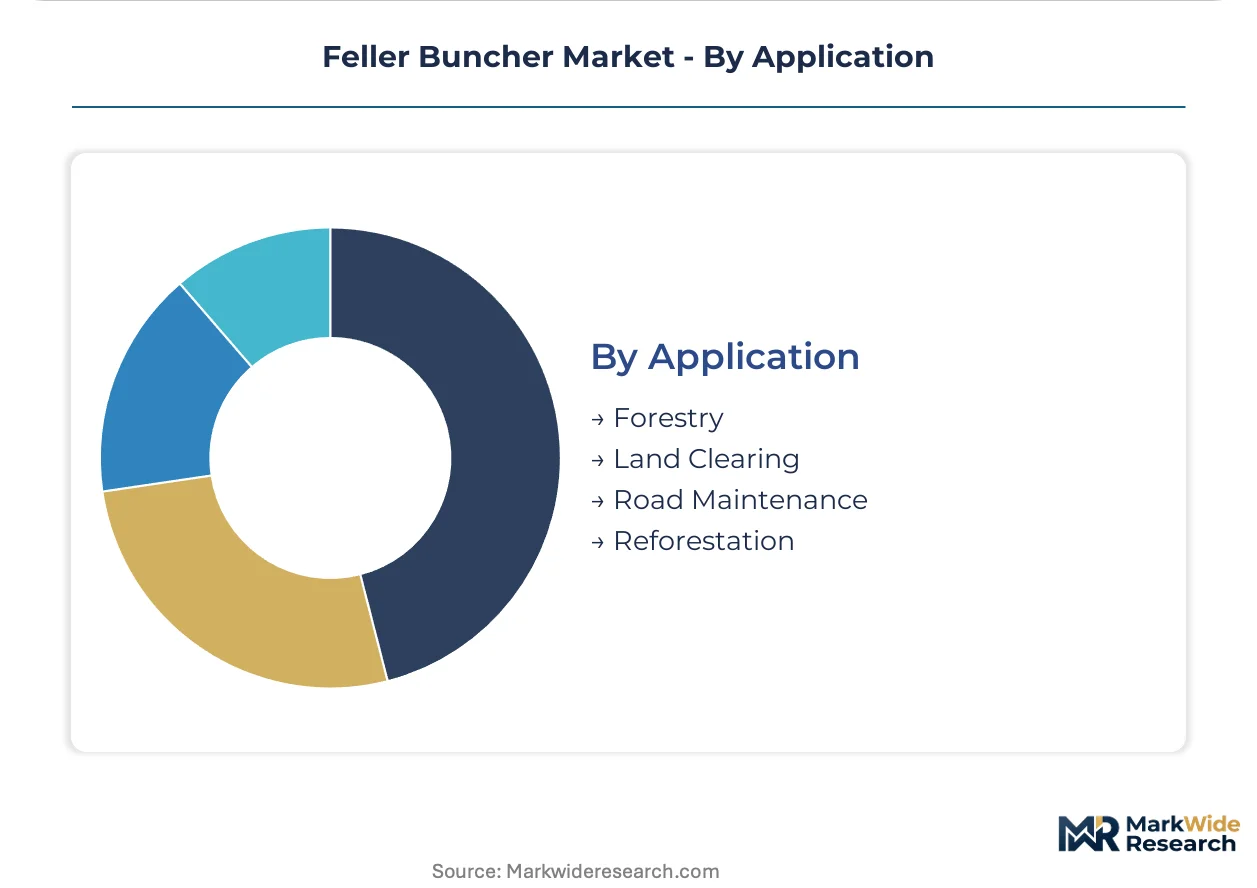
- Forestry:Commercial timber harvesting for sawlogs, pulpwood, and biomass feedstock. This application spans clearcut, seed-tree, and shelterwood silvicultural systems across North American softwood and hardwood operations.
- Land Clearing:Vegetation removal for agricultural conversion, urban expansion, or infrastructure right-of-way preparation.
- Road Maintenance:Corridor brushing and hazard tree removal along forest road networks.
- Reforestation:Site preparation and competing vegetation control prior to planting operations.
Forestry applications generate the dominant equipment demand, with Land Clearing climbing the fastest as renewable energy project siting accelerates vegetation management contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Tier 4 Final standards anchor North American procurement patterns, while EU F-Gas Regulation compliance shapes European hydraulic system specifications. Mechanized harvesting corridors concentrate in specific timber basins where plantation management and steep-slope extraction create divergent equipment requirements.
United States
Pine plantation intensification across Georgia, Alabama, and Mississippi drives wheeled feller buncher demand for rotation-cycle efficiency. OSHA logging safety directives accelerate remote operation pilot programs in Pacific Northwest steep-slope zones. Southeastern contractors defer capital deployment by extending rebuild cycles on pre-Tier 4 Final units.
Canada
Quebec and Maritime Provinces hardwood operations present fleet expansion potential as labor availability tightens in undermechanized regions. Health Canada and provincial regulators enforce forest road weight limits that constrain equipment transport logistics. British Columbia coastal operations concentrate tracked platform demand where slope grades exceed 35%.
Sweden
Cut-to-length integration dominates procurement patterns as contractors bundle forwarder-feller buncher systems for operational efficiency. National forest road weight limit enforcement shapes undercarriage specification requirements. Västerbotten and Norrbotten counties anchor mechanized harvesting corridors for softwood export operations.
Finland
Electronic control architecture adoption accelerates as precision felling demands tighter stump height consistency for sawlog grade recovery. National regulators supplement EU Machinery Directive with supplemental forest road enforcement. Kainuu and North Karelia regions concentrate fleet modernization activity among large-scale timber harvesters.
Brazil
Eucalyptus plantation expansion in Minas Gerais and São Paulo states pulls demand for high-productivity wheeled configurations on gentler topography. ANVISA and environmental licensing frameworks govern equipment import and deployment timelines. Mato Grosso land clearing operations generate secondary demand for vegetation management contracting.
Feller Buncher Market Vendor Landscape
Capability concentration sits with specialized forestry equipment manufacturers; scale advantage sits with diversified industrial conglomerates with forestry divisions. The vendor base organizes around three strategic archetypes: integrated cut-to-length system providers, tracked platform specialists for steep-slope terrain, and wheeled platform leaders for plantation efficiency. Competitive positioning hardens through dealer network density for parts availability and service contract bundling. Vertical integration into hydraulic component supply and backward integration into engine aftertreatment systems represent dominant competitive moves.
Among North American fabricators, John Deere Forestry and Caterpillar Inc. occupy positions anchored by broad dealer infrastructure and multi-product portfolio breadth. Tigercat Industries exemplifies the specialized independent archetype with concentrated forestry equipment focus. Komatsu Forest AB and Ponsse Plc represent European-origin specialists whose geographic positioning reflects Nordic forestry equipment manufacturing heritage. These named entities serve as anchors for understanding how capability specialization and scale breadth create distinct competitive vectors across mechanized harvesting corridors.
| Leading Market Players |
|---|
| Komatsu Forest AB |
| TimberPro Inc. |
| John Deere Forestry |
| Barko Hydraulics LLC |
| Weiler Forestry |
| Tigercat Industries |
| Ponsse Plc |
| Dougherty Forestry Manufacturing |
| Caterpillar Inc. |
| Others |
Supply Flow & Price Mechanics
Tariff exposure between Canadian steel fabricators and U.S. component suppliers determines both pricing tier spreads and supply chain shape across feller buncher manufacturing corridors. EPA Tier 4 Final aftertreatment system costs compress margins at the economy tier while premium tracked platforms absorb compliance premiums through longer replacement cycles.
Pricing Analysis
North American price spreads between Pacific Northwest and southeastern contractors reflect divergent terrain demands and transport logistics burdens. Three-tier pricing structure across premium, standard, and economy levels separates electronic-control tracked units from hydraulic wheeled configurations and legacy rebuild candidates. Cost compression in the economy tier intensifies because pre-Tier 4 Final rebuilds extend service life amid capital deferral patterns. Independent contractors operating mixed-brand fleets exhibit highest price sensitivity; integrated timberland owners prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Tariff exposure between Canadian boom fabrication facilities and U.S. hydraulic cylinder suppliers dominates supply chain risk calculus for North American equipment manufacturers. Component sourcing draws from Finnish electronic control module specialists, Japanese high-pressure hydraulic valve producers, and domestic steel plate rolling operations. Single-source vulnerability concentrates in specialized felling head castings produced by limited qualified foundries. Distribution runs through manufacturer-authorized dealer networks with captive parts warehousing rather than open wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feller buncher market positioning rests on regulatory entrenchment as Tier 4 Final certification timelines and dealer network density create switching costs that cement incumbent relationships across mechanized harvesting corridors.
For Market Incumbents: Harden defensive positioning through backward integration into hydraulic component supply and captive remanufacturing capacity for Tier 4 Final aftertreatment modules. Expand dealer service contract bundling to capture independent contractor maintenance volume threatened by mobile diagnostic technician entrants. Prioritize electronic control architecture R&D to widen the capability gap against hydraulic-system rebuild competitors. For New Entrants and Emerging Players: Build out teleoperation and semi-autonomous control system offerings targeting British Columbia and Washington State steep-slope contractors facing OSHA safety directive compliance pressures. Quebec hardwood operations present the most penetrable geography given undermechanized fleet status and tightening labor availability. Pursue forwarder-feller buncher system bundling as the primary go-to-market angle to displace standalone unit procurement relationships. For Investors and Strategic Acquirers: EPA Tier 4 Final implementation reshapes the acquisition landscape toward electronic-control specialists with validated engine integration capabilities and established dealer service infrastructure. Long-term viability favors vertically integrated manufacturers with captive hydraulic component supply and multi-terrain platform portfolios. Monitor teleoperation pilot program conversion rates from demonstration to fleet deployment as the critical inflection signal for automation technology maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Dealer Network Expansion | John Deere Forestry's dense parts availability infrastructure anchors contractor loyalty in remote logging camps. |
| Electronic Control Integration | Ponsse Plc's CAN-bus architectures enable precision stump height consistency for sawlog grade recovery premiums. |
| Tracked Platform Specialization | Komatsu Forest AB's high-flotation undercarriage configurations dominate Pacific Northwest slope grades exceeding 35%. |
| Cut-to-Length System Bundling | Forwarder-feller buncher pairings create sticky contractor relationships beyond standalone equipment transactions. |
| Teleoperation Capability Development | Remote operation pilots in British Columbia compress the safety-productivity trade-off for steep-slope applications. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of equipment registration databases, customs trade records, and SEC manufacturer filings across the forestry machinery sector. Primary interviews engaged fleet managers at commercial timber harvesters, maintenance directors at independent logging contractors, procurement leads at integrated timberland owners, and aftermarket service heads at regional dealer operations. Secondary validation drew from EPA certification records, provincial forest road weight limit enforcement data, and industry association equipment shipment reports. Bottom-up unit demand estimates triangulated against top-down manufacturer revenue segmentation.
Forecast inputs include replacement cycle timing by equipment vintage, plantation rotation intensification rates, and regulatory compliance cost pass-through elasticity. Segmentation modeling spans undercarriage configuration, control system architecture, end-user scale tier, and application purpose across the projection horizon. CAGRs were derived from slope analysis of historical equipment shipment trajectories and forward-looking contractor capital expenditure surveys. Industry-specific inputs incorporate EPA Tier 4 Final adoption curves and steep-slope mechanization penetration thresholds.
Stress conditions across steel input cost volatility, hydraulic component lead time extension, and diesel-electric hybrid technology maturation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and contractor capital availability. Wildfire mitigation funding durability and labor availability constraints in eastern Canadian hardwood regions represent specific revision risks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Horse Drawn Farming Equipment Market
Agricultural Equipment
Greenhouse Heaters Market
Agricultural Equipment
Commercial Vegetable Chopper Market
Agricultural Equipment
Farm Equipment Market
Agricultural Equipment
Australia Bird Feeder Market
Agricultural Equipment
Billhook Market
Agricultural Equipment
Agricultural Trailer Market
Agricultural Equipment
Sheep Shearing Equipment Market
Agricultural Equipment
Global Infrared Heater for Agriculture Market
Agricultural Equipment
Food Bucket Elevators Market
Agricultural Equipment
Battery Powered Sprayer Market
Agricultural Equipment
Flexible Silos Market
Agricultural Equipment
Fishing Net Market
Agricultural Equipment
Oil Expellers Market
Agricultural Equipment
Battery Powered Cultivators Market
Agricultural Equipment
Plow Folding System Market