
 Automotive EV Charging Adapters Market | 2026-2036
Automotive EV Charging Adapters Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive EV Charging Adapters Market Analysis
SAE J1772 and IEC 61851 qualification cycles is unwinding competitive access across the adapter supply base. Siemens AG leverages its certification breadth to anchor European public charging deployments. Schneider Electric sustains R&D intensity across multi-standard conversion protocols. Tesla Inc. dominates proprietary-to-open-connector bridging through its integrated vehicle-charger ecosystem.
Automotive EV charging adapters are electromechanical interface devices that translate power delivery protocols between discharging infrastructure and onboard vehicle inlets, typically managing currents from 16A to 500A while converting AC to DC signaling paths. Their primary commercial purpose is eliminating connector incompatibility that strands electric vehicles at mismatched charging stations. Combined Charging System adapters command the largest installed base among product types due to automaker consolidation around the standard in North America and Europe. Fleet Charging applications generate the fastest volume acceleration as logistics operators centralize depot infrastructure around multi-vehicle adapter banks. Connector technology segments show margin concentration at Panduit and Amphenol due to their control over high-amperage contact materials rated for 10,000+ insertion cycles.
FCC Part 15 governs electromagnetic emissions from adapter control electronics in the United States, while the EU Green Deal and CE marking framework mandate recyclability and efficiency thresholds for units sold across member states. China's GB standards and MIIT certification requirements create a parallel compliance track that shapes export manufacturing priorities. Stakeholders must monitor whether NACS adoption in North America fragments the adapter landscape or consolidates around a single dominant standard.
Market Dynamics
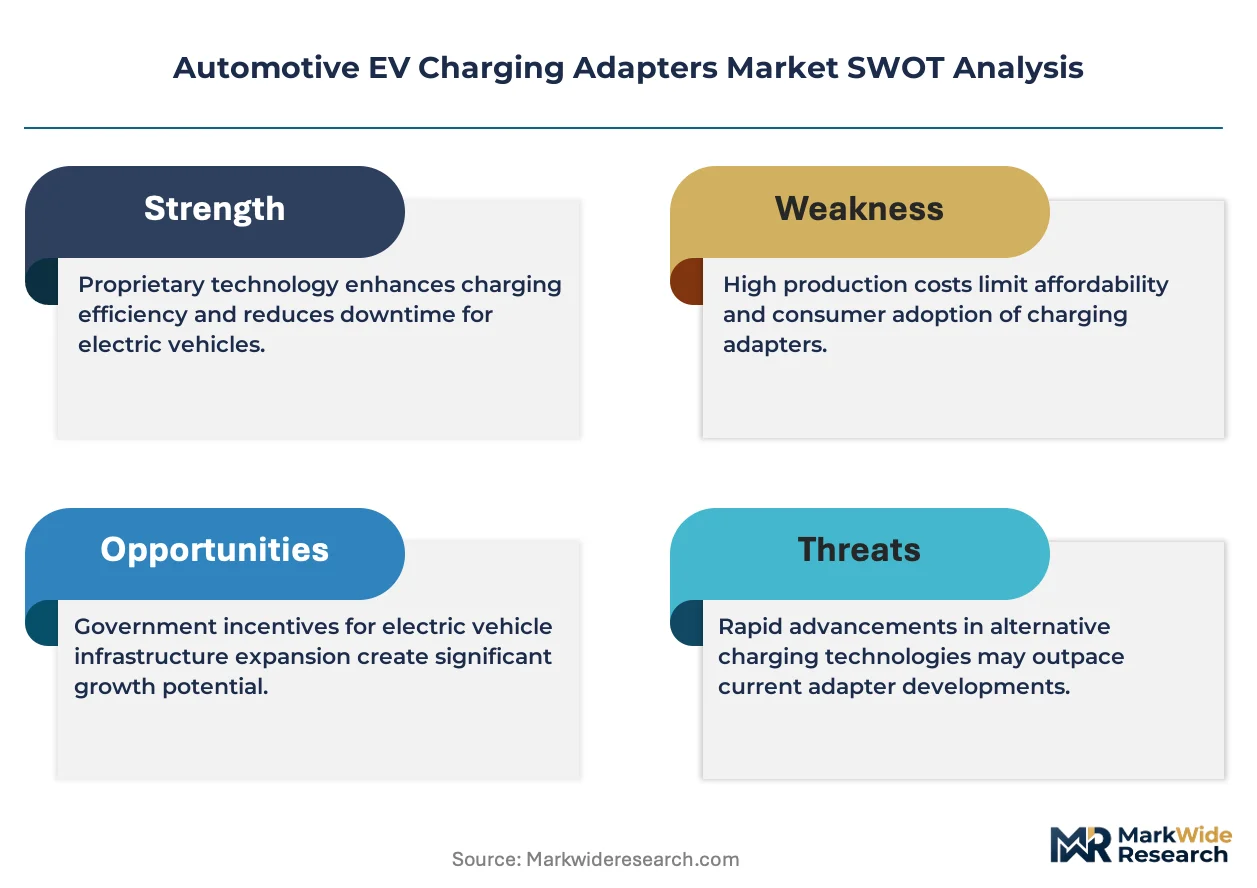
Standard fragmentation between NACS, CCS, and CHAdeMO protocols is forcing adapter manufacturers to engineer multi-standard compatibility into single units, compressing development cycles and elevating certification costs across the supply base.
Growth Catalysts
- Fleet depot electrification mandates:Commercial transport operators in Germany and the Netherlands face binding EU Green Deal targets requiring interoperable charging banks at logistics hubs by mid-decade.
- SAE J1772 certification acceleration:Streamlined qualification timelines in North America are unlocking supplier entry for mid-tier electromechanical specialists previously locked out by protracted approval cycles.
- Copper-aluminum hybrid contact materials:Advanced metallurgy rated for 500A continuous draw is extending adapter lifecycle economics in high-throughput fleet applications.
Market Restraints
- Copper price volatility:Contact material input costs swing with commodity markets, squeezing margin structures for manufacturers without captive smelter relationships.
- Connector supplier concentration:High-amperage contact assembly capacity clusters with three specialized vendors in East Asia, creating single-source vulnerability for tier-one adapter producers.
- GB standard divergence:China's MIIT certification track requires parallel engineering investments that fragment R&D budgets for export-oriented manufacturers.
Strategic Opportunities
- India commercial fleet retrofit:BIS standards alignment with IEC 61851 is opening depot infrastructure contracts for multi-standard adapter banks as state transport corporations electrify bus networks.
- V2G bidirectional integration:Convergence between charging adapters and vehicle-to-grid inverters creates bundled hardware opportunities at utility-scale pilot sites.
- Direct-to-fleet digital procurement:Adapter OEMs are bypassing traditional distribution through API-integrated procurement platforms serving national logistics operators.
Industry Challenges
- EMC compliance engineering scarcity:FCC Part 15 and CE marking electromagnetic compatibility expertise concentrates with specialized test houses, extending product launch timelines.
- Legacy CHAdeMO inventory stranding:Adapter manufacturers holding pre-NACS certification stock face write-down pressure as North American automaker commitments consolidate around the Tesla-derived standard.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive EV Charging Adapters Market |
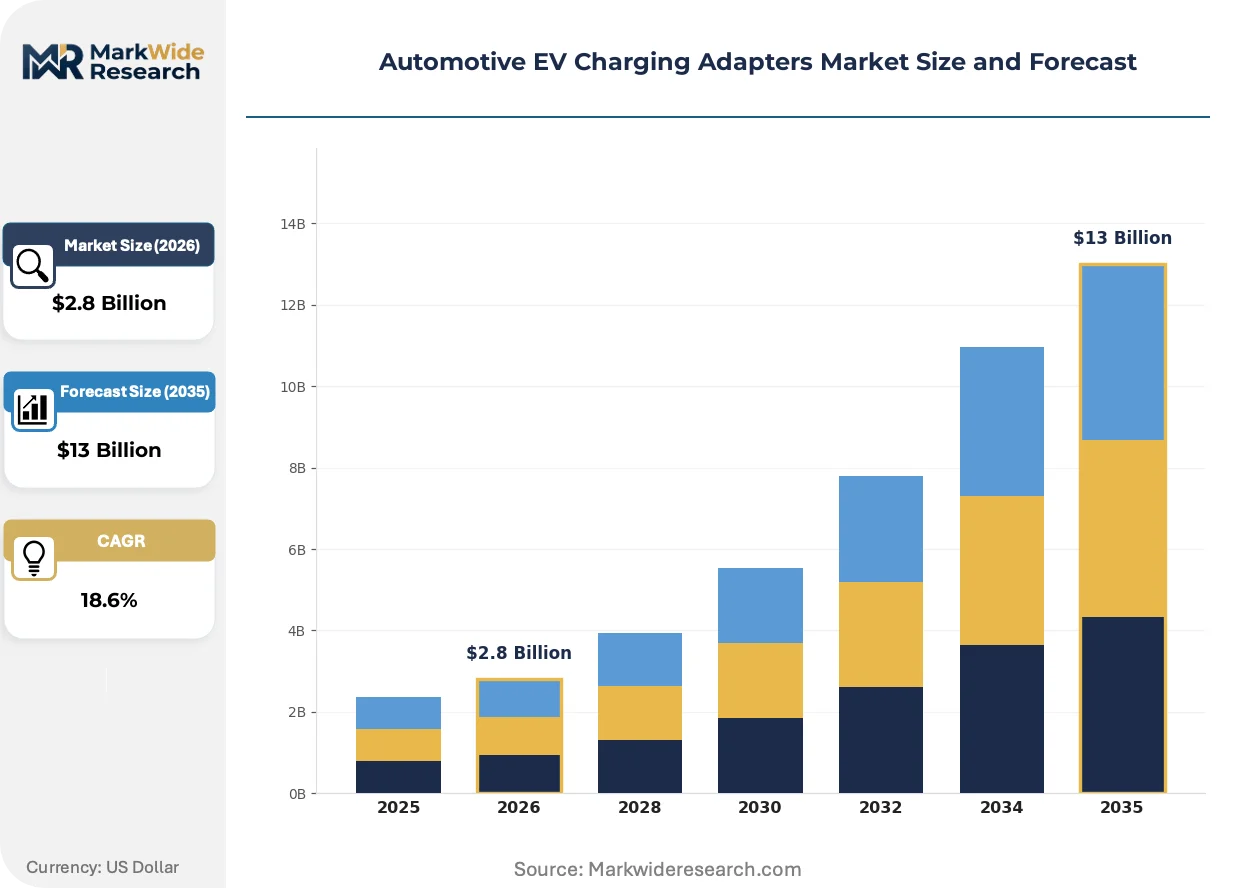
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Type 1, Type 2, CHAdeMO, Combined Charging System, GB/T Connector Technology: Panduit, LEMO, Amphenol, Phoenix Contact, TE Connectivity Application: Residential Charging, Public Fast Charging, Fleet Charging, Workplace Charging End User: OEMs, Charging Network Operators, Energy Providers, Independent Service Providers |
| Companies Covered | Siemens AG, Schneider Electric, Robert Bosch GmbH, Pod Point, Shanghai Zencar Industry Co. Ltd, ChargePoint, Inc., Eaton Corporation plc, Tesla Inc., ABB Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive EV Charging Adapters Market Emerging Trajectories
Silicon carbide power electronics and intelligent thermal management are converging to redefine adapter form factors and efficiency benchmarks, while procurement patterns shift toward specification-driven fleet contracts.
Silicon carbide MOSFET arrays now manage DC fast-charging conversion losses in compact adapter housings previously requiring liquid cooling architectures. Fleet operators in California and Texas are specifying these units for 350kW depot installations. The technology is miniaturizing thermal management footprints from 2-liter volumes to sub-500ml packages, enabling glovebox-stowable emergency adapters.
The EU Green Deal's Ecodesign for Sustainable Products Regulation now mandates modular repairability and recyclability disclosures for charging infrastructure components sold across member states. Adapter manufacturers must redesign housings for tool-free contact replacement and submit material passports to ECHA databases. German industrial corridor deployments are prioritizing suppliers with verified circular economy compliance ahead of the 2027 enforcement window.
Specification-led procurement now dominates fleet charging infrastructure, with technical teams at logistics operators directly authoring connector compatibility requirements that bypass traditional automotive distribution channels. Tier-one adapter vendors are responding with embedded engineering partnerships at depot design stage. This pattern is most pronounced in the Netherlands, where national freight electrification programs consolidate purchasing through centralized transport authority tenders.
Automotive EV Charging Adapters Market Segmentation
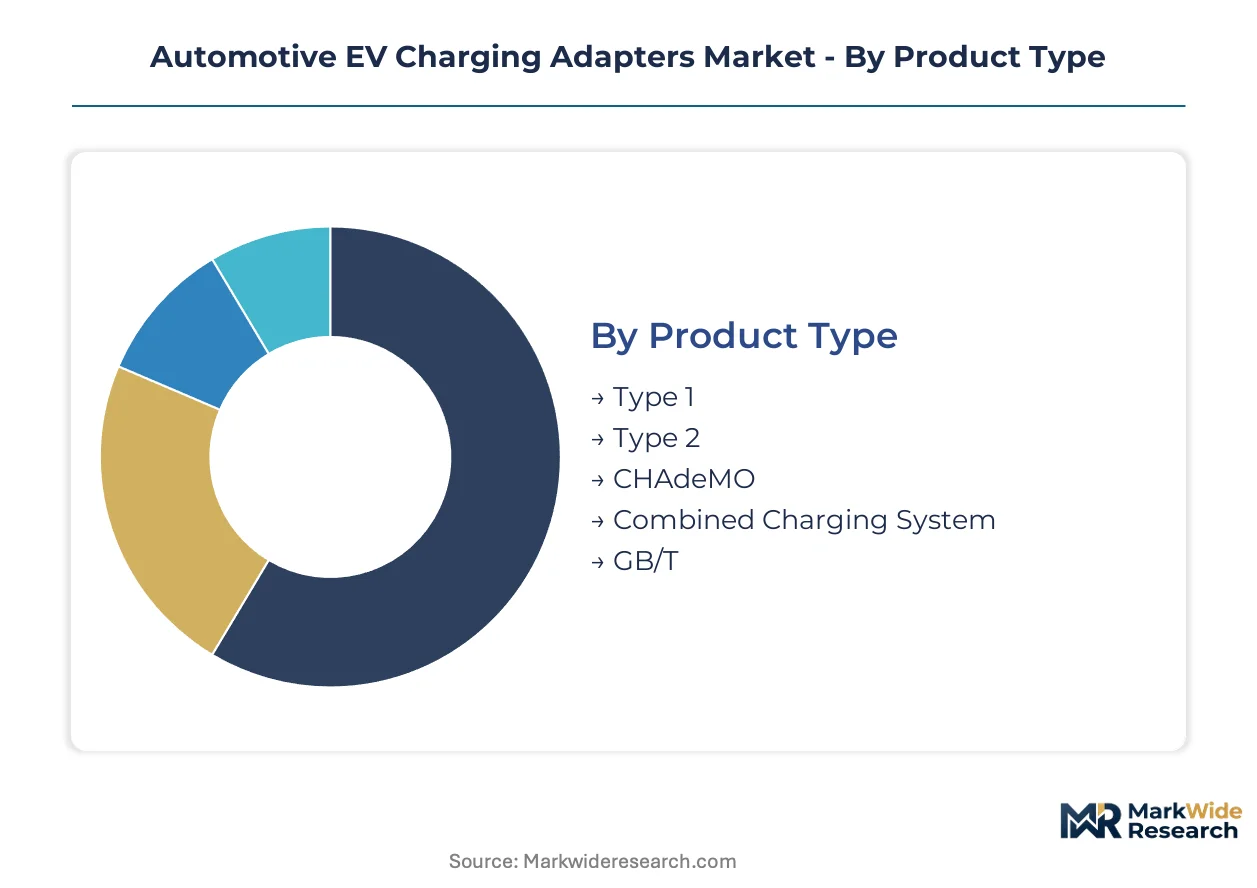
Adapter demand fragments across incompatible charging protocols, forcing procurement teams to map product specifications against depot infrastructure and vehicle fleet composition. Each segmentation dimension reveals distinct margin structures and certification barriers that shape supplier selection.
Product Type:
Combined Charging System adapters dominate export manufacturing from Germany and China, while Type 1 units remain concentrated in domestic North American supply chains.
- Combined Charging System:These adapters integrate AC and DC charging paths through dual-pin configurations rated for 350kW peak delivery. Demand clusters at German automaker charging depots and Netherlands logistics hubs where EU Green Deal mandates require multi-standard interoperability.
- Type 2:Three-phase AC charging up to 43kW defines this European-standard interface. Fleet operators in Germany and France specify these units for workplace and depot installations where IEC 61851 compliance is mandatory.
- Type 1:Single-phase J1772 connectors serve residential and light commercial applications across North America.
- CHAdeMO:DC fast-charging protocol retains installed base in Japanese vehicle fleets and early-generation European deployments.
- GB/T:China's national standard requires parallel engineering for export manufacturers targeting MIIT certification.
Combined Charging System holds the largest share; momentum sits with GB/T as Chinese OEMs expand European vehicle sales.
Connector Technology:
High-amperage contact assembly capacity concentrates with vendors controlling metallurgy for 10,000+ insertion cycles, creating tiered procurement economics.
- Amphenol:Copper-aluminum hybrid contacts rated for 500A continuous draw anchor fleet charging specifications in Texas and California depot tenders. The company's captive smelter relationships buffer margin pressure from commodity volatility.
- Panduit:Modular contact architectures enable tool-free field replacement demanded by EU Ecodesign recyclability mandates. German industrial corridor deployments specify these units ahead of 2027 enforcement windows.
- LEMO:Precision-machined connectors serve high-reliability applications in Swiss and Nordic public charging networks.
- Phoenix Contact:Industrial-grade terminal blocks integrate with depot power distribution systems across Netherlands logistics hubs.
- TE Connectivity:Automotive-qualified contact systems bridge vehicle OEM and charging infrastructure supply chains.
Amphenol commands premium positioning; Panduit is climbing fastest on circular economy compliance.
Application:
Specification-led procurement now separates high-throughput fleet deployments from consumer-facing installations with divergent technical requirements.
- Fleet Charging:Centralized adapter banks at logistics depots require 24/7 availability and multi-vehicle compatibility. Netherlands national freight electrification programs consolidate purchasing through centralized transport authority tenders with embedded engineering partnerships.
- Public Fast Charging:350kW DC installations along German autobahn corridors and California interstate corridors demand silicon carbide thermal management in compact form factors.
- Residential Charging:Single-vehicle overnight charging dominates suburban North American and European household installations.
- Workplace Charging:Multi-employee sites in France and Germany specify mid-speed AC units with load-balancing capabilities.
Fleet Charging anchors volume expansion; Public Fast Charging is gaining share fastest on infrastructure subsidy deployment.
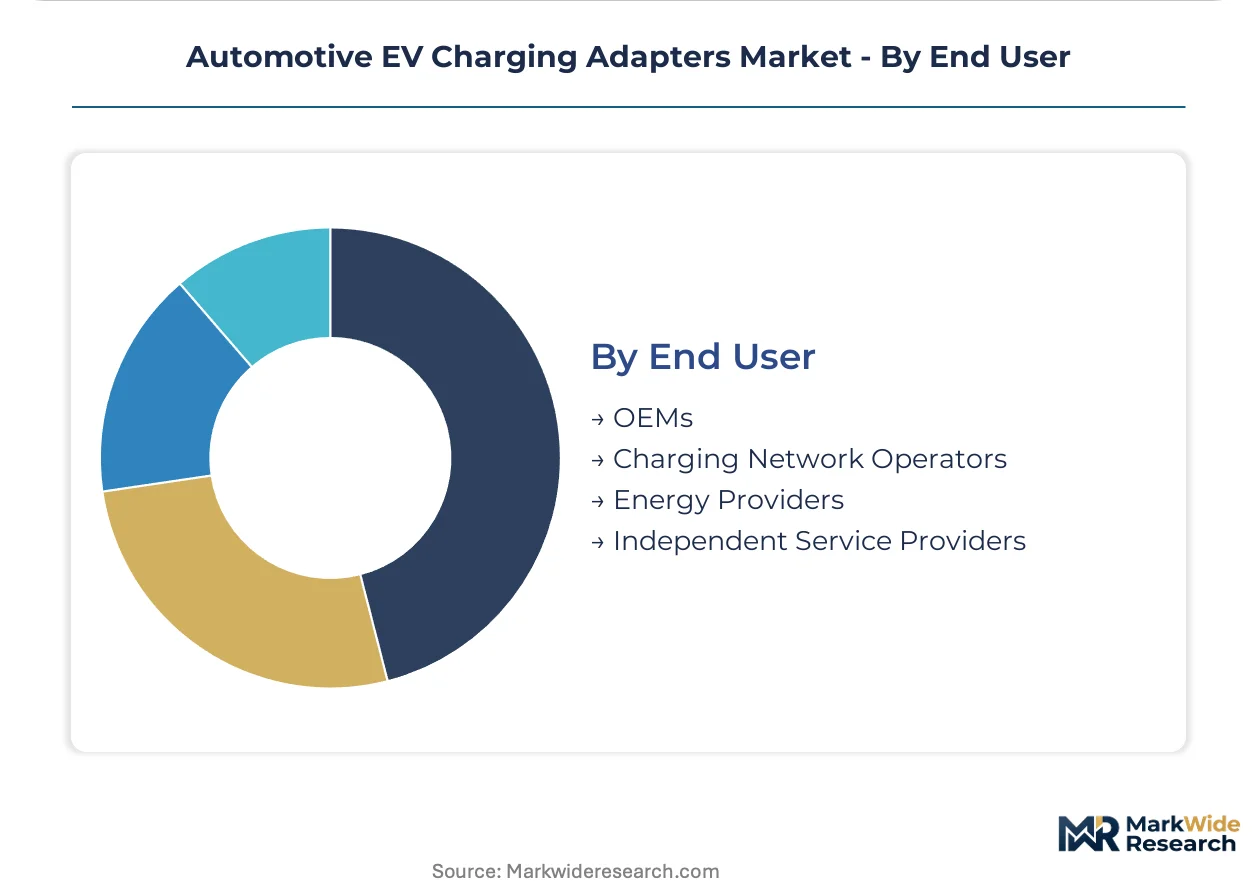
End User:
Direct procurement relationships now bypass traditional distribution channels as technical teams author compatibility specifications.
- Charging Network Operators:Ionity, Fastned, and Electrify America specify multi-standard adapters for public corridor deployment with API-integrated remote monitoring. These operators consolidate European and North American purchasing through framework agreements with tier-one electromechanical vendors.
- OEMs:Vehicle manufacturers bundle adapters with new vehicle sales or operate captive charging networks requiring proprietary-to-open bridging hardware.
- Energy Providers:Utility companies at Texas and California pilot sites bundle adapters with V2G bidirectional inverter installations.
- Independent Service Providers:Regional installers and maintenance contractors supply replacement units and retrofit services.
Charging Network Operators hold the largest share; Energy Providers are expanding most quickly on grid-integration pilots.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's autobahn charging corridor and the Netherlands' port electrification grid anchor European adapter demand. California's interstate fast-charging backbone and China's MIIT-certified manufacturing clusters shape supply-side dynamics. India's state transport electrification programs and Japan's CHAdeMO legacy infrastructure complete the geographic map.
United States
The Biden Administration's NEVI program funds 350kW corridor installations across Texas and California interstate routes. FCC Part 15 governs electromagnetic emissions from adapter control electronics. Detroit's automotive engineering cluster coordinates OEM-agnostic adapter specifications for fleet charging depots.
Germany
The KBA enforces type approval for charging infrastructure components under EU Green Deal Ecodesign mandates. Siemens AG anchors industrial corridor deployments along the Rhine-Ruhr logistics belt. Bavaria's automaker charging networks drive multi-standard adapter procurement for interoperable public stations.
China
MIIT certification requirements and GB/T standards create parallel compliance tracks for export manufacturers. Shanghai Zencar Industry Co. Ltd exemplifies Yangtze River Delta production concentration. Shenzhen's electronics manufacturing base supplies high-amperage contact assemblies for global adapter OEMs.
Netherlands
National freight electrification programs consolidate purchasing through centralized transport authority tenders. CE marking and REACH compliance shape adapter material selection for circular economy mandates. Rotterdam's port electrification grid requires bidirectional V2G-compatible adapter banks for logistics fleets.
India
BIS standards alignment with IEC 61851 opens depot infrastructure contracts for state transport corporations. The PLI scheme incentivizes domestic manufacturing of charging components. Maharashtra's bus network electrification drives multi-standard adapter bank procurement for centralized depots.
Automotive EV Charging Adapters Market Vendor Landscape
Listed leaders compete with private specialists across certification breadth and manufacturing scale. Siemens AG and ABB Group leverage public market capital for R&D intensity across multi-standard protocols. The vendor base fragments across three archetypes: diversified industrial conglomerates, pure-play charging specialists, and automotive-integrated technology platforms. Capacity expansion and strategic partnerships dominate competitive moves as manufacturers secure high-amperage contact supply.
Within the diversified industrial tier, Siemens AG and Schneider Electric exemplify European engineering conglomerates with captive certification capabilities. Tesla Inc. occupies a distinct position bridging proprietary vehicle ecosystems with open-connector infrastructure. Robert Bosch GmbH anchors German automotive supplier integration into charging hardware. These three represent divergent strategic positions: standards-setting platform control, vertical vehicle-charger integration, and tier-one automotive supply chain embeddedness.
| Leading Market Players |
|---|
| Siemens AG |
| Schneider Electric |
| Robert Bosch GmbH |
| Pod Point |
| Shanghai Zencar Industry Co. Ltd |
| ChargePoint, Inc. |
| Eaton Corporation plc |
| Tesla Inc. |
| ABB Group |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with East Asian contact assembly vendors lock in copper-aluminum hybrid material access while capping unit cost exposure for tier-one adapter producers serving German fleet charging tenders. These arrangements bind pricing visibility to certification-grade volume commitments across SAE J1772 and IEC 61851 qualification tiers.
Pricing Analysis
Certification level (SAE J1772/IEC 61851/GB/T-grade) creates the primary spread between premium fleet-specification units and economy residential adapters. Three-tier pricing structure separates CE-marked depot banks from mid-grade workplace installations and unmarked aftermarket alternatives. Cost compression in economy tiers is intensifying because copper price volatility squeezes margin structures for manufacturers without captive smelter relationships. Fleet operators at Netherlands logistics hubs exhibit lowest price sensitivity due to EU Green Deal mandate compliance deadlines, while independent service providers in residential channels face acute margin pressure from commoditized Type 1 imports.
Supply Chain Analysis
Strategic stockpiling of high-amperage contact materials dominates inventory strategy among tier-one adapter OEMs buffering against copper commodity swings and single-source vendor concentration. Manufacturing gravity centers on China, Germany, and South Korea, with Yangtze River Delta facilities feeding global export demand and Rhine-Ruhr clusters serving EU depot infrastructure. Raw material dependencies rest on copper-aluminum hybrid metallurgy, silicon carbide MOSFET arrays, and flame-retardant polymer housings. Single-source vulnerability concentrates at three specialized East Asian contact assembly vendors. Distribution runs through API-integrated procurement platforms serving national logistics operators alongside traditional electromechanical distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adapter lifecycle service contracts—spanning contact replacement, firmware updates, and circular economy compliance documentation—are expanding faster than hardware unit sales as EU Ecodesign mandates deepen recurring-revenue attachment rates.
For Market Incumbents: Secure captive supply of 500A-rated copper-aluminum hybrid contact materials through backward integration or long-term offtake with Yangtze River Delta metallurgy specialists. Defend against NACS standard fragmentation by accelerating multi-protocol R&D across CCS and GB/T conversion architectures. Certification breadth at Siemens AG and Schneider Electric demonstrates how SAE J1772 and IEC 61851 portfolio depth anchors European public charging deployment preference. For New Entrants and Emerging Players: Fleet depot retrofit service gaps—where incumbents under-serve legacy CHAdeMO infrastructure migration—offer white-space entry at Maharashtra state transport corporations and Netherlands port electrification grids. Target India's BIS-aligned IEC 61851 certification track as the most penetrable geography given PLI scheme manufacturing incentives and concentrated state bus network procurement. Pursue direct-to-fleet digital procurement platform integration as the primary go-to-market angle, bypassing traditional automotive distribution channel capture. For Investors and Strategic Acquirers: Pure-play charging hardware specialists with captive certification capabilities and modular repairability IP represent the highest-conviction acquisition archetype for consolidation plays. Long-term viability across the analysis window hinges on circular economy compliance infrastructure and V2G bidirectional integration roadmaps. Monitor NACS adoption velocity across North American OEM commitments as the critical inflection signal; material standard consolidation or fragmentation will reshape competitive economics decisively.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Standard Certification Expansion | Broadens addressable market across EU Green Deal interoperability mandates and NACS transition uncertainty. |
| Copper-Aluminum Hybrid Metallurgy Investment | Secures 500A continuous-draw contact supply for high-throughput fleet depot specifications in Germany and Texas. |
| Circular Economy Compliance Infrastructure | Enables tool-free modular repairability and ECHA material passport submission ahead of 2027 EU enforcement windows. |
| V2G Bidirectional Integration Development | Creates bundled hardware-software offerings at California and Netherlands utility-scale pilot sites. |
| API-Integrated Fleet Procurement Platform Partnership | Bypasses traditional distribution channels to capture Netherlands national freight electrification program tenders. |
Methodological Framework
A standing panel of fleet charging procurement directors, Tier 1 supplier platform engineers, aftermarket distributor operations heads, and EMC compliance test house specialists provided ongoing calibration against secondary validation from SEC filings, customs trade databases, IHS Markit vehicle registration data, and EU Ecodesign regulatory filings. Bottom-up unit demand modeling across fleet, public, residential, and workplace application segments triangulated with top-down market sizing from charging infrastructure deployment pipelines.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type (CCS, Type 2, Type 1, CHAdeMO, GB/T), connector technology tier, application throughput requirement, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to fleet electrification mandate timelines and automaker platform standardization commitments. Industry-specific inputs incorporated copper price futures curves, certification cycle duration distributions, and depot infrastructure subsidy disbursement trajectories.
Forecasts assume regulatory continuity in EU Ecodesign enforcement, FCC Part 15 electromagnetic compliance, and China's MIIT certification track; material policy shifts would require re-modeling. Specific risk factors include NACS standard adoption velocity, copper commodity volatility spikes, and CHAdeMO inventory stranding at legacy adapter manufacturers. Revision becomes warranted when NACS penetration crosses threshold dominance in North American OEM platform commitments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle Charging Pile Cables Market
Electric Vehicle Charging
Portable Charging Units Market
Electric Vehicle Charging
Electric Vehicle Charging Management Software Market
Electric Vehicle Charging
Solar-Based Electronic Vehicle Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Infrastructure Market
Electric Vehicle Charging
Western Europe Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
Europe EV Charging Stations Market
Electric Vehicle Charging
AC Electric Vehicle Charging Station Market
Electric Vehicle Charging
North America EV Charging Stations Market
Electric Vehicle Charging
Germany EV Charging Infrastructure Market
Electric Vehicle Charging
Europe Electric Vehicle Chargers Market
Electric Vehicle Charging
Electric Vehicle DC Fast Charging Station Market
Electric Vehicle Charging
Public EV Charger Market
Electric Vehicle Charging
Electric Vehicle Coin Charging Station Market
Electric Vehicle Charging
EV Charging Cables Market
Electric Vehicle Charging
Global EV Charger Market