
 Thermal Spray Guns Market | 2026-2036
Thermal Spray Guns Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Spray Guns Market Analytics
ISO 14922 certification for thermal spray quality assurance is reorganizing vendor qualification across the supply base. Oerlikon Metco leverages its integrated powder-to-equipment portfolio to control specification workflows for aerospace primes. Linde PLC sustains dominance in industrial gas supply chains that feed HVOF and plasma spray operations worldwide. Höganäs anchors the powder feedstock segment through captive atomization capacity and metallurgical R&D intensity.
Thermal spray guns are precision devices that propel molten or semi-molten material particles at high velocity onto substrates, typically operating at temperatures between 3,000°C and 16,000°C depending on the process, to build protective coatings against wear, corrosion, and thermal fatigue. The equipment serves critical functions in extending component life cycles across rotating machinery, turbine blades, and industrial infrastructure. HVOF guns command premium positioning due to their dense, low-porosity carbide coatings demanded by aerospace and energy end users. Cold spray technology represents the fastest-expanding technology segment as solid-state deposition avoids oxidation and phase changes for temperature-sensitive substrates. Plasma spray retains the largest installed base across repair and surface modification applications where ceramic thermal barrier coatings remain essential.
The US FAA and EPA jointly shape market access through airworthiness directives for coated flight-critical components and emissions controls for spray booth operations. Europe's REACH regulation and F-Gas Directive constrain feedstock chemistry and propellant gas selection, pushing OEMs toward closed-loop systems and lower-GWP alternatives. China's GB standards and MEE environmental enforcement are raising entry barriers for imported equipment while accelerating domestic certification requirements. Stakeholders must monitor how evolving emissions frameworks in the EU and North America redirect capital toward electric-arc and cold spray modalities that reduce process gas intensity.
Market Dynamics
ISO 14922 certification requirements are restructuring vendor qualification protocols across aerospace supply chains, forcing equipment manufacturers to integrate quality assurance systems directly into gun design specifications rather than treating certification as a post-sale add-on.
Growth Catalysts
- HVOF gun demand in aerospace:Turbine engine OEMs require dense carbide coatings for rotating components, pulling premium equipment into production lines.
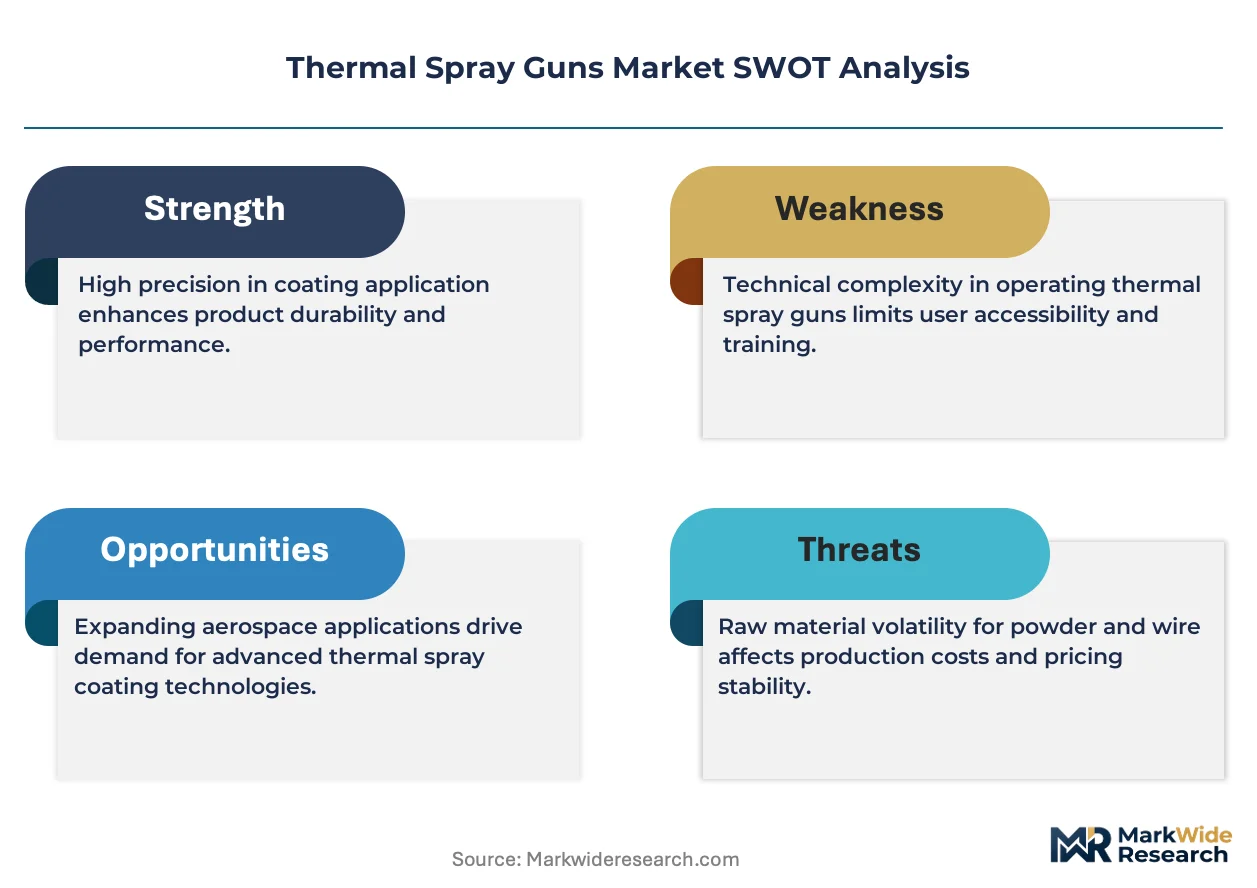
- F-Gas Regulation in Europe:The EU's tightening emissions standards for spray processes accelerate capital deployment toward closed-loop thermal spray systems with gas recovery.
- Cold spray technology maturation:Solid-state deposition methods avoid oxidation damage to temperature-sensitive substrates, opening repair applications for magnesium and aluminum aerospace structures.
Market Restraints
- Helium supply concentration:Cold spray and plasma operations depend on helium feedstock where US and Qatar production dominates, creating price volatility exposure.
- REACH chemical constraints:Feedstock powder chemistries face progressive restriction in Europe, forcing reformulation of established coating compositions.
- High capex for automation:Robotic spray cells require seven-figure investment thresholds that exclude smaller job shops from aerospace qualification tiers.
Strategic Opportunities
- India's defense industrial corridor:Indigenous helicopter and fighter programs create localized coating capacity demand with import substitution incentives.
- Electric-arc wire spray convergence:Integration with wire-fed additive manufacturing systems opens bridge repair and infrastructure applications beyond traditional coating scope.
- Japan's carbon neutrality roadmap:METI efficiency mandates push steel mills toward thermal spray refurbishment of rolling mill rolls versus replacement casting.
Industry Challenges
- Certification timeline compression:FAA airworthiness directives for coated flight-critical components demand extensive qualification data that extends sales cycles.
- Spray booth emissions compliance:EPA and state-level air quality regulations require continuous monitoring infrastructure that raises operational complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Spray Guns Market |
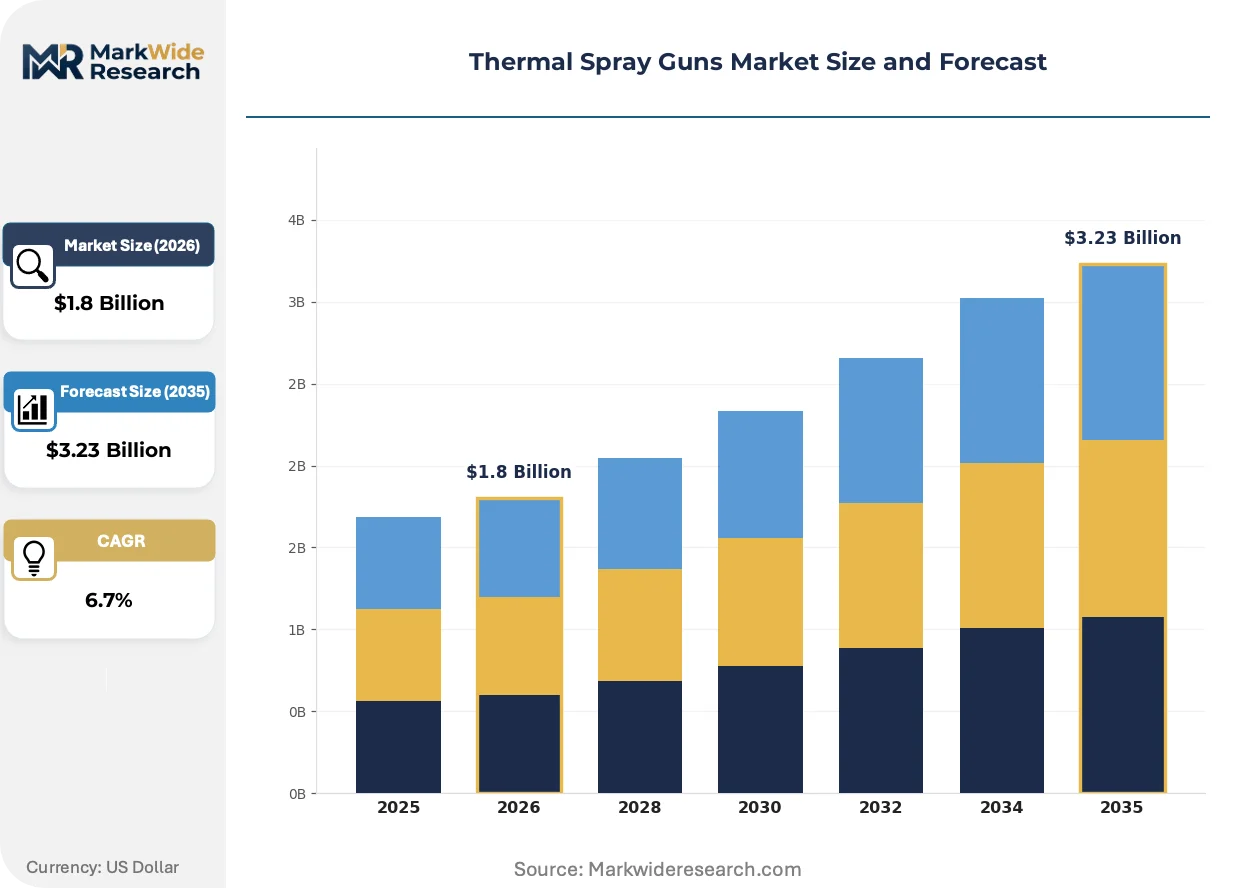
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasma Spray Guns, Flame Spray Guns, HVOF Guns, Cold Spray Guns Technology: Thermal Plasma, High Velocity Oxygen Fuel, Arc Spray, Flame Spray End User: Aerospace, Automotive, Defense, Energy Application: Coating, Repair, Surface Modification, Wear Resistance |
| Companies Covered | Oerlikon Metco, Linde PLC, Bodycote PLC, Sulzer, Kennametal Inc, Castolin Eutectic, Praxis, Höganäs, Thermal Spray Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Spray Guns Market Evolving Landscape
Cold spray technology is compressing the boundary between coating and additive manufacturing, with equipment vendors redesigning gun architectures to accommodate both deposition modes within single platform investments.
Kinetic spray systems are displacing traditional HVOF equipment in MRO facilities where substrate temperature limits prohibit molten particle impact. Aerospace depots in Germany and the US are retrofitting existing booths with portable cold spray units. The technology is displacing fixture-based preheating requirements, reducing process cycle times by eliminating thermal soak periods.
The EU F-Gas Directive is forcing propellant gas substitution across plasma spray operations, with operators trialing lower-GWP alternatives in Stuttgart and Munich industrial clusters. Equipment manufacturers face redesign pressure to accommodate modified gas chemistries without sacrificing coating density specifications. Ceramic thermal barrier coating providers in France and Italy report extended qualification timelines as they validate reformulated processes.
Service unbundling is fragmenting the traditional equipment-plus-consumables bundle, with tier-one aerospace primes demanding separate sourcing of guns, powder, and process IP. German turbine OEMs now contract coating parameters independently from hardware procurement. This pattern concentrates most visibly in Bavaria's aerospace supplier network, where multi-source strategies protect against single-vendor qualification risk.
Thermal Spray Guns Market Segmentation
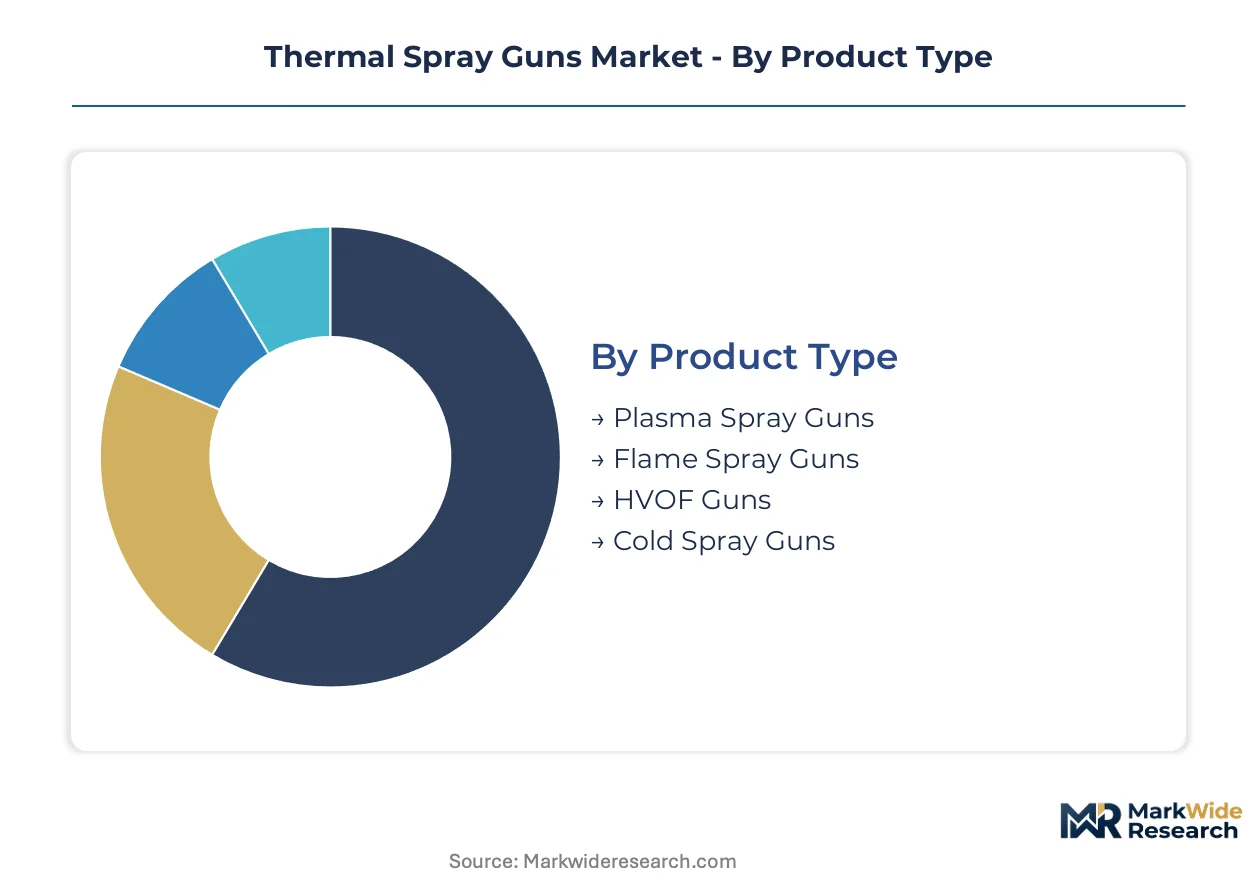
Thermal spray guns serve distinct operational profiles across deposition technologies, with equipment specifications tightly coupled to substrate material limits and coating performance requirements. Segmentation reveals how aerospace qualification tiers, energy infrastructure scale, and repair-versus-production workflows dictate procurement patterns across the supply base.
Product Type:
Equipment flows through three primary channels: OEM direct sales for aerospace production lines, distributor networks serving job shops and MRO facilities, and rental/leasing arrangements for project-based infrastructure work.
- HVOF Guns:These systems propel fuel-oxygen mixtures through convergent-divergent nozzles to achieve particle velocities exceeding 800 m/s, producing dense carbide coatings with porosity below 1%. Demand concentrates at turbine engine OEMs in Germany and the US, where FAA airworthiness directives mandate specific coating densities for rotating flight-critical components.
- Cold Spray Guns:Solid-state deposition accelerates metal powders through supersonic helium or nitrogen jets without melting, preserving substrate microstructure for temperature-sensitive magnesium and aluminum aerospace structures. Expansion concentrates in US and German MRO depots retrofitting existing spray booths with portable units to eliminate preheating cycles.
- Plasma Spray Guns:Arc-generated plasma streams reach 16,000°C, enabling ceramic thermal barrier coatings for turbine blades. Dominant installed base across repair facilities worldwide.
- Flame Spray Guns:Combustion-driven wire or powder feed systems for lower-specification corrosion protection. Common in bridge and marine infrastructure applications.
HVOF guns dominate installed base in aerospace production. Cold spray is where expansion concentrates.
Technology:
Cost tier stratification separates premium plasma and HVOF systems from commodity arc and flame equipment, with price differentials exceeding 10x between laboratory-grade and field-portable configurations.
- Thermal Plasma:DC arc or RF induction generates ionized gas streams for ceramic and refractory metal deposition. Aerospace OEMs in France and Italy specify plasma parameters for thermal barrier coating thickness uniformity on high-pressure turbine vanes. REACH chemical constraints on feedstock powders are extending qualification timelines for reformulated processes.
- High Velocity Oxygen Fuel:Internal combustion produces hypersonic gas streams for cermet and metal alloy coatings. Energy sector demand in Qatar and Saudi Arabia focuses on wear-resistant pump and valve coatings for sour gas service.
- Arc Spray:Electric arc melts twin wires for zinc-aluminum corrosion protection. Dominates infrastructure and marine applications where coating density requirements are less stringent.
- Flame Spray:Oxy-fuel combustion of wire or powder for general-purpose resurfacing. Lowest capital barrier attracts smaller job shops excluded from aerospace qualification tiers.
Thermal plasma commands premium pricing in aerospace. HVOF is gaining share fastest in energy applications.
End User:
Customer type segmentation separates specification-driven OEM procurement from price-sensitive job shop purchasing, with certification requirements creating impermeable boundaries between tiers.
- Aerospace:Turbine engine and airframe manufacturers require ISO 14922-certified equipment integrated into automated spray cells. Germany's Munich and Stuttgart industrial clusters host concentrated coating capacity for Airbus and MTU Aero Engines supply chains. F-Gas Regulation compliance is redirecting capital toward closed-loop gas recovery systems.
- Defense:Indigenous helicopter and fighter programs in India create localized demand with import substitution incentives. Coating parameters often classified, limiting vendor pool to security-cleared suppliers.
- Energy:Oil and gas operators specify HVOF coatings for downhole drilling components and pipeline valves. Qatar's North Field expansion and Saudi Aramco's gas infrastructure drive regional equipment deployment.
- Automotive:Piston ring and cylinder liner coating for high-performance engines. Lower volume intensity than aerospace, with specifications set by German and Japanese OEMs.
Aerospace dominates specification-setting. Defense is where localized capacity investment concentrates.
Application:
Volume concentration separates high-throughput production coating from intermittent repair work, with equipment utilization rates varying 5x between continuous-shift OEM lines and project-based job shops.
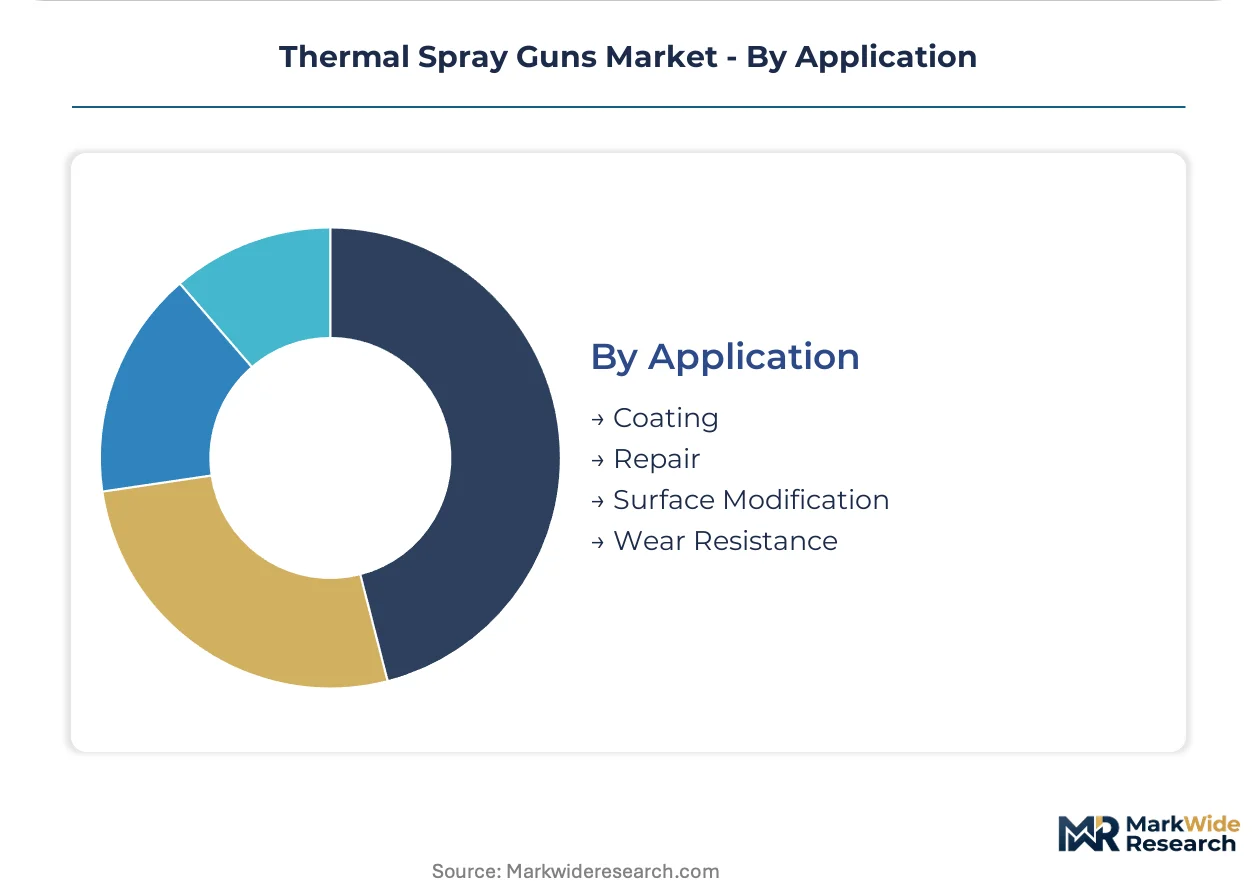
- Coating:Original equipment manufacturing applies thermal spray as a production process for new turbine blades, pistons, and pump components. Requires automated gun manipulation systems with six-axis robotic control and real-time thickness monitoring.
- Repair:MRO facilities restore worn dimensions on shafts, housings, and landing gear components. Cold spray is displacing traditional weld repair for aluminum and magnesium substrates in US Air Force depots.
- Surface Modification:Functional coatings for electrical insulation, biocompatibility, or thermal management. Medical and electronics applications specify plasma-sprayed hydroxyapatite and alumina coatings.
- Wear Resistance:Tungsten carbide and chromium carbide coatings for mining, pulp and paper, and agricultural machinery. Cyclical capital equipment demand tracks commodity price cycles.
Coating dominates production volume. Repair is where technology substitution accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and F-Gas Regulation are redirecting capital toward closed-loop thermal spray systems across industrial clusters. Equipment procurement patterns increasingly reflect national emissions enforcement intensity and aerospace supply chain localization mandates.
United States
FAA airworthiness directives for coated flight-critical components drive specification workflows at turbine engine OEMs. EPA emissions controls for spray booth operations raise operational complexity for job shops. Aerospace depots in California and Texas retrofit existing facilities with portable cold spray units to eliminate preheating cycles on aluminum structures.
Germany
Industrial clusters around Munich and Stuttgart concentrate coating capacity for Airbus and MTU Aero Engines supply chains. REACH chemical constraints on feedstock powders extend qualification timelines for reformulated processes. Bavaria's aerospace supplier network demands separate sourcing of guns, powder, and process IP to mitigate single-vendor qualification risk.
China
GB standards and MEE environmental enforcement raise entry barriers for imported equipment while accelerating domestic certification requirements. State-directed capacity expansion targets turbine blade coating for indigenous aero-engine programs. Yangtze River Delta industrial zones prioritize plasma spray equipment localization to reduce import dependency.
India
Indigenous helicopter and fighter programs create localized coating capacity demand with PLI scheme import substitution incentives. Defense procurement security clearance requirements limit vendor pools for classified coating parameters. Maharashtra and Karnataka defense industrial corridors attract equipment deployment for rotorcraft and combat aircraft MRO.
Qatar
North Field gas infrastructure expansion specifies HVOF coatings for sour gas service in downhole drilling components and pipeline valves. National hydrocarbon investment programs prioritize wear-resistant coating capacity for energy sector maintenance. Doha-based procurement concentrates on premium equipment bundles for continuous-shift production environments.
Thermal Spray Guns Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive powder production and equipment manufacturing capabilities. The supply base organizes around three strategic archetypes: integrated powder-to-equipment portfolios, industrial gas supply chain anchors, and specialized coating service providers. Consolidation pressure intensifies as aerospace primes unbundle equipment from consumables sourcing. Dominant competitive moves include backward integration into feedstock atomization and geographic expansion into defense-industrial corridors.
Within the integrated portfolio tier, Oerlikon Metco and Höganäs represent archetypes of upstream control over specification workflows. Oerlikon Metco exemplifies the powder-to-equipment model through its Swiss-based conglomerate structure. Höganäs anchors metallurgical R&D intensity for feedstock development. Linde PLC occupies a distinct position as an industrial gas supplier sustaining dominance in propellant supply chains for HVOF and plasma spray operations worldwide.
| Leading Market Players |
|---|
| Oerlikon Metco |
| Linde PLC |
| Bodycote PLC |
| Sulzer |
| Kennametal Inc |
| Castolin Eutectic |
| Praxis |
| Höganäs |
| Thermal Spray Technologies |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day lead times for HVOF gun nozzle assemblies concentrate pricing power with Swiss and German equipment manufacturers who control specification workflows for aerospace primes. This inventory compression feeds directly into premium tier positioning, where ISO 14922-certified systems command substantial markups over uncertified alternatives.
Pricing Analysis
Certification level (ISO 14922, CE marking for European compliance) creates the primary spread between equipment tiers. Three-tier pricing structure across premium, standard, and economy levels segments the market: automated aerospace-grade cells with robotic integration anchor the top tier, manual HVOF guns for energy infrastructure occupy the mid-band, and portable flame spray units serve price-sensitive job shops. Pricing pressure stems from helium feedstock volatility for cold spray operations, compressing margins on gas-intensive deposition systems. Defense procurement exhibits lowest price sensitivity due to security clearance barriers limiting vendor pools, while bridge and marine contractors demonstrate acute cost consciousness.
Supply Chain Analysis
Forty-five-day inventory cycles for tungsten carbide powder feedstock expose coating job shops to spot price swings in Germany, Sweden, and China's Yangtze River Delta manufacturing zones. Equipment assembly draws from precision-machined nozzle components sourced from Switzerland, high-pressure gas regulators from Germany, and ceramic insulator assemblies from Japan. Single-source vulnerability concentrates in helium supply chains where Qatar and US production dominance creates price volatility exposure. Distribution runs through OEM direct sales for aerospace qualification tiers, regional distributors serving MRO facilities, and rental channels for project-based infrastructure deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal spray gun demand sits in early-cycle expansion as cold spray technology penetrates temperature-sensitive repair applications previously served by welding. Solid-state deposition methods are compressing adoption timelines across aerospace MRO facilities.
For Market Incumbents: Compound defensive positioning through captive atomization capacity for feedstock powders and accelerated certification investment for EU F-Gas Regulation compliance. Cold spray technology maturation threatens traditional HVOF installed bases in repair applications. Backward integration into gas recovery systems protects margin structures against propellant cost volatility. For New Entrants and Emerging Players: Anchor in India's defense industrial corridor where PLI scheme incentives and security clearance requirements create localized vendor selection pools. Cold spray retrofit kits for existing spray booths represent the most penetrable white-space target. Pursue equipment-leasing models with process parameter training bundles to bypass capital barriers excluding smaller job shops. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because aerospace prime unbundling of equipment from consumables sourcing concentrates supplier qualification risk and rewards integrated powder-to-equipment portfolios. Target mid-tier specialists with captive metallurgical R&D and established FAA airworthiness directive compliance track records. Monitor helium supply contract renegotiation cycles as inflection indicators for cold spray equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Atomization | Höganäs and Oerlikon Metco control specification workflows through captive powder production. |
| Closed-Loop Gas Recovery System Deployment | EU F-Gas Regulation compliance redirects capital toward lower-GWP propellant alternatives in Stuttgart and Munich clusters. |
| Cold Spray Platform Architecture Redesign | Equipment vendors accommodate both coating and additive manufacturing deposition modes within single investments. |
| Defense Industrial Corridor Localization | India's Maharashtra and Karnataka corridors attract equipment deployment for indigenous helicopter and fighter programs. |
| ISO 14922 Certification Integration | Quality assurance systems embedded directly into gun design specifications rather than post-sale add-ons. |
Research Methodology
The analysis maps HVOF, cold spray, plasma spray, and flame spray equipment segments, each validated through equipment procurement directors at turbine engine OEMs, coating cell engineers at aerospace MRO depots, powder metallurgy specialists at feedstock suppliers, and industrial gas supply chain managers. Primary interview findings triangulate against customs trade data for equipment imports, SEC filings from diversified industrial conglomerates, FAA airworthiness directive databases, and EU F-Gas Regulation implementation reports. Bottom-up equipment shipment tracking and top-down end-use demand modeling ensure cross-verification.
Consistency checks validate volume and value outputs against external benchmarks including industrial gas consumption disclosures, powder feedstock production volumes, and aerospace coating capacity expansion announcements. Segmentation dimensions span deposition technology, certification tier, end-use industry, and geographic regulatory cluster. CAGRs derive from installed base replacement cycles, technology substitution rates, and capacity expansion timelines across the projection horizon. Industry-specific forecast inputs include helium supply contract pricing trends and FAA qualification timeline compression effects.
Material uncertainties — regulatory enforcement intensity variations, feedstock chemistry reformulation delays under REACH, and defense procurement budget reallocations — sit outside the modeled envelope. Forecasts reflect documented assumptions about technology adoption curves and certification timeline standardization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Polycarbonate Panels Market
Industrial Materials
Industrial Pails and Drums Market
Industrial Materials
GCC Welding Consumables Market
Industrial Materials
Anode Carbon Block Market
Industrial Materials
Wood Protein Market
Industrial Materials
Acrylic Sheet Market
Industrial Materials
Industrial Strainers Market
Industrial Materials
North America Activated Carbon Market
Industrial Materials
Middle East Activated Carbon Market
Industrial Materials
Global Medical Plastics Extrusion Market
Industrial Materials
Industrial Absorbents Market
Industrial Materials
Industrial Couplings Market
Industrial Materials
Industrial Mixers Market
Industrial Materials
Noise Reduction Plastic Gear Market
Industrial Materials
Stainless Steel Cable Ties Market
Industrial Materials
Plastic Recycling Machine Market