
 Global Graphite Electrode Rod Market | 2026-2036
Global Graphite Electrode Rod Market Size, Share, and Industry Trends Forecast 2026-2036
Global Graphite Electrode Rod Market Analysis
China's capacity build-out in premium electrode manufacturing is reshaping global supply dynamics. GrafTech International leverages vertical integration from petroleum needle coke to finished electrodes, sustaining cost advantages across North American operations. Fangda Carbon New Material anchors domestic supply security for China's expanding electric arc furnace fleet. Tokai Carbon differentiates through advanced thermal treatment technologies that extend electrode lifespan in demanding furnace conditions.
Graphite electrode rods are cylindrical conductors manufactured from petroleum needle coke and coal tar pitch, baked to temperatures exceeding 2,800°C to achieve electrical resistivity below 5.5 μΩ·m and flexural strength above 10 MPa. These specifications enable efficient current transfer into electric arc furnaces for steel scrap melting and refining. Ultra high-power electrodes command the dominant margin pool as furnace operators push for shorter tap-to-tap cycles and higher specific power inputs. Steel manufacturing absorbs the majority of volume, while aluminum production represents a specialized growth corridor requiring modified thermal profiles. Electrode fabrication technology governs cost structure, with impregnation and re-baking steps determining final performance tier classification.
China's MEE enforces emission intensity benchmarks that favor closed-loop furnace operations using premium electrodes. REACH compliance in Europe restricts polycyclic aromatic hydrocarbon content in coal tar pitch binders, elevating formulation costs for exporters. India's BIS certification mandates dimensional tolerances that filter out lower-grade imports. Stakeholders must monitor how carbon border adjustment mechanisms redirect trade flows and whether needle coke supply commitments from petroleum refiners keep pace with furnace electrification trends.
Market Dynamics
China's dual carbon goals are forcing electric arc furnace steelmakers to upgrade electrode specifications, compressing demand for standard-grade rods while ultra high-power variants face supply bottlenecks from needle coke scarcity.
Growth Catalysts
- India's secondary steel sector:Electric arc furnace capacity additions in Gujarat and Odisha are pulling premium electrode imports. The country's PLI scheme for specialty steel accelerates furnace commissioning timelines.
- EU Carbon Border Adjustment Mechanism:Steel importers into Europe face embedded carbon tariffs that favor scrap-based electric arc furnace routes over blast furnace production, indirectly stimulating electrode consumption.
- Needle coke quality differentiation:Petroleum-derived feedstock with low sulfur and nitrogen content enables longer electrode lifespan in high-power furnace operations, justifying price premiums for integrated manufacturers.
Market Restraints
- Petroleum needle coke supply concentration:Four refiners control the majority of premium feedstock output, creating vulnerability to upstream oil sector capital allocation decisions.
- REACH compliance costs:European polycyclic aromatic hydrocarbon restrictions on coal tar pitch binders elevate formulation expenses for exporters serving EU steelmakers.
- Silicon carbide crucible substitution:Aluminum smelters in energy-intensive regions are piloting alternative conductor materials for certain thermal profile applications.
Strategic Opportunities
- Vietnam's steel capacity build-out:Hoa Phat and Formosa Ha Tinh are expanding electric arc furnace operations, creating demand for imported ultra high-power electrodes as domestic supply remains nascent.
- Impregnation technology convergence:Combining pitch impregnation with advanced thermal treatment extends electrode lifespan, enabling service-based revenue models tied to furnace productivity guarantees.
- Japan's METI green steel roadmap:Hydrogen-reduced iron processes paired with electric arc refining create demand for electrodes capable of handling variable metallic charge compositions.
Industry Challenges
- Graphitization furnace operator scarcity:The 2,800°C baking process requires specialized technicians with decade-long training curves, constraining capacity expansion regardless of capital availability.
- BIS certification timelines:India's dimensional tolerance testing creates 6-12 month approval windows that filter out opportunistic exporters during demand spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Graphite Electrode Rod Market |
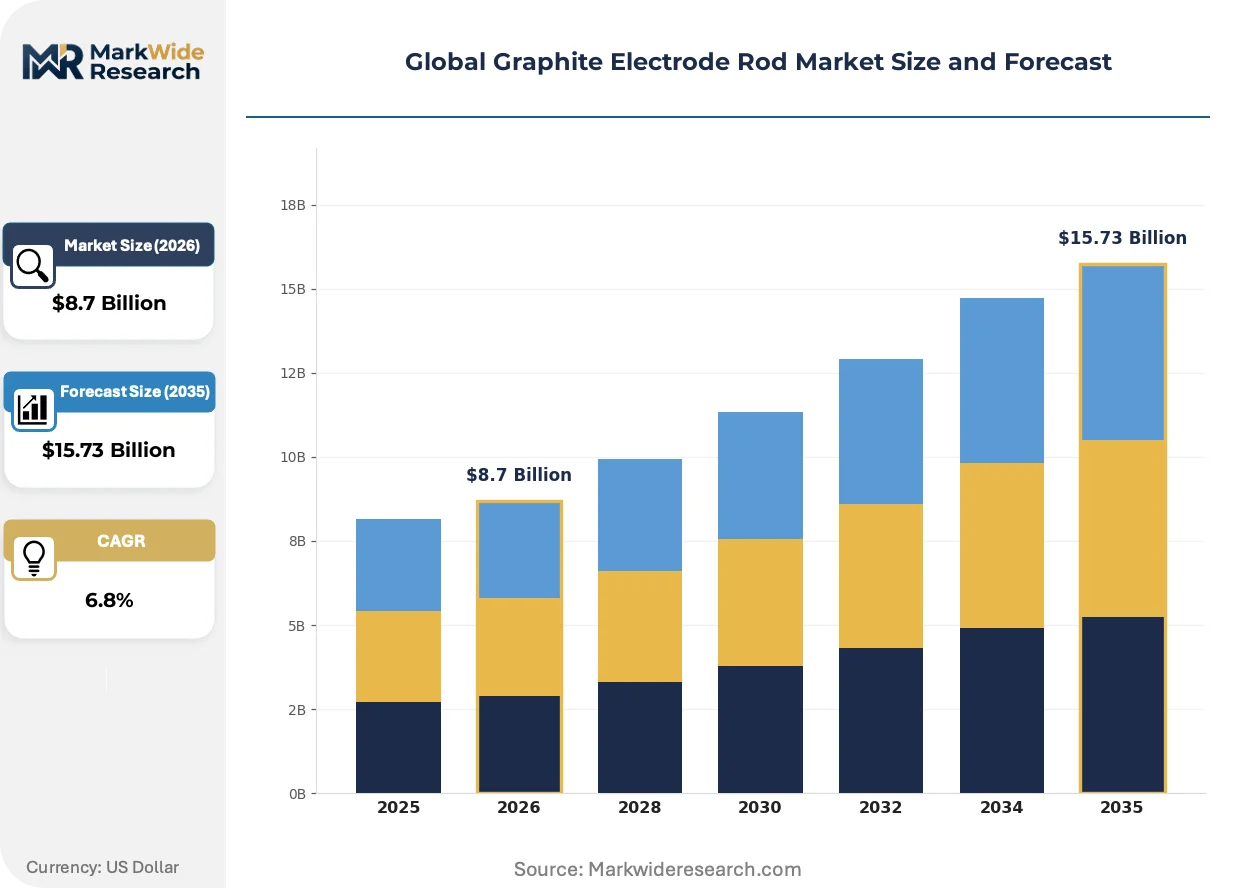
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Power, Ultra High-Power, Regular Power, Composite End User: Steel Manufacturing, Foundries, Aluminum Production, Chemical Industries Technology: Graphite Mining, Electrode Fabrication, Electrical Discharge Machining, Infusion Application: Electric Arc Furnace, Continuous Casting, Ladle Furnace, Welding |
| Companies Covered | GrafTech International, Fangda Carbon New Material, Tokai Carbon, Graphite India, HEG Limited, Resonac Holdings Corporation, Showa Denko, Yangzi Carbon, Nippon Carbon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Graphite Electrode Rod Market Emerging Trajectories
Electrode manufacturers are racing to collapse production cycle times while furnace operators demand predictive performance guarantees rather than commodity procurement.
Impregnated ultra high-power electrodes are collapsing the replacement frequency for demanding furnace operations. Steelmakers in South Korea and Turkey are adopting these variants for stainless and specialty alloy production. The technology is collapsing maintenance windows and labor costs, compressing total cost of ownership calculations that previously favored lower upfront pricing.
China's MEE emission intensity benchmarks are redirecting domestic capacity toward closed-loop furnace designs that consume premium electrodes exclusively. Steelmakers in Hebei and Jiangsu provinces face mandatory carbon intensity reductions that disfavor standard-grade rod consumption. Domestic electrode producers are responding by idling lower-efficiency graphitization lines and redirecting needle coke allocations.
Integrated steel mills are unbundling electrode supply from equipment procurement, creating standalone service contracts tied to furnace productivity metrics. Mill operators in Brazil and Saudi Arabia now specify electrodes by energy transfer efficiency rather than dimensional grade alone. This specification shift is most visible in Gulf Cooperation Council countries where greenfield electric arc furnace complexes lack legacy supplier relationships.
Global Graphite Electrode Rod Market Segmentation
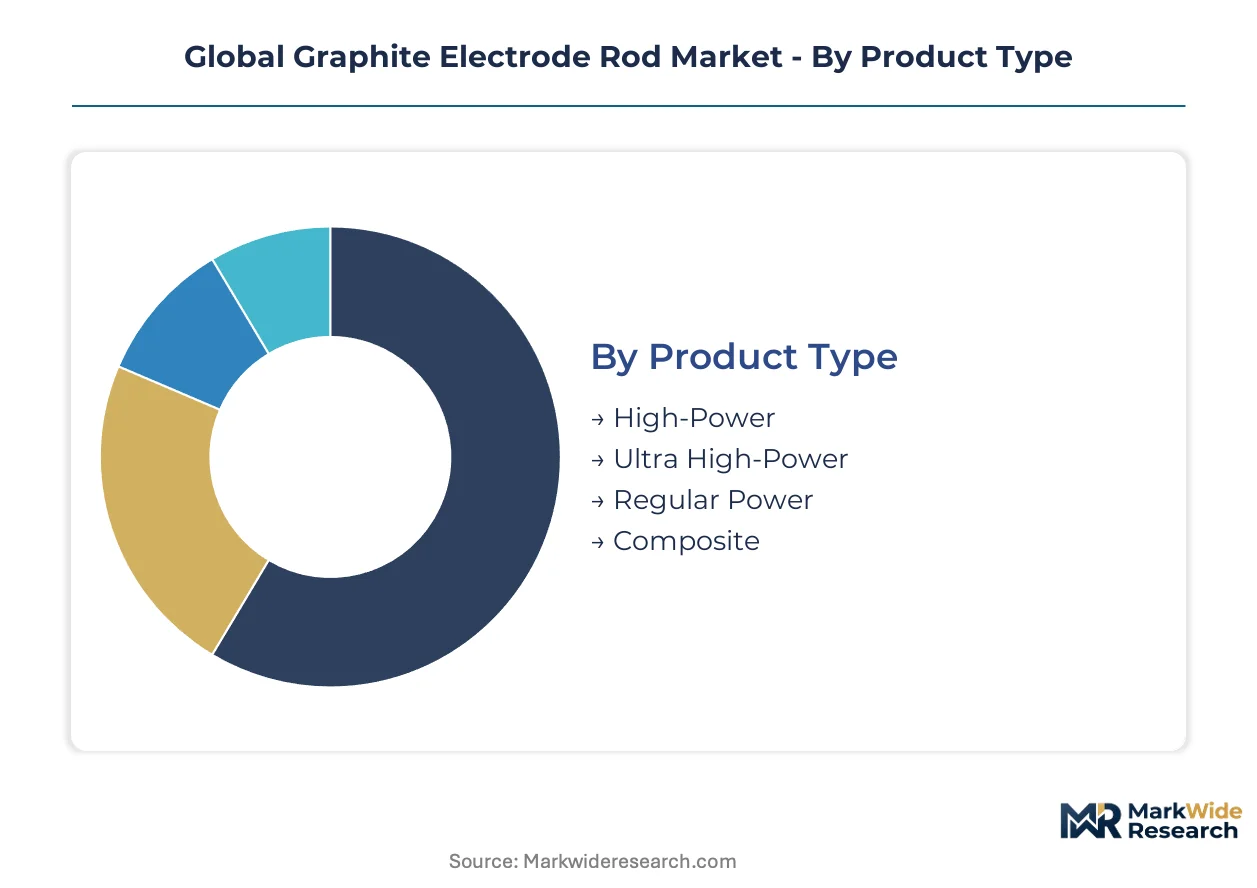
Electrode specification tiers determine furnace performance ceilings and replacement economics. Technology pathways govern capital intensity and geographic production feasibility. Application contexts dictate thermal profile requirements and procurement contract structures.
Product Type:
Cost tier differentiation separates commodity-grade conductors from premium furnace solutions capable of sustaining extreme power densities.
- Ultra High-Power:Manufactured from low-sulfur petroleum needle coke with thermal treatment exceeding 2,800°C, achieving electrical resistivity below 5.0 μΩ·m. Demand concentrates in India's Gujarat and Odisha steel clusters where furnace operators push for sub-60-minute tap-to-tap cycles under the PLI scheme for specialty steel.
- High-Power:Intermediate-grade electrodes serving stainless steel and alloy production with moderate graphitization intensity. South Korean stainless producers favor these variants for their balance of thermal shock resistance and specific energy consumption.
- Regular Power:Standard-grade rods for lower-intensity furnace operations with shorter campaign lengths.
- Composite:Hybrid constructions combining graphite cores with protective ceramic coatings for specialized thermal profiles.
Ultra High-Power commands the established base. The steepest expansion runs through High-Power as mid-tier furnace upgrades accelerate.
End User:
Application maturity varies sharply across industrial verticals, with scrap-based metallurgy dominating volume while emerging sectors reshape specification requirements.
- Steel Manufacturing:Electric arc furnace operators consume the majority of electrode volume, with specific power inputs rising across China, India, and Vietnam. China's MEE emission intensity benchmarks force Hebei and Jiangsu steelmakers toward closed-loop furnace designs using exclusively premium electrodes.
- Aluminum Production:Smelters require modified thermal profiles with specialized electrode geometries for electrolytic reduction cells. Pilot programs in energy-intensive regions are testing silicon carbide crucible alternatives for certain conductor applications.
- Foundries:Smaller-batch ferrous and non-ferrous melting operations with intermittent furnace campaigns.
- Chemical Industries:Specialized applications in chlor-alkali electrolysis and phosphorus production.
Steel Manufacturing anchors procurement volume. Aluminum Production is climbing the fastest as smelter electrification and green aluminum initiatives expand addressable demand.
Technology:
Supply concentration and capability scarcity define competitive positioning across production stages, with graphitization furnace operations representing the critical bottleneck.
- Electrode Fabrication:Combines calcined coke crushing, pitch binding, extrusion, and multi-stage baking. Impregnation and re-baking steps determine final performance tier classification and electrode lifespan in demanding furnace conditions.
- Graphite Mining:Natural flake graphite extraction for lower-specification applications and composite feedstock.
- Infusion:Advanced pitch impregnation techniques extending electrode density and thermal conductivity.
- Electrical Discharge Machining:Precision shaping for specialized electrode geometries in non-standard furnace configurations.
Electrode Fabrication commands the established base. Infusion is gaining share fastest as service-based revenue models tied to furnace productivity guarantees displace commodity procurement.
Application:
Equipment configuration dictates electrode dimensional requirements, connection standards, and replacement frequency economics.
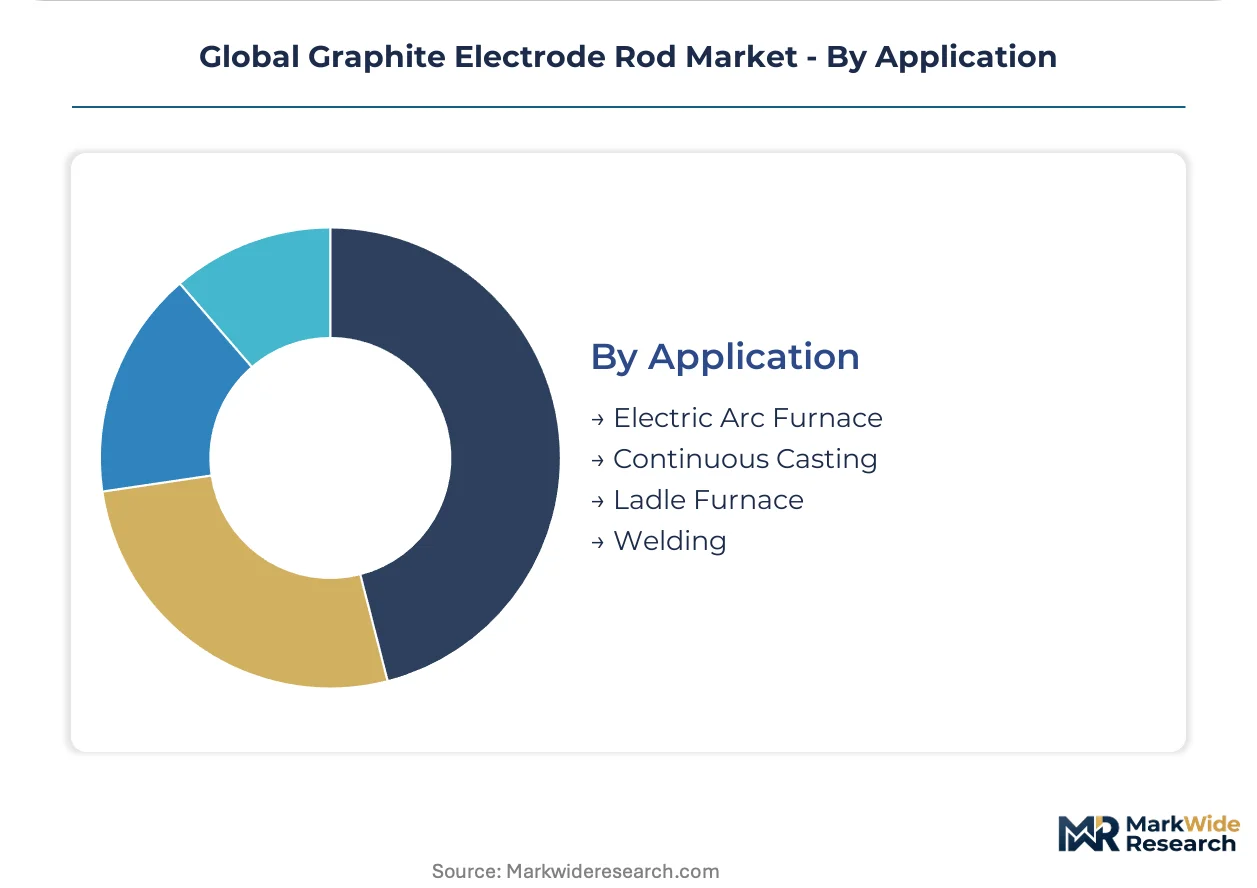
- Electric Arc Furnace:Primary steelmaking and scrap melting operations consuming the majority of ultra high-power electrode volume. Vietnam's Hoa Phat and Formosa Ha Tinh are expanding EAF capacity, creating import demand as domestic electrode supply remains nascent.
- Ladle Furnace:Secondary refining stations requiring electrodes capable of sustaining prolonged argon stirring and temperature holding operations.
- Continuous Casting:Tundish heating and stream protection applications with intermittent thermal cycling.
- Welding:Specialized arc maintenance in submerged arc and electroslag processes.
Electric Arc Furnace commands the established base. Ladle Furnace is expanding most quickly as integrated mills unbundle refining capacity from primary melting operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Four refiners control the majority of premium petroleum needle coke output, concentrating upstream supply in North America and Asia while downstream electrode fabrication clusters near steel demand centers. This configuration creates divergent regional dynamics as furnace electrification accelerates across disparate regulatory environments.
China
Hebei and Jiangsu steel clusters drive ultra high-power electrode consumption as MEE emission intensity benchmarks mandate closed-loop furnace designs. The country's dual carbon goals redirect capacity toward higher-efficiency grades while compressing standard-grade demand. Domestic producers idle lower-efficiency graphitization lines and redirect needle coke allocations toward premium output.
India
Gujarat and Odisha electric arc furnace capacity additions pull premium electrode imports under the PLI scheme for specialty steel. BIS certification mandates dimensional tolerances that filter out lower-grade imports during demand spikes. The secondary steel sector scales fastest here, creating acute consumption concentration.
United States
North American operations leverage captive petroleum needle coke supply from integrated refinery networks. EPA emission standards and IRA clean manufacturing provisions favor scrap-based steel routes, sustaining electrode demand. Regional furnace operators prioritize productivity guarantees over commodity procurement in contract structures.
Japan
METI's green steel roadmap pairs hydrogen-reduced iron processes with electric arc refining, demanding electrodes capable of handling variable metallic charge compositions. Kansai and Chubu industrial corridors host advanced steel research consortia testing next-generation thermal profiles. Domestic carbon neutrality targets accelerate furnace technology refresh cycles.
Vietnam
Hoa Phat and Formosa Ha Tinh expand electric arc furnace operations, creating import demand for ultra high-power electrodes as domestic supply remains nascent. Rapid steel capacity build-out outpaces local electrode fabrication capability. Furnace operators source primarily from Chinese and Indian suppliers while testing qualification timelines.
Global Graphite Electrode Rod Market Vendor Landscape
Vertically integrated petroleum coke producers and specialized electrode fabricators split the market into distinct capability tiers. Consolidation at the needle coke level contrasts with fragmentation among regional electrode converters lacking upstream feedstock control. Two strategic archetypes dominate: integrated energy-materials conglomerates with captive refinery supply, and technology-focused specialists concentrating advanced thermal treatment expertise. Capacity expansion and backward integration into needle coke sourcing represent the dominant competitive moves as supply security trumps pure manufacturing scale.
Among North American integrated producers, GrafTech International anchors the captive supply archetype through in-house petroleum needle coke production. Fangda Carbon New Material exemplifies Chinese domestic supply security positioning for the country's expanding electric arc furnace fleet. Tokai Carbon occupies the advanced technology specialist tier, with thermal treatment capabilities extending electrode lifespan in demanding furnace conditions. These three represent the structural diversity across competitive positioning: upstream control, domestic scale, and technical differentiation.
| Leading Market Players |
|---|
| GrafTech International |
| Fangda Carbon New Material |
| Tokai Carbon |
| Graphite India |
| HEG Limited |
| Resonac Holdings Corporation |
| Showa Denko |
| Yangzi Carbon |
| Nippon Carbon |
| Others |
Supply Flow & Price Mechanics
Four North American petroleum refiners dominate premium needle coke output, anchoring margin pools downstream at the ultra high-power electrode tier where furnace operators pay efficiency premiums over commodity-grade alternatives. China's MEE emission benchmarks and India's BIS certification requirements reshape pricing power by filtering out lower-grade imports and compressing standard-grade demand.
Pricing Analysis
REACH compliance dictates the pricing tier structure across European deliveries, elevating formulation costs for coal tar pitch binders and widening spreads between certified and non-certified supply. Three-tier pricing structure across premium, standard, and economy levels reflects needle coke quality differentiation, with low-sulfur petroleum-derived feedstock commanding the top tier. Cost compression in standard-grade segments is intensifying because Chinese producers idle lower-efficiency graphitization lines and redirect allocations toward premium output. Indian electric arc furnace operators under the PLI scheme exhibit the least price sensitivity, prioritizing electrode lifespan guarantees over upfront unit costs.
Supply Chain Analysis
Export-control regimes on advanced thermal treatment technologies limit graphitization furnace transfers, constraining capacity expansion regardless of capital availability. Supply concentrates in the United States, China, and Japan, with the United States anchoring captive needle coke production and China hosting the majority of downstream electrode fabrication. The supply chain draws from petroleum needle coke, coal tar pitch binders, and specialized graphitization furnace equipment. Single-source vulnerability runs through the four refiners controlling premium needle coke output. Distribution runs through long-term offtake contracts tied to furnace productivity metrics rather than spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward integrated steel mills unbundling electrode supply from equipment procurement, fragmenting procurement authority across standalone service contracts and productivity-based specifications.
For Market Incumbents: Pre-empt silicon carbide crucible substitution in aluminum smelters by accelerating impregnation technology roadmaps that extend electrode lifespan guarantees. Anchor needle coke supply security through backward integration or long-term refinery offtake agreements, as petroleum sector capital allocation decisions threaten feedstock availability. Steelmaker consolidation in the Gulf Cooperation Council creates procurement leverage that demands response through localized technical service presence. For New Entrants and Emerging Players: Build out Vietnam's electric arc furnace supply gap as Hoa Phat and Formosa Ha Tinh expand capacity ahead of domestic electrode fabrication capability. Target ladle furnace applications as integrated mills unbundle refining capacity from primary melting operations, creating standalone demand for electrodes capable of prolonged argon stirring. Pursue qualification partnerships with Indian BIS-certified testing facilities to compress 6-12 month approval timelines. For Investors and Strategic Acquirers: Capital is best deployed toward electrode fabricators with demonstrated graphitization furnace operator training pipelines, as technician scarcity constrains capacity expansion regardless of equipment availability. Long-term viability hinges on positioning for hydrogen-reduced iron process adoption under Japan's METI green steel roadmap. Watch needle coke supply commitments from petroleum refiners as the inflection indicator for premium electrode margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Needle Coke | Secures feedstock supply against petroleum refinery capital reallocation decisions. |
| Impregnation Technology Scale-Up | Enables service-based revenue models tied to furnace productivity guarantees in South Korea. |
| BIS Certification Fast-Track | Filters out opportunistic exporters during India's PLI-driven demand spikes. |
| Graphitization Furnace Operator Academy | Addresses decade-long training curves constraining capacity expansion in China. |
| Hydrogen-Reduced Iron Electrode Development | Positions for METI green steel roadmap requirements in Japan's Kansai corridor. |
Methodological Framework
A standing panel of electric arc furnace operations managers, petroleum needle coke procurement leads, electrode fabrication plant engineers, and BIS certification specialists provided ongoing calibration across primary interview rounds. Secondary validation drew from MEE emission intensity benchmark filings, REACH compliance registries, Indian customs import data, and SEC disclosures from integrated electrode manufacturers. Bottom-up demand modeling triangulated against top-down steel production capacity forecasts across the analysis window.
Scenario-bracketing framed projections across conservative, baseline, and aggressive furnace electrification pathways. Segmentation dimensions modeled include electrode power grade, end-use application, thermal treatment technology, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating needle coke supply constraints and carbon border adjustment mechanism phase-in assumptions. Forecast inputs included electric arc furnace capacity commissioning timelines under India's PLI scheme and China's dual carbon policy enforcement intensity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by silicon carbide crucible developers or petroleum refinery divestiture from needle coke production would shift outcomes. Material shifts in MEE benchmark stringency or EU Carbon Border Adjustment Mechanism scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
High Speed Steels Market
Industrial Materials
Injection Molding Market
Industrial Materials
Mesh Nozzle Plates Market
Industrial Materials
Metal Heat Treatment Market
Industrial Materials
Magnetic Separator Market
Industrial Materials
Industrial Silica Sand Market
Industrial Materials
Silica Fume Market
Industrial Materials
Saudi Arabia Industrial Insulation Market
Industrial Materials
Global High Pressure Seals Market
Industrial Materials
Industrial Anti-Fatigue Mat Market
Industrial Materials
North America Machined Seals Market
Industrial Materials
Cork Material Market
Industrial Materials
Portable Magnetizer Market
Industrial Materials
Industrial Round Wood Market
Industrial Materials
Wear-Resistant Welding Wire Market
Industrial Materials
Wire Mesh Market