
 Global Virtual Restaurant and Ghost Kitchens Market | 2026-2036
Global Virtual Restaurant and Ghost Kitchens Market Size, Share, and Industry Trends Forecast 2026-2036
Global Virtual Restaurant and Ghost Kitchens Market Foresight
The virtual restaurant sector is rebalancing between premium chef-driven concepts and commodity meal-assembly operations. CloudKitchens leverages its real estate aggregation platform to dominate urban logistics corridors. Rebel Foods sustains multi-brand density across Indian metros through centralized production protocols. Kitchen United anchors suburban penetration with shared kitchen infrastructure designed for lower-rent zones.
Virtual restaurants and ghost kitchens operate as delivery-native foodservice facilities without dine-in infrastructure, typically occupying 200–400 square meter industrial spaces optimized for order throughput rather than customer experience. Their primary commercial purpose centers on decoupling food production from front-of-house real estate to capture off-premise dining economics. The cloud kitchen business model leads volume generation by consolidating multiple brands under single-roof operations, while AI-powered analytics within technology integration represents the fastest-expanding margin pool as operators deploy predictive demand forecasting to reduce waste. Multi-brand kitchen types now occupy the structural middle ground between independent single-concept facilities and capital-intensive chain deployments.
The FDA enforces Current Good Manufacturing Practice standards for interstate ghost kitchen commissaries in the United States, while the EU Green Deal's packaging waste directives reshape container specifications across European delivery corridors. FSSAI in India mandates separate licensing categories for cloud kitchens that lack traditional restaurant classifications, creating compliance complexity for cross-border operators. Stakeholders must monitor how municipal zoning boards in Dubai, Singapore, and London recast industrial district classifications to either accelerate or constrain kitchen clustering near residential delivery zones.
Market Dynamics
AI-powered kitchen automation is compressing labor costs and order fulfillment times across delivery-native foodservice operations, fundamentally restructuring unit economics away from front-of-house real estate dependency.
Growth Catalysts
- Urban Millennial Demand Concentration:Metropolitan corridors in the United States, China, and the United Arab Emirates exhibit dense clustering of delivery-native consumers aged 25-40, creating natural demand pools for virtual kitchen deployment without dine-in infrastructure investment.
- FSSAI Licensing Framework Evolution:India's food safety regulator has created distinct compliance categories for cloud kitchens, legitimizing the asset-light format and enabling standardized hygiene protocols that reduce operator uncertainty.
- Predictive Demand Analytics:Machine learning algorithms deployed across multi-brand kitchen operations are reducing ingredient waste and optimizing production scheduling, directly improving margin capture in high-volume delivery corridors.
Market Restraints
- Commercial Real Estate Concentration:Prime industrial kitchen space in last-mile logistics zones of New York, London, and Dubai commands premium rents that compress operator margins, favoring well-capitalized aggregators over independent entrants.
- Interstate Regulatory Fragmentation:FDA Current Good Manufacturing Practice standards apply variably across United States state lines, creating compliance complexity for cloud kitchen commissaries serving multiple jurisdictions.
- Platform Dependency Risk:Third-party delivery aggregators extract substantial commission fees from virtual restaurant operators, constraining pricing autonomy and direct customer relationship ownership.
Strategic Opportunities
- Suburban Penetration White Space:Lower-rent zones in secondary United States metropolitan rings remain underpenetrated by shared kitchen infrastructure, offering first-mover advantages for operators with flexible real estate models.
- EU Green Deal Packaging Mandates:European Union directives on single-use container reduction are creating procurement advantages for virtual kitchens that deploy reusable or compostable packaging systems ahead of compliance deadlines.
- AI-Inventory Convergence:Integration of computer vision with automated inventory management is enabling real-time ingredient tracking across multi-brand production facilities, reducing spoilage in high-SKU operations.
Industry Challenges
- Certification Timeline Compression:Municipal zoning boards in Singapore, London, and Dubai are recasting industrial district classifications at uneven speeds, creating permitting delays for kitchen clustering near residential delivery zones.
- Specialized Culinary Talent Scarcity:Virtual kitchen operations require chefs skilled in high-throughput production protocols rather than traditional plating and service, creating recruitment friction in established foodservice labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Virtual Restaurant and Ghost Kitchens Market |
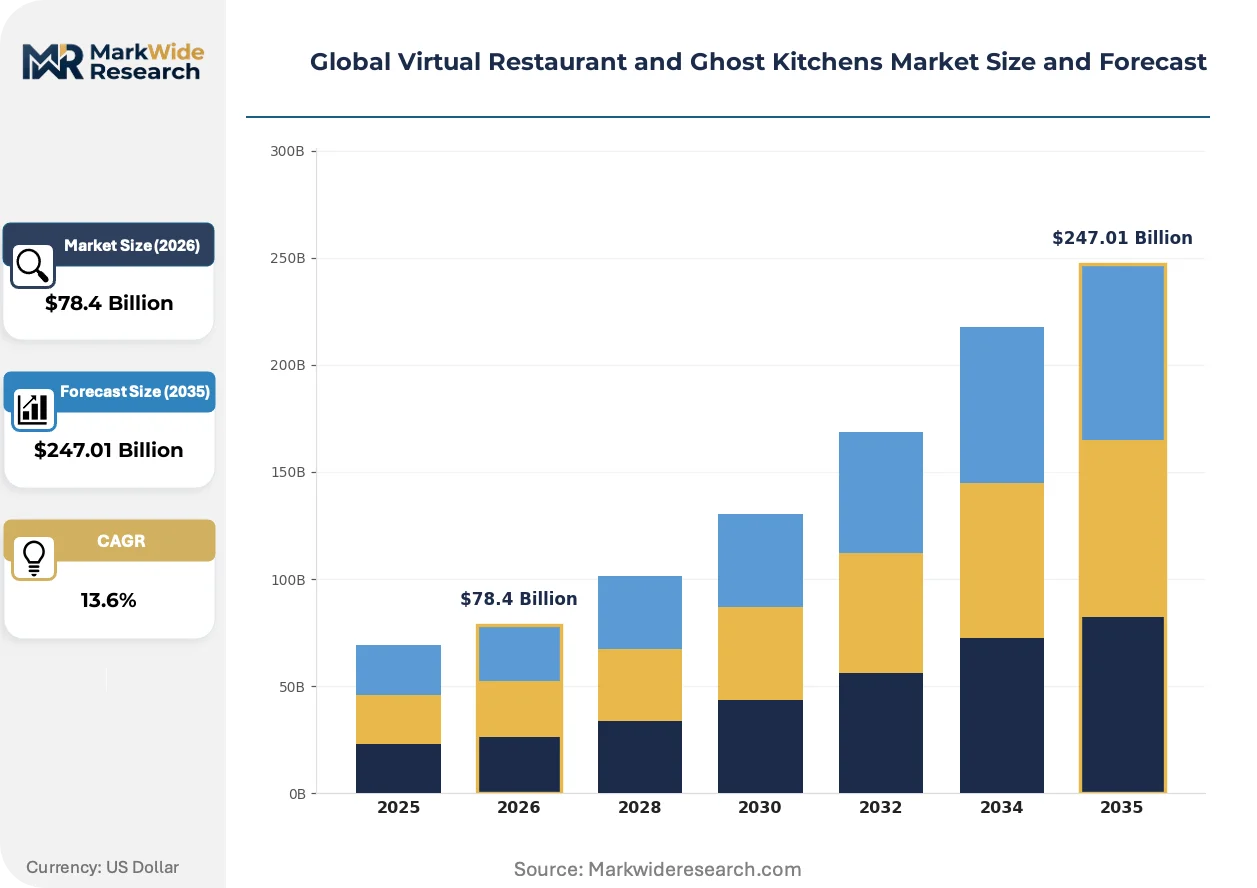
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $247.01 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Business Model: Cloud Kitchen, Commissary Kitchen, Cook & Deliver, Order Only, Delivery-Only Restaurant Kitchen Type: Independent, Multi-Brand, Franchise, Chain, Shared Kitchen End User: Food Delivery Platforms, Food Truck Operators, Catering Services, Meal Prep Companies, Online Grocers Technology Integration: Online Ordering Systems, Inventory Management Software, AI-Powered Analytics, Contactless Payment, Delivery Routing Software |
| Companies Covered | CloudKitchens, Rebel Foods, Kitchen United, Reef Technology, Zuul Kitchens, Kitopi, Nextbite Brands, C3 (Creating Culinary Communities), Virtual Kitchen Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Virtual Restaurant and Ghost Kitchens Market Shifts & Advancements
Automation and regulatory adaptation are converging to reshape how delivery-native foodservice facilities deploy capital, manage compliance, and capture consumer attention across metropolitan corridors.
Robotic cooking stations and automated assembly lines are modularizing kitchen workflows into discrete, interchangeable production cells. Cloud kitchen operators in the United States and United Arab Emirates are adopting these systems fastest, driven by labor shortage pressures and throughput targets. This modularization is enabling multi-brand facilities to reconfigure production lines between concepts within hours rather than days, compressing menu rollout cycles and reducing equipment idle time.
REACH and EU Green Deal packaging directives are mandating material composition shifts across European delivery corridors. Food container specifications must now meet recyclability thresholds and reduced plastic content requirements, forcing virtual kitchen operators to requalify supplier relationships and absorb transitional cost premiums. Central European markets including Germany and the Netherlands are experiencing the steepest compliance curves, with operators accelerating partnerships with biodegradable packaging specialists.
Subscription-based meal programs are displacing transactional delivery orders among urban professional segments in China and India. Virtual restaurant brands are restructuring pricing architectures around weekly commitment models rather than per-order economics, capturing predictable revenue streams. This behavioral pivot is most visible in Shanghai and Bangalore, where platform data shows sustained subscription retention rates driving lifetime value calculations for cloud kitchen investors.
Global Virtual Restaurant and Ghost Kitchens Market Segmentation
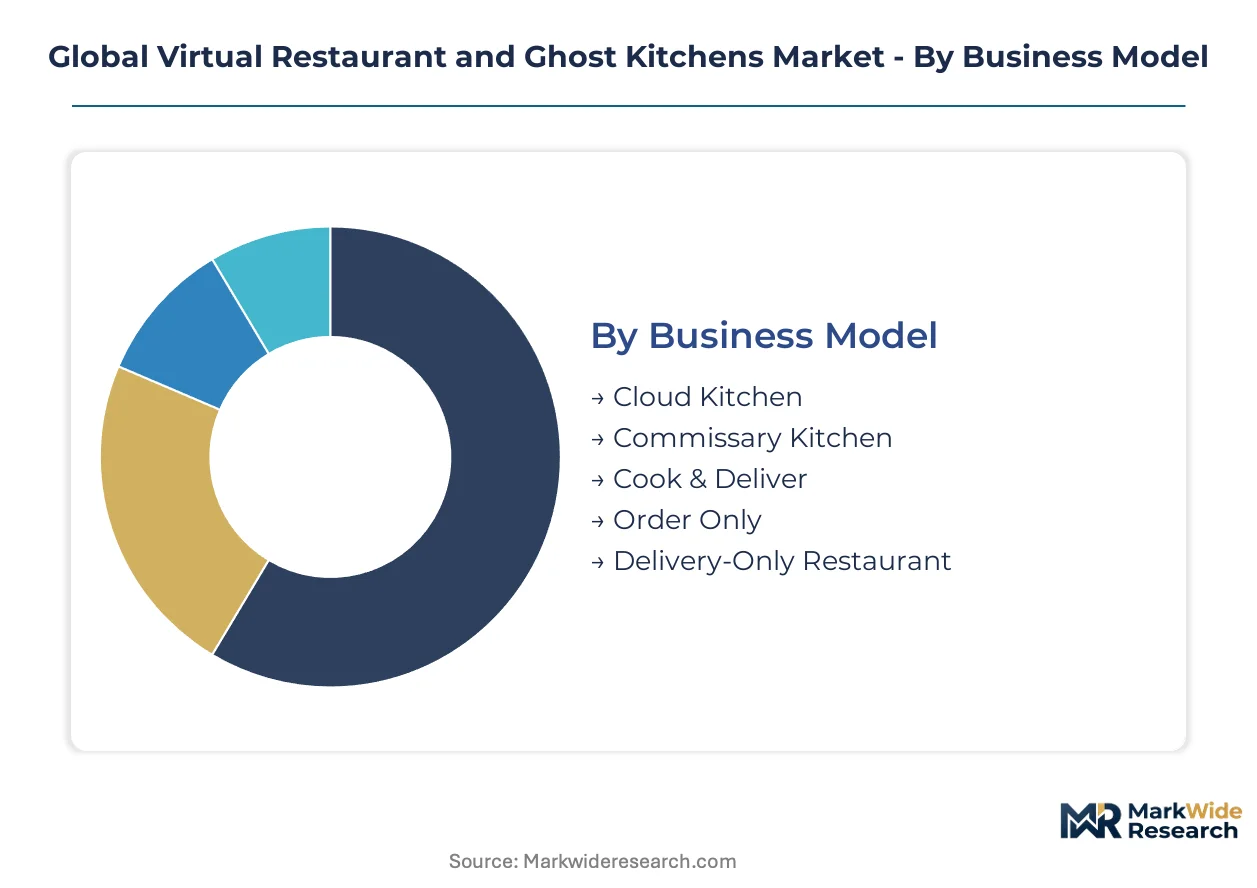
Virtual restaurant and ghost kitchen operators segment their operations across business models, kitchen configurations, end-user channels, and technology stacks to match capital intensity with demand density. Each segment carries distinct regulatory footprints and margin structures that determine viable deployment geographies.
Business Model:
FDA Current Good Manufacturing Practice standards apply variably across these formats, with interstate commissary operations facing the heaviest documentation burden while order-only concepts escape production-floor inspections entirely.
- Cloud Kitchen:Multi-brand production facilities consolidate disparate virtual restaurant concepts under single-roof operations, capturing economies of scale in ingredient procurement and labor scheduling. Demand concentrates in United States metropolitan corridors where real estate costs push traditional restaurants toward asset-light formats, though FSSAI licensing mandates in India create compliance complexity for cross-border operators.
- Commissary Kitchen:Centralized production hubs supply satellite locations or third-party operators with pre-prepped components, requiring HACCP certification and cold-chain documentation. Volume clusters in Dubai and London where municipal zoning boards are recasting industrial district classifications to accommodate kitchen clustering near residential delivery zones.
- Cook & Deliver:End-to-end preparation and dispatch from a single facility, retaining full margin capture but bearing complete labor and equipment costs.
- Order Only:Facilities that accept and route orders without on-site cooking, functioning as pure logistics nodes with minimal regulatory exposure.
- Delivery-Only Restaurant:Single-concept virtual brands operating dedicated kitchens, balancing brand control against higher per-unit overhead.
Leading the category by volume: Cloud Kitchen. Growing fastest: Commissary Kitchen.
Kitchen Type:
Capital deployment patterns diverge sharply between operator-controlled facilities and aggregator-managed infrastructure, with franchise models requiring the most extensive multi-jurisdictional licensing.
- Independent:Single-operator facilities bearing full capital risk and regulatory compliance burden, typically occupying 200–400 square meter industrial spaces.
- Multi-Brand:Shared production environments hosting multiple virtual concepts enable rapid menu testing and equipment utilization optimization. Demand concentrates in Chinese and Indian metros where subscription-based meal programs are displacing transactional orders, with operators leveraging centralized production protocols to reduce per-brand overhead.
- Franchise:Licensed operations replicating proven concepts across markets, requiring standardized hygiene protocols and brand consistency enforcement.
- Chain:Corporate-owned networks achieving procurement scale but facing real estate concentration risk in premium logistics corridors.
- Shared Kitchen:Third-party infrastructure providers offering flexible tenancy terms, lowering barriers to entry for virtual brand launches.
Multi-Brand facilities dominate deployment counts. Shared Kitchen concepts are expanding most quickly in underpenetrated suburban United States markets.
End User:
Channel selection determines pricing autonomy and customer data ownership, with platform-dependent segments sacrificing margin for volume access.
- Food Delivery Platforms:Third-party aggregators commanding substantial commission fees but providing built-in demand access. Volume concentrates in United Arab Emirates and United States corridors where urban millennial density supports high-throughput operations, though platform dependency constrains direct relationship building.
- Food Truck Operators:Mobile foodservice units requiring commissary kitchen partnerships for regulatory compliance and overnight staging.
- Catering Services:Large-format production with advance scheduling, reducing demand volatility but requiring specialized equipment for batch cooking.
- Meal Prep Companies:Subscription-driven weekly commitment models capturing predictable revenue streams in Shanghai and Bangalore.
- Online Grocers:Grocery-anchored meal solutions integrating prepared foods with retail fulfillment infrastructure.
Food Delivery Platforms anchor current volume. Meal Prep Companies are climbing the fastest as subscription architectures displace per-order economics.
Technology Integration:
Margin capture increasingly depends on predictive capabilities that reduce waste and compress fulfillment times, with AI-powered systems representing the steepest investment priority.
- Online Ordering Systems:Customer-facing interfaces managing menu presentation, customization, and payment processing.
- Inventory Management Software:Real-time ingredient tracking reducing spoilage in high-SKU multi-brand operations.
- AI-Powered Analytics:Machine learning algorithms deployed for demand forecasting and production scheduling optimization. Demand concentrates among United States and United Arab Emirates operators facing labor shortage pressures, with predictive analytics directly improving margin capture in high-volume delivery corridors.
- Contactless Payment:Digital transaction infrastructure reducing friction and enabling data collection on purchasing patterns.
- Delivery Routing Software:Last-mile optimization tools compressing fulfillment times and driver utilization rates.
Online Ordering Systems retain the widest deployment base. AI-Powered Analytics shows the steepest expansion trajectory as operators prioritize margin recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New York City's five boroughs concentrate the highest density of cloud kitchen deployment in North America, with operators clustering around last-mile logistics corridors in Queens and Brooklyn to minimize delivery radius to Manhattan's residential towers.
United States
Urban millennials in Chicago, Los Angeles, and Houston are driving demand for subscription meal programs that displace transactional delivery orders. The FDA enforces Current Good Manufacturing Practice standards variably across state lines, creating compliance complexity for interstate commissary operations. Miami's Wynwood and Design District corridors are experiencing rapid kitchen clustering as municipal zoning boards recast industrial classifications.
China
Shanghai and Beijing professionals are accelerating adoption of weekly commitment models over per-order economics in delivery-native dining. The country's national food safety regulator maintains strict licensing frameworks for centralized production facilities without traditional restaurant classifications. The Yangtze River Delta manufacturing belt is integrating automated assembly lines into multi-brand kitchen facilities to compress fulfillment times.
India
Bangalore and Mumbai's tech workforce is sustaining multi-brand density through centralized production protocols optimized for high-throughput operations. FSSAI mandates separate licensing categories for cloud kitchens lacking traditional restaurant classifications, legitimizing asset-light formats. Hyderabad's HITEC City corridor is emerging as a secondary cluster for shared kitchen infrastructure targeting suburban penetration.
United Arab Emirates
Dubai's expatriate professional population supports premium delivery-native concepts across residential zones in Downtown and Dubai Marina. MOHAP oversees food safety compliance for delivery-only facilities operating across the emirate's free zones. Industrial districts near Al Quoz are attracting aggregator-managed infrastructure as real estate costs in prime logistics corridors escalate.
Germany
Berlin and Hamburg's urban consumer base is adapting to reusable container mandates under EU Green Deal packaging directives. REACH and ECHA regulations are forcing requalification of supplier relationships for biodegradable packaging specialists. The Ruhr Valley industrial belt is converting underutilized manufacturing facilities into commissary kitchen hubs serving satellite locations.
Global Virtual Restaurant and Ghost Kitchens Market Competitive Landscape
Capital-heavy real estate aggregators compete with asset-light brand operators across the virtual restaurant ecosystem. The vendor base stratifies between infrastructure owners bearing property risk and concept developers licensing kitchen capacity. Three archetypes dominate: real estate-first platforms controlling logistics corridors, multi-brand operators consolidating production protocols, and technology-anchored aggregators optimizing demand forecasting. Competitive positioning hardens through municipal zoning capture and predictive analytics deployment rather than menu differentiation alone.
Within the real estate-first tier, CloudKitchens and Reef Technology exemplify infrastructure-heavy models that anchor urban logistics corridors through property aggregation. Rebel Foods and Kitopi occupy the multi-brand operator archetype, consolidating disparate virtual concepts under centralized production protocols. Kitchen United represents the suburban-focused shared kitchen model, targeting lower-rent zones with flexible tenancy terms designed for secondary metropolitan rings.
| Leading Market Players |
|---|
| CloudKitchens |
| Rebel Foods |
| Kitchen United |
| Reef Technology |
| Zuul Kitchens |
| Kitopi |
| Nextbite Brands |
| C3 (Creating Culinary Communities) |
| Virtual Kitchen Co. |
| Others |
Supply & Pricing Matrix
Premium chef-driven concepts and commodity meal-assembly operations now diverge sharply across both pricing architectures and sourcing configurations. Cloud kitchen operators in the United States command throughput-based premiums while Indian multi-brand facilities absorb FSSAI compliance costs into leaner unit economics.
Pricing Analysis
Throughput-based pricing anchors operator margins, with facilities charging per-order fees scaled to delivery radius and preparation complexity. Price differentiation separates aggregator-dependent brands absorbing platform commissions from direct-channel operators retaining customer data ownership. Pricing pressure stems from third-party delivery aggregators extracting substantial commission fees across United States and United Arab Emirates corridors. Independent single-concept facilities exhibit highest price sensitivity due to fixed overhead burdens, while real estate-first platforms like CloudKitchens leverage scale to resist margin compression.
Supply Chain Analysis
Domestic-content mandates under India's FSSAI licensing framework are reshaping ingredient sourcing toward verified local suppliers. Supply concentration centers on China for automated kitchen equipment, the United States for predictive analytics software, and India for spice and produce inputs. Single-source vulnerability runs through cloud-based order management platforms serving multiple jurisdictions. Distribution runs through aggregator-controlled last-mile networks in urban logistics corridors, with independent operators increasingly constructing captive delivery fleets to reduce platform dependency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
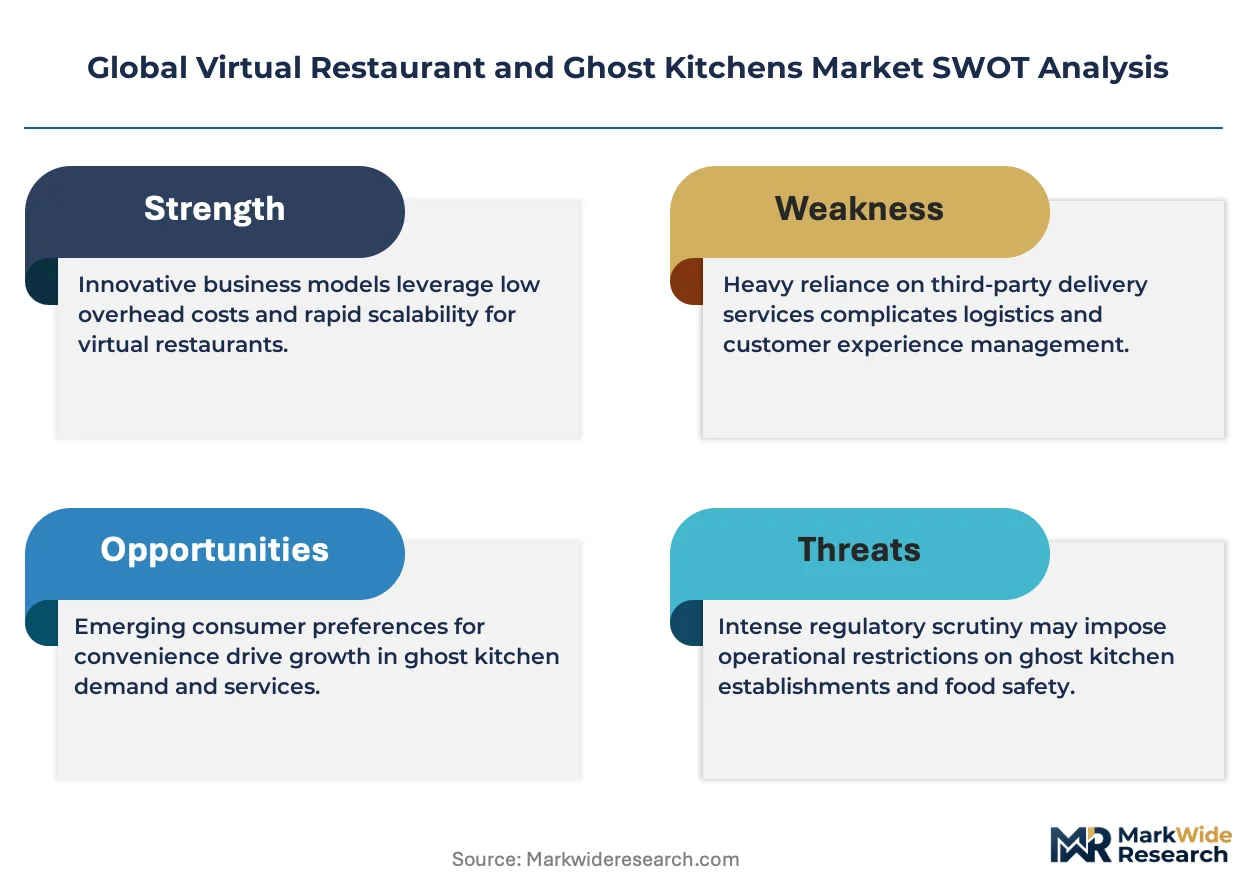
This market functions as a vertical-integration race where upstream control over real estate aggregation and downstream capture of customer data determine sustainable margin structures. Players are pursuing backward integration into proprietary logistics infrastructure to escape platform dependency.
For Market Incumbents: Anticipate zoning recast delays in Singapore and London by securing industrial district permits ahead of municipal board revisions. Reinforce multi-brand density through centralized production protocols that reduce per-concept overhead. Prioritize AI-powered demand forecasting investment to compress ingredient waste and defend margin position against labor cost inflation.
For New Entrants and Emerging Players: Launch via shared kitchen infrastructure in underpenetrated suburban United States metropolitan rings where flexible tenancy terms lower capital barriers. Target meal prep subscription segments displacing transactional orders in Shanghai and Bangalore. Pursue EU Green Deal packaging compliance ahead of deadlines to capture procurement advantages in German and Dutch corridors.
For Investors and Strategic Acquirers: Re-rating potential sits with technology-anchored aggregators deploying predictive analytics given margin recovery acceleration across high-volume delivery corridors. Long-term viability favors operators controlling both production infrastructure and direct customer channels. Watch FSSAI enforcement intensity in India as inflection indicator for cross-border expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Kitchen Automation | CloudKitchens and Kitopi deploy machine learning to compress labor costs and fulfillment times across United States and UAE facilities. |
| Multi-Brand Density Expansion | Rebel Foods consolidates disparate virtual concepts under centralized production protocols optimized for Indian metro throughput. |
| Suburban Shared Kitchen Penetration | Kitchen United targets lower-rent zones in secondary United States metropolitan rings with flexible tenancy infrastructure. |
| EU Green Deal Packaging Compliance | German and Dutch operators accelerate partnerships with biodegradable packaging specialists ahead of REACH mandates. |
| Direct Channel Development | Independent virtual brands construct captive delivery fleets to reduce third-party platform dependency and commission exposure. |
Research Methodology
Independent corroboration across cloud kitchen operators, third-party delivery platform executives, and municipal zoning officials underwrites the qualitative findings. Primary interviews engaged facility managers, food safety compliance officers, and real estate aggregation specialists across United States, Indian, and UAE metropolitan corridors. Secondary validation drew from FSSAI licensing databases, FDA Current Good Manufacturing Practice guidance documents, and EU Green Deal packaging directive filings. Bottom-up facility deployment counts triangulated against top-down market size estimates.
Rate-of-change decomposition across the analysis window segments volume trajectories by business model, kitchen type, end-user channel, and technology integration tier. Modeled dimensions include cloud versus commissary kitchen configurations, multi-brand versus independent operator structures, and AI-powered analytics adoption curves. CAGRs were derived from historical deployment velocity adjusted for regulatory enforcement intensity and real estate cost inflation. Forecast inputs incorporated FSSAI licensing timeline compression and REACH packaging compliance cost premiums.
Municipal zoning recast delays, third-party platform commission escalation, and AI automation deployment failures are the dominant revision risks. Forecasts reflect assumptions regarding sustained urban millennial demand concentration and continued labor shortage pressures across target geographies. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Cambodia Foodservice Market
Food Service
Europe Online Grocery Market
Food Service
United Arab Emirates Quick Service Restaurant Market
Food Service
United Kingdom Foodservice Market
Food Service
Plates Market
Food Service
Commercial Air Fryer Oven Market
Food Service
Europe Out of Home (OOH) Delivery Market
Food Service
Global Sushi Restaurants Market
Food Service
Global Meal Kit Market
Food Service
Food Truck Services Market
Food Service
Onboard Rail Catering Market
Food Service
Saudi Arabia Cloud Kitchen Market
Food Service
Europe Smokeless Indoor Grills Market
Food Service
Countertop Pressure Fryer Market
Food Service
Steam Tables and Food Well Market
Food Service
Global Cafe and Bars Market