
 Gluten-Free Bakery Products Market | 2026-2036
Gluten-Free Bakery Products Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten-Free Bakery Products Market Analysis
Food service procurement is decoupling from commodity wheat-based sourcing as institutional kitchens and restaurant chains build separate gluten-free prep lines. General Mills leverages its cereal manufacturing infrastructure to achieve batch segregation at scale. Dr. Schär AG anchors European supply into North American food service through dedicated gluten-free facilities in Italy and the United States. Bob's Red Mill Natural Foods differentiates via in-house milling of certified gluten-free oats and alternative flours.
Gluten-free bakery products are formulated goods manufactured without wheat, barley, rye, or their crossbred variants, typically employing rice flour, tapioca starch, or almond flour as structural replacements with hydrocolloid binders to replicate gluten's viscoelastic properties; these products serve celiac patients, gluten-sensitive consumers, and lifestyle buyers seeking reduced-wheat diets. Breads dominate volume due to daily consumption frequency, though cookies command higher per-unit margins through premium positioning and gift-packaging applications. Almond flour formulations lead ingredient-type growth as protein-forward positioning attracts paleo and keto-adjacent buyers beyond the celiac core. Supermarkets remain the primary distribution channel, but online retail is gaining share where subscription models address replenishment needs for chronic-condition consumers.
The FDA enforces gluten-free labeling standards requiring under 20 parts per million gluten content, while the EU's Regulation (EC) No 41/2009 mandates equivalent thresholds with additional pre-market notification in member states. Health Canada and the FSSAI in India maintain parallel but non-harmonized certification regimes that fragment export compliance for multinational manufacturers. Stakeholders must monitor evolving threshold debates as detection technologies push toward 10 ppm sensitivity and regulators weigh whether stricter standards would meaningfully benefit diagnosed celiac populations without constraining supply availability.
Market Dynamics
Batch segregation infrastructure is forcing capital reallocation across bakery manufacturing as food service operators demand dedicated gluten-free prep lines separate from wheat-based production. This operational bifurcation is reshaping facility design and procurement patterns.
Growth Catalysts
- Celiac awareness campaigns:Patient advocacy groups in the United States have driven diagnostic rates upward, expanding the addressable patient population requiring medically necessary gluten-free diets.
- FDA gluten-free labeling rule:The 20 ppm threshold provides legal clarity that reduces consumer confusion and enables premium pricing for verified products.
- Almond flour protein positioning:Paleo and keto dietary frameworks are pulling non-celiac consumers into gluten-free bakery categories through macronutrient marketing.
Market Restraints
- Certified oat supply concentration:Purity-protocol oat sourcing is geographically concentrated in North American growing regions, creating input vulnerability.
- Cross-contamination detection costs:ELISA testing and mass spectrometry requirements add per-batch analytical expenses that commodity wheat baking avoids.
- Hydrocolloid price volatility:Xanthan gum and guar gum supply fluctuations in Asian processing hubs destabilize formulation economics.
Strategic Opportunities
- Subscription replenishment models:Direct-to-consumer channels targeting celiac households with auto-ship bread programs capture lifetime value through chronic-condition purchasing.
- EU Regulation (EC) No 41/2009 harmonization:Pre-market notification standardization across member states simplifies pan-European product registration for exporters.
- Food service ingredient kits:Pre-measured gluten-free baking mixes for restaurant chains reduce on-site cross-contamination risk while capturing margin.
Industry Challenges
- Sanitation protocol labor intensity:Dedicated gluten-free lines require validated cleaning procedures that extend changeover times and constrain throughput.
- Dual certification complexity:Simultaneous organic and gluten-free audits from USDA-accredited bodies and third-party celiac organizations multiply compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten-Free Bakery Products Market |
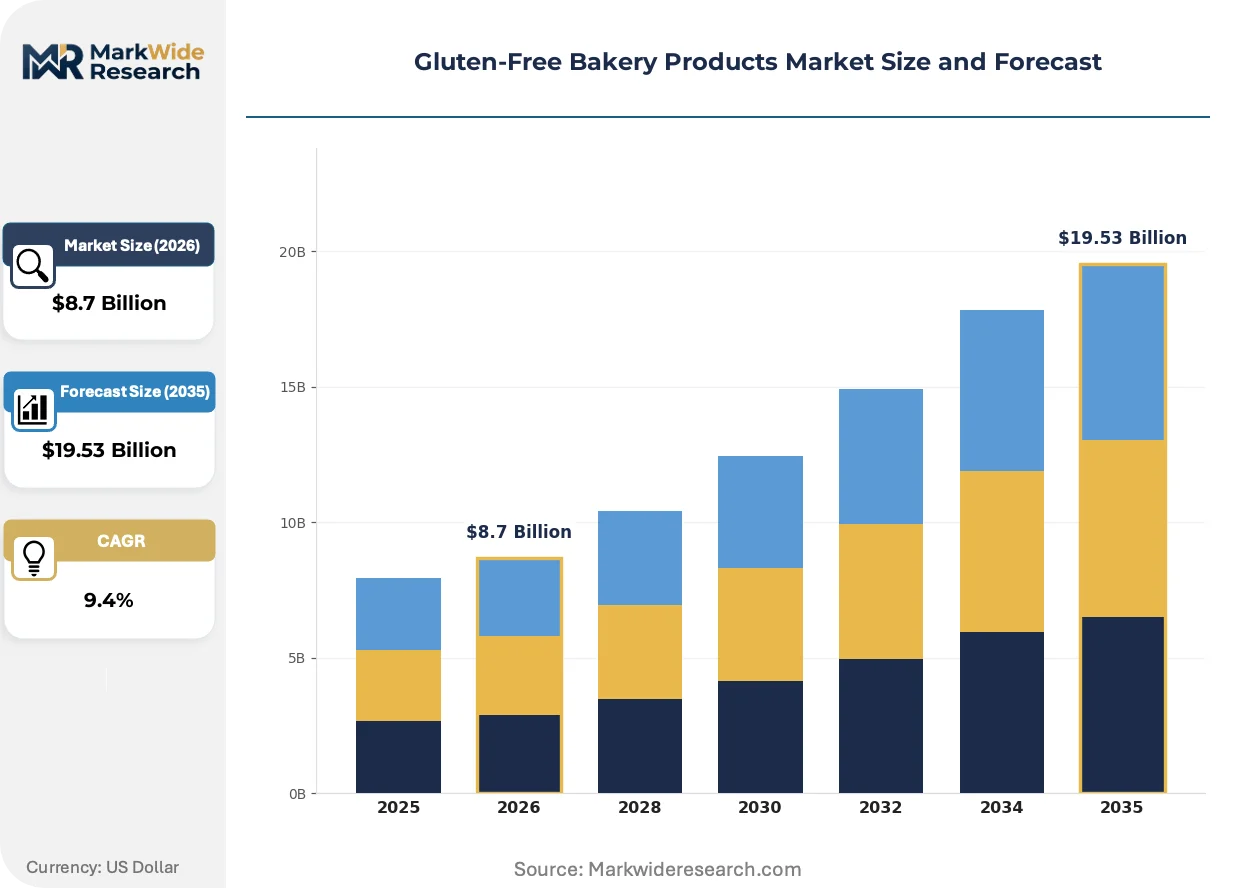
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breads, Cookies, Cakes, Muffins End User: Retail Consumers, Food Service, Catering Services, Health Food Stores Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Ingredient Type: Almond Flour, Coconut Flour, Tapioca Starch, Others |
| Companies Covered | General Mills, Dr. Schär AG, Bob's Red Mill Natural Foods, The Hain Celestial Group, Conagra Brands, Amy's Kitchen, Dawn Food Products, Grupo Bimbo, Canyon Bakehouse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten-Free Bakery Products Market Emerging Trajectories
Reformulation science is advancing rapidly as manufacturers seek functional replacements for wheat gluten's viscoelastic properties. These developments are compressing quality gaps between conventional and gluten-free sensory profiles.
High-pressure processing is automating the structural modification of rice and legume proteins to mimic gluten network formation without chemical additives. Mid-scale regional bakeries in Germany and the United States are piloting this equipment to reduce hydrocolloid dependency. The technology is automating what previously required artisan-level manual intervention, enabling scaled production of artisan-style loaves.
REACH chemical registration requirements in the European Union are tightening scrutiny on processing aids used in gluten-free manufacturing, particularly modified starches and emulsifiers. Manufacturers reformulating for compliance are accelerating clean-label ingredient transitions ahead of consumer-driven timelines. Bakery categories targeting children and institutional feeding programs face the steepest reformulation curves under these rules.
Subscription-based replenishment is displacing supermarket center-store purchasing among diagnosed celiac households who prioritize supply security over price comparison. Direct-to-consumer channels with guaranteed batch-testing documentation are capturing loyalty from this segment. The United States and United Kingdom show the highest subscription penetration, where urban delivery density supports cold-chain bread distribution economics.
Gluten-Free Bakery Products Market Segmentation
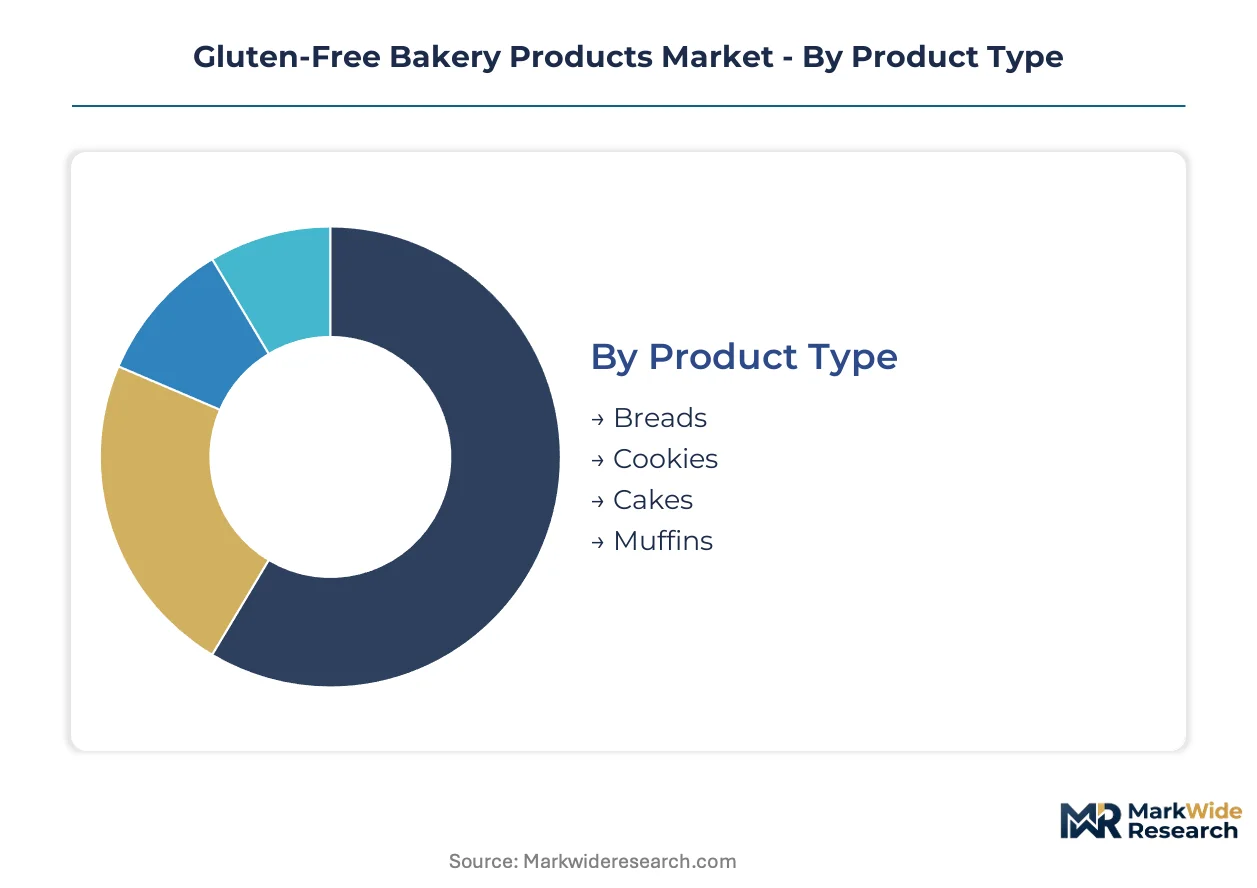
Gluten-free bakery segmentation reflects divergent technical requirements across consumption occasions and supply chain configurations. Product formulation complexity, contamination risk protocols, and channel-specific certification demands create distinct competitive arenas within each dimension.
Product Type:
Structural requirements vary dramatically by product category, with viscoelastic replacement needs driving formulation differentiation.
- Breads:Daily consumption frequency anchors volume demand, though loaf structure demands hydrocolloid binders at 2-4% inclusion rates to replicate gluten network elasticity. Food service operators in the United States specify dedicated prep lines for sandwich bread programs, with batch segregation protocols adding 15-20% production overhead.
- Cookies:Lower structural demands permit cleaner label formulations with reduced additive dependency. Premium gift-packaging applications in European markets command margin multiples through seasonal positioning and certified facility sourcing.
- Cakes:Aeration requirements favor modified starch systems and emulsifier blends for crumb structure.
- Muffins:Quick-bread chemistry accommodates denser alternative flours with minimal binder supplementation.
Breads lead on scale; cookies lead on momentum.
End User:
Procurement sophistication and contamination tolerance thresholds segment demand by customer type.
- Retail Consumers:Subscription replenishment models capture diagnosed celiac households seeking supply security over price elasticity. Direct-to-consumer channels with batch-testing documentation command loyalty premiums in urban United States and United Kingdom markets.
- Food Service:Institutional kitchens and restaurant chains drive capital allocation toward dedicated gluten-free prep lines, with operational bifurcation reshaping facility design and ingredient procurement patterns.
- Catering Services:Event-based demand concentrates in metropolitan clusters with celiac population density.
- Health Food Stores:Curated assortment and staff expertise justify shelf-space premiums for certified products.
Food service leads on scale; retail consumers lead on momentum.
Distribution Channel:
Channel economics reflect cold-chain requirements, certification documentation needs, and replenishment velocity.
- Supermarkets:Center-store placement and dedicated shelf-space investments by specialty retail chains in the United States anchor mainstream accessibility. Planogram negotiations favor manufacturers with multi-SKU breadth and verified supply chain documentation.
- Online Retail:Subscription auto-ship programs address chronic-condition purchasing patterns with guaranteed inventory availability. Cold-chain bread distribution economics depend on urban delivery density.
- Specialty Stores:Staff expertise and curated certification standards attract premium-seeking diagnosed consumers.
- Direct Sales:Farmers market and bakery-direct channels emphasize freshness claims and local production narratives.
Supermarkets lead on scale; online retail leads on momentum.
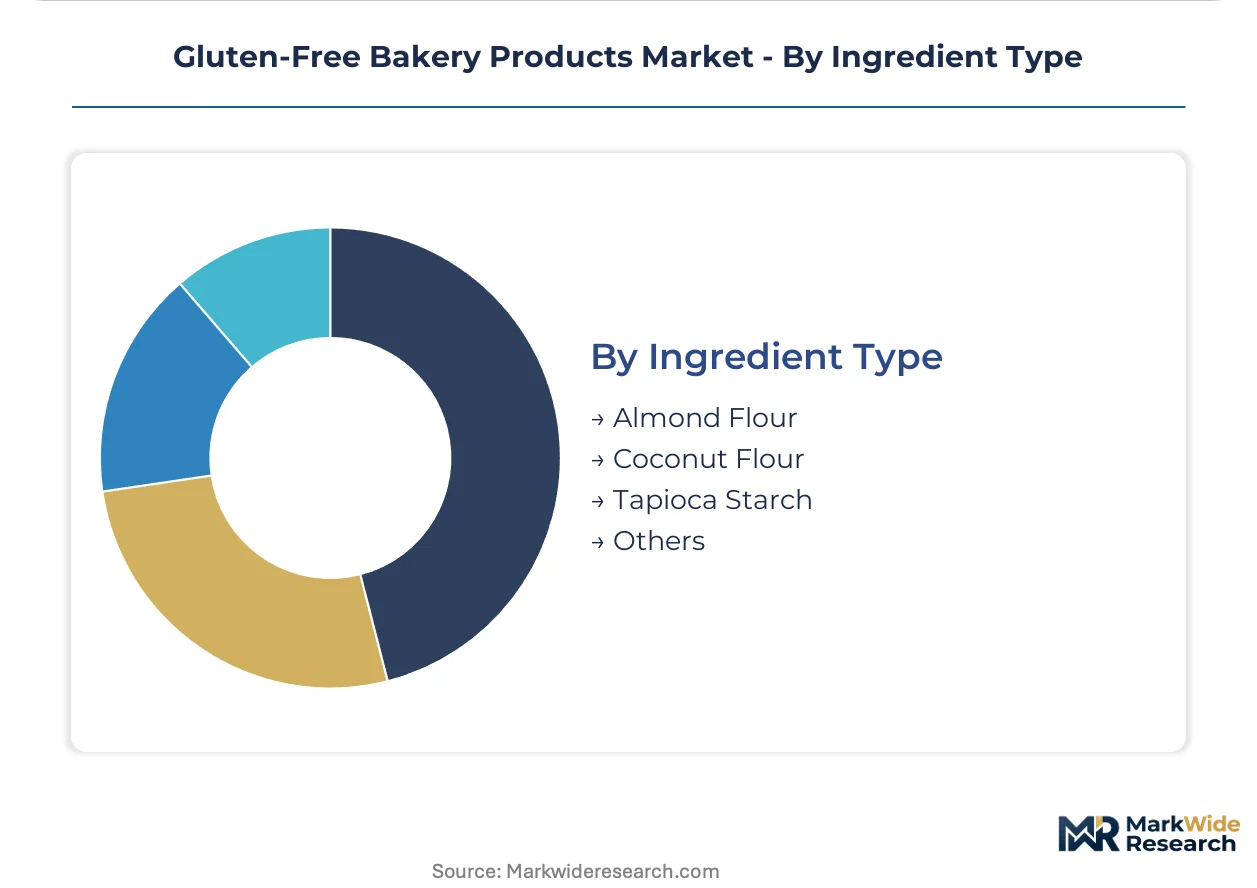
Ingredient Type:
Functional properties and supply security differentiate alternative flour sourcing strategies.
- Almond Flour:Protein-forward positioning at 6-8g per serving attracts paleo and keto-adjacent consumers beyond the celiac core. California orchard supply concentration creates price volatility exposure during drought cycles.
- Tapioca Starch:Neutral flavor profile and clean-label acceptance support broad formulation compatibility.
- Coconut Flour:High fiber content and saturated fat chemistry require hydration adjustments in production.
- Others:Rice flour, sorghum, and legume-based systems serve regional formulation traditions and cost-sensitive applications.
Almond flour leads on scale; tapioca starch leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redirecting gluten-free bakery investment toward jurisdictions with streamlined certification regimes and established ingredient supply chains. Manufacturers are relocating production to exploit cost-of-compliance gaps between strict 20 ppm enforcement markets and emerging economies with nascent regulatory infrastructure.
United States
Diagnostic rates for celiac disease have climbed steadily as patient advocacy groups expand screening campaigns across the Midwest and Northeast. The FDA maintains its 20 ppm gluten-free labeling threshold with substantiation requirements that favor large-scale manufacturers with dedicated batch-segregation facilities. Minneapolis and Chicago anchor the country's largest gluten-free manufacturing clusters, where General Mills operates cereal-adjacent production lines.
Germany
European demand for certified gluten-free bread concentrates in urban centers with high celiac diagnostic density, particularly Berlin and Munich. EFSA guidance on gluten thresholds aligns with Regulation (EC) No 41/2009, though REACH chemical registration requirements are tightening scrutiny on modified starches and hydrocolloid binders. The Baden-Württemberg region hosts pilot facilities testing high-pressure protein modification equipment for reduced-additive formulations.
Italy
Traditional wheat-centric consumption patterns are shifting as Mediterranean diet adaptations incorporate gluten-free alternatives for lifestyle consumers beyond diagnosed celiac populations. Dr. Schär AG maintains dedicated gluten-free facilities in northern Italy that supply North American food service channels through integrated transatlantic distribution. The Emilia-Romagna bakery cluster is diversifying into certified oat and almond flour processing for export markets.
Canada
Health Canada's gluten-free standard mirrors the FDA's 20 ppm threshold, creating regulatory continuity that simplifies cross-border manufacturing for US-based multinationals. Purity-protocol oat sourcing from the Prairie Provinces supplies North American hydrocolloid-dependent formulations. Toronto and Vancouver metropolitan areas show the highest per-capita gluten-free product consumption, driving retail shelf-space expansion at specialty chains.
Australia
FSANZ gluten labeling requirements and high diagnostic awareness have cultivated a mature consumer base with low price elasticity for verified products. The country's isolation has spurred domestic manufacturing investment to reduce import dependency for fresh bread categories. Melbourne and Sydney host the primary gluten-free bakery clusters, with direct-to-consumer subscription models penetrating suburban markets at rates exceeding European benchmarks.
Gluten-Free Bakery Products Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with retail shelf-space concentration favoring diversified food conglomerates while food service channels reward dedicated gluten-only facilities. The vendor base organizes into three tiers: multinational CPG platforms with cereal infrastructure, European specialists with transatlantic supply networks, and regional millers with certified oat capabilities. Competitive positioning hinges on batch-segregation capital deployment and dual certification mastery rather than ingredient cost alone. M&A activity targets regional brands with established retail distribution, while capacity expansion concentrates in Italy and the US Midwest to serve transatlantic demand corridors.
Within the multinational platform tier, General Mills leverages its Minneapolis manufacturing footprint to achieve scale economics in bread and cookie categories that smaller specialists cannot replicate. Dr. Schär AG, the Bolzano-based specialist, anchors European supply into North American food service through dedicated facility networks spanning both continents. Bob's Red Mill Natural Foods occupies a distinct position among certified-oat millers, with in-house milling capabilities that reduce supply chain vulnerability for purity-protocol sourcing. These three archetypes—diversified CPG, transatlantic specialist, and vertical oat miller—represent the structural poles around which remaining competitors must position.
| Leading Market Players |
|---|
| General Mills |
| Dr. Schär AG |
| Bob's Red Mill Natural Foods |
| The Hain Celestial Group |
| Conagra Brands |
| Amy's Kitchen |
| Dawn Food Products |
| Grupo Bimbo |
| Canyon Bakehouse |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between FDA-verified 20 ppm products and uncertified alternatives manifests in both shelf-price premiums and facility-investment requirements. Manufacturers maintaining dedicated batch-segregation lines command higher unit economics while commodity bakers absorb cross-contamination testing costs that compress margins.
Pricing Analysis
Distributor margins for gluten-free bakery products stratify across premium, standard, and economy tiers based on certification documentation depth and brand verification status. Price differentiation hinges on gluten-test batch documentation and organic dual-certification overhead, with food service channels showing lowest price sensitivity due to liability concerns. Cost compression in the standard tier intensifies as private-label entrants replicate basic formulations without dedicated facility investments. Retail consumers with diagnosed celiac disease exhibit least price sensitivity, prioritizing supply security over per-unit cost comparison.
Supply Chain Analysis
Certification gating through FDA gluten-free labeling enforcement and third-party celiac organization audits restricts supplier eligibility to facilities with validated sanitation protocols. Purity-protocol oat sourcing concentrates in the United States and Canada, while almond flour supply rests on California orchard output vulnerable to drought cycles. Single-source vulnerability in Asian hydrocolloid processing hubs for xanthan and guar gum creates formulation cost volatility. Distribution runs through supermarket center-store placement, direct-to-consumer subscription channels, and food service ingredient kit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gluten-free bakery market functions as a regulatory compounder where FDA's 20 ppm labeling threshold permanently expanded the addressable patient population by reducing consumer confusion and enabling premium positioning for verified products.
For Market Incumbents: Hedge against hydrocolloid price volatility through backward integration into alternative binder technologies or long-term supply agreements with Asian processing hubs. Expand batch-segregation capacity in the US Midwest and northern Italy to defend margin position against regional specialists capturing food service share. Prioritize dual organic-gluten-free certification mastery as competitive moat. For New Entrants and Emerging Players: Begin with subscription replenishment models targeting diagnosed celiac households in urban United States and United Kingdom markets where delivery density supports cold-chain economics. White-space opportunity concentrates in pre-measured food service ingredient kits for restaurant chains seeking reduced on-site cross-contamination risk. Pursue direct-to-consumer go-to-market positioning with guaranteed batch-testing documentation. For Investors and Strategic Acquirers: Consolidation pressure builds where regional brands possess established retail distribution but lack capital for dedicated facility expansion. Long-term viability favors transatlantic specialists with integrated Italy-US manufacturing footprints and certified-oat millers with in-house purity-protocol sourcing. Watch for threshold debates shifting toward 10 ppm detection sensitivity as inflection indicator for compliance-cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Batch-Segregation Facility Expansion | General Mills leverages Minneapolis cereal infrastructure to achieve dedicated gluten-free production scale. |
| Subscription Replenishment Launch | Direct-to-consumer auto-ship programs capture lifetime value from chronic-condition celiac households. |
| Dual Certification Investment | Simultaneous organic and gluten-free audits from USDA-accredited bodies multiply compliance overhead. |
| Alternative Binder R&D | High-pressure protein modification reduces hydrocolloid dependency and REACH registration exposure. |
| Food Service Ingredient Kit Development | Pre-measured mixes reduce restaurant cross-contamination risk while capturing margin from chain procurement. |
Methodological Framework
Bottom-up food service and retail consumer modeling reconciled against top-down ingredient supply and manufacturing capacity tracking forms the analytical core. Primary interviews with bakery procurement directors, celiac patient advocacy group executives, supermarket category buyers, food service operators, and third-party certification auditors combined with secondary validation from FDA labeling guidance documents, USDA organic certification databases, EFSA scientific opinions, and trade flow records for alternative flours and hydrocolloids. Triangulation across these sources ensures segmentation integrity.
Historical trendline analysis of celiac diagnostic rates, gluten-free product shelf-space expansion, and subscription channel penetration established baseline growth patterns. The projection framework models product type, end user, distribution channel, and ingredient type dimensions across the analysis window, with CAGRs derived from elasticity-adjusted demand curves and capacity-constrained supply trajectories. Forecast inputs include purity-protocol oat harvest projections and high-pressure processing equipment adoption curves in regional bakery clusters.
Several conditions sit outside the modeled scope, including potential FDA threshold reduction below 20 ppm, EFSA harmonization with stricter member-state regimes, and climate-induced almond flour supply disruption. Forecasts reflect documented assumptions regarding diagnostic rate trajectories and food service operator adoption of dedicated prep lines. Deviation in regulatory threshold stringency or hydrocolloid supply stability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Frozen Bakery Market
Bakery Products
Pizza Crust Market
Bakery Products
Low Fat Oatmeal Cookies Market
Bakery Products
Bakery Fats Market
Bakery Products
GCC Bakery Products Market
Bakery Products
Pancake Mixes Market
Bakery Products
Bakery Premixes Market
Bakery Products
Soft Biscuit Market
Bakery Products
Premix Bread Flour Market
Bakery Products
Healthy Biscuits Market
Bakery Products
Global Rice Cakes Market
Bakery Products
Organic Frozen Bakery Market
Bakery Products
Low Calorie Bread Market
Bakery Products
Ready-To-Finish Bakery Products Market
Bakery Products
Cakes and Pastries Market
Bakery Products
Global Bakery Product Market