
 Prior Authorization Software Market | 2026-2036
Prior Authorization Software Market Size, Share, and Industry Trends Forecast 2026-2036
Prior Authorization Software Market Insights
Cloud infrastructure investment across North American health IT vendors is expanding processing capacity for real-time eligibility verification and automated decision engines. CoverMyMeds leverages its pharmacy network integration to dominate prescription prior authorization workflows. Waystar sustains competitive positioning through revenue cycle management bundling that embeds authorization automation within broader claims operations. Cohere Health differentiates via AI-driven clinical intelligence that reduces manual peer-to-peer review requirements.
Prior authorization software comprises digital platforms that automate the submission, tracking, and adjudication of medical service and pharmaceutical coverage approvals, typically incorporating HL7 FHIR APIs, rules-based clinical logic engines, and EHR-integrated workflow orchestration to replace fax-and-phone-based processes. The primary commercial purpose is reducing administrative cost burden while accelerating patient access to prescribed therapies and procedures. Integrated Platforms command the largest installed base as health systems consolidate point solutions into unified revenue cycle stacks, while SaaS Solutions represent the fastest expansion trajectory due to lower capital requirements and faster implementation cycles. Cloud-Based deployment leads new installations, though Hybrid architectures persist among large payer organizations managing legacy core systems alongside modern API layers.
FDA digital health guidance, HIPAA security rule enforcement, and CMS interoperability mandates collectively shape product architecture requirements and procurement criteria for authorization software vendors. The Interoperability and Prior Authorization Final Rule specifically requires Medicare Advantage plans to implement FHIR-based APIs, directly stimulating platform replacement cycles. Stakeholders must monitor evolving state-level prior authorization reform legislation and payer-specific API maturity to anticipate workflow standardization timelines and compliance investment requirements.
Market Dynamics
CMS Interoperability and Prior Authorization Final Rule mandates are compressing implementation timelines for FHIR-based API infrastructure across Medicare Advantage networks and forcing synchronous technology procurement cycles.
Growth Catalysts
- HL7 FHIR API Mandates:CMS regulations require standardized electronic data exchange between payers and providers, eliminating fax-based workflows and accelerating platform modernization investments.
- Hospital System Consolidation:Health system mergers are creating unified revenue cycle operations that demand centralized prior authorization orchestration across multi-facility networks.
- Real-Time Eligibility Engines:Cloud-native decision support systems enable instantaneous coverage verification at point-of-care, reducing administrative labor and patient access delays.
Market Restraints
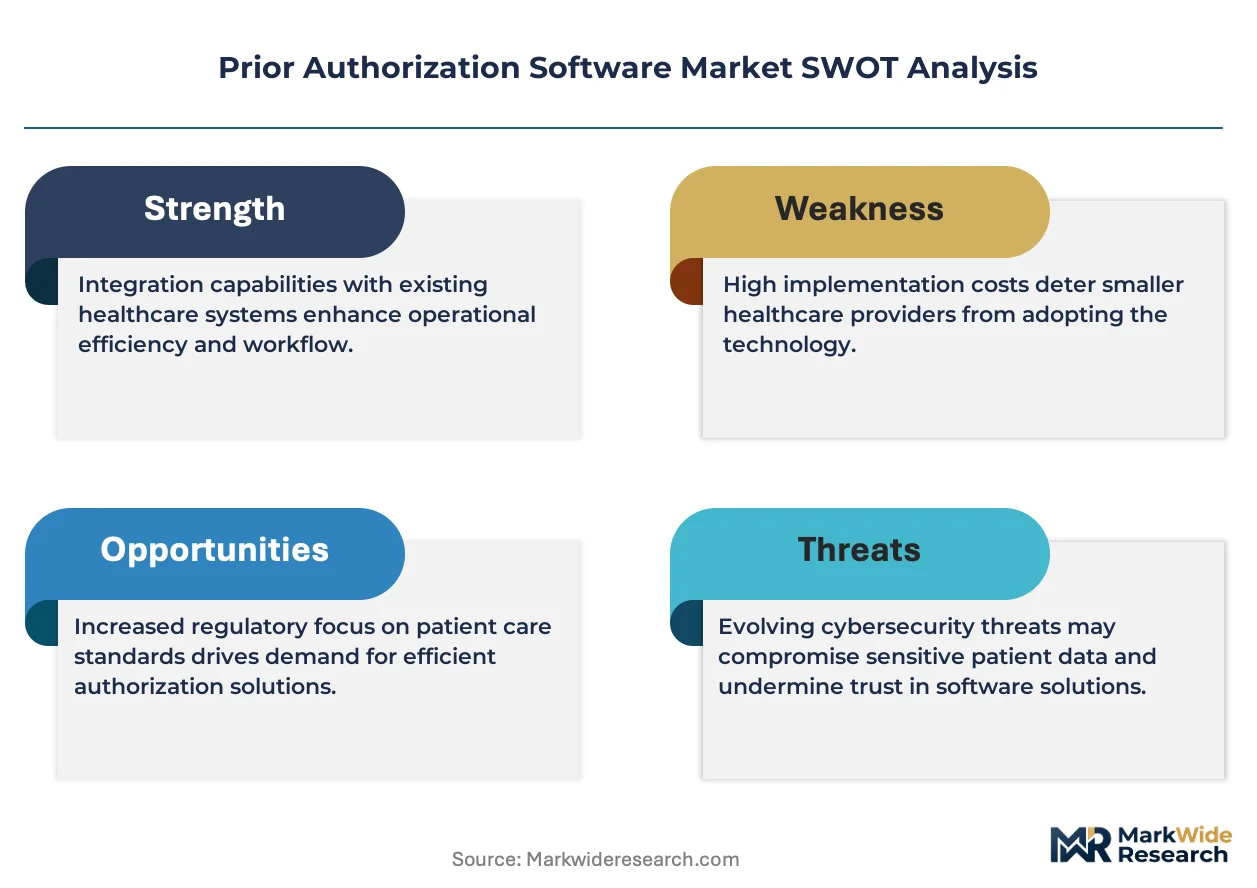
- Legacy Core System Dependencies:Large commercial payers maintain decades-old claims processing infrastructure that resists API-layer integration without costly middleware development.
- State-Level Regulatory Fragmentation:Prior authorization reform legislation varies across California, Texas, New York and other major markets, complicating national platform standardization efforts.
- Specialty Pharmacy Network Complexity:Biologics and cell therapy authorization pathways require manufacturer-specific hub programs that resist generic automation workflows.
Strategic Opportunities
- Specialty Care Vertical Expansion:Oncology, rheumatology and neurology clinics face the highest denial rates and present concentrated demand for AI-assisted clinical documentation.
- Medicaid Expansion States:Arkansas, Missouri and Oklahoma recently expanded eligibility, creating new payer-processor relationships requiring authorization infrastructure deployment.
- Interoperability Certification Programs:ONC Cures Act Final Rule compliance incentives reward vendors achieving standardized data exchange credentials, creating procurement preference advantages.
Industry Challenges
- Clinical Informatics Talent Scarcity:Health systems compete for professionals capable of configuring rules-based logic engines and maintaining payer-specific clinical criteria libraries.
- EHR Integration Complexity:Epic, Cerner and MEDITECH implementations require customized workflow mapping that extends deployment timelines and inflates professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prior Authorization Software Market |
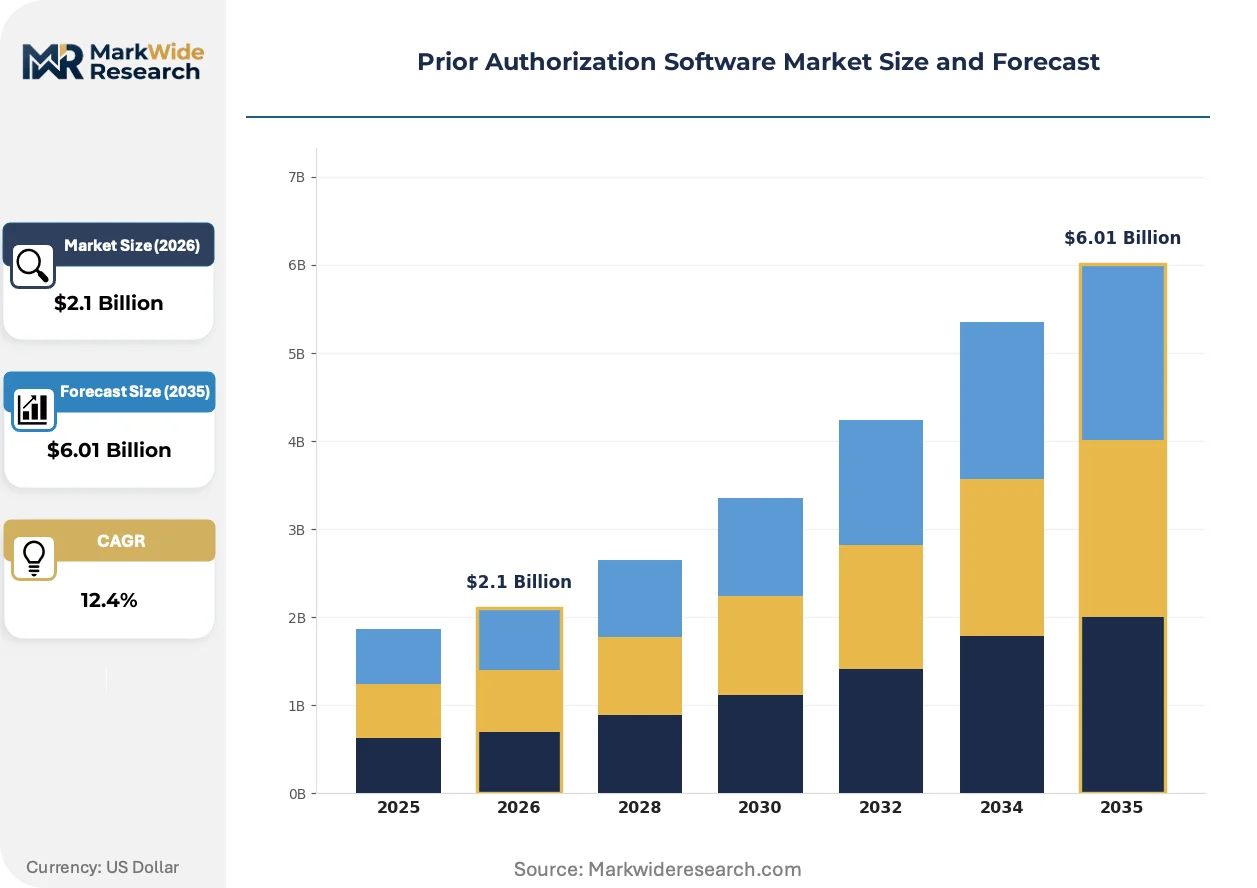
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $6.01 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Solutions, Integrated Platforms, SaaS Solutions, On-Premise Software End User: Healthcare Providers, Insurance Companies, Pharmacies, Third-Party Administrators Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Compliance Standard: HIPAA, URAC, ANSI, CAQH |
| Companies Covered | CoverMyMeds (McKesson), Waystar, Myndshft, Cohere Health, Innovaccer, Availity, Surescripts, Spry, EthermedAI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prior Authorization Software Market Trends and Innovations
Prior authorization software architecture is fragmenting from monolithic suites into composable microservices that health systems selectively deploy against specific payer relationships and clinical service lines.
Artificial intelligence is modularizing clinical decision support by separating natural language processing for medical record review from predictive analytics for denial risk scoring. Large health systems in Texas and Florida are deploying these components asynchronously rather than replacing entire authorization stacks. This modularity enables targeted automation of high-volume service categories while preserving manual workflows for complex cases requiring peer-to-peer review.
CMS Interoperability and Prior Authorization Final Rule enforcement is compelling Medicare Advantage plans to expose provider-facing APIs for standard authorization transactions by 2026. Payer technology teams are re-architecting member portals and clinical data repositories to support real-time eligibility queries and automated determination responses. Medicare Advantage organizations with legacy AS/400 and mainframe infrastructure face the steepest replatforming costs and longest implementation horizons.
Provider procurement patterns are compressing vendor selection cycles as health system executives consolidate purchasing authority within centralized digital transformation offices. Traditional best-of-breed authorization point solutions lose evaluation rounds to revenue cycle management platforms bundling authorization automation with claims management and patient financial engagement. Integrated delivery networks in Pennsylvania and Ohio have recently issued combined RFPs spanning prior authorization, eligibility verification and denial management under single-vendor contracts.
Prior Authorization Software Market Segmentation
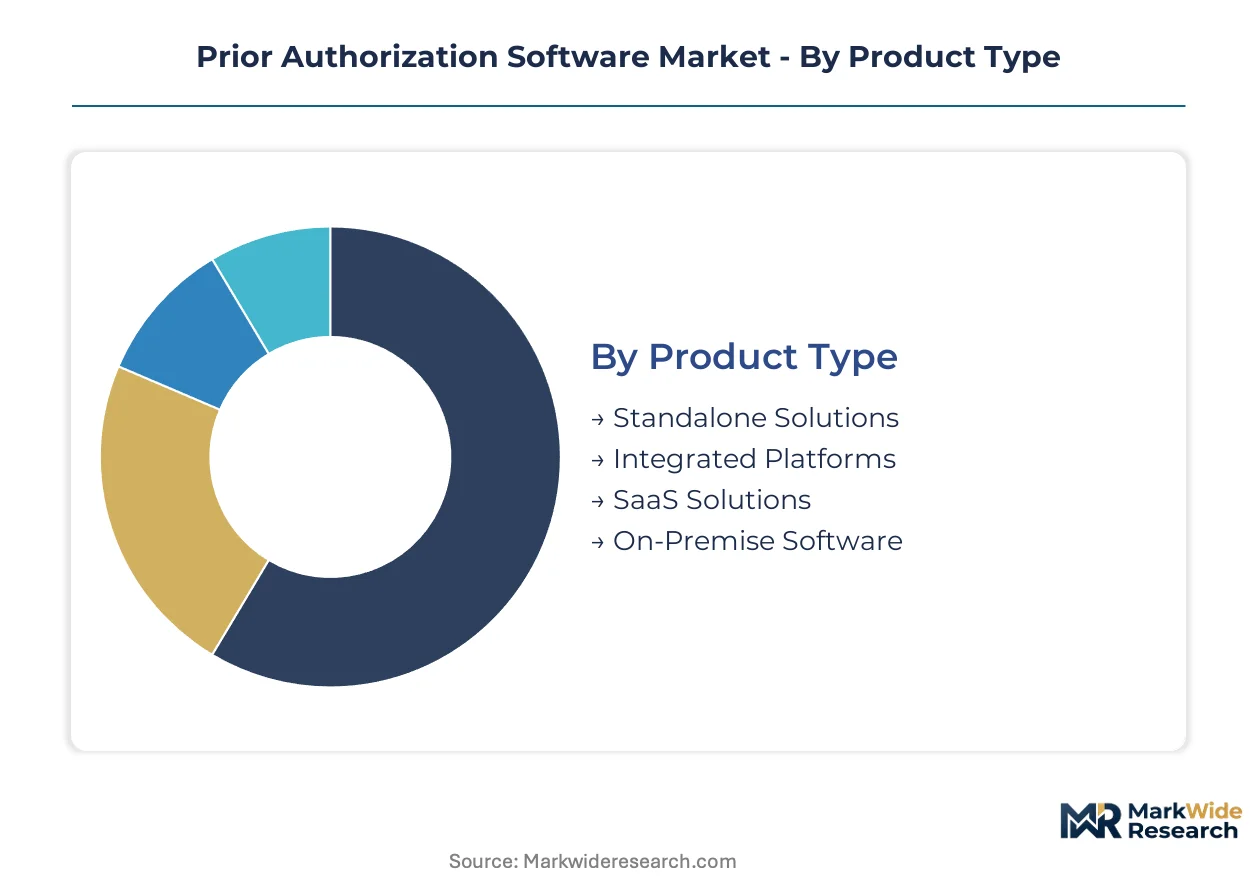
Prior authorization software procurement varies sharply by buyer technical maturity and legacy infrastructure commitments. Health systems with centralized IT governance favor unified platforms, while specialized clinics pursue targeted SaaS deployments. Deployment choices directly determine API architecture requirements and CMS compliance timelines.
Product Type:
Buyers in this category differentiate by existing revenue cycle stack complexity and capital deployment flexibility.
- Integrated Platforms:Unified authorization modules embedded within enterprise revenue cycle suites consolidate multi-facility workflows through single vendor relationships. Large hospital systems in Pennsylvania and Ohio demand these configurations to standardize prior authorization orchestration across acquired community hospitals and specialty clinics.
- SaaS Solutions:Subscription-based authorization platforms deploy through cloud-native architectures with minimal on-site infrastructure requirements. Independent rheumatology and oncology practices in Texas and Florida select these offerings to accelerate implementation without IT staff expansion.
- Standalone Solutions:Point authorization systems address specific payer relationships or service lines without broader revenue cycle integration.
- On-Premise Software:Locally hosted authorization platforms persist among payers with stringent data residency requirements or legacy security protocols.
Integrated Platforms lead volumes today; SaaS Solutions are gaining share fastest.
End User:
Procurement authority in this category concentrates by organization scale and claims volume exposure.
- Healthcare Providers:Hospital systems and specialty clinics deploy authorization automation to reduce administrative labor and accelerate patient access to prescribed therapies. Multi-facility networks in California and New York prioritize EHR-integrated workflows that eliminate fax-based submission processes.
- Insurance Companies:Commercial payers and Medicare Advantage plans invest in FHIR-based API infrastructure to meet CMS interoperability mandates. Organizations with legacy AS/400 and mainframe systems face the steepest replatforming costs to support real-time eligibility queries.
- Pharmacies:Retail and specialty pharmacy networks require prescription-specific authorization workflows integrated with dispensing systems.
- Third-Party Administrators:Benefits administrators serving self-insured employers seek modular authorization components for multi-payer configuration management.
Healthcare Providers anchor current procurement; Insurance Companies are expanding investment most rapidly.
Deployment:
Infrastructure decisions here pivot on data sovereignty requirements and legacy system interdependencies.
- Cloud-Based:Fully hosted authorization platforms enable elastic processing capacity for real-time eligibility verification and automated decision engines. Medicare Advantage organizations select these deployments to accelerate CMS compliance without capital-intensive data center expansion.
- Hybrid:Architectures combining cloud-native API layers with on-premises core systems accommodate large payers managing decades-old claims infrastructure. Commercial insurers in legacy technology environments deploy hybrid models to modernize provider-facing interfaces while preserving existing member databases.
- On-Premises:Entirely local deployments satisfy organizations with stringent data residency or air-gapped security requirements.
- Mobile:Smartphone-optimized authorization applications support point-of-care submission and status tracking for ambulatory providers.
Cloud-Based deployments dominate new installations; Hybrid architectures are climbing the fastest among established payers.
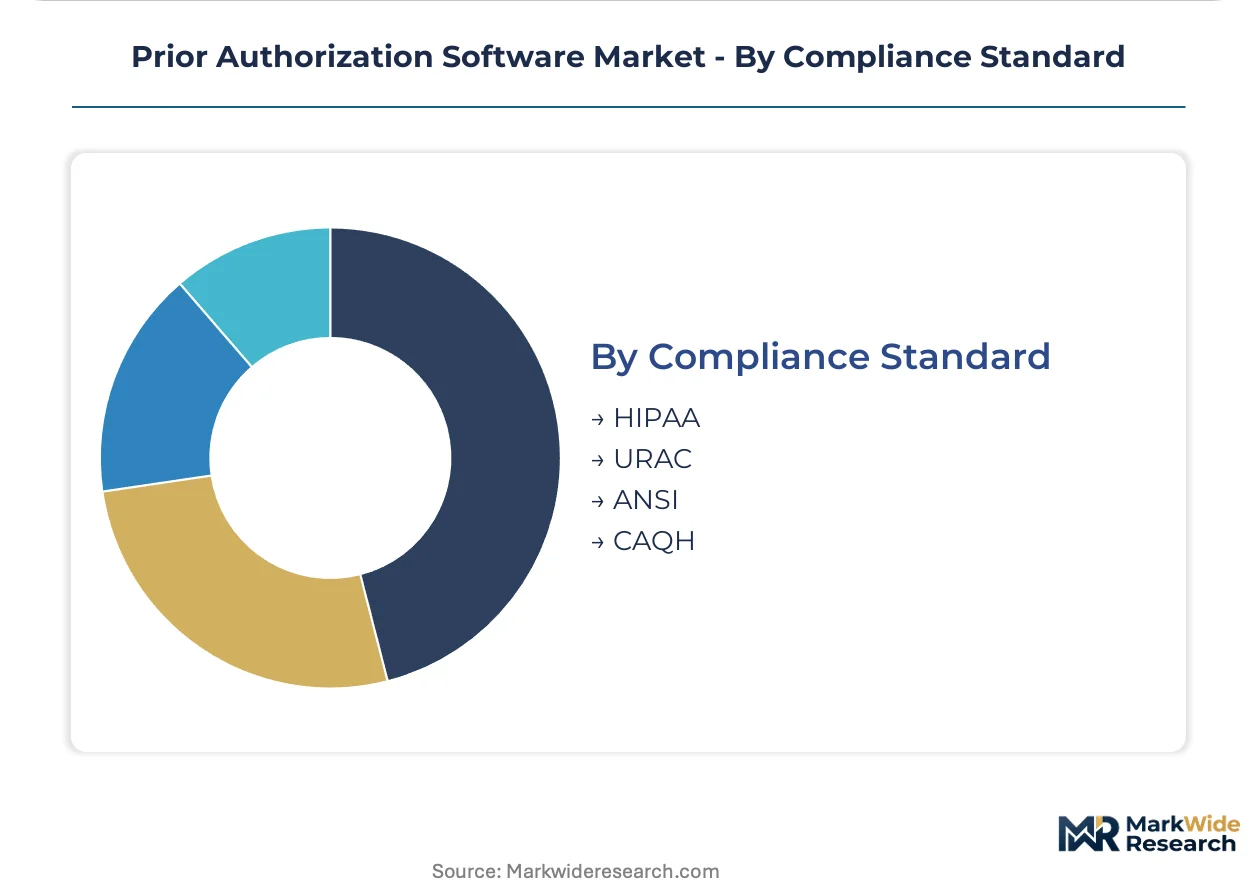
Compliance Standard:
Certification requirements in this category segment buyers by regulatory exposure and payer contract obligations.
- HIPAA:Privacy and security rule compliance forms the baseline procurement filter for all US healthcare software acquisitions. Authorization platforms must demonstrate encrypted data transmission, access logging, and business associate agreement readiness to qualify for hospital system vendor lists.
- URAC:Utilization management accreditation signals clinical criteria rigor and appeals process integrity to commercial payers. Medicare Advantage plans require URAC-certified authorization vendors for delegated utilization management contracts.
- ANSI:X12 EDI transaction standards enable standardized electronic data exchange between payers and providers.
- CAQH:Committee on Operating Rules for Information Exchange certification streamlines administrative simplification compliance for multi-payer environments.
HIPAA compliance is universal; URAC accreditation is expanding most quickly among vendor differentiation strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in prior authorization software procurement concentrates investment in jurisdictions where CMS mandates create compliance-driven technology refresh cycles, while cost-sensitive providers in less regulated markets delay platform modernization.
United States
Hospital systems in Pennsylvania and Ohio consolidate purchasing authority within centralized digital transformation offices, accelerating vendor selection cycles for bundled revenue cycle platforms. CMS Interoperability and Prior Authorization Final Rule enforcement compels Medicare Advantage plans to expose FHIR-based APIs by 2026. Texas and Florida health systems deploy modular AI components asynchronously rather than replacing entire authorization stacks.
Germany
Commercial payers in Baden-Württemberg and Bavaria invest in middleware development to bridge decades-old claims infrastructure with modern API layers. The country's national health technology regulator evaluates digital health applications for reimbursement eligibility, shaping procurement criteria for authorization software vendors. Berlin-Brandenburg health IT clusters concentrate development of HL7 FHIR-compliant workflow orchestration tools for export markets.
United Kingdom
NHS England's digitization programs drive demand for cloud-native eligibility verification systems across integrated care systems in London and the Southeast. The national health service's interoperability standards mandate standardized electronic data exchange between trusts and commissioning groups. Manchester and Birmingham health economies pilot automated prior authorization workflows for specialty pharmaceuticals within regional procurement frameworks.
Canada
Provincial health authorities in Ontario and Quebec modernize authorization infrastructure to reduce administrative burden on multi-payer provider networks. Health Canada digital health guidance shapes product architecture requirements for vendors seeking national procurement contracts. Vancouver and Toronto health technology clusters develop hybrid deployment architectures accommodating legacy core systems alongside modern API layers.
Japan
Metropolitan hospital networks in Tokyo and Osaka accelerate adoption of automated workflows to address workforce constraints in utilization management functions. The national pharmaceutical regulator's digital health guidance influences platform certification requirements for domestic and imported solutions. Nagoya and Fukuoka medical device manufacturing regions extend into adjacent health IT software development for regional export markets.
Prior Authorization Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-driven clinical intelligence differentiation. The vendor base concentrates around three maturity tiers: legacy revenue cycle platforms extending into authorization automation, cloud-native specialists building API-first architectures, and AI-native challengers modularizing clinical decision support. Consolidation pressure intensifies as health system procurement offices bundle authorization with broader claims operations. Dominant competitive moves include strategic partnerships with EHR vendors and technology licensing arrangements for FHIR compliance modules.
Within the integrated platform tier, CoverMyMeds and Waystar represent contrasting archetypes of network-embedded versus revenue-cycle-bundled positioning. Cohere Health exemplifies the AI-native challenger model, occupying a position where clinical intelligence modules reduce manual peer-to-peer review requirements. These three entities anchor the competitive spectrum from pharmacy network integration through enterprise revenue cycle consolidation to specialized clinical automation.
| Leading Market Players |
|---|
| CoverMyMeds (McKesson) |
| Waystar |
| Myndshft |
| Cohere Health |
| Innovaccer |
| Availity |
| Surescripts |
| Spry |
| EthermedAI |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up revenue cycle platforms now control the dominant authorization software vendors, concentrating pricing power among Waystar and similar portfolio companies while compressing professional services margins through standardized implementation playbooks. This ownership structure feeds supply chain discipline by favoring cloud-native component sourcing over bespoke development, with procurement offices demanding fixed-fee SaaS tiers that eliminate legacy customization revenue.
Pricing Analysis
Distributor margins have compressed to near-zero as health system GPOs and digital transformation offices consolidate purchasing authority, forcing vendors to compete on bundled revenue cycle pricing rather than standalone authorization modules. Pricing stratifies across enterprise, mid-market, and clinic-tier levels, with EHR integration complexity and URAC certification status as the primary differentiation drivers. Cost compression in the mid-market tier is intensifying because Medicare Advantage plans demand FHIR-compliant APIs as table stakes. Independent specialty clinics exhibit the highest price sensitivity, while consolidated hospital systems in Pennsylvania and Ohio prioritize total cost of ownership over per-seat licensing.
Supply Chain Analysis
Regional distribution of cloud infrastructure centers on AWS US-East, Azure Central US, and Google Cloud us-central1, with vendor engineering teams concentrated in Austin, Boston, and Bangalore. Software development draws from HL7 FHIR implementation libraries, clinical rules engines licensed from InterSystems and similar health data specialists, and API middleware from MuleSoft and Boomi. Single-source vulnerability in EHR integration partnerships—particularly Epic App Orchard dependencies—creates concentration risk for authorization workflow deployment. Distribution runs through direct enterprise sales teams for health systems above 500 beds, with channel partners and GPO contracts serving ambulatory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prior authorization software procurement functions as a geographic-arbitrage play, with vendors capturing margin expansion by deploying US-developed FHIR modules into German and UK markets where regulatory compliance costs run 40% higher but pricing remains less compressed.
For Market Incumbents: Deepen EHR integration partnerships to lock out modular AI challengers like Cohere Health, while accelerating cloud migration to reduce AS/400 and mainframe maintenance overhead that drags Medicare Advantage client profitability. Consolidate professional services capabilities through acquisition of regional implementation specialists in Texas and Florida, where modular deployment demand is concentrating. For New Entrants and Emerging Players: Capture the Medicaid expansion state opportunity in Arkansas, Missouri, and Oklahoma, where new payer-processor relationships lack incumbent authorization infrastructure and procurement cycles remain open. Specialty oncology and rheumatology clinics present the most penetrable segment, with denial-rate pain justifying premium pricing for AI-assisted clinical documentation tools. For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid-architecture vendors serving large commercial payers with legacy core systems, as cloud-native specialists trade at revenue multiples that assume unlimited SaaS expansion. Target acquisition archetypes include URAC-certified utilization management platforms with existing Medicare Advantage delegated contracts. Watch CMS enforcement timelines for the Interoperability and Prior Authorization Final Rule as the critical inflection signal—delayed compliance deadlines would extend legacy vendor cash flows and compress modernization urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding authorization modules within Epic and Cerner workflows eliminates fax-based submission friction for hospital systems. |
| FHIR Compliance Certification | ONC Cures Act credentials create procurement preference advantages in Medicare Advantage RFP evaluations. |
| AI Clinical Intelligence Module | Natural language processing for medical record review reduces manual peer-to-peer review labor in specialty clinics. |
| Geographic Expansion | Deploying US-developed API architectures into NHS England digitization programs captures higher-margin international revenue. |
| Strategic Partnership | Pharmacy network integration agreements with CoverMyMeds-type hubs secure prescription authorization workflow dominance. |
Research Methodology
Direct dialogue with health system CIOs, revenue cycle VPs, Medicare Advantage technology officers, and EHR integration specialists grounded qualitative findings, cross-referenced against CMS Medicare data, hospital procurement databases, GPO contract disclosures, and URAC accreditation records. Bottom-up and top-down triangulation validated vendor-reported implementation timelines against payer IT budget disclosures and health system capital expenditure patterns.
Bottom-up modeling tracked authorization transaction volumes by deployment model, organization size, and EHR integration complexity across the projection horizon, while top-down analysis anchored total addressable market estimates to national healthcare administrative expenditure trends. CAGRs derived from segment-level growth rate reconciliation against Medicare Advantage enrollment trajectories and CMS compliance deadline enforcement assumptions. Forecast inputs included cloud infrastructure capex disclosures from AWS and Azure health verticals, plus URAC certification pipeline data.
Regulatory enforcement delays, state-level prior authorization reform fragmentation, and specialty pharmacy hub program resistance to generic automation are the dominant revision risks to modeled adoption curves. Forecasts reflect documented assumptions regarding CMS Interoperability and Prior Authorization Final Rule implementation timelines and health system consolidation trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
US Long Term Care Software Market
Healthcare IT
Interactive Patient Care Systems Market
Healthcare IT
Global Personal Health Records Software Market
Healthcare IT
Clinical Communication and Collaboration Market
Healthcare IT
Patient Referral Management Software Market
Healthcare IT
Healthcare HR Software Market
Healthcare IT
Post-Acute Transition Care Coordination Platform Market
Healthcare IT
US Revenue Cycle Management Market
Healthcare IT
Healthcare Smart Card Reader Market
Healthcare IT
Ambulatory Surgical Centers IT Services Market
Healthcare IT
Healthcare Mobility Solutions Market
Healthcare IT
North America Wireless Healthcare Market
Healthcare IT
Prior Authorization Workflow Orchestration Market
Healthcare IT
Chiropractic Software Market
Healthcare IT
Veterinary Dental Software Market
Healthcare IT
Asia-Pacific Revenue Cycle Management Market