
 Clinical Communication and Collaboration Market | 2026-2036
Clinical Communication and Collaboration Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Communication and Collaboration Market Intelligence
The shift towards subscription-based and cloud-hosted purchasing models is narrowing the upfront capital barrier for smaller healthcare providers. Microsoft leverages its extensive enterprise cloud infrastructure to integrate communication tools. Cisco Systems, Inc. specializes in secure networking platforms essential for reliable clinical data exchange. Oracle positions its communication solutions within its broader health information and EHR ecosystems.
Clinical communication and collaboration platforms facilitate the secure, real-time exchange of patient data among care teams. These systems often require end-to-end encryption and API-level integration with Electronic Health Records to ensure data integrity. Their primary purpose is to accelerate clinical decision-making and improve care coordination. Secure messaging platforms represent the largest product segment, while cloud-based deployment is the fastest-growing model.
Regulatory frameworks such as HIPAA in the United States and GDPR in Europe mandate stringent data protection for patient health information. These regulations compel healthcare organizations to adopt compliant, encrypted communication solutions to avoid significant penalties. Consequently, vendor selection now hinges on a platform’s ability to demonstrate auditable compliance and seamless interoperability with existing hospital IT systems.
Market Dynamics
The fundamental dynamic in the clinical communication and collaboration market is the tension between the need for accelerated, mobile-first data exchange and the intensifying stringency of data security mandates like HIPAA and GDPR, forcing a shift to purpose-built platforms.
Growth Catalysts
- Regulatory Mandates:Data protection regulations such as HIPAA in the United States and GDPR in Europe compel healthcare organizations to replace non-compliant communication methods with secure, encrypted, and auditable platforms to avoid substantial financial penalties.
- EHR Integration:The drive for greater interoperability and a unified patient record fuels the adoption of platforms with robust API capabilities that can seamlessly integrate with existing Electronic Health Record systems, streamlining clinical workflows.
- Value-Based Care Models:A transition towards value-based reimbursement in hospital systems necessitates improved care coordination among multidisciplinary teams to enhance patient outcomes and reduce costs, a core function of these collaboration tools.
Market Restraints
- High Implementation Costs:The significant upfront investment required for licensing, integration with legacy IT infrastructure, and comprehensive staff training presents a substantial barrier for smaller hospitals and healthcare facilities with limited capital budgets.
- Interoperability Hurdles:A lack of universal standards across vendor platforms creates data silos and integration friction, complicating the seamless exchange of patient information between different healthcare organizations or departments using disparate systems.
- Legacy System Persistence:The continued reliance on outdated, unsecure communication methods like pagers and non-compliant consumer messaging apps within healthcare settings slows the complete adoption of modern, secure platforms due to institutional inertia.
Strategic Opportunities
- Niche Application Development:There is a significant opportunity to develop specialized platforms tailored to the unique workflow and communication needs of underserved segments such as home healthcare agencies, long-term care facilities, and ambulatory surgery centers.
- AI and Analytics Integration:Incorporating artificial intelligence and predictive analytics into communication platforms can create new value by offering real-time clinical decision support, identifying at-risk patients, and automating administrative tasks for care teams.
- Geographic Expansion:Penetrating healthcare markets in regions like Latin America and Southeast Asia, where governments are investing heavily in modernizing digital health infrastructure, offers substantial growth potential for platform vendors.
Industry Challenges
- Complex Systems Integration:Connecting modern cloud-based collaboration tools with a hospital's array of legacy systems, including EHRs, lab information systems, and imaging archives, is a technically complex and resource-intensive process that can delay deployments.
- Cybersecurity Threat Landscape:As platforms become more integrated with critical patient data, they become higher-value targets for cyberattacks, requiring continuous investment in advanced security measures and constant vigilance to protect sensitive health information.
- User Adoption and Training:Overcoming clinician resistance to changing established workflows and ensuring effective, comprehensive training are persistent operational challenges that can hinder the realization of a platform's full benefits for care coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Communication and Collaboration Market |
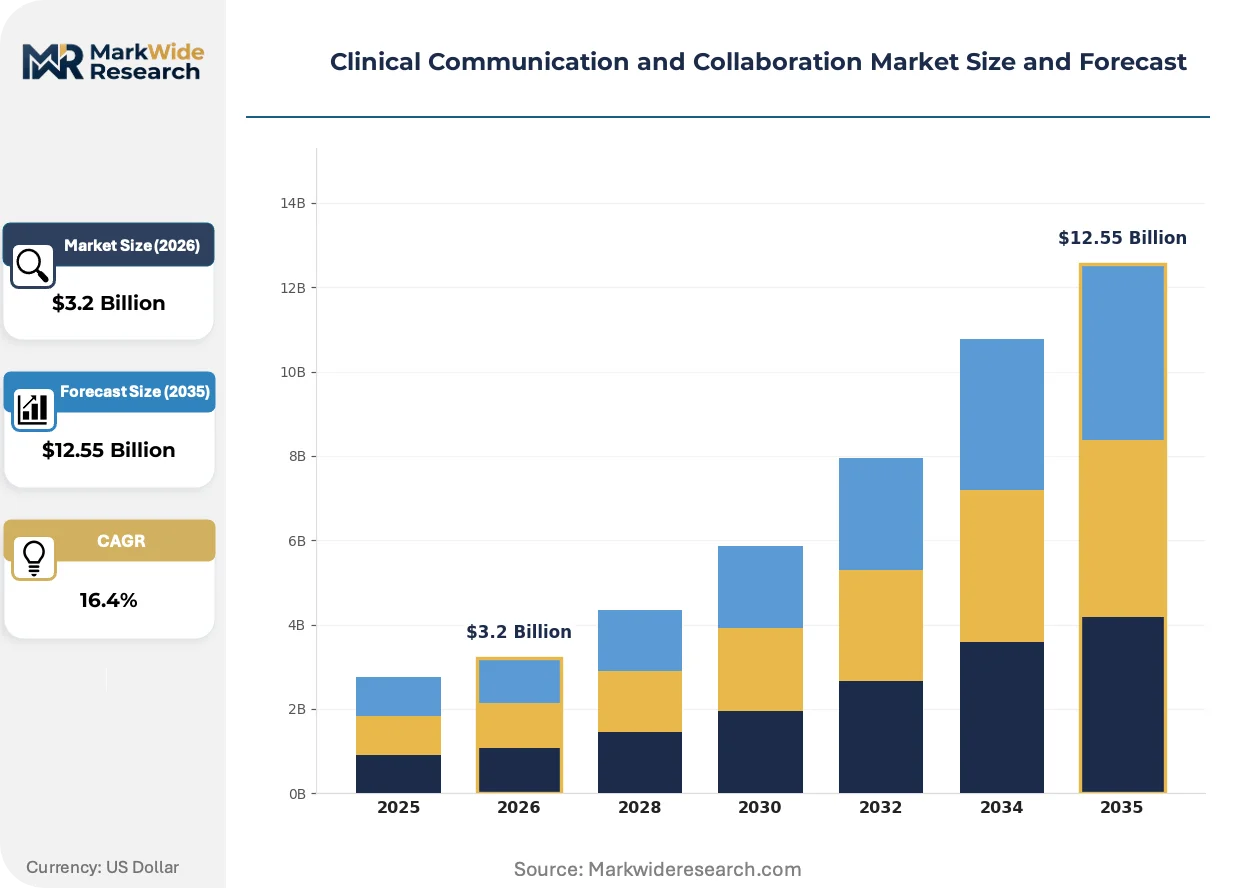
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Secure Messaging Platforms, Voice Communication Systems, Video Conferencing Tools, Clinical Workflow Automation, Alert Notification Systems Application: Patient Data Sharing, Care Coordination, Telemedicine Support, Emergency Response, Remote Monitoring End User: Hospitals, Ambulatory Centers, Diagnostic Laboratories, Home Healthcare Providers, Nursing Facilities Deployment: Cloud-Based, On-Premises, Hybrid Solutions, Web-Based, Mobile Integration |
| Companies Covered | Cisco Systems, Inc., Oracle, Avaya LLC, Stryker, TigerConnect, Microsoft, Intel Corporation, Spok Holdings Inc., NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Communication and Collaboration Market Strategic Shifts & Innovations
The market's evolution is defined by the fusion of consumer-grade user experience with enterprise-level security protocols. This convergence is enabling more intuitive yet fully compliant communication tools that are increasingly augmented by artificial intelligence to enhance clinical decision-making.
AI-powered clinical decision support tools are being integrated directly into messaging platforms. Large hospital systems are the primary adopters, seeking to improve diagnostic accuracy and workflow efficiency. This integration of real-time analytics into the communication channel is collapsing the time between data input, insight generation, and clinical action.
The EU AI Act introduces a risk-based framework for artificial intelligence systems. The regulation compels vendors to ensure transparency and human oversight for AI-driven diagnostic or workflow automation features. The clinical analytics product segment is most affected, requiring significant investment in algorithm validation to operate within the European Union.
A definitive shift from perpetual licenses towards subscription-based, cloud-hosted models is underway. This change lowers upfront capital costs, making platforms more accessible to smaller clinics and disrupting the traditional hospital-centric sales model. The trend is most prominent in North America and Western Europe, where cloud infrastructure is mature.
Clinical Communication and Collaboration Market Segmentation
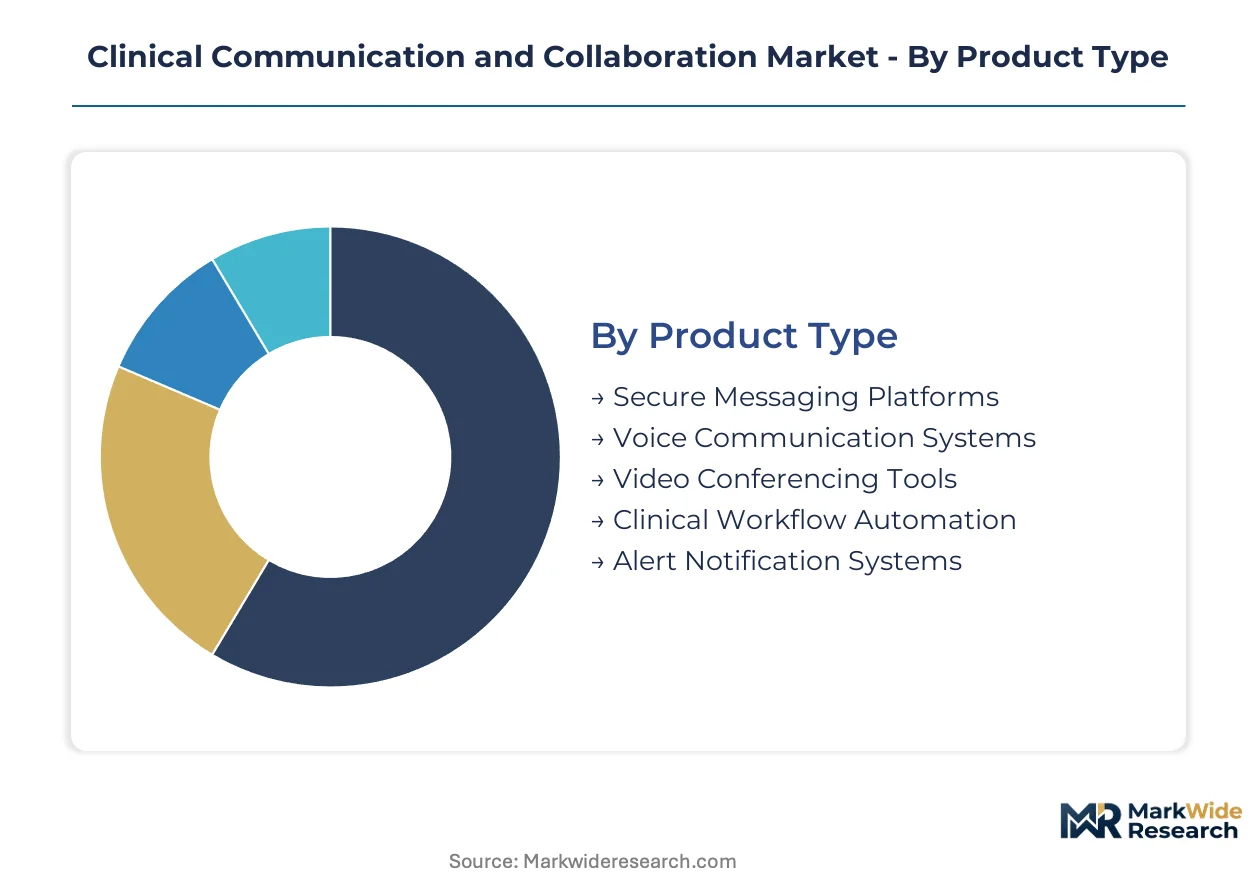
Understanding the segmentation of the clinical communication and collaboration market reveals how diverse healthcare needs drive technology adoption. This analysis highlights specific product functionalities, application areas, end-user types, and deployment methods that define the competitive landscape.
Product Type:
The product type segmentation reflects the diverse range of communication functionalities required by healthcare professionals, from direct patient interaction to back-end administrative support.
- Secure Messaging Platforms:These systems provide encrypted, HIPAA-compliant channels for healthcare teams to exchange patient health information, accelerating clinical decision-making. Demand concentrates in large hospital systems across North America, driven by stringent data security mandates like HIPAA.
- Clinical Workflow Automation:These tools integrate communication with automated tasks such as appointment scheduling, task assignment, and alert routing, streamlining operational efficiency. European healthcare providers are increasingly adopting these solutions to optimize resource allocation and improve care coordination under GDPR.
- Voice Communication Systems:Dedicated voice platforms enable secure, real-time audio communication between clinicians, often integrated with existing hospital phone systems.
- Alert Notification Systems:These systems deliver critical alerts and notifications to care teams for patient status changes, lab results, or emergency situations.
- Video Conferencing Tools:Specialized video conferencing solutions facilitate virtual consultations and multidisciplinary team meetings with secure, high-definition capabilities.
The dominant share belongs to Secure Messaging Platforms, while Clinical Workflow Automation is closing the gap fastest.
Application:
The application segment delineates how clinical communication tools directly enhance various aspects of healthcare delivery and patient management.
- Care Coordination:These applications facilitate seamless communication and task management among multidisciplinary teams, improving patient outcomes and reducing readmissions. Value-based care models in the United States are a significant driver for this application, requiring integrated team communication.
- Patient Data Sharing:This application focuses on the secure exchange of sensitive patient information, including medical history, test results, and treatment plans, between authorized personnel. Data interoperability requirements across Western Europe emphasize robust data sharing capabilities.
- Telemedicine Support:Communication platforms enable virtual patient consultations, remote diagnostics, and follow-up care, expanding access to medical services.
- Emergency Response:These applications provide rapid, secure communication channels for urgent situations, coordinating responses among emergency medical services and hospital staff.
- Remote Monitoring:Communication tools support the transmission of patient vital signs and health data from remote devices to care providers for continuous oversight.
Care Coordination applications hold significant strategic importance, as Patient Data Sharing underpins nearly all other functionalities.
End User:
The end user categories illustrate the varying levels of digital communication maturity and specific operational requirements across different healthcare settings.
- Hospitals:These large institutions require comprehensive communication platforms that integrate with complex EHR systems and support diverse clinical workflows. Hospitals in Germany and France are making substantial investments to modernize their communication infrastructure.
- Home Healthcare Providers:This segment needs mobile-first, secure communication solutions to coordinate care for patients in their residences, often across geographically dispersed teams. The aging populations in Japan and Canada are fueling demand for these services.
- Ambulatory Centers:These facilities require efficient communication for scheduling, patient intake, and coordinating specialist referrals.
- Diagnostic Laboratories:Laboratories utilize communication tools to transmit results securely and consult with referring physicians, ensuring timely patient diagnoses.
- Nursing Facilities:Long-term care facilities leverage these platforms for staff coordination, resident care updates, and family communication.
Hospitals represent the largest adoption base, with Home Healthcare Providers showing significant expansion potential.
Deployment:
Deployment models offer distinct advantages in terms of infrastructure investment, scalability, and data control for healthcare organizations.
- Cloud-Based:These solutions are hosted on remote servers and accessed via the internet, offering scalability, lower upfront costs, and easier maintenance. Small to mid-sized clinics in the United States increasingly favor cloud deployments for their operational flexibility.
- Hybrid Solutions:This model combines on-premises infrastructure with cloud services, providing a balance of control over sensitive data and the flexibility of cloud resources. Large hospital networks in the United Kingdom often opt for hybrid models to integrate legacy systems with modern cloud capabilities.
- On-Premises:These systems are installed and maintained directly within a healthcare organization's own data centers, providing maximum data control.
- Web-Based:These platforms are accessible through web browsers, requiring minimal local software installation and offering broad compatibility.
- Mobile Integration:This deployment focuses on optimizing communication tools for smartphones and tablets, enabling clinicians to access information on the go.
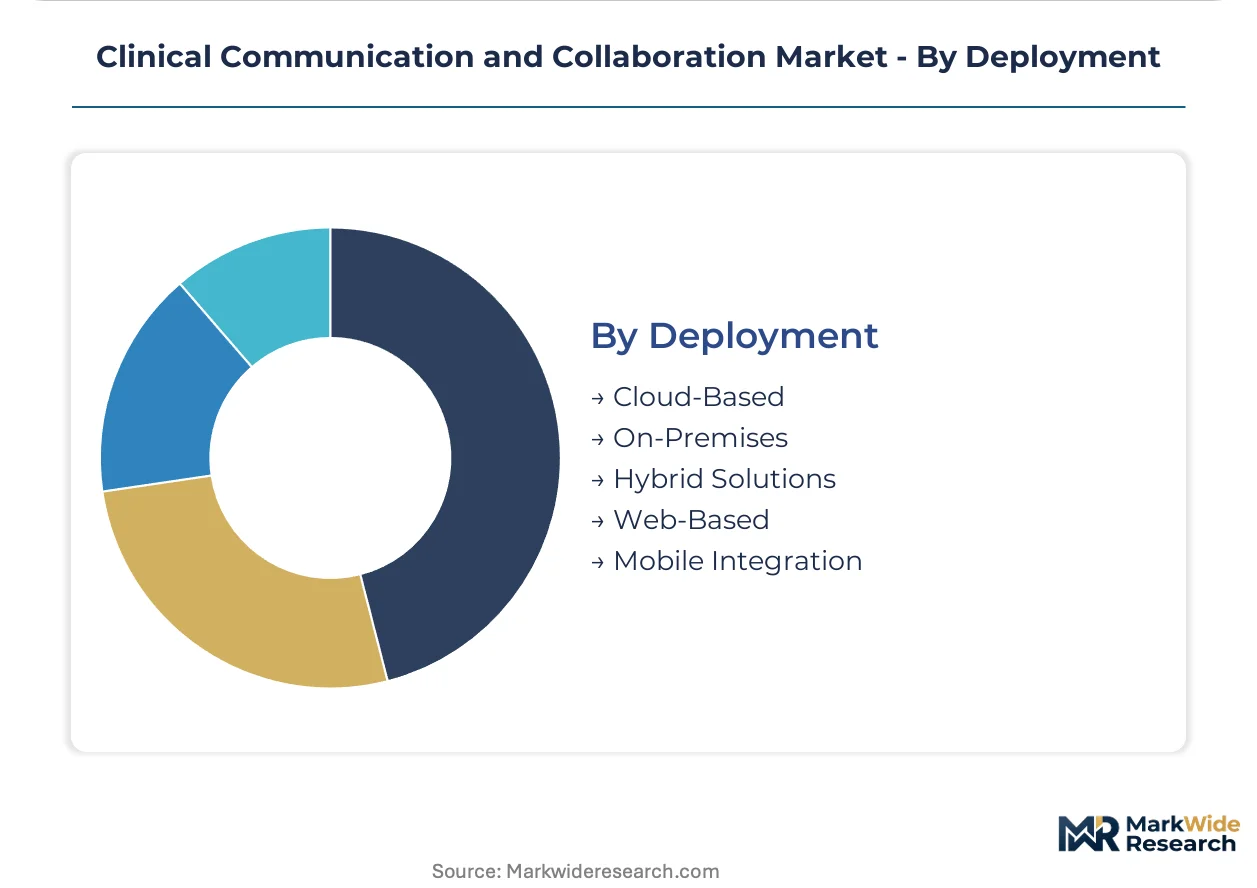
Cloud-Based solutions are increasingly preferred for their flexibility, though Hybrid Solutions address complex legacy infrastructure needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the clinical communication market exhibits asymmetry, with North American providers often commanding higher valuations compared to nascent markets in Southeast Asia. This disparity reflects mature regulatory environments and established digital health infrastructures. Investment in secure communication solutions varies significantly across global healthcare systems.
United States
Demand for secure messaging platforms is high, driven by the need for accelerated data exchange in large hospital systems. HIPAA regulations compel healthcare organizations to adopt compliant, encrypted communication solutions. Major health tech hubs like Boston and San Francisco are fostering innovation in clinical decision support tools.
Germany
Hospitals in Germany are making substantial investments to modernize their communication infrastructure, seeking to streamline clinical workflows. GDPR mandates stringent data protection for patient health information, influencing platform selection. Berlin's growing digital health ecosystem attracts startups developing AI-powered clinical analytics.
Japan
The aging population in Japan fuels demand for mobile-first, secure communication solutions in home healthcare settings. The country's national health policies encourage digital transformation to improve care coordination for chronic conditions. Tokyo's medical technology cluster focuses on integrating remote monitoring with real-time communication platforms.
China
Governments in China are investing heavily in modernizing digital health infrastructure, driving adoption of collaboration platforms. National health initiatives promote integrated care models, requiring robust patient data sharing capabilities. Shenzhen's technology parks are becoming centers for developing secure communication tools tailored for large public hospitals.
United Kingdom
Large hospital networks in the United Kingdom often opt for hybrid solutions to integrate legacy systems with modern cloud capabilities. The National Health Service (NHS) emphasizes interoperability and secure data exchange to enhance patient outcomes. London's health tech sector is a hub for firms specializing in clinical workflow automation for complex care pathways.
Clinical Communication and Collaboration Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing secure networking and cloud infrastructure. The clinical communication market exhibits a tiered structure, with large technology conglomerates offering comprehensive ecosystems and niche players focusing on specific workflow solutions. Strategic archetypes include enterprise cloud providers, secure networking experts, and specialized health IT vendors. Dominant competitive moves involve strategic partnerships for EHR integration and continuous investment in cybersecurity features.
Specialists in secure clinical communication include TigerConnect, which provides mobile-first messaging and on-call scheduling solutions tailored for healthcare teams seeking efficient coordination. Cisco Systems, Inc. exemplifies a secure networking platform provider, leveraging its extensive enterprise infrastructure to facilitate reliable and encrypted clinical data exchange across various healthcare settings. Oracle positions its communication solutions strategically within its broader health information and Electronic Health Record (EHR) ecosystems, primarily targeting large hospital systems that require deep integration. These prominent entities represent distinct approaches to addressing the market's evolving demands for secure, interoperable, and integrated communication functionalities within clinical environments.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Oracle |
| Avaya LLC |
| Stryker |
| TigerConnect |
| Microsoft |
| Intel Corporation |
| Spok Holdings Inc. |
| NEC Corporation |
| Others |
Cost & Logistics Intelligence
Enterprise cloud infrastructure providers, like Microsoft and Cisco, concentrate upstream, enabling platform integrators to capture significant margin pools downstream. This structural dynamic shapes the overall market's pricing power.
Pricing Analysis
Configured-to-order pricing commands a premium compared to standard, off-the-shelf solutions in the clinical communication market. Subscription-based, cloud-hosted models are the dominant pricing structure, offering tiered access based on features and user count. Price differentiation stems from the level of customization required for EHR integration and the complexity of regulatory compliance features. Pricing softness reflects competition for smaller clinics, while large hospital systems prioritize comprehensive, deeply integrated platforms over cost.
Supply Chain Analysis
Extended payment terms are common for large hospital system procurements, reflecting high value and long implementation cycles. Geographic supply concentration for core technology components centers on North America and Western Europe, where major cloud infrastructure and secure networking providers operate. The market draws from specialized software modules and advanced data encryption technologies. Cybersecurity threat landscape represents a significant structural risk for all vendors, and distribution runs primarily through direct sales to large healthcare networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This clinical communication market presents a defensive moat story, primarily due to the regulatory entrenchment created by stringent data protection mandates like HIPAA and GDPR. These frameworks impose high switching costs for healthcare organizations once a compliant platform is adopted.
For Market Incumbents: Harden existing client relationships by deepening EHR integration and investing in advanced AI-powered clinical decision support features. This strategy mitigates the threat from emerging niche players offering specialized tools with limited interoperability. Prioritize R&D in API development to ensure seamless data exchange across complex hospital IT systems. Continuous investment in cybersecurity measures is also critical against evolving threat landscapes.
For New Entrants and Emerging Players: Geographic underpenetration in Latin America and Southeast Asia offers significant expansion potential for clinical communication platforms. Target underserved segments such as home healthcare agencies and long-term care facilities with specialized workflow solutions. A go-to-market angle focused on flexible, subscription-based models with lower upfront costs can attract smaller providers. Focus on demonstrating rapid return on investment through improved care coordination.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed specialized health IT vendors offering secure messaging and workflow automation. This market represents an essential, regulated infrastructure play over the long term. Acquisition targets should include firms with strong API-level EHR integration and proven compliance records. A signal to watch for inflection is increased M&A activity for companies developing AI-driven clinical analytics and decision support tools.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: AI-Powered Clinical Decision Support | New AI-powered tools enhance diagnostic accuracy and workflow efficiency for large hospital systems. |
| Platform Integration: Enhanced EHR Connectivity | Deeper API integration with Electronic Health Records streamlines clinical workflows and data exchange. |
| Strategic Partnership: Telehealth Providers | Collaborations with telehealth platforms extend communication capabilities for remote patient monitoring. |
| Acquisition of Specialist Firm: Home Healthcare Solutions | Acquiring niche providers expands market reach into the growing home healthcare segment. |
| Geographic Expansion: Latin America & Southeast Asia | Penetrating emerging markets diversifies revenue streams and leverages modernizing digital health infrastructure. |
Research Approach
Operator-level perspectives from hospital IT procurement officers, clinicians, regulatory compliance leads, and software architects anchored the qualitative base for this study. Primary interviews with these industry stakeholders were rigorously validated against extensive secondary research. Secondary sources included SEC filings, government health agency reports, academic journals, and industry association publications. A comprehensive bottom-up and top-down triangulation approach ensured data accuracy and market sizing precision.
Scenario-bracketing provided a robust analytical framework, integrating various market dynamics across the analysis window. Segmentation dimensions modeled included product type, application, end-user, deployment model, and regional adoption patterns. Compound annual growth rates were derived through a comprehensive analysis of historical trends and projected market shifts. Key forecast inputs included Electronic Health Record integration rates and healthcare organization investments in regulatory compliance solutions.
Macroeconomic conditions sit as an overlay; deviation in healthcare spending or digital infrastructure investment would shift the trajectory. Forecasts reflect assumptions regarding regulatory stability and technological evolution. Unforeseen healthcare policy changes, major cybersecurity breaches, or rapid technological obsolescence could prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Healthcare IT Provider Market
Healthcare IT
Europe Dental Software Market
Healthcare IT
Technology Spending on Revenue Cycle Management Market
Healthcare IT
Post-Acute Transition Care Coordination Platform Market
Healthcare IT
Pharmaceutical Software Market
Healthcare IT
Healthcare AIDC Market
Healthcare IT
Europe Hospital Capacity Management Solutions Market
Healthcare IT
Prior Authorization Software Market
Healthcare IT
Patient Access Solutions Market
Healthcare IT
IP-Based Nurse Call System Market
Healthcare IT
ECG Management Systems Market
Healthcare IT
Ambulatory Surgical Centers IT Services Market
Healthcare IT
Clinical Healthcare IT Market
Healthcare IT
Healthcare Revenue Cycle Management (RCM) Software Market
Healthcare IT
US Healthcare IT Market
Healthcare IT
Europe Smart Hospital Market