
 Digital Mhealth Solution Market | 2026-2036
Digital Mhealth Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Mhealth Solution Market Insights
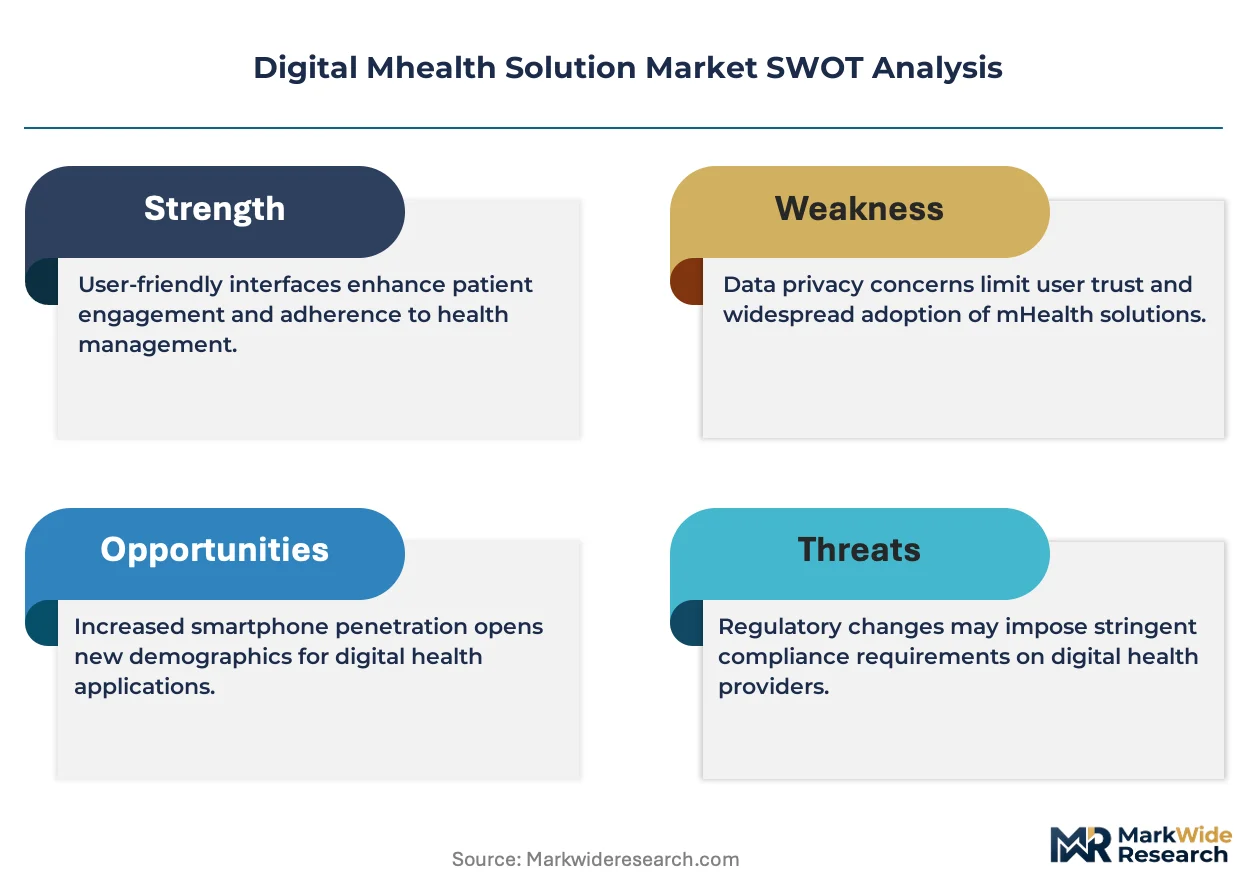
EU AI Act compliance is rebalancing the cost-of-entry calculus for algorithm-driven diagnostic tools in Europe. Medtronic plc navigates this shift through upstream control over its sensor hardware and cloud analytics stack. Apple Inc. differentiates by leveraging its consumer device ecosystem to capture ambulatory health signals at scale. Teladoc Health Inc. anchors its position through channel control across employer and payer virtual care networks.
Digital mHealth solutions encompass software and connected hardware that capture, transmit, and analyze physiological data through wireless protocols such as Bluetooth Low Energy and FHIR-compliant APIs, primarily serving to extend clinical surveillance beyond facility walls. Wearable devices and remote monitoring solutions currently occupy the largest margin pools as reimbursement codes mature for continuous glucose and cardiac telemetry. Mobile apps specializing in mental health support represent the fastest-expanding segment as employer wellness budgets and direct-to-consumer subscriptions converge.
FDA, EMA, and India's CDSCO collectively shape market access through divergent software-as-medical-device classification pathways and post-market surveillance obligations. The EU AI Act adds a risk-based conformity layer that forces developers to document training data provenance and clinical validation endpoints before CE marking. Stakeholders must monitor whether emerging national reimbursement frameworks will favor platform-agnostic interoperability or reinforce proprietary ecosystem lock-in.
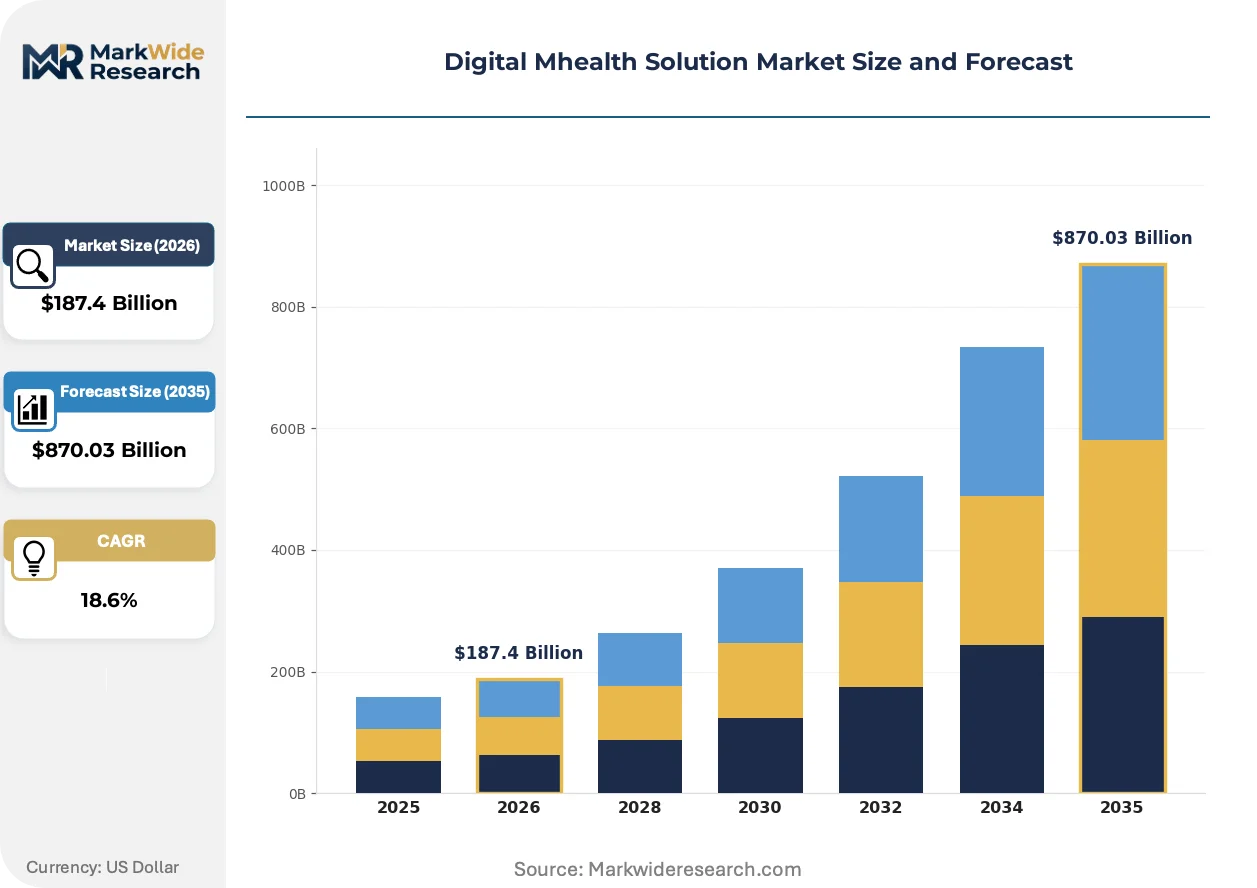
Market Dynamics
Reimbursement code expansion for remote physiological monitoring is compressing the sales cycle for connected care platforms, forcing vendors to reconfigure revenue models around recurring service fees rather than hardware margins.
Growth Catalysts
- FDA 510(k) digital health pathway:Streamlined software-as-medical-device clearance accelerates time-to-market for algorithm-driven diagnostic tools in the United States.
- Bluetooth Low Energy sensor proliferation:Miniaturized biometric capture hardware enables continuous ambulatory monitoring outside clinical settings.
- Employer wellness budget consolidation:Large self-insured employers in the United States are bundling mental health apps into benefits platforms, creating captive demand pools.
Market Restraints
- EU AI Act conformity costs:Risk-based documentation requirements for training data provenance and clinical validation inflate pre-market expenditure for European market entry.
- Cloud infrastructure concentration:Dependence on hyperscale providers for HIPAA-compliant data storage creates single-point vulnerability in vendor supply chains.
- Clinical workflow integration friction:FHIR API interoperability gaps force manual data reconciliation between mHealth platforms and legacy EHR systems.
Strategic Opportunities
- India's Ayushman Bharat digital health mission:National health stack infrastructure creates channel access for low-cost remote monitoring solutions targeting tier-2 and tier-3 cities.
- Germany's DiGA fast-track:Prescription digital health app reimbursement pathway offers regulatory tailwind for evidence-based therapeutic software.
- Continuous glucose monitoring-cardiac telemetry convergence:Multi-parameter wearable platforms capture metabolic-cardiovascular correlation data for predictive risk scoring.
Industry Challenges
- Clinical validation talent scarcity:Shortage of biostatisticians with digital health trial design expertise delays pivotal study execution.
- CE marking timeline compression:MDR technical documentation requirements extend notified body review cycles for software-hardware combination products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Mhealth Solution Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $870.03 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Mobile Apps, Telemedicine Platforms, Remote Monitoring Solutions End User: Healthcare Providers, Patients, Health Insurance Companies, Corporate Wellness Programs Technology: Artificial Intelligence, Blockchain, Cloud Computing, Data Analytics Application: Chronic Disease Management, Fitness Tracking, Mental Health Support, Medication Adherence |
| Companies Covered | Koninklijke Philips N.V., Medtronic plc, Johnson & Johnson, Apple Inc., Teladoc Health Inc., OMRON Healthcare Co., Ltd., GE HealthCare Technologies Inc., Cerner Corporation, Dexcom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Mhealth Solution Market Trends and Innovations
Algorithmic processing of ambulatory biometric streams is shifting diagnostic authority from centralized laboratories to edge-computing wearables, compressing the latency between signal detection and clinical intervention.
Edge AI inference on wearable SoCs is unifying real-time arrhythmia detection with on-device data anonymization. Cardiology departments in integrated delivery networks are piloting these platforms for post-discharge surveillance. The technology is unifying hardware and analytics margins into single-vendor capture models.
The EU AI Act's risk-tier classification system is mandating post-market performance monitoring for high-risk diagnostic algorithms. Developers must maintain quality management systems documenting drift detection protocols. Cardiovascular monitoring applications face the steepest compliance burden, driving consolidation among vendors with captive clinical evidence generation capabilities.
Self-insured employers are unbundling point-solution contracts in favor of platform-agnostic wellness marketplaces. Benefits administrators in the United States are prioritizing API-first vendors that aggregate disparate biometric feeds into unified risk dashboards. This procurement model rotation favors middleware providers over standalone application developers.
Digital Mhealth Solution Market Segmentation
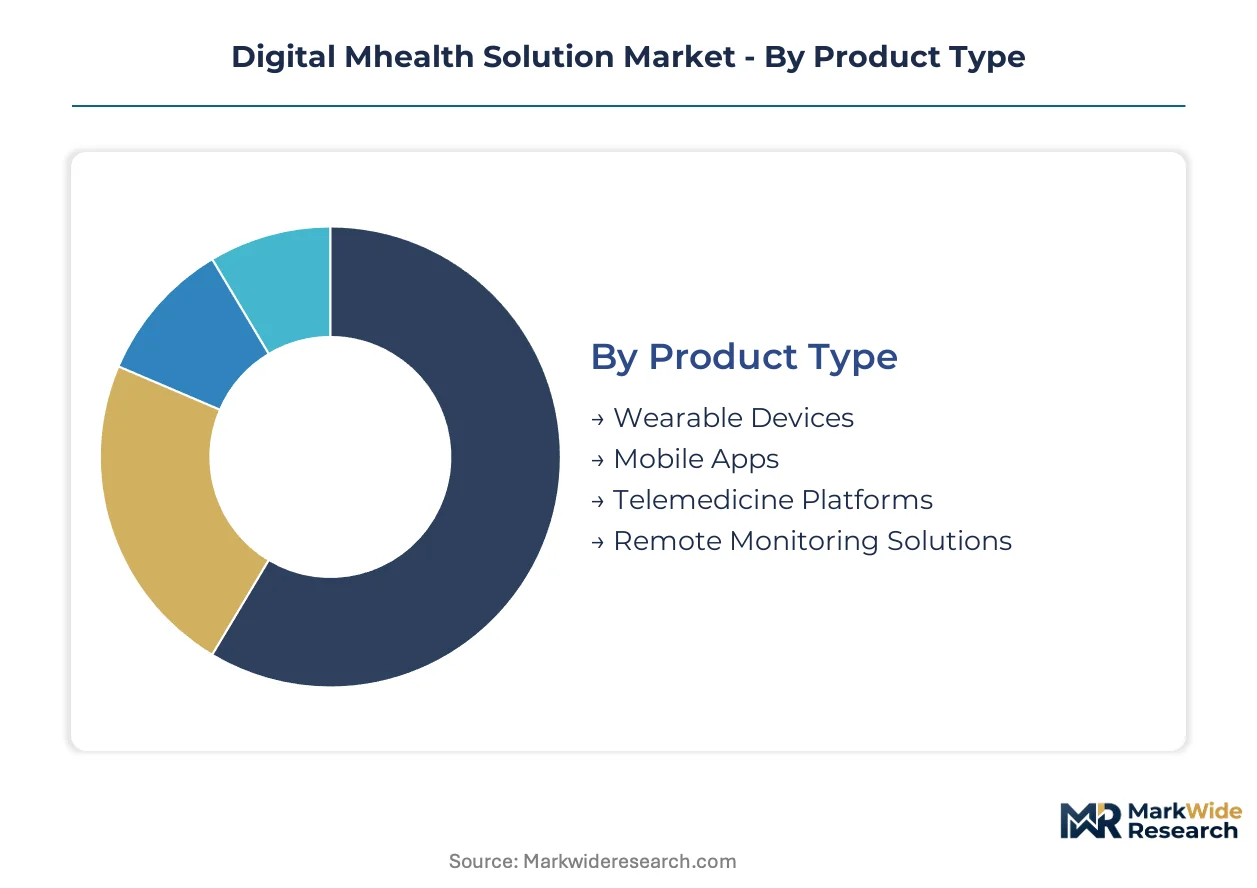
Segmentation in digital mHealth reveals how reimbursement pathways, sensor miniaturization, and algorithmic validation requirements reshape competitive positioning across hardware, software, and service layers. Distinct margin structures and regulatory burdens separate device-centric from platform-centric business models.
Product Type:
Bluetooth Low Energy sensor architectures and FDA 510(k) clearance pathways differentiate hardware from software revenue models in this category.
- Wearable Devices:Continuous glucose monitors and cardiac telemetry patches integrate multi-parameter biometric capture with edge AI inference. Demand concentrates among integrated delivery networks in the United States seeking post-discharge surveillance solutions as remote physiological monitoring reimbursement codes expand.
- Mobile Apps:Mental health and chronic condition management applications deploy FHIR-compliant APIs for EHR integration. Self-insured employers in the United States bundle these into benefits platforms, creating subscription revenue pools independent of hardware sales cycles.
- Telemedicine Platforms:Virtual care infrastructure connecting patients with clinicians through synchronous video and asynchronous messaging.
- Remote Monitoring Solutions:Cloud-based dashboards aggregating biometric streams from dispersed patient populations for centralized clinical review.
Wearable Devices lead on scale; Mobile Apps lead on momentum.
End User:
Procurement authority and budget source determine pricing tolerance and integration complexity across this axis.
- Healthcare Providers:Hospitals and physician groups purchasing enterprise licenses for patient monitoring dashboards. Germany's DiGA fast-track pathway accelerates adoption of prescription digital therapeutics among cardiology and endocrinology departments.
- Patients:Direct-to-consumer subscription purchases of fitness trackers and mental wellness applications. India's tier-2 and tier-3 cities represent emerging demand concentration as Ayushman Bharat infrastructure expands.
- Health Insurance Companies:Payers reimbursing connected care services through value-based contracting arrangements.
- Corporate Wellness Programs:Employer-sponsored benefits aggregating biometric screening and behavioral health support.
Healthcare Providers dominate current revenue capture; Patients represent the steepest expansion trajectory.
Technology:
Computational location—edge, cloud, or distributed ledger—shapes data sovereignty and latency trade-offs.
- Artificial Intelligence:Diagnostic algorithms for arrhythmia detection and glucose prediction requiring EU AI Act conformity documentation. Cardiovascular applications face the steepest compliance burden, favoring vendors with captive clinical evidence generation.
- Cloud Computing:HIPAA-compliant data lakes and FHIR-enabled interoperability layers. Dependence on hyperscale providers creates single-point vulnerability in vendor supply chains.
- Blockchain:Decentralized health record architectures for patient-controlled data sharing.
- Data Analytics:Population health dashboards synthesizing biometric trends for risk stratification.
Artificial Intelligence commands premium pricing; Cloud Computing underpins infrastructure scale.
Application:
Clinical validation requirements and reimbursement maturity separate medically indicated from wellness-oriented use cases.
- Chronic Disease Management:Diabetes and heart failure monitoring platforms with established CPT codes. FDA 510(k) digital health pathway accelerates clearance for algorithm-driven diagnostic tools in the United States.
- Mental Health Support:Cognitive behavioral therapy apps and crisis intervention chatbots. Employer wellness budget consolidation in the United States drives fastest segment expansion.
- Fitness Tracking:Consumer-grade activity and sleep monitoring without clinical claims.
- Medication Adherence:Smart pill dispensers and refill reminder systems for polypharmacy patients.
Chronic Disease Management anchors reimbursement-driven revenue; Mental Health Support gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical engineering talent clusters in Boston, Basel, and Bengaluru anchor regional innovation capacity for algorithm-driven diagnostic platforms.
United States
FDA 510(k) digital health pathway streamlines software-as-medical-device clearance for algorithm-driven diagnostic tools. Remote physiological monitoring reimbursement codes expand through Medicare, compressing sales cycles for connected care vendors. The Greater Boston corridor concentrates FDA-cleared cardiac telemetry startups alongside academic medical centers running pivotal trials.
Germany
DiGA fast-track pathway reimburses prescription digital therapeutics through statutory health insurance. EU AI Act conformity documentation requirements inflate pre-market expenditure for cardiovascular monitoring applications. Berlin and Munich host notified body expertise clusters supporting CE marking for software-hardware combination products.
India
Ayushman Bharat digital health mission infrastructure creates channel access for low-cost remote monitoring solutions. CDSCO software-as-medical-device classification pathways diverge from FDA and EMA frameworks, requiring separate validation strategies. Bengaluru and Hyderabad concentrate engineering talent for FHIR-compliant API development serving tier-2 and tier-3 city deployments.
United Kingdom
NHS England digital-first reimbursement pilots accelerate adoption of mental health support applications. MHRA software medical device guidance aligns partially with EU MDR post-Brexit, creating dual compliance obligations. London's health tech cluster attracts venture funding for platform-agnostic wellness marketplace middleware.
Japan
PMDA digital therapeutics approval pathway lags FDA and EMA timelines, delaying market entry for foreign developers. METI subsidizes edge AI inference chip development for wearable arrhythmia detection platforms. Tokyo and Osaka anchor integrated delivery network pilot programs for post-discharge cardiac telemetry surveillance.
Digital Mhealth Solution Market Competitive Landscape
The competitive structure tilts toward diversified health technology conglomerates with captive clinical evidence generation capabilities. Vendor concentration remains moderate, with medical device incumbents and consumer technology platforms occupying distinct margin pools. Three archetypes dominate: sensor-integrated hardware specialists, cloud-native virtual care platforms, and ecosystem-leveraging consumer device manufacturers. M&A activity concentrates on algorithm validation capabilities and FHIR interoperability assets.
Among diversified medical technology conglomerates, Koninklijke Philips N.V. and Medtronic plc exemplify the sensor-integrated hardware archetype through upstream control over biometric capture and analytics stacks. Teladoc Health Inc. anchors the virtual care platform tier through channel control across employer and payer networks. Apple Inc. occupies a distinct position leveraging consumer device ecosystem penetration for ambulatory signal capture at scale.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Medtronic plc |
| Johnson & Johnson |
| Apple Inc. |
| Teladoc Health Inc. |
| OMRON Healthcare Co., Ltd. |
| GE HealthCare Technologies Inc. |
| Cerner Corporation |
| Dexcom Inc. |
| Others |
Pricing and Supply Chain Analysis
Bluetooth Low Energy sensor module costs cascade through three pricing tiers as hardware margins compress and recurring service fees capture value downstream. Contract manufacturers in Taiwan and China feed miniaturized biometric capture components to vendors who bundle hardware with cloud analytics subscriptions, shifting buyer expenditure from capital to operational budgets.
Pricing Analysis
The bundled-vs-unbundled service split separates device-centric from platform-centric revenue models. SaaS-tiered subscription structures dominate for remote monitoring platforms, while per-unit transactional pricing persists for wearable hardware. Price differentiation rests on FDA 510(k) clearance tier and integration complexity with legacy EHR systems. Pricing pressure stems from employer wellness budget consolidation favoring platform-agnostic vendors over standalone applications. Self-insured employers demonstrate highest price sensitivity; integrated delivery networks purchasing enterprise licenses show lowest.
Supply Chain Analysis
Reverse-logistics flows for continuous glucose monitor and cardiac telemetry patch refurbishment concentrate in Malaysia and Mexico, extending hardware lifecycle value. Component sourcing draws from Taiwan for edge AI inference chips, South Korea for display modules, and China for battery cells. Single-source vulnerability sits with hyperscale cloud providers for HIPAA-compliant data storage. Distribution runs through GPO contracts for healthcare provider procurement and direct-to-consumer channels for patient-facing applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in digital mHealth hinges on algorithm-driven diagnostic tools commanding premium pricing as FDA 510(k) clearance barriers filter competition.
For Market Incumbents: Extend sensor-integrated hardware portfolios into multi-parameter wearable platforms capturing metabolic-cardiovascular correlation data. Acquire FHIR interoperability assets to defend against cloud-native virtual care platforms unbundling point solutions. Cement channel control across employer and payer networks before platform-agnostic wellness marketplaces consolidate procurement authority. For New Entrants and Emerging Players: Tier-2 and tier-3 cities in India represent the most penetrable geography, with Ayushman Bharat infrastructure creating channel access for low-cost remote monitoring solutions. Target mental health support applications for self-insured employers seeking to consolidate point-solution contracts. Pursue API-first positioning enabling aggregation of disparate biometric feeds into unified risk dashboards. For Investors and Strategic Acquirers: Consolidation pressure builds where EU AI Act conformity documentation requirements inflate pre-market expenditure beyond bootstrap capacity. Long-term viability favors vendors with captive clinical evidence generation capabilities spanning cardiovascular and metabolic monitoring applications. Watch FDA 510(k) digital health pathway expansion rates as inflection indicator for algorithm-driven diagnostic tool market entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Digital Health Pathway | Streamlined software-as-medical-device clearance accelerates time-to-market for algorithm-driven diagnostic tools in the United States. |
| CE Marking Pathway | MDR technical documentation requirements extend notified body review cycles for software-hardware combination products entering Europe. |
| Hospital System Partnership | Integrated delivery networks pilot edge AI inference wearables for post-discharge surveillance, compressing intervention latency. |
| Software Companion Development | FHIR-compliant API layers enable EHR integration, reducing clinical workflow friction for remote monitoring platforms. |
| Reimbursement Strategy | Medicare remote physiological monitoring code expansion compresses sales cycles for connected care vendors in the United States. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs leads with secondary validation against FDA filings, CMS Medicare reimbursement databases, hospital procurement records, and CE marking notified body registries. Bottom-up sensor shipment modeling and top-down healthcare IT expenditure analysis triangulated market sizing.
Segment-weighting across product type, end user, technology, and application dimensions anchored the analytical framework over the projection horizon. CAGRs derived from fitted growth curves incorporating reimbursement code expansion velocity, employer wellness budget allocation shifts, and EU AI Act implementation timelines. Modeled inputs included Bluetooth Low Energy sensor cost trajectories and cloud infrastructure pricing elasticity.
Underlying measurement precision varies by segment; wearable devices and remote monitoring solutions carry tighter precision than blockchain-enabled health record architectures. Forecasts reflect assumptions around regulatory pathway stability and reimbursement code durability. Practitioners should monitor FDA 510(k) clearance timeline shifts and EU AI Act risk-tier reclassifications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Global Technology Spending on Core Administration in Healthcare Market
Healthcare IT
Pharmaceutical Quality Management Systems Market
Healthcare IT
Healthcare Mobility Solutions Market
Healthcare IT
Senior Care Technologies Market
Healthcare IT
Global Emergency Department Information System Market
Healthcare IT
Global Hospital Asset Tracking and Inventory Management Systems Market
Healthcare IT
North American Dental Software Market
Healthcare IT
Americas Healthcare Human Resources (HR) Software Market
Healthcare IT
Clinical Practice Management Software Market
Healthcare IT
Healthcare Workforce Management Systems Market
Healthcare IT
Clinical Communication and Collaboration Market
Healthcare IT
Healthcare IT Market
Healthcare IT
Hospital Capacity Management Solutions Market
Healthcare IT
Global Personal Health Records Software Market
Healthcare IT
Assisted Living Software Market
Healthcare IT
US Revenue Cycle Management Market