
 E-Prescribing Systems Market | 2026-2036
E-Prescribing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
E-Prescribing Systems Market Analysis
Cloud-native architecture is consolidating traditional on-premise installations across health system IT estates. Epic Systems Corporation leverages its dominant EHR footprint to embed prescribing workflows directly into clinical encounters. Cerner Corporation anchors multi-hospital deployments through its Cerner Millennium platform integration. Athenahealth competes on SaaS economics, reducing upfront capital barriers for outpatient clinic networks.
E-prescribing systems are electronic platforms that transmit prescription data between authorized prescribers and dispensers using standardized messaging protocols such as NCPDP SCRIPT, eliminating paper-based workflows and enabling real-time formulary checking, prior authorization, and medication history retrieval. Cloud-based delivery dominates new procurement cycles as health systems prioritize remote accessibility and reduced infrastructure overhead. EHR integration represents the most technically demanding segment, where bidirectional data synchronization with existing clinical repositories determines implementation success and long-term user retention. Hospitals constitute the highest-value end-user category, though outpatient clinics represent the fastest expansion vector as federally qualified health centers modernize.
FDA oversees controlled substance e-prescribing standards under DEA Schedule II-V regulations, while ONC certifies interoperability requirements through its Health IT Certification Program. HIPAA mandates govern prescription data transmission security, creating compliance thresholds that filter vendor eligibility. Stakeholders must monitor evolving state-level mandate harmonization and pharmacy network consolidation to anticipate platform connectivity requirements.
Market Dynamics
Federal mandate convergence with pharmacy benefit manager consolidation is compressing vendor selection cycles and elevating interoperability requirements as the defining competitive filter.
Growth Catalysts
- The 21st Century Cures Act:Electronic prescribing mandates for controlled substances are forcing DEA Schedule II-V compliance upgrades across ambulatory and inpatient settings.
- Cloud-native architecture:Health system IT estates are migrating from on-premise installations to SaaS delivery models, reducing capital barriers for mid-size hospital networks.
- Hospital network consolidation:Multi-facility health systems are standardizing prescribing workflows across acquired entities, creating platform-scale procurement opportunities.
Market Restraints
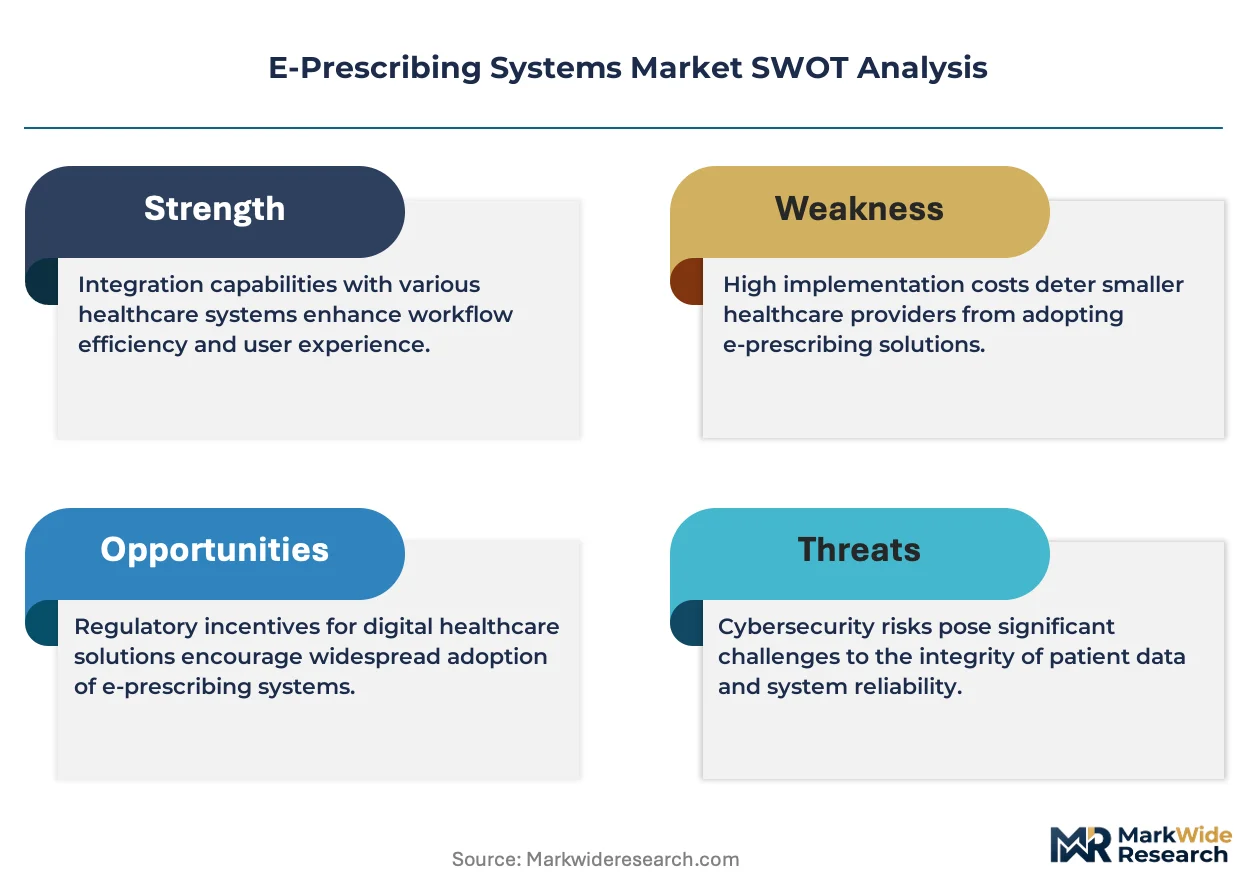
- Interoperability complexity:Bidirectional data synchronization with legacy EHR repositories extends implementation timelines and elevates failure risk.
- State-level mandate fragmentation:Non-uniform e-prescribing requirements across US jurisdictions create compliance overhead for multi-state provider organizations.
- Specialty pharmacy exclusion:Limited connectivity to compounding and specialty dispensing channels restricts clinical utility for complex therapeutic categories.
Strategic Opportunities
- Federally qualified health centers:Rural and community clinic modernization programs represent underpenetrated deployment vectors outside major hospital networks.
- Real-time benefit integration:Convergence of prescribing workflows with patient-specific cost transparency tools is opening new value-added service layers.
- Substance abuse monitoring:Prescription drug monitoring program (PDMP) integration mandates are creating demand for enhanced controlled substance tracking modules.
Industry Challenges
- Clinical informatics talent scarcity:Health systems face recruitment gaps for specialists capable of configuring medication decision support rules and alert fatigue mitigation.
- ONC certification timeline compression:Accelerated Health IT Certification Program update cycles strain vendor development resources and customer upgrade coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Prescribing Systems Market |
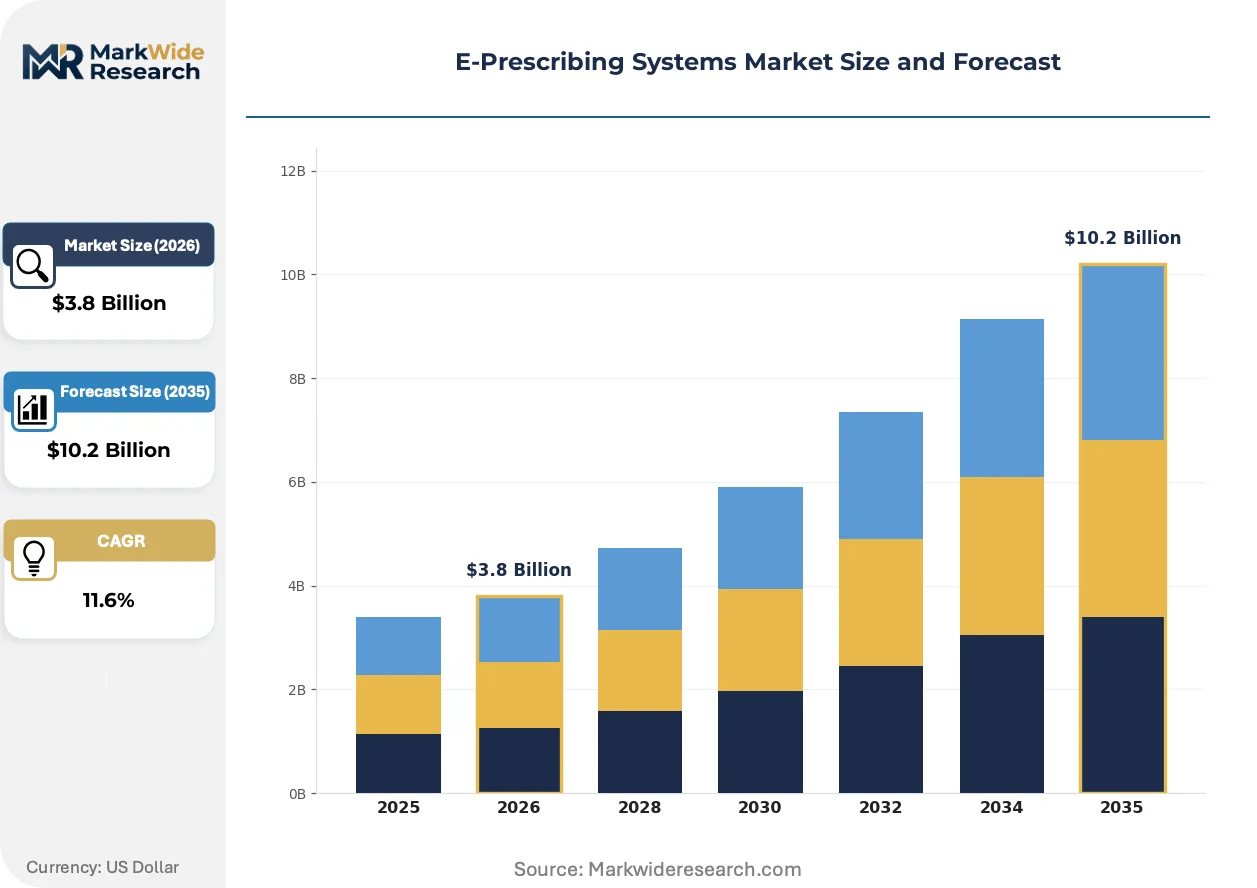
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, Web-Based, Software, Mobile Technology: Interoperability, EHR Integration, Analytics Tools, Blockchain End User: Pharmacies, Healthcare Providers, Hospitals, Outpatient Clinics Delivery Mode: On-Premise, SaaS, Remote Access, Hybrid |
| Companies Covered | Allscripts Healthcare Solutions, Change Healthcare, Epic Systems Corporation, eClinicalWorks, DrFirst, Surescripts, Athenahealth, Henry Schein, Cerner Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Prescribing Systems Market Emerging Trajectories
Prescribing platform architecture is pivoting from standalone modules toward embedded, context-aware workflow components that anticipate clinical decision points rather than interrupt them.
Artificial intelligence is absorbing medication reconciliation and drug-drug interaction surveillance from rule-based engines. Hospital networks with advanced clinical informatics capabilities are piloting machine learning models for predictive adverse event flagging. This capability shift is absorbing technical differentiation from legacy alert systems into algorithmic platforms.
The DEA's electronic prescribing for controlled substances (EPCS) final rule is mandating two-factor authentication and identity proofing standards that exceed baseline HIPAA requirements. Specialty practices with high controlled substance volumes are experiencing the steepest compliance cost escalations. Vendors are responding by embedding EPCS certification into core platform offerings rather than treating it as a premium module.
Consolidated purchasing through pharmacy benefit manager-owned technology subsidiaries is displacing direct vendor relationships for large employer-sponsored health plans. Self-insured employers are ceding prescribing platform selection to their PBM partners in exchange for integrated formulary management. This channel concentration is most pronounced in the United States, where vertical integration between PBMs and technology platforms has advanced furthest.
E-Prescribing Systems Market Segmentation
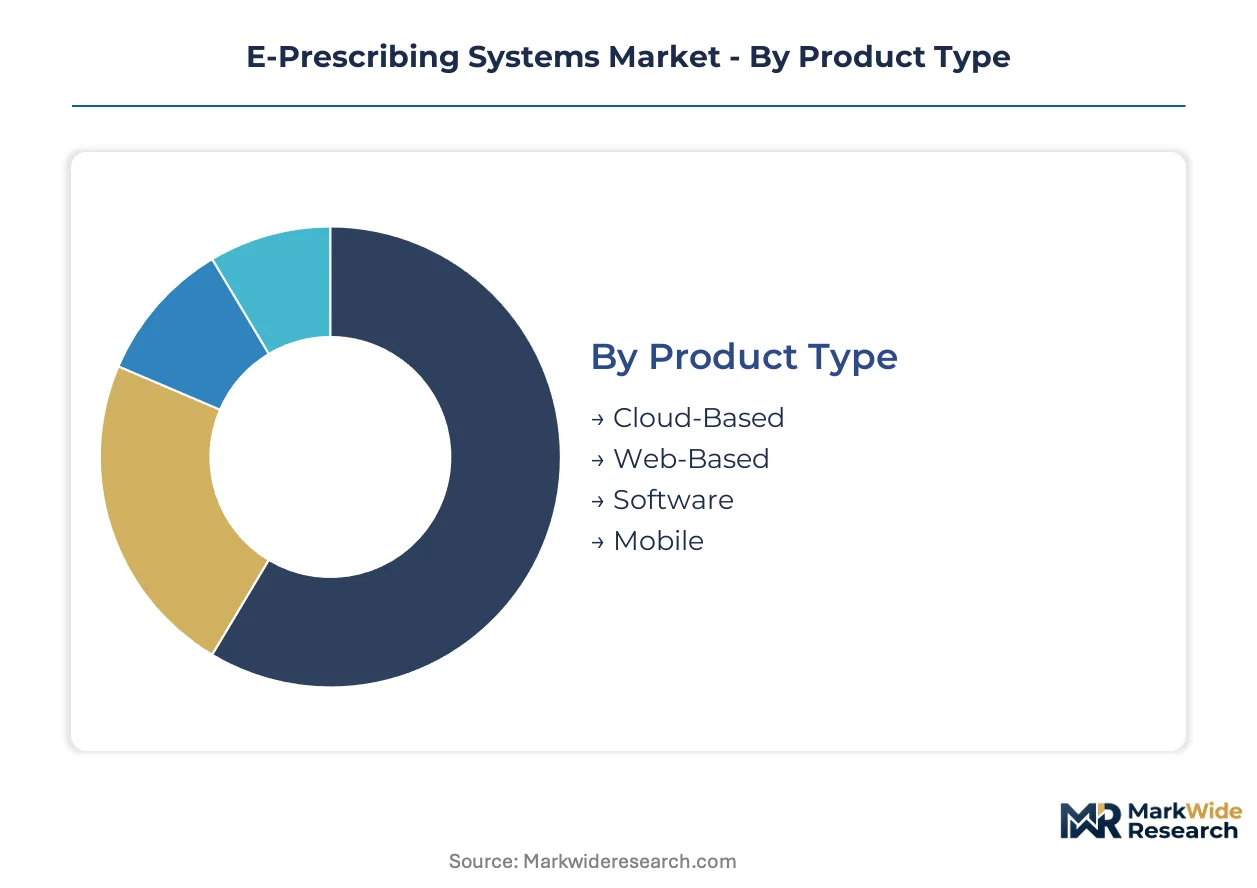
E-prescribing system segmentation reveals how procurement decisions split across technical architecture, integration depth, and care setting economics. Vendors must align platform roadmaps with the dominant purchasing logic of each axis to capture expansion opportunities.
Product Type:
Deployment architecture determines capital commitment, upgrade velocity, and IT staffing requirements across buyer organizations.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server maintenance and enable automatic regulatory compliance updates. Hospital networks in the United States with limited internal IT infrastructure favor this model for DEA EPCS mandate adherence without hardware investment.
- Web-Based:Browser-accessible platforms with lighter client-side requirements suit distributed clinic networks and rural health centers. Federally qualified health centers expanding e-prescribing capacity select web-based options for minimal endpoint configuration.
- Software:Perpetual license installations with local data retention persist in health systems with strict data sovereignty policies. These deployments concentrate in specialty hospital networks with legacy infrastructure dependencies.
- Mobile:Native iOS and Android applications extend prescribing workflows to point-of-care mobility. Outpatient clinic physicians with high patient throughput utilize mobile interfaces for prescription generation between examination rooms.
Mature deployment sits with Software installations in established hospital networks. Newer deployment is concentrated in Cloud-Based platforms across mid-size health systems.
Technology:
Functional capabilities differentiate vendor offerings beyond basic prescription transmission, with integration sophistication commanding premium positioning.
- Interoperability:NCPDP SCRIPT standard compliance and cross-platform data exchange protocols enable pharmacy network connectivity. Health systems consolidating multiple EHR instances prioritize interoperability layers to unify prescribing workflows.
- EHR Integration:Bidirectional data synchronization with clinical repositories embeds prescribing into existing documentation workflows. Epic and Cerner deployments require deep EHR integration for user adoption and alert fatigue mitigation.
- Analytics Tools:Medication adherence dashboards, prescriber pattern analysis, and population health reporting modules. Pharmacy benefit managers embed analytics tools for formulary compliance monitoring across covered lives.
- Blockchain:Distributed ledger architectures for controlled substance tracking and prescription audit trails. Pilot implementations focus on opioid prescription integrity verification in states with aggressive PDMP mandates.
Revenue concentration aligns with EHR Integration capabilities in large hospital networks. Analytics Tools are gaining share fastest among value-based care organizations.
End User:
Purchasing authority and workflow requirements vary substantially across the care continuum, shaping solution packaging and sales channel strategy.
- Pharmacies:Dispensing system connectivity, real-time prescription status updates, and inventory synchronization requirements. Independent pharmacies and regional chains drive demand for multi-vendor interoperability.
- Healthcare Providers:Individual and small-group practices requiring streamlined prior authorization and formulary checking. Solo practitioners in outpatient settings select lightweight platforms with minimal training requirements.
- Hospitals:Enterprise-scale deployments with inpatient and ambulatory workflow coverage, anesthesia and emergency department modules, and controlled substance vault integration. Academic medical centers represent the highest-complexity implementation category.
- Outpatient Clinics:Federally qualified health centers, urgent care chains, and specialty clinics with high prescription volume and limited IT support. Rural clinic modernization programs are expanding this segment most aggressively.
Platform complexity peaks with Hospital deployments. Outpatient Clinics represent the steepest expansion trajectory as federal incentive programs extend to community care settings.
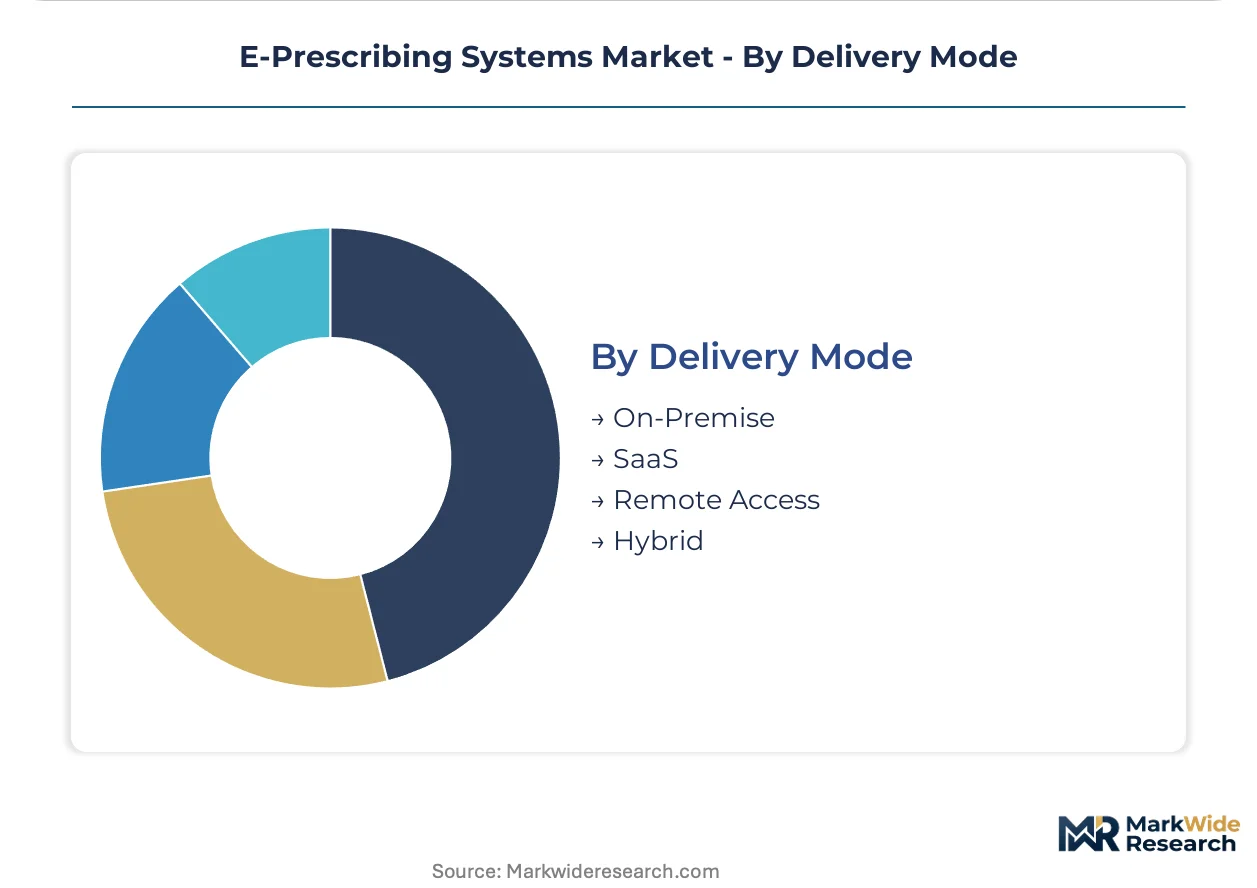
Delivery Mode:
Infrastructure control preferences and security postures determine how health systems balance operational flexibility against data governance requirements.
- On-Premise:Local server installations with direct hardware control and customizable security configurations. Health systems with legacy capital investments and specialized compliance needs maintain on-premise deployments.
- SaaS:Subscription-based cloud delivery with vendor-managed infrastructure and automatic feature updates. Mid-size hospital networks reducing IT overhead are migrating procurement toward SaaS models.
- Remote Access:Virtual private network and terminal services enabling prescribing from non-facility locations. Telehealth expansion and physician mobility requirements are elevating remote access module priority.
- Hybrid:Split architectures with sensitive controlled substance functions on-premise and standard prescribing in cloud environments. Multi-state health systems navigate varying state data residency laws through hybrid configurations.
Procurement gravity centers on SaaS for new health system implementations. Hybrid architectures are climbing fastest among organizations with complex regulatory footprints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital networks in the United States absorb the dominant share of e-prescribing platform procurement, driven by federal mandate convergence and pharmacy benefit manager integration. Cloud-native deployments concentrate most intensely in this market, with mid-size health systems accelerating migration from legacy on-premise installations.
United States
Federal incentive programs and DEA EPCS mandates drive procurement velocity across ambulatory and inpatient settings. The 21st Century Cures Act forces compliance upgrades for Schedule II-V controlled substances nationwide. Hospital consolidation in Texas, Florida, and California creates multi-facility standardization opportunities for platform vendors.
Germany
EMA electronic prescribing guidelines and national health IT modernization programs elevate interoperability requirements. The country's national pharmaceutical regulator mandates cross-border prescription recognition under EU digital health frameworks. Berlin and Munich health clusters pilot blockchain-enabled audit trails for opioid tracking.
United Kingdom
NHS Digital's Electronic Prescription Service expansion targets primary care network integration. The national health service's IT certification program filters vendor eligibility through stringent security thresholds. London's academic medical centers represent the highest-complexity implementation category for embedded prescribing workflows.
Canada
Provincial health authority procurement concentrates demand in Ontario, Quebec, and British Columbia. Health Canada oversees controlled substance e-prescribing standards that exceed baseline privacy requirements. Toronto and Vancouver hospital networks standardize prescribing workflows across acquired community clinic entities.
Australia
TGA digital health frameworks and national medication safety initiatives accelerate platform adoption. The country's national pharmaceutical regulator certifies interoperability requirements through its health IT conformance program. Sydney and Melbourne health clusters lead deployment of real-time benefit integration tools.
E-Prescribing Systems Market Vendor Landscape
Strategic partnerships dominate the current landscape as vendors embed prescribing modules into broader clinical platform ecosystems. The vendor base splits between EHR-integrated incumbents and standalone SaaS specialists, with mid-tier consolidation accelerating through health system procurement centralization. Three archetypes define competitive positioning: EHR-native platforms, independent cloud specialists, and pharmacy network infrastructure providers. M&A activity and API-based ecosystem expansion represent the dominant competitive moves as vendors race to capture health system standardization mandates.
Within the EHR-native tier, Epic Systems Corporation and Cerner Corporation anchor enterprise-scale deployments through embedded workflow integration. Athenahealth exemplifies the SaaS economics archetype, reducing upfront capital barriers for outpatient clinic networks. Surescripts occupies a position as the pharmacy network infrastructure anchor, facilitating cross-platform prescription routing and formulary verification.
| Leading Market Players |
|---|
| Allscripts Healthcare Solutions |
| Change Healthcare |
| Epic Systems Corporation |
| eClinicalWorks |
| DrFirst |
| Surescripts |
| Athenahealth |
| Henry Schein |
| Cerner Corporation |
| Others |
Supply Flow & Price Mechanics
Hospital procurement centralization in the United States is compressing vendor selection cycles and forcing platform providers to absorb implementation cost overruns to secure multi-facility contracts. This buyer-side consolidation is reshaping how e-prescribing vendors structure subscription tiers and where they anchor development resources.
Pricing Analysis
Volume concentration among large health systems is squeezing margins for mid-tier vendors while premium positioning persists for EHR-integrated incumbents. SaaS subscription models dominate new procurement, with pricing stratifies across enterprise, mid-market, and clinic-tier levels based on EHR integration depth and controlled substance compliance modules. Cost compression in the mid-market tier is intensifying because Athenahealth and similar cloud specialists are undercutting legacy perpetual-license vendors. Federally qualified health centers exhibit highest price sensitivity, while academic medical centers prioritize integration sophistication over subscription cost.
Supply Chain Analysis
Direct-to-hospital sales channels handle enterprise-scale deployments, with value-added resellers and GPO contracts capturing mid-size network demand. Development resources concentrate in the United States, India, and Ireland, with cloud infrastructure provisioning anchored in domestic data centers for HIPAA compliance. Platform engineering draws from specialized health IT talent pools, cybersecurity certification pipelines, and clinical informatics training programs. Single-source vulnerability in DEA EPCS certification auditing creates compliance bottleneck risk. Distribution runs through pharmacy benefit manager technology subsidiaries for employer-sponsored plan segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
E-prescribing platform consolidation is accelerating as interoperability mandates and certification overhead force subscale vendors toward exit or acquisition. Federal compliance timeline compression is the dominant pressure eliminating weaker players.
For Market Incumbents: Deepen EHR integration moats by embedding predictive medication decision support directly into Epic and Cerner clinical workflows. Acquire specialized PDMP connectivity vendors to preempt standalone competitors from capturing controlled substance tracking modules. Cloud-native challengers with superior SaaS economics represent the primary threat to embedded positioning. For New Entrants and Emerging Players: Launch via lightweight web-based platforms targeting federally qualified health centers in rural Texas and Florida markets underserved by enterprise sales teams. White-space opportunity concentrates in real-time benefit integration tools for value-based care organizations. Go-to-market angle should emphasize rapid DEA EPCS compliance without hardware investment. For Investors and Strategic Acquirers: The window for entry favors clinical informatics specialists with proven ONC certification track records. Long-term viability hinges on platform consolidation into broader health IT ecosystems rather than standalone prescribing functionality. Acquisition target archetype: cloud-native vendors with existing hospital network deployments and embedded analytics capabilities. Signal to watch is PBM-owned technology subsidiary acquisition velocity as vertical integration accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding prescribing workflows into Epic and Cerner EHR architectures captures hospital standardization mandates. |
| DEA EPCS Certification | Two-factor authentication and identity proofing compliance opens controlled substance prescribing revenue pools. |
| PDMP Module Development | Prescription drug monitoring program integration addresses state-level substance abuse tracking requirements. |
| Real-Time Benefit Integration | Patient-specific cost transparency tools create value-added service layers for value-based care organizations. |
| Geographic Expansion | Rural clinic modernization programs in Texas and Florida extend platform reach outside major hospital networks. |
Methodological Framework
Independent corroboration across hospital CIO interviews, pharmacy benefit manager technology officers, and clinical informatics directors underwrites the qualitative findings. Primary fieldwork captured prescribing workflow requirements, EHR integration pain points, and procurement decision criteria across ambulatory and inpatient settings. Secondary validation drew from FDA EPCS guidance documents, ONC Health IT Certification Program updates, CMS Medicare e-prescribing incentive data, and state-level PDMP mandate registries. Bottom-up deployment estimates triangulated against top-down health system IT spending benchmarks.
Rate-of-change decomposition across deployment model shifts, regulatory compliance waves, and hospital consolidation patterns structured the analytical framework. Segmentation modeling captured product architecture, EHR integration depth, end-user category, and care setting economics throughout the forecast period. CAGRs derived from facility-level adoption curves, mandate phase-in schedules, and technology replacement cycles. Forecast inputs included DEA EPCS compliance deadlines and federally qualified health center modernization program allocations.
Regulatory timeline delays, PBM technology subsidiary acquisition patterns, and interoperability standard revision cycles are the dominant revision risks. Forecasts reflect assumptions regarding federal mandate enforcement consistency and hospital network consolidation velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Veterinary Practice Management Software Market
Healthcare IT
Healthcare Business Collaboration Tools Market
Healthcare IT
Healthcare Ediscovery Market
Healthcare IT
Global Technology Spending on Core Administration in Healthcare Market
Healthcare IT
Asia-Pacific Dental Practice Management Software Market
Healthcare IT
Neurosurgery Software Market
Healthcare IT
Pharma Management Software Market
Healthcare IT
Global Pharmacy Inventory Management Software Solutions and Cabinets Market
Healthcare IT
ECG Management Systems Market
Healthcare IT
Global Computerized Physician Order Entry (CPOE) Systems Market
Healthcare IT
Global Orthopedic Software Market
Healthcare IT
Global Patient Intake Software Market
Healthcare IT
Global RFID in Healthcare Market
Healthcare IT
Anatomic Pathology Track and Trace Solutions Market
Healthcare IT
Prior Authorization Software Market
Healthcare IT
Veterinary Dental Software Market