
 Hospital Logistics Robots Market | 2026-2036
Hospital Logistics Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Logistics Robots Market Analysis
Market Context with Strategic Players
Modular robot fleets bundled with software analytics and charging infrastructure are broadening procurement options for hospital administrators weighing capital versus operational expenditure models. Swisslog Healthcare leverages its heritage in pneumatic tube systems to anchor automated guided vehicle deployments across integrated delivery networks. Diligent Robotics Inc. specializes in humanoid-style autonomous mobile robots designed specifically for clinical supply rounds in acute care corridors. Panasonic Holdings Corporation extends its sensor manufacturing scale into navigation hardware for third-party robot integrators.
Technical Definition and Structural Segments
Hospital logistics robots comprise wheeled autonomous systems equipped with lidar, ultrasonic arrays, and computer vision processors, typically operating at speeds below two meters per second within mapped facility zones to transport pharmaceuticals, linens, laboratory specimens, and meals. Their primary commercial purpose is to displace manual transport labor while reducing delivery latency and chain-of-custody errors in twenty-four-hour healthcare operations. Autonomous mobile robots now capture the fastest expansion trajectory as lidar costs decline and simultaneous localization and mapping algorithms mature for dynamic pedestrian environments. Material handling applications dominate current installed base value, though inventory management functions are deepening through IoT Integration with existing enterprise resource planning systems. Robotic delivery systems occupy a narrower but higher-margin niche serving sterile processing departments and operating room supply replenishment.
Regulatory Frame and Forward Outlook
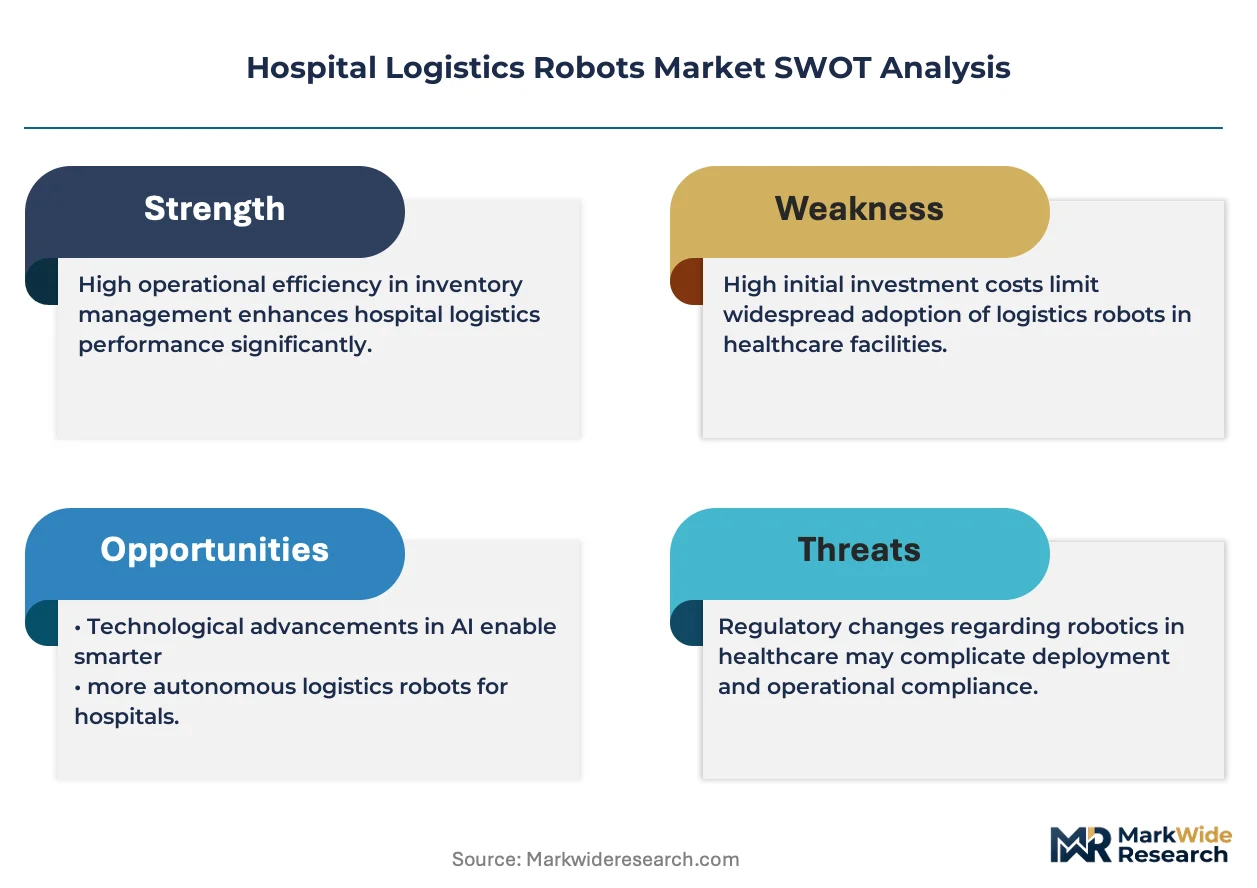
The FDA regulates these systems under medical device or general wellness classifications depending on payload risk, while OSHA workplace safety standards govern human-robot collaboration zones in US facilities; the EU Medical Device Regulation and CE marking requirements shape market access for European deployments. Japan's Ministry of Economy, Trade and Industry promotes hospital automation through JIS standards harmonization with ISO 13482 service robot safety protocols. Stakeholders must monitor how cybersecurity frameworks for connected healthcare infrastructure reshape software update obligations and liability allocation across robot OEMs and hospital operators.
Market Dynamics
Fleet standardization pressures are compressing procurement cycles as acute care hospitals consolidate vendor relationships around platforms offering unified software analytics, charging infrastructure, and predictive maintenance modules.
Growth Catalysts
- FDA pathway clarity:Evolving guidance on autonomous medical device systems accelerates product clearance timelines for navigation hardware and control software submissions in the United States.
- Acute care labor displacement:Twenty-four-hour medication and supply transport rounds create persistent demand for wheeled autonomous systems operating below two meters per second in mapped corridors.
- Lidar cost deflation:Simultaneous localization and mapping algorithm maturation for dynamic pedestrian environments expands deployable use cases beyond sterile processing into general medical-surgical units.
Market Restraints
- Navigation sensor supply concentration:Lidar and computer vision processor manufacturing clusters in East Asian foundries expose fleet operators to semiconductor allocation volatility and tariff exposure.
- Capital expenditure intensity:Charging infrastructure, facility mapping, and integration with enterprise resource planning systems require upfront outlays that strain non-profit hospital balance sheets.
- Cybersecurity liability fragmentation:Unclear allocation of software update obligations between robot original equipment manufacturers and hospital operators under connected healthcare infrastructure frameworks creates procurement hesitation.
Strategic Opportunities
- Inventory management convergence:IoT integration with existing enterprise resource planning systems deepens robot fleet utility beyond material handling into real-time supply chain visibility.
- German installation base expansion:Swisslog Healthcare and Mobile Industrial Robots A/S anchor European demand concentration, creating reference architecture for neighboring acute care networks in Austria and Switzerland.
- Japan METI automation promotion:Ministry of Economy, Trade and Industry harmonization of JIS standards with ISO 13482 service robot safety protocols subsidizes hospital automation pilot programs.
Industry Challenges
- Human-robot collaboration zone design:OSHA workplace safety standards in the United States require facility reconfiguration for mapped autonomous zones, extending deployment timelines.
- Legacy pneumatic tube integration:Hospitals with extensive existing tube infrastructure face complex interoperability decisions when layering autonomous mobile robots onto established supply workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital Logistics Robots Market |
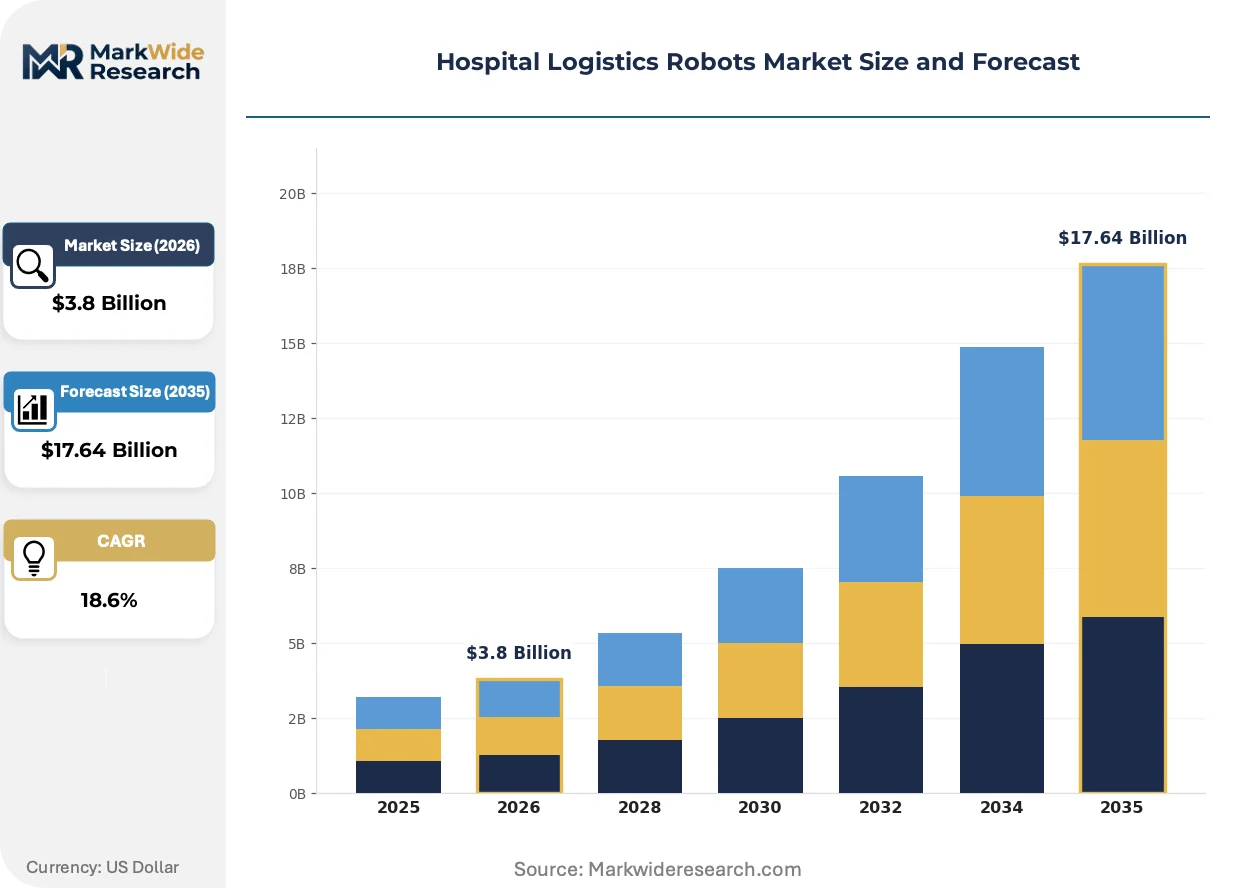
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Robot Type: Automated Guided Vehicles, Autonomous Mobile Robots, Robotic Delivery Systems, Robotic Shelving Units Application: Material Handling, Inventory Management, Waste Disposal, Patient Transport End User: Hospitals, Clinics, Research Facilities, Rehabilitation Centers Technology: IoT Integration, Machine Learning, Navigation Systems, Computer Vision |
| Companies Covered | Mobile Industrial Robots A/S, Swisslog Healthcare, DF Automation & Robotics Sdn Bhd, Relay Robotics Inc., Panasonic Holdings Corporation, Diligent Robotics Inc., Omron Robotics, St Engineering Aethon Inc., JBT Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Logistics Robots Market Emerging Trajectories
Navigation hardware architectures and software control layers are decoupling from monolithic platform sales, enabling hospital administrators to mix sensor suppliers and fleet management providers within unified operational environments.
Autonomous mobile robot chassis designs are modularizing around swappable payload compartments, allowing identical base units to alternate between pharmaceutical transport, linen delivery, and meal distribution within single shift cycles. Acute care hospitals in integrated delivery networks are adopting these flexible configurations to maximize fleet utilization rates across variable demand patterns. This hardware flexibility is modularizing procurement decisions, separating navigation system investments from application-specific payload engineering and compressing total cost of ownership calculations.
The EU Medical Device Regulation and CE marking requirements are tightening clinical evidence standards for robots transporting sterile supplies and laboratory specimens in European facilities. Manufacturers must now submit technical documentation demonstrating electromagnetic compatibility and biocompatibility for payload contact surfaces, extending clearance timelines. German and Swiss acute care networks are responding by pre-qualifying vendors with established MDR conformity assessment certificates, concentrating procurement among incumbent suppliers.
Hospital administrators are unbundling after-sales service contracts from initial capital purchases, negotiating separate agreements for predictive maintenance, software updates, and cybersecurity monitoring. This purchasing behavior shift disrupts traditional bundled pricing models and pressures original equipment manufacturers to disclose component-level service costs. The United States exhibits the most advanced unbundling, with multi-hospital systems leveraging scale to demand granular service line-item transparency.
Hospital Logistics Robots Market Segmentation
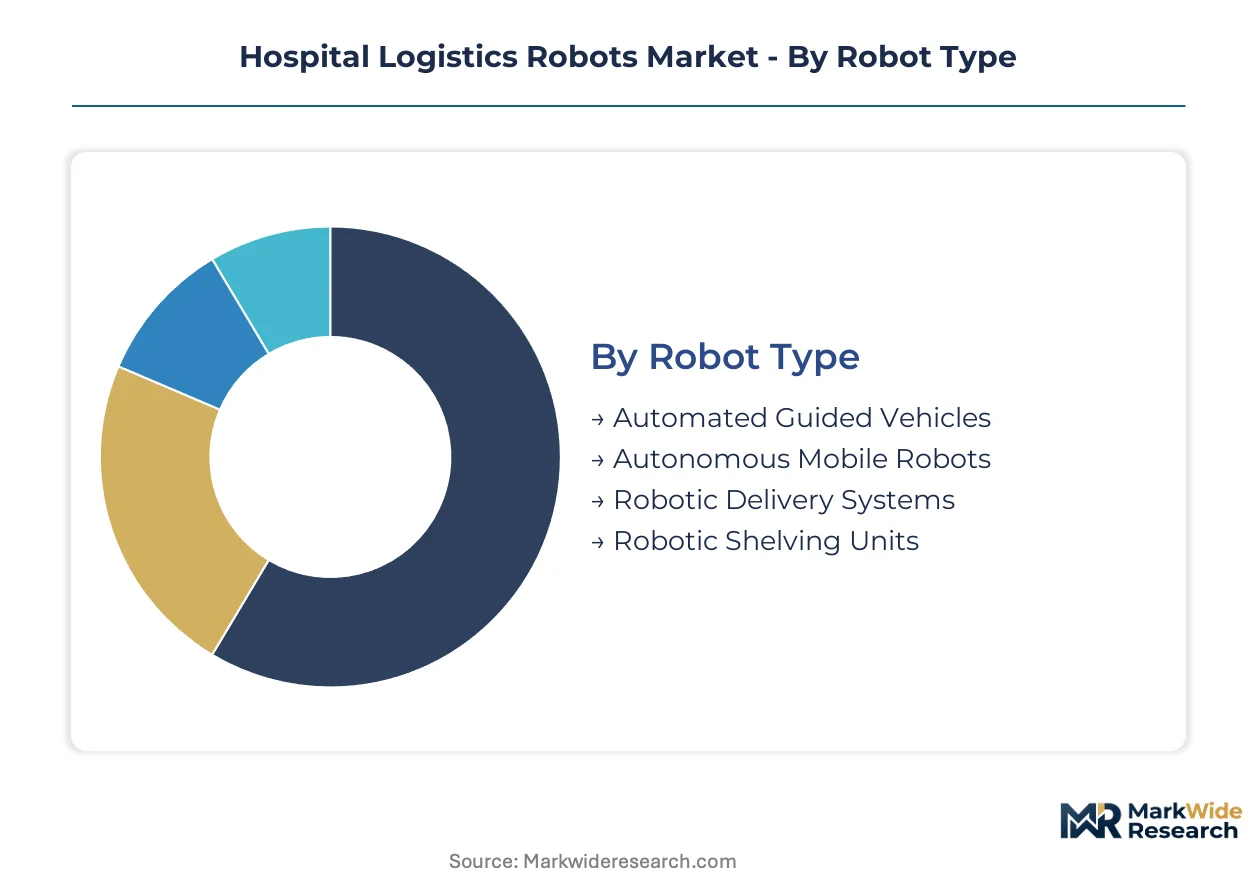
Hospital logistics robots serve distinct operational layers within healthcare facilities, from standalone corridor transport to deeply embedded inventory systems. Understanding where each segment sits on this integration spectrum clarifies procurement priorities for administrators balancing immediate labor displacement against long-term digital infrastructure.
Robot Type:
Standalone wheeled systems dominate corridor deployments, while embedded infrastructure requires tighter building integration and longer capital cycles.
- Automated Guided Vehicles:These magnetically or tape-guided platforms follow fixed facility routes at controlled speeds, typically below two meters per second. Acute care networks in Germany concentrate procurement here, drawn by Swisslog Healthcare's pneumatic tube heritage and proven integration with legacy building systems. Magnet tape infrastructure limits flexibility but delivers predictable capital expenditure profiles for non-profit hospital balance sheets.
- Autonomous Mobile Robots:Lidar-equipped units navigate dynamic pedestrian environments without facility-mounted guidance infrastructure. Demand concentrates in United States integrated delivery networks where FDA pathway clarity on autonomous medical device systems accelerates deployment timelines. Simultaneous localization and mapping algorithm maturation expands these units from sterile processing into general medical-surgical corridors.
- Robotic Delivery Systems:Specialized chassis designed for sterile supply and operating room replenishment with sealed payload compartments.
- Robotic Shelving Units:Vertical storage systems with automated retrieval for pharmacy and central supply inventory.
Automated Guided Vehicles lead volumes today; Autonomous Mobile Robots are gaining share fastest.
Application:
Material movement commands current fleet deployment, though data-layer applications deepen software attach rates and recurring revenue.
- Material Handling:Pharmaceutical, linen, meal, and specimen transport between departments via wheeled autonomous platforms. Acute care hospitals deploy these systems to displace twenty-four-hour manual transport rounds, with United States facilities leading adoption under OSHA workplace safety frameworks for human-robot collaboration zones.
- Inventory Management:Real-time supply chain visibility through IoT Integration with enterprise resource planning systems. German and Swiss acute care networks prioritize this function, responding to EU Medical Device Regulation requirements for chain-of-custody documentation on sterile supplies and laboratory specimens.
- Waste Disposal:Automated collection and transport of regulated medical waste from patient care areas to processing stations.
- Patient Transport:Non-ambulatory patient movement between departments via specialized robotic stretcher and wheelchair platforms.
Material Handling leads volumes today; Inventory Management is climbing the fastest as IoT integration deepens.
End User:
Facility scale determines fleet economics, with larger campuses amortizing charging infrastructure and mapping costs across more robot units.
- Hospitals:Multi-building acute care campuses with twenty-four-hour operations and complex internal logistics networks. These facilities concentrate demand in the United States and Germany, where FDA and EU Medical Device Regulation frameworks respectively shape clearance pathways for autonomous systems.
- Clinics:Smaller outpatient and ambulatory surgical facilities with lighter transport volumes and simpler corridor layouts.
- Research Facilities:Academic medical centers and biotechnology laboratories with specialized specimen handling requirements.
- Rehabilitation Centers:Long-term care and physical therapy facilities with patient mobility assistance needs.
Hospitals lead volumes today; Research Facilities are expanding most quickly as laboratory automation converges with logistics robotics.
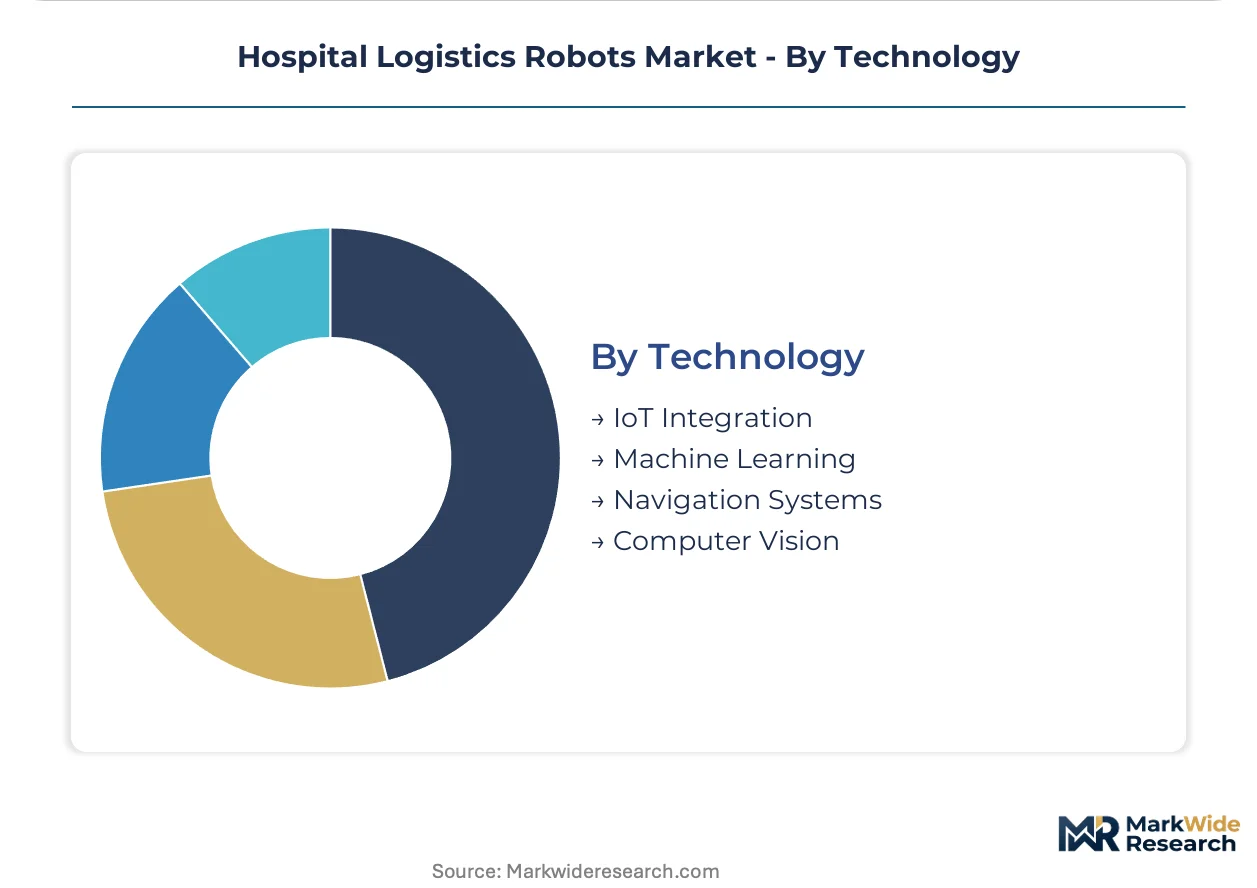
Technology:
Hardware-software decoupling enables hospital administrators to mix sensor suppliers and fleet management providers within unified operational environments.
- IoT Integration:Connected sensor networks linking robot fleets to enterprise resource planning and building management systems. United States multi-hospital systems leverage this capability most aggressively, unbundling after-sales service contracts to demand granular software update and cybersecurity monitoring transparency.
- Navigation Systems:Lidar, ultrasonic arrays, and simultaneous localization and mapping processors enabling autonomous corridor operation. Panasonic Holdings Corporation extends its sensor manufacturing scale into this layer for third-party robot integrators, with East Asian foundries concentrating production.
- Machine Learning:Predictive algorithms for demand forecasting, route optimization, and predictive maintenance scheduling.
- Computer Vision:Camera-based object recognition and pedestrian detection for dynamic environment navigation.
Navigation Systems lead volumes today; IoT Integration is expanding most quickly as fleet management platforms consolidate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital logistics robotics originated in European acute care networks during the 1990s, with Swiss and German facilities pioneering automated guided vehicle deployments for sterile supply chains. This heritage continues shaping procurement patterns across mature healthcare systems.
United States
Integrated delivery networks in Texas and Florida are consolidating fleet procurement around unified software analytics platforms. FDA pathway clarity on autonomous medical device systems accelerates product clearance timelines for navigation hardware submissions. The Greater Boston corridor hosts concentrated pilot programs testing human-robot collaboration zones under OSHA workplace safety frameworks.
Germany
Acute care hospitals in Bavaria and North Rhine-Westphalia anchor European installation volumes for medication transport systems. EU Medical Device Regulation requirements for chain-of-custody documentation on sterile supplies tighten vendor qualification standards. Stuttgart-based engineering clusters supply lidar navigation hardware to third-party robot integrators serving neighboring Swiss and Austrian networks.
Japan
Metropolitan Tokyo hospitals are expanding autonomous mobile robot trials for twenty-four-hour supply rounds in aging demographic conditions. METI harmonization of JIS standards with ISO 13482 service robot safety protocols subsidizes automation pilot programs. Osaka-Kansai medical centers concentrate demand for robotic shelving units in pharmacy inventory applications.
China
Tier-one hospitals in Shanghai and Beijing are importing navigation hardware for domestic robot assembly under technology transfer arrangements. NMPA medical device classification frameworks for autonomous systems remain under development, creating regulatory uncertainty. Yangtze River Delta manufacturing clusters produce ultrasonic sensor arrays for regional robot integrators.
Switzerland
Swiss acute care networks in Zurich and Geneva pre-qualify vendors with established MDR conformity assessment certificates, concentrating procurement among incumbent suppliers. Swissmedic oversight of connected medical devices shapes cybersecurity requirements for fleet management software. Basel pharmaceutical logistics hubs drive demand for sealed payload compartments in laboratory specimen transport.
Hospital Logistics Robots Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with healthcare divisions rather than pure-play robotics specialists. Tier-one positions cluster around companies with pneumatic tube heritage or sensor manufacturing scale, while mid-tier players compete on modular chassis flexibility. Two strategic archetypes dominate: integrated platform providers bundling hardware with predictive maintenance software, and component suppliers selling navigation systems to third-party integrators. Capacity expansion in East Asian foundries and strategic partnerships between sensor manufacturers and hospital systems represent the primary competitive moves.
Within the diversified conglomerate tier, Panasonic Holdings Corporation and JBT Corporation occupy positions anchored by manufacturing scale and process automation heritage respectively. Mobile Industrial Robots A/S and Swisslog Healthcare exemplify the integrated platform archetype, with the latter leveraging pneumatic tube system heritage. Diligent Robotics Inc. represents the specialized clinical application segment, while Relay Robotics Inc. and St Engineering Aethon Inc. sit within the mid-tier autonomous mobile robot category. Omron Robotics and DF Automation & Robotics Sdn Bhd anchor regional supply positions in East Asian and Southeast Asian markets respectively.
| Leading Market Players |
|---|
| Mobile Industrial Robots A/S |
| Swisslog Healthcare |
| DF Automation & Robotics Sdn Bhd |
| Relay Robotics Inc. |
| Panasonic Holdings Corporation |
| Diligent Robotics Inc. |
| Omron Robotics |
| St Engineering Aethon Inc. |
| JBT Corporation |
| Others |
Supply Flow & Price Mechanics
United States hospital procurement committees are unbundling after-sales service contracts from capital purchases, forcing original equipment manufacturers to disclose component-level costs and compressing bundled pricing premiums across navigation hardware and fleet management software tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared autonomous systems from CE-marked equivalents and uncertified regional alternatives. Price differentiation hinges on electromagnetic compliance certification grade and predictive maintenance software bundling. Cost compression in economy tiers is intensifying because East Asian sensor suppliers are bypassing integrators to sell direct to mid-tier robot assemblers. Non-profit hospital systems exhibit highest price sensitivity, while integrated delivery networks prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Ocean freight and air cargo costs for lidar arrays and computer vision processors from East Asian foundries to German and United States assembly plants represent 8-12% of landed navigation hardware cost. Manufacturing concentrates in China, Taiwan, and South Korea for ultrasonic sensor arrays, lidar emitters, and SLAM processing chips. Semiconductor allocation volatility and tariff exposure on Chinese-origin components constitute the primary structural risk. Distribution runs through third-party robot integrators who combine navigation systems with chassis assembly and hospital facility mapping services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where FDA pathway clarity in the United States accelerates premium product clearance timelines against EU MDR documentation burdens that extend vendor qualification cycles in Germany and Switzerland.
For Market Incumbents: Extend predictive maintenance software attach rates to defend against modular hardware-software decoupling threats from navigation component suppliers. Deepen backward integration into lidar assembly through partnerships with Stuttgart-based engineering clusters to secure supply continuity. Lock in multi-hospital system master service agreements before procurement committees complete vendor consolidation around unified fleet analytics platforms. For New Entrants and Emerging Players: Launch via software-only fleet management licensing to bypass capital-intensive chassis manufacturing barriers. White-space opportunity concentrates in Japanese metropolitan hospital pilots subsidized by METI automation programs, where incumbent presence remains thin. Target research facility laboratory automation convergence as the most penetrable application segment, leveraging simpler corridor layouts and lighter regulatory documentation requirements than acute care sterile processing. For Investors and Strategic Acquirers: Asymmetric upside sits with navigation hardware specialists possessing ISO 13482 safety certification and existing hospital system reference contracts. Five-to-ten year viability depends on cybersecurity software recurring revenue attach rates overtaking hardware depreciation cycles. Watch FDA guidance evolution on autonomous medical device classification as the signal indicating whether capital expenditure intensity will shift toward operational expenditure models.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Swisslog Healthcare leverages pneumatic tube heritage to anchor integrated delivery network fleet standardization decisions. |
| FDA Submission Pathway | Navigation hardware vendors accelerate product clearance timelines under evolving autonomous medical device guidance. |
| CE Marking Pathway | EU MDR technical documentation requirements for electromagnetic compatibility extend sterile supply robot clearance timelines. |
| Software Companion Development | IoT integration modules deepen enterprise resource planning connectivity and expand inventory management recurring revenue. |
| Reimbursement Strategy | Operational expenditure models align hospital procurement with GPO contract structures for medical device leasing. |
Methodological Framework
Multiple input streams — hospital procurement committee interviews, biomedical engineer surveys, and GPO contracts database analysis — were reconciled against secondary validation from FDA 510(k) filings, EU MDR technical documentation repositories, and METI automation pilot program disclosures. Primary fieldwork engaged fleet operations managers, clinical supply directors, and robot OEM product strategists. Secondary sources included hospital capital expenditure records, pneumatic tube system migration case studies, and semiconductor trade flow data. Bottom-up unit deployment estimates and top-down healthcare logistics automation spending analysis were cross-referenced for triangulation.
Data-stream reconciliation across the analysis window applied segment-specific growth coefficients to robot type, application, end user, and technology dimensions. Modeled variables included lidar cost deflation trajectories, acute care labor displacement rates, and cybersecurity software attach rate assumptions. CAGRs were derived from logistic diffusion curves fitted to historical fleet deployment patterns and projected facility automation budgets. Industry-specific forecast inputs incorporated OSHA workplace safety standard evolution timelines and JIS-ISO 13482 harmonization progress.
Several conditions sit outside the modeled scope, including NMPA regulatory framework finalization in China, unforeseen semiconductor supply disruptions, and hospital merger activity altering integrated delivery network procurement authority concentration. Forecasts reflect documented assumptions about algorithm maturation rates and sensor manufacturing scale economies. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Cleaning Robot Market
Robotics and Automation
Non-Medical Biomimetic Robots Market
Robotics and Automation
Rehabilitation Robot Gloves Market
Robotics and Automation
SLAM Robots Market
Robotics and Automation
Commercial Robotics Market
Robotics and Automation
Automated Guided Vehicle (AGV) Market
Robotics and Automation
North America Collaborative Robots Market
Robotics and Automation
Robotic Drilling Market
Robotics and Automation
Intelligent Vending Machines Market
Robotics and Automation
Thailand Cloud Robotics Market
Robotics and Automation
Robot for Public Service Market
Robotics and Automation
Snake Robots Market
Robotics and Automation
Robotics Actuators Market
Robotics and Automation
Agriculture Robotics Market
Robotics and Automation
Autonomous Drilling Robots Market
Robotics and Automation
Global Adaptive Robotics Market