
 Tie Layer Resin Market | 2026-2036
Tie Layer Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Tie Layer Resin Market Analysis
REACH compliance is realigning the cost-of-entry calculus for European tie layer resin suppliers, forcing reformulation investments that smaller compounders struggle to fund. Dow Chemical Co. leverages its integrated polyethylene backbone to sustain cost advantages across multilayer film grades. ExxonMobil Corporation anchors its position through proprietary metallocene catalyst technology that delivers precise adhesion control. Mitsui Chemicals, Inc. competes by specializing in acid-modified polyolefins for automotive fuel tank barriers.
Tie layer resin functions as a chemically functionalized polyolefin interlayer engineered to bond dissimilar polymers in coextruded structures, typically incorporating maleic anhydride grafting at 0.1–0.5 weight percent to achieve polar adhesion to polyamide or ethylene vinyl alcohol. The material enables critical barrier performance in food packaging, fuel systems, and potable water infrastructure by preventing delamination under thermal and mechanical stress. Polyethylene formulations dominate volume throughput due to their compatibility with standard extrusion lines and broad substrate adhesion, while polyurethane variants command premium positioning in medical film laminates where FDA compliance tightens qualification cycles. Extrusion technology leads processing adoption for sheet and blown film, though injection molding gains traction as automotive tank-in-tank designs proliferate.
FDA migration limits and EPA leachate standards govern North American product qualification, while ECHA substance restrictions under REACH reshape European additive portfolios. China's GB standards and SAMR food-contact notifications create parallel compliance tracks that fragment certification costs across export destinations. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and redundant testing spend.
Market Dynamics
REACH compliance in Europe is forcing wholesale reformulation of maleic anhydride grafting chemistries, raising R&D burn rates for compounders while advantaging integrated resin producers with captive polymer backbones.
Growth Catalysts
- Multilayer packaging film demand:Food shelf-life extension requirements in North America and Asia-Pacific are accelerating coextrusion line installations, directly consuming acid-modified polyolefin interlayers.
- REACH-driven chemistry innovation:ECHA substance restrictions on high-migration additives are compelling suppliers to develop lower-extraction tie layer formulations that command qualification premiums.
- Infrastructure-grade pipe procurement:Centralized water and gas distribution projects in China and India are specifying multilayer polymer pipes with bonded barrier layers.
Market Restraints
- Maleic anhydride feedstock volatility:Crude butadiene and refinery stream disruptions transmit directly to grafting monomer costs, compressing compounder margins unpredictably.
- Specialty catalyst supply concentration:Metallocene and single-site catalyst production clusters in Germany and the United States create single-source vulnerability for precision adhesion grades.
- Polyurethane substitution in medical films:Solvent-free polyurethane laminates are displacing polyolefin tie layers in FDA Class II device packaging where migration limits tighten.
Strategic Opportunities
- Automotive tank-in-tank fuel systems:European OEMs are specifying coextruded high-density polyethylene barriers with tie layers to meet evaporative emission standards under UN ECE R34.
- Recyclable mono-material packaging:Design-for-recycling mandates under the EU Packaging and Packaging Waste Regulation are creating demand for compatibilizer tie layers that bond identical polymer types.
- Bio-based feedstock integration:Mass-balance certified polyethylene backbones are enabling premium positioning for tie layers in brand-owner sustainability scorecards.
Industry Challenges
- Migration testing protocol fragmentation:Divergent FDA, EFSA, and SAMR extraction conditions force redundant analytical spend and extend qualification timelines by 8-14 months.
- Coextrusion die design complexity:Layer thickness uniformity below 5 micrometers requires computational fluid dynamics expertise that resin suppliers rarely possess in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tie Layer Resin Market |
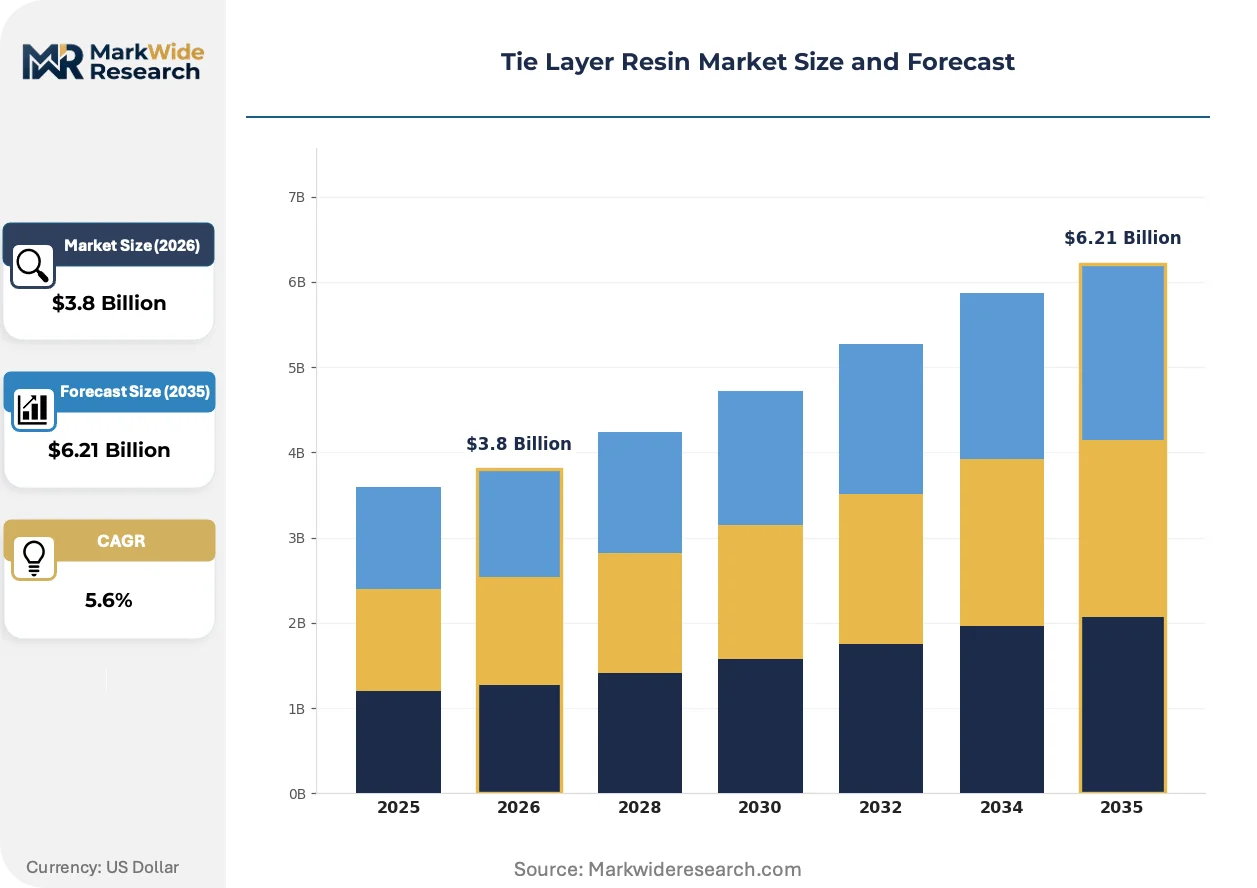
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Ethylene Vinyl Acetate, Polypropylene, Polyurethane Application: Pipes, Films, Coatings, Adhesives End User: Construction, Automotive, Packaging, Electronics Technology: Extrusion, Injection Molding, Blow Molding, Thermoforming |
| Companies Covered | LyondellBasell Industries Holdings B.V., Westlake Corporation, Mitsui Chemicals, Inc., Mitsubishi Chemical Corporation, Dow Chemical Co., Arkema Group, ExxonMobil Corporation, Eastman Chemical Company, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tie Layer Resin Market Emerging Trajectories
Reactive extrusion technology and regulatory chemistry constraints are converging to reshape how tie layer resins are formulated, processed, and qualified across food, medical, and industrial end-uses.
Multifunctional tie layer formulations incorporating both adhesion promotion and active oxygen scavenging are unifying previously separate film layers in retort pouch applications. Japanese packaging converters are piloting these hybrid grades for ready-meal formats. The technology is compressing total layer counts from seven to five while maintaining 24-month shelf stability.
REACH Annex XVII restrictions on phthalate-derived plasticizers are forcing reformulation of flexible tie layer grades used in medical tubing. German compounders are accelerating bio-circular feedstock certifications to maintain EMA medical device master file access. Pediatric and neonatal care segments face the steepest requalification burdens.
Direct resin procurement from compounders by multinational food brands is bypassing traditional distributor channels. North American CPGs are establishing approved supplier lists with audit rights over grafting reaction protocols. This disintermediation concentrates volume with tier-one resin producers while marginalizing regional compounders lacking ISO 22000 certification.
Tie Layer Resin Market Segmentation
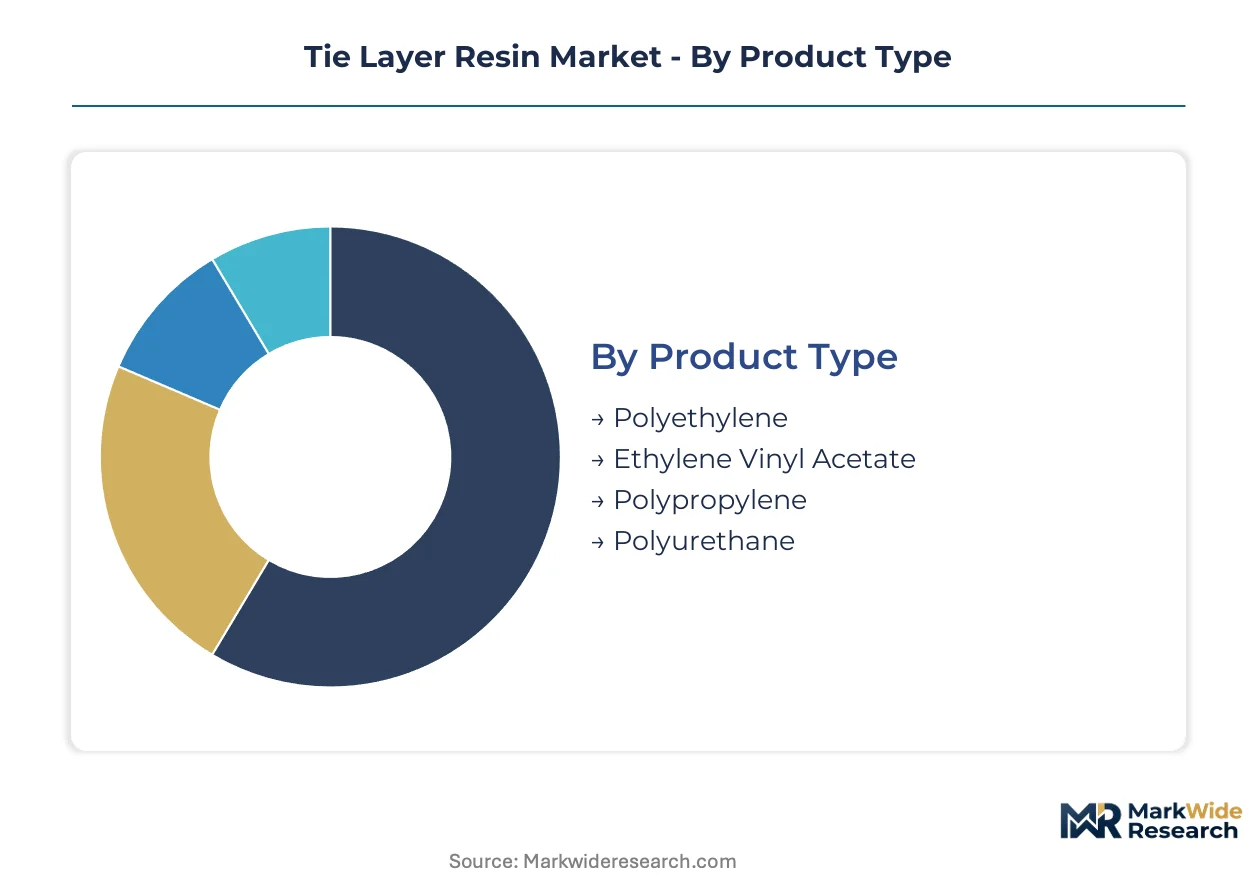
Tie layer resin segmentation reveals how formulation chemistry, processing method, and end-use specifications create distinct value tiers. Manufacturers optimize grafting density and backbone selection against thermal stress requirements and regulatory migration limits.
Product Type:
Polyethylene dominates volume throughput while polyurethane commands the steepest price premiums per kilogram.
- Polyethylene:Maleic anhydride grafted linear low-density and high-density variants constitute the workhorse grade, compatible with standard extrusion temperatures and broad substrate adhesion. Demand concentrates in Chinese and Indian infrastructure pipe projects where multilayer barrier designs replace metal distribution systems.
- Polyurethane:Solvent-free and moisture-cure formulations deliver superior bonding to polar substrates in medical film laminates. FDA migration limits tighten qualification cycles, extending approval timelines and concentrating procurement with compounders holding ISO 13485 certification.
- Ethylene Vinyl Acetate:Flexible interlayer with tunable vinyl acetate content for low-temperature adhesion in frozen food packaging.
- Polypropylene:Higher thermal stability suits automotive underhood applications and retort pouch structures.
Mature deployment sits with polyethylene. Newer deployment is concentrated in polyurethane.
Application:
Film applications generate the highest unit volumes, while pipe specifications drive compounder margin expansion through technical qualification barriers.
- Films:Coextruded blown and cast film structures for food packaging represent the largest addressable volume. EFSA and FDA extraction testing protocols force redundant analytical spend, advantaging suppliers with in-house migration laboratories.
- Pipes:Multilayer polyethylene pipes for potable water and gas distribution specify tie layers to bond barrier layers against permeation. Chinese GB standards and Indian BIS certifications create parallel compliance tracks that fragment testing costs.
- Coatings:Extrusion-coated paper and foil laminates for aseptic liquid packaging.
- Adhesives:Hot-melt and reactive tie layer formulations for specialty lamination.
Film specifications dominate current procurement. Pipe applications are climbing the fastest on infrastructure spend.
End User:
Packaging procurement scales with consumer goods volume, while automotive specifications concentrate with emission-compliant fuel system designs.
- Packaging:Food and beverage multilayer structures consume acid-modified polyolefins for oxygen and moisture barrier adhesion. North American CPGs are establishing approved supplier lists with audit rights over grafting reaction protocols.
- Automotive:Tank-in-tank fuel systems and evaporative emission barriers specify coextruded high-density polyethylene with tie layers meeting UN ECE R34. European OEMs are consolidating procurement with compounders holding IATF 16949 certification.
- Construction:Geomembranes and roofing membranes requiring weathering resistance.
- Electronics:Flexible circuit and display lamination for moisture protection.
Packaging represents established demand. Automotive is expanding most quickly on regulatory emission standards.
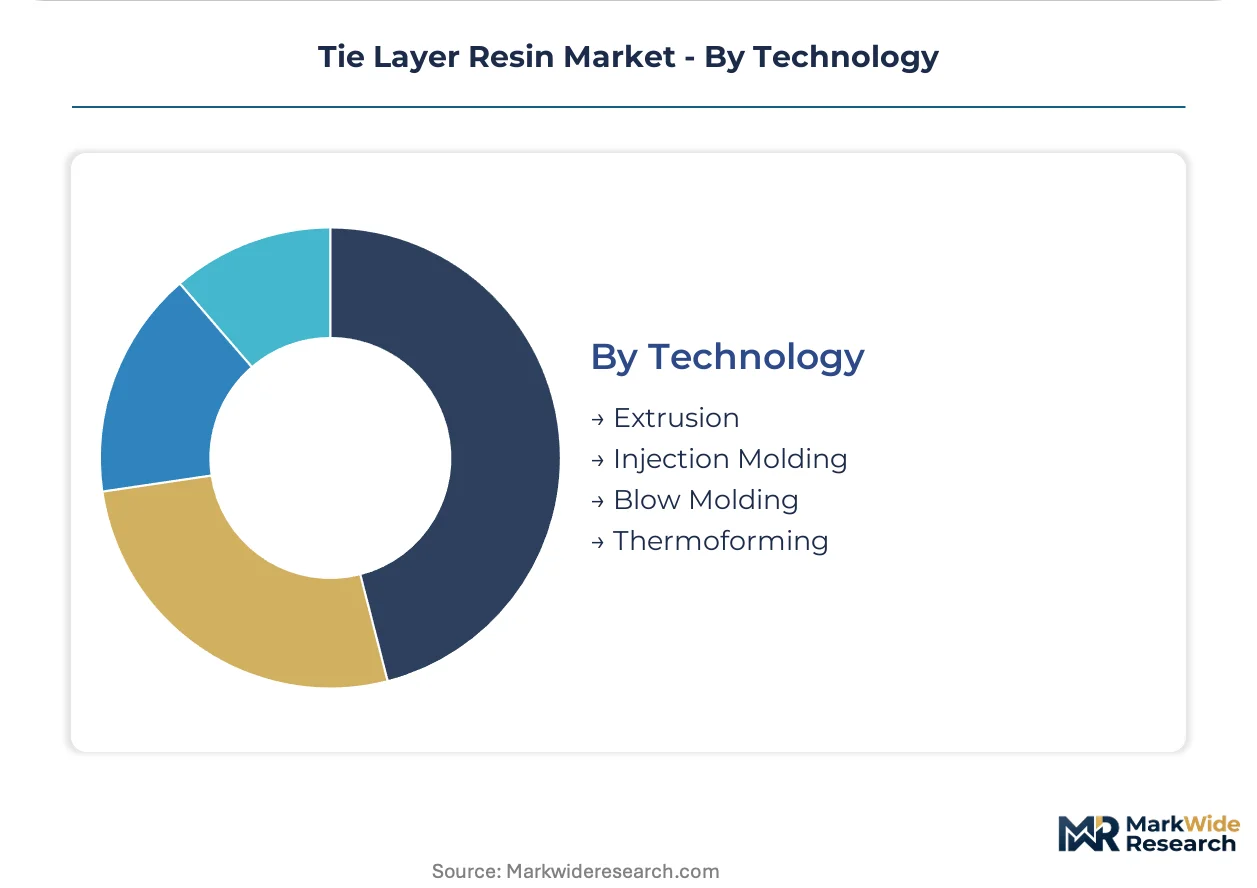
Technology:
Extrusion technology anchors current capacity installation, while blow molding gains share on automotive tank designs.
- Extrusion:Sheet, blown film, and cast film lines process the majority of tie layer resin volume. Layer thickness uniformity below 5 micrometers requires computational fluid dynamics expertise that resin suppliers rarely possess in-house.
- Blow Molding:Coextrusion blow molding for fuel tanks and industrial containers is displacing monolayer designs. German automotive suppliers are specifying six-layer tank structures with tie layers bonding ethylene vinyl alcohol barrier cores.
- Injection Molding:Technical parts and overmolding applications.
- Thermoforming:Sheet-based forming for food trays and medical device packaging.
Extrusion maintains process maturity. Blow molding is gaining share fastest on fuel system redesign.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta free-trade zones concentrate multilayer pipe manufacturing for water infrastructure. German chemical parks in Ludwigshafen and Leverkusen anchor European specialty resin production. Indian state-level PLI schemes for packaging materials accelerate coextrusion capacity buildout in Gujarat and Maharashtra.
United States
FDA migration limits and EPA leachate standards govern food-contact and potable water applications. The EPA's TSCA Section 5 notification requirements for new chemical substances extend qualification timelines for modified grafting chemistries. Houston-Gulf Coast petrochemical corridors host integrated polyethylene producers with captive maleic anhydride grafting capabilities.
China
GB standards and SAMR food-contact notifications create compliance tracks distinct from Western regulatory frameworks. MIIT's dual carbon goals pressure resin producers toward mass-balance certified feedstocks. Yangtze River Delta converters in Jiangsu and Zhejiang provinces scale multilayer blown film lines for domestic flexible packaging demand.
Germany
ECHA REACH Annex XVII restrictions on high-migration additives force reformulation of medical-grade tie layers. The EU Packaging and Packaging Waste Regulation's design-for-recycling mandates create demand for compatibilizer tie layers in mono-material structures. Chemical parks in North Rhine-Westphalia concentrate metallocene catalyst production and acid-modified polyolefin compounding.
India
BIS certification requirements for multilayer pipes used in gas distribution create technical entry barriers for imported resins. Central government Jal Jeevan Mission water infrastructure spending drives specification of bonded barrier-layer pipes in rural districts. Gujarat's Dahej and Mundra port zones concentrate import-dependent resin distribution for northern and western state markets.
Japan
METI's resource circulation policy and plastic recycling targets incentivize tie layer development for recyclable packaging structures. PMDA medical device regulations enforce stringent extraction testing for film laminates used in pharmaceutical packaging. Kansai region converters in Osaka prefecture pilot oxygen-scavenging hybrid tie layers for retort pouch applications.
Tie Layer Resin Market Vendor Landscape
North American producers anchor one tier; European and Japanese specialists hold differentiated positions in medical and automotive grades. The supplier base concentrates around integrated petrochemical majors with captive polyethylene backbones and independent compounders serving niche qualification requirements. Three archetypes dominate: backbone-integrated resin producers, specialty grafting compounders, and catalyst technology licensors. Capacity expansion and strategic technology licensing represent the dominant competitive vectors.
Within the integrated-producer tier, Dow Chemical Co. and ExxonMobil Corporation exemplify backbone control strategies, while Mitsui Chemicals, Inc. occupies a position among acid-modified polyolefin specialists serving fuel system applications. Arkema Group and Eastman Chemical Company represent European and US-based compounders navigating REACH-driven reformulation cycles. LyondellBasell Industries Holdings B.V. and Westlake Corporation sit within the commodity-scale resin production segment with distribution reach across packaging end-uses.
| Leading Market Players |
|---|
| LyondellBasell Industries Holdings B.V. |
| Westlake Corporation |
| Mitsui Chemicals, Inc. |
| Mitsubishi Chemical Corporation |
| Dow Chemical Co. |
| Arkema Group |
| ExxonMobil Corporation |
| Eastman Chemical Company |
| DuPont |
| Others |
Supply Flow & Price Mechanics
Reactive extrusion technology adoption is compressing grafting reaction costs for integrated polyethylene producers while concentrating pricing power among compounders with captive maleic anhydride supply. This production-method transition simultaneously erodes margin buffers for toll compounders dependent on spot monomer purchases and rewards backward-integrated suppliers with cost structures insulated from crude butadiene volatility.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to medical-grade tie layers requiring ISO 13485-certified batch documentation within 48 hours. Contract-based long-term offtake dominates polyethylene volume procurement for Chinese infrastructure pipe projects, while spot-market transactions concentrate among smaller North American packaging converters. Price differentiation hinges on REACH compliance certification tier and volume scale, with FDA master file access commanding substantial premiums. Pricing pressure stems from polyurethane substitution in medical films, compressing polyolefin tie layer margins in Class II device packaging segments. Regional compounders lacking integrated backbones exhibit highest price sensitivity, whereas automotive OEMs prioritize emission-compliant qualification over unit cost.
Supply Chain Analysis
India's BIS localization mandates for multilayer gas distribution pipes are redirecting procurement toward domestic compounding facilities in Gujarat and Maharashtra. Raw material flows concentrate in Germany, the United States, and Saudi Arabia for metallocene catalyst precursors and high-purity maleic anhydride feedstock. Supply chain vulnerability centers on single-source dependency for single-site catalyst production clusters in Ludwigshafen chemical parks. Distribution runs through approved supplier lists maintained by multinational food brands, bypassing traditional distributor channels and concentrating volume with tier-one resin producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty catalyst production bottlenecks in German chemical parks are constraining precision adhesion grade supply, sustaining pricing premiums for qualified compounders through the projection horizon.
For Market Incumbents: Deepen backward integration into maleic anhydride production to neutralize feedstock volatility exposure threatening compounder margins. Expand IATF 16949-certified capacity in European automotive corridors to capture tank-in-tank fuel system specifications under UN ECE R34. Secure mass-balance certification for polyethylene backbones ahead of EU Packaging and Packaging Waste Regulation mandates to defend positioning in brand-owner sustainability scorecards. For New Entrants and Emerging Players: Launch via direct resin procurement partnerships with North American CPGs establishing approved supplier lists with grafting protocol audit rights. Target Indian state-level PLI schemes for packaging materials in Gujarat and Maharashtra, where coextrusion capacity buildout outpaces qualified tie layer supply. Penetrate medical film segments through ISO 13485 certification investment, exploiting extended qualification timelines that marginalize incumbent polyurethane suppliers facing REACH-driven reformulation burdens. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated petrochemical majors seeking acid-modified polyolefin technology access. Five-to-ten year viability favors compounders with captive catalyst licensing relationships and established EMA medical device master files. Monitor ECHA Annex XVII substance restriction announcements as inflection indicators for reformulation-driven consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Maleic Anhydride | Captive monomer supply insulates margin structures from crude butadiene volatility transmitted through refinery stream disruptions. |
| REACH-Compliant Reformulation Investment | Lower-extraction chemistry development secures ECHA regulatory continuity for European medical and food-contact applications. |
| Mass-Balance Certification Program | Bio-circular feedstock credentials unlock premium positioning in CPG sustainability procurement scorecards. |
| IATF 16949 Capacity Expansion | Automotive quality certification enables specification for European OEM tank-in-tank fuel system programs under UN ECE R34. |
| Oxygen-Scavenging Hybrid Formulation Launch | Multifunctional tie layers compress film layer counts for Japanese retort pouch converters piloting ready-meal formats. |
Methodological Framework
Multi-period observation of coextrusion line installation rates, REACH substance restriction timelines, and automotive emission regulation adoption anchored the trend analysis, supplemented by interviews with plant managers at multilayer film converters, procurement leads at downstream packaging OEMs, technical R&D directors at grafting compounders, and distribution channel partners in chemical parks. Secondary validation drew from customs and trade data, SEC 10-K filings, ECHA regulatory dossiers, and ACC industry reports. Bottom-up volume modeling triangulated against top-down value estimates derived from resin producer revenue disclosures.
Input-output matrices mapped polyethylene backbone supply, maleic anhydride grafting capacity, and end-use demand across packaging, automotive, and infrastructure segments over the projection horizon. Segmentation dimensions included product chemistry grade, processing technology, end-use industry, and regional regulatory cluster. CAGRs were synthesized from production capacity buildout schedules, OEM specification adoption curves, and infrastructure spending commitments. Industry-specific forecast inputs incorporated ECHA substance restriction implementation phases and MIIT dual carbon policy compliance trajectories.
Feedstock price volatility, regulatory divergence between FDA and SAMR extraction protocols, and polyurethane substitution acceleration in medical films are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions regarding catalyst supply continuity and coextrusion technology diffusion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Europe Polyamide Market
Polymers & Resins
Medical Polymers Market
Polymers & Resins
Bio-Polybutadiene Market
Polymers & Resins
Polyvinyl Butyral (PVB) Market
Polymers & Resins
Polystyrene (PS) and Expanded Polystyrene (EPS) Market
Polymers & Resins
Phthalonitrile Resin Market
Polymers & Resins
PET Foam Market
Polymers & Resins
Silicone Resins Market
Polymers & Resins
Rigid Colored PU Foam Market
Polymers & Resins
Global High Temperature Resin Market
Polymers & Resins
Polytrimethylene Terephthalate Market
Polymers & Resins
High-Purity Epoxy Resin Market
Polymers & Resins
Ammonium Polyphosphate (Phase II) Market
Polymers & Resins
Bio-Based Emulsion Polymers Market
Polymers & Resins
Soil-Release Functional Polymers for Performance Apparel Care Market
Polymers & Resins
CO2-Based Polycarbonate Polyols for Flexible PU Foam Market